
 Glycosylated Peptide Market | 2026-2036
Glycosylated Peptide Market Size, Share, and Industry Trends Forecast 2026-2036
Glycosylated Peptide Market Analysis
Aftermarket analytical service revenue is tilting toward glycan characterization and batch-release testing as originator biologics face biosimilar pressure. Lonza Group AG sustains manufacturing scale across multi-modal peptide-glycan conjugation platforms. GenScript Biotech Corporation specializes in custom glycoengineering for early-stage drug candidates. Thermo Fisher Scientific Inc. dominates analytical instrumentation workflows that validate glycosylation patterns.
Glycosylated peptides are amino acid chains bearing covalently linked carbohydrate moieties, typically assembled through enzymatic or chemoenzymatic glycosylation with defined glycan structures at asparagine or serine residues. These molecules modulate protein folding, serum half-life, and receptor binding specificity in therapeutic proteins. Among product types, glycoprotein segments carry the deepest margin pools due to complexity premiums in cell-line development. Parenteral delivery mode leads volume given bioavailability constraints of glycosylated macromolecules, while oral formulations represent the fastest-growing delivery investigation. Therapeutic application anchors current revenue, though drug discovery usage expands fastest as AI-driven target identification multiplies candidate screening throughput.
FDA enforces glycosylation consistency requirements under biosimilar comparability guidelines, while EMA's MDR framework tightens analytical characterization standards for advanced therapy medicinal products. The European F-Gas Regulation additionally shapes manufacturing location decisions by restricting fluorinated solvent use in peptide synthesis facilities. Stakeholders must monitor evolving pharmacopeial monographs for glycan profiling methods and preemptively invest in mass spectrometry capacity to retain market access across jurisdictions.
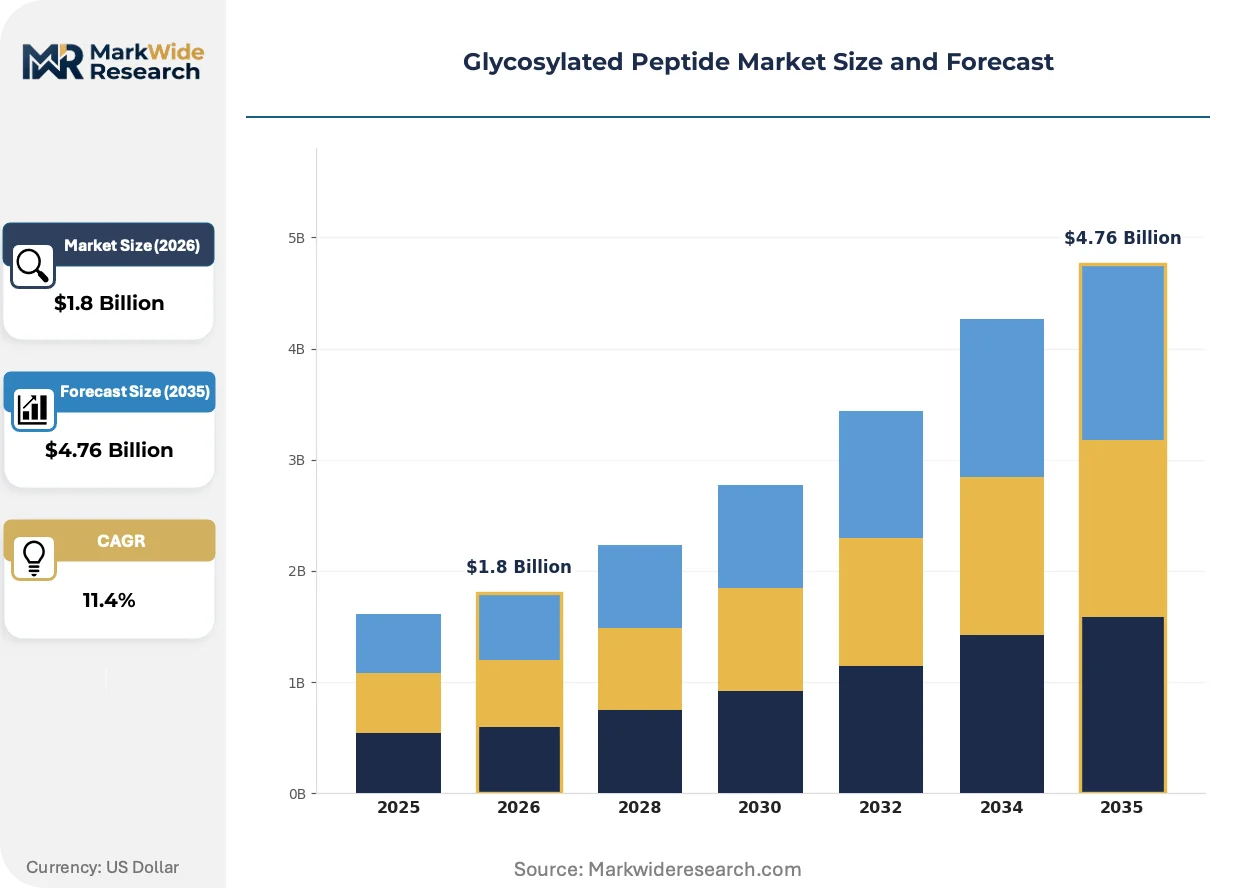
Market Dynamics
Controlled glycosylation engineering is compressing development timelines for therapeutic proteins while FDA and EMA biosimilar comparability guidelines force analytical rigor upgrades across contract manufacturing networks.
Growth Catalysts
- EMA MDR Framework:Tightened characterization standards for advanced therapy medicinal products expand demand for validated glycan profiling services.
- Monoclonal Antibody Manufacturing:Biopharmaceutical producers require glycosylated peptides to optimize effector function and serum half-life in next-generation therapeutics.
- Precision Medicine Clusters:Concentrated R&D investment in the United States, Germany, and Japan generates sustained demand for custom glycoengineering capabilities.
Market Restraints
- Fluorinated Solvent Restrictions:Europe's F-Gas Regulation limits manufacturing location flexibility by constraining solvent use in peptide synthesis facilities.
- Mass Spectrometry Capacity Scarcity:Specialized analytical instrumentation requires multi-year capital deployment cycles that constrain batch-release throughput.
- Cell-Line Development Complexity:Glycoprotein production demands extended development timelines that compress margin pools for standard peptide offerings.
Strategic Opportunities
- AI-Driven Target Identification:Machine learning platforms accelerate candidate screening throughput, expanding drug discovery application revenue faster than therapeutic segments.
- Oral Formulation Development:Bioavailability investigations for glycosylated macromolecules represent the fastest-growing delivery mode investigation.
- Aftermarket Analytical Services:Glycan characterization and batch-release testing revenue tilts upward as originator biologics face intensifying biosimilar pressure.
Industry Challenges
- Pharmacopeial Method Harmonization:Evolving glycan profiling monographs across jurisdictions force preemptive mass spectrometry capacity investments to retain market access.
- Multi-Modal Conjugation Expertise Gap:Peptide-glycan platform specialization requires rare cross-disciplinary talent spanning synthetic chemistry and enzymatic engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glycosylated Peptide Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monosaccharide, Oligosaccharide, Polysaccharide, Glycoprotein End User: Pharmaceutical Companies, Research Institutions, Biotechnology Firms, Contract Research Organizations Application: Therapeutic, Diagnostics, Research & Development, Drug Discovery Delivery Mode: Parenteral, Oral, Topical, Inhalation |
| Companies Covered | Pfizer Inc., Bachem Holding AG, Roche Holding AG, Merck KGaA, Thermo Fisher Scientific Inc., Teva Pharmaceutical Industries Ltd., Lonza Group AG, GenScript Biotech Corporation, Celltrion Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glycosylated Peptide Market Emerging Trajectories
Chemoenzymatic glycosylation methods are displacing purely chemical synthesis as the dominant production paradigm, while regulatory agencies tighten analytical comparability requirements and procurement patterns shift toward integrated manufacturing-analytical bundles.
Site-specific glycan installation technology enables defined carbohydrate structures at asparagine or serine residues with batch-to-batch consistency previously unattainable through stochastic methods. Biopharmaceutical manufacturers with biosimilar portfolios adopt these platforms to satisfy FDA glycosylation consistency requirements. The technology is migrating from early-stage discovery workflows into commercial manufacturing specifications, compressing the analytical validation burden for contract development organizations.
Europe's F-Gas Regulation now restricts fluorinated solvent use in peptide synthesis facilities, forcing manufacturing location decisions toward jurisdictions with alternative solvent infrastructure. This policy friction elevates capital requirements for facility retrofitting while creating geographic advantage for existing multi-modal platform operators. Germany and Switzerland-based manufacturers with established non-fluorinated process capabilities capture contract manufacturing share from facilities facing compliance-driven downtime.
Integrated manufacturing-analytical service bundles disaggregate traditional procurement patterns separating peptide synthesis from glycan characterization. Biopharmaceutical sponsors now favor single-provider relationships spanning conjugation through batch-release testing, compressing vendor management overhead. This consolidation pattern concentrates contract value with multi-modal platform operators in the United States and Germany, marginalizing pure-play analytical service providers lacking captive manufacturing capacity.
Glycosylated Peptide Market Segmentation
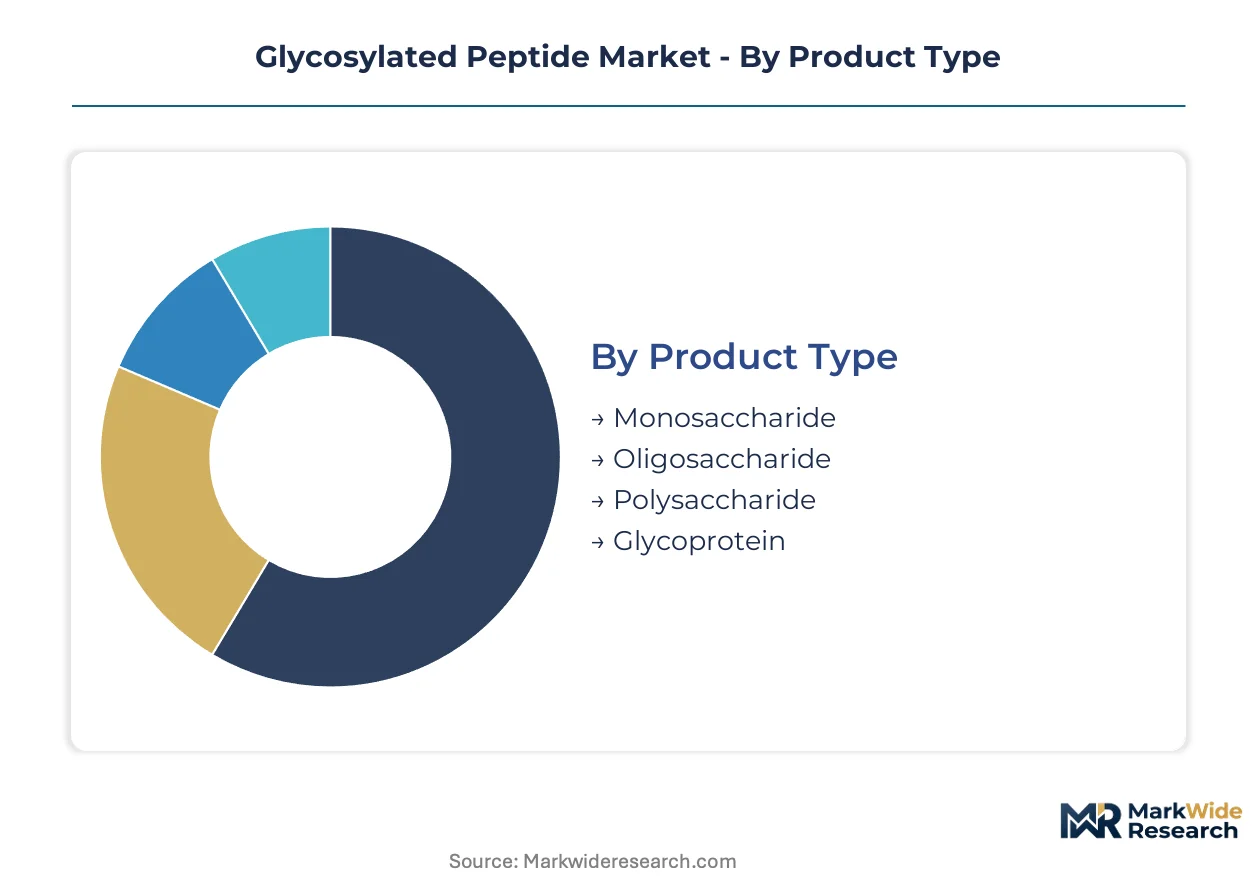
Glycosylated peptide segmentation reveals divergent margin structures across molecular complexity tiers. Product type stratification separates commodity carbohydrate conjugates from high-value glycoprotein therapeutics requiring extended cell-line development cycles.
Product Type:
Glycoprotein segments command the longest development timelines while monosaccharide conjugates turn inventory fastest through standardized chemoenzymatic workflows.
- Glycoprotein:Complex therapeutic proteins bearing N-linked or O-linked glycan structures at defined asparagine or serine residues. Biopharmaceutical manufacturers in the United States and Germany concentrate procurement here to optimize monoclonal antibody effector function and serum half-life, though EMA MDR framework compliance extends analytical validation cycles.
- Polysaccharide:Extended carbohydrate chains conjugated to peptide backbones through enzymatic transferase reactions. Research institutions in Japan drive demand for vaccine adjuvant applications where multivalent glycan presentation enhances immunogenic response, constrained by batch-to-batch consistency requirements under tightening pharmacopeial standards.
- Oligosaccharide:Mid-length glycan structures (3-10 sugar units) enabling defined receptor binding specificity in targeted therapeutics.
- Monosaccharide:Single-sugar modifications for rapid pharmacokinetic tuning in early-stage drug candidates.
Glycoprotein anchors the volume base while monosaccharide conjugates gain share at the steepest rate through accelerated discovery workflows.
End User:
Procurement scale varies sharply across customer type, with pharmaceutical companies committing to multi-year manufacturing agreements while research institutions purchase through project-based spot contracts.
- Pharmaceutical Companies:Originators and biosimilar developers requiring GMP-grade glycosylated peptides for commercial therapeutic production. FDA biosimilar comparability guidelines force these buyers toward integrated manufacturing-analytical bundles that compress vendor management overhead.
- Biotechnology Firms:Venture-backed developers of novel modalities including antibody-drug conjugates and bispecifics. These buyers cluster in Boston and San Francisco precision medicine corridors, prioritizing custom glycoengineering capabilities over standardized catalog offerings.
- Contract Research Organizations:CDMOs and analytical service providers building glycan characterization capacity to capture aftermarket revenue from originator biologics facing biosimilar pressure.
- Research Institutions:Academic laboratories investigating glycobiology fundamentals through grant-funded procurement with limited volume commitment.
Pharmaceutical companies dominate absolute spend while biotechnology firms expand procurement most quickly through platform technology licensing.
Application:
Commercial maturity spreads from established therapeutic revenue to emerging drug discovery segments where AI-driven target identification multiplies candidate screening throughput.
- Therapeutic:Approved biologics and late-stage clinical assets where glycosylation engineering directly modulates efficacy and safety profiles. Parenteral delivery constraints limit formulation flexibility, though oral bioavailability investigations now attract R&D investment.
- Drug Discovery:Early-stage target validation and lead optimization workflows. Machine learning platforms accelerate glycosylated peptide library generation, expanding this segment faster than therapeutic applications despite smaller individual contract values.
- Diagnostics:Glycan-based biomarker detection and imaging agents where defined carbohydrate structures enable disease-specific targeting.
- Research & Development:Process development and analytical method validation supporting regulatory filing preparation.
Therapeutic applications anchor current revenue while drug discovery usage climbs the fastest as computational biology platforms mature.
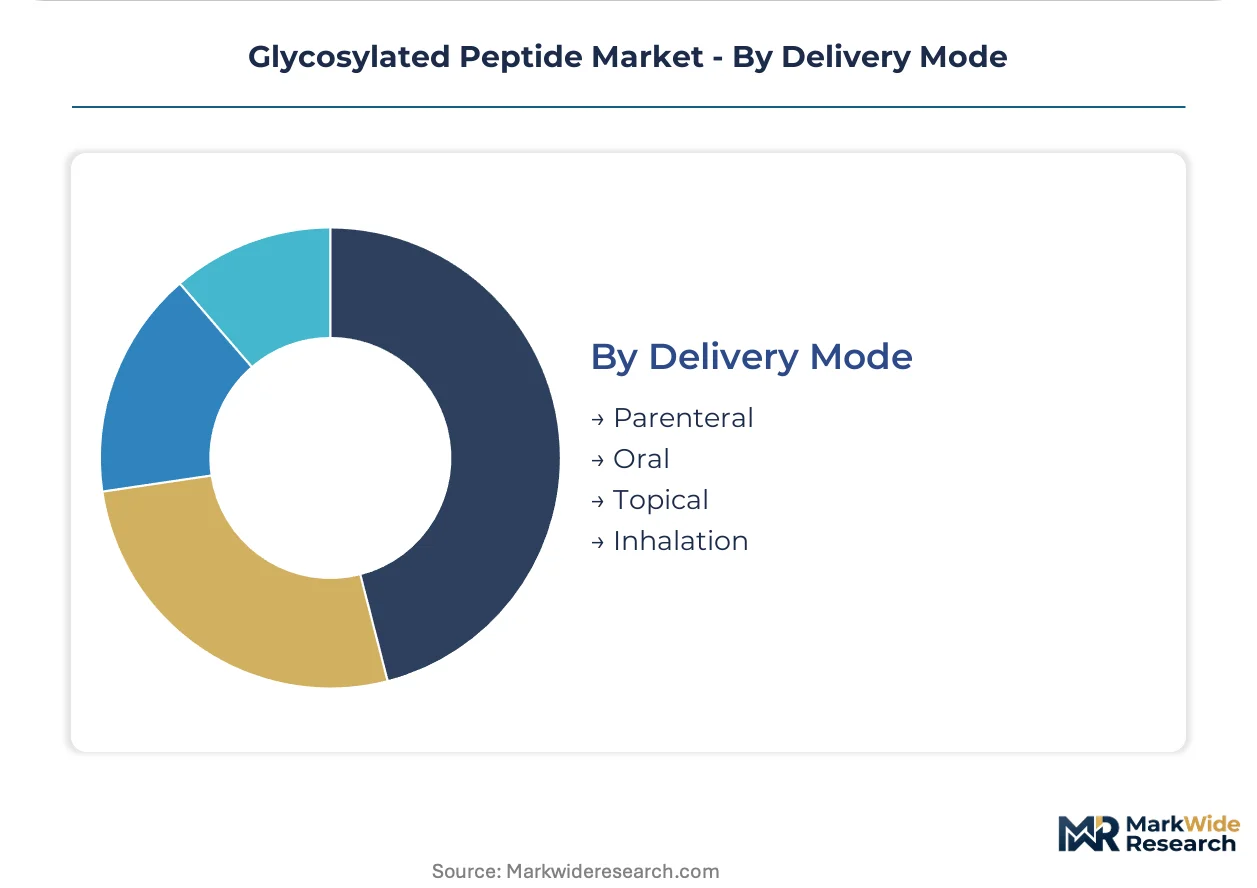
Delivery Mode:
Bioavailability constraints concentrate volume in parenteral administration while formulation innovation drives investigation toward non-invasive alternatives.
- Parenteral:Intravenous and subcutaneous injection of glycosylated macromolecules where molecular weight and hydrophilicity prevent gastrointestinal absorption. This mode carries deepest revenue concentration given manufacturing scale and regulatory familiarity.
- Oral:Encapsulation and permeation-enhancement strategies for glycosylated peptide delivery. Biotechnology firms in Germany and Japan lead investigation here, attracted by patient compliance advantages and competitive differentiation potential.
- Topical:Transdermal and mucosal applications for localized therapeutic effect with limited systemic exposure.
- Inhalation:Pulmonary delivery targeting respiratory indications where glycan-mediated cell entry mechanisms offer therapeutic rationale.
Parenteral delivery commands the installed base while oral formulation development shows the steepest expansion trajectory among investigation-stage programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States and Germany absorb complexity premiums with limited price elasticity, while procurement in India and emerging Asian markets sharpens cost sensitivity for standardized glycan conjugates.
United States
Precision medicine corridors in Boston and San Francisco generate concentrated demand for custom glycoengineering capabilities. FDA biosimilar comparability guidelines mandate glycosylation consistency validation, elevating analytical service procurement. The Greater Boston biotechnology cluster anchors contract manufacturing agreements for monoclonal antibody production.
Germany
Pharmaceutical manufacturers prioritize GMP-grade glycoprotein supply for therapeutic optimization. EMA's MDR framework tightens characterization standards for advanced therapy medicinal products. Bavaria-based production facilities capture contract share from competitors facing Europe's F-Gas Regulation compliance costs.
Switzerland
Specialized peptide-glycan conjugation platforms attract multi-year manufacturing partnerships from global biopharmaceutical sponsors. Swissmedic maintains stringent batch-release requirements that favor established analytical infrastructure. Basel-Zurich corridor operations benefit from proximity to European pharmaceutical headquarters.
Japan
Research institutions in Tokyo and Osaka drive demand for vaccine adjuvant applications with multivalent glycan presentation. PMDA guidelines shape glycan profiling method validation for commercial therapeutic filings. The Kanto region concentrates early-stage drug discovery procurement through platform technology licensing.
India
Cost-sensitive buyers prioritize standardized chemoenzymatic workflows for early-stage candidate supply. CDSCO regulatory pathways for biosimilars create compliance investment requirements for domestic manufacturers. Hyderabad and Mumbai clusters expand analytical service capacity to capture aftermarket revenue from originator biologics.
Glycosylated Peptide Market Vendor Landscape
Capability concentration sits with integrated manufacturing-analytical platform operators; scale advantage sits with multi-site contract development organizations serving global pharmaceutical sponsors. The vendor structure stratifies across three tiers: captive biopharmaceutical manufacturing arms, independent CDMOs with glycoengineering specialization, and analytical service providers lacking conjugation capacity. Dominant competitive moves include geographic expansion to circumvent solvent regulation constraints and strategic partnerships bundling synthesis through batch-release testing.
Within the integrated platform tier, Lonza Group AG and Thermo Fisher Scientific Inc. exemplify archetypes combining manufacturing scale with analytical validation infrastructure. GenScript Biotech Corporation occupies a specialist position in custom glycoengineering for early-stage candidates. These three entities anchor the competitive structure: Swiss-based Lonza represents multi-modal conjugation capability, American Thermo Fisher dominates analytical instrumentation workflows, and Chinese GenScript captures discovery-stage procurement through accelerated turnaround offerings.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Bachem Holding AG |
| Roche Holding AG |
| Merck KGaA |
| Thermo Fisher Scientific Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Lonza Group AG |
| GenScript Biotech Corporation |
| Celltrion Inc. |
| Others |
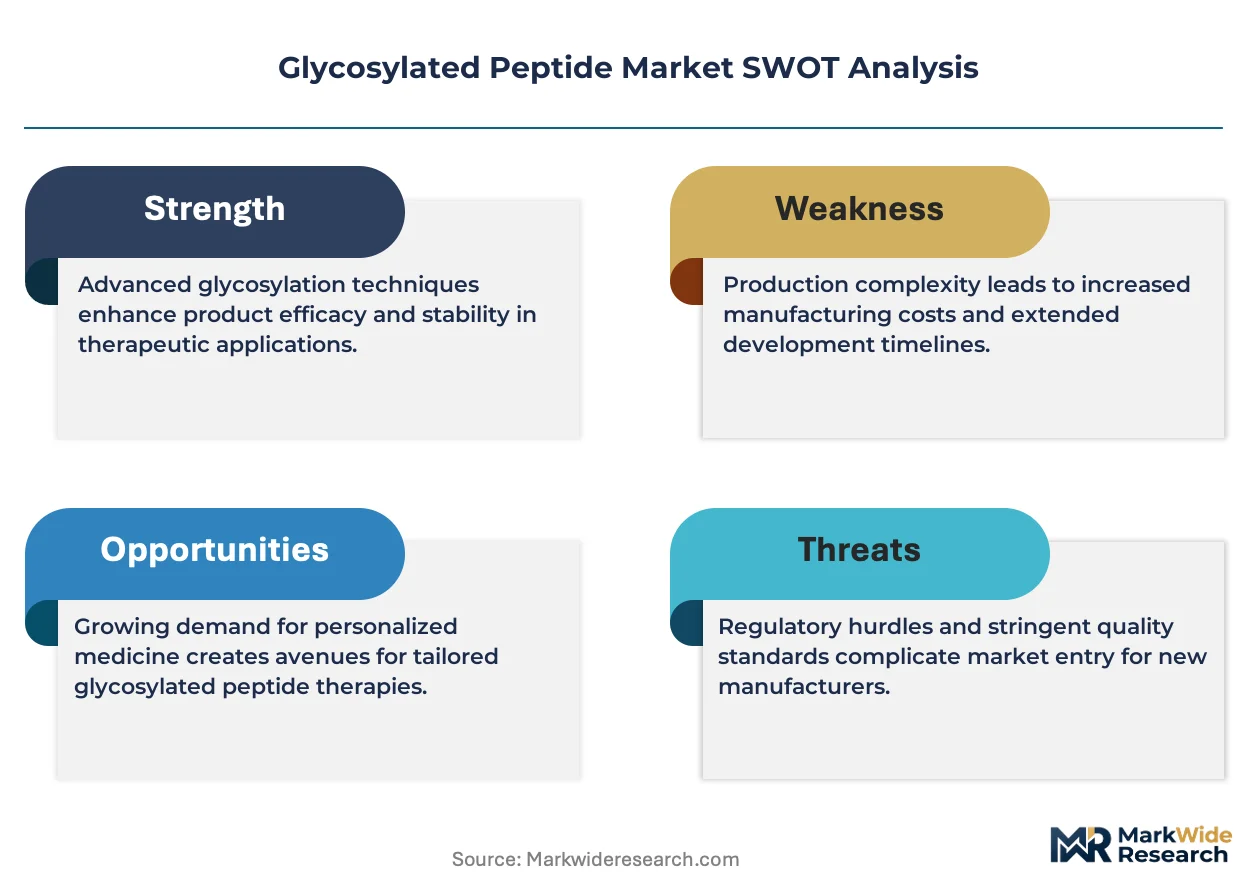
Supply Flow & Price Mechanics
Swiss and German multi-modal conjugation platforms anchor upstream supply for glycosylated peptides, concentrating margin capture with integrated manufacturing-analytical operators while fragmenting returns across pure-play analytical service providers lacking captive synthesis capacity.
Pricing Analysis
Aftermarket analytical service revenue, spanning glycan characterization and batch-release testing, drives lifetime value compression as originator biologics face intensifying biosimilar pressure. Three-tier pricing structure across premium, standard, and economy levels separates GMP-grade glycoprotein therapeutics from research-use catalog offerings and commodity monosaccharide conjugates. Cost compression in standard peptide tiers is intensifying because European F-Gas Regulation compliance elevates facility retrofitting capital requirements. Biotechnology firms in Boston and San Francisco precision medicine corridors exhibit least price sensitivity for custom glycoengineering capabilities, while Indian CDMOs prioritize standardized chemoenzymatic workflows for cost-sensitive early-stage candidate supply.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Swiss and German platform operators are displacing transactional procurement patterns toward multi-year manufacturing partnerships. Geographic supply concentration centers on Switzerland, Germany, and the United States for GMP-grade glycoprotein production, with India and China anchoring research-use peptide supply. Raw material dependencies rest on fluorinated solvents, enzymatic transferase reagents, and mass spectrometry calibration standards. Single-source vulnerability in specialized glycan characterization instrumentation constrains batch-release throughput. Distribution runs through integrated manufacturing-analytical bundles that compress vendor management overhead for biopharmaceutical sponsors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-disciplinary talent spanning synthetic chemistry and enzymatic engineering represents the critical capability gap constraining platform expansion, with multi-modal conjugation expertise commanding scarcity premiums across contract manufacturing networks.
For Market Incumbents: Insulate analytical validation infrastructure through preemptive mass spectrometry capacity investments that satisfy evolving pharmacopeial monograph requirements across FDA and EMA jurisdictions. Captive cell-line development capabilities defend against margin compression from emerging chemoenzymatic platform specialists. Geographic expansion into non-fluorinated solvent jurisdictions circumvents Europe's F-Gas Regulation compliance costs. For New Entrants and Emerging Players: Oral formulation development programs in Germany and Japan represent the most penetrable entry point, as biotechnology firms there lead bioavailability investigations for glycosylated macromolecules with limited established supplier relationships. AI-driven drug discovery platforms in the Kanto region offer second white-space targeting through accelerated glycosylated peptide library generation. Licensing site-specific glycan installation technology from academic spinouts provides differentiated go-to-market positioning against standardized catalog competitors. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across mass spectrometry-dependent analytical service tiers as regulatory agencies tighten glycosylation consistency requirements. Long-term viability favors acquisition targets combining captive manufacturing capacity with validated batch-release infrastructure rather than pure-play analytical providers. The signal to monitor is EMA MDR framework enforcement intensity, which would accelerate demand concentration with established multi-modal platform operators.| Strategic Initiative | Industry Significance |
|---|---|
| Mass Spectrometry Capacity Expansion | Preemptive instrumentation investments satisfy FDA glycosylation consistency requirements for biosimilar comparability filings. |
| Non-Fluorinated Solvent Process Transition | Facility retrofitting captures contract share from competitors facing Europe's F-Gas Regulation compliance-driven downtime. |
| Integrated Manufacturing-Analytical Bundling | Single-provider relationships spanning conjugation through batch-release testing compress vendor management overhead for sponsors. |
| Site-Specific Glycan Platform Licensing | Defined carbohydrate installation technology migrates from discovery workflows into commercial manufacturing specifications. |
| AI-Driven Discovery Partnership | Machine learning platform alliances accelerate candidate screening throughput for early-stage glycosylated peptide libraries. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with biopharmaceutical development executives, regulatory affairs leads at CDMOs, hospital formulary directors, and glycobiology principal investigators at research institutions. Secondary validation drew from FDA biosimilar comparability guidelines, EMA MDR framework documentation, pharmacopeial monograph evolution records, and Swissmedic batch-release requirement updates. Bottom-up procurement pattern analysis triangulated against top-down therapeutic protein production forecasts.
Calibration against historical glycoprotein therapeutic approval trajectories and cell-line development timeline benchmarks anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed product type complexity tiers, end-user procurement scale, therapeutic versus drug discovery application maturity, and parenteral versus oral delivery mode investigation intensity. CAGRs were derived from weighted scenario analysis incorporating regulatory enforcement trajectory assumptions and precision medicine R&D investment clustering patterns.
Practitioners should monitor pharmacopeial method harmonization progress and fluorinated solvent regulatory expansion for early signals of analytical capacity constraint intensification. Forecasts reflect assumptions regarding EMA MDR enforcement consistency and AI-driven target identification platform maturation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Incretin-Based Drugs Market
Biopharmaceuticals
Human Immunodeficiency Virus (HIV) Drugs Market
Biopharmaceuticals
Cancer Drug Market
Biopharmaceuticals
Bromodomain and Extraterminal Domain (BET) Inhibitors Market
Biopharmaceuticals
Recombinant Therapeutic Antibodies and Proteins Market
Biopharmaceuticals
Liposomal Doxorubicin Market
Biopharmaceuticals
Immunocytokines Market
Biopharmaceuticals
Terbinafine Tablet Market
Biopharmaceuticals
Latin America Insulin Pens Market
Biopharmaceuticals
Brazil Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Proteinuria Therapeutics Market
Biopharmaceuticals
Ewing Sarcoma Drugs Market
Biopharmaceuticals
Botanical and Plant Derived Drugs Market
Biopharmaceuticals
North America Diabetes Drugs Market
Biopharmaceuticals
Rivaroxaban Market
Biopharmaceuticals
Antibody Drug Conjugates Market