
 Asparaginase Market | 2026-2036
Asparaginase Market Size, Share, and Industry Trends Forecast 2026-2036
Asparaginase Market Analysis
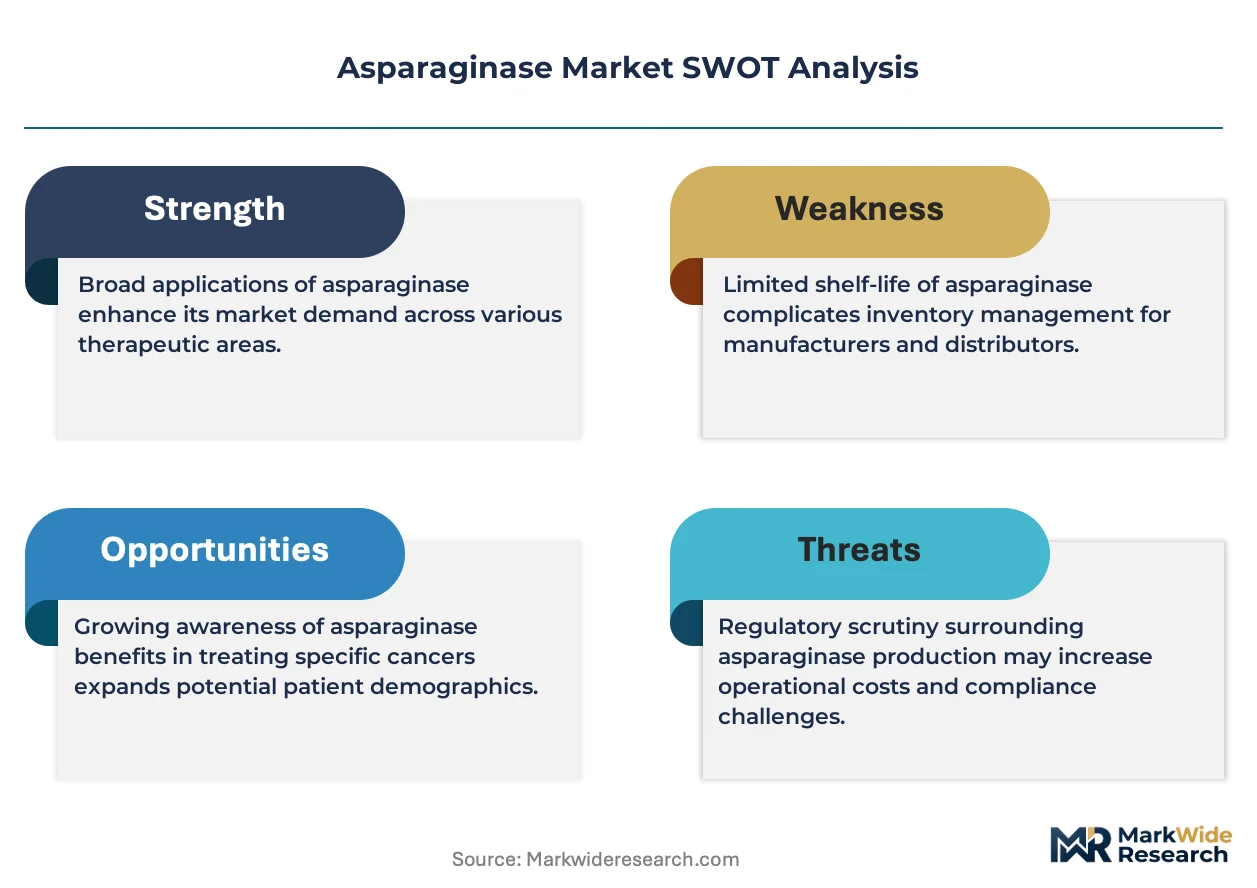
Aftermarket service revenue around patient monitoring and infusion support is tilting toward biopharma firms with dedicated oncology platforms. Jazz Pharmaceuticals plc leverages its hematology commercial infrastructure to sustain high-touch distribution models for asparaginase therapies. medac GmbH anchors European supply through specialized cold-chain logistics that compete on reliability rather than price. Servier Pharmaceuticals LLC differentiates via its hospital-centric account management that controls formulary access in key treatment centers.
Asparaginase denotes a family of enzymes, principally derived from Escherichia coli or Erwinia chrysanthemi, that catalyze the hydrolysis of asparagine to aspartic acid and ammonia; the enzyme requires pH stability between 7.0 and 8.5 and cold storage at 2°C to 8°C to preserve activity. Its primary commercial purpose is depleting circulating asparagine to arrest proliferation of asparagine-dependent malignant lymphoblasts in hematologic oncology. Pegaspargase formulations command premium positioning due to extended half-life and reduced immunogenicity compared with native asparaginase, while Erwinia-derived products capture growing share among patients with hypersensitivity to E. coli-derived therapy. Pediatric hospitals represent the most concentrated end-user segment, with procurement patterns shaped by protocol adherence requirements and adverse-event management capabilities rather than unit cost alone.
The FDA's orphan drug exclusivity provisions and EMA's pediatric investigation plan mandates shape clinical development timelines and market access pathways for asparaginase developers. ISO 13485 quality management standards and national pharmacovigilance reporting obligations in Germany through BfArM and in France through ANSM govern post-market surveillance intensity. Stakeholders must monitor evolving biosimilar entry strategies and immunogenicity testing protocols to anticipate shifts in prescribing preferences and reimbursement positioning.
Market Dynamics
Pediatric leukemia protocol standardization is compressing procurement cycles and concentrating purchasing authority within academic medical center networks, forcing suppliers to build dedicated cold-chain capabilities rather than compete on unit economics alone.
Growth Catalysts
- EMA Pediatric Investigation Plan mandates:Developers must include pediatric study arms in oncology trials, accelerating asparaginase formulation approvals for younger patient populations.
- Hypersensitivity management protocols:Clinical guidelines now require Erwinia-derived alternatives for E. coli asparaginase-intolerant patients, expanding addressable patient pools across hematology wards.
- United States academic medical center concentration:Treatment standardization through Children's Oncology Group protocols creates predictable, high-volume demand streams for approved formulations.
Market Restraints
- Biologic cold-chain dependency:Enzyme activity degradation above 8°C forces investment in validated shipping infrastructure, raising distribution costs disproportionately for smaller markets.
- Immunogenicity surveillance burden:FDA pharmacovigilance requirements and EMA risk management plans mandate extensive post-market antibody monitoring, extending compliance timelines.
- Native asparaginase substitution pressure:Pegaspargase's extended half-life reduces dosing frequency, compressing volume demand for unmodified enzyme products in frontline protocols.
Strategic Opportunities
- Biosimilar pathway exploitation:FDA's abbreviated licensure route for biologics opens market entry for pegaspargase alternatives with reduced clinical trial investment.
- Home infusion service models:Subcutaneous administration protocols enable ambulatory care expansion, shifting site-of-care from inpatient wards to specialty pharmacy networks.
- Immunogenicity testing integration:Companion diagnostic development for anti-asparaginase antibody detection creates service revenue streams alongside drug supply.
Industry Challenges
- Bioprocess engineering talent scarcity:Fermentation scale-up expertise for pH-sensitive enzyme production concentrates among legacy CMOs, constraining manufacturing expansion.
- Multi-jurisdiction batch release complexity:Divergent stability testing requirements between FDA, EMA, and national European regulators delay commercial supply availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asparaginase Market |
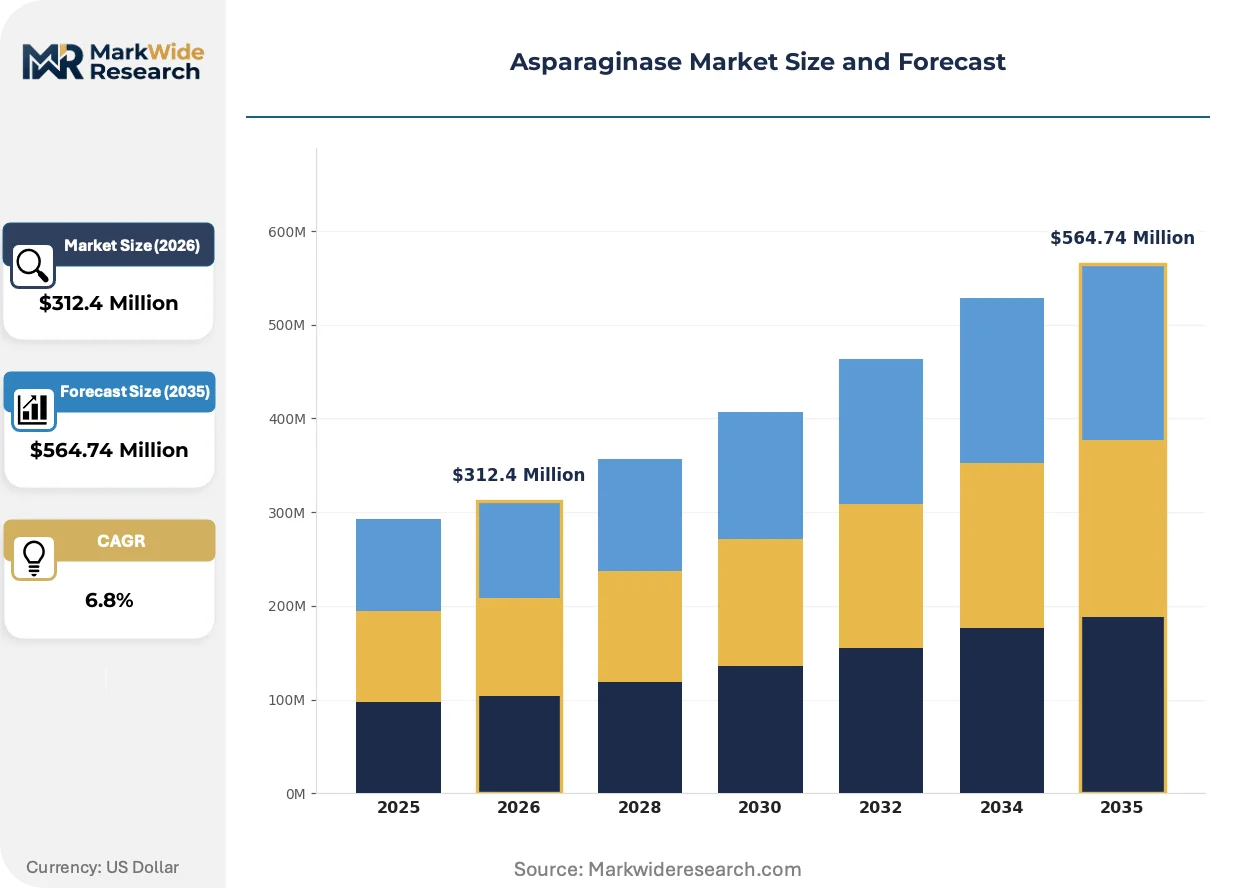
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Erwinia asparaginase, Pegaspargase, Native asparaginase, Others End User: Pediatric Hospitals, Adult Clinics, Academic Research Centers, Blood Cancer Treatment Facilities Delivery Mode: Intravenous, Intramuscular, Subcutaneous, Oral Application: Acute Lymphoblastic Leukemia, Lymphoma Treatment, Metastatic Cancers, Others |
| Companies Covered | Jazz Pharmaceuticals plc, medac GmbH, Servier Pharmaceuticals LLC, Taj Pharmaceuticals Limited, Porton Biopharma, Merck & Co., Amgen Inc., Changzhou Qianhong Bio-pharma Co Ltd, Kyowa Hakko Kirin Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asparaginase Market Emerging Trajectories
Formulation science and site-of-care economics are jointly redefining competitive advantage, with half-life extension technologies and infusion logistics commanding R&D investment ahead of novel molecular targets.
Pegaspargase polyethylene glycol conjugation technology extends circulating enzyme persistence from days to weeks. Pediatric oncology wards in the United States have adopted this formulation as first-line standard. The technology is migrating from premium positioning in relapsed settings to frontline protocol dominance, compressing native asparaginase to hypersensitivity rescue indications.
EMA's pediatric investigation plan requirements now bind oncology developers to include patients under 18 years in clinical trials. This regulatory obligation accelerates label expansion for existing asparaginase products. Formulation sponsors must redesign study protocols to satisfy both adult and pediatric endpoints simultaneously, raising trial complexity but securing broader market access.
Hospital purchasing committees now bundle enzyme supply with infusion nursing and adverse event monitoring services. Academic medical centers in the United States negotiate multi-year agreements that lock in formulary position. This consolidation concentrates procurement authority within supply chain departments, displacing physician-driven product selection with total-cost-of-care contracting.
Asparaginase Market Segmentation
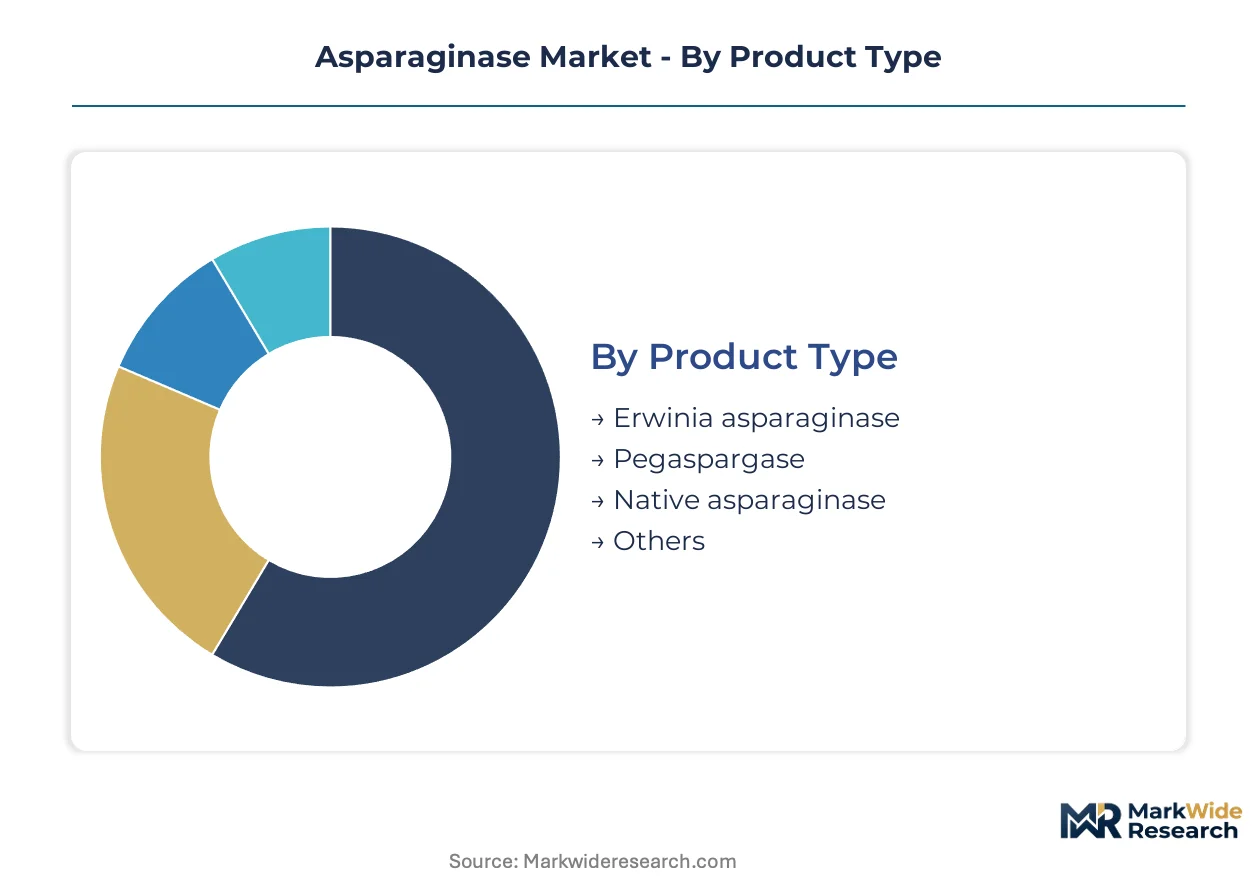
Asparaginase procurement patterns diverge sharply across formulation chemistry, patient age cohorts, and site-of-care economics. Pediatric protocol standardization and hypersensitivity management protocols create distinct demand profiles that reshape supplier positioning within each segment category.
Product Type:
Mature polyethylene glycol conjugation technology dominates frontline protocols while emerging enzyme sourcing alternatives capture hypersensitivity rescue demand.
- Pegaspargase:Polyethylene glycol conjugation extends circulating half-life from days to weeks, reducing dosing frequency and immunogenicity incidence. United States academic medical centers anchor demand through Children's Oncology Group protocol adoption. EMA pediatric investigation plan requirements accelerate label expansion for younger patient populations.
- Erwinia asparaginase:Derived from Erwinia chrysanthemi rather than E. coli, this formulation serves patients with documented hypersensitivity to bacterial-derived alternatives. Clinical guidelines in Germany and France now mandate availability for E. coli-intolerant cases. Cold-chain requirements match E. coli-derived products, preserving supplier interchangeability.
- Native asparaginase:Unmodified enzyme formulations retain niche positioning for cost-constrained protocols and specific regional tenders.
- Others:Investigational formulations and biosimilar candidates in development pipelines.
Pegaspargase retains volume leadership; Erwinia asparaginase holds the steepest expansion curve.
End User:
Procurement authority concentrates in high-acuity settings with adverse-event management capabilities rather than spreading evenly across treatment sites.
- Pediatric Hospitals:These institutions command the most concentrated demand through standardized leukemia protocols requiring specialized nursing and rapid hypersensitivity response. United States children's hospitals negotiate multi-year supply agreements that bundle enzyme procurement with infusion training and pharmacovigilance reporting.
- Adult Clinics:Outpatient hematology practices in France and Germany manage asparaginase therapy for adult acute lymphoblastic leukemia cases, though volume trails pediatric settings significantly.
- Academic Research Centers:Clinical trial networks in the United States and Europe drive formulation development and protocol refinement.
- Blood Cancer Treatment Facilities:Dedicated oncology centers in the United Kingdom and Italy handle complex cases requiring multi-agent regimens.
Pediatric hospitals dominate procurement volume; adult clinics are expanding most quickly as treatment protocols extend to older patient populations.
Delivery Mode:
Site-of-care economics and patient convenience requirements are displacing traditional administration routes with ambulatory-compatible alternatives.
- Intravenous:Hospital-based infusion remains standard for initial induction therapy, requiring nursing supervision for hypersensitivity monitoring. United States academic medical centers maintain dedicated infusion units with emergency response capabilities.
- Subcutaneous:Home administration protocols enable specialty pharmacy distribution models, reducing hospital bed utilization. German and Swiss reimbursement frameworks increasingly favor ambulatory delivery for maintenance phases.
- Intramuscular:Limited applications in specific European protocols where vascular access is compromised.
- Oral:No clinically effective oral asparaginase formulation exists due to gastric enzyme degradation.
Intravenous delivery retains volume leadership; subcutaneous administration holds the steepest expansion curve.
Application:
Disease-specific protocol standardization creates divergent demand intensity across hematologic malignancy types.
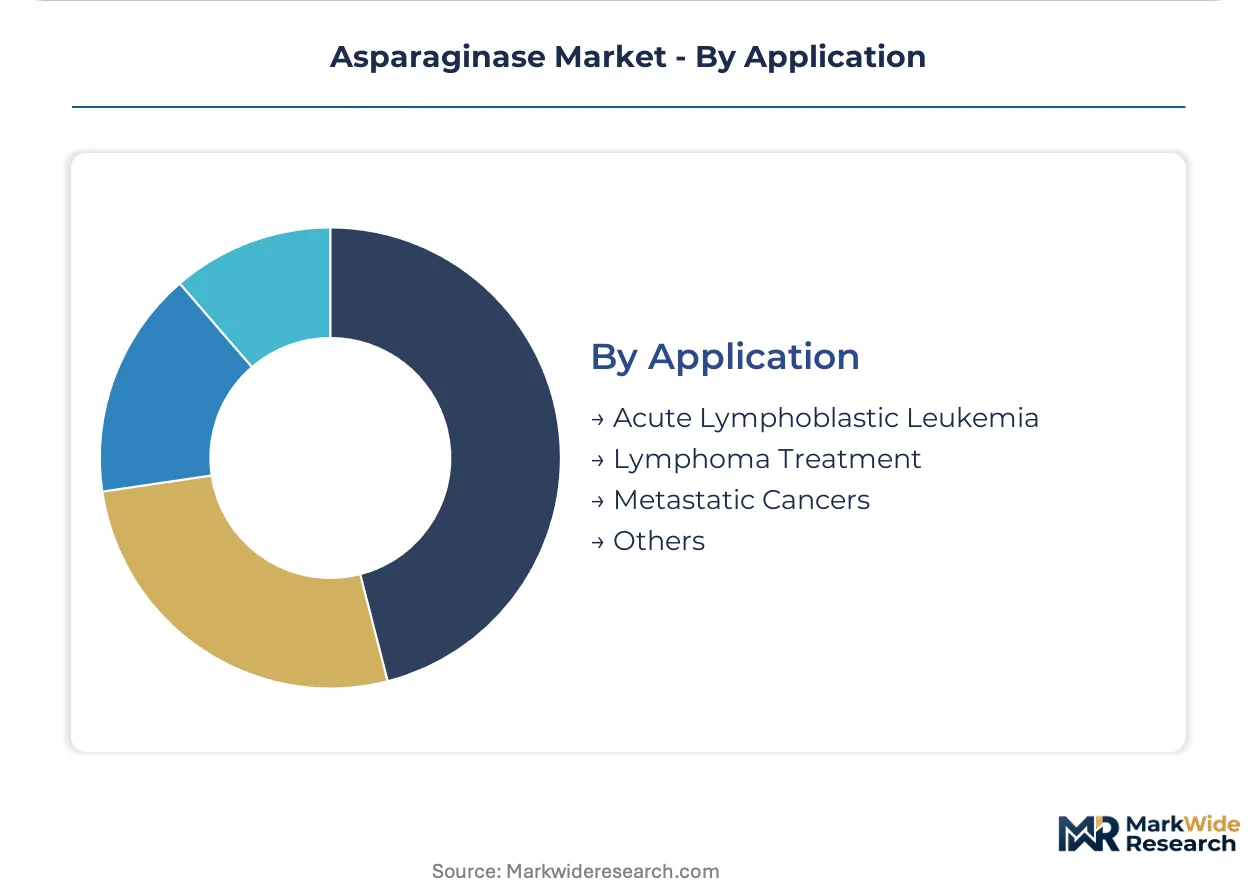
- Acute Lymphoblastic Leukemia:Frontline pediatric protocols in the United States, Germany, and Japan constitute the primary commercial indication. EMA pediatric investigation plan mandates ensure continued formulation development for this population.
- Lymphoma Treatment:Adult non-Hodgkin lymphoma protocols in France and the United Kingdom generate secondary demand, particularly for relapsed cases requiring salvage regimens.
- Metastatic Cancers:Investigational applications in solid tumor asparagine dependency remain preclinical or early-phase.
- Others:Rare hematologic indications and compassionate use programs.
Acute lymphoblastic leukemia retains volume leadership; lymphoma treatment holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cold-chain logistics infrastructure and pediatric oncology protocol standardization concentrate asparaginase supply reliability in markets with established biopharma distribution networks. Academic medical centers in high-income countries anchor procurement volume through multi-year formulary agreements.
United States
Pediatric leukemia treatment standardization through Children's Oncology Group protocols drives concentrated demand at major children's hospitals. FDA orphan drug exclusivity provisions incentivize sustained investment in formulation development. The Boston-Cambridge biopharma corridor hosts clinical trial networks that validate new asparaginase delivery protocols.
Germany
BfArM pharmacovigilance requirements shape post-market surveillance intensity for enzyme therapies distributed through hospital pharmacies. EMA pediatric investigation plan mandates accelerate label expansion for younger patient populations. The Rhine-Main region anchors European cold-chain distribution with validated logistics hubs serving hematology wards across Central Europe.
France
ANSM risk management plans govern immunogenicity monitoring obligations for asparaginase prescribers in public hospital networks. National tender processes for oncology biologics concentrate procurement authority at the regional level. The Paris-Saclay cluster coordinates multi-center pediatric trials that inform EMA regulatory submissions.
Japan
PMDA consultation procedures for pediatric oncology products streamline development pathways for asparaginase formulations targeting acute lymphoblastic leukemia. National health insurance reimbursement listing decisions hinge on pharmacoeconomic evidence from domestic trial data. The Kanto region's university hospitals anchor clinical research networks for hematologic malignancy protocols.
United Kingdom
NICE technology appraisals for oncology biologics determine formulary access within National Health Service trusts. Specialized commissioning arrangements concentrate complex leukemia treatment at designated cancer centers. The Oxford-Cambridge-London golden triangle hosts early-phase clinical trial units that evaluate novel asparaginase administration schedules.
Asparaginase Market Vendor Landscape
Specialized biopharma firms and diversified pharmaceutical manufacturers split the market between focused hematology platforms and broad oncology portfolios. Consolidation around cold-chain capabilities and hospital account management has created tiered competitive positions. Three archetypes dominate: dedicated hematology commercial infrastructure operators, European specialized logistics providers, and diversified biologics manufacturers. Capacity expansion in validated fermentation facilities and strategic partnerships for distribution rights constitute the primary competitive moves reshaping supplier positioning.
Within the specialized hematology tier, Jazz Pharmaceuticals plc and medac GmbH exemplify contrasting geographic anchoring strategies for enzyme therapy commercialization. Servier Pharmaceuticals LLC occupies a position bridging hospital-centric account management with multi-therapeutic area portfolios. Taj Pharmaceuticals Limited and Porton Biopharma represent manufacturing-origin competitors competing on supply reliability rather than brand recognition. Changzhou Qianhong Bio-pharma Co Ltd and Kyowa Hakko Kirin Co., Ltd. anchor Asia-Pacific supply positions through regional regulatory registrations.
| Leading Market Players |
|---|
| Jazz Pharmaceuticals plc |
| medac GmbH |
| Servier Pharmaceuticals LLC |
| Taj Pharmaceuticals Limited |
| Porton Biopharma |
| Merck & Co. |
| Amgen Inc. |
| Changzhou Qianhong Bio-pharma Co Ltd |
| Kyowa Hakko Kirin Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in validated fermentation facilities across Germany and the United States drives supplier consolidation and sustains premium pricing power for pH-sensitive enzyme production. Cold-chain infrastructure investments compound cost structures, forcing buyers into long-term offtake agreements that lock in formulary positions.
Pricing Analysis
Aftermarket service revenue from infusion nursing and adverse-event monitoring drives lifetime value beyond unit supply margins. Three-tier pricing structure across premium pegaspargase, standard E. coli-derived formulations, and economy rescue alternatives stratifies procurement tiers. Price differentiation hinges on half-life extension technology and ISO 13485 certification status. Cost compression in native asparaginase intensifies as pegaspargase captures frontline protocols. Pediatric hospitals exhibit lowest price sensitivity due to protocol adherence mandates; adult clinics in France and Germany face tighter budget scrutiny.
Supply Chain Analysis
Upstream microbial strain development and polyethylene glycol feedstock sourcing anchor production economics in the United States, Germany, and Japan. Fermentation capacity draws from specialized CMOs with legacy pH-control expertise; cold-chain packaging materials rest on polymer suppliers in the Rhine-Main region. Single-source vulnerability concentrates in validated shipping lane certification between European production hubs and United States children's hospitals. Distribution runs through hospital pharmacy direct contracts and specialty pharmacy networks for subcutaneous home administration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as site-of-care economics splinter procurement authority between inpatient formulary committees and ambulatory specialty pharmacies. Hypersensitivity protocol expansion creates distinct service-revenue niches alongside traditional supply contracts.
For Market Incumbents: Pre-empt biosimilar entry by securing multi-year pediatric hospital agreements that bundle enzyme supply with companion diagnostic development. Expand backward integration into captive fermentation capacity in the Boston-Cambridge corridor to reduce CMO dependency. Lock in cold-chain logistics partnerships before EMA pediatric investigation plan deadlines compress available supplier slots. For New Entrants and Emerging Players: Establish a beachhead in adult lymphoma protocols where formulary barriers remain lower than pediatric leukemia standards. Target German and Swiss reimbursement frameworks favoring subcutaneous home administration models. Lead with immunogenicity testing integration as a service wedge alongside commodity enzyme supply. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pegaspargase biosimilar development programs as FDA abbreviated licensure pathways demand expanded immunogenicity surveillance. Five-to-ten year viability favors platforms with hospital-centric account management infrastructure over pure manufacturing-origin competitors. Watch for EMA pediatric investigation plan compliance deadlines as inflection signals for distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Partnership | Validated logistics hubs in the Rhine-Main region secure EMA distribution compliance for Central European hematology wards. |
| Companion Diagnostic Development | Anti-asparaginase antibody detection platforms create service revenue streams alongside drug supply contracts. |
| EMA Pediatric Investigation Plan Submission | Regulatory compliance accelerates label expansion for younger patient populations across European markets. |
| Specialty Pharmacy Network Integration | Subcutaneous administration protocols shift site-of-care economics toward ambulatory reimbursement frameworks. |
| Fermentation Capacity Expansion | In-house pH-controlled enzyme production reduces dependency on legacy CMOs with scarce bioprocess engineering talent. |
Methodological Framework
Desk research of FDA orphan drug filings, EMA pediatric investigation plan submissions, and hospital procurement databases preceded structured interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from ClinicalTrials.gov records, BfArM pharmacovigilance reports, and ANSM risk management plan disclosures. Bottom-up volume estimates across formulation types and top-down market sizing triangulated to constrain projection variance.
Assumptions held fixed include EMA pediatric investigation plan mandate continuity and United States Children's Oncology Group protocol standardization; variables tested included biosimilar entry timing and subcutaneous administration reimbursement expansion. Segmentation dimensions spanned formulation chemistry, patient age cohort, delivery mode, and regional regulatory cluster. CAGRs derived from protocol adoption curves and hypersensitivity incidence modeling across hematology wards.
Stress conditions across cold-chain disruption frequency, immunogenicity surveillance cost inflation, and native asparaginase substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against FDA adverse event reporting system benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Global MRSA Testing Market
Medical Biotechnology
Global Mononucleosis Diagnostic Market
Medical Biotechnology
Smart Drug Discovery Market
Medical Biotechnology
Immortalized Cell Line Market
Medical Biotechnology
Fetal Valproate Syndrome Market
Medical Biotechnology
Galectin Inhibitor Therapeutics Market
Medical Biotechnology
Botulism Illness Market
Medical Biotechnology
Neurotrophins Market
Medical Biotechnology
Cell Culture Market
Medical Biotechnology
Waldenstrom Macroglobulinemia Market
Medical Biotechnology
Humanized Liver Mice Model Market
Medical Biotechnology
Myeloproliferative Disorders Drugs Market
Medical Biotechnology
Myoglobin Market
Medical Biotechnology
Mucormycosis Market
Medical Biotechnology
Serum Lactate Testing Market
Medical Biotechnology
Global DNA Vaccines Market