
 Cyclin-Dependent Kinase Inhibitor Market | 2026-2036
Cyclin-Dependent Kinase Inhibitor Market Size, Share, and Industry Trends Forecast 2026-2036
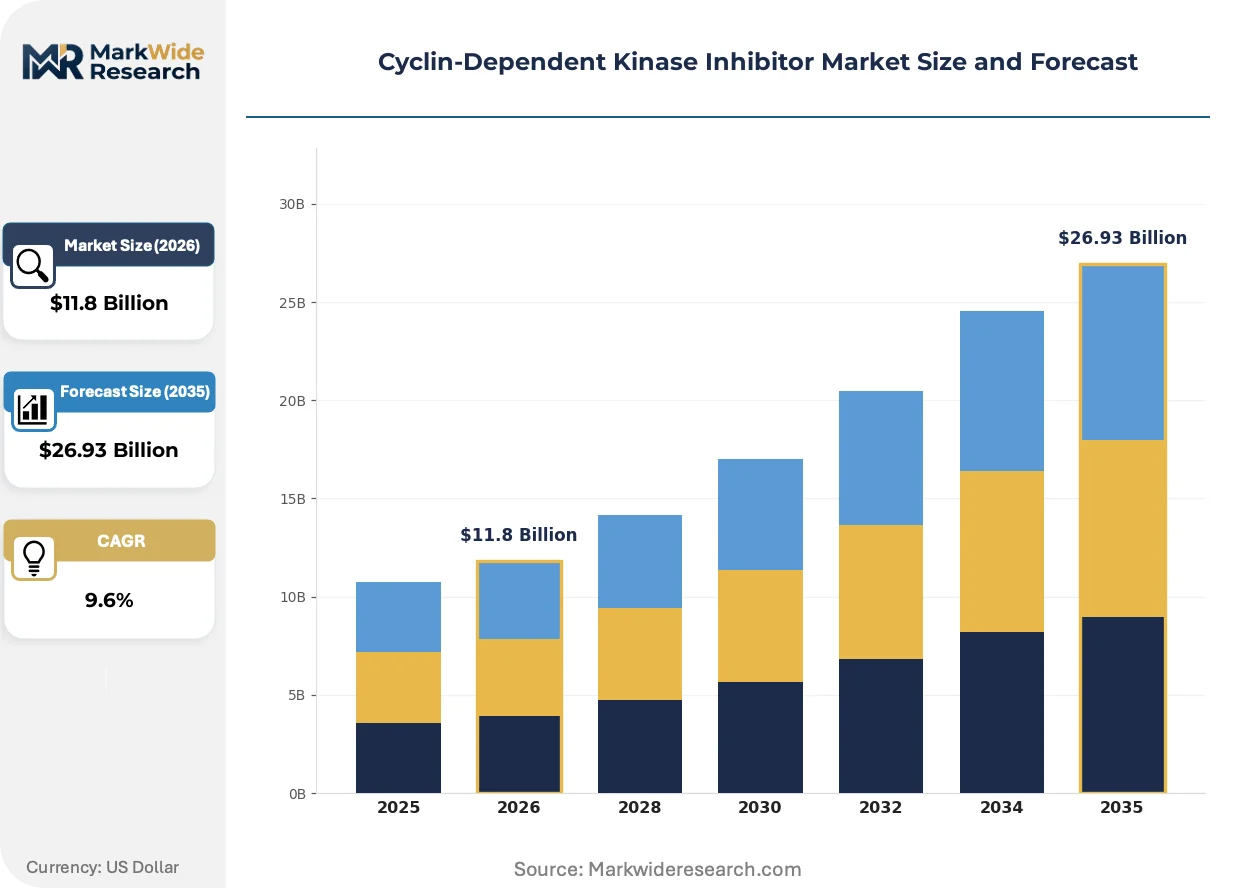
Cyclin-Dependent Kinase Inhibitor Market Outlook
FDA Breakthrough Therapy designation is bifurcating the competitive landscape between firms with validated regulatory track records and newer entrants. AstraZeneca leverages its oncology portfolio depth to sustain pipeline momentum across multiple CDK targets. Pfizer anchors its position through manufacturing scale and established distribution into hospital formularies. Novartis competes via differentiated clinical positioning in hematology applications.
Cyclin-dependent kinase inhibitors are small-molecule compounds that selectively block ATP-binding sites on CDK4, CDK6, or other cyclin-dependent kinases, arresting cell-cycle progression in malignant cells. These agents serve primarily as targeted oncology therapeutics, with particular efficacy in hormone receptor-positive breast cancer and emerging utility in other solid tumors. Palbociclib and ribociclib dominate current revenue pools as mature first-line therapies, while abemaciclib extends into adjuvant settings where longer treatment durations expand prescription volume. Small molecule technology leads manufacturing economics, though genomics-guided patient selection is reshaping which segments capture premium pricing.
FDA, EMA, and NMPA each enforce distinct chemistry-manufacturing-controls standards that determine which production facilities qualify for multi-regional supply. The FDA's accelerated approval framework creates demand surges that strain active pharmaceutical ingredient capacity, while China's NMPA reforms are opening parallel review pathways for domestic innovators. Stakeholders must monitor how post-approval confirmatory trial requirements evolve across these regulators, as withdrawal risks for failed studies now reshape portfolio prioritization decisions.
Market Dynamics
Post-approval confirmatory trial failures are forcing portfolio reprioritization across CDK inhibitor pipelines, as regulators tighten withdrawal mechanisms and payers demand survival data before reimbursing extended treatment durations.
Growth Catalysts
- FDA Accelerated Approval:The pathway compresses commercialization timelines for breakthrough oncology therapies, pulling forward revenue recognition for validated CDK4/6 inhibitors in hormone receptor-positive breast cancer.
- Adjuvant Expansion:Extended treatment protocols in early-stage settings multiply prescription volumes per patient, anchoring demand in academic medical centers with longitudinal oncology programs.
- Genomics-Guided Selection:Biomarker-driven patient stratification is improving response rates and justifying premium positioning for targeted CDK inhibitors against chemotherapy backbones.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing for small-molecule CDK inhibitors clusters in select Asian contract manufacturers, creating vulnerability to single-site disruptions.
- Reimbursement Compression:Payer formularies in the United States are tightening prior authorization requirements, extending approval timelines and increasing administrative burden on oncology practices.
- Cardiotoxicity Monitoring:QT prolongation risks with ribociclib-class agents require electrocardiogram surveillance infrastructure that limits adoption in resource-constrained treatment settings.
Strategic Opportunities
- China NMPA Parallel Review:Domestic innovator pathways are opening for locally developed CDK inhibitors, enabling first-mover positioning ahead of multinational patent cliffs.
- Brain Metastasis Indications:Blood-brain barrier penetration data for next-generation CDK inhibitors is creating expansion potential in HER2-negative breast cancer with CNS involvement.
- Combination Immunotherapy:CDK4/6 inhibition plus checkpoint blockade is showing mechanistic synergy in preclinical models, opening trial design white space in solid tumor types beyond breast.
Industry Challenges
- Biostatistics Talent Scarcity:Adaptive trial design expertise for confirmatory studies is concentrated among specialized CROs, inflating contract costs and extending study startup timelines.
- Multi-Regional CMC Harmonization:FDA, EMA, and NMPA enforce divergent chemistry-manufacturing-controls standards, forcing redundant facility qualifications and inspection cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cyclin-Dependent Kinase Inhibitor Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $26.93 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Palbociclib, Ribociclib, Abemaciclib, Others Application: Oncology, Hematology, Research, Others End User: Hospitals, Clinics, Research Institutions, Pharmacies Technology: Small Molecules, Combinatorial Chemistry, Genomics, Others |
| Companies Covered | AstraZeneca, Merck, Pfizer, Gilead Sciences, Jiangsu Hengrui Pharmaceuticals, Novartis, Bristol Myers Squibb, Syros Pharmaceuticals, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cyclin-Dependent Kinase Inhibitor Market Strategic Shifts
CDK inhibitor development is pivoting from pan-cyclin blockade toward selective target modulation, with translational biomarker platforms determining which mechanistic hypotheses advance to registrational trials.
Next-generation CDK2 and CDK7 selective inhibitors are fragmenting the historical CDK4/6 monopoly in hormone receptor-positive breast cancer. Academic medical centers in the United States are early-adopting these agents through investigator-initiated trials. The technology is fragmenting patient segmentation strategies, as pharmaceutical sponsors must now defend differentiated efficacy claims against entrenched standards rather than chemotherapy comparators.
EMA's Oncology Working Party has issued draft guidance on progression-free survival as a primary endpoint in CDK inhibitor trials, tightening evidentiary standards for conditional marketing authorizations. The policy compresses acceptable hazard ratio thresholds and mandates mature overall survival data for full approval conversions. European sponsors are responding by embedding interim analyses earlier in phase III protocols to preserve regulatory optionality.
Hospital formulary committees are consolidating purchasing authority for oncology therapeutics into centralized pharmacy and therapeutics committees, displacing individual physician prescribing autonomy. This concentration is compressing price negotiation cycles and demanding real-world evidence packages at contract inception. The pattern is most visible in United States integrated delivery networks, where pharmacy benefit managers now sit on formulary voting panels.
Cyclin-Dependent Kinase Inhibitor Market Segmentation
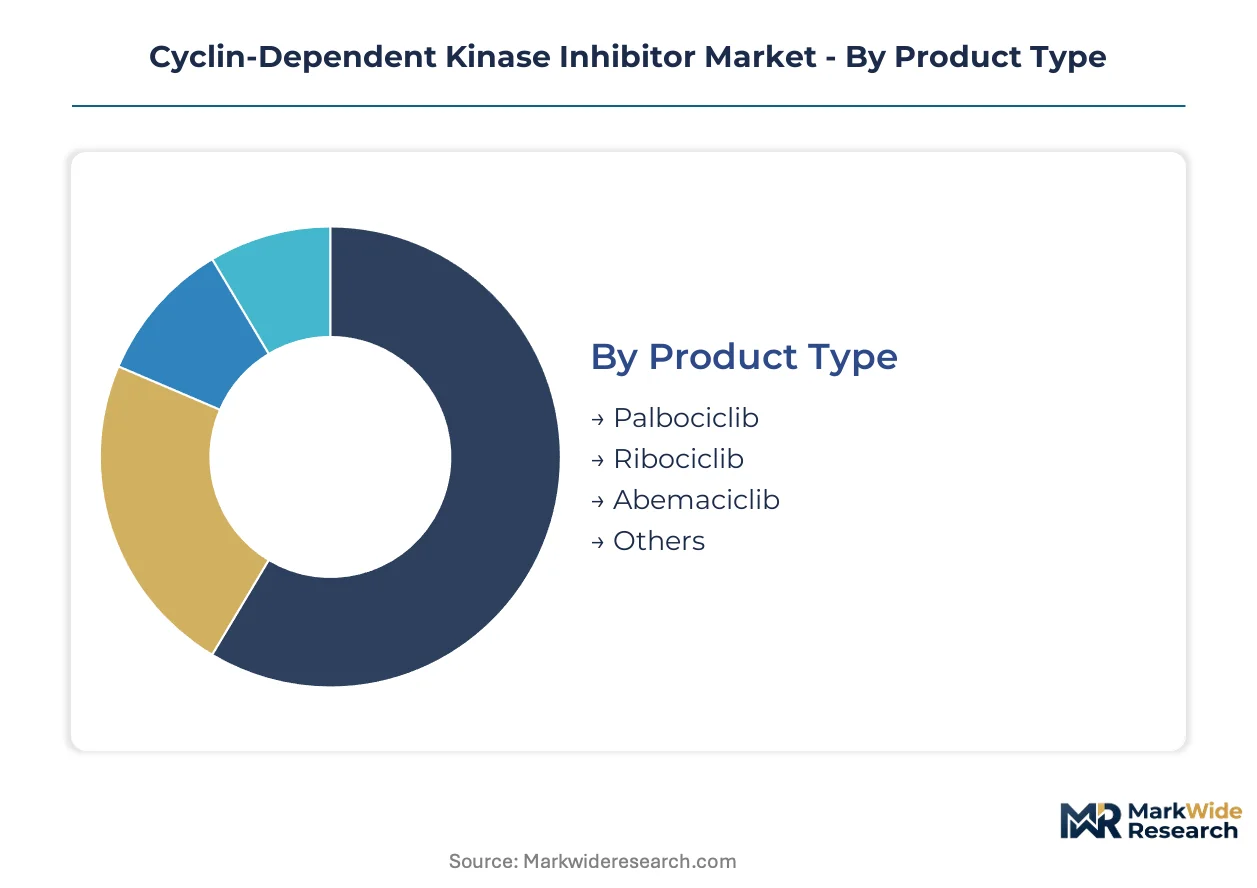
CDK inhibitor market segmentation reveals how therapeutic positioning, manufacturing technology, and clinical setting determine pricing power and competitive moats. Distinct patient selection criteria and regulatory pathways fragment commercial strategies across each dimension.
Product Type:
Palbociclib and ribociclib anchor United States demand through established FDA approvals in hormone receptor-positive breast cancer, while abemaciclib penetrates adjuvant protocols with longer treatment durations.
- Palbociclib:First-in-class CDK4/6 inhibitor with mature reimbursement pathways in academic medical centers. United States oncology departments anchor volume through first-line breast cancer protocols, though cardiotoxicity monitoring requirements constrain community clinic adoption.
- Ribociclib:Competes via MONALEESA trial data showing overall survival advantages in specific patient subpopulations. European EMA approvals and NMPA pathways in China drive export-led growth as patent cliffs approach in domestic markets.
- Abemaciclib:Differentiates through continuous dosing regimens and adjuvant approvals. Manufacturing scale at Pfizer facilities supplies hospital formularies with extended-duration prescriptions.
- Others:Emerging CDK2 and CDK7 selective inhibitors from biotech pipelines. Investigator-initiated trials at United States academic centers test mechanistic hypotheses ahead of registrational studies.
Palbociclib commands the established base. The steepest expansion runs through abemaciclib adjuvant indications.
Application:
Oncology applications concentrate revenue in breast cancer, while hematology and research segments open differentiated pricing tiers based on evidence requirements.
- Oncology:Hormone receptor-positive breast cancer dominates prescription volume. Genomics-guided patient selection at United States cancer centers improves response rates and supports premium positioning against chemotherapy backbones.
- Hematology:Novartis leverages differentiated clinical positioning in myeloma and lymphoma applications. EMA conditional marketing authorizations in Europe require confirmatory survival data for full approval conversions.
- Research:Preclinical and clinical trial supply chains serve pharmaceutical sponsors and academic laboratories. Contract manufacturers in Asia produce active pharmaceutical ingredients for investigational programs.
- Others:Emerging solid tumor types including lung and gastrointestinal cancers. Brain metastasis indications with blood-brain barrier penetration data attract venture funding.
Oncology anchors current revenue pools. Research applications climb fastest as next-generation targets advance through translational pipelines.
End User:
Hospital networks consolidate purchasing authority through centralized pharmacy and therapeutics committees, displacing individual physician autonomy and compressing negotiation cycles.
- Hospitals:Integrated delivery networks in the United States demand real-world evidence packages at contract inception. Formulary committees now include pharmacy benefit managers in voting panels, tightening prior authorization requirements.
- Clinics:Community oncology practices face administrative burden from reimbursement compression. QT prolongation monitoring infrastructure limits ribociclib adoption in resource-constrained settings.
- Research Institutions:Academic medical centers anchor early adoption of next-generation CDK2 and CDK7 inhibitors through investigator-initiated trials. NIH-funded programs supply longitudinal data for regulatory submissions.
- Pharmacies:Specialty pharmacy distribution handles oral small-molecule dispensing. Cold chain requirements are minimal compared to biologics, simplifying logistics.
Hospitals control the volume base. Research institutions gain share fastest as translational programs expand.
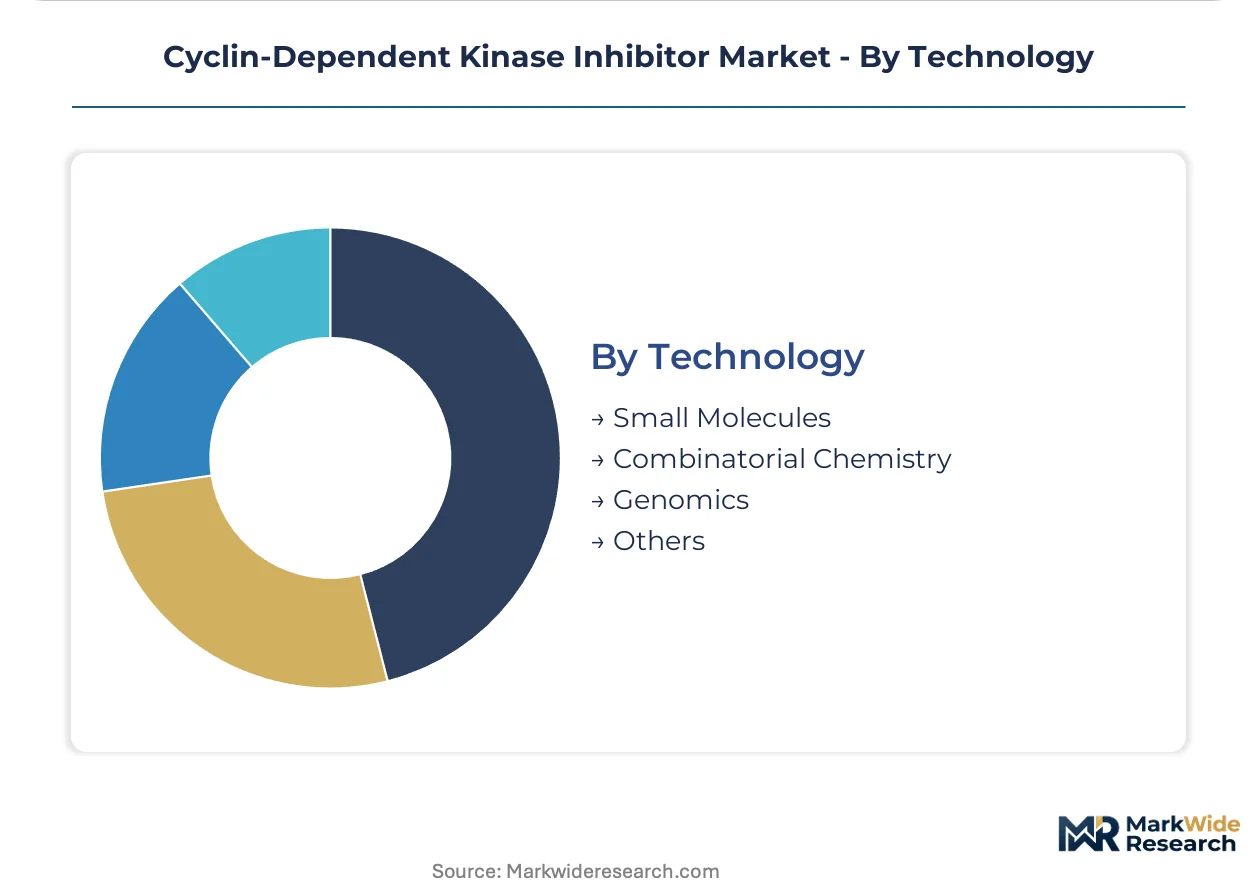
Technology:
Small molecule manufacturing economics dominate commercial production, while genomics and combinatorial approaches reshape which targets advance to clinical validation.
- Small Molecules:ATP-competitive inhibitors of CDK4/6 represent mature manufacturing platforms. Asian contract manufacturers concentrate active pharmaceutical ingredient production, creating single-site disruption vulnerabilities.
- Combinatorial Chemistry:Library screening approaches identify selective CDK2 and CDK7 scaffolds. Biotech sponsors partner with specialized CROs for adaptive trial design expertise.
- Genomics:Biomarker-driven patient stratification improves response rates and justifies premium pricing. FDA breakthrough therapy designation accelerates timelines for validated targets.
- Others:Protein degradation and covalent inhibitor modalities explore novel pharmacology. Preclinical mechanistic synergy with checkpoint blockade opens combination trial design space.
Small molecules hold the established manufacturing base. Genomics platforms expand most quickly as predictive biomarkers reshape trial enrollment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold chain infrastructure underwrites Europe's distribution role for temperature-sensitive oncology APIs, while Singapore's Changi air cargo hub anchors Asia-Pacific transit for clinical trial supplies.
United States
FDA accelerated approval pathways pull forward commercialization timelines for breakthrough CDK4/6 inhibitors in hormone receptor-positive breast cancer. The IRA's Medicare drug price negotiation provisions reshape payer contracting dynamics for mature oncology assets. Academic medical centers in Boston and Houston anchor clinical adoption through longitudinal oncology programs.
China
NMPA parallel review pathways for domestic innovators accelerate timelines for locally developed CDK inhibitors ahead of multinational patent cliffs. The country's dual carbon goals pressure energy-intensive API manufacturing facilities toward process intensification. Contract manufacturers in Jiangsu province concentrate small-molecule production for export markets.
Germany
EMA conditional marketing authorizations require confirmatory survival data for full approval conversions of CDK inhibitors in hematology applications. The EU Green Deal's pharmaceutical sustainability requirements reshape chemistry-manufacturing-controls documentation standards. Frankfurt's logistics cluster handles temperature-controlled distribution into Central and Eastern European markets.
Japan
PMDA's Sakigake designation accelerates access for innovative CDK2 and CDK7 selective inhibitors addressing unmet needs in refractory cancers. METI's pharmaceutical industry revitalization program subsidizes domestic manufacturing capacity for critical oncology APIs. The Kansai region's biotech cluster supports translational research partnerships between academic institutions and multinational sponsors.
Switzerland
Swissmedic's streamlined review procedures attract headquarters operations for companies developing next-generation cyclin-dependent kinase inhibitors. The country's bilateral recognition agreements with FDA and EMA reduce redundant facility inspection cycles. Basel's pharmaceutical research corridor concentrates medicinal chemistry expertise for selective CDK target modulation.
Cyclin-Dependent Kinase Inhibitor Market Competitive Environment
Listed leaders compete with private specialists across regulatory validation and manufacturing scale dimensions. The competitive structure concentrates around firms with established FDA track records and emerging entrants pursuing differentiated target selectivity. Three archetypes dominate: multinational pharmaceutical conglomerates with oncology portfolio depth, mid-cap biotech specialists in next-generation CDK targets, and Asian contract manufacturers supplying API capacity. Competitive moves center on adaptive trial design partnerships and multi-regional CMC harmonization investments.
Among the multinational tier, AstraZeneca, Pfizer, and Novartis occupy positions reflecting distinct strategic emphases. AstraZeneca exemplifies portfolio breadth across multiple CDK targets through sustained pipeline investment. Pfizer represents manufacturing scale advantages and established hospital formulary penetration. Novartis anchors a differentiated positioning in hematology applications where EMA conditional approvals create regulatory optionality.
| Leading Market Players |
|---|
| AstraZeneca |
| Merck |
| Pfizer |
| Gilead Sciences |
| Jiangsu Hengrui Pharmaceuticals |
| Novartis |
| Bristol Myers Squibb |
| Syros Pharmaceuticals |
| Eli Lilly and Company |
| Others |
Value Chain & Pricing Dynamics
Manufacturing scale at Pfizer's API facilities anchors cost structures across the CDK inhibitor landscape, concentrating supply-side leverage among producers with validated multi-regional chemistry-manufacturing-controls documentation. This scale concentration simultaneously elevates price floors for entrants lacking equivalent facility qualifications and compresses margins for contract manufacturers competing on volume.
Pricing Analysis
Volume-discount tiering structures dominate hospital procurement negotiations, with integrated delivery networks extracting graduated rebates based on annual prescription commitments. Pricing stratifies across premium branded CDK4/6 inhibitors, standard-of-care abemaciclib, and emerging economy-tier generics approaching patent cliffs. Cost compression in the standard tier intensifies as China's NMPA approvals for domestic innovators expand supply alternatives. Community oncology practices exhibit highest price sensitivity due to reimbursement compression and administrative burden, while academic medical centers prioritize clinical efficacy data over acquisition cost.
Supply Chain Analysis
Jiangsu province's API manufacturing cluster represents the dominant chokepoint for small-molecule CDK inhibitor production, with Changshu and Taizhou facilities supplying active pharmaceutical ingredients to Pfizer, Novartis, and AstraZeneca formulation sites. Synthesis draws from specialized pyridine and pyrimidine intermediate feedstocks concentrated in Zhejiang and Shandong provinces. Single-source vulnerability at select Asian contract manufacturers creates exposure to environmental compliance disruptions under China's dual carbon goals. Distribution runs through Rotterdam's pharmaceutical cold chain hub for European hospital networks and Singapore's Changi air cargo terminal for Asia-Pacific clinical trial supplies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital formulary consolidation into centralized pharmacy and therapeutics committees has shifted procurement leverage toward integrated delivery networks, fragmenting individual physician prescribing autonomy and compressing vendor negotiation cycles.
For Market Incumbents: Compound defensive moats through backward integration into API manufacturing capacity in Switzerland and Singapore, reducing exposure to Asian contract manufacturer concentration. Secure FDA breakthrough therapy designations for next-generation CDK2 and CDK7 selective inhibitors ahead of ribociclib patent cliffs. Deepen formulary penetration by embedding real-world evidence generation programs within academic medical center longitudinal oncology protocols. For New Entrants and Emerging Players: Anchor in brain metastasis indications where blood-brain barrier penetration data creates differentiation white space against entrenched CDK4/6 standards. Target China's NMPA parallel review pathways for domestic innovators, exploiting regulatory optionality before multinational patent expirations. Deploy investigator-initiated trial partnerships with NIH-funded academic programs as primary go-to-market mechanism for mechanistic validation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among mid-cap biotech specialists with selective CDK target pipelines and adaptive trial design CRO partnerships. Long-term viability over the next decade hinges on biomarker-driven patient stratification capabilities and multi-regional regulatory track records. Monitor FDA post-approval confirmatory trial withdrawal rates as inflection indicator for portfolio risk reassessment.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Trial Design Partnership | Specialized CRO expertise compresses confirmatory study timelines for CDK inhibitors facing FDA withdrawal mechanisms. |
| Multi-Regional CMC Harmonization | Unified FDA-EMA-NMPA facility qualifications reduce redundant inspection cycles and accelerate supply chain qualification. |
| Biomarker Platform Investment | Genomics-guided patient selection improves response rates and supports premium positioning against chemotherapy backbones. |
| Adjuvant Indication Expansion | Extended treatment protocols in early-stage breast cancer multiply prescription volumes per patient at academic medical centers. |
| China NMPA Parallel Review | Domestic innovator pathways enable first-mover positioning ahead of multinational CDK inhibitor patent cliffs. |
Study Parameters
The analysis maps CDK4/6 inhibitor commercialization pathways, next-generation CDK2/CDK7 selective inhibitors, and adjuvant expansion protocols, each validated through primary interviews with drug development executives, regulatory affairs leads, hospital formulary directors, and payer access specialists. Secondary sources include FDA accelerated approval filings, EMA conditional marketing authorization submissions, ClinicalTrials.gov protocol registries, and hospital procurement database extracts. Bottom-up prescription volume modeling triangulates against top-down manufacturer revenue disclosures.
Consistency checks validated volume and value outputs against external benchmarks including formulary placement rates at integrated delivery networks and API production capacity disclosures from Asian contract manufacturers. Segmentation dimensions span product type, application across oncology and hematology, end-user archetype, and technology platform. CAGRs derive from patent cliff modeling, biosimilar entry assumptions, and genomics-guided adoption curve projections across the analysis window. Industry-specific inputs incorporate QT prolongation monitoring infrastructure penetration and Medicare drug price negotiation provision impacts.
Decision-makers should treat outputs as directional under base assumptions of sustained FDA accelerated approval pathway access and stable NMPA reform momentum; material deviation in confirmatory trial success rates or reimbursement compression severity would warrant model refresh. Practitioners should keep alternative scenarios live as post-approval withdrawal mechanisms and payer prior authorization requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Medroxyprogesterone Market
Medical Biotechnology
Cellular Epigenetics Market
Medical Biotechnology
RNA Interference (Rnai) Drug Delivery Market
Medical Biotechnology
Global Diagnostic Specialty Enzymes Market
Medical Biotechnology
Immortalized Cell Line Market
Medical Biotechnology
Balantidiasis Market
Medical Biotechnology
Alcohol Dehydrogenase Enzymes Market
Medical Biotechnology
Global Antisense and Rnai Therapeutics Market
Medical Biotechnology
Amoxicillin Market
Medical Biotechnology
Myoglobin Market
Medical Biotechnology
Antimicrobial Peptides Market
Medical Biotechnology
Cancer Antigens Market
Medical Biotechnology
Myeloproliferative Disorders Drugs Market
Medical Biotechnology
Smart Drug Discovery Market
Medical Biotechnology
Cell and Tissue Preservation Market
Medical Biotechnology
Mecobalamin Injection Market