
 Insulinoma Market | 2026-2036
Insulinoma Market Size, Share, and Industry Trends Forecast 2026-2036
Insulinoma Market Foresight
Aftermarket service revenue from surgical device maintenance and radiopharmaceutical handling protocols is reconfiguring how manufacturers capture lifetime value across the insulinoma care pathway. Novartis leverages its radiolabeled therapy portfolio to anchor supply relationships with specialized cancer centers performing peptide receptor radionuclide therapy. Pfizer sustains competitive presence through broad chemotherapeutic formulations that clinicians deploy in unresectable cases. Medtronic dominates surgical navigation and ablation technologies that endocrinology-oncology teams employ during pancreatic resections.
Insulinoma denotes a rare functional pancreatic neuroendocrine tumor arising from insulin-secreting beta cells, typically measuring under 2 cm in diameter, characterized by Whipple's triad of hypoglycemic symptoms, documented low plasma glucose, and symptom resolution upon glucose administration. The tumor's autonomous insulin secretion drives its primary clinical purpose: identification and elimination of life-threatening hypoglycemia sources through surgical excision or medical management when metastasis precludes resection. Chemotherapeutics and targeted therapy segments carry mature margin profiles where generic competition has compressed pricing, while radiolabeled therapy represents the fastest-expanding category as lutetium-based agents gain therapeutic guidelines endorsement. Surgical intervention retains volume leadership in localized disease, though delivery mode preferences increasingly favor intravenous administration for systemic approaches over subcutaneous alternatives in hospital settings.
The FDA's orphan drug program shapes development economics by granting seven-year market exclusivity and tax incentives for insulinoma-targeted therapies, while EMA's parallel designation streamlines European access for radiopharmaceutical innovators. ISO 13485 quality management standards govern surgical instrument and implantable device manufacturing, directly affecting product certification timelines for Boston Scientific Corporation and Medtronic. Stakeholders must monitor evolving NCCN guideline revisions that redefine first-line therapy hierarchies between surgical resection and systemic approaches, as these determinations redirect procurement budgets across outpatient clinics and specialized cancer centers.
Market Dynamics
The orphan drug designation pathway is concentrating development economics for insulinoma therapeutics, with FDA and EMA incentives redirecting R&D investment toward radiolabeled therapy platforms and away from mature chemotherapeutic categories where generic erosion has compressed returns.
Growth Catalysts
- Peptide receptor radionuclide therapy expansion:Lutetium-based agents are gaining NCCN guideline endorsement for unresectable neuroendocrine tumors, expanding addressable patient populations beyond surgical candidates.
- Hospital infrastructure investment:Specialized cancer centers in the United States are building dedicated radiopharmaceutical handling facilities to support same-day therapy administration.
- ISO 13485 certification harmonization:Streamlined quality management standards are accelerating surgical instrument and implantable device approval timelines for pancreatic resection procedures.
Market Restraints
- Isotope supply concentration:Lutetium-177 production depends on a limited number of nuclear reactors, creating geographic supply vulnerability concentrated in European and North American facilities.
- Technical detection limitations:Sub-centimeter insulinomas evade conventional imaging modalities, delaying definitive diagnosis and compressing the window for curative surgical intervention.
- Substitution pressure from medical management:Diazoxide and somatostatin analogs provide symptomatic control that defers surgical referral in frail patient populations.
Strategic Opportunities
- Underpenetrated European markets:France and Germany lack the referral network density seen in US pancreatic neuroendocrine tumor centers, creating whitespace for specialized clinic development.
- Ga-68 DOTATATE imaging convergence:Positron emission tomography paired with computed tomography is improving lesion localization precision, enabling minimally invasive surgical planning.
- Aftermarket service unbundling:Surgical device manufacturers are capturing lifetime value through maintenance contracts and radiopharmaceutical handling protocol training rather than upfront equipment sales alone.
Industry Challenges
- Nuclear medicine specialist scarcity:Radiopharmaceutical therapy administration requires board-certified practitioners with specific isotope handling credentials that training programs produce insufficiently.
- Cross-border licensing complexity:Orphan drug exclusivity terms differ between FDA seven-year and EMA ten-year frameworks, complicating parallel market entry strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulinoma Market |
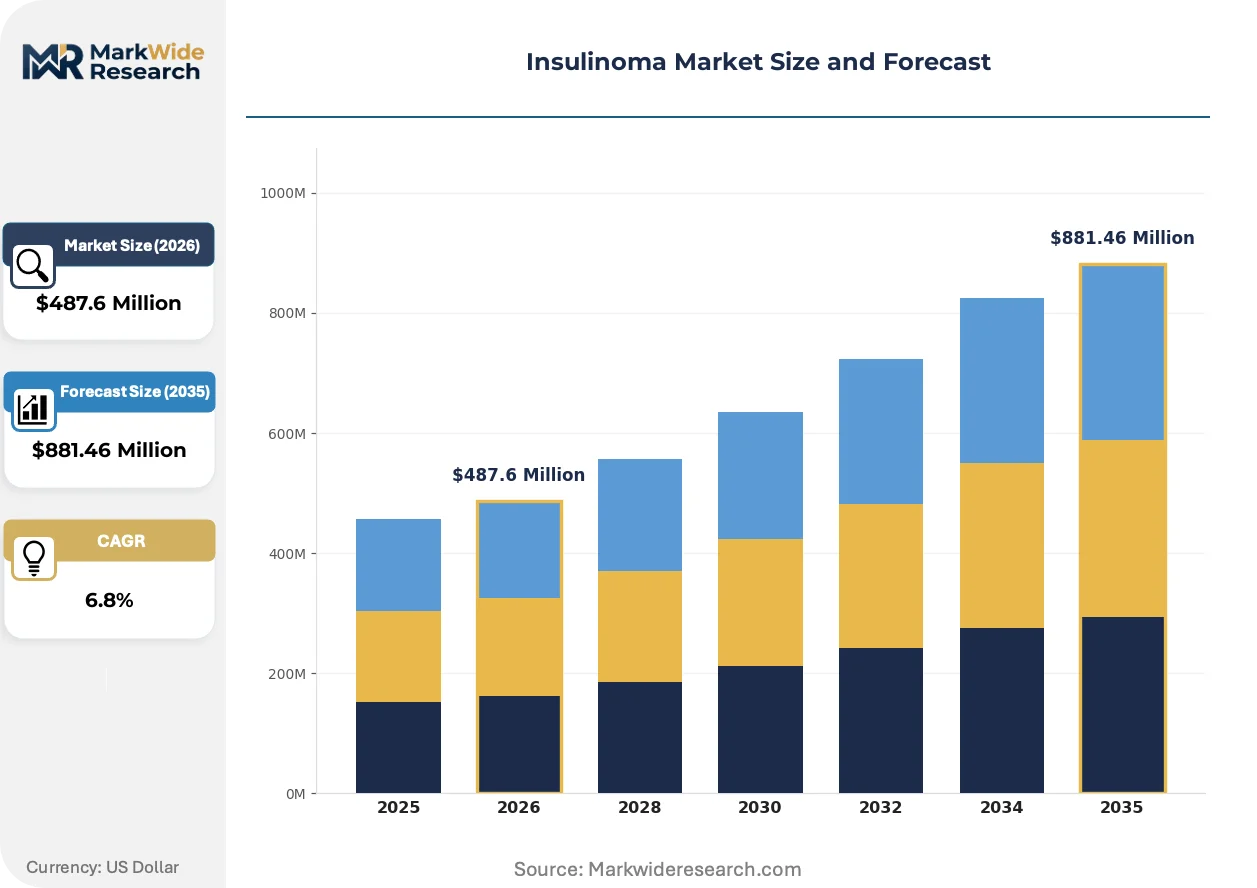
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapeutics, Targeted Therapy, Radiolabeled Therapy, Surgical Intervention Care Setting: Outpatient Clinics, Hospitals, Specialized Cancer Centers, Home Care End User: Oncologists, Endocrinologists, Surgeons, General Practitioners Delivery Mode: Oral, Injectable, Intravenous, Subcutaneous |
| Companies Covered | Novartis, Pfizer, Ipsen Pharma, Teva Pharmaceutical Industries, Medtronic, Boston Scientific Corporation, Abcam, Roche, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulinoma Market Shifts & Advancements
Digital pathology integration and radiopharmaceutical manufacturing automation are compressing diagnostic-to-treatment intervals while regulatory harmonization efforts reshape competitive positioning across the insulinoma care pathway.
Ga-68 DOTATATE positron emission tomography is digitizing lesion detection workflows by replacing conventional somatostatin receptor scintigraphy with higher-resolution functional imaging. Endocrinology-oncology teams at tertiary referral centers are adopting this platform within twelve-to-eighteen-month procurement cycles. The technology is digitizing surgical planning by enabling three-dimensional tumor mapping that reduces operative time and pancreatic tissue loss.
EMA's Medical Device Regulation is imposing stricter clinical evidence requirements on surgical navigation systems used during pancreatic resections. Manufacturers must now submit prospective performance data rather than predicate device equivalency. Class III device categories face extended notified body review timelines, compressing product launch windows for European market entry.
Academic medical centers are consolidating insulinoma referrals into designated centers of excellence, compressing the traditional community-hospital-to-tertiary transfer pathway. This concentration is displacing dispersed general surgery departments from complex pancreatic procedures. The United States exhibits the most pronounced referral consolidation, with Medicare reimbursement differentials reinforcing volume-to-outcome incentives.
Insulinoma Market Segmentation
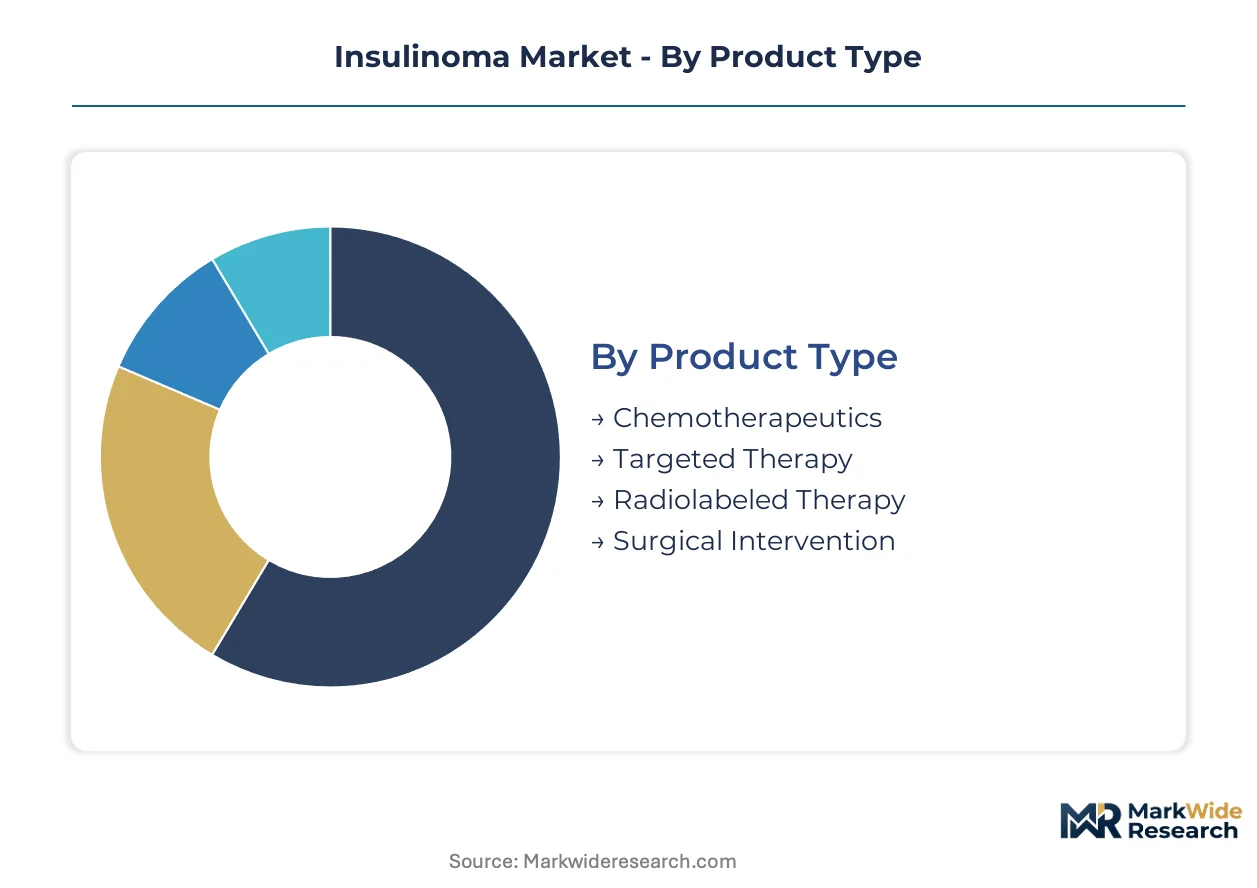
Segmentation in the insulinoma market reveals divergent procurement cycles across therapeutic modalities, with surgical equipment refresh timelines stretching years while radiopharmaceutical dosing operates on weekly replenishment rhythms. Understanding these temporal patterns enables manufacturers to align inventory strategies with clinical workflow realities.
Product Type:
Cycle times vary dramatically across therapeutic categories, with surgical instruments requiring capital budget cycles while radiolabeled agents demand just-in-time supply chains.
- Surgical Intervention:Enucleation and partial pancreatectomy procedures utilizing electrocautery devices, laparoscopic staplers, and intraoperative ultrasound probes. Hospital procurement committees in the United States dominate equipment acquisition, constrained by OR block scheduling limitations and sterilization throughput capacity.
- Radiolabeled Therapy:Lutetium-177 DOTATATE and yttrium-90 based peptide receptor radionuclide therapy agents requiring cyclotron or reactor-produced isotopes. Specialized cancer centers in Germany and the United States concentrate demand, driven by NCCN guideline upgrades and EMA marketing authorization expansions.
- Targeted Therapy:Everolimus and sunitinib formulations addressing mTOR and tyrosine kinase pathways in unresectable disease.
- Chemotherapeutics:Streptozocin and temozolomide regimens for aggressive tumor phenotypes, facing generic substitution pressure.
Surgical intervention anchors the volume base while radiolabeled therapy gains share at the steepest rate.
Care Setting:
Cost tier stratification separates capital-intensive hospital infrastructure from lean outpatient delivery models.
- Hospitals:Tertiary medical centers with 24-hour endocrinology coverage and on-site nuclear medicine capabilities. Medicare reimbursement differentials in the United States reinforce inpatient admission for complex pancreatic resections.
- Specialized Cancer Centers:Designated neuroendocrine tumor programs with consolidated multidisciplinary teams and dedicated radiopharmaceutical handling suites. France and the United States lead facility development, constrained by isotope supply logistics and shielded room construction costs.
- Outpatient Clinics:Community endocrinology practices managing stable patients on somatostatin analogs.
- Home Care:Subcutaneous octreotide administration and glucose monitoring for palliative hypoglycemia control.
Hospitals capture the highest per-procedure revenue while specialized cancer centers expand their patient throughput most aggressively.
End User:
Customer type specialization determines prescribing authority and device utilization patterns across the care pathway.
- Surgeons:Hepatopancreatobiliary specialists performing enucleation, distal pancreatectomy, or Whipple procedures. Academic medical centers in the United States concentrate surgical volume, with Medicare's volume-to-outcome metrics reshaping referral patterns.
- Endocrinologists:Diagnostic gatekeepers managing Whipple's triad workup, 72-hour supervised fast protocols, and preoperative medical optimization. Community practice penetration varies by region, with the United States showing higher specialist density than European markets.
- Oncologists:Medical oncology teams selecting systemic therapy sequences for metastatic disease.
- General Practitioners:Frontline recognition of hypoglycemic symptoms and initial glucose management.
Surgeons command the highest per-case economic value while endocrinologists drive the greatest diagnostic referral volume.
Delivery Mode:
Application requirements dictate route selection, with tumor location and urgency determining administration pathway.
- Intravenous:Radiolabeled therapy infusion and emergency dextrose administration requiring vascular access and cardiac monitoring. Hospital-based administration dominates, with EMA's Good Manufacturing Practice standards governing radiopharmaceutical preparation protocols.
- Injectable:Somatostatin analog depot formulations and intraoperative methylene blue injection for lesion localization. Outpatient clinic administration in the United States concentrates demand, supported by specialty pharmacy distribution networks.
- Oral:Diazoxide and corticosteroid tablets for chronic hypoglycemia suppression.
- Subcutaneous:Patient-administered octreotide for symptom control between hospital visits.
Intravenous administration commands the highest reimbursement intensity while injectable formulations sustain the broadest patient reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for insulinoma therapeutics diverge sharply between mature markets with established referral networks and emerging regions where diagnostic infrastructure lags. The United States concentrates radiolabeled therapy adoption while European markets fragment across national reimbursement schemes. Hospital infrastructure investment and specialist training density determine regional penetration rates.
United States
Medicare reimbursement differentials and NCCN guideline endorsements accelerate peptide receptor radionuclide therapy uptake at tertiary centers. FDA orphan drug exclusivity provisions incentivize Novartis and Ipsen to prioritize US market entry sequences. The Mayo Clinic Rochester and MD Anderson Houston anchor specialized neuroendocrine tumor referral networks that consolidate surgical volume.
Germany
EMA marketing authorizations for lutetium-based agents preceded US approvals, establishing Heidelberg and Munich as early radiopharmaceutical therapy hubs. The country's statutory health insurance system mandates cost-effectiveness assessments that delay novel therapy access versus private-pay markets. Baden-Württemberg and Bavaria concentrate cyclotron infrastructure for isotope production.
France
ANSM regulatory frameworks govern radiopharmaceutical handling protocols that limit therapy site expansion outside Paris and Lyon academic centers. The national cancer plan designates reference centers for rare endocrine tumors, compressing referral pathways from community hospitals. Île-de-France dominates Ga-68 DOTATATE imaging installation density.
United Kingdom
NICE technology appraisals impose incremental cost-effectiveness thresholds that restrict systemic therapy access in metastatic disease cases. NHS England specialist commissioning concentrates insulinoma surgery at Royal Free London and Oxford University Hospitals. The UK lags continental Europe in radiopharmaceutical manufacturing capacity.
Japan
PMDA accelerated approval pathways for orphan diseases compress development timelines for domestic radiolabeled therapy candidates. METI funding supports nuclear medicine specialist training programs addressing practitioner scarcity. Tokyo and Osaka medical districts concentrate the country's limited peptide receptor radionuclide therapy administration sites.
Insulinoma Market Competitive Landscape
Capability concentration sits with radiopharmaceutical innovators possessing isotope supply relationships; scale advantage sits with diversified surgical device manufacturers with established hospital contracting networks. The market structures around three archetypes: radiolabeled therapy specialists with cyclotron partnerships, broad oncology portfolio holders with chemotherapeutic legacies, and surgical navigation technology providers. Competitive moves center on aftermarket service unbundling and radiopharmaceutical handling protocol certification programs rather than upfront equipment sales.
Among Swiss-based pharmaceutical conglomerates, Novartis anchors the radiolabeled therapy tier through its lutetium-based agent portfolio. Pfizer occupies a position exemplifying the diversified oncology archetype with broad chemotherapeutic formulations deployed in unresectable cases. Medtronic represents the surgical technology tier, dominating navigation and ablation systems that endocrinology-oncology teams employ during pancreatic resections.
| Leading Market Players |
|---|
| Novartis |
| Pfizer |
| Ipsen Pharma |
| Teva Pharmaceutical Industries |
| Medtronic |
| Boston Scientific Corporation |
| Abcam |
| Roche |
| Sanofi |
| Others |
Supply & Pricing Matrix
Heidelberg and Munich radiopharmaceutical clusters anchor European isotope production capacity, concentrating downstream pricing power among cyclotron-equipped centers that handle lutetium-based therapy preparation. This geographic concentration lets specialized cancer centers command premium reimbursement rates while peripheral hospitals face cost compression from isotope logistics and shielded facility requirements.
Pricing Analysis
Long-term offtake agreements dominate radiolabeled therapy procurement, with specialized cancer centers locking multi-year isotope supply contracts to secure lutetium-177 allocation against spot-market volatility. Price differentiation rests on GMP certification tier and after-sales radiopharmaceutical handling training bundled into therapy administration packages. Cost compression in chemotherapeutic generics is intensifying because patent expirations have opened streptozocin and temozolomide to multi-source competition. Outpatient clinics on diazoxide maintenance show highest price sensitivity, while tertiary centers pursuing peptide receptor radionuclide therapy expansion absorb premium pricing for isotope security.
Supply Chain Analysis
Contract manufacturing for surgical navigation systems concentrates with Medtronic and Boston Scientific in-house production facilities, while radiopharmaceutical synthesis relies on specialized CMOs with cyclotron infrastructure. Isotope supply draws from nuclear reactors in the Netherlands, Belgium, and South Africa, with lutetium-177 production tethered to limited high-flux research reactor capacity. Single-source vulnerability runs through the handful of facilities capable of pharmaceutical-grade isotope production. Distribution runs through cold-chain logistics networks with radiation shielding requirements that limit handler certification pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
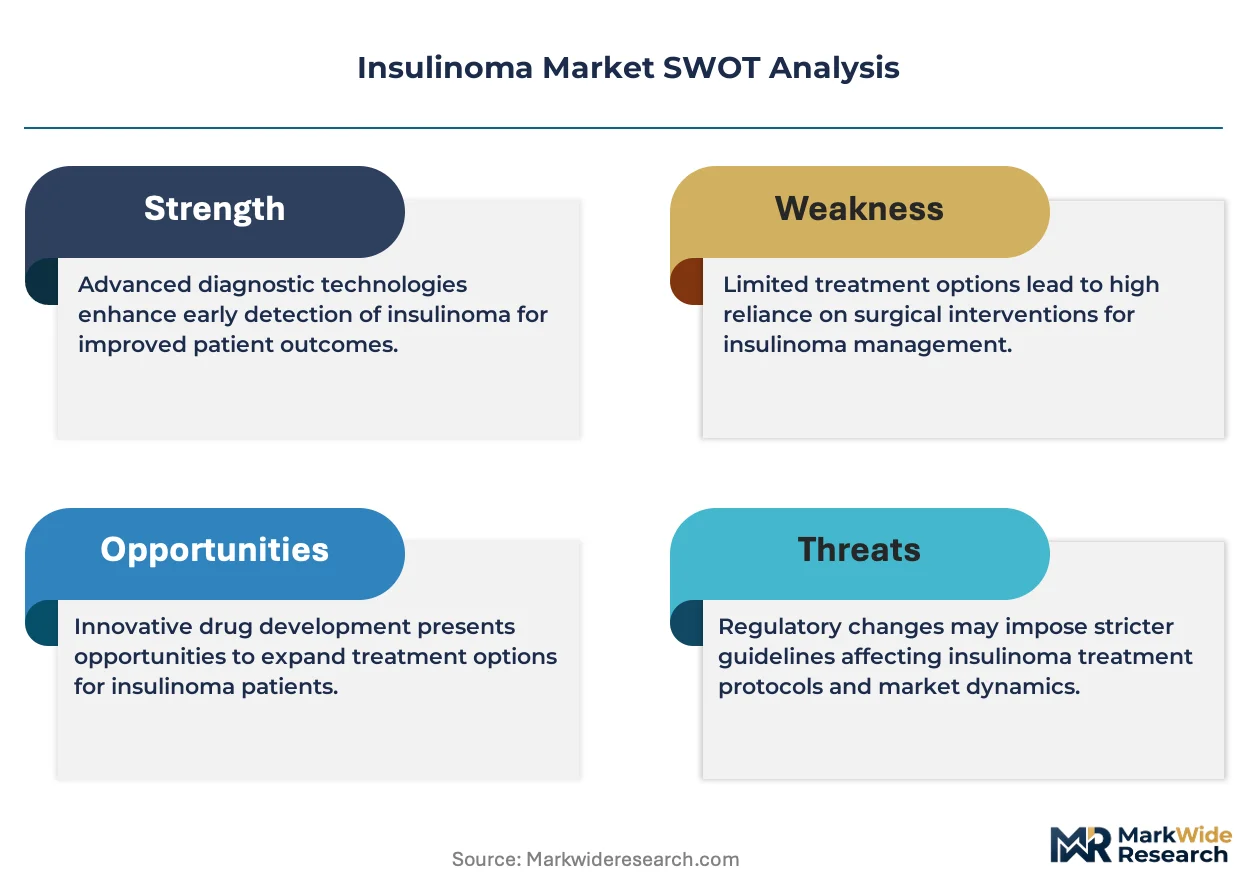
The insulinoma therapeutic landscape builds defensive moats through regulatory entrenchment: FDA orphan drug exclusivity and EMA parallel designation create seven-to-ten-year barriers that compound with nuclear medicine specialist scarcity to protect incumbent positions.
For Market Incumbents: Entrench cyclotron partnerships through exclusive isotope supply agreements that preempt competitor radiopharmaceutical manufacturing capacity. Add shielded therapy suites in Baden-Württemberg and Bavaria to capture German statutory insurance reimbursement before cost-effectiveness assessments tighten. Counter substitution pressure from diazoxide medical management by embedding surgical navigation systems into hospital GPO contracts with multi-year maintenance lock-in. For New Entrants and Emerging Players: Pursue Ga-68 DOTATATE imaging convergence as the most penetrable entry vector, targeting French and UK centers where PET-CT installation lags German and US density. White-space exists in automated radiopharmaceutical compounding systems that reduce nuclear medicine specialist dependency. Go-to-market through EMA notified body relationships that accelerate Class III device review timelines under Medical Device Regulation clinical evidence requirements. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because orphan drug designation pathways and isotope handling licensing create compounding barriers to replication. Acquisition targets should screen for cyclotron access agreements or ISO 13485-certified surgical device manufacturing footprints. Watch NCCN guideline revision timing as the inflection signal that redirects procurement budgets between surgical resection and systemic therapy hierarchies.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pathway | FDA seven-year exclusivity accelerates Novartis lutetium-based therapy commercialization timelines. |
| Ga-68 DOTATATE Imaging Deployment | PET-CT convergence enables three-dimensional tumor mapping that reduces operative tissue loss. |
| Hospital System Partnership | GPO contracting with Mayo Clinic and MD Anderson consolidates surgical navigation device procurement. |
| Radiopharmaceutical Handling Certification | EMA Good Manufacturing Practice training programs limit competitor technician pool expansion. |
| CE Marking Pathway | Medical Device Regulation clinical evidence requirements extend review timelines for surgical navigation systems. |
Research Methodology
Initial hypotheses were tested against primary input from nuclear medicine specialists, hepatopancreatobiliary surgeons, endocrinology-oncology directors, hospital procurement managers, and formulary access leads, then refined against secondary validation from FDA orphan drug filings, EMA marketing authorization submissions, ClinicalTrials.gov protocol registries, NCCN guideline revision archives, and CMS Medicare reimbursement databases. Bottom-up patient-flow modeling and top-down therapeutic category spend analysis were triangulated to converge volume estimates.
Demand-supply balance framing anchored the forecast framework, with patient incidence rates, surgical candidacy eligibility, and radiopharmaceutical therapy capacity constraints modeled across the projection horizon. Segmentation dimensions included therapeutic modality, care setting infrastructure tier, end-user specialty, and delivery mode administration route. CAGRs were derived from therapy adoption curve analysis and reimbursement trajectory assessment, with isotope supply availability and specialist training pipeline throughput as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement rates, statutory health insurance cost-effectiveness thresholds, or nuclear reactor maintenance schedules would shift the trajectory. Forecasts reflect assumptions about guideline endorsement timing and regulatory harmonization progress that carry revision risk from clinical trial readouts or orphan drug policy changes. Cross-checking against hospital capital expenditure surveys and radiopharmaceutical manufacturing capacity announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Beta Thalassemia Testing Market
Medical Biotechnology
Myoglobin Market
Medical Biotechnology
Ornithine Transcarbamylase (OTC) Deficiency Treatment Market
Medical Biotechnology
Leprosy Vaccines Market
Medical Biotechnology
Global Preimplantation Genetic Diagnosis (PGD) Market
Medical Biotechnology
Insulin Management System Market
Medical Biotechnology
Mitochondrial Myopathies Market
Medical Biotechnology
X-Linked Hypophosphatemia Market
Medical Biotechnology
Human Placental Protein Market
Medical Biotechnology
Recombinant Human Endostatin Market
Medical Biotechnology
Myeloproliferative Disorders Drugs Market
Medical Biotechnology
Asparaginase Market
Medical Biotechnology
Nanomedicine Market
Medical Biotechnology
Global Ornithine-Transcarbamylase Deficiency Market
Medical Biotechnology
Cell Culture Market
Medical Biotechnology
Medroxyprogesterone Market