
 Fluidized-Bed Bioreactors Market | 2026-2036
Fluidized-Bed Bioreactors Market Size, Share, and Industry Trends Forecast 2026-2036
Fluidized-Bed Bioreactors Market Analytics
The capital-intensity gap between stainless-steel and single-use fluidized-bed systems is collapsing as modular designs reduce upfront facility investment. Sartorius leverages its polymer science expertise to dominate disposable bioreactor supply for contract manufacturing organizations. Procedyne anchors the high-pressure thermal processing niche with alloy fabrication capabilities that few competitors replicate.
Fluidized-bed bioreactors suspend particulate biocatalysts in upward-flowing liquid or gas streams, achieving mass transfer coefficients of 0.1–1.0 s⁻¹ that enable high-cell-density fermentation for monoclonal antibody production. Continuous flow technology leads in commercial adoption because perfusion modes yield higher volumetric productivity than batch alternatives. Anaerobic configurations represent the fastest-expanding product category, driven by biomethane upgrading and industrial wastewater treatment applications where oxygen exclusion determines process economics.
FDA process analytical technology guidelines and EMA good manufacturing practice standards for biologics production mandate validated control systems that fluidized-bed vendors must embed. China's NMPA biologics approval pathway and India's CDSCO manufacturing licensing requirements are tightening equipment qualification protocols across Asian supply chains. Stakeholders must weigh single-use against stainless-steel platform commitments before facility designs lock in decade-long operating cost structures.
Market Dynamics
Continuous processing mandates from FDA process analytical technology guidelines are compressing batch-to-perfusion conversion timelines across biologics manufacturing facilities.
Growth Catalysts
- EMA Good Manufacturing Practice Standards:Biologics production protocols now require validated control systems that fluidized-bed configurations embed natively, accelerating equipment qualification cycles.
- Cell Culture Intensification:High-cell-density fermentation for monoclonal antibody production achieves mass transfer coefficients of 0.1–1.0 s⁻¹ in suspended particulate systems, outperforming stirred-tank alternatives.
- Germany's Biomanufacturing Expansion:Contract manufacturing organizations in Baden-Württemberg and Bavaria are replacing stainless-steel trains with modular single-use fluidized-bed platforms.
Market Restraints
- Specialized Alloy Fabrication Bottlenecks:High-pressure thermal processing vessels require nickel-based superalloy welding capabilities concentrated in fewer than twelve qualified fabricators globally.
- Polymer Supply Concentration:Single-use bioreactor film supply chains anchor in German and US polymer science clusters, creating vulnerability to specialty resin allocation disruptions.
- Stainless-Steel Sunk Cost Inertia:Existing validated facilities face decade-long depreciation cycles that deter platform migration despite operating cost differentials.
Strategic Opportunities
- Biomethane Upgrading Applications:Anaerobic fluidized-bed configurations for industrial wastewater treatment remain underdeployed in US municipal utility markets.
- China's NMPA Biologics Pathway:Tightening equipment qualification protocols across Asian supply chains create first-mover advantage for pre-qualified system vendors.
- Perfusion-Digital Twin Convergence:Real-time sensor integration with predictive process control is opening continuous manufacturing service contracts.
Industry Challenges
- ASME Bioprocessing Equipment Certification Timelines:Pressure vessel qualification for high-cell-density applications extends facility commissioning by fourteen to eighteen months.
- Legacy Distributed Control System Integration:Brownfield sites face protocol translation complexity when embedding modern fluidized-bed skids into Siemens or Rockwell automation architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluidized-Bed Bioreactors Market |
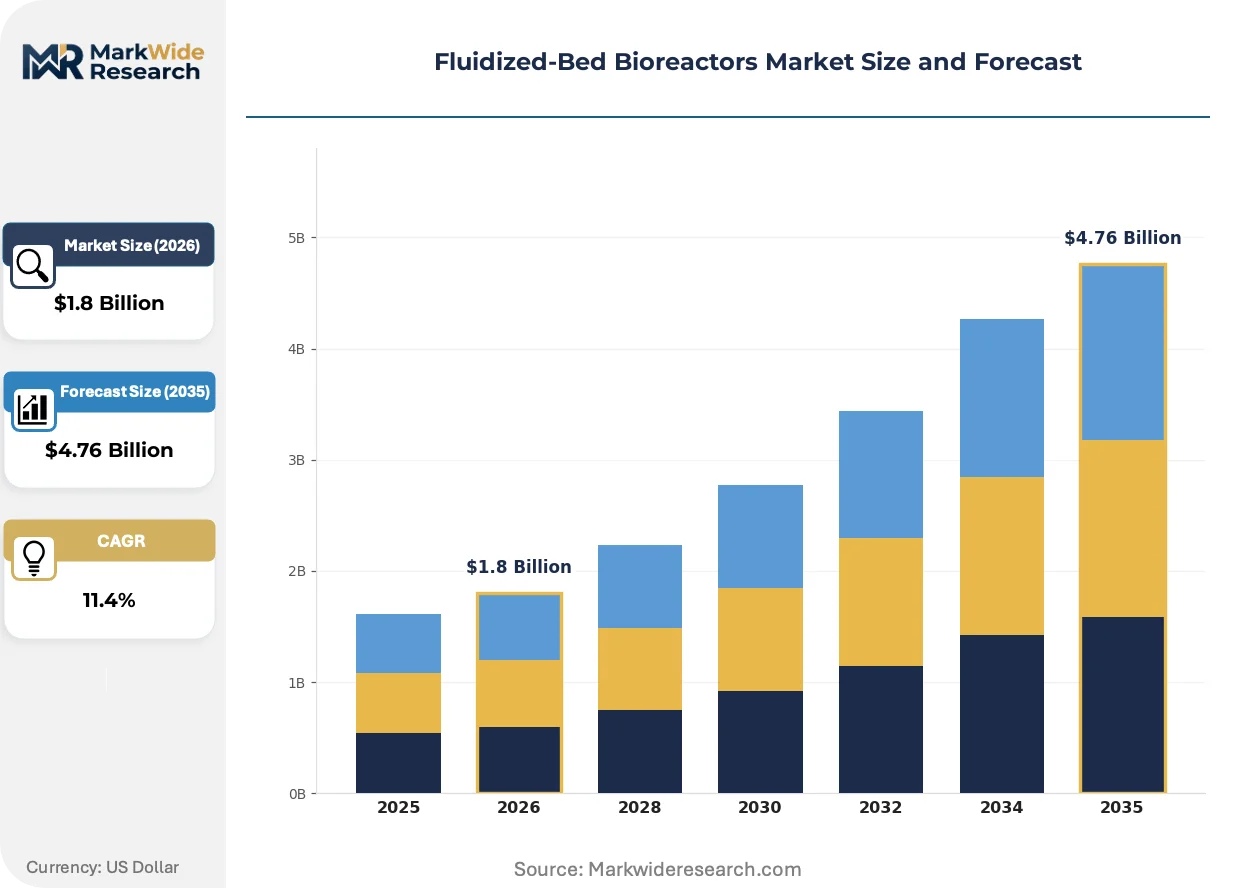
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stirred Tank, Aerobic, Anaerobic, Hybrid Technology: Continuous Flow, Batch Process, Semi-Batch, Multi-Stage End User: Pharmaceuticals, Biotechnology, Food & Beverage, Environmental Application: Bioprocessing, Wastewater Treatment, Biofuel Production, Bioremediation |
| Companies Covered | Procedyne, Soldo Cavitators, Surface Combustion, Sartorius, BP Littleford, Albertus Energy, Masterinox, Amar Equipments, Parr Instrument Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluidized-Bed Bioreactors Market Evolving Landscape
Single-use polymer science advances are collapsing the capital-intensity gap between disposable and stainless-steel platforms, reshaping facility investment calculus.
Modular skid-mounted fluidized-bed systems are displacing centralized stainless-steel infrastructure in greenfield biologics facilities. Pharmaceutical manufacturers in Massachusetts and North Carolina are specifying plug-and-process units with six-month deployment horizons. This architecture is displacing traditional stick-built facility approaches that require thirty-six-month construction cycles.
REACH chemical registration requirements for polymer contact materials are tightening extractables and leachables documentation burdens. European contract manufacturers now demand comprehensive migration testing data before single-use system qualification. Germany and Switzerland anchor this regulatory stringency, with EMA guidance documents driving harmonized compliance investment across continental supply chains.
Service-unbundling from equipment procurement is compressing vendor-customer relationships toward performance-based operating agreements. Biologics manufacturers in the United States are separating capital acquisition from process validation responsibility, shifting risk to equipment suppliers. This restructuring concentrates in CDMO segments where facility utilization volatility demands variable cost structures.
Fluidized-Bed Bioreactors Market Segmentation
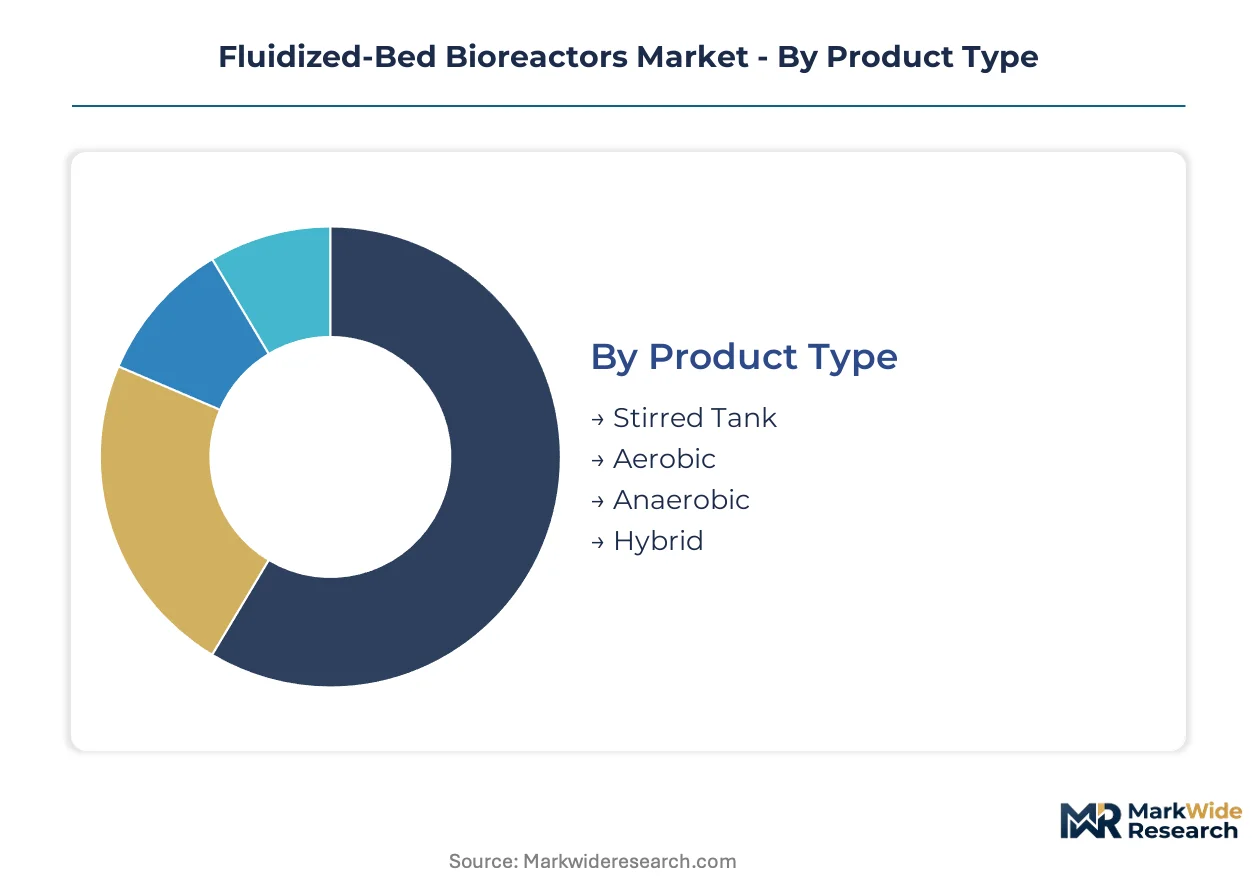
Fluidized-bed bioreactor purchasing decisions split across four distinct dimensions, each carrying different qualification burdens and margin structures. Regulatory pathways, process economics, and facility infrastructure constraints determine which segmentation axis dominates vendor selection in specific deployment contexts.
Product Type:
FDA process analytical technology guidelines and EMA good manufacturing practice standards impose divergent validation requirements across aerobic versus anaerobic configurations, reshaping procurement patterns in biologics versus industrial applications.
- Stirred Tank:Mechanical agitation systems dominate legacy pharmaceutical installations with validated control architectures. Massachusetts and North Carolina biologics manufacturers favor these configurations for monoclonal antibody production where process transfer from development to commercial scale demands minimal protocol revision.
- Aerobic:Oxygen-enriched fluidization achieves the 0.1–1.0 s⁻¹ mass transfer coefficients required for high-cell-density fermentation. Contract manufacturing organizations in Baden-Württemberg specify aerobic systems for perfusion-based continuous processing, aligning with EMA biologics production mandates.
- Anaerobic:Oxygen-excluded configurations serve biomethane upgrading and industrial wastewater treatment applications where methanogenic consortia determine yield economics.
- Hybrid:Dual-mode systems switch between aerobic and anaerobic operation, enabling multi-product facilities to repurpose single infrastructure across process types.
Established volume favors stirred tank; emerging adoption favors anaerobic.
Technology:
Capital deployment timelines stretch from six months for skid-mounted continuous units to thirty-six months for stick-built batch infrastructure, compressing technology selection into facility financing decisions.
- Continuous Flow:Perfusion-mode operation yields higher volumetric productivity than batch alternatives through real-time cell retention and nutrient refresh. Sartorius and Procedyne anchor supply for continuous systems, with polymer science and alloy fabrication capabilities respectively.
- Batch Process:Discrete-cycle operation retains dominance in validated stainless-steel facilities where decade-long depreciation cycles deter platform migration despite operating cost differentials.
- Semi-Batch:Fed-batch configurations balance operational simplicity with partial continuous nutrient addition, serving mid-scale bioprocessing where full perfusion economics do not close.
- Multi-Stage:Cascaded reactor arrays enable substrate gradient control for complex metabolic pathways, finding application in biofuel production where product inhibition limits single-vessel yields.
Batch process retains installed base dominance; continuous flow is climbing the fastest.
End User:
Customer concentration varies sharply across segments, with pharmaceutical procurement consolidating through contract manufacturing organizations while environmental applications fragment across municipal utilities.
- Pharmaceuticals:Monoclonal antibody manufacturers drive specification stringency, requiring ASME bioprocessing equipment certification and fourteen-to-eighteen-month qualification timelines. China's NMPA tightening of equipment protocols is accelerating vendor pre-qualification investment.
- Biotechnology:Cell and gene therapy developers favor single-use fluidized-bed platforms for process flexibility, with modular designs reducing upfront facility investment.
- Food & Beverage:Enzyme production and fermentation applications prioritize hygienic design over pharmaceutical-grade validation, opening supply to mid-tier equipment vendors.
- Environmental:Municipal wastewater treatment operators and industrial effluent processors deploy anaerobic configurations for biomethane recovery, with US utility markets remaining underpenetrated relative to European adoption.
Pharmaceuticals command specification leadership; environmental is gaining share fastest.
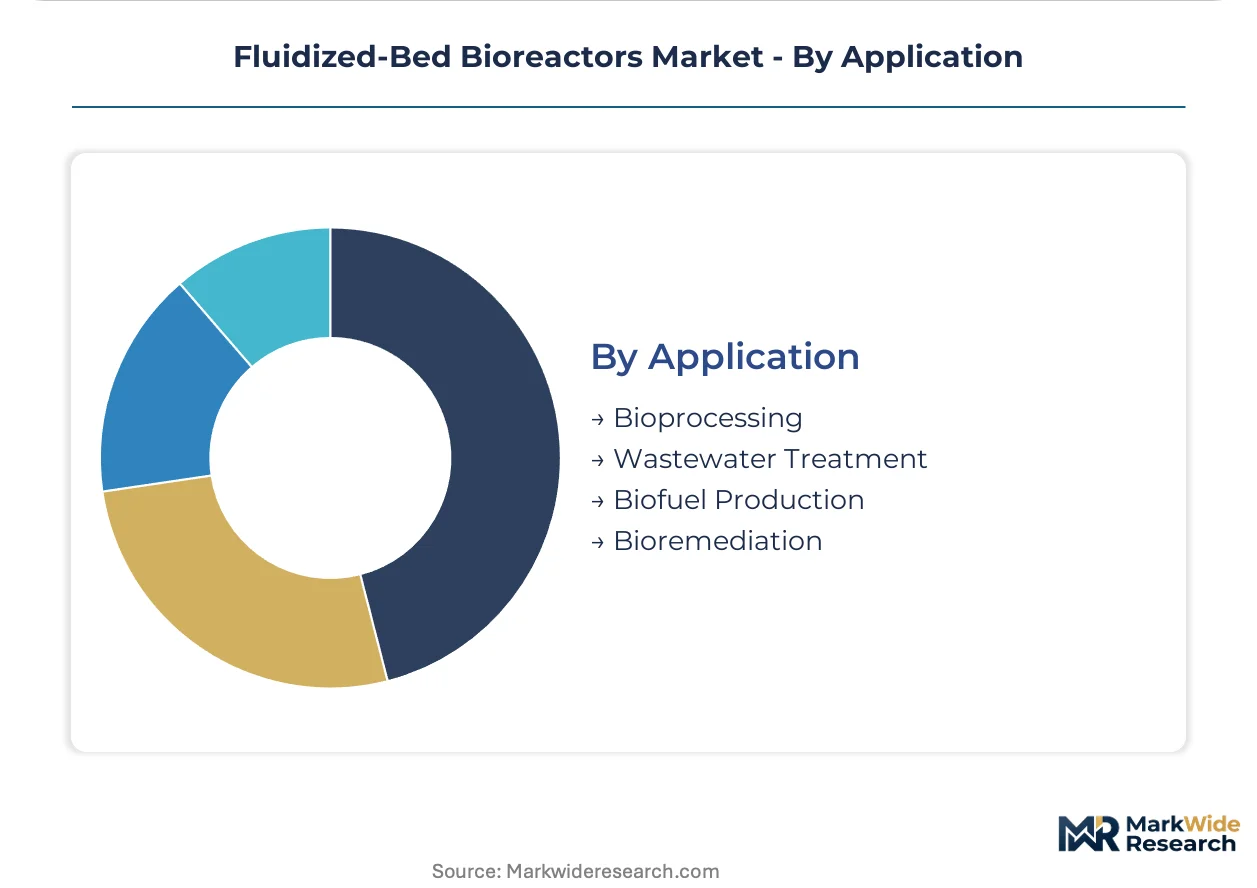
Application:
Process analytical technology integration requirements diverge across applications, with bioprocessing mandating embedded sensor arrays while wastewater treatment tolerates simpler control architectures.
- Bioprocessing:Cell culture intensification for therapeutic protein production demands validated mass transfer performance and real-time metabolite monitoring. REACH chemical registration requirements for polymer contact materials are tightening extractables documentation burdens in European contract manufacturing.
- Wastewater Treatment:Anaerobic fluidized-bed systems achieve chemical oxygen demand reduction while generating biomethane for energy recovery, with process economics determined by oxygen exclusion efficiency.
- Biofuel Production:Lignocellulosic ethanol and renewable diesel applications require multi-stage configurations to manage substrate toxicity and product inhibition.
- Bioremediation:Contaminated soil and groundwater treatment employs specialized biocatalyst immobilization, with site-specific contaminant profiles driving custom vessel design.
Bioprocessing anchors revenue concentration; biofuel production shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys fluidized-bed bioreactors predominantly for monoclonal antibody production, while Germany and China prioritize continuous processing for biosimilars and cell culture intensification respectively, creating distinct procurement specifications across major demand centers.
United States
FDA process analytical technology guidelines mandate validated control systems for perfusion-based bioprocessing, accelerating equipment replacement in legacy facilities. Massachusetts and North Carolina biologics manufacturers specify modular single-use platforms with six-month deployment horizons. Contract manufacturing organizations in Greater Boston are converting stainless-steel trains to fluidized-bed perfusion systems.
Germany
EMA good manufacturing practice standards for biologics production tighten equipment qualification protocols across Baden-Württemberg and Bavaria. REACH chemical registration requirements for polymer contact materials drive extractables documentation investment. Contract manufacturers in Stuttgart and Munich are replacing centralized infrastructure with skid-mounted continuous systems.
China
NMPA biologics approval pathway tightening creates first-mover advantage for pre-qualified system vendors in Yangtze River Delta clusters. The country's dual carbon goals accelerate anaerobic configuration adoption for biomethane upgrading. Shanghai and Suzhou biomanufacturing parks are expanding fluidized-bed capacity for biosimilar production.
Switzerland
Swissmedic biologics manufacturing licensing aligns with EMA standards while maintaining distinct equipment validation timelines. Basel and Zurich pharmaceutical clusters demand ASME-certified vessels for high-cell-density applications. The country's precision engineering base supports specialized alloy fabrication for thermal processing units.
India
CDSCO manufacturing licensing requirements for biologics are tightening equipment qualification protocols across Maharashtra and Gujarat. The country's PLI scheme for pharmaceuticals incentivizes domestic bioreactor assembly. Hyderabad and Mumbai contract research organizations are adopting single-use fluidized-bed platforms for cost-competitive bioprocessing.
Fluidized-Bed Bioreactors Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in fluidized-bed bioreactor supply. Sartorius leverages polymer science capabilities across disposable platform portfolios, while Procedyne anchors high-pressure thermal processing with alloy fabrication expertise. The market structure separates disposable technology providers from stainless-steel system fabricators, with hybrid specialists occupying intermediate positions. Competitive moves concentrate on modular skid development and continuous processing service contracts.
Among the named suppliers, Sartorius represents the integrated polymer-science archetype with disposable bioreactor dominance, Procedyne exemplifies specialized alloy-fabrication positioning in thermal processing niches, and Parr Instrument Company occupies precision pressure-vessel engineering territory. These three anchors illustrate how vendor strategies diverge across material-science versus mechanical-engineering competencies. Geographic distribution spans German, US, and Indian manufacturing origins, reflecting regional cluster specializations in pharmaceutical equipment supply.
| Leading Market Players |
|---|
| Procedyne |
| Soldo Cavitators |
| Surface Combustion |
| Sartorius |
| BP Littleford |
| Albertus Energy |
| Masterinox |
| Amar Equipments |
| Parr Instrument Company |
| Others |
Value Network & Pricing Analysis
Long-term service contracts anchor fluidized-bed bioreactor procurement, locking in spare parts allocation and predictive maintenance pricing for pharmaceutical manufacturers across Massachusetts and North Carolina facilities. This contract structure collapses equipment acquisition into decade-long operating agreements that shift qualification risk onto Sartorius and Procedyne while guaranteeing polymer film and alloy fabrication supply access.
Pricing Analysis
After-market service revenue tiers now exceed hardware margins for established vendors, with validation support and sensor calibration contracts driving lifetime value. Three-tier pricing structure across premium ASME-certified, standard CE-marked, and economy non-validated levels separates biologics manufacturers from food-grade processors. Cost compression in standard-tier stainless-steel systems is intensifying because modular single-use platforms collapse facility investment differentials. Contract manufacturing organizations exhibit highest price sensitivity; monoclonal antibody producers show lowest due to regulatory compliance imperatives.
Supply Chain Analysis
Nickel-based superalloy welding capacity concentrated in Germany, Switzerland, and the United States creates fabrication chokepoints for high-pressure thermal processing vessels. Polymer film supply draws from German and US specialty resin clusters, with REACH chemical registration requirements tightening extractables documentation burdens. Single-source vulnerability runs through qualified ASME vessel fabricators numbering fewer than twelve globally. Distribution feeds from regional equipment hubs through direct vendor-to-CDMO relationships, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluidized-bed bioreactor supply is restructuring toward performance-based operating agreements, with process validation and digital twin integration services expanding faster than hardware shipments. This service-attach dynamic concentrates in CDMO segments where facility utilization volatility demands variable cost structures.
For Market Incumbents: Fortify polymer science capabilities against stainless-steel sunk cost inertia by embedding predictive process control into continuous processing service contracts. Anchor high-pressure thermal processing positioning through captive alloy fabrication capacity in Switzerland and Germany. Defend against modular single-use entrants by accelerating ASME certification timelines for skid-mounted platforms. For New Entrants and Emerging Players: Differentiate on anaerobic configuration specialization for US municipal utility markets where biomethane upgrading remains underpenetrated relative to European adoption. Target environmental end-use segments with simplified control architectures that bypass pharmaceutical-grade validation burdens. Enter through equipment-leasing models that convert capital expenditure into operating expense for wastewater treatment operators. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with backward integration into polymer film extrusion or precision pressure-vessel engineering. Long-term viability favors vendors capturing recurring validation revenue streams over pure hardware manufacturers. Watch NMPA equipment qualification protocol tightening as inflection indicator for pre-qualified system vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Perfusion-Digital Twin Convergence | Real-time sensor integration with predictive control opens continuous manufacturing service contracts for CDMOs. |
| Modular Skid-Mounted Platform Development | Six-month deployment horizons displace thirty-six-month stick-built construction cycles in greenfield biologics facilities. |
| ASME Bioprocessing Equipment Pre-Certification | Fourteen-to-eighteen-month qualification timelines compress competitive positioning for validated control system vendors. |
| Polymer Science Backward Integration | Captive specialty resin supply secures REACH-compliant extractables documentation for European contract manufacturers. |
| Anaerobic Configuration Market Development | Biomethane upgrading applications in US municipal utilities address underpenetrated environmental segment expansion. |
Research Methodology
Initial hypotheses were tested against primary input from bioprocessing facility engineers, CDMO procurement directors, regulatory affairs specialists, and aftermarket service managers, then refined through secondary validation against FDA process analytical technology guidelines, EMA good manufacturing practice standards, NMPA biologics approval filings, and ASME bioprocessing equipment certification databases. Bottom-up vendor shipment analysis triangulated with top-down facility investment tracking across Massachusetts, North Carolina, Baden-Württemberg, Bavaria, and Yangtze River Delta clusters.
Variance decomposition across product type, technology mode, end-use industry, application, and regional regulatory framework shaped the analytical framework. CAGRs were derived from segment-level volume trajectories and value-per-unit trends throughout the forecast period. Modeled inputs included monoclonal antibody production capacity expansion, continuous processing conversion rates, and anaerobic configuration adoption curves for biomethane upgrading.
The analysis sits within stated boundaries; outcomes outside sustained biologics manufacturing investment or relaxed equipment qualification timelines would require recalibration. Forecasts reflect assumptions about regulatory stringency persistence and polymer resin supply stability. Practitioners should keep alternative scenarios live as NMPA protocol evolution and REACH chemical registration enforcement trajectories shift.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Single-Use Bioreactor Bag Integrity and Leak Test Equipment Market
Biotechnology Equipment
Asia-Pacific Transfection Reagent and Equipment Market
Biotechnology Equipment
Cell Separation Bead Market
Biotechnology Equipment
Global Cell Separation Technology Market
Biotechnology Equipment
Global Latex Agglutination Test Kits Market
Biotechnology Equipment
Tissue Microarrayer Market
Biotechnology Equipment
Global Biotechnology Instruments Market
Biotechnology Equipment
Restriction Endonucleases Products (REP) Market
Biotechnology Equipment
Global Plant Cell Culture Equipment Market
Biotechnology Equipment
Global Competent Cells Market
Biotechnology Equipment
Measurement Technologies in Downstream Processing Market
Biotechnology Equipment
Tissue Processor Equipment Market
Biotechnology Equipment
Low Endotoxin Gelatin Market
Biotechnology Equipment
ELISA POT Assay Kits Market
Biotechnology Equipment
IVF Workstation Market
Biotechnology Equipment
Global Bioprocess Container Market