
 Stable Cell Line Development Market | 2026-2036
Stable Cell Line Development Market Size, Share, and Industry Trends Forecast 2026-2036
Stable Cell Line Development Market Analytics
Modular service bundling is rebalancing procurement patterns across biologics developers. Lonza leverages its integrated manufacturing footprint to anchor large-molecule clients seeking end-to-end cell line-to-GMP pathways. Thermo Fisher Scientific competes through extensive distribution and platform breadth spanning CRISPR editing tools and clonal screening systems. WuXi AppTec sustains cost-advantaged scale in Asia-Pacific while extending service menus into characterization and regulatory submission support.
Stable cell line development encompasses the genetic engineering and clonal selection of mammalian or microbial host cells to produce consistent, high-yielding biotherapeutic proteins over extended passages. Chinese hamster ovary (CHO) cells remain the dominant expression platform, typically engineered for glutamine synthetase or dihydrofolate reductase selection systems to achieve titers exceeding five grams per liter in fed-batch culture. CRISPR-based editing and viral vector transduction now command premium positioning as developers prioritize speed-to-clinic and regulatory predictability. Biologics production applications occupy the deepest margin pools, while gene therapy cell lines represent the fastest-expanding demand segment as AAV and lentiviral vector manufacturing scales.
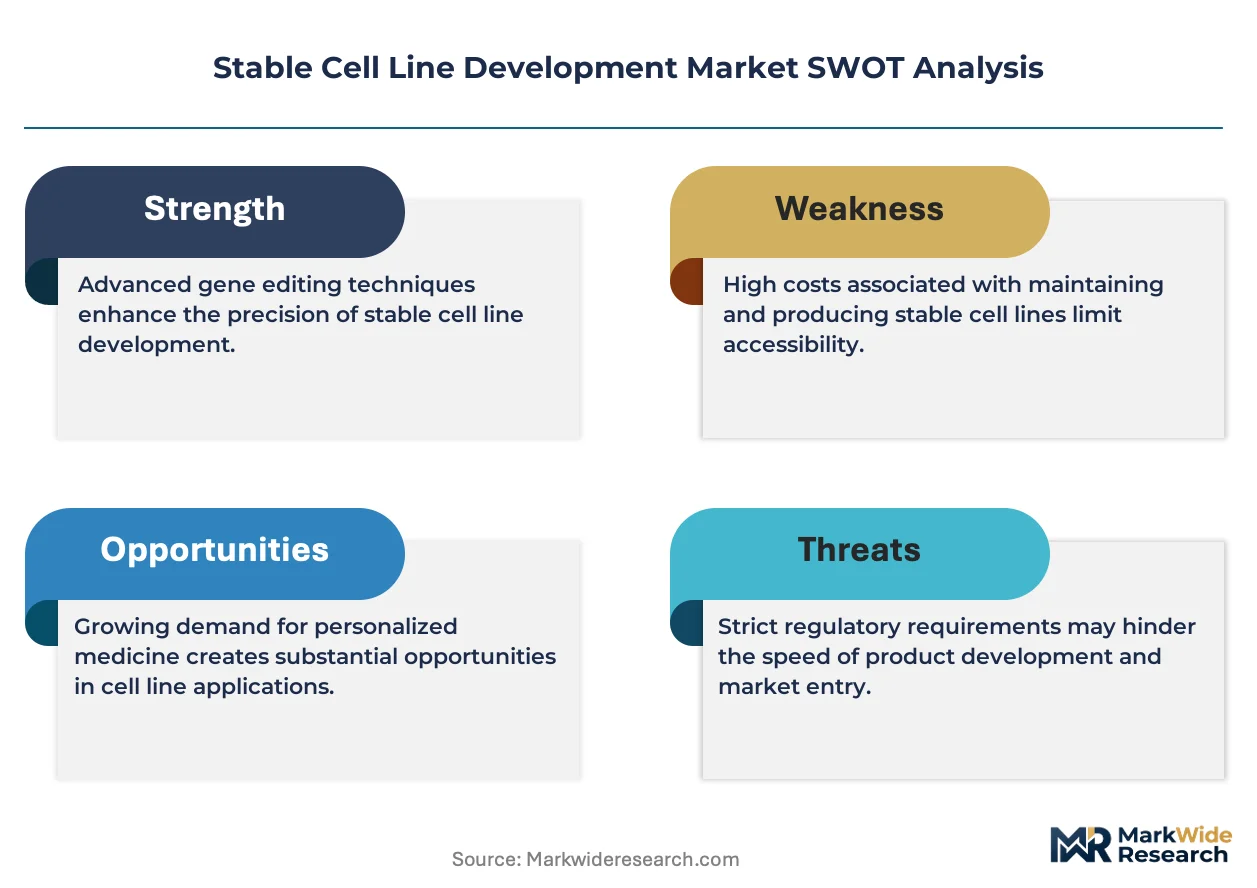
FDA guidelines on clonality demonstration and ICH Q5D standards for cell substrate qualification directly shape platform selection and documentation burdens for developers. EMA's ATMP framework and evolving gene therapy manufacturing expectations further tighten characterization requirements, favoring vendors with integrated analytical and regulatory capabilities. Stakeholders must weigh platform flexibility against regulatory precedent as novel modalities expand beyond traditional monoclonal antibodies.
Market Dynamics
CRISPR-based editing platforms and viral vector transduction systems are compressing cell line development timelines from months to weeks, forcing service providers to reconfigure platform architectures around speed-to-clinic metrics rather than incremental titer improvements alone.
Growth Catalysts
- FDA Clonality Guidelines:The agency's 2023 updated expectations for monoclonality demonstration have elevated demand for high-throughput single-cell cloning and imaging documentation services.
- Gene Therapy Manufacturing:AAV and lentiviral vector production scale-up is pulling specialized stable producer cell lines into commercial workflows previously dominated by transient transfection.
- CDMO Capacity Expansion:Biologics manufacturers in the United States, China, and Germany are outsourcing cell line creation to access modular service bundles combining engineering with regulatory submission support.
Market Restraints
- Master Cell Bank Scarcity:Qualified CHO-K1 and CHO-S substrates suitable for GMP banking concentrate among three legacy suppliers, creating single-source vulnerability for developers.
- Plasmid DNA Cost Volatility:GMP-grade transfection reagents and viral packaging plasmids have experienced input cost swings exceeding 40% since 2022, squeezing margins at fixed-price contract development agreements.
- ICH Q5D Documentation Burden:Cell substrate qualification requirements extend characterization timelines by 6-12 months for novel host platforms lacking established regulatory precedent.
Strategic Opportunities
- India Biologics Manufacturing:CDSCO's streamlined biosimilar approval pathways and PLI scheme incentives are attracting cell line development investment for export-oriented production.
- Continuous Bioprocessing Convergence:Integration of perfusion-ready cell lines with automated clone selection is opening service contracts for integrated upstream-downstream platform providers.
- Next-Generation Sequencing:NGS-based clonality verification is displacing limiting dilution statistics as the preferred documentation method for regulatory submissions to EMA and FDA.
Industry Challenges
- Cell Line Engineer Talent Gap:CRISPR screening and clone imaging expertise concentrates among specialists trained at fewer than 15 academic centers globally, constraining hiring pipelines for service expansion.
- Legacy Platform Integration:Bioprocess equipment designed for fed-batch CHO workflows requires capital-intensive retooling to accommodate continuous culture modalities and associated cell line architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stable Cell Line Development Market |
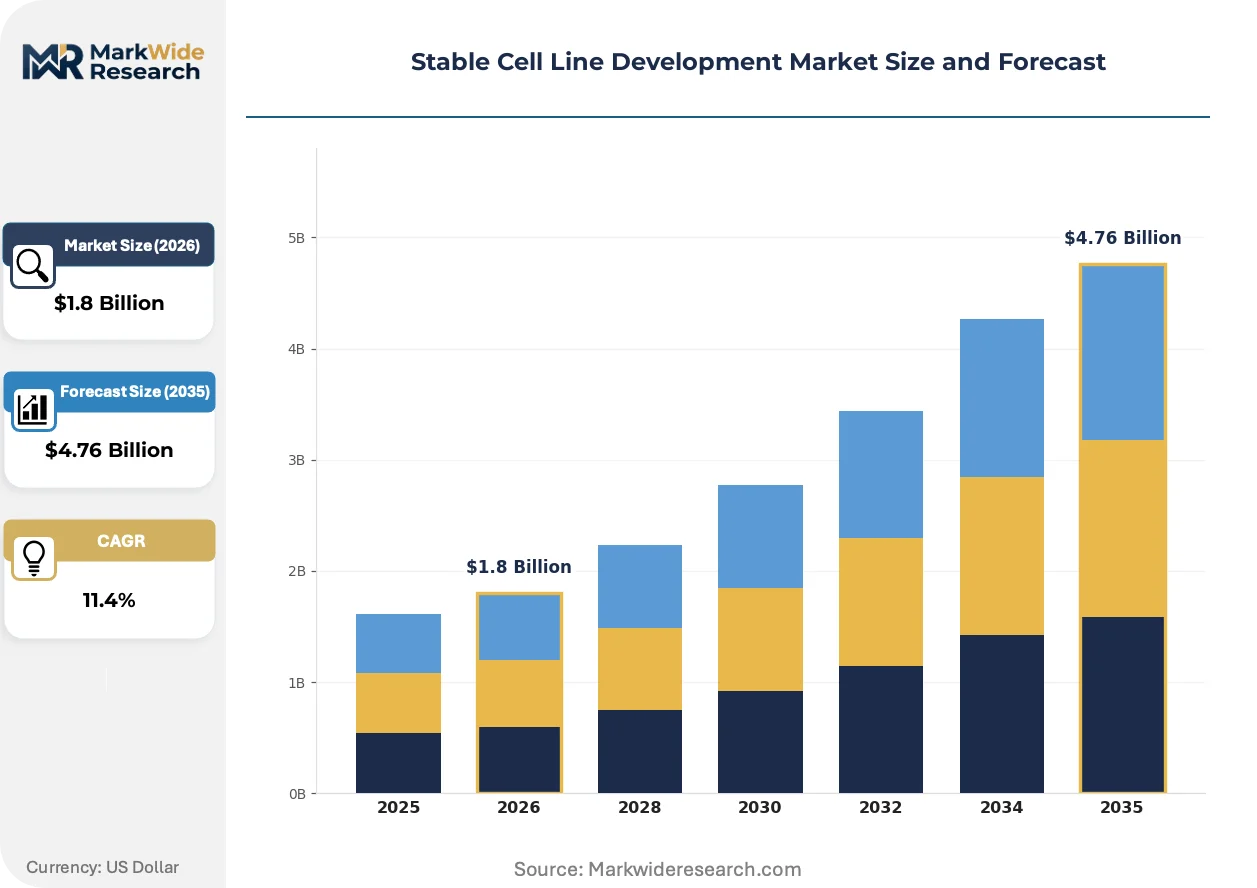
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Transfection, Viral Vector, CRISPR, Microinjection Application: Biologics Production, Drug Development, Gene Therapy, Vaccine Manufacturing End User: Pharmaceuticals, Biotechnology Firms, Academic Research Institutions, Contract Research Organizations Solution: Cell Line Services, Characterization Tools, Media & Supplements, Storage Solutions |
| Companies Covered | Thermo Fisher Scientific, Lonza, WuXi AppTec, Merck KGaA, Sartorius AG, Catalent, Charles River Laboratories, Bio-Techne, Promega Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stable Cell Line Development Market Evolving Landscape
Automated clone selection and AI-guided sequence optimization are redefining competitive differentiation in stable cell line services, shifting value capture from manual screening labor toward computational platform licensing and integrated data packages.
CRISPR-Cas9 knock-in systems with site-specific landing pads are consolidating platform standardization across major service providers. Large-molecule developers at mid-cap biotechs are adopting these architectures to reduce line-to-line expression variability. The technology is consolidating vendor market share around providers with validated guide RNA libraries and off-target screening protocols.
EMA's ATMP manufacturing guidelines are tightening characterization expectations for gene therapy cell substrates. Developers must now demonstrate extended genetic stability across 60+ population doublings for commercial approval. European gene therapy sponsors are responding by front-loading analytical development budgets and selecting host platforms with established regulatory histories.
Biologics developers are unbundling cell line creation from downstream process development, awarding discrete contracts to specialized vendors rather than integrated CDMOs. This pattern concentrates among emerging biotechs in Boston and San Francisco seeking to preserve equity capital. The United States displays the most pronounced fragmentation between upstream cell line specialists and downstream manufacturing partners.
Stable Cell Line Development Market Segmentation
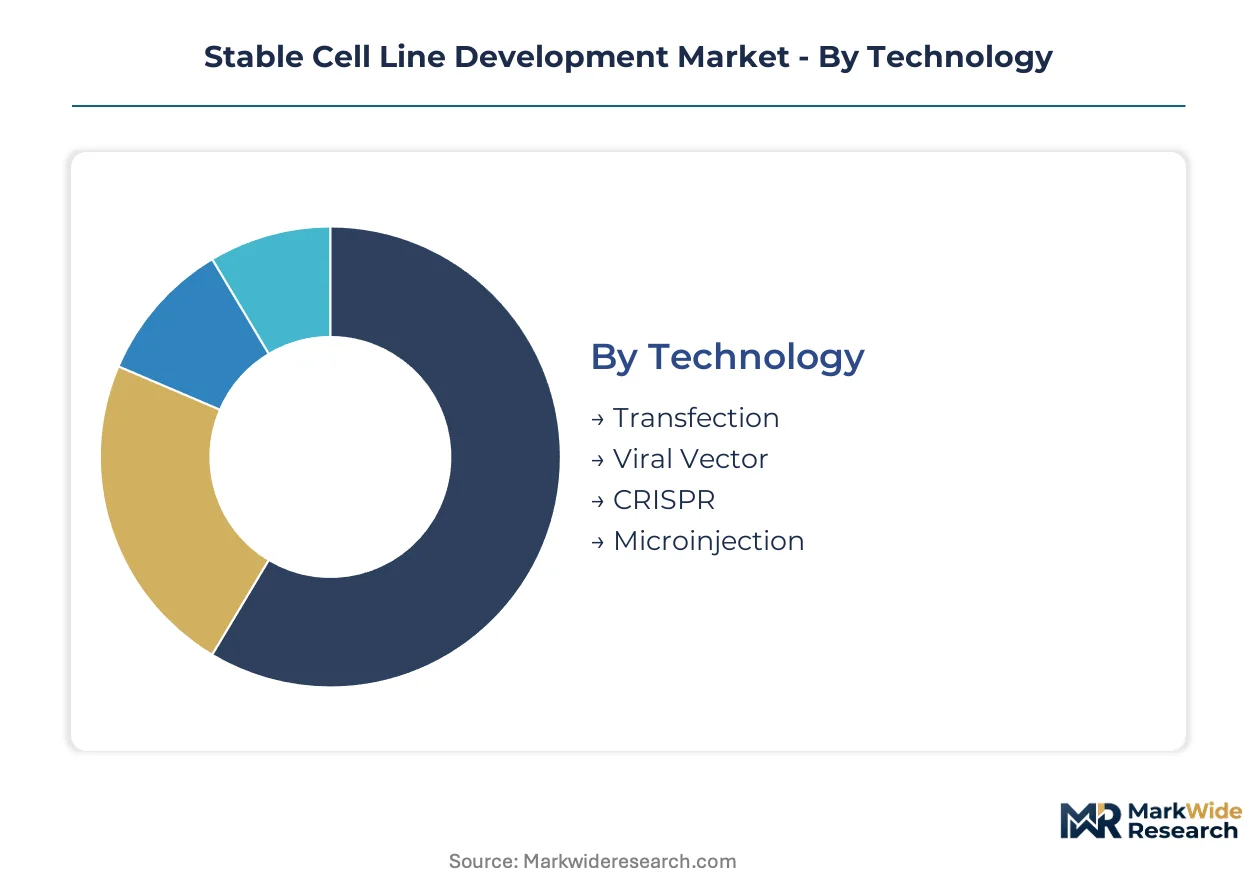
Segmentation in stable cell line development reveals how regulatory burden and technical complexity distribute across customer types and workflows. Technology choices determine FDA and EMA documentation requirements, while application focus shapes margin profiles and service bundling strategies.
Technology:
FDA clonality guidelines and EMA ATMP standards impose distinct qualification burdens on each engineering approach, with newer platforms facing steeper characterization requirements.
- CRISPR:Site-specific knock-in systems with validated guide RNA libraries enable rapid clonal selection. Biologics developers in the United States favor this platform for speed-to-clinic timelines, though off-target screening protocols add analytical costs.
- Viral Vector:Lentiviral and AAV packaging systems dominate gene therapy cell line creation. Demand concentrates among Chinese and German CDMOs scaling AAV producer lines for commercial vector manufacturing.
- Transfection:Electroporation and lipid-based delivery remain workhorse methods for CHO cell engineering.
- Microinjection:Precision injection systems serve specialized applications requiring controlled copy number integration.
Viral vector sits at the top of the volume ranking, with CRISPR climbing the fastest.
Application:
Cost tiers separate commodity vaccine workflows from premium gene therapy platforms requiring extended genetic stability demonstration.
- Gene Therapy:AAV and lentiviral producer cell lines demand 60+ population doubling documentation under EMA ATMP guidelines. European sponsors front-load analytical budgets to meet commercial approval standards.
- Biologics Production:Monoclonal antibody manufacturing drives the deepest margin pools, with fed-batch CHO titers exceeding five grams per liter. German and United States biologics capacity expansion sustains contract demand.
- Drug Development:Early-phase candidate screening requires rapid turnaround cell lines with abbreviated characterization.
- Vaccine Manufacturing:Viral vaccine substrates prioritize yield consistency over maximal expression.
Biologics production commands the largest revenue share, while gene therapy displays the steepest expansion trajectory.
End User:
Customer type determines procurement sophistication, with large pharmaceuticals favoring integrated bundles and emerging biotechs unbundling services to preserve capital.
- Pharmaceuticals:Large-molecule developers anchor demand for end-to-end cell line-to-GMP pathways. United States and German manufacturers outsource to access modular service combinations spanning engineering with regulatory submission support.
- Biotechnology Firms:Mid-cap and emerging biotechs in Boston and San Francisco fragment procurement, awarding discrete contracts to specialized upstream vendors.
- Academic Research Institutions:Basic research programs utilize cell lines for mechanism studies and early proof-of-concept work.
- Contract Research Organizations:CDMO capacity expansion across China and Germany pulls specialized cell line creation into outsourced workflows.
Pharmaceuticals dominate contract value, with biotechnology firms expanding most quickly.
Solution:
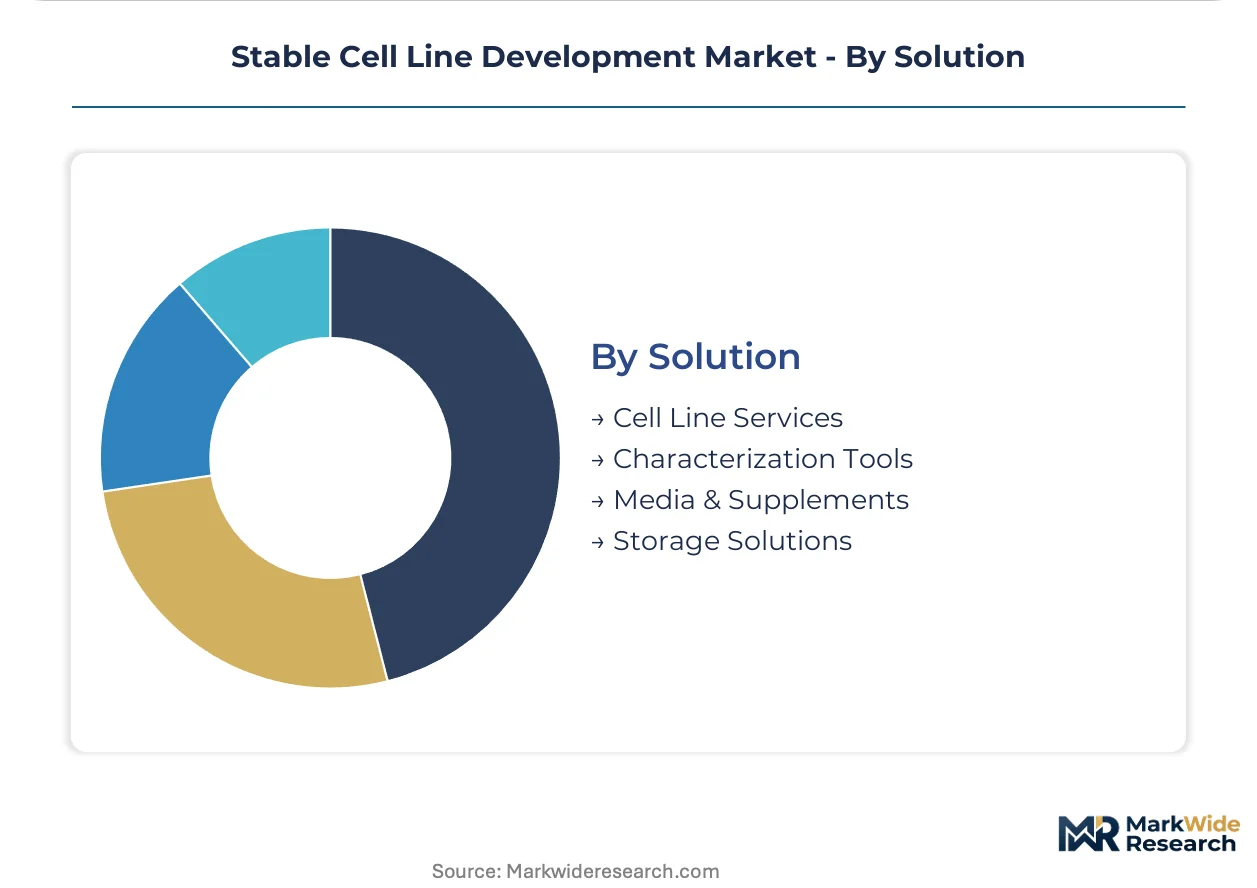
Margin concentration follows the analytical intensity of deliverables, with characterization tools capturing premium pricing against commoditized media formulations.
- Cell Line Services:Integrated creation, screening, and banking bundles command premium positioning. Lonza and WuXi AppTec compete on platform breadth and regulatory submission support.
- Characterization Tools:NGS-based clonality verification and automated imaging systems displace legacy limiting dilution methods. EMA and FDA submission preferences drive replacement demand.
- Media & Supplements:Chemically defined feeds and selection reagents support fed-batch and perfusion workflows.
- Storage Solutions:Master and working cell bank cryopreservation services ensure genetic stability across extended passages.
Cell line services generate the highest absolute revenue, with characterization tools gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The stable cell line development industry traces its commercial roots to Swiss pharmaceutical manufacturing in the 1980s, where CHO cell engineering first achieved industrial scale. Today, demand concentrates in jurisdictions with mature biologics infrastructure and active regulatory frameworks governing cell substrate qualification.
United States
FDA clonality guidelines and IRA-driven biomanufacturing incentives are accelerating CDMO investment across Massachusetts and California. The agency's 2023 updated expectations for monoclonality demonstration have elevated demand for high-throughput single-cell cloning services. Greater Boston hosts the densest cluster of emerging biotechs unbundling cell line creation from downstream development.
Germany
EMA's ATMP framework and ICH Q5D implementation are tightening characterization requirements for commercial cell substrates. Bavaria and North Rhine-Westphalia anchor contract demand from large-molecule developers seeking modular service bundles. German biologics capacity expansion sustains outsourcing relationships with integrated platform providers.
China
NMPA regulatory convergence with ICH standards and domestic biologics pipeline growth are pulling cell line development investment toward Shanghai and Suzhou industrial parks. CDMO scale advantages in the Yangtze River Delta support export-oriented production for international sponsors. WuXi AppTec anchors regional service integration across engineering and regulatory submission support.
India
CDSCO's streamlined biosimilar approval pathways and PLI scheme incentives are attracting cell line development investment for export-oriented production. Maharashtra and Gujarat host emerging biomanufacturing clusters targeting contract opportunities from European and US sponsors. Cost-advantaged scale positions Indian vendors for characterization and banking service expansion.
Switzerland
Swissmedic's alignment with EMA standards and legacy CHO platform expertise sustain Basel and Zurich as centers of cell line innovation. The country's pharmaceutical manufacturing heritage supports specialized service providers targeting gene therapy and biologics applications. Swiss vendors emphasize regulatory predictability and extended genetic stability documentation for commercial approvals.
Stable Cell Line Development Market Competitive Landscape
The competitive structure tilts toward integrated platform providers with validated regulatory submission capabilities. Service bundling and speed-to-clinic metrics now outweigh incremental titer improvements as selection criteria. Three archetypes dominate: end-to-end CDMOs spanning cell line-to-GMP pathways, specialized upstream engineering shops, and analytical/characterization tool vendors. Capacity expansion and strategic partnerships represent the primary competitive moves, with technology licensing agreements accelerating CRISPR platform standardization.
Within the integrated CDMO tier, Lonza, Thermo Fisher Scientific, and WuXi AppTec occupy positions defined by manufacturing footprint breadth and regulatory support depth. Lonza leverages Swiss and US-based infrastructure to anchor large-molecule clients. Thermo Fisher Scientific competes through distribution reach and platform breadth spanning editing tools with clonal screening systems. WuXi AppTec sustains cost-advantaged scale in Asia-Pacific while extending service menus into characterization capabilities.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Lonza |
| WuXi AppTec |
| Merck KGaA |
| Sartorius AG |
| Catalent |
| Charles River Laboratories |
| Bio-Techne |
| Promega Corporation |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up CDMO specialists have consolidated cell line engineering capacity across Switzerland, Germany, and the United States, creating pricing discipline through portfolio rationalization while concentrating GMP-grade substrate supply among legacy CHO-K1 and CHO-S holders. This ownership pattern tightens margin capture at the master cell bank tier and amplifies cost pass-through volatility when plasmid DNA or viral packaging reagents experience input swings.
Pricing Analysis
Project-based contracting with milestone payments dominates stable cell line services, separating premium integrated bundles from discrete characterization-only engagements. Price differentiation rests on regulatory submission support depth and clonality documentation rigor under FDA and EMA standards. Cost compression in standard CHO engineering is intensifying because CDMO capacity expansion in China and India adds price-competitive supply. Emerging biotechs in Boston and San Francisco display highest price sensitivity, fragmenting procurement across specialized upstream vendors to preserve equity capital.
Supply Chain Analysis
Direct-to-biologics-manufacturer channels handle large-pharma demand for end-to-end cell line-to-GMP pathways, while distributor-mediated access serves smaller biotechnology firms and academic institutions. Geographic supply concentration centers on Switzerland, Germany, and the United States for GMP banking services, with China and India expanding cost-advantaged engineering capacity. Raw material dependencies include GMP-grade plasmid DNA, viral packaging reagents, and chemically defined media formulations. Single-source vulnerability at the master cell bank tier creates structural supply risk when qualified CHO substrates concentrate among three legacy suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stable cell line development market compounds steadily as biologics pipeline expansion and gene therapy manufacturing scale-up sustain contract demand across regulatory jurisdictions. Outsourcing penetration deepens as emerging biotechs prioritize speed-to-clinic metrics over captive capacity investment.
For Market Incumbents: Anchor regulatory predictability as the primary defensive moat by extending clonality documentation capabilities and ICH Q5D submission support. Deepen backward integration into CRISPR guide RNA libraries and off-target screening protocols to capture platform licensing revenue. Capacity addition in India and China preserves cost competitiveness against regional challengers. For New Entrants and Emerging Players: AI-guided sequence optimization and automated clone selection offer technology-first entry points against labor-intensive incumbent workflows. White-space targets include NGS-based clonality verification services displacing limiting dilution statistics for EMA and FDA submissions, and perfusion-ready cell line engineering for continuous bioprocessing adopters. A characterization-first go-to-market angle bypasses capital-intensive GMP banking requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized upstream engineering shops lacking integrated regulatory submission capabilities. Long-term viability favors vendors with validated ATMP documentation experience as gene therapy cell substrate requirements tighten. The signal to watch is CDMO consolidation activity in the Yangtze River Delta and Bavaria indicating platform standardization momentum.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR Platform Licensing | Standardized knock-in systems with validated guide RNA libraries accelerate client onboarding across FDA jurisdictions. |
| Regulatory Submission Support | Integrated ICH Q5D and EMA ATMP documentation capabilities differentiate service bundles for commercial cell substrates. |
| Continuous Bioprocessing Convergence | Perfusion-ready cell line engineering opens contracts with automated upstream-downstream platform providers. |
| NGS Clonality Verification | Next-generation sequencing methods displace limiting dilution for FDA and EMA monoclonality demonstration. |
| India Biologics Manufacturing | CDSCO streamlined pathways and PLI incentives attract export-oriented cell line development investment. |
Research Methodology
Multiple input streams — executive interviews with cell line engineering directors, regulatory affairs leads at biologics developers, and CDMO procurement officers — were reconciled against FDA filing databases, EMA submission records, and clinical trial registry data. Secondary validation drew from SEC 10-K disclosures, ICH guideline documentation, and customs trade flows for GMP-grade reagents. Bottom-up service provider capacity estimates and top-down biologics pipeline analysis were triangulated to anchor market sizing.
Data-stream reconciliation across technology adoption curves, application demand trajectories, and end-user procurement patterns informed the analytical framework over the projection horizon. Segmentation dimensions modeled include engineering platform type, therapeutic application, customer scale tier, and regional regulatory cluster. CAGRs were derived from capacity expansion announcements, CDMO contract visibility, and biologics manufacturing investment flows across the analysis window.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CRISPR regulatory guidance evolution and gene therapy manufacturing scale-up delays. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Bio-Services Market
Biotechnology Services
Global Digital PCR (Dpcr) and Real-Time PCR (Qpcr) Market
Biotechnology Services
Riboflavin Kinase Market
Biotechnology Services
Plasmid DNA Contract Manufacturing Market
Biotechnology Services
Marine Polysaccharides Fucoidan Alginate Market
Biotechnology Services
Asia-Pacific Mirna Tools and Services Market
Biotechnology Services
Molecular Methods Market
Biotechnology Services
Global Reporter Gene Assay Market
Biotechnology Services
Cdna Synthesis Market
Biotechnology Services
Biotech API Manufacturing Services Market
Biotechnology Services
Cell Lysis and Dissociation Market
Biotechnology Services
Cell Culture Media Market
Biotechnology Services
Global Cell Banking Outsourcing Market
Biotechnology Services
Phycobiliproteins Market
Biotechnology Services
Recombinant Factor C Assay Market
Biotechnology Services
GMO Testing Services Market