
 Plasma Feed Market | 2026-2036
Plasma Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Plasma Feed Market Intelligence
Specialized animal protein processors in North America and Europe are expanding their spray-drying capacity to meet demand for high-quality plasma. Darling Ingredients Inc. leverages its extensive raw material collection network to ensure consistent supply. The SARIA Group specializes in converting animal by-products into functional ingredients for multiple end markets. Veos Group differentiates through its focus on specific animal plasma fractions for high-value applications.
Plasma feed is a protein-rich ingredient derived from animal blood via centrifugation and spray-drying, containing high levels of immunoglobulins. Its primary purpose is to improve gut health and palatability in young animal diets, especially for swine and poultry. Animal nutrition applications, specifically for piglets and calves, represent the largest use case. Powder plasma feed dominates product forms due to its stability, shelf life, and ease of integration into feed manufacturing.
Regulatory frameworks from the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) dictate strict safety, sourcing, and processing standards. In China, the State Administration for Market Regulation (SAMR) manages feed additive approvals, directly influencing market access for imported products. Navigating these varied national biosecurity and import requirements remains a critical competency for suppliers.
Market Dynamics
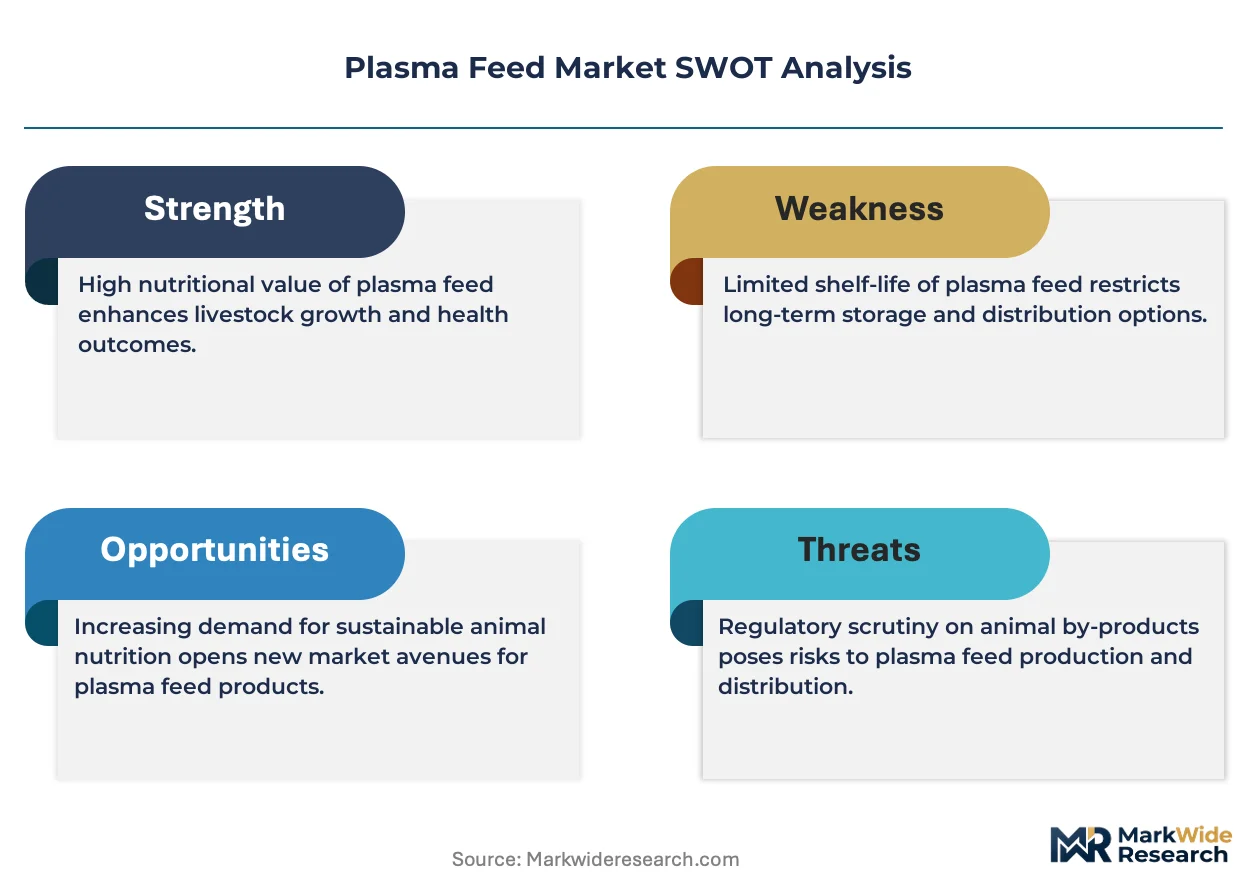
The central force shaping the plasma feed market is the global regulatory pivot away from antibiotic growth promoters in livestock. This shift elevates the role of functional proteins like spray-dried plasma as a primary tool for enhancing gut health and immunity in young animals.
Growth Catalysts
- Regulatory Restrictions on Antibiotics:European Union regulations banning antibiotic growth promoters in animal feed create a direct and sustained demand for effective alternatives, positioning plasma as a preferred functional ingredient for maintaining animal health and performance.
- Intensive Swine Production:The focus on reducing pre-weaning mortality and improving piglet health in major pork-producing nations, particularly China and the United States, drives consistent demand for plasma in starter feeds to boost immunity and feed intake.
- Spray-Drying Advancements:Continuous improvements in spray-drying technology allow for better preservation of the functional properties of immunoglobulins, increasing the efficacy of plasma feed and reinforcing its value proposition to animal nutritionists and veterinarians.
Market Restraints
- Raw Material Volatility:The supply and cost of raw animal blood are directly tied to slaughterhouse throughput, which can fluctuate due to livestock disease outbreaks, economic cycles, or processing disruptions, creating price instability for plasma feed producers.
- Threat from Protein Alternatives:Competition from other functional protein sources, including yeast extracts, potato protein, and fishmeal, presents a significant substitution risk, especially for cost-sensitive buyers in the poultry and aquaculture feed sectors.
- Biosecurity and Trade Barriers:Strict import controls and testing protocols related to animal diseases like African Swine Fever can halt trade flows abruptly, creating significant market access risk for exporters and supply chain uncertainty for importers.
Strategic Opportunities
- Expansion in Aquaculture Feeds:There is a significant opportunity to increase the use of plasma feed in starter diets for high-value aquaculture species, such as shrimp and marine finfish, where improving larval survival and disease resistance is critical.
- Geographic Penetration in Southeast Asia:Markets like Vietnam and Thailand, with their rapidly commercializing livestock sectors, represent underpenetrated regions where plasma feed can be introduced to improve animal health standards and production efficiency.
- Development of Plasma Fractions:Isolating specific components like immunoglobulin G (IgG) or albumin allows for the creation of high-value, targeted products for specific health challenges or for non-feed applications like pet food and diagnostics.
Industry Challenges
- Cold Chain Management:Maintaining an unbroken and sanitary cold chain for raw blood from the point of collection at abattoirs to the processing facility is a complex and costly logistical challenge that directly impacts final product quality.
- Navigating Compliance Requirements:Adhering to the diverse and stringent biosecurity, safety, and import certification standards of different national bodies, such as the USDA and China's SAMR, requires significant investment in testing and documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plasma Feed Market |
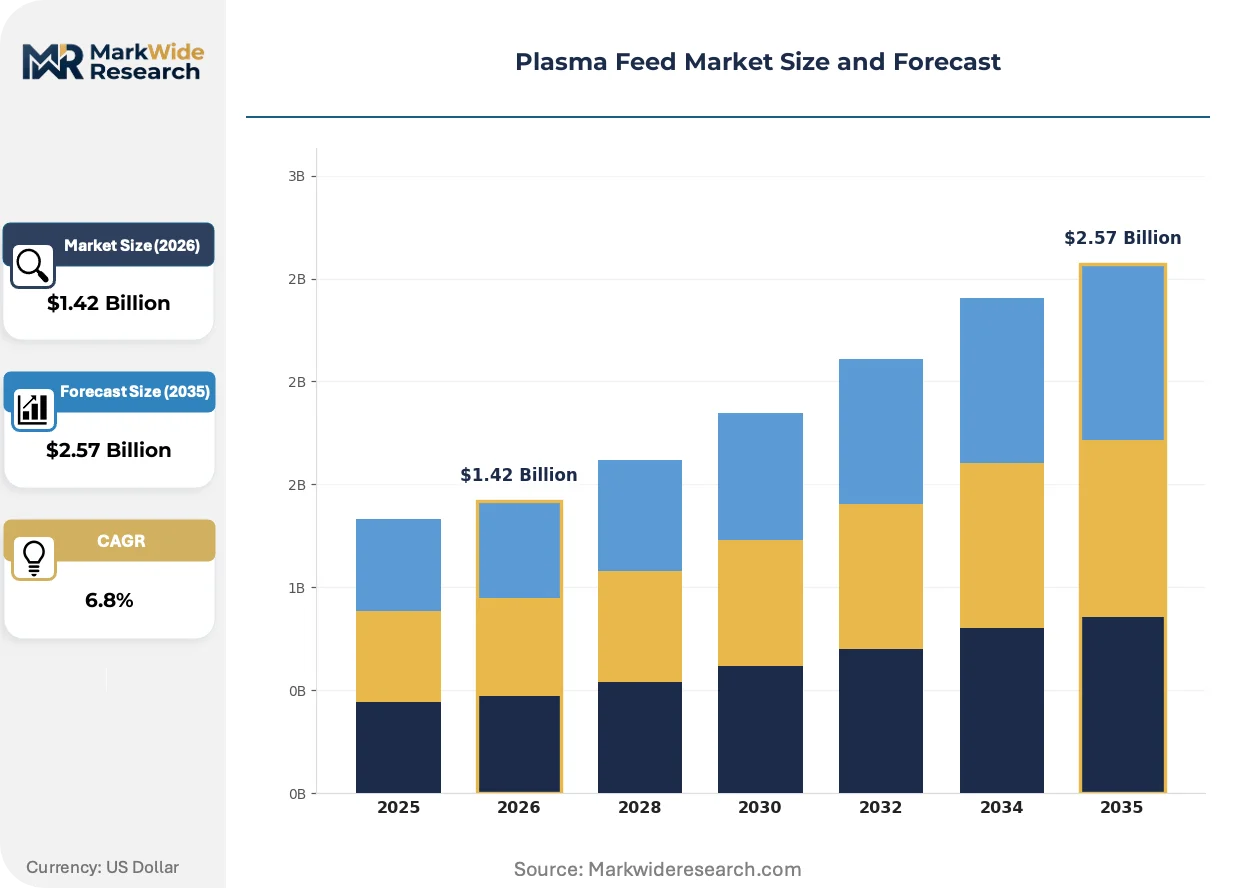
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder Plasma Feed, Liquid Plasma Feed, Solid Plasma Feed, Enriched Plasma Feed, Custom Plasma Feed Application: Animal Nutrition, Agriculture Enhancement, Pharmaceutical Processing, Cosmetic Ingredient, Biotechnological Research End User: Livestock Farms, Crop Producers, Feed Manufacturers, Research Institutes, Pharmaceutical Companies Distribution Channel: Direct Sales, Distributors, Online Platform, Retail Outlets, Bulk Suppliers |
| Companies Covered | Sera Scandia, Puretein Agri LLC, Darling Ingredients Inc., Kraeber & Co GmbH, Veos Group, Lauridsen Group Inc., Lican Food, Rocky Mountain Biologicals, SARIA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plasma Feed Market Strategic Shifts & Innovations
Functional value and scientific validation are becoming the primary competitive differentiators in the plasma feed market. The industry is moving beyond commoditized protein content, with innovation focused on enhancing bioavailability, proving efficacy through animal trials, and ensuring verifiable product safety.
Advanced fractionation technology isolates specific protein components like albumin and globulins from raw plasma. Animal nutrition formulators are adopting these fractions for high-value therapeutic and life-stage-specific diets. This specialization is decentralizing the market from a monolithic spray-dried product into a portfolio of targeted, high-margin ingredients for specific health outcomes.
Heightened biosecurity regulations, including stringent source-verification protocols from the European Food Safety Authority (EFSA), are forcing processors to invest in advanced traceability. This industrial consequence requires robust systems for tracking raw materials from the individual animal or farm through to the final spray-dried batch. Exporters targeting the European Union and Japan are most affected, as they must provide extensive documentation to prove product origin and safety.
Large-scale integrators in the swine and poultry sectors are demanding performance data and field trial results to justify using premium ingredients like plasma. This shift moves purchasing criteria away from simple cost-per-unit protein analysis toward a total economic value assessment, including feed conversion ratios and reduced medication expenses. This evidence-based procurement model is most visible in the sophisticated production systems of North America and Europe.
Plasma Feed Market Segmentation
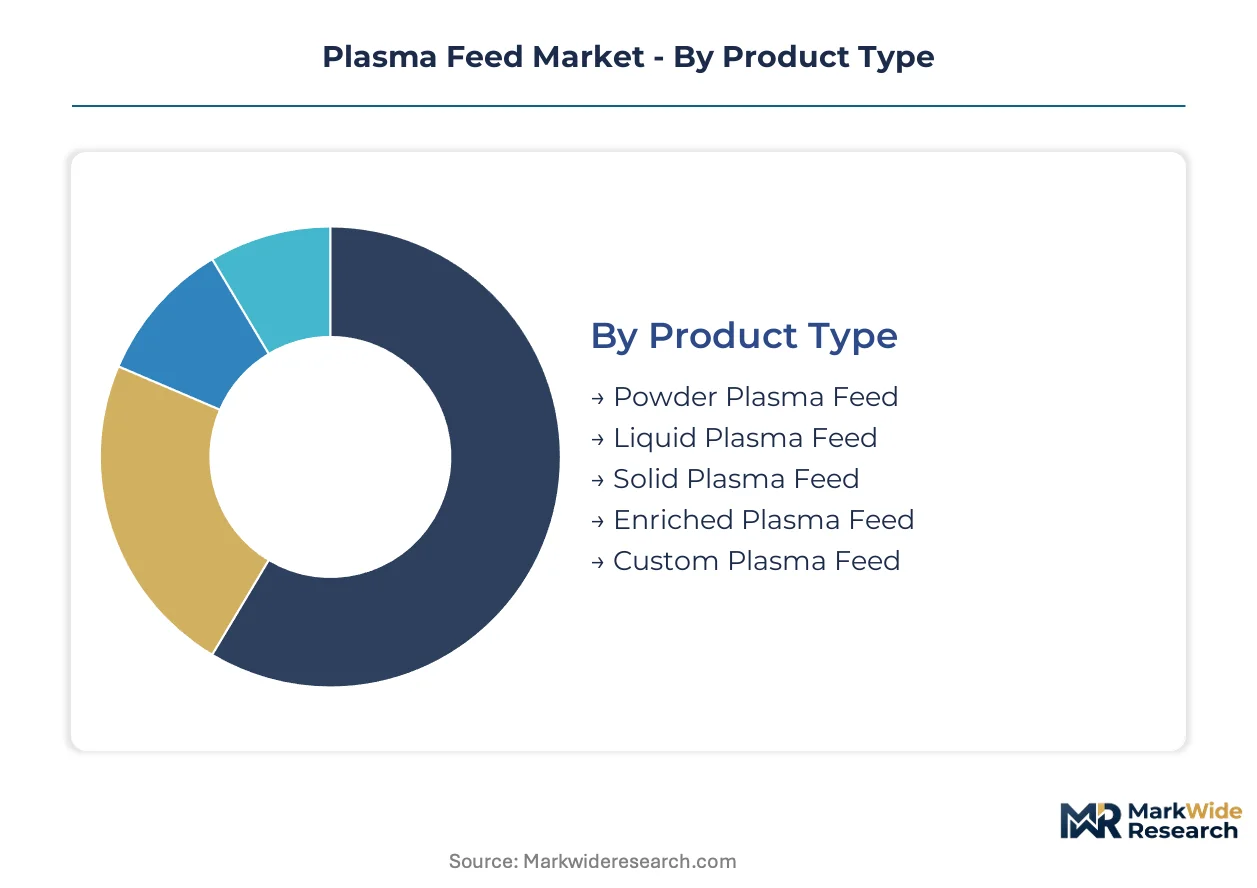
The plasma feed market segmentation highlights the diverse product forms, applications, and end-user requirements driving its expansion. Understanding these distinct segments allows stakeholders to identify specific growth vectors and tailor product development to meet specialized needs across the animal nutrition value chain.
Product Type:
Different product forms of plasma feed reflect varying levels of processing and integration into animal nutrition systems.
- Powder Plasma Feed:This form is created through spray-drying, resulting in a stable, easily transportable, and shelf-stable product. Demand concentrates in starter feeds for swine and poultry in major producing nations like China and the United States, driven by its ease of handling and consistent quality.
- Liquid Plasma Feed:Representing a less processed form, liquid plasma feed typically has a shorter shelf life and requires careful cold chain management. Its use is prevalent in specialized applications for calves and in certain aquaculture starter diets, where rapid nutrient absorption is a critical factor.
- Solid Plasma Feed:Less common than powder, this form is sometimes used as a binder in feed pellets or incorporated into specific pet food formulations.
- Enriched Plasma Feed:These products contain additional functional ingredients or higher concentrations of specific immunoglobulins, targeting particular health outcomes in young animals.
- Custom Plasma Feed:Formulated to meet the unique dietary requirements of specific animal species or specialized livestock production systems, often for high-value animals.
Powder Plasma Feed leads volumes today; Enriched Plasma Feed is gaining share fastest.
Application:
Plasma feed applications span various end-user sectors, each requiring tailored product characteristics and delivery mechanisms.
- Animal Nutrition:This application represents the primary use case for plasma feed, leveraging its role in improving gut health and immunity in young animals. Demand is particularly strong for piglets and calves in North America and Europe, driven by regulatory mandates to reduce antibiotic use.
- Pharmaceutical Processing:This segment utilizes high-purity plasma components as raw materials for drug development, vaccine production, and diagnostic reagents. Biopharmaceutical companies in the United States and Germany require stringent quality control and certified sourcing for these applications.
- Agriculture Enhancement:This niche application includes plasma components potentially used as soil amendments or in specialized plant growth formulas, though it is a minor segment.
- Cosmetic Ingredient:Specific proteins derived from plasma find limited use in high-end skincare or hair products due to their functional properties.
- Biotechnological Research:Research institutes and laboratories use plasma as a vital component in cell culture media or as a protein source for various scientific studies.
The largest segment, Animal Nutrition, drives significant revenue, while Pharmaceutical Processing demonstrates rapid expansion.
End User:
End-user segments for plasma feed reflect diverse operational scales and varying levels of technological sophistication in their procurement practices.
- Livestock Farms:These entities are direct purchasers of plasma feed for on-farm feed mixing, particularly large-scale swine and poultry operations. Farms in Brazil and Vietnam prioritize plasma for its impact on feed conversion ratios and reduced pre-weaning mortality.
- Feed Manufacturers:These companies integrate plasma as a functional ingredient into their proprietary feed formulations for various animal species. Major feed producers in the Netherlands and Thailand seek consistent supply and technical support from plasma suppliers.
- Crop Producers:This segment has minimal direct engagement with plasma feed, potentially limited to niche organic farming or specialized agricultural applications.
- Research Institutes:Academic and commercial research institutions utilize plasma for scientific studies focused on animal health, nutrition, and physiological responses.
- Pharmaceutical Companies:These firms procure specific plasma fractions for the development of therapeutic products and other biomedical applications.
Demand from Feed Manufacturers accounts for the majority of consumption, with Pharmaceutical Companies showing considerable future potential.
Distribution Channel:
Distribution channels for plasma feed vary based on customer scale and the logistical demands of specialized ingredients.
- Direct Sales:Plasma processors sell directly to large-volume feed manufacturers, integrators, or major livestock operations. Large integrators in the United States and Germany often prefer direct sales for long-term contracts and dedicated technical service.
- Distributors:Third-party distribution companies manage logistics, warehousing, and regional market access for plasma feed products. Smaller feed mills and specialized farms across Europe rely on distributors for localized inventory and support.
- Online Platform:This emerging channel facilitates smaller orders and specialized product sales, offering convenience and broader market reach for certain plasma feed varieties.
- Retail Outlets:Plasma feed has limited presence in retail, primarily for pet food or small-scale animal supplement sales.
- Bulk Suppliers:These suppliers cater to very large industrial buyers, focusing on high-volume, low-margin transactions for basic plasma feed products.
While Direct Sales remains the dominant route, Online Platform is experiencing notable expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global plasma feed market exhibits a complex regional dynamic, largely driven by regulatory arbitrage where production and demand concentrate in areas balancing livestock intensity with evolving feed additive policies. This creates distinct growth patterns across major agricultural economies.
United States
Intensive swine production and a focus on reducing pre-weaning mortality significantly drive demand for plasma in starter feeds. The US Food and Drug Administration (FDA) sets stringent safety and sourcing standards for feed ingredients, ensuring product quality. Major feed manufacturing hubs in the Midwest, particularly Iowa and Nebraska, integrate plasma into high-performance animal diets.
China
China's massive pork production sector consistently fuels plasma feed demand, especially for improving piglet health and immunity. The State Administration for Market Regulation (SAMR) manages feed additive approvals, directly impacting market access for imported plasma products. Shandong and Henan provinces, key livestock regions, represent significant consumption centers for plasma feed.
Germany
European Union regulations banning antibiotic growth promoters have created a sustained demand for functional protein alternatives like plasma feed. The European Food Safety Authority (EFSA) enforces strict biosecurity and processing standards for animal-derived ingredients. North Rhine-Westphalia and Lower Saxony, with their dense livestock populations, are pivotal markets for plasma feed integration.
Vietnam
Rapidly commercializing livestock sectors, particularly in swine and poultry, present substantial growth opportunities for plasma feed in Southeast Asia. Government initiatives to modernize agricultural practices and improve animal health drive the adoption of advanced feed ingredients. The Mekong Delta region, a major agricultural zone, is witnessing increased use of plasma in starter diets.
Brazil
Brazil's position as a leading global exporter of pork and poultry underpins a robust domestic demand for performance-enhancing feed additives. The country's national agricultural regulatory bodies oversee feed safety and quality, influencing ingredient sourcing. The states of Santa Catarina and Rio Grande do Sul, major livestock producing areas, are key consumers of plasma feed.
Plasma Feed Market Key Industry Players
North American processors anchor one tier of the plasma feed market, leveraging extensive raw material networks, while European specialists hold strong positions through advanced processing technologies. The market structure is characterized by a balance between large-scale integrators and niche ingredient providers. Competitive moves include significant capacity expansions and strategic partnerships to secure raw material supply.
Specialists in converting animal by-products into functional ingredients, such as SARIA Group, exemplify a focus on diversified end markets. Darling Ingredients Inc. represents a vertically integrated model, leveraging its extensive raw material collection network for consistent supply. Veos Group occupies a position as a differentiated player through its focus on specific animal plasma fractions for high-value applications.
| Leading Market Players |
|---|
| Sera Scandia |
| Puretein Agri LLC |
| Darling Ingredients Inc. |
| Kraeber & Co GmbH |
| Veos Group |
| Lauridsen Group Inc. |
| Lican Food |
| Rocky Mountain Biologicals |
| SARIA Group |
| Others |
Cost & Logistics Intelligence
Skilled technicians in specialized spray-drying facilities across North America and Europe influence pricing-tier spreads for plasma feed. Labor-cost differentials affect the premium for high-quality, processed plasma, creating distinct pricing for specialized fractions versus commodity powder.
Pricing Analysis
Distributor margins significantly influence the final cost of plasma feed to smaller feed mills. Contract-based long-term offtake dominates for large integrators, while transactional pricing applies to smaller buyers. Quality grade, such as immunoglobulin concentration, and biosecurity certifications, like EFSA compliance, drive premium pricing. Pricing pressure stems from raw material volatility and competition from protein alternatives. Livestock farms in cost-sensitive regions like Southeast Asia are more price-sensitive, while pharmaceutical companies prioritize purity and certified sourcing.
Supply Chain Analysis
Strict biosecurity certifications, such as those from the US FDA and EFSA, gate market access for plasma feed suppliers. Production concentrates in major livestock regions including the United States, Germany, and Brazil. The supply chain critically relies on raw animal blood from abattoirs and specialized spray-drying equipment. Commodity price volatility for raw blood and trade barriers due to animal disease outbreaks pose significant structural risks. Direct sales to large feed manufacturers and integrators form the dominant downstream structure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plasma feed market represents a margin-expansion story, driven by the premium-tier shift towards high-value plasma fractions and advanced spray-drying technologies. These innovations enable specialized products with enhanced efficacy for targeted animal nutrition.
For Market Incumbents: To counter substitution risk from alternative protein sources, incumbents must invest in R&D for novel plasma fractions and scientifically validate their efficacy through animal trials. Deepen upstream control over raw material sourcing through long-term contracts with abattoirs to mitigate supply volatility. Expand spray-drying capacity in key pork-producing regions like China and the United States.
For New Entrants and Emerging Players: Begin with targeting underpenetrated aquaculture feeds in Southeast Asia, focusing on species like shrimp and marine finfish where larval survival is critical. Differentiate by offering enriched plasma feeds with higher concentrations of specific immunoglobulins for niche health challenges. Leverage online platforms for specialized product sales and broader market reach.
For Investors and Strategic Acquirers: Biopharmaceutical companies are the most active acquirers in this space, seeking specialized plasma fractions for drug development and diagnostic reagents. The market offers long-term viability due to sustained regulatory pressure against antibiotic growth promoters. Target mid-sized processors with proprietary fractionation technology or strong biosecurity compliance records. Increased M&A activity involving specialized plasma component manufacturers is a signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Meets growing demand from commercializing livestock sectors in Vietnam and Thailand. |
| Advanced Fractionation Technology Investment | Enables creation of high-value, targeted plasma products for specific health outcomes. |
| Enhanced Traceability Systems | Ensures compliance with stringent biosecurity regulations from EFSA and USDA. |
| Strategic Partnerships with Slaughterhouses | Secures consistent raw material supply and mitigates volatility risks. |
| Clinical Trial Collaboration | Provides performance data and scientific validation for premium plasma ingredients. |
Research Approach
Bottom-up animal nutrition application modeling reconciled against top-down plasma processor capacity tracking forms the analytical core of this study. Primary interviews with animal nutritionists, feed manufacturers, biosecurity experts, and regulatory officials informed market dynamics. Secondary validation drew from USDA reports, EFSA scientific opinions, SAMR feed additive approvals, and industry association publications. This approach ensures robust data triangulation.
An input-output matrix frames the forecast, projecting volume and value across the analysis window. Segmentation dimensions modeled include product type, application, end-user, and distribution channel, alongside regional livestock production intensity. CAGRs were derived using historical trends, regulatory impact assessments, and projected technology adoption rates. Key inputs include global protein demand and antibiotic restriction timelines.
Several conditions sit outside the modeled scope, including unforeseen global pandemics impacting livestock populations or rapid shifts in consumer protein preferences. Forecasts reflect assumptions regarding stable regulatory environments and continued investment in animal health. A model refresh is warranted upon material change in global biosecurity policies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
In Vivo CRO Market
Biotechnology Services
Cell Characterization Assays Kits Market
Biotechnology Services
Bioanalytical Testing Services Market
Biotechnology Services
Global Protein Purification and Isolation Market
Biotechnology Services
Recombinant Proteins Manufacturing Services Market
Biotechnology Services
Global High Throughput Screening Market
Biotechnology Services
Luciferase Assay Market
Biotechnology Services
Cell Lysis and Disruption Market
Biotechnology Services
Loop-Mediated Isothermal Amplification (LAMP) Market
Biotechnology Services
Cell Culture Media Market
Biotechnology Services
Europe Flow Cytometry Market
Biotechnology Services
Cell Lysis and Dissociation Market
Biotechnology Services
Global Alpha Galactosidase Market
Biotechnology Services
Industrial Microbiology Testing Services Market
Biotechnology Services
Drug Discovery Services Market
Biotechnology Services
Plasmid DNA Contract Manufacturing Market