
 France Insulin Drugs and Delivery Devices Market | 2026-2036
France Insulin Drugs and Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
France Insulin Drugs and Delivery Devices Market Foresight
Hospital procurement concentration is hardening across France's regional health agencies, with ARS-led tenders consolidating volume toward fewer approved suppliers. Novo Nordisk leverages its integrated portfolio of analog insulins and connected pens to anchor long-term hospital contracts. Sanofi competes through sustained manufacturing presence within French borders, reducing customs-dependent supply risk for public purchasers.
France Insulin Drugs and Delivery Devices encompass recombinant human and analog insulin formulations alongside mechanical and electronic systems for subcutaneous administration, with modern pumps achieving basal rate precision of 0.025 units per hour and smart pens recording dose-time data via Bluetooth. The primary purpose spans glycemic control in diabetes mellitus, reducing microvascular complications through tighter glucose management. Long-acting insulin formulations occupy the largest revenue pool among drug categories, while insulin pumps represent the fastest-expanding delivery segment driven by reimbursement expansion for Type 1 patients. Pre-filled pens dominate ambulatory channels where home care providers seek reduced needle-stick error rates.
ANSM oversees market authorization and post-market surveillance of insulin products, while CE marking under the EU MDR governs device safety standards for pumps and pen injectors, with notified bodies intensifying clinical evidence requirements for software-enabled delivery systems. France's HAS evaluates therapeutic benefit through SMR-ASMR ratings, directly shaping reimbursement levels that determine patient access and manufacturer pricing latitude. Stakeholders must monitor the convergence of MDR transition timelines with France's national diabetes strategy revisions, as reimbursement list updates will redistribute volume across delivery mechanism categories.
Market Dynamics
Hospital procurement consolidation under France's regional health agencies is compressing supplier margins while accelerating standardization of connected insulin delivery systems across public networks.
Growth Catalysts
- ANSM Pharmacovigilance Modernization:Tighter post-market surveillance requirements for connected devices are accelerating clinical evidence generation, which strengthens reimbursement dossiers submitted to HAS.
- Île-de-France Teaching Hospital Adoption:Parisian academic medical centers are piloting closed-loop pump systems, creating reference sites that diffuse technology standards to regional hospitals.
- Bluetooth-Enabled Dose Logging:Smart pens recording time-stamped injection data are expanding the addressable population for digital therapeutics integration.
Market Restraints
- EU MDR Clinical Evidence Burden:Software-enabled delivery systems now require enhanced technical documentation, extending notified body review timelines and freezing product line extensions.
- Active Pharmaceutical Ingredient Concentration:Recombinant insulin bulk manufacturing concentrates in Danish and German facilities, exposing French formulators to cross-border supply disruptions.
- Biologic Substitution Limits:Interchangeability restrictions on insulin analogs prevent automatic pharmacy substitution, preserving originator pricing power and limiting cost containment.
Strategic Opportunities
- Auvergne-Rhône-Alpes Regional Expansion:Lyon-based hospital groups are consolidating diabetes care pathways, creating procurement templates replicable across southeastern France.
- Home Care Provider Channel Integration:Nursing networks are assuming pump initiation and training functions previously hospital-bound, opening ambulatory volume.
- SMR-ASMR Rating Optimization:Manufacturers structuring real-world evidence programs to secure improved HAS reimbursement ratings can unlock premium pricing corridors.
Industry Challenges
- Diabetes Technology Specialist Shortage:Endocrinology departments face recruitment gaps for pump-certified educators, constraining patient onboarding capacity.
- Legacy HIS Integration Complexity:Connected pen and pump data streams require middleware development to interface with heterogeneous hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Insulin Drugs and Delivery Devices Market |
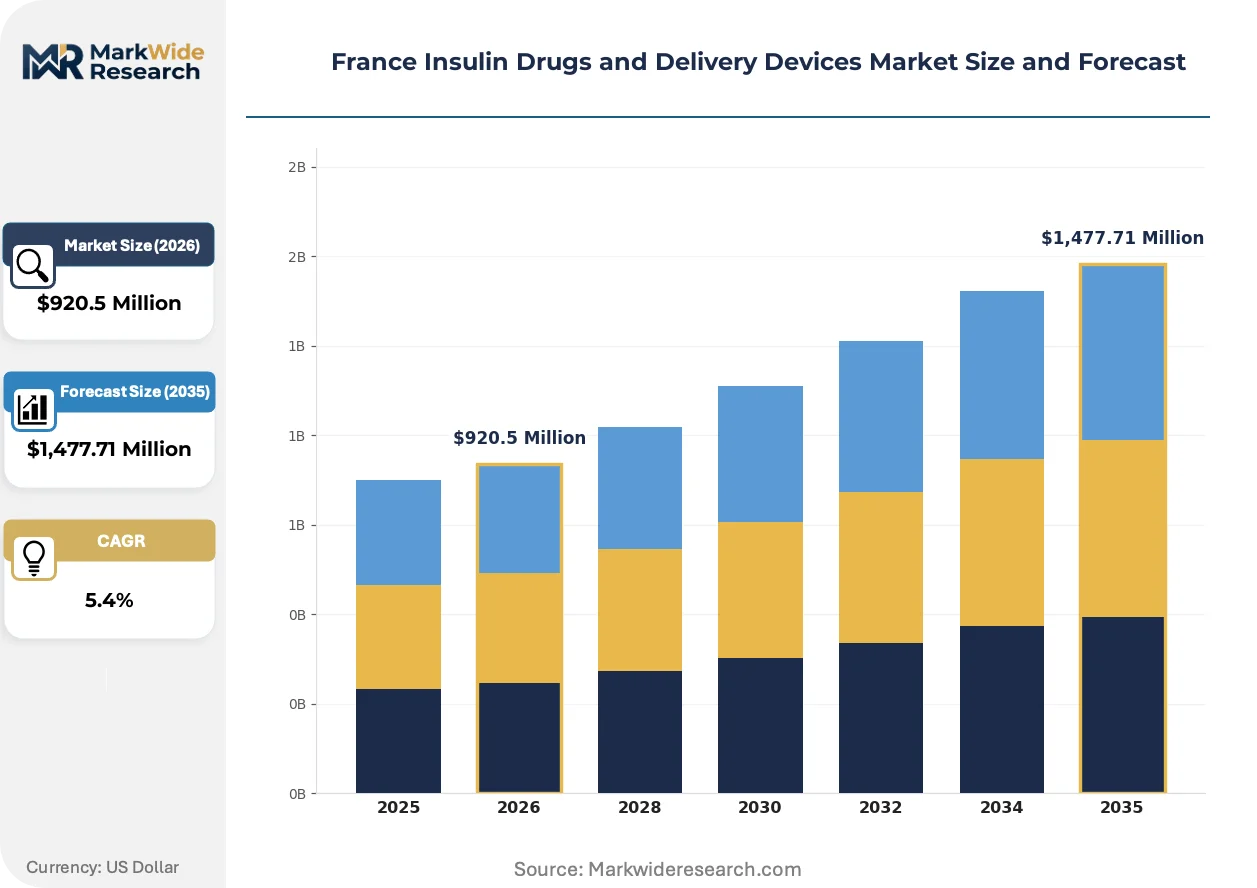
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $1,477.71 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid-Acting Insulin, Long-Acting Insulin, Premixed Insulin, Insulin Pumps, Pre-Filled Pens, Disposable Syringes Delivery Mechanism: Injection, Insulin Pen, Continuous Subcutaneous Insulin Infusion, Inhalable Insulin, Jet Injector Patient Segment: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Pediatric Patients, Geriatric Patients End User: Hospitals, Diabetes Care Centers, Specialty Clinics, Home Care Providers |
| Companies Covered | Novo Nordisk, Sanofi, Eli Lilly, Medtronic, Ypsomed, Becton Dickinson, Biocon, Embecta Corp., Roche, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Insulin Drugs and Delivery Devices Market Shifts & Advancements
Closed-loop automation and real-world data capture are converging to shift diabetes management from episodic clinical encounters toward continuous algorithmic intervention.
Artificial pancreas systems integrating continuous glucose monitors with algorithm-controlled insulin pumps are decentralizing glycemic control from hospital endocrinology units toward patient-managed home environments. Type 1 diabetes centers in Paris and Marseille are expanding pump prescription eligibility to adolescents with suboptimal injection therapy adherence. This shift is compressing the role of specialized diabetes nurses toward remote monitoring and troubleshooting rather than in-person dose titration.
France's national diabetes program revisions are mandating interoperability standards for connected devices, forcing manufacturers to adopt common data exchange protocols. The ANSM is aligning software lifecycle requirements with EU MDR cybersecurity annexes, elevating documentation burdens for algorithm updates. Pump manufacturers are responding by modularizing hardware platforms to isolate regulatory recertification to software components alone.
Hospital group purchasing organizations are unbundling device procurement from consumables contracts, reversing historical bundled-supply arrangements. ARS-led regional tenders now separate pump capital acquisition from infusion set and reservoir recurring purchases, enabling mixed-supplier configurations. This pattern is most visible in Grand Est and Hauts-de-France, where procurement teams are negotiating three-year device leases with volume-flexible consumables riders.
France Insulin Drugs and Delivery Devices Market Segmentation
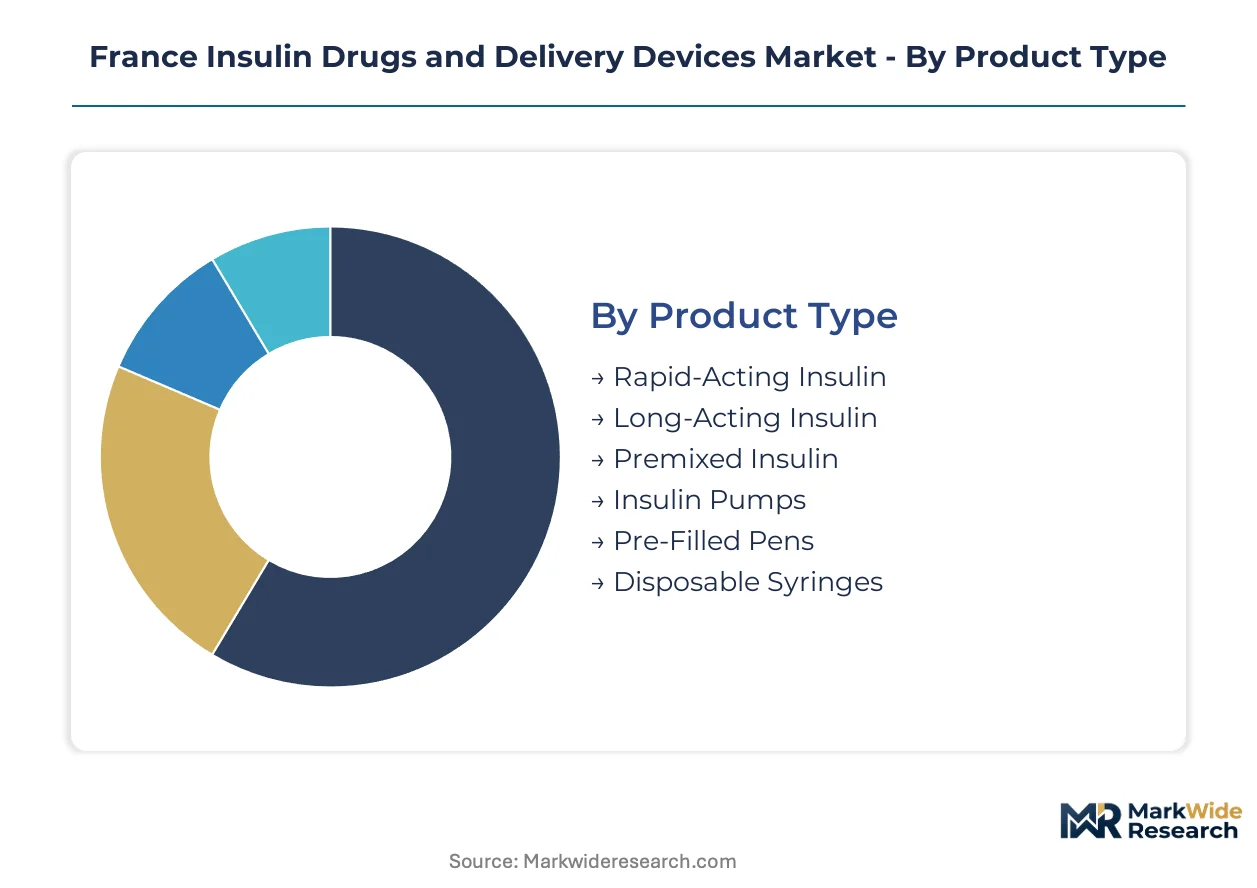
Segmentation of the France Insulin Drugs and Delivery Devices Market reveals how reimbursement pathways, patient acuity, and care setting economics allocate volume across formulation types and delivery technologies. Understanding these splits enables suppliers to align clinical evidence generation with HAS evaluation criteria and regional procurement templates.
Product Type:
Technology differentiation in insulin formulations and delivery hardware determines reimbursement tier placement and patient access pathways across French healthcare networks.
- Long-Acting Insulin:Basal analog formulations such as glargine and degludec provide 24-hour glycemic coverage with reduced hypoglycemia risk. Demand concentrates in ambulatory settings where HAS SMR-ASMR ratings favor these agents for Type 2 patients with adherence challenges in Île-de-France and Auvergne-Rhône-Alpes.
- Insulin Pumps:Electronic delivery systems achieving basal rate precision of 0.025 units per hour integrate with continuous glucose monitors for closed-loop control. Parisian teaching hospitals drive early adoption, with ARS-led tenders now expanding pump eligibility to adolescent Type 1 patients across Grand Est.
- Rapid-Acting Insulin:Prandial analogs including lispro and aspart enable post-meal glucose correction.
- Premixed Insulin:Fixed-ratio basal-bolus combinations simplify dosing for elderly patients with cognitive limitations.
- Pre-Filled Pens:Disposable injection devices reduce needle-stick errors in home care environments.
- Disposable Syringes:Basic vial-and-syringe administration persists in cost-constrained hospital formularies.
Mature deployment sits with Long-Acting Insulin formulations dominating prescription volumes. Newer deployment is concentrated in Insulin Pumps gaining share fastest through expanded Type 1 reimbursement.
Delivery Mechanism:
Patient self-management capability and care setting infrastructure determine which administration modality achieves procurement preference in French diabetes pathways.
- Continuous Subcutaneous Insulin Infusion:Pump-based basal-bolus delivery with algorithmic dose adjustment enables tight glycemic control for brittle Type 1 diabetes. Adoption concentrates in pediatric and adolescent populations at CHU de Paris and Marseille university hospitals, where ANSM pharmacovigilance requirements for connected devices are shaping registration timelines.
- Insulin Pen:Cartridge-based reusable and disposable injection systems dominate adult Type 2 management. Home care providers in Hauts-de-France and Nouvelle-Aquitaine favor Bluetooth-enabled pens for remote dose monitoring, expanding the addressable population for digital therapeutics integration.
- Injection:Traditional vial-and-syringe administration remains in hospital inpatient protocols.
- Inhalable Insulin:Pulmonary delivery of prandial insulin offers needle-free alternatives for phobic patients.
- Jet Injector:Needle-free pressure-based delivery systems serve specific dermatological sensitivities.
Standard care relies on Injection and Insulin Pen modalities. Steepest expansion trajectory belongs to Continuous Subcutaneous Insulin Infusion as closed-loop automation diffuses from academic centers.
Patient Segment:
Disease etiology and demographic factors shape insulin requirement profiles, dosing complexity, and reimbursement justification in France's national diabetes program.
- Type 1 Diabetes:Absolute insulin deficiency requiring lifelong exogenous replacement drives demand for pump-eligible populations. HAS reimbursement expansion for adolescent patients with suboptimal injection adherence is accelerating device adoption in Lyon and Paris diabetes centers.
- Type 2 Diabetes:Progressive beta-cell dysfunction creates expanding insulin initiation needs as oral agents fail. Volume concentrates in geriatric populations across regional hospital networks where biologic substitution limits preserve originator analog pricing.
- Gestational Diabetes:Pregnancy-induced insulin resistance requires short-term glycemic management.
- Pediatric Patients:Growth-adjusted dosing and family education needs favor pump therapy initiation.
- Geriatric Patients:Cognitive and dexterity limitations drive preference for simplified pen devices.
Largest prescription volume sits with Type 2 Diabetes. Fastest-growing eligibility expansion targets Type 1 Diabetes through pediatric and adolescent pump access programs.
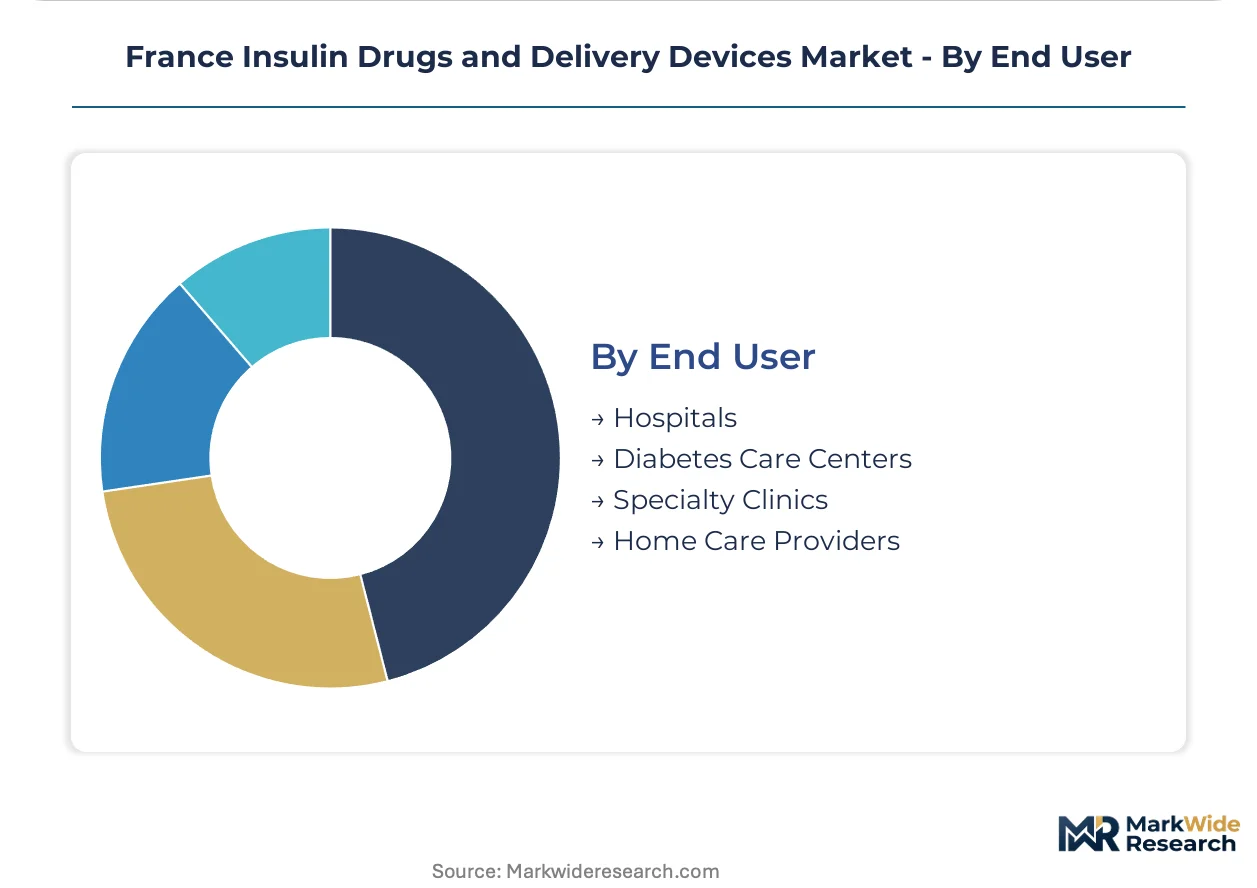
End User:
Care setting economics and patient acuity determine procurement authority and device sophistication requirements across French healthcare delivery.
- Hospitals:Acute care settings and regional diabetes centers manage inpatient glycemic crises and pump initiations. ARS-led tender consolidation in Grand Est and Hauts-de-France is hardening procurement concentration toward fewer approved suppliers with integrated insulin and device portfolios.
- Home Care Providers:Nursing networks assume pump training and troubleshooting functions previously hospital-bound. Auvergne-Rhône-Alpes home care organizations are pioneering remote monitoring protocols that diffuse to southeastern France regional groups.
- Diabetes Care Centers:Specialized endocrinology units concentrate pump-certified educator expertise.
- Specialty Clinics:Private endocrinology practices manage stable Type 2 patients with pen-based regimens.
Institutional purchasing power centers on Hospitals. Volume migration is accelerating toward Home Care Providers as reimbursement shifts favor ambulatory diabetes management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for insulin drugs and delivery devices concentrates heavily in Île-de-France, where Parisian teaching hospitals drive early adoption of closed-loop pump systems and anchor procurement volumes for connected delivery technologies.
Île-de-France
Parisian academic medical centers at CHU de Paris and Assistance Publique-Hôpitaux de Paris pilot artificial pancreas systems, creating reference sites that diffuse technology standards to regional hospital networks. ANSM pharmacovigilance requirements for connected devices shape registration timelines for manufacturers seeking HAS reimbursement approval. The concentration of endocrinology expertise in Paris generates disproportionate pump prescription volumes relative to population share.
Auvergne-Rhône-Alpes
Lyon-based hospital groups consolidate diabetes care pathways, creating procurement templates replicable across southeastern France. HAS reimbursement expansion for adolescent Type 1 patients accelerates device adoption in Lyon university hospitals. Home care organizations in the region pioneer remote monitoring protocols that diffuse to neighboring regional health agencies.
Grand Est
ARS-led tender consolidation compresses supplier margins while accelerating standardization of connected insulin delivery systems across public networks. Regional procurement teams negotiate three-year pump device leases with volume-flexible consumables riders, unbundling historical bundled-supply arrangements. Strasbourg and Nancy university hospitals anchor diabetes technology adoption in the northeastern corridor.
Hauts-de-France
Home care providers in Lille and surrounding nursing networks assume pump training functions previously hospital-bound, opening ambulatory volume migration. Bluetooth-enabled smart pens gain preference among home care organizations for remote dose monitoring capabilities. Regional hospital procurement concentration hardens toward fewer approved suppliers with integrated insulin and device portfolios.
Provence-Alpes-Côte d'Azur
Marseille university hospitals expand pump prescription eligibility to adolescents with suboptimal injection therapy adherence, replicating Parisian adoption patterns. The region's diabetes centers face recruitment gaps for pump-certified educators, constraining patient onboarding capacity relative to device availability. Mediterranean climate factors influence patient preference for wearable pump systems over injection regimens.
France Insulin Drugs and Delivery Devices Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital therapeutics integration and closed-loop automation partnerships. The market structure consolidates around integrated portfolios spanning analog insulins and connected delivery hardware, with hospital procurement favoring suppliers offering bundled drug-device contracts. Three archetypes dominate: multinational pharmaceutical conglomerates with captive insulin manufacturing, specialized diabetes technology developers focusing on pump and sensor systems, and diversified medical device manufacturers supplying injection delivery platforms. Competitive moves center on securing long-term hospital contracts through ARS-led regional tenders and modularizing hardware platforms to isolate regulatory recertification burdens.
Among Denmark-based insulin specialists, Novo Nordisk anchors the integrated portfolio archetype combining analog insulins with connected pen systems. Sanofi occupies a position exemplifying sustained European manufacturing presence that reduces customs-dependent supply risk for French public purchasers. Eli Lilly represents the rapid-acting and long-acting formulation specialist tier within the competitive landscape.
| Leading Market Players |
|---|
| Novo Nordisk |
| Sanofi |
| Eli Lilly |
| Medtronic |
| Ypsomed |
| Becton Dickinson |
| Biocon |
| Embecta Corp. |
| Roche |
| Others |
Supply & Pricing Matrix
Pump-certified diabetes educator shortages in Île-de-France and Auvergne-Rhône-Alpes widen labor-cost spreads between premium closed-loop systems and standard pen-based therapies, compressing mid-tier pricing corridors as hospitals consolidate procurement under ARS-led tenders.
Pricing Analysis
Volume concentrates in long-acting insulin analogs where HAS SMR-ASMR ratings preserve originator pricing power, while margins compress fastest in electronic delivery systems facing EU MDR recertification burdens. Price differentiation hinges on CE marking tier under EU MDR and bundled drug-device contract availability. Pricing pressure stems from ARS-led regional tenders unbundling devices from consumables. Home care providers exhibit highest price sensitivity; Parisian teaching hospitals show lowest sensitivity given pilot program budgets.
Supply Chain Analysis
Regional distribution centers in Denmark and Germany anchor recombinant insulin API flows to French formulators, with warehouse layers in Lyon and Paris managing last-mile hospital and home care deployment. Active pharmaceutical ingredient manufacturing concentrates in Danish and German facilities; electronic pump components source from Swiss and German precision engineering hubs. Supply chain risk centers on single-source vulnerability for recombinant insulin bulk. Distribution runs through ARS-coordinated regional hospital group purchasing organizations with three-year lease structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France insulin market has become a vertical-integration race where captive control over connected pen data streams and algorithmic dosing software determines long-term contract viability with consolidating hospital networks.
For Market Incumbents: Acquire real-world evidence generation capabilities to secure improved HAS reimbursement ratings, while deepening backward integration into continuous glucose monitor sensor manufacturing to reduce customs-dependent component exposure. Novo Nordisk's integrated portfolio anchors hospital contracts; Sanofi's French manufacturing presence reduces supply risk for ARS purchasers. Defend against emerging diabetes technology developers by modularizing hardware platforms to isolate regulatory recertification to software components alone. For New Entrants and Emerging Players: Begin with Bluetooth-enabled smart pen systems for home care providers in Hauts-de-France and Nouvelle-Aquitaine, where remote dose monitoring protocols are expanding fastest. Target adolescent Type 1 diabetes pump eligibility expansion in Lyon and Marseille, where HAS reimbursement revisions are opening new patient populations. Partner with nursing networks assuming pump training functions previously hospital-bound to bypass concentrated hospital procurement barriers. For Investors and Strategic Acquirers: Re-rating potential sits with specialized diabetes technology developers possessing FDA breakthrough device designation and European notified body MDR certification, given ANSM pharmacovigilance requirements are extending registration timelines for uncertified competitors. Long-term viability favors platforms with modular hardware architectures and software subscription revenue streams. Watch for ARS tender announcements unbundling device and consumables contracts as the inflection signal for mixed-supplier configuration opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Real-World Evidence Program Development | Structured evidence generation secures improved HAS SMR-ASMR ratings and premium pricing corridors. |
| Modular Hardware Platform Engineering | Isolates EU MDR recertification to software components, accelerating algorithm update deployment. |
| Home Care Provider Channel Partnership | Nursing networks in Auvergne-Rhône-Alpes pioneer remote monitoring protocols replicable across regions. |
| Closed-Loop Automation Integration | Artificial pancreas systems at CHU de Paris create reference sites diffusing standards to regional hospitals. |
| ARS Tender Response Optimization | Three-year device lease structures with volume-flexible consumables riders match Grand Est procurement templates. |
Research Methodology
ANSM regulatory filings, HAS reimbursement dossiers, and ARS regional tender databases formed the secondary backbone, supplemented by primary interviews with hospital procurement managers, diabetes center clinical directors, biomedical engineers, and home care network operations leads. Bottom-up prescription volume modeling triangulated against top-down healthcare expenditure flows from French national health insurance accounts.
Historical trendline analysis of insulin delivery device adoption rates across Parisian teaching hospitals and regional hospital networks established baseline penetration curves. Segmentation modeling spanned formulation type, delivery mechanism sophistication, patient diabetes etiology, and care setting procurement authority. CAGRs derived from polynomial trend fitting of reimbursement expansion scenarios and technology diffusion coefficients from academic medical center pilot programs.
Underlying measurement precision varies by segment; insulin pump volume projections carry tighter precision than inhalable insulin adoption curves given established reimbursement pathways. Forecasts reflect assumptions of continued ARS procurement consolidation and EU MDR transition timeline adherence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Generic Drugs Market
Biopharmaceuticals
Global Flu Vaccine Market
Biopharmaceuticals
Bioequivalence Studies Market
Biopharmaceuticals
Human Insulin Drugs Market
Biopharmaceuticals
1-Step RT-PCR Kits Market
Biopharmaceuticals
Global Thrombin Market
Biopharmaceuticals
Pruritus Therapeutics Market
Biopharmaceuticals
Triclabendazole Market
Biopharmaceuticals
Russia Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Erythropoietin Drugs Market
Biopharmaceuticals
Liposomal Doxorubicin Market
Biopharmaceuticals
HIV Market
Biopharmaceuticals
Octreotide Market
Biopharmaceuticals
Mefentrifluconazole Market
Biopharmaceuticals
North Africa Generic Drug Market
Biopharmaceuticals
Anti-Neoplastic Pharmaceutical Agents Market