
 Rhu Albumin Market | 2026-2036
Rhu Albumin Market Size, Share, and Industry Trends Forecast 2026-2036
Rhu Albumin Market Insights
GMP certification for recombinant therapeutic proteins is unwinding competitive access across the Rhu Albumin landscape. Baxter International Inc leverages its plasma fractionation heritage to anchor hospital supply contracts in mature markets. Octapharma AG competes through specialized recombinant production infrastructure in European biomanufacturing zones. Merck KGaA differentiates via integrated cell culture media systems that bundle albumin with upstream bioprocessing workflows.
Recombinant human albumin (Rhu Albumin) comprises a 585-amino acid single-chain protein expressed in yeast or mammalian cell lines, engineered to match plasma-derived serum albumin in molecular weight and ligand-binding capacity. It functions as an excipient in biologic drug formulations, a stabilizer in cell culture media, and a volume expander in clinical settings. Lyophilized products command premium positioning due to cold-chain elimination and extended shelf stability in hospital pharmacies. Drug delivery applications lead volume absorption as monoclonal antibody manufacturers adopt serum-free media protocols. Research laboratories represent the fastest-growing end user segment as contract development organizations expand cell-line engineering programs.
FDA, EMA, and WHO standards collectively govern Rhu Albumin purity thresholds, viral clearance validation, and endotoxin limits that determine market entry eligibility. These frameworks compel manufacturers to maintain dedicated recombinant production suites rather than shared-use facilities, elevating capital requirements for new entrants. Stakeholders must monitor evolving pharmacopeial monograph revisions that could redefine acceptable host-cell protein contamination levels.
Market Dynamics
Plasma supply volatility is forcing biopharmaceutical manufacturers to reconfigure excipient sourcing strategies around recombinant alternatives, tightening qualification timelines and supplier consolidation pressures across formulation supply chains.
Growth Catalysts
- FDA Purity Benchmarks:Tightened endotoxin and host-cell protein thresholds for recombinant therapeutics are disqualifying legacy plasma-derived suppliers from new drug master files, accelerating Rhu Albumin qualification in monoclonal antibody manufacturing.
- Serum-Free Media Protocols:Cell culture media formulators are eliminating bovine and human serum components to mitigate transmissible spongiform encephalopathy risks, creating immediate substitution demand for recombinant albumin as a chemically defined stabilizer.
- Germany Biomanufacturing Clusters:Concentrated expansion of contract development and manufacturing organizations around Heidelberg and Munich is generating localized procurement pull for GMP-certified recombinant excipients with auditable yeast or mammalian expression lineages.
Market Restraints
- Dedicated Production Suite Capital:EMA and FDA mandates for segregated recombinant manufacturing infrastructure require USD 50-120 million facility investments, elevating breakeven volumes beyond reach of mid-scale entrants.
- Chinese Recombinant Capacity Concentration:A limited cohort of yeast-expression specialists controls bulk recombinant albumin supply, creating single-source vulnerability for European formulation houses dependent on just-in-time excipient delivery.
- Plasma-Derived Price Anchoring:Fractionated human serum albumin from established plasma collectors maintains 30-40% cost advantage in volume expander applications, compressing recombinant pricing power in clinical settings.
Strategic Opportunities
- India CDMO Expansion:Contract development and manufacturing organizations in Hyderabad and Bengaluru are building biologics capacity without legacy plasma infrastructure, creating greenfield adoption pathways for recombinant excipients.
- Lyophilized Formulation Growth:Cold-chain elimination requirements for rural hospital distribution are driving demand for stabilized, ambient-temperature biologic formulations where recombinant albumin enables extended shelf life.
- Cell Therapy Manufacturing:Chimeric antigen receptor T-cell production protocols require serum-free expansion media, opening a specialized application segment with premium excipient specifications and limited incumbent competition.
Industry Challenges
- Yeast Expression Purification Expertise:Scarcity of process engineers capable of optimizing Pichia pastoris secretion systems and downstream chromatography trains is extending facility commissioning timelines by 12-18 months.
- Pharmacopeial Harmonization Delays:Divergent host-cell protein acceptance criteria between USP, EP, and JP monographs force manufacturers to maintain multiple product specifications, complicating inventory management and release testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rhu Albumin Market |
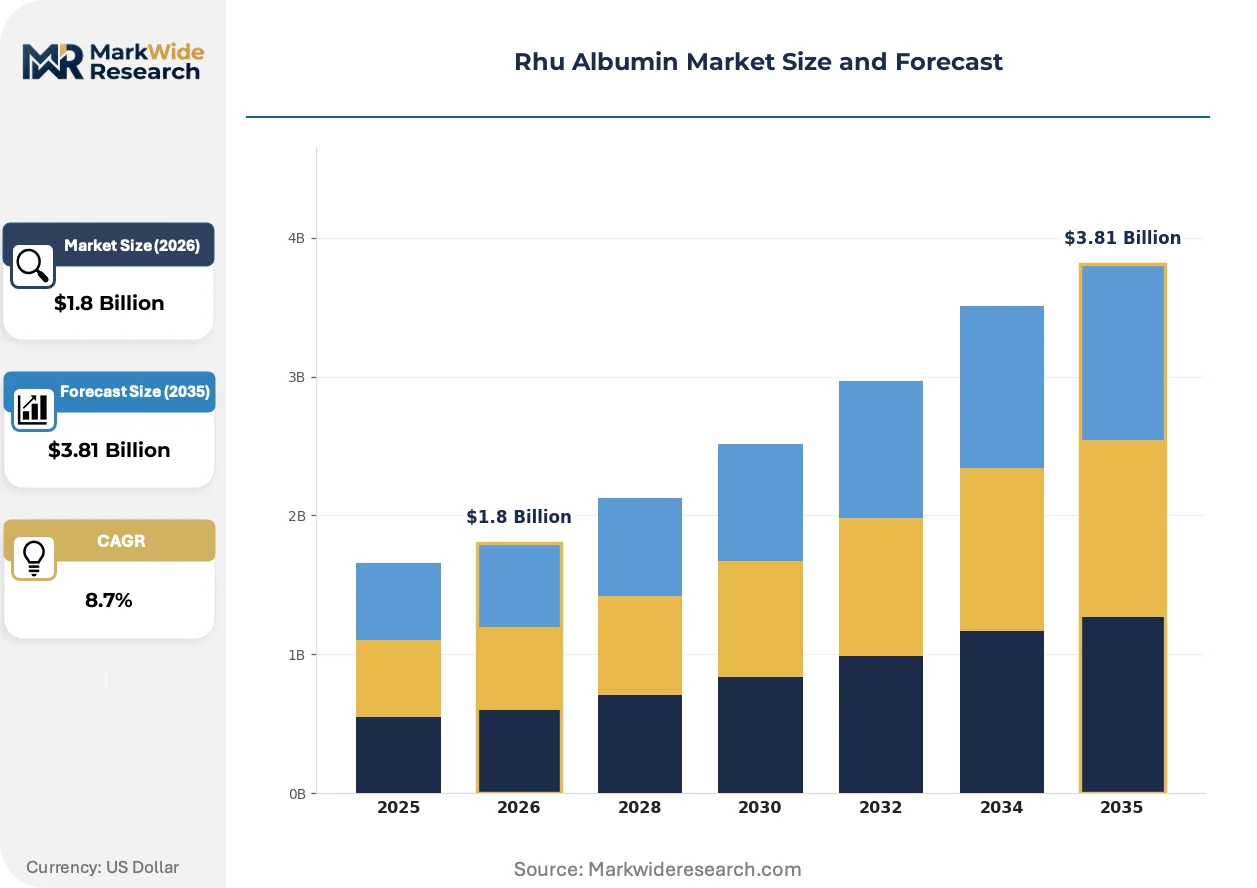
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intravenous Solutions, Inhalable Formulations, Lyophilized Products, Diagnostic Kits End User: Hospitals, Research Laboratories, Clinics, Blood Banks Distribution Channel: Online Pharmacies, Hospital Pharmacies, Retail Pharmacies, Direct Sales Application: Drug Delivery, Nutritional Supplementation, Diagnostic Testing, Transfusion Support |
| Companies Covered | Merck KGaA, HiMedia Laboratories Pvt. Ltd., Albumedix, InVitria, ScienCell Research Laboratories, Inc., Lee Biosolutions, Inc., Abcam Plc, Baxter International Inc, Octapharma AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rhu Albumin Market Trends and Innovations
Continuous manufacturing architectures and single-use bioreactor systems are compressing batch cycle times while regulatory agencies harmonize quality expectations around process analytical technology verification.
Yeast-derived recombinant albumin expressed in Pichia pastoris systems is supplanting plasma-derived alternatives in monoclonal antibody formulation buffers. Contract manufacturing organizations in the United States and Germany have completed supplier qualification switches within 18-month windows. This substitution is compressing viral clearance validation burdens while eliminating lot-to-lot variability from pooled human donors.
EMA's revised guidelines on host-cell protein immunogenicity risk assessment now require quantitative mass spectrometry characterization of residual yeast or mammalian proteins in recombinant excipients. Biopharmaceutical sponsors must submit orthogonal detection methods with new drug applications. European formulation houses are responding by demanding certificate of analysis packages with peptide mapping data from albumin suppliers.
Biopharmaceutical procurement teams are consolidating excipient supplier panels from 8-12 vendors to 3-4 strategic partners with dedicated quality agreements. Large-cap drug manufacturers are displacing spot-market purchasing with multi-year supply contracts incorporating capacity reservation fees. This concentration is most visible among United States-based monoclonal antibody producers seeking supply security for blockbuster product lines.
Rhu Albumin Market Segmentation
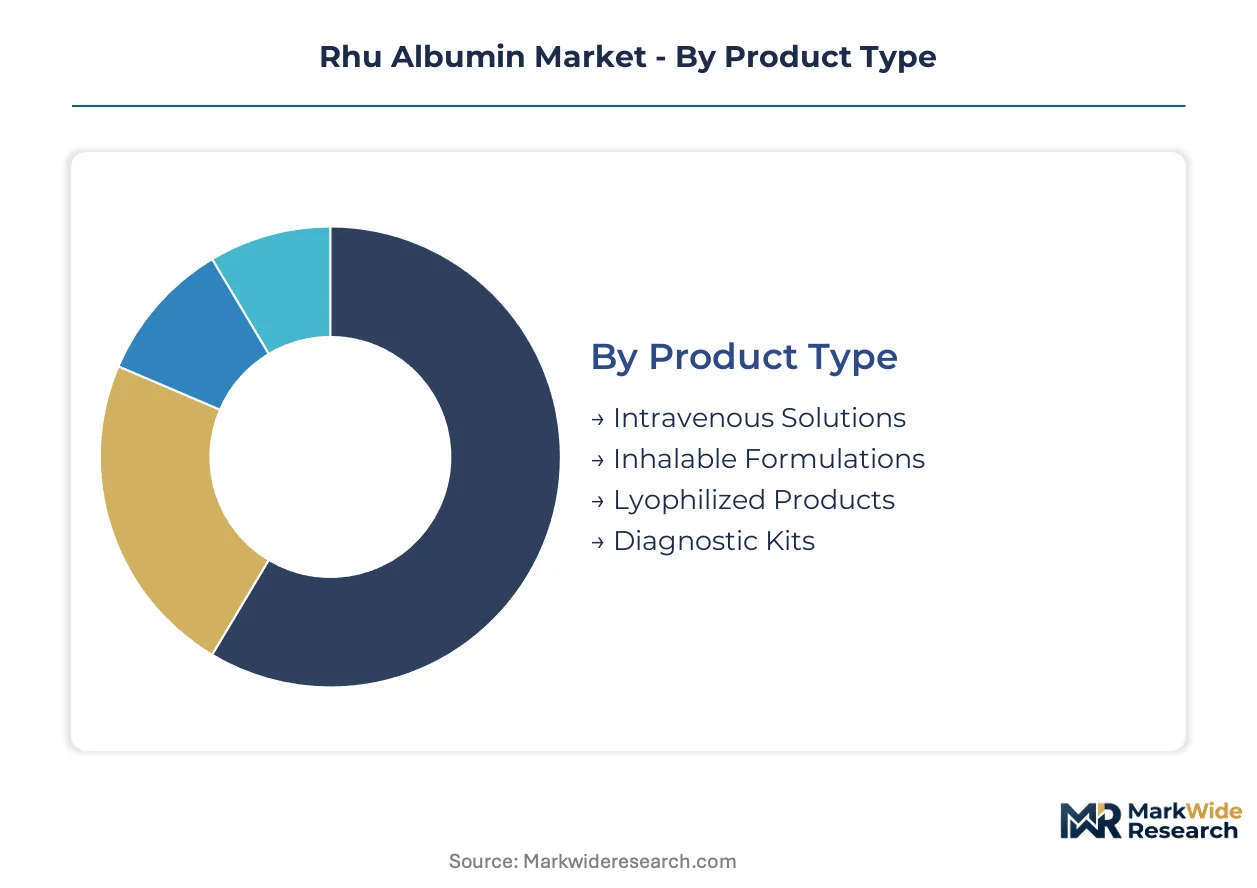
Segmentation in the Rhu Albumin market reveals how formulation requirements, procurement pathways, and end-use specifications create distinct competitive arenas. Each category channels different margin structures and regulatory burdens across the value chain.
Product Type:
Domestic procurement dominates lyophilized and intravenous formats in North American and European hospital systems, while inhalable and diagnostic formats show heavier export orientation toward Asia-Pacific manufacturing hubs.
- Lyophilized Products:Freeze-dried recombinant albumin eliminates cold-chain dependency and extends shelf stability to 36 months at ambient temperatures. Hospital pharmacies in the United States and Germany are consolidating procurement around these formats for rural distribution networks where refrigeration infrastructure is sparse. FDA stability testing requirements for lyophilized biologics add 8-12 months to qualification timelines.
- Intravenous Solutions:Liquid formulations for volume expansion and drug delivery require sterile aqueous preparation with endotoxin limits below 0.5 EU/mL per USP standards. Demand concentrates in tertiary care hospitals performing monoclonal antibody infusions, where albumin functions as both excipient and patient volume support. EMA batch release testing for intravenous recombinant proteins maintains stricter host-cell protein thresholds than diagnostic-grade alternatives.
- Inhalable Formulations:Pulmonary delivery systems utilize recombinant albumin as a stabilizer for protein therapeutics and vaccines. Japanese pharmaceutical manufacturers lead qualification programs for nebulized biologic formulations targeting respiratory indications.
- Diagnostic Kits:Immunoassay and cell culture applications employ non-GMP recombinant albumin as a blocking agent or nutrient supplement. Research laboratories in contract development organizations drive spot-market purchasing with lower purity specifications.
Lyophilized products hold the largest share; momentum sits with inhalable formulations as pulmonary biologic delivery expands.
End User:
Cost tier separation is pronounced: hospitals and blood banks operate under capitated reimbursement with price sensitivity on volume expanders, while research laboratories absorb premium pricing for specialized cell culture grades.
- Research Laboratories:Contract development organizations and academic cell engineering facilities purchase recombinant albumin for serum-free media formulation and cryopreservation protocols. CDMO clusters around Heidelberg, Munich, and Boston are expanding captive cell-line development programs that specify auditable yeast expression lineages. Peptide mapping documentation requirements from EMA guidelines are extending supplier qualification cycles by 6-9 months.
- Hospitals:Inpatient facilities utilize recombinant albumin for hypovolemia management and as an excipient in compounded biologic infusions. United States health system procurement consortia are consolidating supplier panels from 6-8 vendors to 2-3 strategic partners with dedicated quality agreements.
- Clinics:Outpatient infusion centers administer albumin-stabilized therapeutics in ambulatory settings. German outpatient oncology networks are adopting prefilled syringe formats to reduce compounding labor costs.
- Blood Banks:Plasma fractionation facilities and transfusion services employ recombinant albumin as a stabilizer in red blood cell preservation solutions. Japanese Red Cross blood centers are piloting recombinant alternatives to plasma-derived albumin in additive solutions.
Hospitals represent the highest volume tier; research laboratories are climbing the fastest as cell therapy manufacturing scales.
Distribution Channel:
Channel selection tracks customer scale and urgency: direct sales and hospital pharmacies serve just-in-time biopharmaceutical manufacturing, while retail and online channels capture smaller research quantities.
- Direct Sales:Manufacturer-to-sponsor relationships dominate biopharmaceutical excipient procurement, with multi-year supply contracts incorporating capacity reservation fees. Large-cap monoclonal antibody producers in the United States and Germany are displacing spot-market purchasing with structured agreements covering 3-5 year horizons. FDA drug master file cross-referencing requirements favor direct supplier relationships over intermediated channels.
- Hospital Pharmacies:Integrated health system distribution captures intravenous and lyophilized formats for inpatient administration. Group purchasing organizations in North America are negotiating tiered pricing based on annual volume commitments.
- Retail Pharmacies:Community pharmacy networks stock limited albumin inventory for outpatient volume expansion therapy. Reimbursement compression on plasma-derived alternatives limits recombinant penetration in this channel.
- Online Pharmacies:E-commerce platforms serve research laboratories and small clinics with catalog purchasing of diagnostic-grade and non-GMP formats. Indian CDMOs in Hyderabad and Bengaluru are utilizing digital procurement channels for initial supplier qualification before transitioning to direct sales.
Direct sales command the dominant share; online pharmacies are gaining share fastest as remote research procurement normalizes post-pandemic.
Application:
Application maturity varies: drug delivery and transfusion support operate at commercial scale with defined pharmacopeial standards, while diagnostic testing and nutritional supplementation remain fragmented with lower regulatory barriers.
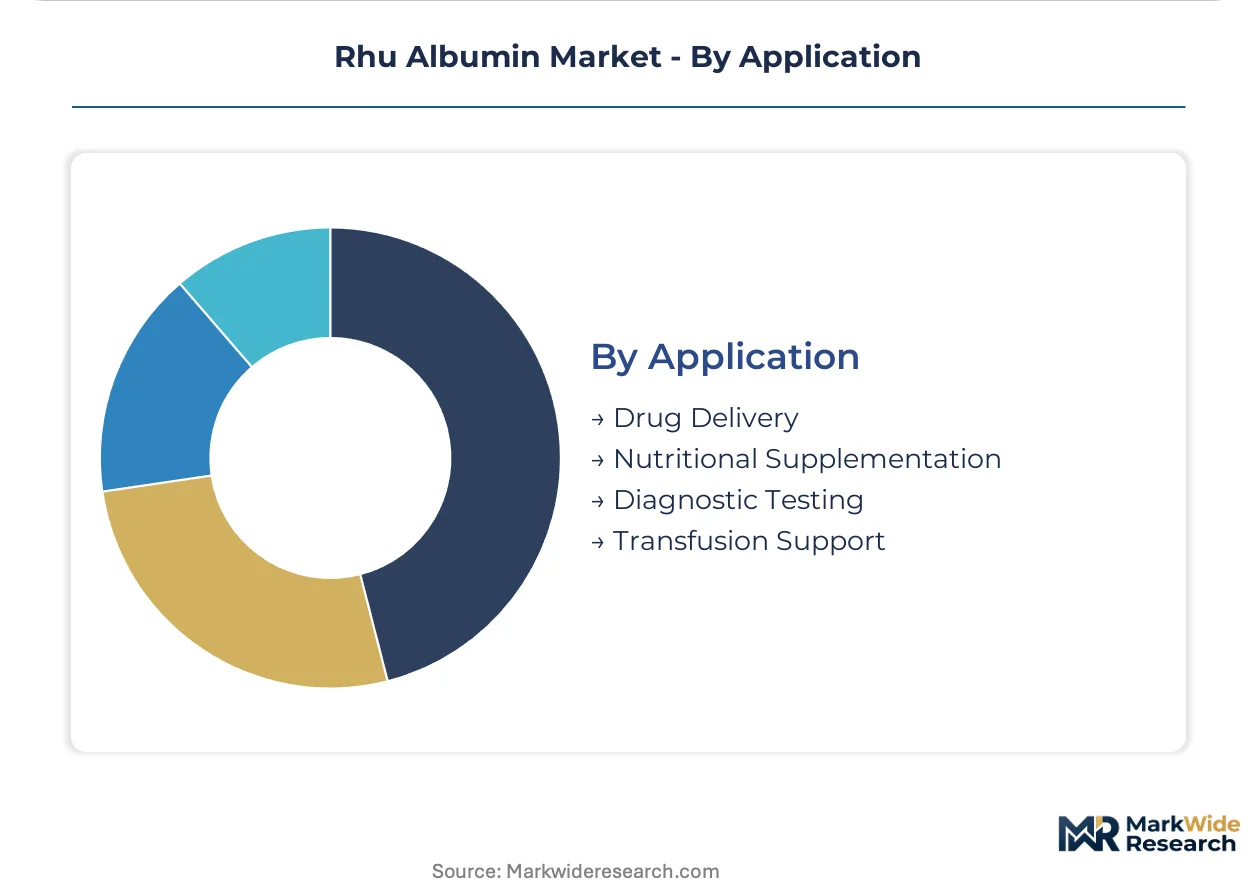
- Drug Delivery:Recombinant albumin functions as a stabilizer, solubility enhancer, and half-life extender in monoclonal antibody, fusion protein, and peptide formulations. Biopharmaceutical manufacturers in the United States, Germany, and Japan have completed supplier qualification switches from plasma-derived to recombinant excipients within 18-month windows. EMA host-cell protein immunogenicity risk assessments now require quantitative mass spectrometry characterization for new drug applications.
- Transfusion Support:Volume expansion and plasma protein replacement in surgical and critical care settings utilize both intravenous solutions and lyophilized formats. Japanese and German hospital systems are expanding recombinant procurement as plasma collection constraints tighten fractionated supply.
- Diagnostic Testing:Immunoassay blocking buffers, cell culture media supplements, and calibrator formulations employ lower-purity recombinant grades. Research reagent manufacturers in contract development organizations drive demand with less stringent viral clearance documentation.
- Nutritional Supplementation:Enteral and parenteral nutrition formulations incorporate albumin for protein support in malabsorption syndromes. Clinical adoption remains limited by cost disadvantage versus synthetic amino acid solutions.
Drug delivery holds the largest share; diagnostic testing shows steepest expansion trajectory as cell-line engineering programs multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA tightened endotoxin thresholds for recombinant therapeutics in 2024, accelerating supplier qualification timelines for biopharmaceutical manufacturers seeking plasma-free excipients. Germany's EMA-aligned GMP certification requirements and Japan's PMDA stability protocols are synchronizing purity benchmarks across major production clusters.
United States
Monoclonal antibody manufacturers in Massachusetts and California completed 18-month supplier switches from plasma-derived to recombinant albumin. FDA drug master file cross-referencing requirements favor direct manufacturer relationships, consolidating procurement panels from 8-12 vendors to 3-4 strategic partners. Boston's contract development organizations are expanding captive cell-line engineering programs that specify auditable yeast expression lineages.
Germany
Heidelberg and Munich biomanufacturing clusters are generating localized procurement pull for GMP-certified recombinant excipients. EMA revised guidelines on host-cell protein immunogenicity risk assessment now mandate quantitative mass spectrometry characterization for new drug applications. Bavarian formulation houses are demanding certificate of analysis packages with peptide mapping data from albumin suppliers.
Japan
Japanese Red Cross blood centers pilot recombinant alternatives to plasma-derived albumin in red blood cell preservation solutions. PMDA stability testing protocols for lyophilized biologics add 8-12 months to qualification timelines. Tokyo and Osaka pharmaceutical manufacturers lead qualification programs for nebulized biologic formulations targeting respiratory indications.
India
Hyderabad and Bengaluru contract development organizations are building biologics capacity without legacy plasma infrastructure, creating greenfield adoption pathways for recombinant excipients. CDSCO biopharmaceutical manufacturing guidelines align with ICH Q5D standards for cell substrate qualification. Indian CDMOs utilize digital procurement channels for initial supplier qualification before transitioning to direct sales agreements.
China
A concentrated cohort of yeast-expression specialists controls bulk recombinant albumin supply, creating single-source vulnerability for European formulation houses. NMPA viral clearance validation requirements for recombinant therapeutics mirror FDA benchmarks. Shanghai and Suzhou biomanufacturing zones are expanding serum-free media production capacity for export markets.
Rhu Albumin Market Competitive Landscape
Player mix skews toward plasma fractionation heritage companies diversifying into recombinant production and specialized bioprocessing suppliers bundling excipients with upstream workflows. The vendor base separates into three archetypes: integrated life science conglomerates with cell culture media portfolios, dedicated recombinant protein specialists with yeast expression platforms, and plasma-derived fractionators extending into engineered alternatives. Dominant competitive moves include multi-year supply contracts incorporating capacity reservation fees and pharmacopeial pre-certification investments that compress customer qualification cycles.
Among Germany-based integrated suppliers, Merck KGaA exemplifies the bundled bioprocessing archetype, while Albumedix represents the specialized recombinant protein tier with focused yeast expression capabilities. Baxter International Inc occupies a position bridging plasma heritage and recombinant diversification, leveraging hospital supply relationships established through fractionated product lines. These three anchors illustrate how competitive positioning stratifies across integrated workflow providers, pure-play recombinant specialists, and legacy fractionators transitioning production platforms.
| Leading Market Players |
|---|
| Merck KGaA |
| HiMedia Laboratories Pvt. Ltd. |
| Albumedix |
| InVitria |
| ScienCell Research Laboratories, Inc. |
| Lee Biosolutions, Inc. |
| Abcam Plc |
| Baxter International Inc |
| Octapharma AG |
| Others |
Pricing and Supply Chain Analysis
Yeast-expression recombinant albumin displacing plasma-derived alternatives in monoclonal antibody formulations simultaneously redistributes supply geography toward Chinese bulk manufacturers and compresses pricing power through cost-advantaged volume expander competition from established plasma fractionators.
Pricing Analysis
Cost-plus contracts with raw-material indexation dominate biopharmaceutical excipient procurement, linking albumin pricing to yeast extract and chromatography resin cost fluctuations. GMP certification grade and annual volume scale drive price differentiation between strategic partners and spot-market buyers. Pricing pressure stems from plasma-derived albumin's 30-40% cost advantage in clinical volume expansion applications. Hospital procurement consortia exhibit highest price sensitivity, while research laboratories absorb premiums for peptide-mapped documentation packages.
Supply Chain Analysis
Inbound logistics costs through Shanghai and Rotterdam ports constrain just-in-time delivery windows for European formulation houses sourcing Chinese bulk recombinant albumin. Supply concentrates in China, the United States, and Germany, with the former controlling yeast-expression bulk capacity. Raw material dependencies include yeast extract, chromatography resins, and sterile filtration membranes. Single-source vulnerability from concentrated Chinese bulk supply creates structural risk. Distribution runs through direct manufacturer-to-sponsor relationships with multi-year capacity reservation agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Rhu Albumin market constitutes a regulatory-entrenchment defensive moat, where FDA and EMA drug master file cross-referencing requirements lock in incumbent supplier relationships and extend new entrant qualification timelines beyond practical breakeven horizons.
For Market Incumbents: Compound GMP certification investments with pharmacopeial pre-certification programs that compress customer qualification cycles by 6-9 months. Expand dedicated production suite capacity in Heidelberg and Munich biomanufacturing clusters to capture localized CDMO procurement pull. Defend against Chinese bulk suppliers by embedding quality agreements with peptide mapping documentation requirements that EMA guidelines now mandate. For New Entrants and Emerging Players: Differentiate on auditable yeast expression lineages for serum-free media protocols in Indian CDMO greenfield facilities. Target Hyderabad and Bengaluru contract development organizations building biologics capacity without legacy plasma infrastructure. Penetrate through digital procurement channels for initial supplier qualification before transitioning to direct sales with capacity reservation structures. For Investors and Strategic Acquirers: The market sits at a supplier consolidation phase that favors integrated bioprocessing conglomerates with cell culture media bundling capabilities. Long-term viability hinges on captive demand from blockbuster monoclonal antibody pipelines requiring supply security across 5-10 year horizons. Target acquisition archetypes include specialized recombinant protein specialists with Pichia pastoris optimization expertise. Monitor EMA pharmacopeial monograph revisions on host-cell protein thresholds as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Certification Pre-Investment | Compresses customer qualification timelines ahead of EMA peptide mapping mandates. |
| Yeast Expression Platform Expansion | Captures serum-free media substitution demand from Massachusetts antibody manufacturers. |
| Direct Sales Agreement Structuring | Locks in capacity reservation fees from United States monoclonal antibody producers. |
| Lyophilized Format Development | Enables rural hospital distribution without cold-chain infrastructure requirements. |
| Cell Therapy Media Qualification | Opens premium excipient segment with limited incumbent competition in CAR-T expansion protocols. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with biopharmaceutical development executives, regulatory affairs leads, hospital procurement managers, and CDMO technical directors; and secondary validation through FDA drug master file databases, EMA submission records, pharmacopeial monograph revisions, and hospital procurement consortium contracts. Bottom-up volume estimates from individual manufacturer capacity disclosures were triangulated against top-down demand projections from monoclonal antibody pipeline analysis.
Across the analysis window, forecasts were constructed using a segmented analytical framework spanning product type, end user, distribution channel, and application dimensions, with additional modeling of GMP certification tier and regional regulatory cluster effects. CAGRs were derived from regression analysis of historical qualification timeline compression and substitution elasticity parameters. Industry-specific inputs included serum-free media adoption curves and EMA host-cell protein immunogenicity risk assessment implementation timelines.
Forecasts assume regulatory continuity in FDA and EMA recombinant therapeutic purity regimes; material policy shifts affecting endotoxin or host-cell protein thresholds would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Heparin API Market
Biopharmaceuticals
Immunocytokines Market
Biopharmaceuticals
Global Bovine Blood Plasma Derivatives Market
Biopharmaceuticals
Oligonucleotide API Market
Biopharmaceuticals
Chemotherapy Market
Biopharmaceuticals
Clindamycin Phosphate Market
Biopharmaceuticals
Global Blood Product Market
Biopharmaceuticals
Immunotoxins Market
Biopharmaceuticals
Primary Biliary Cholangitis (PBC) Therapeutics Market
Biopharmaceuticals
Tuberculosis Biomarkers Market
Biopharmaceuticals
Octreotide Market
Biopharmaceuticals
Drug Discovery Outsourcing Market
Biopharmaceuticals
Biobetters Market
Biopharmaceuticals
Brazil Generic Drug Market
Biopharmaceuticals
Biologics Contract Development Market
Biopharmaceuticals
Germany Insulin Drugs and Delivery Devices Market