
 Tumor-Sequencing Blood Testing Market | 2026-2036
Tumor-Sequencing Blood Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Tumor-Sequencing Blood Testing Market Analytics
Hospital procurement consolidation is expanding as large health systems centralize molecular diagnostic contracts across multiple sites. Thermo Fisher Scientific leverages its integrated instrument-reagent platform to anchor long-term supply agreements with these consolidating buyers. Guardant Health competes through specialized oncology-focused test menus, while Illumina sustains technology leadership in sequencing-by-synthesis instrumentation that underpins most laboratory workflows.
Tumor-sequencing blood testing isolates and analyzes circulating nucleic acids from plasma to detect somatic mutations without tissue biopsy, requiring specialized collection tubes, cfDNA extraction protocols, and detection limits below 0.1% variant allele frequency for reliable clinical use. Circulating tumor DNA applications command premium positioning due to their minimally invasive profile and repeatability for patient monitoring. Next-generation sequencing dominates instrument-installed bases, though targeted sequencing approaches capture margin pools in companion diagnostic settings where panel breadth must align with specific therapeutic labels.
FDA oversees premarket approval pathways for liquid biopsy devices under its in vitro diagnostics framework, while EMA's IVDR transition reshapes conformity requirements across European laboratories. China's NMPA has accelerated review timelines for innovative oncology diagnostics, altering competitive access patterns in that market. Stakeholders must monitor how regulator divergence in clinical evidence standards affects test portability and multi-region launch sequencing.
Market Dynamics
Hospital procurement consolidation is compressing vendor relationships into multi-site framework agreements, forcing molecular diagnostic suppliers to anchor integrated platform contracts rather than transactional reagent sales.
Growth Catalysts
- FDA liquid biopsy pathway expansion:Streamlined premarket review for companion diagnostics accelerates clinical adoption of circulating tumor DNA assays in oncology treatment selection.
- China's centralized cancer genomics infrastructure:Government-funded regional sequencing centers in Beijing, Shanghai, and Guangzhou are standardizing cfDNA workflows across tertiary hospital networks.
- Repeatable patient monitoring protocols:Minimally invasive blood draws enable serial mutation tracking during therapy, creating recurring revenue streams distinct from one-time tissue biopsy alternatives.
Market Restraints
- Specialized collection tube supply concentration:Cell-free DNA stabilization chemistry depends on a limited supplier base, creating input vulnerability for high-volume laboratories.
- Variant allele frequency detection thresholds:Clinical reliability demands sensitivity below 0.1%, requiring costly instrument calibration and quality control protocols that elevate operational overhead.
- EMA IVDR conformity transition:European laboratories face extended certification timelines and notified body capacity constraints that delay test launches in Germany, France, and Italy.
Strategic Opportunities
- Germany's statutory health insurance reimbursement:New diagnostic benefit assessment pathways for liquid biopsy create accessible payment channels for molecular tumor boards in university hospitals.
- Artificial intelligence-variant calling convergence:Machine learning algorithms trained on large cfDNA datasets reduce false-positive rates and enable smaller bioinformatics teams to scale test volumes.
- Direct-to-oncologist distribution models:Specialty pharmaceutical-style detailing bypasses traditional laboratory sales channels, accelerating adoption in community oncology practices.
Industry Challenges
- Bioinformatics pipeline standardization:Lack of harmonized variant interpretation guidelines across clinical laboratories complicates multi-site validation and inter-laboratory concordance studies.
- Pre-analytical workflow integration:Blood collection-to-plasma processing time windows require coordination between phlebotomy, logistics, and molecular pathology departments that legacy hospital information systems struggle to synchronize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tumor-Sequencing Blood Testing Market |
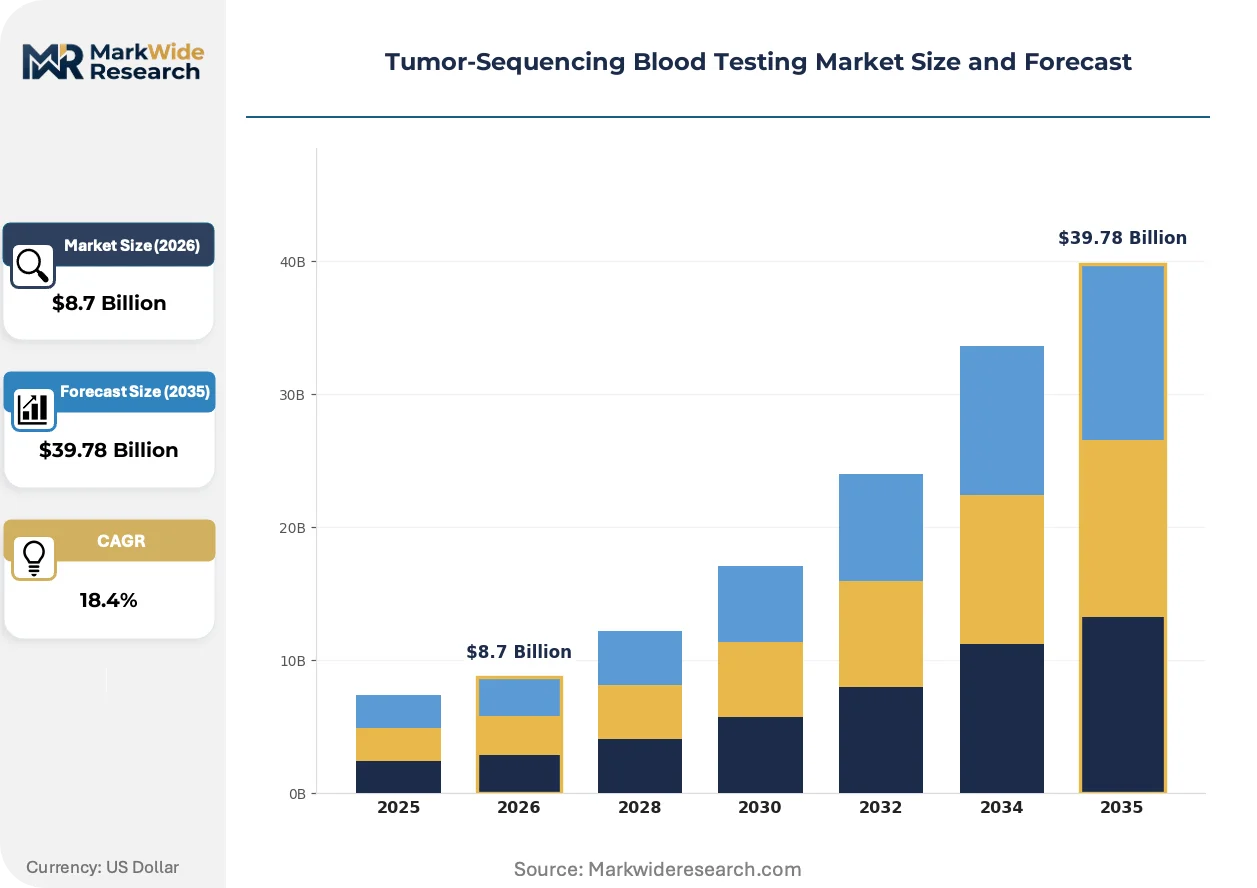
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Sequencing, RNA Sequencing, Circulating Tumor DNA, Next-Generation Sequencing Technology: Sequencing-by-Synthesis, Single-Molecule Real-Time, Targeted Sequencing, Massively Parallel Sequencing End User: Hospitals, Diagnostic Laboratories, Research Institutions, Clinics Application: Oncology Research, Companion Diagnostics, Strain Identification, Patient Monitoring |
| Companies Covered | Thermo Fisher Scientific, Illumina, Guardant Health, QIAGEN, F. Hoffmann-La Roche Ltd, Labcorp, Danaher Corporation, Abbott Laboratories, Foundation Medicine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tumor-Sequencing Blood Testing Market Evolving Landscape
Next-generation sequencing instrumentation is consolidating around modular platforms that separate sample preparation from detection chemistry, enabling laboratories to upgrade analytical throughput without full system replacement.
Targeted amplicon sequencing is consolidating its position in companion diagnostic applications where panel content must align precisely with FDA-approved therapeutic labels. Pharmaceutical sponsors specify these narrower gene sets during clinical trial design, forcing diagnostic partners to lock content configurations years before commercial launch. This dynamic compresses flexibility for laboratories seeking to expand indication claims post-approval.
China's NMPA has accelerated innovative oncology diagnostic review timelines, compressing market entry cycles for circulating tumor DNA tests submitted through its breakthrough device pathway. Domestic manufacturers in Shanghai and Suzhou are exploiting this regulatory velocity to secure reimbursement codes ahead of multinational competitors. The policy shift is concentrating competitive advantage in laboratories with established NMPA regulatory affairs capabilities.
Oncology departments are unbundling molecular testing decisions from centralized laboratory procurement, placing test selection authority directly with treating physicians rather than pathology committees. This shift displaces volume-based contract leverage with clinical utility evidence and turnaround time performance. The pattern is most visible in United States academic medical centers where molecular tumor boards now specify assay platforms case-by-case.
Tumor-Sequencing Blood Testing Market Segmentation
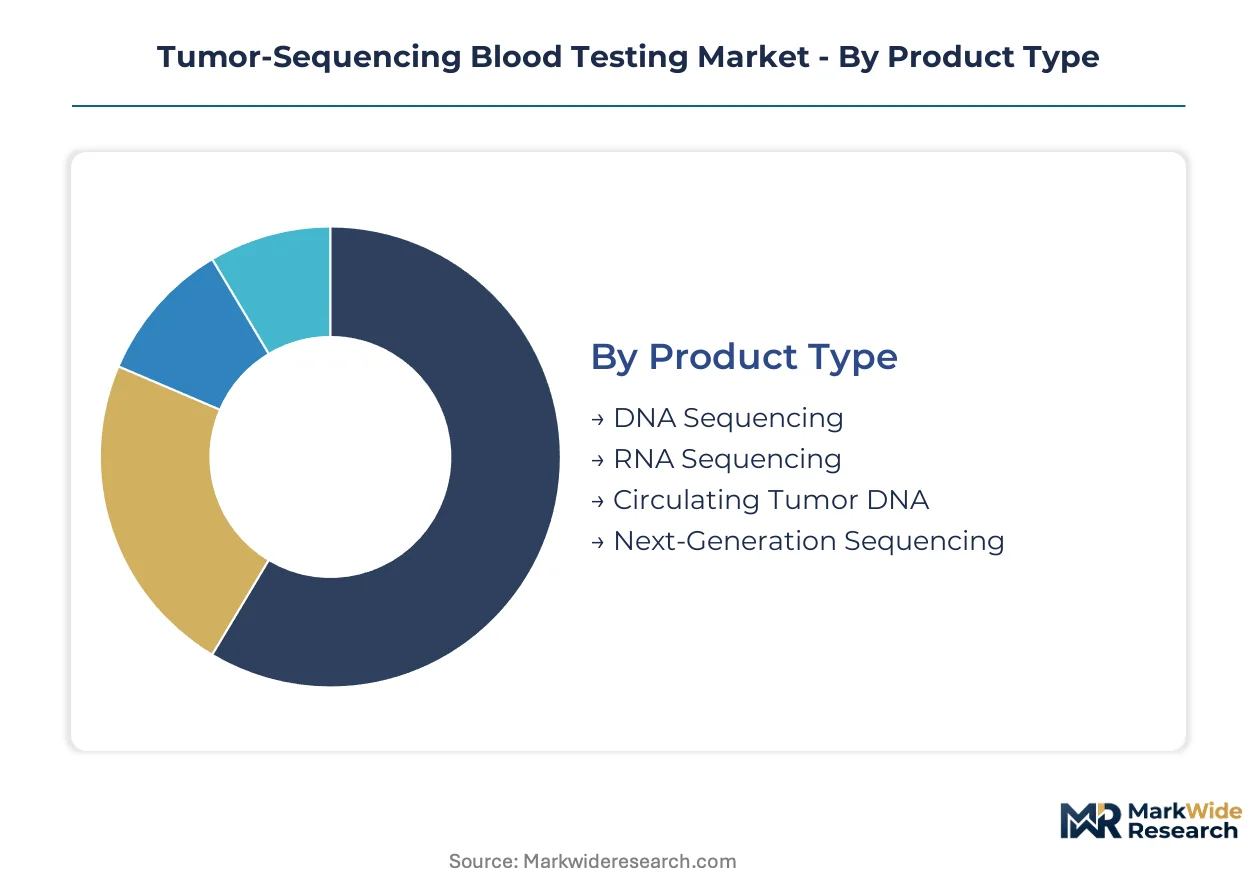
Segmentation in tumor-sequencing blood testing reveals how purchasing authority, technical specifications, and reimbursement pathways diverge across clinical settings. Laboratories prioritize detection sensitivity and workflow integration when selecting platforms, while research buyers emphasize throughput scalability and data analysis flexibility.
Product Type:
Procurement teams weigh analytical sensitivity against panel breadth when committing to multi-year reagent contracts.
- Circulating Tumor DNA:Isolates fragmented tumor-derived DNA from plasma to detect somatic mutations without invasive tissue sampling. Demand concentrates in United States academic medical centers where serial monitoring protocols require repeat blood draws during therapy cycles.
- Next-Generation Sequencing:Enables massively parallel analysis of millions of DNA fragments simultaneously, delivering comprehensive genomic profiling from limited input material. Germany's university hospitals are standardizing NGS workflows for molecular tumor boards, driven by new statutory health insurance reimbursement pathways for liquid biopsy.
- DNA Sequencing:Traditional Sanger and targeted approaches retain utility in confirmatory testing and low-complexity variant detection.
- RNA Sequencing:Profiles gene expression and fusion transcripts, finding niche adoption in research institutions studying tumor heterogeneity.
Volume sits with Next-Generation Sequencing; growth tilts toward Circulating Tumor DNA.
Technology:
Platform selection locks laboratories into specific reagent ecosystems and service dependencies for seven-to-ten year depreciation cycles.
- Sequencing-by-Synthesis:Employs reversible terminator chemistry to detect incorporated nucleotides through fluorescent imaging, dominating installed bases in high-throughput clinical laboratories. China's regional sequencing centers in Beijing and Shanghai have standardized this approach for cfDNA workflows across tertiary hospital networks.
- Targeted Sequencing:Focuses analysis on predefined gene panels aligned with FDA-approved therapeutic labels, capturing margin pools in companion diagnostic applications. Pharmaceutical sponsors specify these narrower gene sets during clinical trial design, compressing flexibility for post-approval indication expansion.
- Single-Molecule Real-Time:Detects nucleotide incorporation in real time using zero-mode waveguides, offering longer read lengths for structural variant analysis.
- Massively Parallel Sequencing:Describes the underlying architecture enabling simultaneous analysis of millions of DNA fragments, now table stakes for competitive platforms.
Sequencing-by-Synthesis commands current volume; Targeted Sequencing gains share fastest as companion diagnostic specifications tighten.
End User:
Buying authority is fragmenting as oncology departments bypass centralized laboratory procurement to specify platforms directly.
- Diagnostic Laboratories:High-throughput reference labs process thousands of samples monthly, requiring automated sample-to-report workflows and LIMS integration. Hospital procurement consolidation is compressing vendor relationships into multi-site framework agreements across United States health systems.
- Hospitals:Tertiary care centers with embedded molecular pathology departments balance turnaround time against send-out costs for complex cases. Molecular tumor boards in academic medical centers now specify assay platforms case-by-case, displacing volume-based contract leverage.
- Research Institutions:Prioritize data generation flexibility and publication-grade analytical pipelines over regulatory certification.
- Clinics:Community oncology practices seek simplified workflows with minimal bioinformatics infrastructure requirements.
Diagnostic Laboratories anchor current volume; Hospitals show the steepest expansion trajectory as decentralized testing authority spreads.
Application:
Reimbursement coding and clinical evidence requirements determine which applications can sustain profitable test menus.
- Companion Diagnostics:Links specific biomarker detection to FDA-approved therapeutic selections, requiring locked panel content and premarket regulatory submissions. EMA's IVDR transition is reshaping conformity requirements across European laboratories, extending certification timelines.
- Patient Monitoring:Enables serial mutation tracking during therapy through minimally invasive blood draws, creating recurring revenue streams distinct from one-time tissue biopsy alternatives. Repeatable protocols are concentrating demand in United States and China where longitudinal care models are reimbursed.
- Oncology Research:Exploratory profiling for biomarker discovery and clinical trial enrollment, less constrained by regulatory evidence standards.
- Strain Identification:Microbial and viral genotyping applications represent adjacent use cases with distinct technical specifications.
Companion Diagnostics holds established volume; Patient Monitoring climbs the fastest as longitudinal reimbursement models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for tumor-sequencing blood testing concentrates in the United States, China, and Germany, where centralized cancer genomics infrastructure and streamlined regulatory pathways accelerate clinical adoption of circulating tumor DNA workflows.
United States
FDA's expanded liquid biopsy pathway for companion diagnostics accelerates premarket review timelines for circulating tumor DNA assays. Academic medical centers in Boston and Houston are deploying serial monitoring protocols that require repeat blood draws during therapy cycles. Molecular tumor boards now specify assay platforms case-by-case, displacing traditional volume-based laboratory procurement contracts.
China
NMPA's breakthrough device pathway compresses market entry cycles for innovative oncology diagnostics submitted by domestic manufacturers. Government-funded regional sequencing centers in Beijing, Shanghai, and Guangzhou standardize cfDNA workflows across tertiary hospital networks. Laboratories in Suzhou exploit regulatory velocity to secure reimbursement codes ahead of multinational competitors.
Germany
New statutory health insurance reimbursement pathways for liquid biopsy create accessible payment channels for molecular tumor boards in university hospitals. EMA's IVDR transition extends certification timelines for European laboratories, though German facilities maintain operational continuity through early notified body engagement. The Rhine-Ruhr and Munich clusters anchor high-throughput diagnostic infrastructure.
Japan
PMDA review timelines for oncology companion diagnostics shape commercial launch sequencing for multinational test manufacturers. Tokyo and Osaka medical centers integrate circulating tumor DNA monitoring into longitudinal cancer care protocols. METI funding for genomic medicine infrastructure supports regional sequencing hub development.
United Kingdom
NHS England's genomic medicine service specifications influence test menu standardization across national laboratory networks. London and Cambridge academic hospitals pilot artificial intelligence-assisted variant calling for cfDNA analysis. The Medicines and Healthcare products Regulatory Agency aligns conformity assessment with emerging IVDR requirements.
Tumor-Sequencing Blood Testing Market Competitive Landscape
United States-based integrated platform providers anchor one tier; specialized oncology diagnostic companies and European diversified healthcare conglomerates hold differentiated positions. The market structure reflects consolidation around instrument-reagent ecosystems that lock laboratories into multi-year supply dependencies. Three archetypes dominate: full-stack platform vendors, cancer-focused test developers, and sequencing technology specialists. Competitive dynamics center on multi-site framework agreements with consolidating health systems and regulatory approval velocity across FDA, EMA, and NMPA jurisdictions.
Among United States-based platform providers, Thermo Fisher Scientific exemplifies the integrated instrument-reagent archetype through its anchor position in laboratory supply agreements. Illumina represents sequencing technology leadership that underpins competitor workflows. Guardant Health occupies the specialized oncology diagnostic tier with cancer-focused test menus. These three companies illustrate how competitive positioning fragments across technology layer, clinical application depth, and customer relationship model.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Illumina |
| Guardant Health |
| QIAGEN |
| F. Hoffmann-La Roche Ltd |
| Labcorp |
| Danaher Corporation |
| Abbott Laboratories |
| Foundation Medicine |
| Others |
Value Network & Pricing Analysis
FDA's IVDR-equivalent quality system requirements for liquid biopsy companion diagnostics gate qualified supply access for European and United States laboratories seeking premium-tier reimbursement positioning. These regulatory mandates concentrate purchasing power among manufacturers with validated cfDNA stabilization chemistry and instrument-reagent platform integration, compressing margin pools for undifferentiated reagent vendors.
Pricing Analysis
Volume sits with standardized sequencing-by-synthesis reagent contracts at compressed margins; margin pools concentrate in companion diagnostic test menus with locked FDA-approved panel content. Price differentiation hinges on detection sensitivity thresholds below 0.1% variant allele frequency and NMPA/FDA/EMA regulatory certification tier. Pricing pressure stems from hospital procurement consolidation forcing multi-site framework agreements across United States health systems. Community oncology practices show highest price sensitivity due to minimal bioinformatics infrastructure; academic medical centers prioritize turnaround time and clinical utility evidence over unit cost.
Supply Chain Analysis
Cell-free DNA stabilization chemistry rests on a concentrated supplier base in the United States, Germany, and Japan, with specialized collection tube manufacturing anchored in Becton Dickinson and Streck production networks. Key inputs span proprietary blood collection tube additives, cfDNA extraction magnetic bead chemistries, and sequencing flowcell consumables. Single-source vulnerability concentrates around cell-free DNA stabilization patents held by limited manufacturers. Distribution runs through laboratory supply distributors and direct-to-hospital contracts negotiated by health system GPOs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where hospital procurement centralization and regulatory certification barriers force subscale reagent vendors toward exit or acquisition. EMA's IVDR transition and FDA's liquid biopsy pathway expansion together compress competitive room for undifferentiated entrants lacking multi-jurisdictional regulatory affairs capabilities.
For Market Incumbents: Lock in long-term instrument-reagent platform contracts with consolidating United States health systems before procurement decisions migrate to molecular tumor boards. Anchor supply agreements through integrated cfDNA workflow validation and LIMS integration services. Defensive priority centers on backward integration into cell-free DNA stabilization chemistry to neutralize single-source input vulnerability from specialized collection tube suppliers.
For New Entrants and Emerging Players: Direct-to-oncologist digital detailing routes bypass entrenched laboratory sales channels and accelerate adoption in community oncology practices underserved by high-touch field forces. White-space targets concentrate in China's regional sequencing centers exploiting NMPA breakthrough device velocity, and in Germany's statutory health insurance reimbursement pathways for liquid biopsy. Go-to-market angle emphasizes artificial intelligence-variant calling convergence to reduce false-positive rates without scaling bioinformatics headcount.
For Investors and Strategic Acquirers: FDA 510(k) clearance for circulating tumor DNA companion diagnostics is the leading indicator that a target has secured viable reimbursement positioning and hospital procurement access. Long-term viability over a multi-year window favors vertically integrated platform providers with captive instrument installed bases over pure-play test developers exposed to reagent commoditization. Acquisition target archetype: specialized oncology diagnostic companies with NMPA regulatory affairs capabilities and established cfDNA test menus. Signal to monitor: molecular tumor board case-by-case platform specification displacing centralized laboratory procurement contracts.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Liquid Biopsy Pathway Submission | Premarket approval unlocks companion diagnostic reimbursement and hospital procurement access. |
| Hospital System Partnership | Multi-site framework agreements with consolidating United States health systems anchor reagent volume. |
| Software Companion Development | Artificial intelligence-variant calling reduces false-positive rates and bioinformatics staffing requirements. |
| CE Marking Pathway | EMA IVDR conformity enables European laboratory access despite extended certification timelines. |
| Reimbursement Strategy | Germany's statutory health insurance diagnostic benefit assessment creates accessible payment channels. |
Research Methodology
FDA 510(k) and PMA filings, EMA IVDR technical documentation, and NMPA breakthrough device submissions formed the secondary backbone for regulatory pathway analysis. Primary interviews with molecular pathology laboratory directors, hospital procurement managers, GPO contracts specialists, and companion diagnostic regulatory affairs leads validated instrument-reagent platform adoption patterns and pricing dynamics. Bottom-up triangulation across cfDNA test volume estimates and top-down reconciliation against health system expenditure data anchored market sizing.
Historical trendline analysis of circulating tumor DNA assay adoption across academic medical centers and community oncology practices informed projection frameworks. Segmentation modeling spanned product type, technology platform, end-user category, and application across the analysis window. CAGRs derived from weighted average of instrument installed base expansion, reagent consumption per test, and reimbursement code activation timelines. Industry-specific inputs incorporated phlebotomy-to-report turnaround time requirements and molecular tumor board case volume growth.
The model holds under stable FDA and EMA regulatory review timelines; deviation in NMPA policy velocity or IVDR notified body capacity constraints would shift competitive access patterns. Forecasts reflect assumptions regarding hospital procurement consolidation trajectory and companion diagnostic panel content lock-in by pharmaceutical sponsors. Regulatory divergence in clinical evidence standards, pre-analytical workflow standardization, and artificial intelligence-variant calling reimbursement warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
NGS Automation Market
Genomics
Nutrigenomics Testing Market
Genomics
Pre-Pregnancy Genetic Testing Market
Genomics
DNA Mass Ladder Market
Genomics
Genetic Material Market
Genomics
Next Generation Sequencing Market
Genomics
Global Metagenomic Sequencing Market
Genomics
Omics Lab Services Market
Genomics
Mitochondrial DNA Market
Genomics
Global Metagenomics Market
Genomics
Dna Polymerase Market
Genomics
Global Gene Amplification Technologies Market
Genomics
Pharmacogenomics Technology Market
Genomics
Europe Gene Synthesis (Research Use) Market
Genomics
Global Gene Expression Market
Genomics
SNP Genotyping Market