
 Anti-Nuclear Antibody (ANA) Testing Market | 2026-2036
Anti-Nuclear Antibody (ANA) Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Nuclear Antibody (ANA) Testing Market Analysis
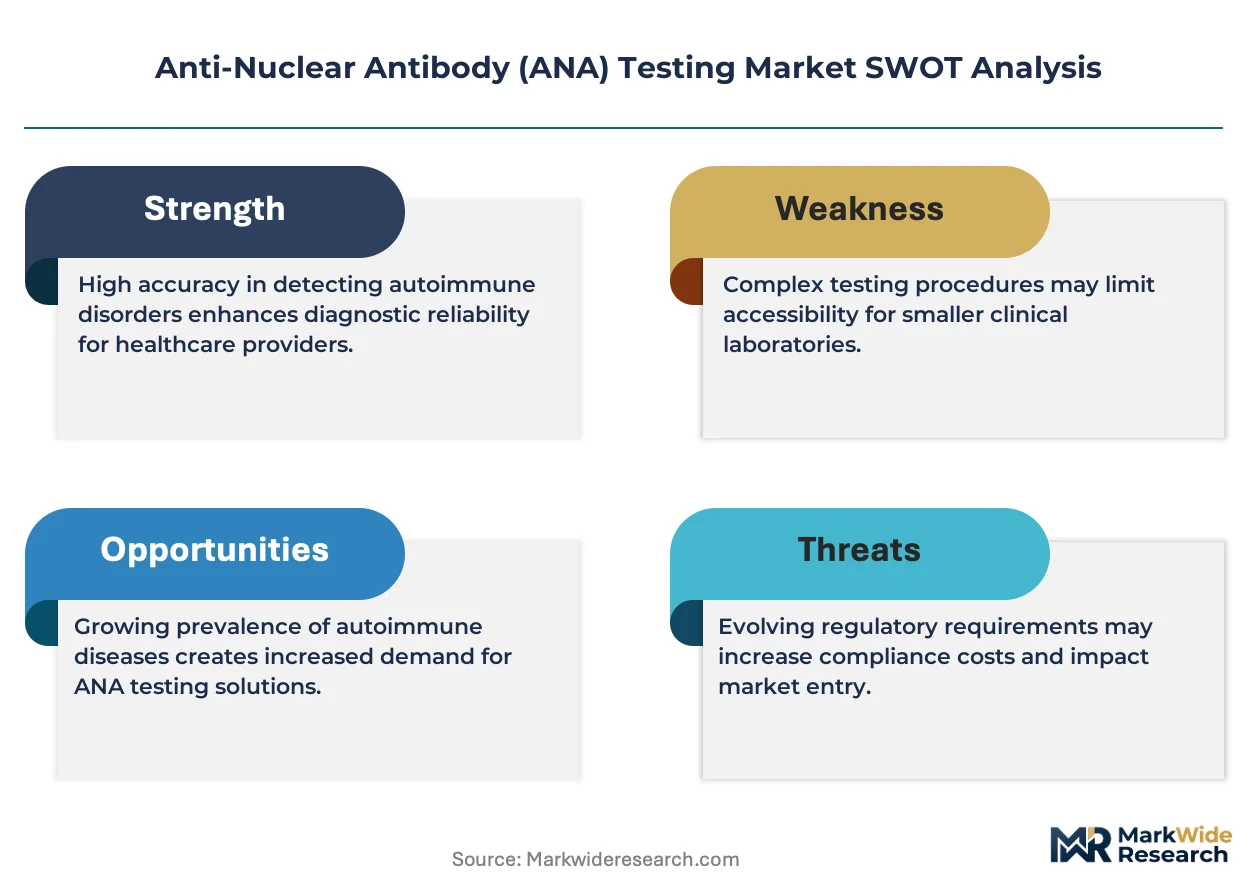
Reagent rental programs and per-test subscription contracts is recalibrating how laboratories acquire ANA testing platforms. Thermo Fisher Scientific leverages its global distribution infrastructure to sustain instrument placements in mid-sized hospital labs. Bio-Rad Laboratories differentiates through specialized autoimmune reagent portfolios that anchor long-term consumable revenue streams.
Anti-Nuclear Antibody testing comprises serological assays that detect autoantibodies targeting intracellular nuclear antigens, with indirect immunofluorescence on HEp-2 cell substrates remaining the reference method for pattern interpretation. These tests serve as primary screening tools for systemic autoimmune rheumatic diseases including systemic lupus erythematosus and scleroderma. Indirect immunofluorescence dominates routine screening due to its established clinical utility and pattern specificity, while ELISA formats compete on throughput and standardization for high-volume laboratories. End users concentrate in diagnostic laboratories where automated platforms reduce technologist time per sample.
The US FDA governs assay classification and premarket pathways for ANA testing systems, while the Clinical Laboratory Improvement Amendments set proficiency standards that shape laboratory accreditation and test complexity tiers. The EU In Vitro Diagnostic Regulation requires notified body oversight for higher-risk autoimmune assays, altering market access timelines for manufacturers. Stakeholders must monitor evolving harmonization efforts between pattern interpretation guidelines and automated scoring algorithms.
Market Dynamics
Automated pattern recognition algorithms are compressing the clinical validation timeline for ANA testing, forcing laboratories to restructure technologist workflows around machine-learning-assisted interpretation rather than manual microscopy review.
Growth Catalysts
- CLIA Proficiency Standards:The Clinical Laboratory Improvement Amendments mandate rigorous external quality assessment for immunofluorescence assays, compelling laboratories to upgrade to standardized automated platforms that reduce inter-operator variability.
- Integrated Health Network Consolidation:Hospital system mergers in the United States are centralizing reference laboratory volumes, creating procurement leverage that favors high-throughput screening instruments with multi-year consumable contracts.
- HEp-2 Substrate Innovation:Engineered cell line modifications with enhanced antigen presentation are improving pattern clarity for dense fine speckled and centromere classifications, reducing ambiguous referrals to tertiary centers.
Market Restraints
- Fluorophore Cost Volatility:Specialized conjugated secondary antibodies derived from goat and rabbit serum face input price instability tied to livestock supply chain disruptions in Australia and New Zealand.
- EU MDR Notification Bottlenecks:The In Vitro Diagnostic Regulation's expanded technical documentation requirements for Class C autoimmune assays are extending market access timelines by 12-18 months for novel platform launches.
- ELISA Standardization Limitations:Enzyme-linked immunosorbent assay formats lack the pattern specificity of indirect immunofluorescence, creating clinical pushback in academic medical centers that prioritize diagnostic granularity over throughput.
Strategic Opportunities
- Point-of-Care Rheumatology:Miniaturized immunofluorescence readers with smartphone-based image capture could penetrate community rheumatology practices in Germany where patient-to-rheumatologist ratios exceed national averages.
- AI-Assisted Triage:Convolutional neural networks trained on annotated pattern libraries are converging with cloud-based laboratory information systems to enable remote interpretation by subspecialist pathologists.
- India PLI Scheme Alignment:The Production Linked Incentive scheme for medical devices offers tariff advantages to manufacturers establishing domestic reagent production for autoimmune diagnostics.
Industry Challenges
- Pattern Interpretation Expertise Gap:Experienced medical technologists capable of distinguishing homogeneous from peripheral patterns are retiring faster than training programs can replace them, particularly in community hospital laboratories.
- LIS Integration Complexity:Automated ANA platforms require bidirectional interfaces with legacy laboratory information systems that lack HL7 FHIR compatibility, demanding expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Nuclear Antibody (ANA) Testing Market |
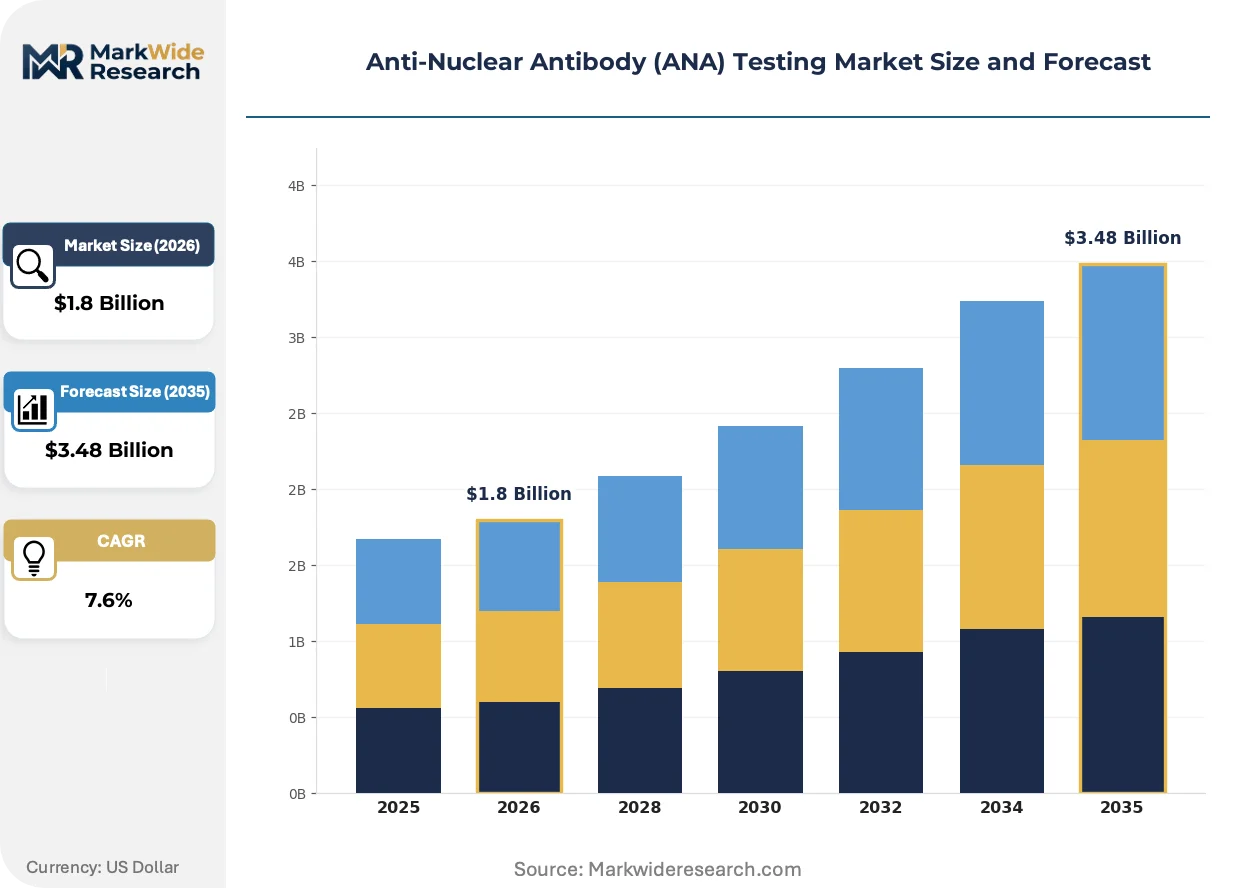
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: ENAs, Indirect Immunofluorescence, ELISA, Western Blot End User: Hospitals, Diagnostic Laboratories, Research Institutions, Clinics Service Type: Routine Testing, Specialty Testing, Genetic Testing, Point-of-Care Testing Technology: Microarray, Flow Cytometry, Luminex, PCR |
| Companies Covered | F. Hoffmann-La Roche Ltd., PerkinElmer Inc., Abbott Laboratories, Inova Diagnostics Inc., Zeus Scientific Inc., Thermo Fisher Scientific Inc., Grifols SA, Antibodies Incorporated, Bio-Rad Laboratories, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Nuclear Antibody (ANA) Testing Market Emerging Trajectories
Digital pathology infrastructure is rewriting the economics of autoimmune serology, compressing the cost per reportable result while fragmenting where interpretation expertise physically resides.
Multiplex bead-based immunoassays are consolidating screening and confirmatory testing into single-platform workflows. High-volume reference laboratories in the United States are adopting these systems to eliminate the reflex cascade from positive screens to antigen-specific ELISAs. The technology is consolidating vendor relationships as laboratories reduce from multiple assay suppliers to single-source automated lines.
The EU In Vitro Diagnostic Regulation's performance evaluation requirements are forcing manufacturers to generate clinical evidence from European patient cohorts rather than extrapolating from US studies. This regulatory friction is advantaging established players with existing notified body relationships. Smaller reagent specialists are responding by pursuing strategic partnerships with contract research organizations to share clinical trial costs.
Laboratory procurement teams are unbundling instrument placement from reagent supply agreements, negotiating separate capital leases for automated platforms while soliciting competitive bids for consumable contracts. This purchasing behavior shift is disrupting the traditional reagent rental model that locked laboratories into sole-source relationships. The trend is most visible in US health systems with centralized supply chain governance that spans multiple hospital laboratories.
Anti-Nuclear Antibody (ANA) Testing Market Segmentation
Segmentation in the ANA testing market reveals how laboratories prioritize throughput against diagnostic granularity when allocating capital budgets. Procurement patterns diverge sharply between academic medical centers demanding pattern specificity and high-volume reference laboratories optimizing cost per reportable result.
Test Type:
Platform upgrade cycles are compressing as laboratories replace legacy manual microscopes with automated imaging systems that reduce technologist time per sample.
- Indirect Immunofluorescence:The reference method employs FITC-conjugated secondary antibodies on HEp-2 cell substrates to generate interpretable fluorescence patterns. Demand concentrates in US academic medical centers where rheumatology departments require centromere, nucleolar, and speckled pattern differentiation for scleroderma and lupus subtyping; CLIA proficiency mandates are accelerating automated platform adoption.
- ELISA:Solid-phase enzyme immunoassays quantitate antibody titers against recombinant nuclear antigens with higher throughput than immunofluorescence. Commercial laboratories in Germany and France favor ELISA for initial screening cascades; standardization advantages reduce inter-laboratory variability in multi-site health networks.
- ENAs:Extractable nuclear antigen panels deliver antigen-specific confirmation following positive screens.
- Western Blot:Line immunoassays resolve antibody specificities against purified native antigens.
Volume placements concentrate in Indirect Immunofluorescence; the faster expansion belongs to ELISA.
End User:
Customer procurement authority is shifting from individual hospital laboratories to centralized supply chain governance spanning integrated delivery networks.
- Diagnostic Laboratories:Reference laboratories process thousands of autoimmune serology specimens daily through automated lines. Quest Diagnostics and LabCorp in the United States negotiate multi-year consumable contracts that lock in reagent pricing; FDA-cleared platforms with bidirectional LIS integration command premium placement terms.
- Hospitals:Mid-sized hospital labs balance STAT turnaround requirements against capital constraints. Community hospitals in India's tier-2 cities are adopting compact immunofluorescence systems under CDSCO import regulations; reagent rental programs reduce upfront instrument costs.
- Research Institutions:Academic centers validate novel autoantibody biomarkers for preclinical studies.
- Clinics:Rheumatology practices seek rapid turnaround for patient management decisions.
Revenue concentration sits with Diagnostic Laboratories; margin expansion is steepest in Clinics.
Service Type:
Service line economics are fragmenting as laboratories unbundle screening from confirmatory testing to optimize reimbursement capture.
- Routine Testing:High-volume screening for ANA positivity follows standardized protocols with automated result reporting. National reference laboratories in Japan under PMDA oversight process routine panels for regional hospital networks; throughput optimization drives platform consolidation to single-vendor relationships.
- Specialty Testing:Complex cases require manual pattern interpretation by experienced technologists. Tertiary centers in the United Kingdom handle dense fine speckled and proliferating cell nuclear antigen patterns for lupus overlap syndromes; NHS procurement frameworks prioritize CE-marked platforms with documented clinical utility.
- Genetic Testing:Pharmacogenomic associations guide biologic therapy selection in refractory cases.
- Point-of-Care Testing:Miniaturized systems enable rheumatology clinic-based screening.
Patient volumes flow heaviest through Routine Testing; reimbursement rates favor Specialty Testing.
Technology:
Technology substitution is accelerating as bead-based multiplexing displaces sequential ELISA workflows in high-complexity laboratories.
- Luminex:Multiplex bead immunoassays simultaneously quantitate multiple autoantibody specificities from single sample aliquots. US commercial reference laboratories are consolidating screening and confirmation onto Luminex platforms; reduced technologist hands-on time compresses cost per reportable result below sequential ELISA cascades.
- Flow Cytometry:Cell-based assays detect antibodies against membrane-expressed nuclear antigens. Research hospitals in Switzerland employ flow cytometry for rare autoantibody discovery under Swissmedic clinical trial frameworks; instrument multiplexing justifies capital investment across immunology and hematology service lines.
- Microarray:Protein arrays enable high-density antigen screening for novel biomarker identification.
- PCR:Molecular confirmation supports select autoimmune diagnostics with genetic associations.
Installed base dominance rests with Luminex; the steepest growth trajectory belongs to Microarray.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reagent manufacturing concentrates in Germany and Switzerland, while diagnostic consumption tilts toward the United States and Japan where integrated health networks process the highest screening volumes. Regulatory divergence between FDA pathways and EU MDR timelines is fragmenting product launch synchronization across these production-consumption corridors.
United States
Hospital system mergers in Texas and Florida are consolidating reference laboratory volumes under centralized supply chain governance. FDA's updated in vitro diagnostic guidance is reshaping assay validation requirements for automated platforms. The Boston-Cambridge corridor anchors autoimmune diagnostics R&D, with several manufacturers maintaining regulatory affairs offices near the agency.
Germany
Community rheumatology practices in Bavaria and Baden-Württemberg face patient-to-specialist ratios exceeding national averages, creating demand for streamlined screening workflows. The EU In Vitro Diagnostic Regulation requires notified body oversight for higher-risk autoimmune assays, extending market access timelines. The Frankfurt-Rhine-Main region hosts several reagent specialists serving central European laboratory networks.
Japan
National reference laboratories under PMDA oversight process routine autoimmune panels for regional hospital networks in the Kanto and Kansai regions. METI standards for medical device quality management shape domestic manufacturing requirements. Osaka-based diagnostic companies supply automated platforms to Southeast Asian markets through established distribution partnerships.
India
Tier-2 cities in Maharashtra and Karnataka are adopting compact immunofluorescence systems under CDSCO import regulations. The Production Linked Incentive scheme for medical devices offers tariff advantages to manufacturers establishing domestic reagent production. Hyderabad's medical device cluster is attracting contract manufacturing for autoimmune diagnostics targeting Middle Eastern markets.
Switzerland
Research hospitals in Zurich and Geneva employ flow cytometry for rare autoantibody discovery under Swissmedic clinical trial frameworks. Precision diagnostics specialists maintain headquarters near Basel's pharmaceutical corridor, leveraging proximity to contract research organizations. The country's bilateral agreements with the EU facilitate CE-marked product access despite non-member status.
Anti-Nuclear Antibody (ANA) Testing Market Vendor Landscape
Capital-heavy instrument manufacturers compete with asset-light reagent specialists across the ANA testing value chain. The market structure tilts toward consolidation at the platform level while fragmenting across specialized consumable suppliers. Three archetypes dominate: diversified life science conglomerates with global distribution infrastructure, mid-sized autoimmune-focused reagent houses with deep pattern interpretation expertise, and emerging platform developers betting on AI-assisted scoring algorithms. Competitive moves center on unbundling instrument placement from consumable contracts, and pursuing strategic partnerships to share EU MDR clinical trial costs.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc. and F. Hoffmann-La Roche Ltd. exemplify scale-driven positioning through global logistics networks and multi-year hospital system contracts. Bio-Rad Laboratories, Inc. occupies a specialist position, representing the autoimmune-focused reagent house archetype with concentrated expertise in HEp-2 substrate engineering and pattern-specific assay development.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| PerkinElmer Inc. |
| Abbott Laboratories |
| Inova Diagnostics Inc. |
| Zeus Scientific Inc. |
| Thermo Fisher Scientific Inc. |
| Grifols SA |
| Antibodies Incorporated |
| Bio-Rad Laboratories, Inc. |
| Others |
Supply Flow & Price Mechanics
Fluorophore conjugation chemistry costs cascade through ANA testing supply chains, with FITC-labeled secondary antibodies manufactured in Australia and New Zealand feeding into three-tier pricing structures across premium, standard, and economy instrument tiers in US hospital laboratories.
Pricing Analysis
Margin tightening in economy-tier ELISA platforms reflects procurement consolidation by integrated health networks demanding multi-year consumable discounts. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared automated immunofluorescence systems from CE-marked workhorse platforms and unvalidated research-use-only reagents. Academic medical centers show lowest price sensitivity for pattern-specific assays, while commercial reference laboratories drive hardest bargains on per-test subscription contracts.
Supply Chain Analysis
Single-source vulnerability sits with Australian and New Zealand livestock serum suppliers, whose goat and rabbit herds provide polyclonal antibody feedstock for conjugated secondary reagents. Manufacturing concentration in Germany, Switzerland, and the United States draws from HEp-2 cell substrate lines, recombinant antigen production, and precision optics components. Tariff exposure through CDSCO import pathways in India threatens margin structures for compact immunofluorescence systems. Distribution runs through diagnostic reagent distributors with cold-chain logistics capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ANA testing market is consolidating around platform manufacturers with EU MDR notified body relationships, as extended clinical trial timelines force smaller reagent houses into partnership or exit.
For Market Incumbents: Cement platform stickiness through bidirectional LIS integration investments that raise switching costs for hospital laboratories. Deepen consumable revenue streams by engineering HEp-2 substrate modifications with proprietary antigen presentation profiles. Acquire pattern interpretation expertise through targeted hiring of retiring medical technologists before competitor poaching accelerates. For New Entrants and Emerging Players: Capture white-space in India's tier-2 city hospital laboratories where CDSCO import regulations favor compact system footprints and reagent rental programs reduce capital barriers. Target community rheumatology practices in Germany's Bavaria and Baden-Württemberg regions with miniaturized smartphone-connected immunofluorescence readers. Pursue PLI scheme alignment for domestic reagent manufacturing to unlock tariff advantages against imported competitors. For Investors and Strategic Acquirers: FDA submission timelines stretching beyond EU MDR notification bottlenecks are the leading indicator that regulatory affairs capabilities will determine survival. Position for 5-10 year viability by acquiring autoimmune-focused reagent houses with established notified body relationships and annotated pattern libraries for AI training. Watch for consolidation signals when mid-sized laboratories begin unbundling instrument placements from consumable contracts.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Trial Partnership | Shared evidence generation costs accelerate Class C autoimmune assay market access timelines. |
| AI Pattern Recognition Development | Convolutional neural networks trained on annotated libraries compress technologist interpretation workflows. |
| Reagent Rental Program Expansion | Per-test subscription contracts reduce upfront capital barriers in India's tier-2 hospital laboratories. |
| HEp-2 Substrate Engineering | Enhanced antigen presentation improves pattern clarity for dense fine speckled classifications. |
| Hospital System Partnership | Multi-year consumable contracts with Quest Diagnostics and LabCorp lock in reference laboratory volumes. |
Methodological Framework
Independent corroboration across hospital laboratory directors, rheumatology department chiefs, diagnostic reagent procurement managers, and regulatory affairs specialists at IVD manufacturers underwrites the qualitative findings. Primary interviews with biomedical engineers and GPO contracts managers were validated against FDA 510(k) filings, EU MDR technical documentation, CDSCO import registration databases, and hospital procurement contract disclosures. Bottom-up instrument placement estimates and top-down reagent consumption models were cross-referenced for convergence.
Comparable historical periods anchored the projection horizon across the analysis window, with segmentation modeling across test type, end user, service type, and technology dimensions. CAGRs were derived from instrument replacement cycle analysis, reagent consumption per placement assumptions, and pricing trajectory assessments. Forecast inputs incorporated CLIA proficiency mandate compliance rates, EU MDR notification backlog resolution patterns, and integrated health network consolidation velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to fluorophore cost volatility, pattern interpretation expertise attrition, and algorithmic scoring regulatory acceptance. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Leukocyte Count Testing Market
Testing Services
Cannabis Testing Services Market
Testing Services
Minimal Residual Disease Testing Market
Testing Services
South America Endotoxin and Pyrogen Testing Market
Testing Services
Global C-Reactive Protein Testing Market
Testing Services
Prothrombin Time Testing Market
Testing Services
Point of Care Testing Market
Testing Services
Paediatric and Neonatal Testing Kits Market
Testing Services
Anticoagulant Therapeutic Drug Monitoring Assay Kits Market
Testing Services
Human Papilloma Virus Testing Market
Testing Services
Sickle Cell Anemia Testing and Screening Market
Testing Services
Home Menopause Testing Market
Testing Services
Global IVD Regulatory Affairs Outsourcing Market
Testing Services
Instrument Calibration Services Market
Testing Services
Gamma Glutamyl Transferase Testing Market
Testing Services
Metabolic Biomarker Testing Market