
 Paediatric and Neonatal Testing Kits Market | 2026-2036
Paediatric and Neonatal Testing Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Paediatric and Neonatal Testing Kits Market Analytics
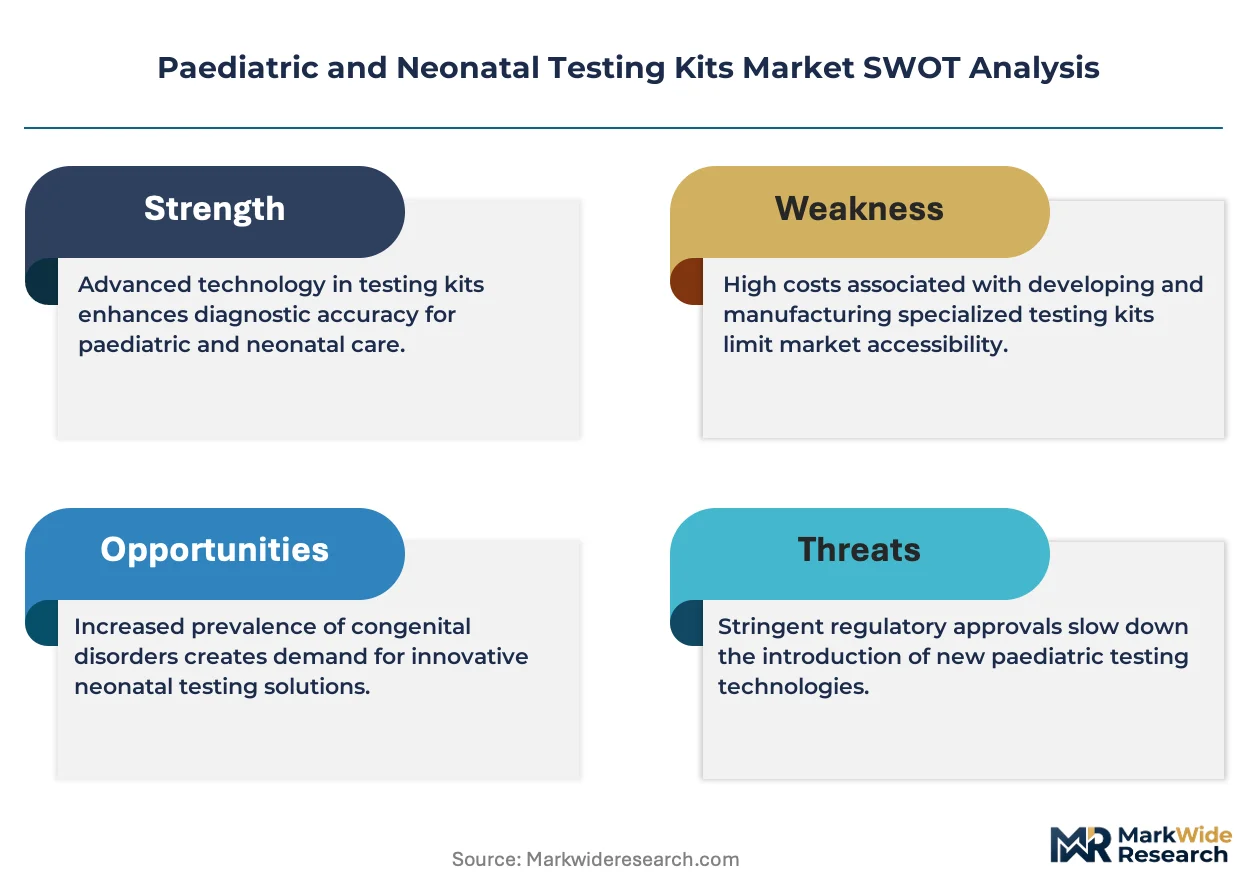
Software-defined assay calibration is decoupling instrument sales from recurring revenue streams in paediatric and neonatal diagnostics. Abbott Laboratories leverages its installed base of point-of-care devices to sustain consumable pull-through across hospital networks. Thermo Fisher Scientific anchors its position through R&D intensity in fluorescent detection platforms for newborn screening panels.
Paediatric and neonatal testing kits comprise disposable diagnostic consumables—blood glucose monitors, bilirubin test strips, electrolyte test devices, and hemoglobin kits—engineered for micro-volume sample analysis, typically requiring capillary blood draws under 500 microliters to accommodate low-birth-weight infants. These kits serve the clinical imperative of rapid metabolic and hematologic assessment in critical care and nursery settings where turnaround time directly informs therapeutic intervention. Immunoassay-based newborn screening commands the deepest margin pools due to reagent stickiness and regulatory complexity, while point-of-care electrolyte test devices represent the fastest-expanding application as decentralization of neonatal monitoring accelerates beyond tertiary centers.
FDA premarket review and CLIA complexity categorization shape product development timelines and market access pathways for US manufacturers, while the EU MDR and IVDR frameworks impose parallel conformity demands on European market entrants. India's CDSCO and the national newborn screening program create procurement corridors that favor kit suppliers meeting BIS quality benchmarks alongside WHO prequalification standards. Stakeholders must weigh regulatory jurisdiction stacking against the volume upside of emerging national screening mandates.
Market Dynamics
Software-defined assay calibration is severing the traditional bond between instrument hardware and recurring consumable revenue, forcing kit manufacturers to defend margin pools through reagent stickiness and regulatory complexity rather than captive device ecosystems.
Growth Catalysts
- India's national newborn screening program:Government-backed procurement corridors under CDSCO oversight widen kit volumes for domestic and imported suppliers meeting BIS quality benchmarks.
- Neonatal intensive care unit expansion:Tertiary hospitals in Brazil, South Africa, and Vietnam are broadening test panel adoption beyond basic metabolic screening.
- Micro-volume capillary sampling:Advances in sub-500 microliter blood draw technologies enable testing of low-birth-weight infants previously excluded from rapid diagnostic protocols.
Market Restraints
- Specialized polymer supply concentration:Reagent-grade membrane substrates for immunoassay strips concentrate among Japanese and German chemical suppliers, exposing kit makers to input volatility.
- FDA premarket review timelines:Extended 510(k) and De Novo pathways for novel biomarker panels delay US market entry by 18-36 months versus historical averages.
- Point-of-care electrolyte device commoditization:Ion-selective electrode modules face pricing pressure from Asian contract manufacturers, compressing hardware margins.
Strategic Opportunities
- Sub-Saharan Africa screening gaps:WHO prequalification pathways create first-mover advantage for bilirubin and glucose kit suppliers in Nigeria, Kenya, and Ghana.
- EU MDR companion diagnostic alignment:In vitro diagnostic regulation convergence with pharmaceutical therapy selection protocols opens reimbursement corridors for multiplex newborn panels.
- Telemedicine-integrated home sampling:Remote paediatric monitoring platforms in Australia and Canada are creating demand for consumer-grade hemoglobin and electrolyte test kits with digital readout integration.
Industry Challenges
- Multiplex assay validation complexity:Simultaneous detection of 40+ metabolic markers requires harmonized reference ranges across ethnic populations, straining clinical trial design.
- CLIA laboratory certification bottlenecks:US hospital systems face 12-18 month waits for high-complexity testing permits, delaying point-of-care expansion plans.
- Legacy LIS integration friction:Proprietary data formats from incumbent device manufacturers resist seamless connectivity with cloud-based neonatal health record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paediatric and Neonatal Testing Kits Market |
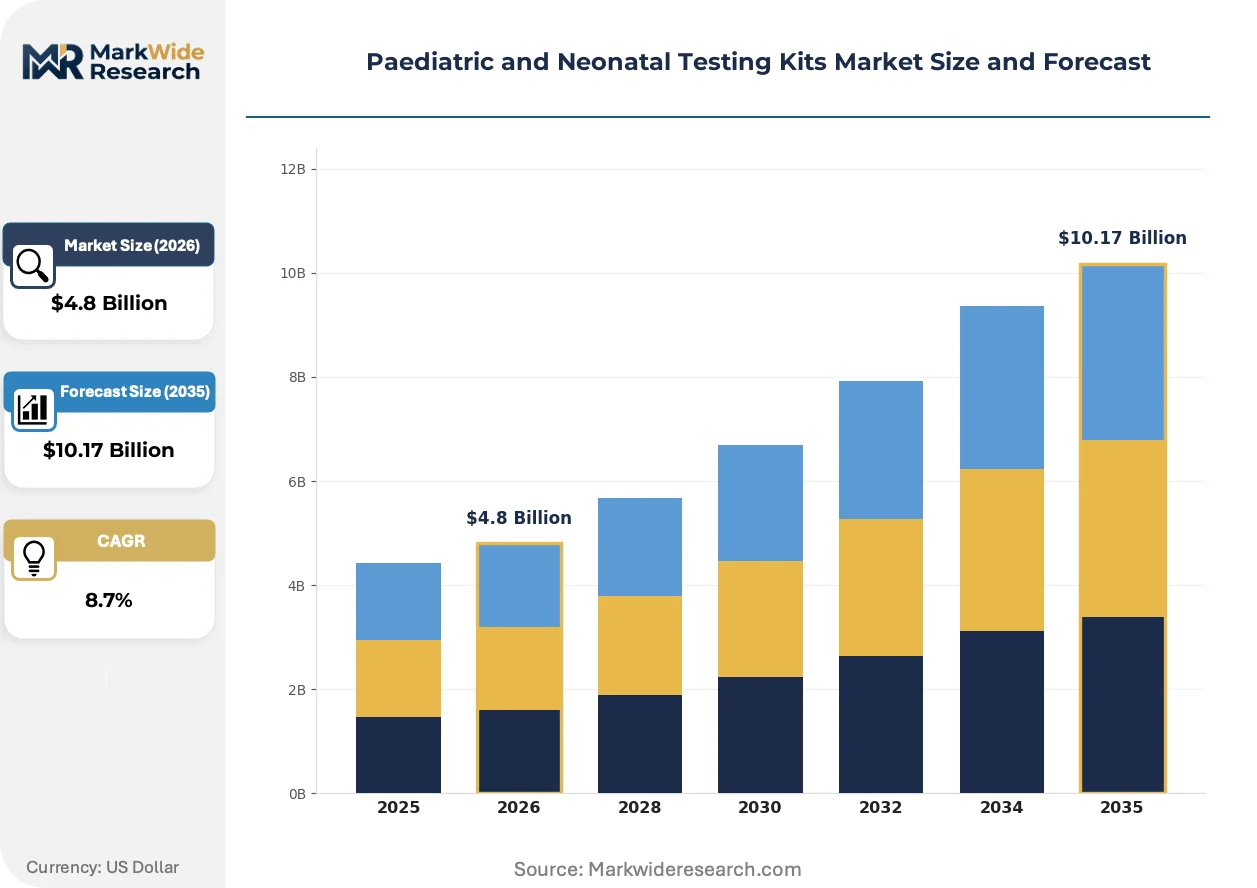
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Glucose Monitors, Hemoglobin Test Kits, Bilirubin Test Strips, Electrolyte Test Devices Application: Critical Care, Newborn Screening, Routine Testing, Point of Care End User: Hospitals, Clinics, Diagnostic Laboratories, Home Care Technology: Colorimetric, Enzymatic Assays, Fluorescent Detection, Immunoassays |
| Companies Covered | PerkinElmer Inc., Bio-Rad Laboratories, Abbott Laboratories, Thermo Fisher Scientific Inc., Danaher Corporation, Roche Diagnostics, Siemens Healthineers, GE Healthcare, Becton, Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paediatric and Neonatal Testing Kits Market Evolving Landscape
Fluorescent detection platforms and machine-learning-enabled result interpretation are compressing turnaround times for critical metabolic assays while regulatory harmonization efforts reshape competitive access across major economies.
Multiplex tandem mass spectrometry is consolidating the newborn screening workflow by enabling simultaneous quantification of amino acids, acylcarnitines, and fatty acid oxidation markers from a single dried blood spot. State-level public health laboratories in the US and provincial screening centers in Canada are adopting these expanded panels at replacement cycle points. This consolidation is compressing the addressable market for standalone immunoassay kits while elevating technical barriers to market entry.
The EU In Vitro Diagnostic Regulation (IVDR) is reclassifying neonatal screening devices into higher-risk categories, mandating clinical evidence dossiers and notified body conformity assessments that were previously self-certified. Kit manufacturers serving European markets face 24-36 month recertification timelines for legacy products. The immunoassay segment bears the heaviest compliance burden, with several mid-tier suppliers withdrawing from the EU rather than absorbing notified body costs.
Hospital procurement departments are bundling point-of-care testing contracts with neonatal intensive care unit supply agreements, displacing standalone kit purchasing. Group purchasing organizations in the US and hospital networks in Germany are consolidating vendor lists to three preferred suppliers per test category. This concentration is most visible in electrolyte and blood gas monitoring, where tertiary centers now demand 10-year total cost-of-ownership guarantees inclusive of calibration and quality control materials.
Paediatric and Neonatal Testing Kits Market Segmentation
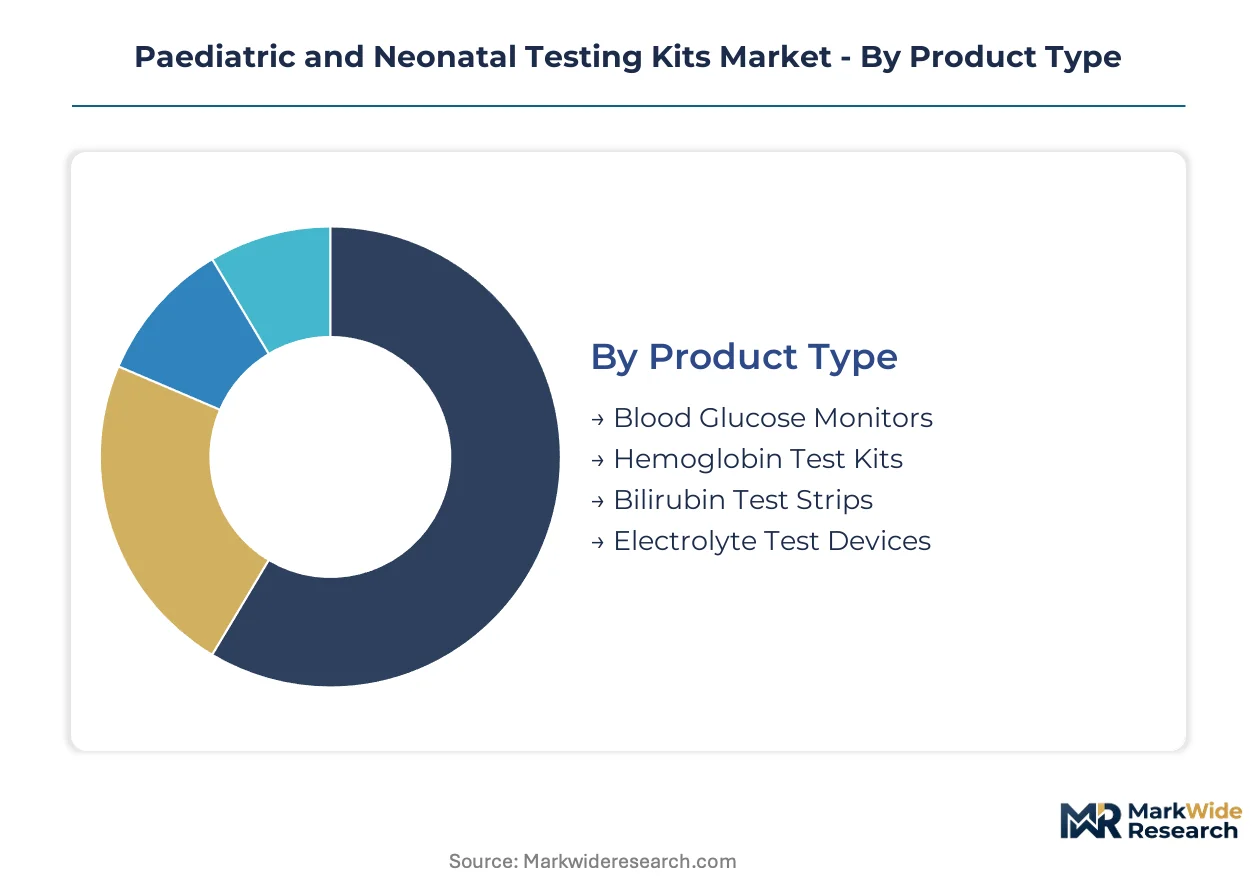
Product differentiation in paediatric and neonatal diagnostics hinges on sample volume tolerance, turnaround speed, and regulatory complexity. Kit manufacturers calibrate portfolio depth across these axes to capture procurement contracts from NICU networks and national screening programs.
Product Type:
Standardization dominates consumables with established reimbursement codes, while specialized micro-volume formats command customization premiums for preterm infant protocols.
- Blood Glucose Monitors:Capillary-draw devices with sub-0.5 microliter sample requirements enable hypoglycemia surveillance in low-birth-weight neonates. Demand concentrates in tertiary hospital NICUs across Brazil and Vietnam where glycemic control protocols are expanding.
- Hemoglobin Test Kits:Point-of-care photometric analyzers deliver immediate anemia screening without centrifugation. Procurement corridors in India's national health mission favor BIS-certified suppliers meeting WHO prequalification for district hospital deployment.
- Bilirubin Test Strips:Transcutaneous and serum-based formats for hyperbilirubinemia screening in nursery settings.
- Electrolyte Test Devices:Ion-selective electrode cartridges for sodium, potassium, and ionized calcium measurement at bedside.
Most installed capacity flows through Blood Glucose Monitors. Expansion is steepest in Electrolyte Test Devices.
Application:
Volume scale inverses with clinical urgency across this category, as mass screening programs generate kit throughput while critical care commands per-test premiums.
- Critical Care:Real-time metabolic monitoring in NICU settings drives consumption of multi-analyte panels with sub-15-minute turnaround. Tertiary centers in South Africa and Kenya are adopting expanded electrolyte and blood gas protocols as infrastructure investment deepens.
- Newborn Screening:Dried blood spot collection cards and tandem mass spectrometry consumables for 40+ metabolic disorder panels. State public health laboratories in the US and provincial programs in Canada dominate procurement volume.
- Routine Testing:Scheduled hematologic and chemistry assessments in paediatric outpatient settings.
- Point of Care:Decentralized testing at clinics and midwife stations without laboratory infrastructure.
Newborn Screening anchors procurement volume through government-mandated programs. Critical Care is gaining share fastest as NICU bed expansion accelerates in middle-income markets.
End User:
Procurement sophistication stratifies sharply, with hospital networks demanding total cost-of-ownership contracts while home care channels prioritize single-use simplicity.
- Hospitals:Integrated delivery networks negotiate multi-year supply agreements bundling devices, consumables, and calibration services. Group purchasing organizations in the US have consolidated preferred vendor lists to three suppliers per test category.
- Diagnostic Laboratories:High-throughput reference labs processing samples from multiple collection sites. CDSCO-registered facilities in India operate as regional hubs for newborn screening panel analysis.
- Clinics:Mid-volume settings requiring CLIA-waived or moderately complex test systems.
- Home Care:Consumer-grade devices with digital connectivity for remote paediatric monitoring in Australia and Canada.
Diagnostic Laboratories process the highest kit volumes through centralized screening mandates. Home Care is expanding most quickly as telemedicine integration matures.
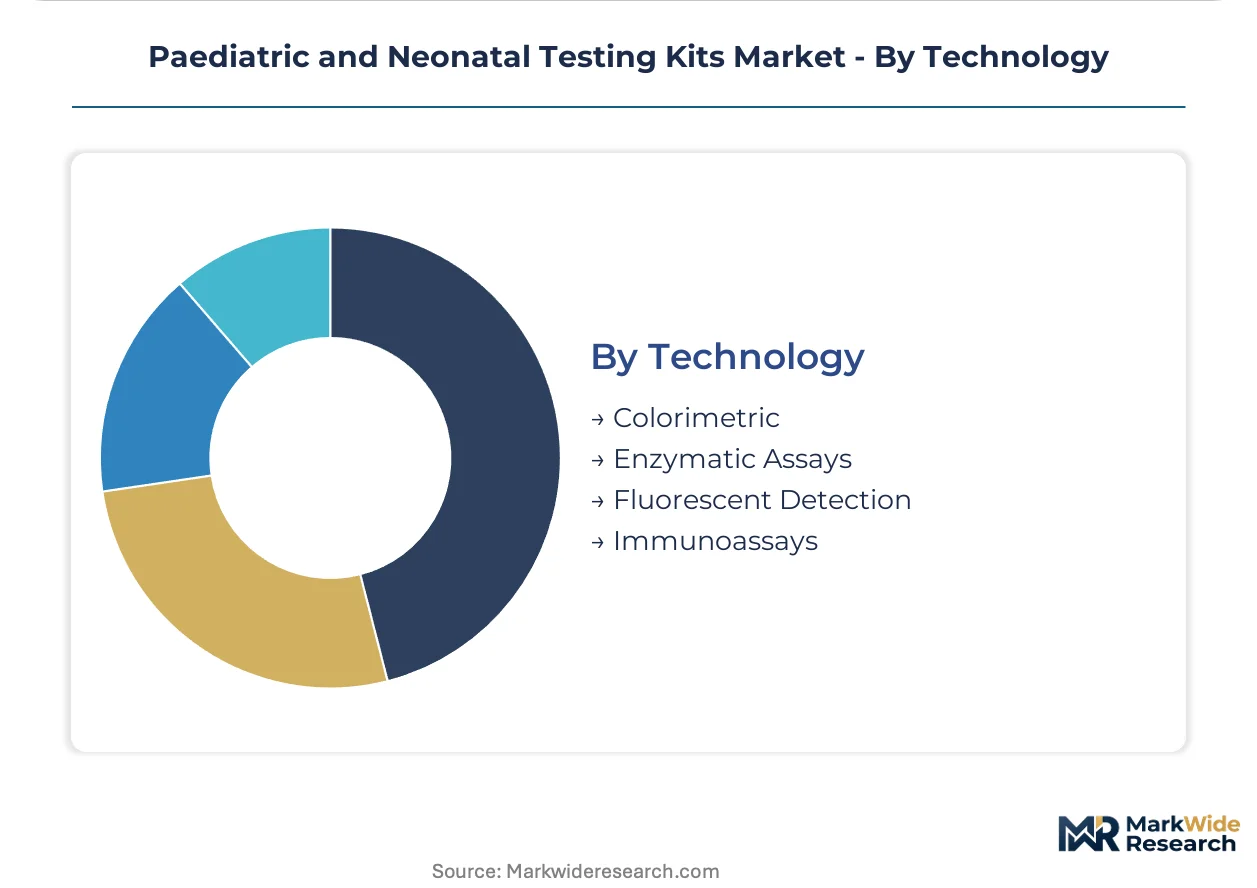
Technology:
Detection chemistry determines regulatory pathway complexity and reagent margin durability, with fluorescent and immunoassay platforms facing steeper evidentiary requirements than colorimetric alternatives.
- Immunoassays:Antibody-based detection for hormone and protein markers in newborn screening panels. EU IVDR reclassification into higher-risk categories has extended recertification timelines to 24-36 months, compressing supplier participation.
- Fluorescent Detection:Time-resolved fluorometry and enzyme-linked amplification for high-sensitivity metabolic assays. Thermo Fisher Scientific anchors R&D investment in this segment for expanded newborn screening workflows.
- Colorimetric:Visual or reflectance-based readout systems for glucose and bilirubin estimation.
- Enzymatic Assays:Biosensor-catalyzed reactions for substrate quantification in point-of-care formats.
Immunoassays command the deepest reagent margins through regulatory stickiness. Fluorescent Detection is climbing the fastest as multiplex panel adoption consolidates instrument platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's government-backed screening corridors widen kit procurement faster than Brazil's NICU expansion, yet both markets concentrate demand in contrasting care settings—decentralized district hospitals versus tertiary critical care hubs.
United States
FDA premarket review and CLIA complexity categorization shape development timelines for point-of-care devices. State public health laboratories in California and New York anchor procurement volume for expanded newborn screening panels. Boston and San Diego clusters concentrate fluorescent detection R&D for multiplex metabolic assays.
Germany
EU MDR and IVDR frameworks impose conformity demands that extend recertification timelines for legacy immunoassay products. Hospital networks in Bavaria and North Rhine-Westphalia consolidate vendor lists to three preferred suppliers per test category. Munich-based procurement consortia demand decade-long total cost-of-ownership guarantees.
India
CDSCO oversight and BIS quality benchmarks filter kit suppliers for the national newborn screening program. Maharashtra and Karnataka host regional diagnostic hubs processing dried blood spot panels from district collection sites. Tamil Nadu's tertiary NICUs drive point-of-care electrolyte device adoption beyond metropolitan centers.
Brazil
Neonatal intensive care unit expansion in São Paulo and Rio de Janeiro broadens test panel adoption beyond basic metabolic screening. ANVISA regulatory pathways shape import licensing for multinational kit manufacturers. Minas Gerais emerges as a secondary demand cluster as provincial health systems deepen glycemic control protocols.
South Africa
Tertiary centers in Gauteng and Western Cape adopt expanded electrolyte and blood gas monitoring as infrastructure investment accelerates. National procurement frameworks favor WHO-prequalified suppliers for bilirubin and glucose kits. Cape Town's academic medical centers pilot machine-learning-enabled result interpretation platforms.
Paediatric and Neonatal Testing Kits Market Competitive Landscape
Top-tier vendors anchor instrument-consumable ecosystems, while mid-tier specialists defend position through regulatory complexity and reagent stickiness. The market structure concentrates around conglomerate-backed diagnostics divisions and focused neonatal screening pure-plays. Three archetypes dominate: full-platform integrators bundling devices with recurring revenue, assay-specialists leveraging fluorescent detection IP, and regional contract manufacturers serving price-sensitive procurement corridors. Consolidation through vertical acquisition of membrane substrate suppliers and strategic partnerships for multiplex panel development represent the dominant competitive moves.
Within the full-platform integrator tier, Abbott Laboratories and Thermo Fisher Scientific occupy positions shaped by installed base leverage and R&D intensity respectively. Abbott's point-of-care device networks sustain consumable pull-through across hospital systems, while Thermo Fisher anchors fluorescent detection advancement for expanded newborn screening workflows. PerkinElmer exemplifies the assay-specialist archetype through its concentration on dried blood spot and tandem mass spectrometry consumables for public health laboratory contracts.
| Leading Market Players |
|---|
| PerkinElmer Inc. |
| Bio-Rad Laboratories |
| Abbott Laboratories |
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| Roche Diagnostics |
| Siemens Healthineers |
| GE Healthcare |
| Becton, Dickinson and Company |
| Others |
Value Network & Pricing Analysis
Reagent-grade membrane substrates from Japanese and German chemical suppliers cascade through three pricing tiers before reaching kit manufacturers, with FDA-certified immunoassay strips commanding premiums over CLIA-waived point-of-care devices sold to price-sensitive district hospitals in India.
Pricing Analysis
Capacity additions in China and South Korea are reshaping price floors for ion-selective electrode modules used in electrolyte test devices. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared neonatal panels from BIS-certified kits for India's national screening program and unbranded consumables for African procurement corridors. Cost compression in the economy tier is intensifying because Asian contract manufacturers are flooding point-of-care hardware markets. District hospital procurement officers in Maharashtra and Karnataka exhibit the highest price sensitivity, while tertiary NICU networks in São Paulo and Boston prioritize total cost-of-ownership guarantees over unit pricing.
Supply Chain Analysis
Refurbishment flows for fluorescent detection platforms concentrate in Germany and the United States, where instrument redeployment extends hardware lifecycles and delays new kit consumable pull-through. Raw material dependencies center on specialized polymers from Japan, optical components from Germany, and biosensor membranes from the United States. Single-source vulnerability looms over reagent-grade membrane substrates, with two Japanese suppliers controlling over 70 percent of global capacity for immunoassay strip substrates. Distribution runs through hospital group purchasing organizations in the United States, regional diagnostic hubs in India, and WHO prequalification corridors for sub-Saharan Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in paediatric and neonatal testing kits rests on software-defined assay calibration reducing instrument dependency, while multiplex panel consolidation shifts procurement toward premium-tier fluorescent detection platforms with deeper reagent stickiness.
For Market Incumbents: Deepen captive supply of membrane substrates through backward integration into Japanese polymer suppliers or long-term offtake agreements with German optical component manufacturers. Expand CLIA-waived test portfolios to defend against point-of-care commoditization by Asian contract manufacturers entering electrolyte device markets. Prioritize R&D investment in machine-learning-enabled result interpretation to differentiate fluorescent detection platforms from colorimetric alternatives. For New Entrants and Emerging Players: Launch via WHO prequalification pathways targeting bilirubin and glucose kit procurement in Nigeria, Kenya, and Ghana where incumbent presence remains thin. The most penetrable white space sits in telemedicine-integrated home sampling for hemoglobin and electrolyte monitoring in Australia and Canada, where consumer-grade digital readout demand outstrips supply. Pursue regulatory arbitrage by securing BIS certification for India's national newborn screening program before attempting FDA 510(k) pathways. For Investors and Strategic Acquirers: Consolidation pressure builds where EU IVDR recertification costs exceed 20 million euros for mid-tier immunoassay suppliers, forcing withdrawal from European markets and creating distressed asset opportunities. Over the medium-term horizon, vertically integrated platform vendors with installed device bases command superior multiples versus pure-play assay specialists exposed to tandem mass spectrometry workflow consolidation. Monitor CDSCO registration velocity for Indian newborn screening program suppliers as the inflection indicator for emerging market procurement momentum.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Multiplex Panels | Accelerates US market access for expanded metabolic disorder screening beyond state laboratory contracts. |
| Backward Integration into Membrane Substrates | Secures captive supply of reagent-grade polymers from Japanese chemical suppliers against input volatility. |
| WHO Prequalification for Bilirubin Kits | Unlocks procurement corridors in Nigeria, Kenya, and Ghana with first-mover advantage over European incumbents. |
| Hospital System Partnership for NICU Bundling | Locks in 10-year consumable contracts through integrated device-service agreements with US group purchasing organizations. |
| Software Companion Development for Telemedicine | Captures home care expansion in Australia and Canada via digital readout integration with remote paediatric monitoring platforms. |
Research Methodology
Direct dialogue with neonatologists, hospital procurement managers, biomedical engineers, and CDSCO regulatory consultants anchored the qualitative foundation, cross-referenced against FDA 510(k) filings, EU IVDR notified body assessments, WHO prequalification registries, and Indian national health mission procurement databases. Bottom-up kit volume estimates from tertiary NICU networks and state public health laboratories triangulated against top-down market sizing from instrument installed base analysis.
Segmentation outputs across product type, application, end user, and technology dimensions fed into growth projections over the analysis window, with CAGR derivation incorporating replacement cycle timing for tandem mass spectrometry platforms and expansion rates for point-of-care electrolyte device adoption. Key inputs included CDSCO registration trajectories, CLIA complexity categorization trends, and GPO contract consolidation patterns in US hospital systems.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of extended FDA premarket review timelines or accelerated EU IVDR enforcement against legacy immunoassay products. Periodic stress-testing of base assumptions is recommended, particularly around membrane substrate supply disruption and Indian national screening program budget allocation volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Roadside Drug Testing Devices Market
Testing Services
Europe Esoteric Testing Market
Testing Services
Ige Allergy Blood Tests Market
Testing Services
Drug Testing Systems Market
Testing Services
Fungal Testing Kits Market
Testing Services
Service Laboratory Market
Testing Services
Leukocyte Count Testing Market
Testing Services
Pancreatic Stone Protein Testing Market
Testing Services
Biological Safety Testing Products and Services Market
Testing Services
Rapid Test Cards Market
Testing Services
Global Bilirubin Colorimeter Assay Market
Testing Services
Radiographic Testing Market
Testing Services
Toxicity Testing Outsourcing Market
Testing Services
Global Extractables and Leachables Testing Services Market
Testing Services
Global Anti Thrombin III Testing Market
Testing Services
Anti-Nuclear Antibody (ANA) Testing Market