
 Gamma Glutamyl Transferase Testing Market | 2026-2036
Gamma Glutamyl Transferase Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Gamma Glutamyl Transferase Testing Market Foresight
Synthetic substrate formulations are recalibrating reagent cost structures across the Gamma Glutamyl Transferase Testing landscape. Roche Diagnostics leverages its integrated diagnostic platform to anchor premium market positioning in automated analyzer deployments. Beckman Coulter sustains competitive density through broad clinical chemistry menu integration that bundles GGT with comprehensive metabolic panels. Abbott Laboratories specializes in point-of-care connectivity, extending its influence into decentralized testing environments where turnaround time commands procurement priority.
Gamma glutamyl transferase testing measures serum GGT enzyme activity, typically via kinetic spectrophotometric methods operating at 37°C with L-γ-glutamyl-3-carboxy-4-nitroanilide substrate, to detect hepatobiliary dysfunction and alcohol-induced liver damage. The enzymatic assay segment dominates routine clinical throughput due to established standardization and cost efficiency, while chemiluminescence formats capture margin pools in high-sensitivity reference laboratories requiring expanded dynamic ranges. Reagents constitute the recurring revenue backbone of the product mix, whereas analyzer placements function as strategic anchors that lock institutions into multi-year consumable contracts.
The FDA's in vitro diagnostic regulatory framework and Clinical Laboratory Improvement Amendments shape analytical performance thresholds and market access requirements for GGT testing platforms. ISO 15189 accreditation standards and EU In Vitro Diagnostic Regulation compliance obligations are forcing manufacturers to recertify legacy assays, creating compliance-driven replacement cycles. Stakeholders must monitor evolving liver disease screening guidelines from hepatology societies and reimbursement authority determinations that directly influence test volume expansion in integrated delivery networks.
Market Dynamics
Integrated health networks in the United States are consolidating laboratory purchasing decisions, compressing vendor margins while demanding expanded test menus and connectivity standards from GGT testing platform suppliers.
Growth Catalysts
- CLIA Laboratory Certification Requirements:The FDA's evolving in vitro diagnostic regulations are pushing clinical laboratories toward higher analytical sensitivity standards, forcing equipment upgrades and reagent standardization.
- Alcohol-Induced Liver Damage Screening Protocols:Hepatology societies are expanding GGT inclusion in routine liver function panels, driving test volume expansion across hospital networks and outpatient clinics.
- Point-of-Care Connectivity Infrastructure:Decentralized testing environments are prioritizing turnaround time, creating procurement priority for platforms with bidirectional laboratory information system integration.
Market Restraints
- Reagent Cost Volatility:Synthetic substrate formulations using L-γ-glutamyl-3-carboxy-4-nitroanilide face input cost pressure from specialty chemical supply concentration in Germany and Switzerland.
- Analyzer Lock-In Effects:Multi-year consumable contracts tied to strategic analyzer placements create switching friction that suppresses competitive entry for mid-tier manufacturers.
- Kinetic Spectrophotometric Method Limitations:Temperature sensitivity at 37°C calibration creates analytical drift in high-throughput environments without continuous quality control investment.
Strategic Opportunities
- EU In Vitro Diagnostic Regulation Compliance Cycles:Legacy assay recertification obligations are creating replacement demand windows for manufacturers with pre-validated quality management systems.
- Chemiluminescence Format Expansion:High-sensitivity reference laboratories require expanded dynamic ranges, opening margin pools beyond routine enzymatic assay commoditization.
- Decentralized Testing Channel Development:Physician office laboratories and urgent care chains represent underpenetrated deployment environments for compact analyzer formats with waived complexity status.
Industry Challenges
- ISO 15189 Accreditation Timeline Compression:Accelerated recertification schedules are straining quality assurance staffing capacity at mid-sized clinical laboratories.
- Multi-Platform Integration Complexity:Health information exchange requirements demand seamless connectivity between GGT analyzers and disparate electronic medical record systems from Epic, Cerner, and MEDITECH.
- Interference Substance Standardization Gaps:Variability in bilirubin and hemoglobin interference thresholds across manufacturer platforms complicates result harmonization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gamma Glutamyl Transferase Testing Market |
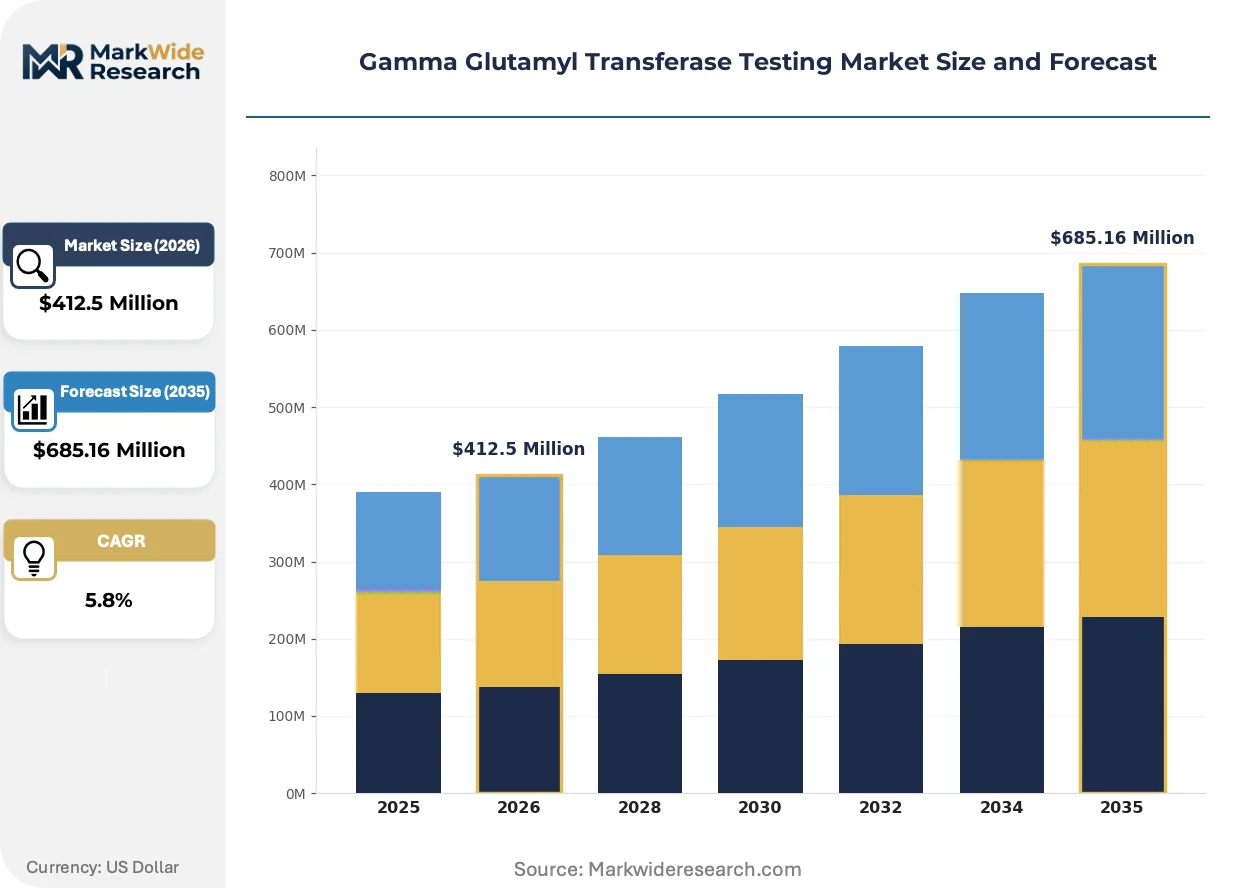
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Analyzers, Test Kits, Calibrators, Controls Technology: Enzymatic Assay, Chemiluminescence, Spectrophotometry, Electrochemical Detection, Immunoassay Application: Liver Function Screening, Alcohol Abuse Diagnosis, Hepatobiliary Diseases, Drug Toxicity Monitoring, Pancreatitis Assessment End User: Diagnostic Laboratories, Research Institutes, Clinical Laboratories, Academic Medical Centers, Biotechnology Firms |
| Companies Covered | Beckman Coulter, Sysmex Corporation, Roche Diagnostics, DiaSys Diagnostic Systems, Horiba Medical, Abbott Laboratories, Randox Laboratories, Ortho Clinical Diagnostics, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gamma Glutamyl Transferase Testing Market Shifts & Advancements
Automation architecture and regulatory recalibration are restructuring competitive positioning in GGT testing, while procurement concentration alters vendor relationship economics.
Microfluidic cartridge systems for GGT quantification are rewriting the capital-labor tradeoff in decentralized environments. Urgent care chains and physician office laboratories are adopting these platforms at accelerated pace to bypass centralized laboratory logistics. This technology is compressing the viable market for high-throughput floor-standing analyzers below 500 tests per day throughput thresholds.
EU In Vitro Diagnostic Regulation technical documentation requirements are forcing manufacturers to revalidate legacy assays with expanded clinical evidence packages. Industrial consequence includes 18-24 month certification timelines that favor incumbents with dedicated regulatory affairs infrastructure. High-sensitivity reference laboratories in France and Germany are responding by consolidating supplier relationships to reduce qualification burden.
Integrated delivery networks are unbundling reagent procurement from analyzer service contracts, creating direct purchasing relationships with consumable manufacturers. Group purchasing organizations are capturing this channel shift through specialized laboratory contracting divisions. This pattern is most visible in United States health systems exceeding 10 hospital affiliates, where procurement centralization has reached 70% contract coverage for clinical chemistry menus.
Gamma Glutamyl Transferase Testing Market Segmentation
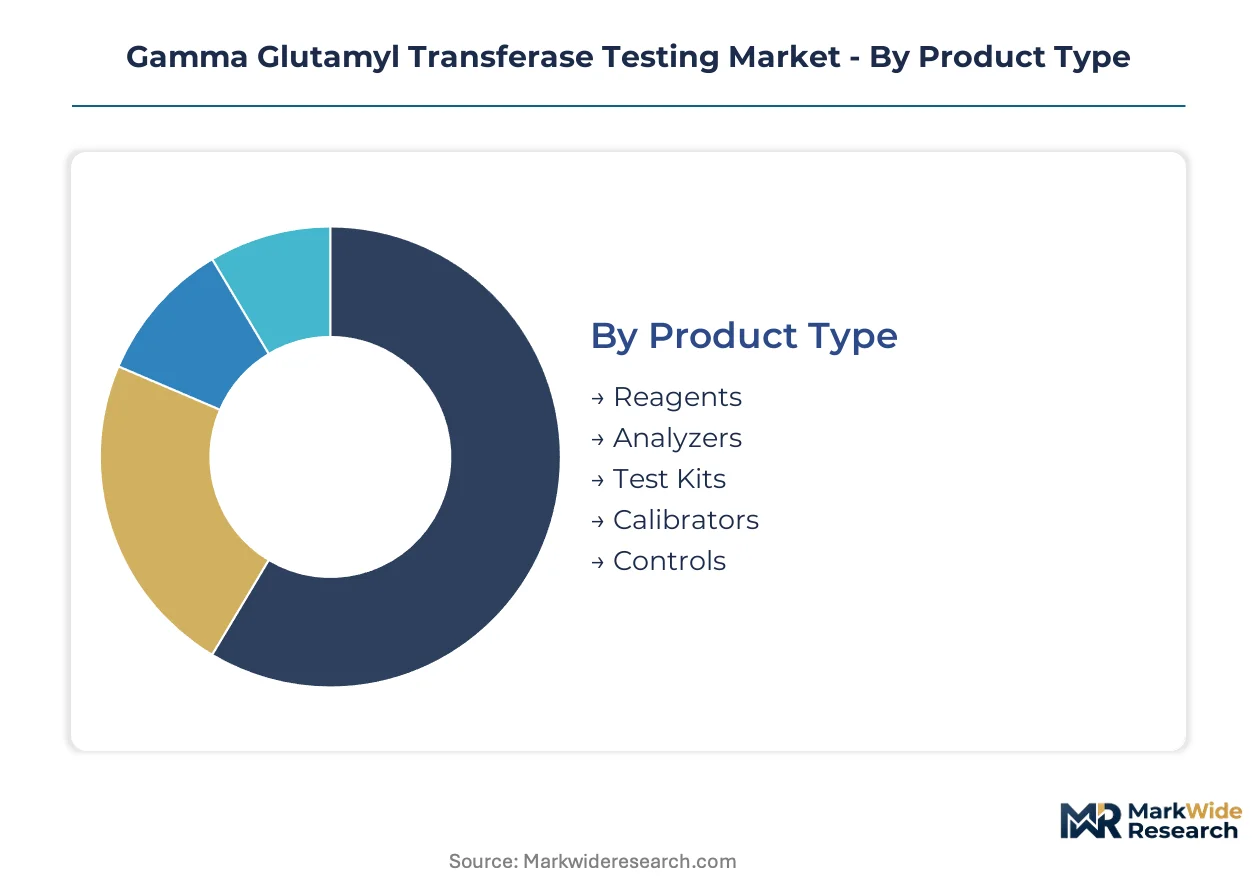
Segmentation in the Gamma Glutamyl Transferase Testing Market reveals how procurement patterns and regulatory recertification cycles concentrate value across distinct product tiers and deployment environments. Understanding these divisions exposes where manufacturers can defend margin positions and where commoditization pressures erode pricing power.
Product Type:
Upgrade and replacement cycles vary sharply across product categories, with analyzer placements driving multi-year consumable lock-in while standalone reagents face annual competitive rebidding.
- Reagents:Synthetic substrate formulations using L-γ-glutamyl-3-carboxy-4-nitroanilide constitute the recurring revenue backbone, with purchasing concentrated in integrated health networks consolidating laboratory contracts. FDA in vitro diagnostic regulations force reformulation investments that favor incumbents with dedicated quality management systems.
- Analyzers:Floor-standing and compact formats anchor strategic placements through bidirectional laboratory information system connectivity, with procurement priority shifting toward platforms supporting waived complexity status in decentralized environments. Temperature calibration stability at 37°C remains a critical performance threshold.
- Test Kits:Pre-configured consumable sets reduce setup variability in mid-throughput laboratories.
- Calibrators:Traceability standards compliance drives replacement demand in EU In Vitro Diagnostic Regulation recertification windows.
- Controls:Quality assurance mandates sustain steady procurement volumes across clinical chemistry menus.
Reagents sit at the top of the volume ranking, with analyzers climbing the fastest as integrated delivery networks consolidate capital equipment decisions.
Technology:
Cost tier stratification separates premium chemiluminescence platforms from commoditized enzymatic methods, with margin pools concentrating in high-sensitivity reference laboratories requiring expanded dynamic ranges.
- Enzymatic Assay:Kinetic spectrophotometric methods operating at 37°C dominate routine clinical throughput through established standardization and cost efficiency, with demand concentrated in hospital networks processing liver function panels at scale. CLIA laboratory certification requirements sustain replacement cycles for legacy equipment.
- Chemiluminescence:High-sensitivity formats capture margin pools in reference laboratories requiring expanded measurement ranges for hepatobiliary disease staging, with procurement concentrated in academic medical centers and specialty diagnostics chains. EU In Vitro Diagnostic Regulation compliance obligations favor pre-validated platforms.
- Spectrophotometry:Visible-range detection supports cost-sensitive deployment in physician office laboratories.
- Electrochemical Detection:Point-of-care connectivity integration drives adoption in urgent care chains prioritizing turnaround time.
- Immunoassay:Antibody-based quantification serves niche applications in research institute settings.
Enzymatic assay maintains the highest test volume, with chemiluminescence gaining share fastest among technology transitions.
Application:
Application maturity varies from routine screening protocols with established reimbursement codes to emerging monitoring use cases still negotiating coverage determinations.
- Liver Function Screening:Standard inclusion in metabolic panels drives baseline demand across outpatient and inpatient settings, with hepatology society guidelines expanding test frequency recommendations. Procurement concentrates in United States integrated health networks consolidating laboratory purchasing decisions.
- Alcohol Abuse Diagnosis:GGT elevation patterns support abstinence monitoring and relapse detection in addiction medicine programs, with demand growing in behavioral health integration initiatives. FDA regulatory frameworks shape analytical performance thresholds for forensic-admissible results.
- Hepatobiliary Diseases:Cholestatic pattern differentiation sustains specialist laboratory volumes.
- Drug Toxicity Monitoring:Pharmaceutical safety protocols drive contract research organization demand.
- Pancreatitis Assessment:Adjunctive diagnostic use supports emergency department triage algorithms.
Liver function screening leads application volume, with alcohol abuse diagnosis expanding most quickly amid behavioral health integration trends.
End User:
Customer type determines connectivity requirements and service contract structures, with diagnostic laboratories demanding enterprise integration while research institutes prioritize analytical flexibility.
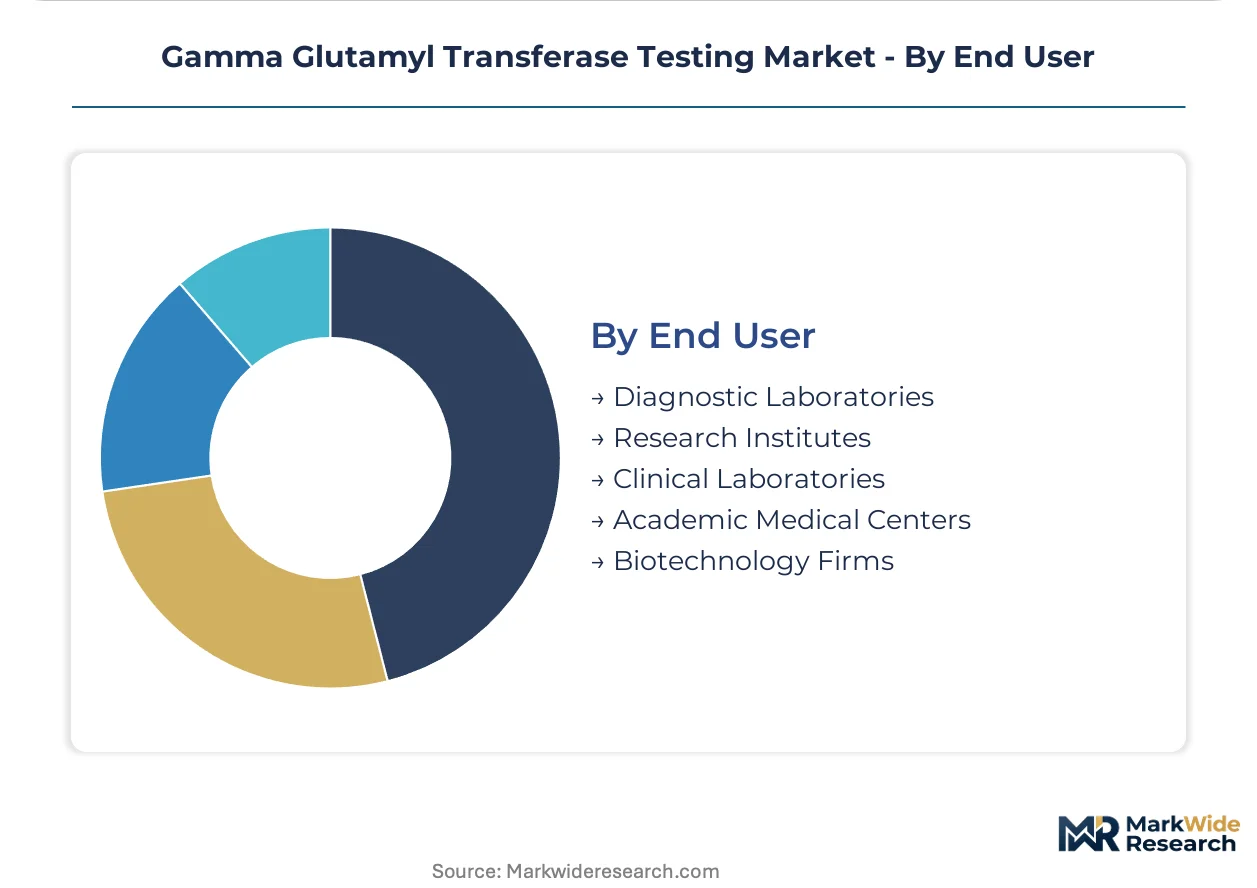
- Diagnostic Laboratories:High-throughput processing environments drive demand for automated analyzer platforms with continuous quality control capabilities, with purchasing concentrated in United States group purchasing organization networks exceeding 10 hospital affiliates. ISO 15189 accreditation timelines compress vendor qualification windows.
- Clinical Laboratories:Mid-tier facilities balance throughput requirements against capital constraints, with procurement shifting toward reagent rental agreements bundled with service contracts. Health information exchange requirements demand seamless Epic and Cerner electronic medical record integration.
- Research Institutes:Method development flexibility sustains demand for customizable assay parameters.
- Academic Medical Centers:Teaching and research missions drive dual-use platform procurement.
- Biotechnology Firms:Drug development toxicology screening supports specialized contract manufacturing demand.
Diagnostic laboratories command the highest test volume, with clinical laboratories climbing fastest as procurement centralization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated health networks in the United States concentrate the highest test volumes for Gamma Glutamyl Transferase Testing, while European regulatory recertification cycles and Asian manufacturing expansion reshape procurement geography.
United States
Hospital network consolidation drives analyzer standardization across multi-site laboratory systems. FDA in vitro diagnostic regulations enforce CLIA laboratory certification upgrades for analytical sensitivity compliance. The Mayo Clinic and Cleveland Clinic anchor reference laboratory demand in the Upper Midwest.
Germany
Specialty chemical suppliers concentrate synthetic substrate production for enzymatic assay reagents. EU In Vitro Diagnostic Regulation technical documentation requirements force 18-24 month legacy assay recertification timelines. Industrial clusters in Baden-Württemberg host precision diagnostics manufacturing.
Japan
Aging demographics expand liver function screening protocols in metropolitan hospital networks. PMDA regulatory frameworks shape analytical performance thresholds for automated chemistry platforms. Tokyo and Osaka academic medical centers drive high-sensitivity chemiluminescence adoption.
China
Hospital laboratory automation upgrades accelerate throughput expansion in tier-one cities. NMPA in vitro diagnostic registration requirements standardize reagent quality management systems. Shanghai and Beijing anchor integrated diagnostics platform deployment.
India
Private diagnostic chains expand point-of-care connectivity in tier-two urban centers. CDSCO medical device regulations harmonize with ISO 15189 accreditation standards for laboratory quality assurance. Mumbai and Delhi NCR concentrate reference laboratory infrastructure investment.
Gamma Glutamyl Transferase Testing Market Competitive Landscape
Global majors compete with regional champions across reagent standardization and analyzer platform integration. Market structure tilts toward consolidated procurement leverage, with integrated health networks compressing vendor margins through multi-year consumable contracts. Three archetypes dominate: diversified diagnostics conglomerates with full chemistry menus, specialized reagent manufacturers with substrate formulation expertise, and point-of-care connectivity specialists. Competitive moves center on analyzer placement strategies that lock institutions into captive reagent supply, alongside regulatory pre-validation investments that accelerate EU IVDR compliance timelines.
Among diversified platform suppliers, Roche Diagnostics, Beckman Coulter, and Abbott Laboratories exemplify distinct competitive positioning. Roche anchors premium automated analyzer deployment through integrated diagnostic ecosystems. Beckman Coulter occupies a position bundling GGT within broad clinical chemistry menus for high-throughput hospital laboratories. Abbott represents point-of-care connectivity specialization, extending influence into decentralized testing environments where turnaround time determines procurement priority.
| Leading Market Players |
|---|
| Beckman Coulter |
| Sysmex Corporation |
| Roche Diagnostics |
| DiaSys Diagnostic Systems |
| Horiba Medical |
| Abbott Laboratories |
| Randox Laboratories |
| Ortho Clinical Diagnostics |
| Thermo Fisher Scientific |
| Others |
Supply & Pricing Matrix
Specialized biochemist labor pools in Baden-Württemberg and Basel anchor synthetic substrate production, with wage differentials between German precision manufacturing hubs and Swiss pharmaceutical corridors driving tiered reagent pricing spreads across enzymatic assay supply tiers.
Pricing Analysis
Input-cost pass-through from L-γ-glutamyl-3-carboxy-4-nitroanilide substrate formulations anchors reagent pricing structures, with specialty chemical concentration in Germany and Switzerland amplifying volatility transmission to end-user contracts. Three-tier pricing structure across premium chemiluminescence, standard enzymatic, and economy spectrophotometry levels separates reference laboratories from routine hospital processors. Cost compression in mid-tier reagent bundles is intensifying because integrated health networks are unbundling analyzer service contracts from consumable procurement. Physician office laboratories exhibit highest price sensitivity, while academic medical centers with research missions demonstrate lowest sensitivity due to dual-use platform requirements.
Supply Chain Analysis
Warehouse-distribution layer consolidation around regional clinical laboratory hubs in the United States, Germany, and Japan shapes just-in-time re replenishment patterns for temperature-sensitive substrate inventories. Synthetic substrate production draws from German and Swiss specialty chemical manufacturers, with analyzer final assembly concentrated in Japanese and American precision diagnostics facilities. Single-source vulnerability in L-γ-glutamyl-3-carboxy-4-nitroanilide precursor supply creates concentration risk at intermediate chemical processors. Distribution runs through group purchasing organization networks and direct manufacturer relationships with integrated delivery networks exceeding ten hospital affiliates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU In Vitro Diagnostic Regulation compliance timelines stretching 18-24 months against streamlined FDA 510(k) pathways create geographic-arbitrage opportunities for manufacturers with dual-registered quality management systems, exploiting regulatory cost differentials between European recertification burdens and American market access efficiency.
For Market Incumbents: Lock in multi-year consumable contracts through strategic analyzer placements in consolidating United States health networks, defending against mid-tier manufacturers with pre-validated EU IVDR technical documentation. Prioritize backward integration into synthetic substrate formulation to capture margin pools eroding from specialty chemical supplier pricing power. Channel control through bidirectional laboratory information system integration with Epic and Cerner platforms sustains switching friction against emerging connectivity specialists. For New Entrants and Emerging Players: Enter via physician office laboratories and urgent care chains in tier-two United States metropolitan markets, where waived complexity status requirements and turnaround-time procurement priorities remain underpenetrated by floor-standing analyzer incumbents. Target compact microfluidic cartridge formats with point-of-care connectivity as the most penetrable deployment environment. Go-to-market execution should emphasize direct purchasing relationships with group purchasing organization laboratory contracting divisions bypassing legacy analyzer lock-in effects. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized reagent manufacturers with substrate formulation expertise lacking integrated analyzer platforms, as diversified diagnostics conglomerates command premium multiples for captive consumable ecosystems. Long-term viability over the projection horizon favors targets with pre-validated EU IVDR quality management systems and established relationships with academic medical center reference laboratories. Monitor hepatology society guideline revisions expanding GGT inclusion frequency as the signal to watch for test volume inflection and replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU IVDR Pre-Validation Investment | Accelerated 18-24 month certification timelines favor incumbents with dedicated regulatory infrastructure in Germany and France. |
| Microfluidic Cartridge Development | Compact formats capture urgent care and physician office laboratory demand prioritizing turnaround time over throughput. |
| Analyzer Placement with Consumable Lock-In | Strategic capital equipment deployment secures multi-year reagent contracts in consolidating United States health networks. |
| Backward Integration into Substrate Synthesis | In-house production of L-γ-glutamyl-3-carboxy-4-nitroanilide formulations defends margins against German and Swiss chemical supplier concentration. |
| Bidirectional LIS Integration Partnership | Seamless Epic and Cerner connectivity creates procurement priority in integrated delivery networks exceeding ten hospital affiliates. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with clinical laboratory directors, IVD regulatory affairs specialists, hospital procurement committee members, and group purchasing organization contracting officers alongside secondary validation from FDA 510(k) filings, EU IVDR technical documentation databases, hospital procurement records, and SEC diagnostics segment disclosures. Bottom-up test volume modeling and top-down market sizing triangulation anchor analytical rigor.
Granularity-level framing applies country-specific regulatory pathway modeling for United States CLIA certification, EU IVDR compliance, and Japan PMDA registration, with technology segmentation distinguishing enzymatic assay from chemiluminescence format adoption curves across the projection horizon. Product type, application, and end-user dimensions incorporate analyzer placement cycles, reagent consumption rates, and integrated health network consolidation patterns. CAGRs derive from test volume trajectory analysis weighted by reimbursement code stability and hepatology society guideline revision probabilities.
The model holds under stable regulatory enforcement timelines and continued hospital network consolidation; deviation in EU IVDR implementation delays or CLIA waiver expansion would shift competitive positioning and replacement demand timing. Forecasts reflect documented assumptions regarding substrate cost trajectories and analyzer technology transition rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Point of Care Testing Market
Testing Services
Global Direct-To-Consumer (DTC)Testing Market
Testing Services
Nucleic Acid Amplification Testing Market
Testing Services
Global Legionella Testing Market
Testing Services
Global Enzyme Linked Immunosorbent Assay (ELISA) Testing Market
Testing Services
Friability Tester Market
Testing Services
Global Nitric Oxide Test Market
Testing Services
Redox Meter Market
Testing Services
STD Testing Devices Market
Testing Services
Global Bioburden Testing Market
Testing Services
Home Menopause Testing Market
Testing Services
Biological Indicator Incubators Market
Testing Services
Global GI Stool Testing Market
Testing Services
Ige Allergy Blood Tests Market
Testing Services
Employer and Workplace Drug Testing Market
Testing Services
US Independent Diagnostic Testing Facility Market