
 Global IVD Regulatory Affairs Outsourcing Market | 2026-2036
Global IVD Regulatory Affairs Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Global IVD Regulatory Affairs Outsourcing Market Foresight
Modular service bundling is recalibrating how IVD manufacturers select regulatory partners. IQVIA Holdings Inc. leverages its integrated clinical and regulatory data infrastructure to capture multi-year engagements across molecular diagnostics portfolios. Charles River Laboratories International, Inc. anchors its positioning through deep preclinical-to-registration continuity, particularly for novel biomarker submissions. WuXi AppTec competes on geographic density, operating regulatory hubs that reduce turnaround times for Asia-origin manufacturers seeking FDA clearance.
IVD regulatory affairs outsourcing encompasses the delegation of compliance strategy, submission preparation, quality system maintenance, and post-market surveillance to third-party specialists possessing jurisdiction-specific expertise and established rapport with health authorities. The practice centers on navigating technical documentation requirements—clinical evidence packages, performance evaluation reports, and risk management files—that vary across the FDA's 510(k) and PMA pathways, the EU IVDR's Class A-D stratification, and Japan PMDA's QMS ordinances. Regulatory submissions and compliance audits dominate current service demand, reflecting backlog accumulation at understaffed notified bodies and intensified FDA inspection frequency. Clinical trial management within the outsourcing frame is expanding fastest among biotechnology companies lacking in-house regulatory infrastructure for companion diagnostic co-development programs.
FDA, EMA through its notified body designation framework, and Japan's PMDA collectively shape market access timelines and service pricing through divergent evidentiary standards and inspection cadences. The EU IVDR's 2022 enforcement window and subsequent capacity bottlenecks at BSI Group and TÜV SÜD Product Service GmbH have permanently altered manufacturer build-vs-buy calculations for regulatory staffing. Stakeholders must monitor notified body designation expansions and FDA's emerging guidance on artificial intelligence-enabled IVD algorithms to calibrate partnership depth and geographic coverage.
Market Dynamics
Notified body capacity constraints under the EU IVDR are compressing manufacturer timelines and forcing permanent recalibration of regulatory staffing models toward external partners.
Growth Catalysts
- EU IVDR Class D backlog:High-risk device manufacturers face 18-24 month review queues at designated notified bodies, creating immediate pull for submission-ready documentation services.
- Companion diagnostic co-development:Oncology drug sponsors lacking parallel IVD regulatory infrastructure outsource end-to-end PMA pathway management to compress combined approval timelines.
- Germany:Concentration of notified body headquarters in Munich and Frankfurt generates geographic clustering of regulatory expertise demand from pan-European manufacturers.
Market Restraints
- Notified body oligopoly:BSI Group, TÜV SÜD Product Service GmbH, and DEKRA Testing and Certification GmbH control over 70% of IVDR designation capacity, creating single-point-of-failure risk for outsourced submission timelines.
- Clinical evidence cost inflation:Performance evaluation report preparation for novel biomarkers requires specialized biostatisticians and clinical laboratorians, driving 15-20% annual fee escalation at top-tier consultancies.
- Substitution by captive regulatory teams:Large diagnostic manufacturers including Roche Diagnostics and Abbott Laboratories are rebuilding in-house EU regulatory functions post-IVDR stabilization, reducing addressable outsourcing pool.
Strategic Opportunities
- Japan PMDA QMS ordinance convergence:Outsourcing providers with dual FDA-PMDA expertise capture molecular diagnostic manufacturers seeking synchronized US-Japan registration strategies.
- Artificial intelligence-enabled IVD algorithms:FDA's emerging software-as-medical-device guidance creates white space for regulatory partners specializing in algorithm validation and predetermined change control plans.
- Post-market surveillance unbundling:Vigilance reporting and periodic safety update report preparation represent underpenetrated service lines with 40-50% margin profiles versus submission work.
Industry Challenges
- Competent authority liaison scarcity:Experienced notified body relationship managers command premium compensation, constraining boutique consultancy scale-up.
- Legacy quality system integration:Manufacturers with ISO 13485:2016 certificates require gap assessment and documentation remediation before IVDR Annex IX compliance, extending engagement timelines unpredictably.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IVD Regulatory Affairs Outsourcing Market |
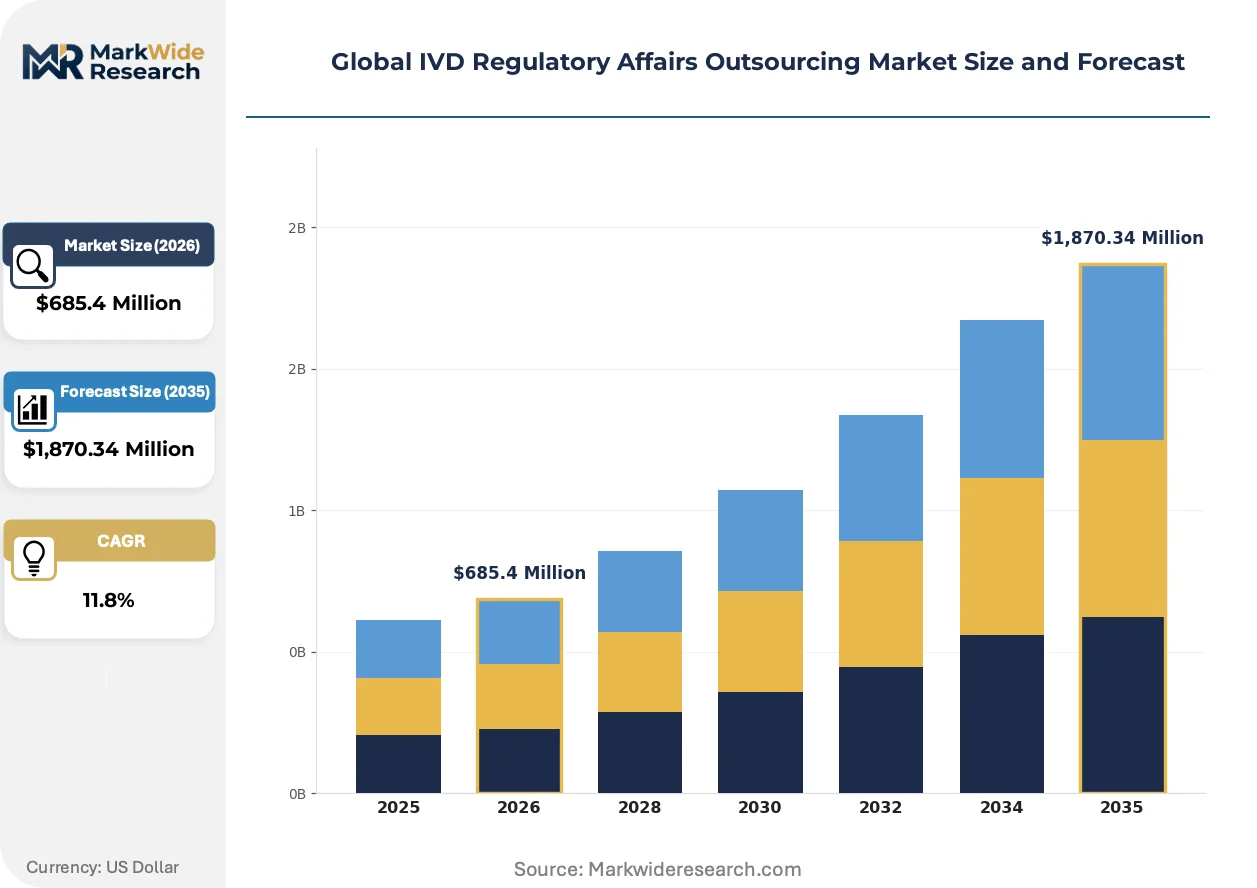
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,870.34 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Regulatory Submissions, Compliance Audits, Labeling Support, Clinical Trial Management, Risk Assessment End User: Diagnostic Laboratories, Medical Research Institutes, Biotechnology Companies, Government Agencies, Independent Testing Facilities Technology: Molecular Diagnostics, Immunodiagnostics, Hematology, Microbiology, Biochemistry Engagement Type: Project-Based, Retainer-Based, Hybrid Model, Time & Material, Outcome-Based |
| Companies Covered | ICON plc, Labcorp (Laboratory Corporation of America Holdings), IQVIA Holdings Inc., SGS SA, Intertek Group plc, Charles River Laboratories International, Inc., WuXi AppTec, Eurofins Scientific, PAREXEL International Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IVD Regulatory Affairs Outsourcing Market Shifts & Advancements
Regulatory technology platforms are embedding machine learning into submission document preparation, compressing review cycles while raising new questions about audit trail integrity and health authority acceptance.
Natural language processing tools for predicate device identification and 510(k) substantial equivalence argumentation are absorbing tasks previously executed by junior regulatory associates. Mid-tier IVD manufacturers deploy these platforms to reduce reliance on high-cost consultancy hours for routine submission preparation. The technology is absorbing lower-complexity documentation work and forcing service providers to reposition toward strategic regulatory pathway design and health authority negotiation.
The FDA's 2023 guidance on clinical decision support software and its 2024 draft on AI-enabled device transparency are reshaping evidentiary requirements for algorithm-based diagnostics. Manufacturers must now submit model development descriptions and performance monitoring protocols that exceed traditional analytical validation packages. Software-only IVD developers with limited regulatory infrastructure represent the fastest-growing client segment for specialized AI/ML regulatory consultancies.
Diagnostic sponsors are unbundling regulatory affairs from full-service clinical research organization contracts, establishing direct relationships with niche regulatory boutiques for submission work while retaining large CROs for trial execution. This disintermediation reflects dissatisfaction with generalized regulatory expertise at volume-focused service providers. Biotechnology companies in the San Francisco Bay Area and Boston-Cambridge corridor lead this procurement pattern shift, seeking specialized IVD regulatory depth over therapeutic trial scale.
Global IVD Regulatory Affairs Outsourcing Market Segmentation
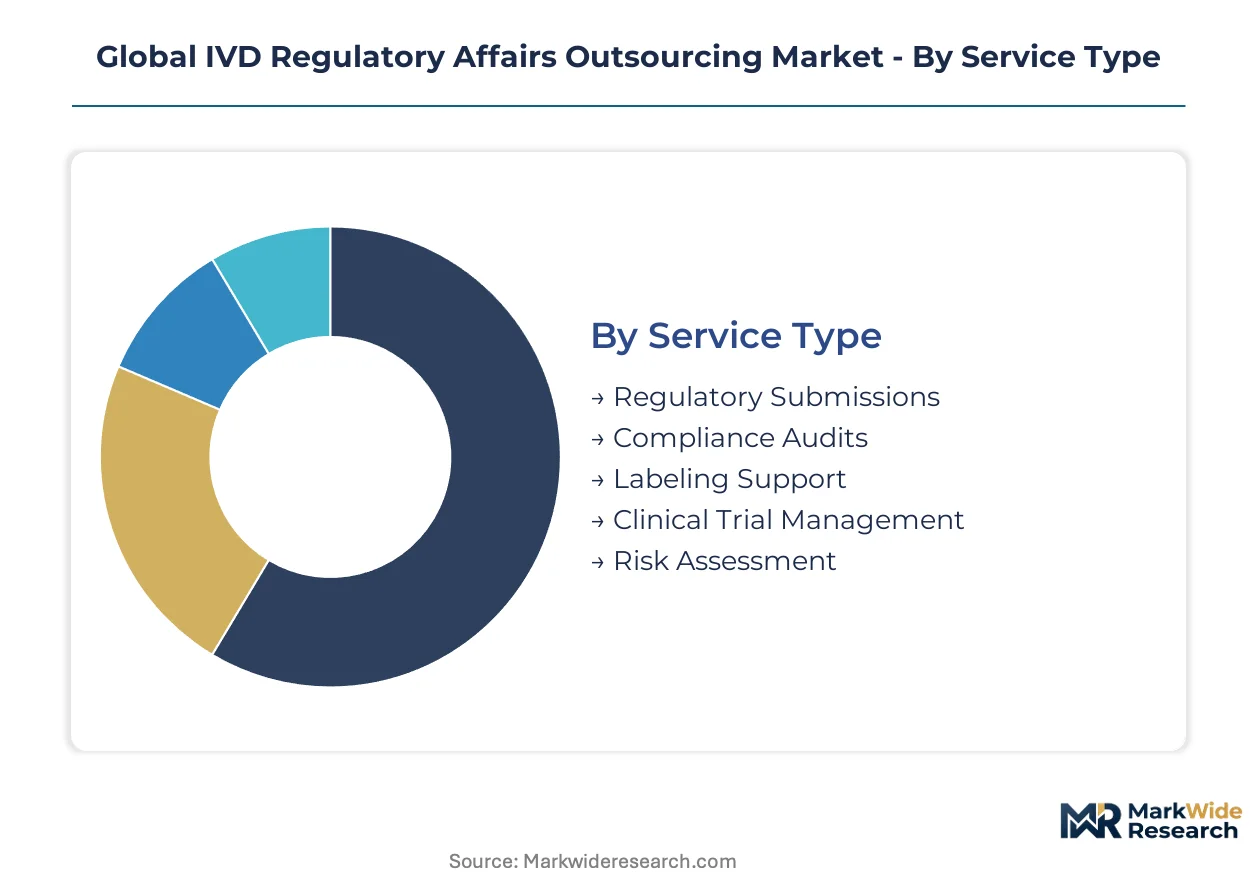
IVD regulatory outsourcing contracts fragment across service intensity, client sophistication, and technology complexity. Procurement patterns diverge sharply between manufacturers seeking discrete submission support and those requiring embedded regulatory partnerships across multi-jurisdictional portfolios.
Service Type:
Regulatory submissions and compliance audits command premium pricing due to specialized technical documentation requirements and direct health authority interface demands.
- Regulatory Submissions:Encompasses 510(k), PMA, and IVDR technical file preparation with predicate device analysis and substantial equivalence argumentation. Demand concentrates in Germany and the United States where notified body backlogs and FDA inspection intensity compress internal timelines.
- Compliance Audits:Covers ISO 13485 surveillance audits, IVDR Annex IX gap assessments, and FDA QSIT inspections. Biotechnology companies in Boston-Cambridge and San Francisco Bay Area clusters drive fastest expansion as companion diagnostic programs multiply.
- Labeling Support:IFU drafting, symbol standardization per ISO 15223-1, and multilingual translation management for EU member state requirements.
- Clinical Trial Management:Performance evaluation study design, biostatistics, and clinical evidence package assembly for novel biomarker submissions.
- Risk Assessment:ISO 14971-compliant hazard analysis, post-market surveillance integration, and vigilance reporting workflow design.
Mature deployment sits with Regulatory Submissions. Newer deployment is concentrated in Clinical Trial Management.
End User:
Customer scale determines contract structure, with large diagnostic manufacturers favoring retainer arrangements and emerging biotechnology sponsors preferring project-based engagements.
- Diagnostic Laboratories:Hospital-affiliated and reference laboratories facing EU IVDR Class D device transitions outsource technical documentation and notified body liaison. Germany's concentrated notified body headquarters generates geographic clustering of demand from pan-European laboratory networks.
- Biotechnology Companies:Oncology drug developers lacking parallel IVD infrastructure for companion diagnostic co-development represent the steepest expansion trajectory. These sponsors require end-to-end PMA pathway management to synchronize therapeutic and diagnostic approvals.
- Medical Research Institutes:Academic medical centers with laboratory-developed test portfolios seeking FDA enforcement discretion navigation.
- Government Agencies:National health ministries and reference laboratories in emerging markets requiring WHO prequalification support.
- Independent Testing Facilities:Contract research organizations and specialized analytical laboratories supplementing internal quality assurance functions.
Volume concentration aligns with Diagnostic Laboratories. Margin expansion is strongest in Biotechnology Companies.
Technology:
Regulatory complexity escalates with analytical platform sophistication, with algorithm-enabled molecular diagnostics requiring novel evidentiary frameworks.
- Molecular Diagnostics:PCR, NGS, and nucleic acid amplification platforms with companion diagnostic claims. FDA's emerging AI-enabled device guidance and software-as-medical-device frameworks create white space for specialized regulatory partners managing algorithm validation protocols.
- Immunodiagnostics:ELISA, chemiluminescence, and lateral flow devices with established predicate pathways. Manufacturers in Japan and the United States seek synchronized PMDA-FDA registration strategies for autoimmune and infectious disease panels.
- Hematology:Cell counting and coagulation analyzers with mature 510(k) submission precedents.
- Microbiology:Culture-based and rapid antimicrobial susceptibility testing platforms.
- Biochemistry:Clinical chemistry analyzers and point-of-care metabolite testing with standardized analytical validation requirements.
Regulatory novelty is highest in Molecular Diagnostics. Submission standardization is most advanced in Biochemistry.
Engagement Type:
Contract economics reflect outcome uncertainty, with outcome-based structures emerging for novel technology categories lacking established approval precedents.
- Project-Based:Discrete submission preparation with defined deliverables and fixed fees. Dominates among mid-tier IVD manufacturers with intermittent regulatory needs.
- Retainer-Based:Continuous advisory access and proactive compliance monitoring. Large diagnostic manufacturers in Germany and the United States favor this structure for multi-jurisdictional portfolio management.
- Hybrid Model:Baseline retainer with project-specific surge capacity. Gaining share fastest among molecular diagnostic developers balancing pipeline unpredictability with core regulatory infrastructure needs.
- Time & Material:Hourly billing for unpredictable scope engagements, common in legacy quality system remediation.
- Outcome-Based:Success fees tied to approval milestones, emerging for AI-enabled IVD algorithms with uncertain regulatory pathways.
Structural stability characterizes Retainer-Based arrangements. Pricing innovation is concentrated in Outcome-Based contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory service production concentrates in jurisdictions with mature health authority infrastructure, while demand emanates from manufacturers navigating complex multi-market submissions. The United States and Germany anchor service supply through FDA and notified body proximity. China, Japan, and the United Kingdom generate outsized demand relative to domestic regulatory capacity.
United States
FDA's intensified inspection cadence and 510(k) submission volume drive demand for submission-ready documentation services. The agency's 2023 guidance on clinical decision support software and 2024 draft on AI-enabled device transparency reshape evidentiary requirements. The San Francisco Bay Area and Boston-Cambridge corridor concentrate biotechnology sponsors seeking specialized IVD regulatory depth over generalized CRO offerings.
Germany
Notified body headquarters in Munich and Frankfurt create geographic clustering of regulatory expertise demand from pan-European manufacturers. BSI Group, TÜV SÜD Product Service GmbH, and DEKRA Testing and Certification GmbH control over 70% of IVDR designation capacity, compressing manufacturer timelines. The country's laboratory networks outsource technical documentation for Class D device transitions under EU IVDR enforcement.
China
NMPA's evolving medical device classification rules and growing molecular diagnostic innovation drive demand for dual FDA-NMPA registration strategies. Domestic manufacturers expanding into US and EU markets lack parallel regulatory infrastructure for companion diagnostic co-development. Shanghai and Beijing concentrate outsourcing providers serving Asia-origin manufacturers seeking FDA clearance.
Japan
PMDA's QMS ordinance convergence with international standards creates opportunity for outsourcing providers with dual FDA-PMDA expertise. Molecular diagnostic manufacturers seek synchronized US-Japan registration strategies for oncology panels. Tokyo and Osaka anchor demand from domestic sponsors lacking in-house regulatory infrastructure for PMA-equivalent pathways.
United Kingdom
Post-Brexit divergence from EU IVDR implementation creates parallel compliance obligations for manufacturers maintaining CE UKCA dual marking. The Medicines and Healthcare products Regulatory Agency's evolving IVD framework generates demand for gap assessment and documentation remediation. London and Cambridge concentrate biotechnology companies unbundling regulatory affairs from full-service CRO contracts.
Global IVD Regulatory Affairs Outsourcing Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across service intensity tiers. The market structures around three player categories: integrated clinical research organizations with regulatory divisions, dedicated regulatory consultancies, and quality system specialists. Consolidation pressures favor scale-driven players with multi-jurisdictional coverage, while boutique firms defend position through notified body relationship depth and therapeutic specialization. Strategic moves center on geographic hub expansion and technology platform integration.
Among integrated service providers, IQVIA Holdings Inc., Charles River Laboratories International, Inc., and WuXi AppTec occupy distinct positioning archetypes. IQVIA exemplifies the data-integrated model leveraging clinical and regulatory infrastructure for multi-year engagements. Charles River represents preclinical-to-registration continuity specialists. WuXi AppTec anchors geographic density advantages for Asia-origin manufacturers. These three illustrate how scale, specialization, and regional presence segment competitive terrain.
| Leading Market Players |
|---|
| ICON plc |
| Labcorp (Laboratory Corporation of America Holdings) |
| IQVIA Holdings Inc. |
| SGS SA |
| Intertek Group plc |
| Charles River Laboratories International, Inc. |
| WuXi AppTec |
| Eurofins Scientific |
| PAREXEL International Corporation |
| Others |
Supply & Pricing Matrix
Outsourced regulatory expertise anchors both supply positioning and pricing power across the IVD compliance services landscape. Captive regulatory teams at large diagnostic manufacturers in Germany and the United States create tiered demand structures, with project-based engagements commanding premium rates over retainer arrangements.
Pricing Analysis
Margin tightening in submission-ready documentation services reflects specialized biostatistician scarcity and 15-20% annual fee escalation at top-tier consultancies. Project-based pricing dominates among mid-tier IVD manufacturers, while retainer structures prevail for multi-jurisdictional portfolio management. Price differentiation hinges on notified body relationship depth and algorithm validation specialization. Biotechnology sponsors in Boston-Cambridge and San Francisco Bay Area clusters demonstrate lowest price sensitivity, prioritizing regulatory pathway certainty over cost minimization.
Supply Chain Analysis
Dual-sourcing requirements for EU IVDR technical documentation mandate qualification of multiple notified body liaison partners. Supply concentrates in Germany, the United States, and China, with Munich and Frankfurt hosting headquarters of BSI Group, TÜV SÜD Product Service GmbH, and DEKRA Testing and Certification GmbH. Raw material inputs draw from clinical evidence packages, performance evaluation reports, and risk management files. Single-source vulnerability permeates the notified body oligopoly controlling over 70% of IVDR designation capacity. Distribution runs through direct manufacturer relationships and disintermediated boutique consultancy engagements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory technology platforms are displacing legacy manual documentation preparation, compressing review cycles while elevating strategic pathway design value.
For Market Incumbents: Lock in multi-year engagements across molecular diagnostics portfolios through integrated clinical and regulatory data infrastructure. Deepen notified body relationship management capabilities to defend against boutique specialist competition. Expand algorithm validation and predetermined change control plan services as FDA software-as-medical-device guidance matures. For New Entrants and Emerging Players: Enter via post-market surveillance unbundling, where vigilance reporting and periodic safety update preparation remain underpenetrated with 40-50% margin profiles. Target biotechnology companies in San Francisco Bay Area and Boston-Cambridge corridors seeking specialized IVD regulatory depth. Pursue direct procurement relationships disintermediated from full-service CRO contracts. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated clinical research organizations seeking regulatory depth augmentation. Long-term viability favors boutiques with dual FDA-PMDA expertise and AI/ML algorithm validation specialization. Monitor FDA draft guidance finalization on artificial intelligence-enabled device transparency as inflection indicator for algorithm-centric regulatory service demand.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Liaison Expansion | BSI Group and TÜV SÜD capacity constraints create premium positioning for relationship managers. |
| Regulatory Technology Platform Integration | Machine learning document preparation absorbs junior associate tasks, forcing strategic repositioning. |
| Dual FDA-PMDA Expertise Development | QMS ordinance convergence enables synchronized US-Japan registration for molecular diagnostics. |
| AI/ML Algorithm Validation Specialization | FDA emerging guidance on software-as-medical-device creates white space for technical specialists. |
| Post-Market Surveillance Service Unbundling | Vigilance reporting margins exceed submission work, attracting boutique consultancy entrants. |
Research Methodology
Document review covered FDA 510(k) and PMA submission databases, EU IVDR technical file registries, and notified body designation records, complemented by interviews with regulatory affairs directors, quality system managers, and health authority liaison specialists. Secondary sources included EMA implementation guidance, PMDA QMS ordinances, and ISO 13485 certification body reports. Bottom-up service demand modeling and top-down market sizing triangulated volume estimates.
Cross-referencing historical regulatory submission volume patterns against expert panel input shaped the analytical framework. Segmentation dimensions encompassed service type, end user sophistication, technology complexity, and engagement structure. CAGRs were derived from trajectory analysis across the projection horizon, incorporating IVDR transition timeline compression and companion diagnostic co-development pipeline expansion as industry-specific inputs.
Revisions become necessary when notified body designation expansions, FDA guidance finalization on AI-enabled algorithms, or large manufacturer in-sourcing decisions materialize. Deviation in EU IVDR enforcement intensity or health authority inspection cadence would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Genetic Toxicology Testing Market
Testing Services
Faecal Calprotectin Testing Market
Testing Services
Rapid Coagulation Testing Market
Testing Services
Asia-Pacific Hereditary Cancer Testing Market
Testing Services
Global Sleep Testing Services Market
Testing Services
Zika Virus Testing Market
Testing Services
Home Care Testing Market
Testing Services
Global Terminal Sterilization Services Market
Testing Services
Breath Biopsy Testing Market
Testing Services
Warfarin Sensitivity Test Market
Testing Services
Medical Device Testing, Inspection, and Certification Market
Testing Services
Global Virology Testing Market
Testing Services
Global Newborn Screening Market
Testing Services
Monkeypox Testing Market
Testing Services
US Pharmaceutical Sterility Testing Market
Testing Services
Global Mycoplasma Testing Market