
 Point of Care Testing Market | 2026-2036
Point of Care Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Point of Care Testing Market Analysis
The Point of Care Testing Market is pivoting on a widening performance gap between premium molecular diagnostic platforms and commodity rapid strip tests. Abbott Laboratories leverages vertically integrated biosensor manufacturing to sustain cost advantages in glucose monitoring. Siemens Healthineers anchors its position through embedded assay menus on compact hematology systems. Danaher Corporation differentiates via microfluidic cartridge architectures that compress workflow steps for urgent care operators.
Point of care testing encompasses diagnostic assays performed at or near the patient site, typically delivering results within 5–30 minutes using portable or benchtop devices with sample volumes under 500 microliters. These systems eliminate central laboratory logistics, enabling clinical decisions during a single encounter. Immunoassay technology dominates current installed bases due to established reliability in cardiac marker and infectious disease panels. Molecular diagnostics represents the fastest-expanding technology segment as PCR-miniaturization and isothermal amplification methods penetrate outpatient settings. Home care end users command premium pricing for connected devices with cloud-based result transmission, while hospital point-of-care remains the largest volume channel.
FDA CLIA waiver classifications and EPA disposal standards for infectious test consumables shape product design requirements and channel eligibility in the United States. ISO 15189 and IEC 61010-1 standards govern analytical validation and electrical safety for devices sold across multiple jurisdictions. Stakeholders must weigh regulatory clearance timelines against assay menu breadth when allocating R&D budgets across platform generations.
Market Dynamics
The Point of Care Testing Market is being restructured by the convergence of CLIA-waived molecular platforms and decentralized hospital workflows, compressing the traditional central lab model into bedside decision cycles.
Growth Catalysts
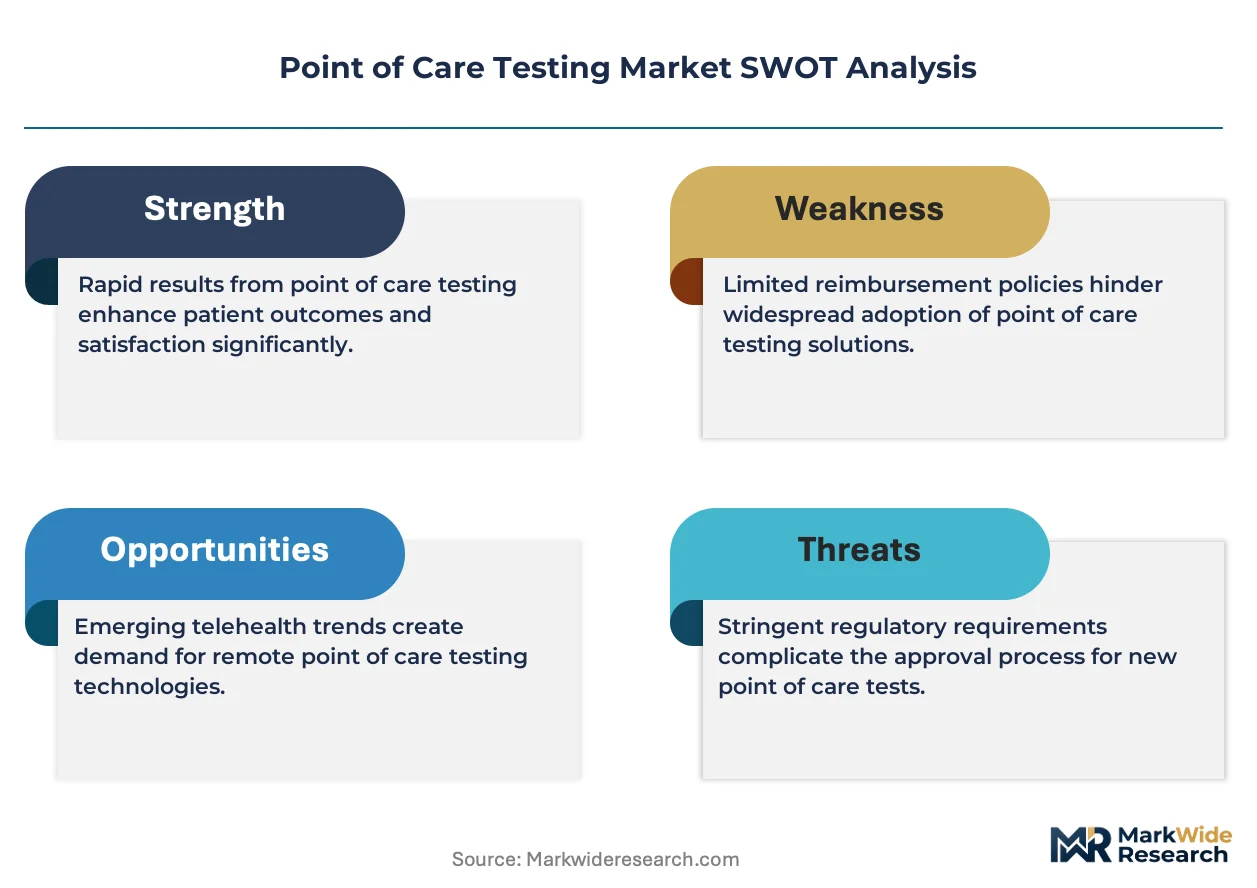
- FDA CLIA Waiver Pathway:Moderate-complexity test reclassification accelerates commercialization timelines for multiplex infectious disease panels, expanding eligible test menus for urgent care operators.
- Hospital Emergency Department Expansion:Bedside diagnostic workflows reduce patient length-of-stay metrics, driving capital allocation toward portable hematology and immunoassay systems.
- Isothermal Amplification Miniaturization:Loop-mediated amplification and recombinase polymerase amplification methods enable PCR-equivalent sensitivity without thermal cycling hardware, penetrating resource-limited outpatient settings.
Market Restraints
- Reagent Supply Concentration:Polymerase and fluorescent probe manufacturing clusters in Germany and South Korea create single-source vulnerabilities for cartridge-based molecular platforms.
- Disposable Cost Structure:Microfluidic cartridge production requires precision injection molding and surface chemistry functionalization, locking per-test costs above central lab economics for high-volume screening.
- EPA Infectious Waste Disposal Standards:Blood-borne pathogen test consumables trigger regulated medical waste streams, adding logistics overhead and compliance liability for point-of-care operators.
Strategic Opportunities
- Home Care Connectivity Integration:Cloud-based result transmission to electronic health records creates recurring revenue models for glucose and coagulation monitoring devices in Medicare-eligible populations.
- Antimicrobial Stewardship Mandates:Joint Commission requirements for rapid pathogen identification in hospital-acquired infection protocols expand addressable demand for multiplex respiratory panels.
- Retail Clinic Channel Penetration:MinuteClinic and similar walk-in formats in the United States adopt waived streptococcal and influenza tests to reduce physician consultation bottlenecks during peak respiratory seasons.
Industry Challenges
- Multiplex Assay Validation Complexity:Cross-reactivity testing for respiratory pathogen panels extends FDA 510(k) review timelines, delaying product launches against seasonal demand windows.
- Legacy LIS Integration Friction:Hospital information systems require HL7 interface customization for each point-of-care device model, inflating IT deployment costs and support overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Point of Care Testing Market |
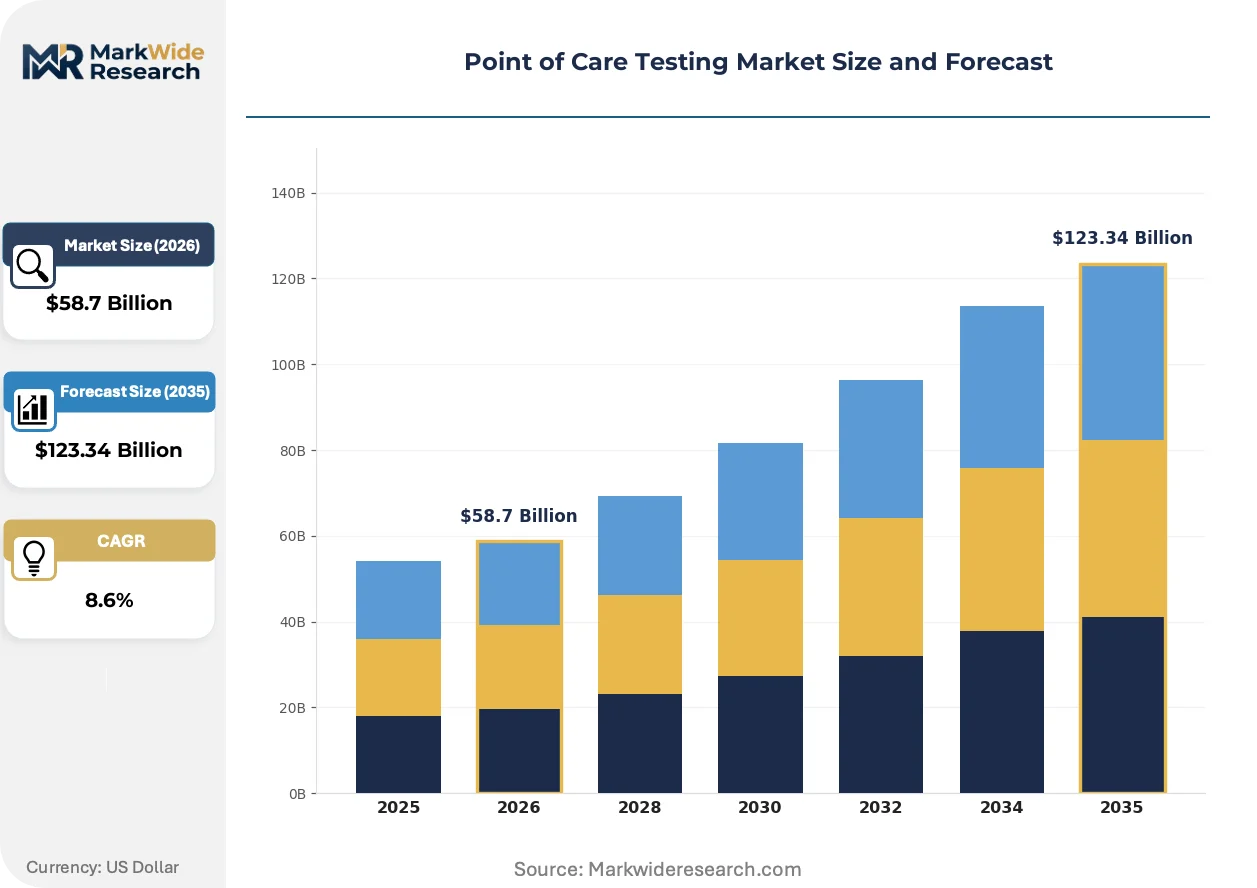
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $123.34 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glucose Meters, Rapid Tests, Hematology Analyzers, Coagulation Analyzers Technology: Immunoassays, Molecular Diagnostics, Microfluidics, Optical Detection End User: Hospitals, Urgent Care Centers, Home Care, Laboratories Application: Infectious Disease Testing, Cardiac Markers, Clinical Chemistry, Blood Gas Analysis |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd., Siemens Healthineers AG, Danaher Corporation, bioMérieux, QIAGEN N.V., Becton Dickinson, Thermo Fisher Scientific Inc., QuidelOrtho Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Point of Care Testing Market Emerging Trajectories
Molecular miniaturization and regulatory pathway optimization are collapsing the performance-cost tradeoff that previously separated central laboratory and bedside testing modalities.
Isothermal nucleic acid amplification is overtaking traditional thermal cycler architectures in outpatient infectious disease testing. Urgent care chains and retail clinic networks are adopting these platforms for influenza and respiratory syncytial virus detection within fifteen-minute encounter windows. The technology is overtaking legacy PCR workflows by eliminating power-intensive heating elements and reducing instrument footprint to handheld dimensions.
The FDA's 2023 guidance on dual 510(k)/CLIA waiver submissions streamlines moderate-complexity reclassification for multiplex molecular assays. This policy compresses regulatory review cycles from sequential to parallel pathways, reducing time-to-market for cartridge-based platforms. Hospital point-of-care coordinators in the United States are responding by expanding waived test menus into traditionally send-out categories like sexually transmitted infection screening.
Consolidated procurement by integrated delivery networks is displacing individual hospital purchasing autonomy for point-of-care devices. Health system supply chain executives are mandating standardized platforms across ambulatory, emergency, and inpatient settings to reduce training burden and consumable fragmentation. This concentration is most visible in the United States, where Catholic Health Initiatives and Kaiser Permanente scale have forced manufacturers into enterprise pricing frameworks.
Point of Care Testing Market Segmentation
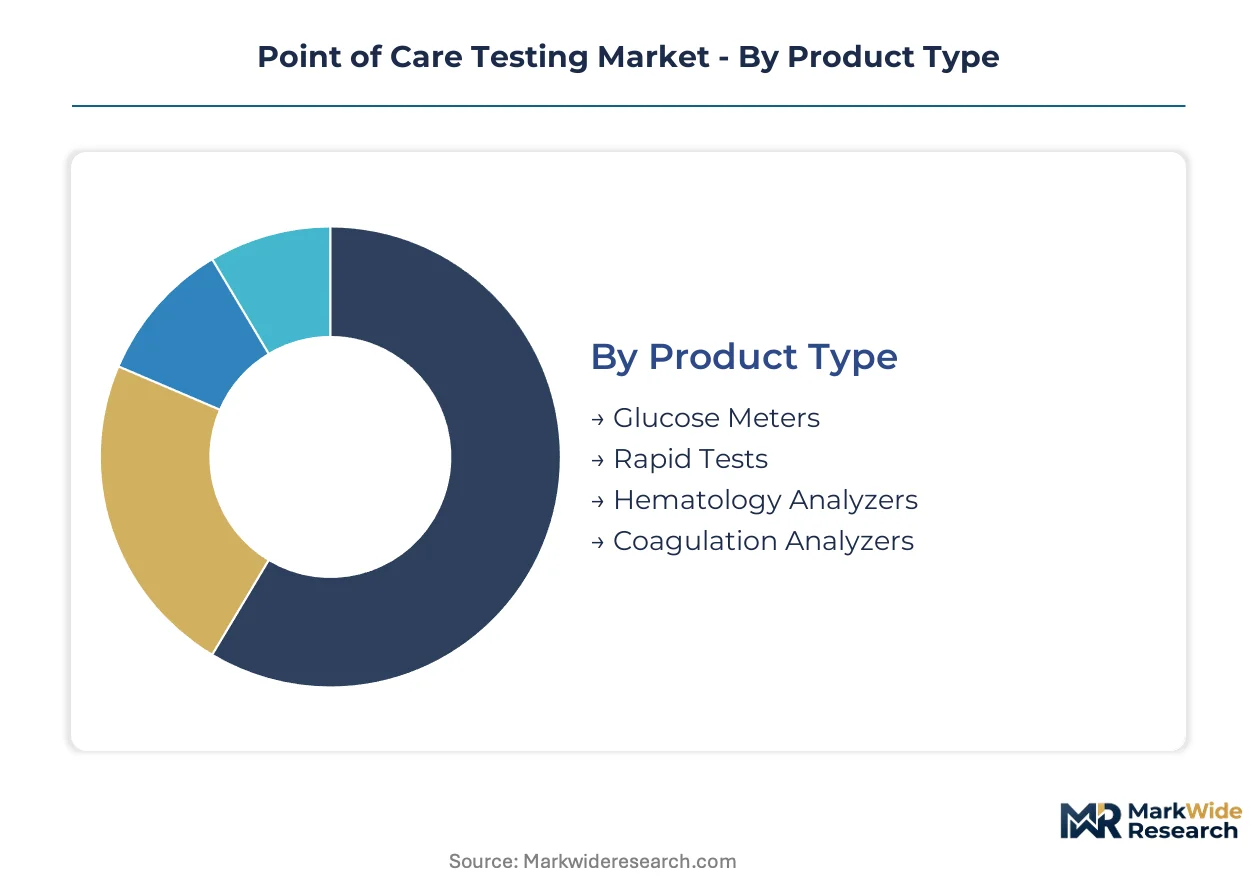
Point of care testing procurement decisions pivot on workflow integration speed, regulatory clearance status, and per-test economics. Segmentation reveals how technology maturity and care setting requirements fragment addressable demand across distinct performance tiers.
Product Type:
Capital allocation intensity separates bedside operators from retail clinic buyers, with instrument footprint and consumable bundling driving contract terms.
- Glucose Meters:Electrochemical biosensor strips deliver capillary whole-blood glucose quantification within five seconds. Home care and hospital bedside units in the United States dominate procurement volumes under Medicare reimbursement codes, though pricing compression from pharmacy chain private labels constrains manufacturer margins.
- Rapid Tests:Lateral flow immunoassay cassettes detect infectious antigens or antibodies without powered instrumentation. Urgent care networks prioritize these for influenza and streptococcal screening during respiratory season surges, accepting lower analytical sensitivity for fifteen-minute turnaround.
- Hematology Analyzers:Compact impedance-based systems enumerate complete blood count parameters from venous or capillary samples.
- Coagulation Analyzers:Cartridge-based prothrombin time and activated clotting time devices serve anticoagulation clinics.
Volume sits with glucose meters; growth tilts toward rapid tests.
Technology:
Assay sensitivity thresholds and regulatory pathway complexity determine which platforms penetrate hospital versus home care channels.
- Immunoassays:Enzyme-linked and fluorescence-based antibody detection dominates cardiac troponin and infectious disease installed bases. Emergency departments in the United States standardize on these for chest pain protocol compliance, with FDA 510(k) clearance timelines averaging shorter than molecular alternatives.
- Molecular Diagnostics:Miniaturized PCR and isothermal amplification achieve pathogen-specific nucleic acid detection at near-central-lab sensitivity. Outpatient clinics and retail health settings adopt these for sexually transmitted infection panels where antibiotic stewardship mandates rapid definitive diagnosis.
- Microfluidics:Laminated polymer cartridges integrate sample preparation, reaction, and detection in disposable formats.
- Optical Detection:Reflectance and turbidimetry methods support coagulation and clinical chemistry readouts.
Installed base concentrates in immunoassays; expansion concentrates in molecular diagnostics.
End User:
Reimbursement structure and patient acuity stratify demand across institutional and consumer-directed settings.
- Hospitals:Emergency departments and intensive care units deploy multiplex platforms for sepsis and respiratory pathogen identification. Joint Commission antimicrobial stewardship requirements in the United States mandate rapid diagnostic capability, embedding point-of-care devices into core infrastructure budgets.
- Home Care:Medicare-eligible patients with diabetes or warfarin therapy drive connected device adoption for remote monitoring. Cloud-integrated result transmission to electronic health records supports recurring revenue models through subscription consumable programs.
- Urgent Care Centers:Walk-in volume operators prioritize waived test menus with minimal operator training.
- Laboratories:Satellite draw stations use compact analyzers for stat testing outside core lab hours.
Revenue scale favors hospitals; connectivity integration favors home care.
Application:
Clinical decision urgency and test menu breadth determine platform selection across diagnostic categories.
- Infectious Disease Testing:Multiplex respiratory panels and rapid streptococcal assays command premium pricing during seasonal demand peaks. Retail clinic networks in the United States adopt these to reduce physician consultation bottlenecks and capture pharmacy adjacency revenue.
- Cardiac Markers:High-sensitivity troponin I and BNP immunoassays enable chest pain protocol compliance within ninety-minute encounter windows. Emergency department accreditation standards in the United States mandate these capabilities, locking in replacement demand for legacy systems.
- Clinical Chemistry:Electrolyte, renal function, and liver enzyme testing supports metabolic monitoring.
- Blood Gas Analysis:Handheld cartridges measure pH, pCO2, and pO2 for ventilator management.
Test volume concentrates in infectious disease; cardiac marker platforms command highest per-test pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Route 128 corridor anchors North American point-of-care diagnostics development, with FDA clearance pipelines clustering around Massachusetts medical device incubators and New Jersey pharmaceutical corridors.
United States
Emergency department expansion and Medicare remote monitoring reimbursement drive installed base growth. FDA CLIA waiver pathways compress commercialization timelines for multiplex respiratory panels. The Research Triangle Park in North Carolina concentrates cartridge manufacturing operations serving urgent care networks.
Germany
Polymerase and fluorescent probe manufacturing clusters sustain reagent supply for European molecular platforms. EMA regulatory alignment with FDA standards accelerates dual-market product launches. The Rhine-Main biotech corridor around Frankfurt hosts precision injection molding facilities for microfluidic consumables.
China
Domestic isothermal amplification platform development targets county hospital tier penetration. NMPA streamlined review pathways for innovative devices reduce registration timelines. The Suzhou Industrial Park concentrates electrochemical biosensor manufacturing for glucose monitoring exports.
Japan
Aging demographics and home care policy subsidies expand connected device adoption among diabetes and anticoagulation patients. PMDA harmonization with FDA quality system standards facilitates parallel submissions. The Kobe biomedical cluster anchors compact hematology analyzer assembly for Asia-Pacific distribution.
India
Public health screening programs and tier-two hospital network expansion create demand for waived rapid tests. CDSCO streamlined medical device rules align with ISO 13485 quality benchmarks. The Hyderabad pharmaceutical corridor hosts contract manufacturing for lateral flow immunoassay cassettes.
Point of Care Testing Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the point-of-care testing landscape. Vertically integrated diagnostics conglomerates with captive biosensor foundries sustain cost advantages in high-volume consumable categories. Three archetypes dominate: diversified med-tech conglomerates with multi-platform portfolios, molecular diagnostic specialists with miniaturized amplification expertise, and rapid test pure-plays with lean manufacturing footprints. Competitive positioning hinges on CLIA waiver portfolio breadth and health system enterprise contract capture.
Among diversified conglomerates, Abbott Laboratories and Siemens Healthineers occupy positions spanning glucose monitoring through molecular platforms. Danaher Corporation exemplifies the precision tools-to-diagnostics trajectory through its life sciences instrumentation heritage. Roche and bioMérieux represent European-centric molecular diagnostic anchoring, with QIAGEN occupying a position in nucleic acid sample preparation workflows that feed downstream point-of-care amplification systems.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd. |
| Siemens Healthineers AG |
| Danaher Corporation |
| bioMérieux |
| QIAGEN N.V. |
| Becton Dickinson |
| Thermo Fisher Scientific Inc. |
| QuidelOrtho Corporation |
| Others |
Supply Flow & Price Mechanics
Precision injection molding for microfluidic cartridges consumes 35-45% of consumable production costs in Germany and South Korea, translating into tiered pricing stratification across hospital procurement networks, retail clinic chains, and home care subscription programs.
Pricing Analysis
Outcome-based pricing anchors hospital point-of-care contracts, with per-test rates tied to turnaround-time guarantees and assay menu breadth. Three-tier pricing structure across premium, standard, and economy levels separates CLIA-waived molecular platforms from rapid strip tests and glucose meters. Cost compression in rapid test categories intensifies because pharmacy chain private labels erode branded manufacturer margins. Retail clinic networks exhibit highest price sensitivity; integrated delivery networks command lowest unit costs through enterprise volume commitments.
Supply Chain Analysis
Polymerase and fluorescent probe manufacturing rests on German specialty chemical producers and South Korean biotech reagent foundries, creating concentrated upstream dependencies for molecular diagnostic cartridges. Surface chemistry functionalization reagents, precision-molded thermoplastics, and electrochemical biosensor membranes feed downstream assembly operations. Single-source vulnerability for isothermal amplification enzymes poses structural risk. Distribution runs through health system GPO contracts, urgent care network purchasing cooperatives, and direct-to-consumer pharmacy retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Isothermal amplification miniaturization is displacing legacy thermal cycler architectures, compressing the performance-cost frontier that previously separated central laboratory and bedside testing modalities.
For Market Incumbents: Extend CLIA waiver portfolio breadth into traditionally send-out categories like sexually transmitted infection panels before emerging molecular specialists capture hospital point-of-care coordinator attention. Deepen backward integration into electrochemical biosensor manufacturing to defend margin position against pharmacy chain private label encroachment in glucose monitoring. Prioritize HL7 interface standardization investments to reduce health system IT deployment friction.
For New Entrants and Emerging Players: Launch via retail clinic channel partnerships targeting waived respiratory panel adoption during seasonal demand peaks. MinuteClinic and similar walk-in formats represent the most penetrable segment, with minimal operator training requirements and pharmacy adjacency revenue capture. Pursue antimicrobial stewardship mandate alignment as the primary go-to-market angle for multiplex sepsis identification platforms.
For Investors and Strategic Acquirers: FDA dual 510(k)/CLIA waiver submission approvals are the leading indicator that regulatory pathway optimization is accelerating commercialization timelines for cartridge-based molecular platforms. The five-to-ten year viability window favors precision tools-to-diagnostics trajectories with microfluidic architecture expertise. Target acquisition archetypes include isothermal amplification specialists with handheld instrument footprints and cloud connectivity integration capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Waiver Portfolio Expansion | FDA reclassification accelerates urgent care network penetration for multiplex infectious disease panels. |
| Microfluidic Cartridge Manufacturing Scale-Up | Precision injection molding investments in the Rhine-Main corridor reduce per-test consumable costs. |
| Cloud Connectivity Integration | Medicare remote monitoring reimbursement supports recurring revenue models for home care devices. |
| Health System Enterprise Contract Capture | Integrated delivery network standardization mandates displace fragmented hospital purchasing autonomy. |
| Isothermal Amplification Platform Development | Loop-mediated methods enable PCR-equivalent sensitivity without thermal cycling hardware in outpatient settings. |
Methodological Framework
Independent corroboration across hospital point-of-care coordinators, urgent care network procurement directors, and biomedical engineers underwrites the qualitative findings on workflow integration priorities. Primary interviews with GPO contracts managers, CLIA compliance officers, and retail clinic operations executives combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up instrument shipment analysis and top-down health system capital expenditure triangulation anchored market sizing.
Rate-of-change decomposition across the analysis window separates volume expansion from pricing trajectory and mix-shift effects. Segmentation dimensions modeled include technology tier, regulatory clearance status, end-user setting, and application category. CAGRs derived from instrument replacement cycles, consumable attach rates, and test menu expansion patterns. Forecast inputs incorporated CLIA waiver approval timelines, antimicrobial stewardship mandate adoption curves, and integrated delivery network consolidation trajectories.
Regulatory clearance delays, reagent supply disruptions, and health system IT integration bottlenecks are the dominant revision risks that could compress or extend projected adoption curves. Forecasts reflect documented assumptions on waiver pathway efficiency and enterprise contract capture rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Ige Allergy Blood Tests Market
Testing Services
Pregnancy Point of Care Testing Market
Testing Services
US Viral Clearance Market
Testing Services
Employer and Workplace Drug Testing Market
Testing Services
Indoor Allergen and Particulate Exposure Assessment Test Devices Market
Testing Services
Global Nitric Oxide Test Market
Testing Services
Global GMP Testing Service Market
Testing Services
Carbapenem-Resistant Enterobacteriaceae Testing Market
Testing Services
Global Electronystagmography Testing Market
Testing Services
Europe Medical Device Testing Market
Testing Services
US Cannabis Testing Market
Testing Services
Home Menopause Testing Market
Testing Services
US at-Home Testing Kits Market
Testing Services
Asia-Pacific Antimicrobial Susceptibility Testing Market
Testing Services
Friability Tester Market
Testing Services
Germany Testing, Inspection and Certification Market