
 Global C-Reactive Protein Testing Market | 2026-2036
Global C-Reactive Protein Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global C-Reactive Protein Testing Market Foresight
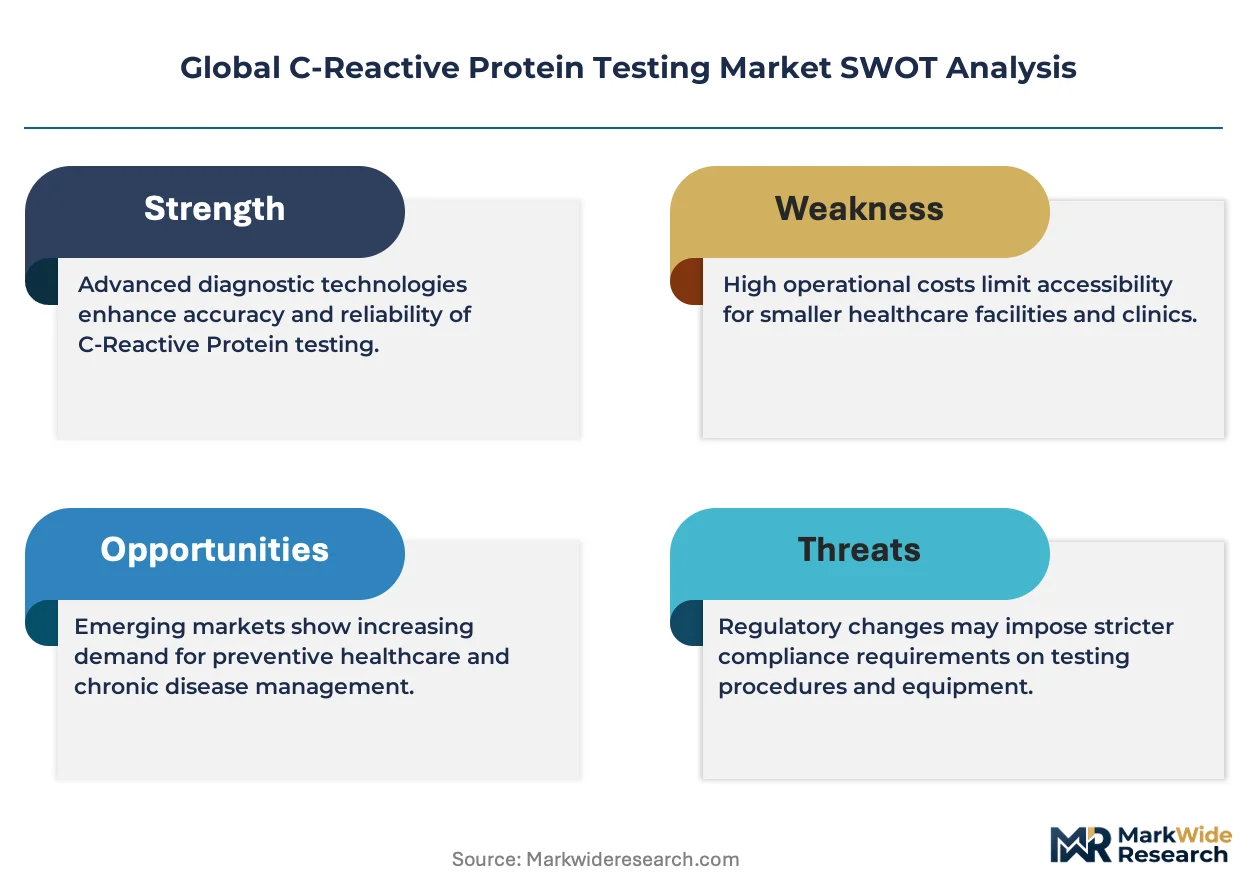
Clinical laboratory technologist shortages across North America and Western Europe is bifurcating the competitive landscape between automated platform vendors and point-of-care specialists. Abbott Laboratories leverages its integrated immunoassay architecture to sustain hospital laboratory contracts across the United States. Siemens Healthineers anchors European demand through its nephelometry and immunoturbidimetric systems installed in centralized labs. Thermo Fisher Scientific differentiates via reagent supply agreements that extend its footprint into academic research institutes.
C-reactive protein testing measures serum CRP concentration, an acute-phase reactant synthesized by hepatocytes with a normal circulating half-life of approximately 19 hours, to detect and monitor systemic inflammation. The assay serves primary commercial purposes in cardiovascular risk stratification, infection screening, and post-operative complication surveillance across clinical and research settings. High-sensitivity CRP dominates cardiovascular risk assessment applications where low-grade inflammation detection drives reagent consumption. Point-of-care CRP tests represent the fastest-expanding product category as decentralized diagnostic protocols displace centralized laboratory workflows. Immunoturbidimetric assay technology occupies the largest installed base while enzyme-linked immunosorbent assay formats retain strong positions in research and specialty reference laboratories.
FDA 510(k) clearance pathways and CLIA complexity classifications shape product development timelines and commercial access for CRP assay manufacturers in the United States. EMA in vitro diagnostic regulation and EU MDR conformity requirements impose clinical evidence standards that filter market entry across European member states. India's CDSCO and BIS quality certification protocols for imported diagnostics create compliance thresholds that favor established multinational suppliers. Stakeholders must monitor evolving point-of-care reimbursement codes and decentralized testing policy shifts to align platform investments with care delivery migration patterns.
Market Dynamics
Point-of-care CRP testing is fragmenting diagnostic workflows as decentralized protocols displace centralized laboratory processing, forcing vendors to choose between high-throughput automation and portable assay platforms.
Growth Catalysts
- EMA diagnostic stewardship guidelines:German hospitals deploy rapid CRP testing to curb antibiotic overprescription, expanding installed base for handheld analyzers in emergency departments.
- High-sensitivity CRP cardiovascular protocols:Cardiology clinics in the United States integrate hs-CRP into routine risk panels, sustaining reagent consumption for low-grade inflammation detection.
- India's urban diagnostic consolidation:CDSCO quality enforcement drives chain laboratories toward standardized immunoassay platforms, concentrating procurement among accredited suppliers.
Market Restraints
- Clinical laboratory technologist shortages:North American and Western European staffing gaps constrain centralized lab throughput, capping reagent volume expansion regardless of installed instrument base.
- EU MDR conformity costs:Enhanced clinical evidence requirements for in vitro diagnostics extend product registration timelines and elevate compliance expenditure for assay manufacturers.
- Reagent supply concentration:Specialist suppliers control critical antibody and calibrator production, creating input vulnerability for platform-agnostic testing vendors.
Strategic Opportunities
- India's tier-2 and tier-3 cities:Underpenetrated diagnostic infrastructure outside Mumbai, Delhi, and Bangalore offers white-space expansion for portable CRP systems as CDSCO extends quality norms nationally.
- Home-based inflammation monitoring:Consumer wellness segments in Japan and South Korea pilot self-testing devices, opening direct-to-patient channels outside institutional procurement.
- Digital connectivity integration:Convergence of lateral flow assays with smartphone-read platforms enables remote result transmission, aligning with telehealth reimbursement expansion in select US markets.
Industry Challenges
- ISO 15189 accreditation timelines:Laboratory quality certification delays in emerging markets extend sales cycles and defer revenue recognition for instrument placements.
- Interoperability with legacy LIS infrastructure:Point-of-care devices require middleware development to integrate with established laboratory information systems, elevating deployment complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global C-Reactive Protein Testing Market |
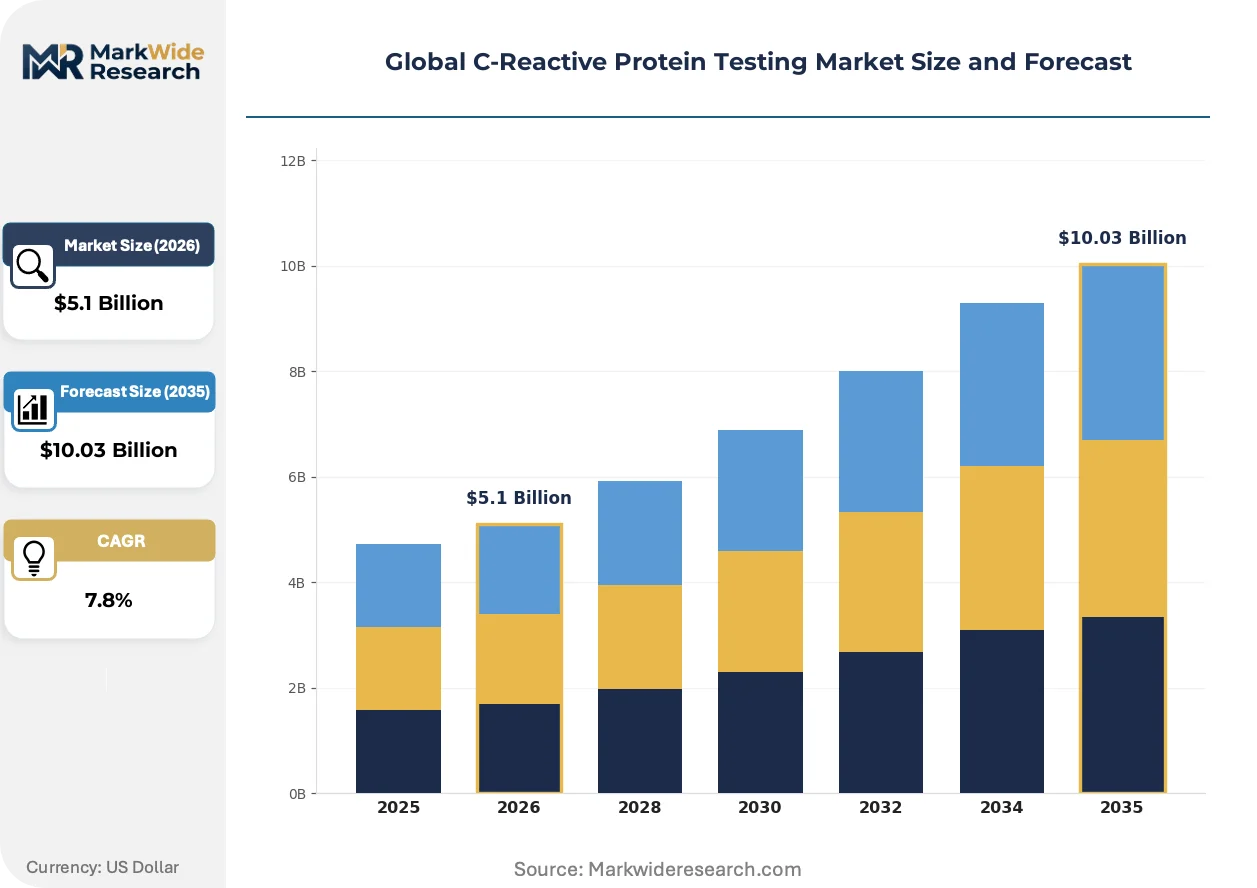
| Market Size in 2026 | $5.1 Billion |
| Market Size in 2035 | $10.03 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Sensitivity CRP, Standard CRP Test, Point of Care CRP Test, Quantitative CRP Test Application: Cardiovascular Risk Assessment, Infectious Disease Diagnosis, Autoimmune Disorder Monitoring, Post-Surgical Inflammation Evaluation End User: Diagnostic Laboratories, Specialty Clinics, Academic Research Institutes, Preventive Healthcare Centers Technology: Immunoturbidimetric Assay, Enzyme-Linked Immunosorbent Assay, Latex Agglutination, Nephelometry |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd, Siemens Healthineers, Thermo Fisher Scientific, Danaher, Quest Diagnostics, Merck KGaA, Randox Laboratories, HORIBA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global C-Reactive Protein Testing Market Shifts & Advancements
Assay miniaturization and connected diagnostics are restructuring how CRP testing reaches patients, compressing the distance between sample collection and clinical decision.
Multiplexed immunoassay platforms is bifurcating the competitive landscape between dedicated CRP analyzers and combination inflammation panels. Rheumatology and oncology clinics in Germany and France adopt these systems to consolidate cytokine and acute-phase protein testing. The technology is bifurcating vendor strategies into specialized single-analyte specialists versus broad-menu platform suppliers.
EU MDR clinical evidence requirements are elevating post-market surveillance obligations for CRP assay manufacturers. European notified bodies demand extended performance studies for high-sensitivity claims, filtering market entry to well-capitalized suppliers. Nephelometry and immunoturbidimetric systems face recertification pressure, accelerating consolidation among IVD platform vendors.
Hospital procurement committees now unbundle instrument placement from exclusive reagent contracts. US health systems negotiate flexible supply agreements permitting multi-vendor sourcing, compressing switching costs for laboratory directors. This pattern concentrates in integrated delivery networks where centralized purchasing overrides individual laboratory preferences.
Global C-Reactive Protein Testing Market Segmentation
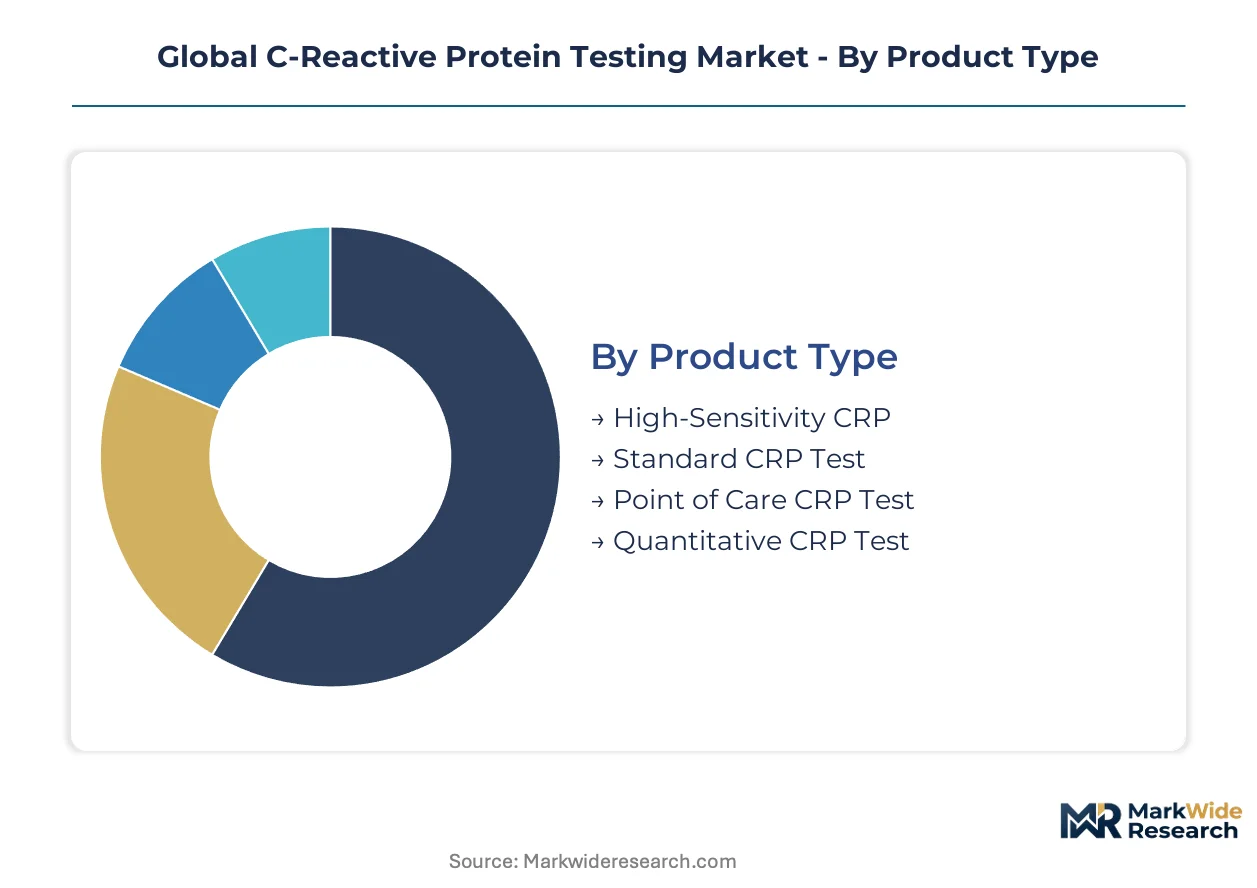
CRP testing segments diverge sharply by clinical setting sensitivity and workflow integration requirements. Product differentiation now hinges on whether assays serve centralized laboratory throughput or decentralized point-of-care speed. Application segmentation tracks how cardiovascular protocols, infection screening, and post-operative surveillance create distinct performance specifications for assay manufacturers.
Product Type:
Substitution pressure from high-sensitivity platforms threatens standard CRP tests in cardiology settings where low-grade inflammation detection commands premium positioning.
- High-Sensitivity CRP:Detects serum concentrations below 1 mg/L through enhanced precision chemistry. Cardiology clinics in the United States integrate hs-CRP into routine risk panels, sustaining reagent consumption as low-grade inflammation protocols expand.
- Point of Care CRP Test:Delivers quantitative results within 3-5 minutes via capillary whole blood sampling. German emergency departments deploy handheld analyzers under EMA diagnostic stewardship guidelines to curb antibiotic overprescription.
- Standard CRP Test:Measures 1-10 mg/L ranges for acute infection screening in primary care settings.
- Quantitative CRP Test:Provides numerical concentration values rather than semi-qualitative thresholds for treatment monitoring.
Standard CRP anchors the volume base while point-of-care CRP gains share at the steepest rate.
Application:
Cost tier stratification separates premium cardiovascular risk assessment from commodity infection screening in procurement negotiations.
- Cardiovascular Risk Assessment:Requires hs-CRP precision below 0.5 mg/L for metabolic syndrome stratification. United States health systems bundle these assays into preventive care contracts with integrated delivery networks.
- Infectious Disease Diagnosis:Depends on rapid turnaround for antibiotic stewardship decisions in acute settings. Indian urban diagnostic chains concentrate procurement here as CDSCO tightens quality norms for imported immunoassay kits.
- Autoimmune Disorder Monitoring:Tracks inflammatory flare patterns in rheumatology and lupus management protocols.
- Post-Surgical Inflammation Evaluation:Surveys complication risk in orthopedic and cardiac procedure recovery pathways.
Infectious disease diagnosis generates the highest test frequency while cardiovascular risk assessment commands the steepest price premium per reportable result.
End User:
Customer type fragmentation splits procurement between institutional laboratory contracts and decentralized clinic purchasing authority.
- Diagnostic Laboratories:Process high-volume batch testing through automated immunoturbidimetric platforms. North American staffing shortages constrain throughput expansion regardless of installed instrument base.
- Specialty Clinics:Demand rapid turnaround for same-day clinical decisions in cardiology and rheumatology practices. German and French rheumatology clinics adopt multiplexed platforms to consolidate cytokine and acute-phase protein testing.
- Academic Research Institutes:Drive reagent consumption for longitudinal inflammation studies and biomarker validation protocols.
- Preventive Healthcare Centers:Screen asymptomatic populations for cardiovascular risk in Japan and South Korea wellness programs.
Diagnostic laboratories anchor the volume base while specialty clinics gain share at the steepest rate.
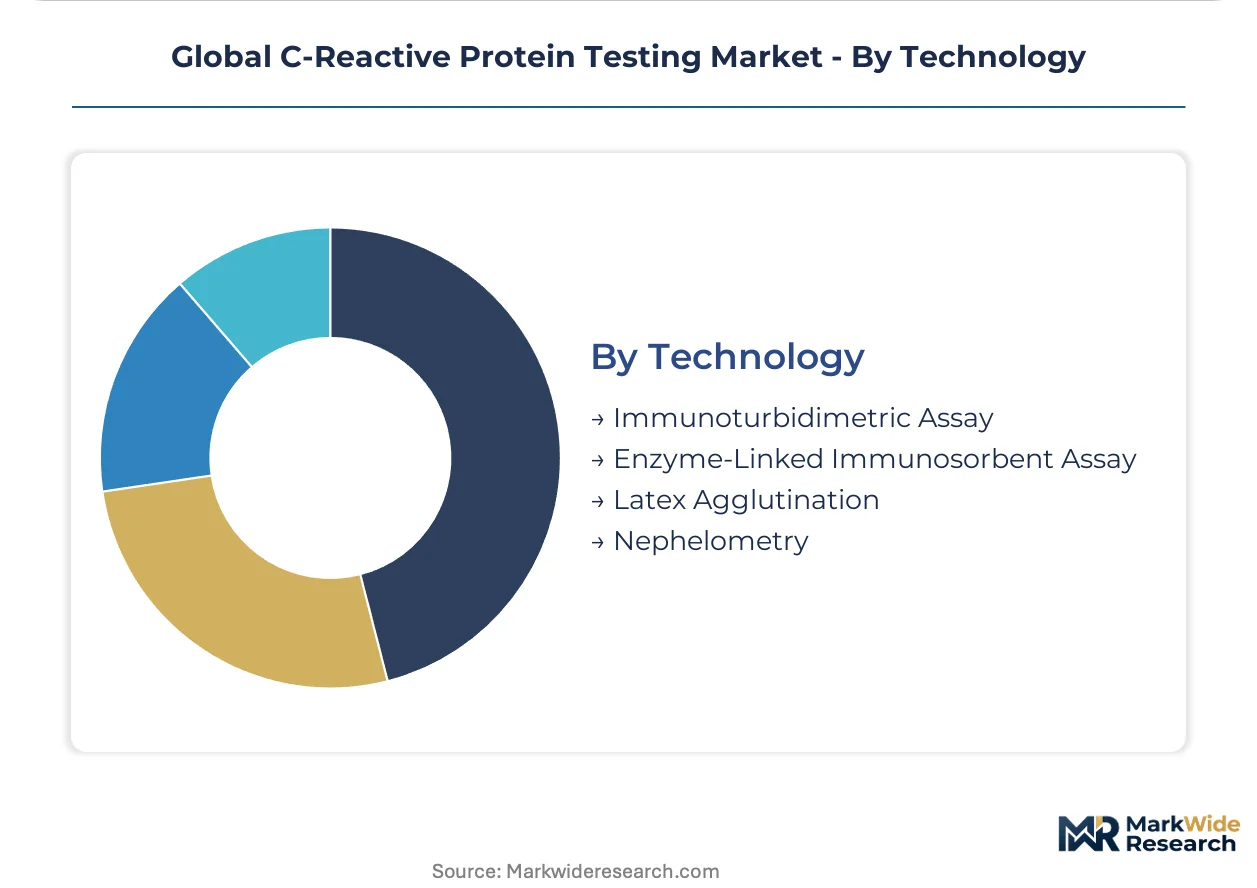
Technology:
Maturity curves separate established nephelometry installations from emerging smartphone-read lateral flow formats in platform replacement cycles.
- Immunoturbidimetric Assay:Dominates centralized laboratory installations through compatibility with high-throughput clinical chemistry analyzers. Siemens Healthineers anchors European demand through installed nephelometry and immunoturbidimetric systems.
- Enzyme-Linked Immunosorbent Assay:Retains strong positions in research and specialty reference laboratories requiring manual workflow flexibility. Academic institutes in the United States sustain reagent agreements through extended supply contracts.
- Latex Agglutination:Serves resource-limited settings with visual endpoint detection and minimal equipment requirements.
- Nephelometry:Provides gold-standard precision for high-sensitivity cardiovascular applications in accredited reference laboratories.
Immunoturbidimetric assay anchors the volume base while latex agglutination gains share at the steepest rate in tier-2 and tier-3 city expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospital procurement commands premium pricing for high-sensitivity CRP platforms while Indian urban diagnostic chains negotiate volume discounts on standardized immunoassay kits, creating a transatlantic pricing asymmetry that shapes vendor portfolio strategies.
United States
Cardiology clinics in the United States integrate hs-CRP into routine risk panels for metabolic syndrome stratification. FDA 510(k) clearance pathways and CLIA complexity classifications shape product development timelines for assay manufacturers. Integrated delivery networks in the Northeast Corridor and California concentrate procurement authority, unbundling instrument placement from exclusive reagent contracts.
Germany
German hospitals and emergency departments deploy rapid CRP testing to curb antibiotic overprescription under EMA diagnostic stewardship guidelines. EU MDR conformity requirements impose clinical evidence standards that filter market entry across European member states. Rheumatology clinics in Berlin and Munich adopt multiplexed platforms to consolidate cytokine and acute-phase protein testing.
India
Urban diagnostic chains in Mumbai, Delhi, and Bangalore concentrate demand as CDSCO tightens quality norms for imported immunoassay kits. BIS quality certification protocols for imported diagnostics create compliance thresholds favoring established multinational suppliers. Tier-2 and tier-3 cities outside major metros offer white-space expansion for portable CRP systems as quality norms extend nationally.
Japan
Preventive healthcare centers in Japan screen asymptomatic populations for cardiovascular risk through wellness programs. PMDA regulatory pathways govern in vitro diagnostic approvals with extended performance study requirements. Consumer wellness segments in Tokyo and Osaka pilot self-testing devices, opening direct-to-patient channels outside institutional procurement.
South Korea
Specialty clinics in Seoul Capital Area demand rapid turnaround for same-day clinical decisions in cardiology practices. MFDS quality standards align with international ISO 15189 accreditation protocols for laboratory certification. Digital connectivity integration converges lateral flow assays with smartphone-read platforms in Busan-Ulsan medical device clusters.
Global C-Reactive Protein Testing Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the CRP testing ecosystem, producing a bifurcated structure where automated platform vendors compete with point-of-care specialists. The market consolidates around three strategic archetypes: integrated diagnostics conglomerates with full immunoassay architectures, specialized point-of-care manufacturers with handheld analyzer portfolios, and reagent-focused suppliers with extended supply agreements into academic channels. Dominant competitive moves include strategic partnerships between platform vendors and reagent specialists, plus geographic expansion into underpenetrated tier-2 and tier-3 city markets.
Among integrated diagnostics conglomerates, Abbott Laboratories and Siemens Healthineers occupy positions exemplifying the automated platform archetype, while Thermo Fisher Scientific represents the reagent supply agreement model extending into academic research institutes. F. Hoffmann-La Roche Ltd anchors the high-sensitivity cardiovascular application segment. These entities collectively illustrate how vendor strategies diverge between specialized single-analyte positioning and broad-menu platform supply.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Siemens Healthineers |
| Thermo Fisher Scientific |
| Danaher |
| Quest Diagnostics |
| Merck KGaA |
| Randox Laboratories |
| HORIBA |
| Others |
Supply & Pricing Matrix
Batch-scale economies in immunoturbidimetric reagent manufacturing concentrate cost advantages among high-throughput platform vendors, compressing price floors for point-of-care specialists while elevating switching costs for hospital laboratory contracts. This scale dynamic reinforces supply concentration around established multinational suppliers who anchor antibody and calibrator production, filtering procurement authority toward integrated delivery networks and diagnostic chain consolidators.
Pricing Analysis
The customization-premium spread separates configured-to-order high-sensitivity cardiovascular platforms from standard infectious-disease screening assays. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with FDA-cleared hs-CRP systems commanding premium positioning against CDSCO-accredited standard kits. Pricing pressure stems from unbundled instrument-reagent contracts that compress switching costs for laboratory directors. Diagnostic laboratories exhibit highest price sensitivity due to batch-volume procurement leverage, while specialty clinics tolerate premium tiers for rapid turnaround specifications.
Supply Chain Analysis
Just-in-time reagent replenishment dominates centralized laboratory workflows, whereas strategic stockpiling of lateral flow components supports point-of-care expansion in tier-2 and tier-3 city markets. Antibody production concentrates in the United States, Germany, and China, with specialized calibrator manufacturing anchored in Switzerland and Japan. Critical input dependencies include monoclonal antibody supply, synthetic peptide standards, and nitrocellulose membrane substrates. Single-source vulnerability in recombinant antibody production elevates supply risk for platform-agnostic vendors. Distribution runs through diagnostic distributor networks and direct hospital system contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Point-of-care CRP testing represents a high-growth disruption as decentralized protocols displace centralized workflows, with EMA diagnostic stewardship guidelines and FDA 510(k) clearance pathways serving as regulatory inflection points that accelerate procurement migration.
For Market Incumbents: Secure reagent supply agreements with academic research institutes to defend against point-of-care substitution in longitudinal inflammation studies. Extend backward integration into antibody production to reduce single-source vulnerability from specialist suppliers. Anchor hospital laboratory contracts through integrated immunoassay architectures that elevate switching costs for procurement committees. For New Entrants and Emerging Players: Lead with portable CRP systems targeting India's tier-2 and tier-3 cities where CDSCO quality norm extension creates white-space expansion. Penetrate Japanese consumer wellness segments through smartphone-read lateral flow platforms for home-based inflammation monitoring. Pursue direct-to-patient channels outside institutional procurement as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors reagent-focused suppliers with extended supply agreements into academic channels over dedicated single-analyte specialists facing multiplexed platform substitution. Long-term viability hinges on convergence with digital connectivity and telehealth reimbursement expansion. Target acquisition archetypes include point-of-care manufacturers with handheld analyzer portfolios and smartphone-read platform capabilities. The signal to watch is EU MDR recertification timelines for nephelometry systems as consolidation accelerates among IVD platform vendors.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates commercial access for high-sensitivity CRP cardiovascular applications in United States health systems. |
| CE Marking Pathway | Filters market entry to well-capitalized suppliers under EU MDR clinical evidence requirements across member states. |
| Hospital System Partnership | Secures instrument placement contracts with integrated delivery networks unbundling exclusive reagent agreements. |
| Software Companion Development | Enables smartphone-read lateral flow integration with telehealth reimbursement expansion in select US markets. |
| Reimbursement Strategy | Aligns point-of-care CRP testing codes with decentralized diagnostic protocol migration patterns. |
Research Methodology
Operator-level perspectives from hospital laboratory directors, clinical biochemists, diagnostic procurement managers, and point-of-care device engineers anchored the qualitative base for this analysis. Primary interviews combined with secondary validation from FDA 510(k) filings, EMA submission databases, CDSCO import registration records, and hospital procurement contract disclosures. Bottom-up instrument placement modeling and top-down reagent consumption estimates triangulated market sizing across the projection horizon.
Sensitivity analysis tested forecast robustness against alternative scenarios for laboratory technologist shortage persistence and point-of-care reimbursement expansion velocity. Segmentation dimensions modeled include product type sensitivity tiers, application cost stratification, end-user procurement authority, and technology platform maturity curves. CAGRs derived from reagent consumption trajectories and installed base replacement cycles, with cardiovascular protocol adoption rates and infection screening test frequency serving as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained EMA diagnostic stewardship enforcement or accelerated CDSCO quality norm extension would require recalibration. Forecasts reflect documented assumptions regarding decentralized workflow migration and multiplexed platform substitution thresholds. Revision becomes warranted when EU MDR recertification delays or reagent supply concentration disruptions cross materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Legionella Testing Market
Testing Services
Carbapenem-Resistant Enterobacteriaceae Testing Market
Testing Services
Fertility Testing Market
Testing Services
Allergy Tester Market
Testing Services
Europe Newborn Screening Market
Testing Services
Aerospace and Life Science Testing Certification Market
Testing Services
Global Multiplex Assays Market
Testing Services
Antibiotic Residue Test Kits Market
Testing Services
Urodynamic Testing Market
Testing Services
Host Cell Protein Testing Market
Testing Services
At-Home Testing Market
Testing Services
Aerospace and Life Sciences TIC Market
Testing Services
Europe Endotoxin and Pyrogen Testing Market
Testing Services
Large Molecule Bioanalytical Testing Services Market
Testing Services
Warfarin Sensitivity Test Market
Testing Services
Asia Pacific Pregnancy and Ovulation Testing Market