
 Italy Nuclear Imaging Market | 2026-2036
Italy Nuclear Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Nuclear Imaging Market Foresight
Aftermarket service revenue is tilting toward hybrid system maintenance contracts as Italian hospitals extend equipment lifecycles. Siemens Healthineers anchors this shift through its dense field engineering network across the peninsula. Bracco Group leverages its domestic radiopharmaceutical production to sustain recurring revenue streams. GE Healthcare competes by positioning integrated service agreements alongside its imaging hardware deployments.
Nuclear imaging encompasses diagnostic techniques utilizing radiopharmaceuticals to visualize physiological function, with PET systems detecting positron-emitting isotopes at spatial resolutions below 5 mm for metabolic mapping. Hybrid systems dominate capital expenditure flows as Italian providers prioritize PET-CT and PET-MRI platforms that merge functional and anatomical data. Oncology applications absorb the largest share of procedure volume, while cardiology SPECT maintains stable utilization in regional hospitals. Detector technologies represent the fastest-evolving segment, with silicon photomultiplier arrays displacing conventional photomultiplier tubes in premium installations.
AIFA governs radiopharmaceutical reimbursement and clinical indication approvals, while INAIL and regional health authorities enforce radiation safety protocols that shape procurement specifications. CE marking under the EU MDR extends conformity requirements to software-driven imaging platforms, tightening market access for non-compliant vendors. Stakeholders must monitor AIFA's periodic revision of nuclear medicine tariff schedules, as reimbursement shifts directly alter hospital investment timelines.
Market Dynamics
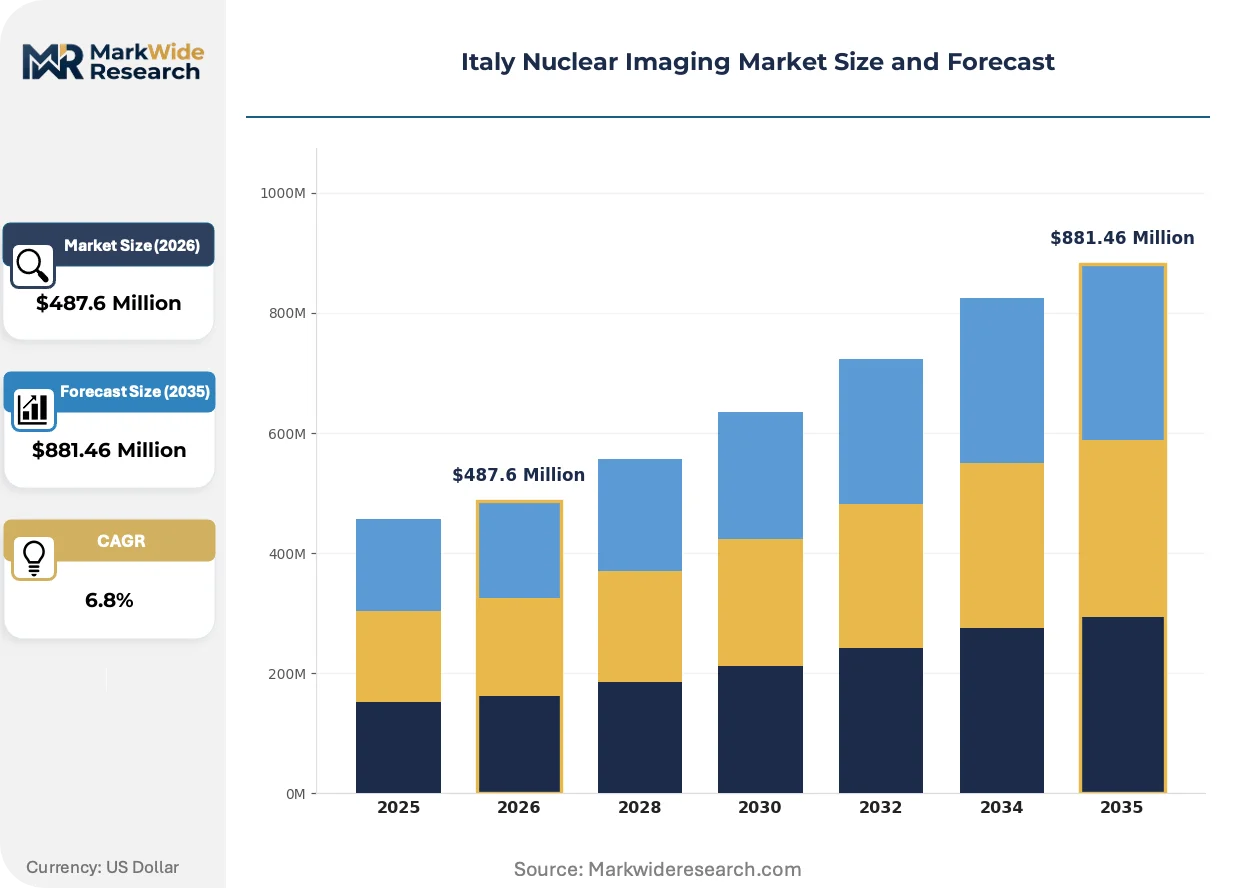
Italian hospital procurement committees are prioritizing hybrid PET-CT platforms over standalone systems, compressing capital cycles as regional health authorities consolidate imaging networks into metropolitan hubs. This equipment transition is restructuring vendor relationships and radiopharmaceutical supply chains simultaneously.
Growth Catalysts
- AIFA Reimbursement Expansion:The Italian Medicines Agency's periodic tariff revisions for FDG-PET procedures are accelerating hospital adoption of metabolic imaging for oncology staging across Lombardy's integrated care networks.
- Silicon Photomultiplier Arrays:Solid-state detector technology is improving spatial resolution below 4 mm while reducing scanner footprint, enabling installation in mid-sized regional hospitals previously excluded from PET capacity.
- Lombardy Network Consolidation:Metropolitan hospital clusters in Milan and surrounding provinces are centralizing nuclear medicine services, creating procurement volume sufficient to justify premium hybrid system investments.
Market Restraints
- Cyclotron Supply Concentration:Domestic FDG production clusters around northern Italian radiopharmaceutical facilities, exposing hospital networks to geographic supply risk during transport disruptions.
- EU MDR Conformity Costs:CE marking extensions to software-driven imaging platforms under the Medical Device Regulation are extending market access timelines for innovative detector technologies.
- SPECT Substitution Pressure:Cardiac PET perfusion imaging is encroaching on traditional technetium-based SPECT utilization in tertiary centers, stranding existing gamma camera investments.
Strategic Opportunities
- Emilia-Romagna Secondary Clusters:Bologna and Modena hospital networks are expanding PET-CT capacity for neurodegenerative disease protocols, creating procurement white space beyond saturated Lombardy markets.
- PET-MRI Convergence:Integrated platforms combining metabolic PET data with high-field MRI soft-tissue contrast are opening neurology and pediatric oncology applications previously inaccessible to CT-based hybrid systems.
- Regional Tender Aggregation:Veneto's consolidated procurement frameworks for medical devices are streamlining vendor selection processes, reducing transaction costs for multi-site imaging network deployments.
Industry Challenges
- Qualified Medical Physics Shortage:Italian universities are producing insufficient nuclear medicine physicists to staff expanded PET-CT operations across regional hospital networks.
- Legacy PACS Integration:Hybrid system DICOM outputs require reconfiguration of existing picture archiving infrastructure, extending commissioning timelines and delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Nuclear Imaging Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gamma Camera, SPECT, PET, Hybrid Systems Application: Cardiology, Oncology, Neurology, Thyroid Imaging End User: Hospitals, Diagnostic Centers, Research Institutions, Imaging Facilities Technology: Software Solutions, Imaging Techniques, Detector Technologies, Contrast Agents |
| Companies Covered | Fujifilm Holdings Corporation, Bracco Group, GE Healthcare, Bayer AG, Curium, Siemens Healthineers AG, Canon Medical Systems Corporation, Novartis AG (Advanced Accelerator Applications), Koninklijke Philips N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Nuclear Imaging Market Shifts & Advancements
Detector architecture is undergoing generational replacement while Italian reimbursement frameworks accelerate procedure migration toward quantitative metabolic imaging. Procurement centralization is simultaneously reshaping vendor contracting terms and service delivery models.
Silicon photomultiplier arrays are migrating from conventional photomultiplier tubes in premium PET installations. Major university hospitals in Milan and Rome are adopting solid-state detectors for time-of-flight PET systems, drawn by improved energy resolution and magnetic field compatibility. This migration from vacuum-tube technology is compressing the serviceable installed base of legacy detector systems and accelerating obsolescence cycles for maintenance-dependent hardware.
AIFA's periodic revision of nuclear medicine tariff schedules is restructuring hospital investment timelines for radiopharmaceutical-dependent procedures. Reimbursement rate adjustments for FDG-PET oncology indications are directly influencing procurement committee prioritization of metabolic imaging capacity over anatomical modalities. Oncology departments within Lombardy's metropolitan networks are responding by accelerating PET-CT procurement to capture revised tariff yields.
Service contract unbundling is fragmenting traditional vendor-hospital relationships in Italian imaging markets. Procurement committees are separating hardware acquisition from maintenance agreements, soliciting independent service organizations for detector calibration and cyclotron maintenance. This behavioral shift is most visible among Veneto's regional hospital networks, where multi-vendor service aggregation is reducing annual maintenance expenditure through competitive tendering of discrete technical functions.
Italy Nuclear Imaging Market Segmentation
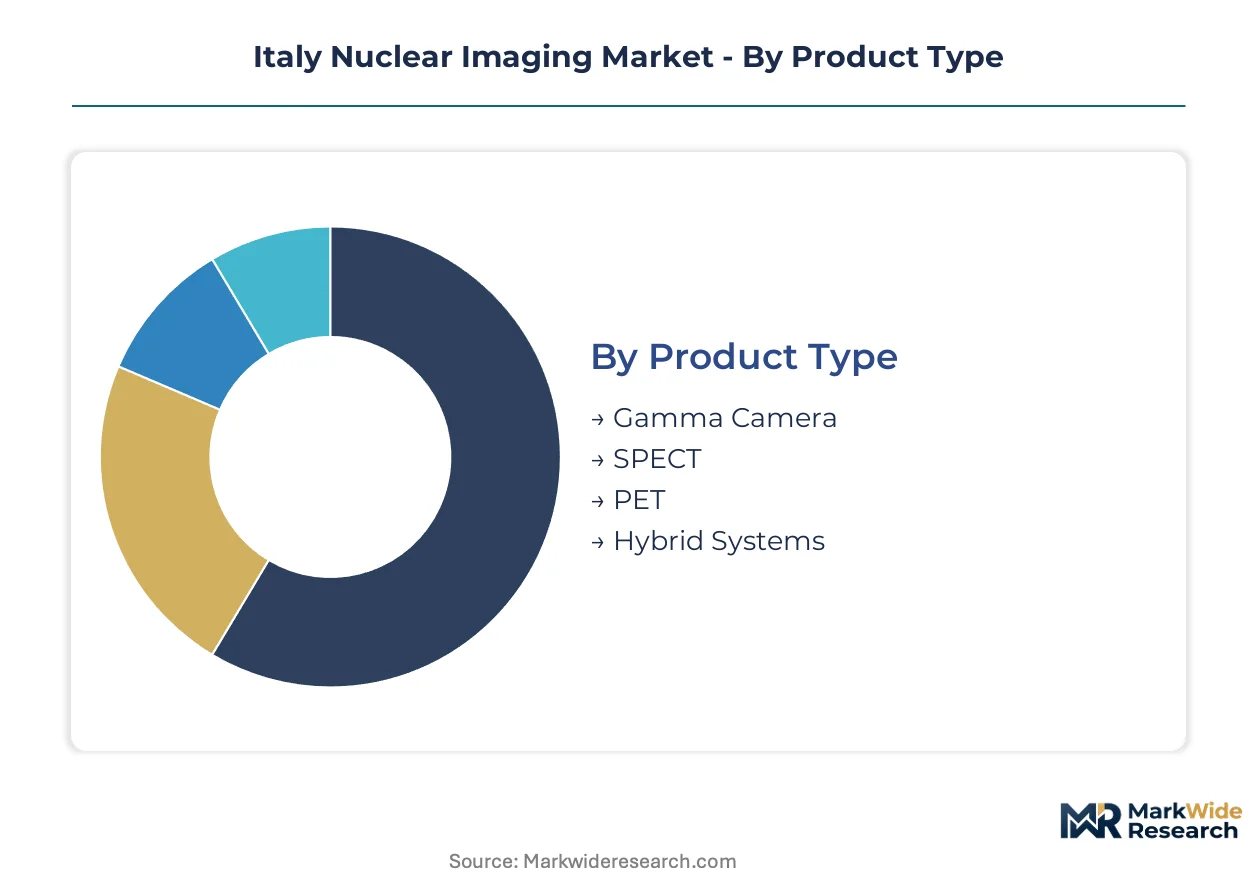
Equipment heterogeneity across Italian nuclear imaging demands differentiated service infrastructure. Vendor profitability depends on matching contract structures to the technical complexity and utilization intensity of each segment.
Product Type:
After-sales service intensity varies dramatically across equipment categories, with hybrid systems commanding multi-year comprehensive contracts while standalone gamma cameras operate on break-fix arrangements.
- Hybrid Systems:PET-CT and PET-MRI platforms integrate metabolic and anatomical imaging modalities. Lombardy's metropolitan hospital networks in Milan concentrate procurement of these capital-intensive units, driven by AIFA reimbursement expansion for FDG-PET oncology staging protocols.
- PET:Positron emission tomography systems detect positron-emitting isotopes at spatial resolutions below 5 mm. Demand clusters in Emilia-Romagna's university hospitals, where neurology and pediatric oncology applications justify dedicated metabolic imaging capacity.
- SPECT:Single photon emission computed tomography remains prevalent in regional cardiology workflows. Stable utilization persists across Veneto's provincial hospital networks despite encroachment from cardiac PET perfusion imaging.
- Gamma Camera:Conventional planar imaging systems serve thyroid and bone scintigraphy procedures. Compact footprint and lower capital requirements sustain deployment in smaller diagnostic centers.
By volume, SPECT leads installed base. By growth pace, Hybrid Systems are climbing the fastest.
Application:
Procedure reimbursement rates determine equipment utilization intensity and replacement cycles across clinical domains.
- Oncology:FDG-PET staging for solid tumors dominates procedure volume in Italian nuclear medicine departments. Milan's integrated cancer centers anchor demand, with AIFA tariff revisions directly influencing scanner procurement timelines.
- Cardiology:Myocardial perfusion imaging sustains SPECT utilization across regional hospital networks. Tertiary centers in Bologna and Rome are transitioning toward rubidium-82 PET perfusion for higher diagnostic accuracy.
- Neurology:Amyloid and tau imaging for neurodegenerative disease protocols is expanding PET-CT capacity in Emilia-Romagna. Academic medical centers drive adoption of specialized radiopharmaceuticals.
- Thyroid Imaging:Iodine-131 scintigraphy and therapy procedures maintain steady demand. Regional endocrinology networks utilize gamma camera systems for diagnostic and therapeutic applications.
Oncology generates highest revenue per procedure. Neurology applications are gaining share fastest among emerging indications.
End User:
Procurement authority concentration shapes vendor contracting strategies and service delivery models.
- Hospitals:Public and private hospital networks consolidate the majority of Italian nuclear imaging capacity. Lombardy's metropolitan clusters centralize PET-CT procurement through regional health authority frameworks.
- Diagnostic Centers:Independent imaging facilities focus on high-throughput cardiology and oncology procedures. Veneto's consolidated tender processes streamline multi-site equipment deployments.
- Research Institutions:University hospitals in Milan and Rome pioneer solid-state detector adoption. Clinical trial activity drives demand for quantitative metabolic imaging capabilities.
- Imaging Facilities:Specialized nuclear medicine centers concentrate radiopharmaceutical production and distribution. Cyclotron-equipped sites in northern Italy anchor FDG supply networks.
Hospitals command largest installed base. Diagnostic Centers show steepest expansion trajectory among outpatient settings.
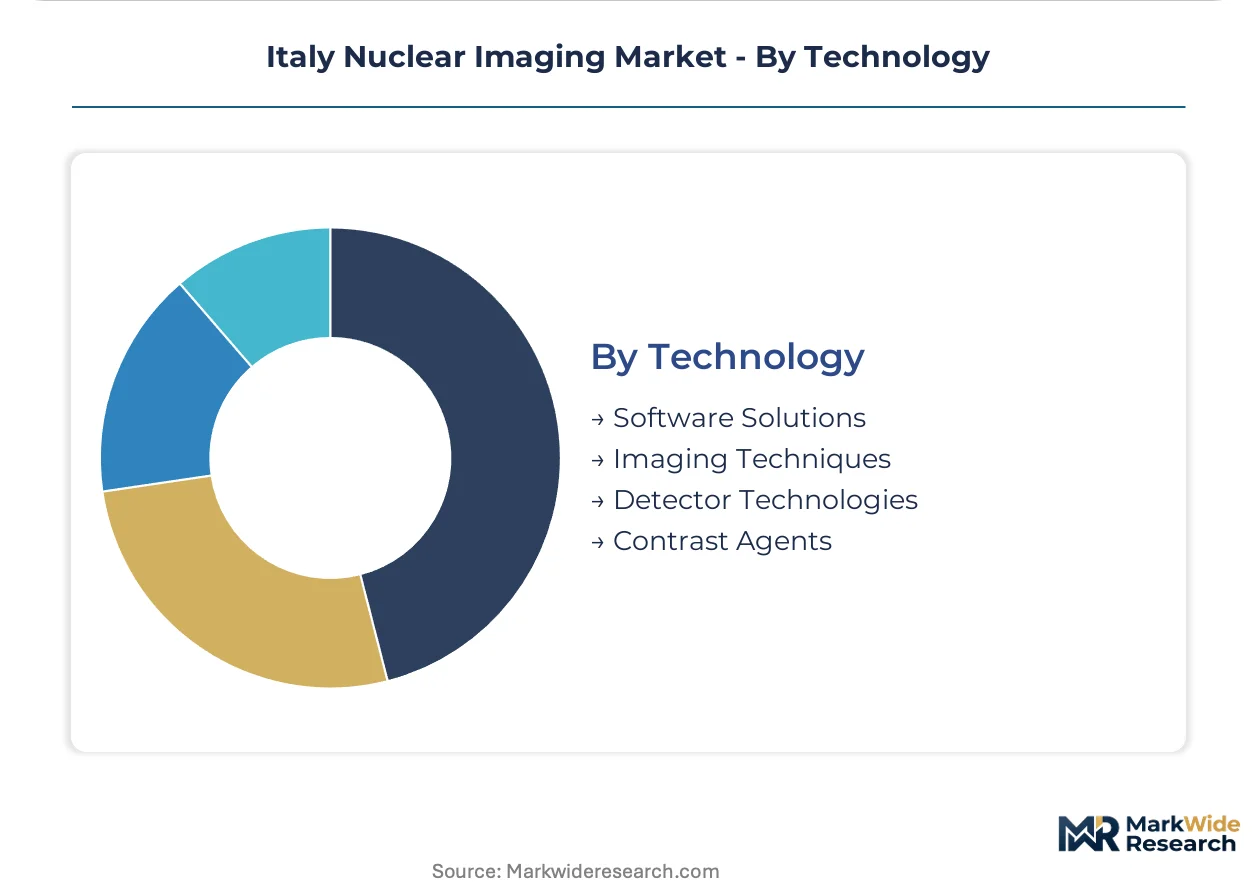
Technology:
Component-level innovation cycles determine upgrade pathways and obsolescence risk across the installed base.
- Detector Technologies:Silicon photomultiplier arrays are displacing conventional photomultiplier tubes in premium installations. Improved energy resolution and magnetic field compatibility enable PET-MRI convergence.
- Imaging Techniques:Time-of-flight PET reconstruction algorithms enhance signal-to-noise ratios. Software-driven advances extend useful life of existing hardware platforms.
- Software Solutions:DICOM-compliant image processing and PACS integration requirements shape procurement specifications. Legacy system compatibility challenges delay commissioning timelines.
- Contrast Agents:Radiopharmaceutical production and distribution networks concentrate around northern Italian cyclotron facilities. FDG supply geography exposes hospital networks to transport disruption risks.
Detector Technologies attract largest R&D investment. Software Solutions are expanding most quickly as vendors unbundle service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in Lombardy exhibit the lowest price elasticity, absorbing premium hybrid system costs through consolidated regional budgets, while Veneto and Emilia-Romagna networks demonstrate higher sensitivity to capital expenditure compression.
Lombardy
Milan's metropolitan hospital networks anchor Italy's PET-CT procurement volume, driven by AIFA reimbursement expansion for FDG-PET oncology staging. The regional health authority's centralized purchasing frameworks compress vendor negotiation cycles. Integrated cancer centers in Monza and Pavia are extending PET-MRI capacity for neuro-oncology applications.
Emilia-Romagna
Bologna and Modena university hospitals are expanding metabolic imaging capacity for amyloid and tau neurodegenerative disease protocols. AIFA tariff revisions for specialized radiopharmaceuticals are accelerating scanner deployment timelines. The region's cyclotron-equipped production facilities in Bologna anchor FDG supply networks for central Italy.
Veneto
Provincial hospital networks in Verona and Padua maintain stable SPECT utilization for cardiology workflows while selectively adopting cardiac PET perfusion imaging. Regional tender aggregation frameworks are streamlining multi-site equipment procurement and reducing transaction costs. Independent service organizations are capturing maintenance contracts through competitive bidding processes.
Piedmont
Turin's university hospital system is pioneering silicon photomultiplier array adoption in time-of-flight PET systems for research-intensive applications. INAIL radiation safety enforcement shapes procurement specifications for detector technologies. The city's imaging facilities are consolidating radiopharmaceutical distribution networks across the Alpine corridor.
Lazio
Rome's academic medical centers concentrate pediatric oncology PET-MRI applications, leveraging high-field MRI soft-tissue contrast for treatment planning. CE marking requirements under EU MDR are extending conformity timelines for software-driven imaging platforms. University hospitals in the capital are driving quantitative metabolic imaging protocol standardization.
Italy Nuclear Imaging Market Competitive Landscape
Capability concentration sits with integrated radiopharmaceutical-producer tier; scale advantage sits with diversified imaging hardware manufacturers. The vendor base separates into three strategic archetypes: domestic radiopharmaceutical specialists with cyclotron infrastructure, multinational hybrid system integrators with dense service networks, and component technology suppliers advancing solid-state detector architectures. Competitive moves center on service contract unbundling and regional tender aggregation partnerships.
Among Italy-anchored radiopharmaceutical producers, Bracco Group exemplifies the integrated domestic specialist archetype through its cyclotron-equipped production footprint. Siemens Healthineers AG and GE Healthcare occupy positions within the multinational system integrator tier, leveraging field engineering density across the peninsula. Koninklijke Philips N.V. represents the diversified imaging technology vector competing through detector innovation and software integration capabilities.
| Leading Market Players |
|---|
| Fujifilm Holdings Corporation |
| Bracco Group |
| GE Healthcare |
| Bayer AG |
| Curium |
| Siemens Healthineers AG |
| Canon Medical Systems Corporation |
| Novartis AG (Advanced Accelerator Applications) |
| Koninklijke Philips N.V. |
| Others |
Supply & Pricing Matrix
The Brenner Pass corridor freight costs cascade through Italian nuclear imaging supply chains, amplifying price spreads between cyclotron-equipped northern hubs and radiopharmaceutical-dependent southern facilities while compressing margins for mid-tier detector suppliers.
Pricing Analysis
After-sales service contracts drive lifetime value capture across Italian nuclear imaging installations. Three-tier pricing structure across premium, standard, and economy levels segments buyers by detector technology sophistication and bundled maintenance scope. Cost compression in economy-tier gamma camera segments is intensifying because independent service organizations are undercutting OEM maintenance rates. Regional hospital networks in Veneto exhibit highest price sensitivity, while Lombardy's metropolitan cancer centers absorb premium hybrid system costs with minimal procurement friction.
Supply Chain Analysis
Upstream fluorine-18 feedstock production centers on Belgium, the Netherlands, and northern Italian cyclotron clusters. Detector crystal arrays draw from Chinese rare earth processing and Japanese silicon foundries. Single-source vulnerability concentrates in lutetium oxyorthosilicate scintillator supply from Ukrainian raw material streams. Distribution runs through radiopharmaceutical production hubs in Bologna and Milan before last-mile cold-chain delivery to regional hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italian nuclear imaging is cycling through post-pandemic procedure volume recovery as AIFA tariff revisions restore hospital capital expenditure capacity for metabolic imaging platforms.
For Market Incumbents: Entrench service contract density across Lombardy's consolidated procurement frameworks before independent service organizations capture detector calibration revenue. Counter silicon photomultiplier substitution pressure by extending legacy photomultiplier tube maintenance availability for provincial SPECT installations. Deepen backward integration into cyclotron maintenance capabilities to defend against Bracco Group's radiopharmaceutical-service bundling. For New Entrants and Emerging Players: Pursue Emilia-Romagna's neurodegenerative disease imaging white space where amyloid and tau radiopharmaceutical protocols outpace installed PET-CT capacity. Target Veneto's tender-aggregated procurement frameworks with unbundled detector calibration services priced below OEM benchmarks. Lead with software-driven quantitative metabolic imaging analytics to bypass hardware incumbent relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational imaging conglomerates seeking to divest non-core cyclotron maintenance operations or legacy gamma camera service divisions. Long-term viability hinges on exposure to hybrid system installed base growth rather than stranded SPECT assets. Monitor AIFA's periodic tariff schedule revisions as the primary inflection signal for hospital capital commitment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photomultiplier Migration | Solid-state detector adoption at Milan's university hospitals accelerates obsolescence of vacuum-tube PET systems. |
| Regional Tender Aggregation | Veneto's consolidated procurement frameworks reduce transaction costs for multi-site hybrid network deployments. |
| Reimbursement Strategy Alignment | AIFA tariff revision timing directly shapes hospital PET-CT procurement committee prioritization schedules. |
| Independent Service Organization Capture | Unbundled maintenance contracts fragment traditional vendor-hospital relationships across provincial networks. |
| Radiopharmaceutical Production Integration | Cyclotron-equipped facilities in Bologna anchor FDG supply security for central Italian hospital clusters. |
Research Methodology
A standing panel of hospital procurement committee chairs, nuclear medicine department heads, biomedical physicists, and AIFA reimbursement specialists provided ongoing calibration against secondary validation through EU MDR conformity databases, Italian regional health authority tender records, and radiopharmaceutical production facility regulatory filings. Bottom-up equipment installation tracking triangulated with top-down regional health expenditure analysis.
Scenario-bracketing framed projections across the analysis window through segmented modeling of product type, application, end user, and detector technology evolution. CAGRs derived from procedure volume elasticity to reimbursement rate changes and equipment replacement cycle compression. Forecast inputs incorporated silicon photomultiplier adoption curves and cyclotron capacity expansion timelines.
Sensitivities concentrate around AIFA tariff revision timing, EU MDR software conformity enforcement intensity, and qualified medical physics staffing constraints. Cross-checking against Italian National Health Service expenditure benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Spain Computed Tomography Market
Medical Imaging
Global Computed Tomography (CT) Market
Medical Imaging
Teleradiology Market
Medical Imaging
Brazil Nuclear Imaging Market
Medical Imaging
Portable MRI Market
Medical Imaging
China Nuclear Imaging Market
Medical Imaging
United Arab Emirates Diagnostic Imaging Equipment Market
Medical Imaging
Veterinary Computed Tomography Scanner Market
Medical Imaging
AI-Enabled Diagnostic Imaging Market
Medical Imaging
Molecular Imaging Market
Medical Imaging
Japan Diagnostic Imaging Market
Medical Imaging
Teleradiology Services Market
Medical Imaging
PACS and RIS Market
Medical Imaging
Asia Pacific Computed Tomography (CT) Market
Medical Imaging
United States Mammography Market
Medical Imaging
Medical X-Ray Market