
 Prothrombin Time Testing Market | 2026-2036
Prothrombin Time Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Prothrombin Time Testing Market Analytics
China is fragmenting its prothrombin time testing supply base as domestic IVD manufacturers scale reagent production for hospital laboratories. Siemens Healthineers leverages its installed base of coagulation analyzers across European reference labs. Abbott Laboratories sustains competitive positioning through point-of-care PT testing platforms deployed in emergency departments. Werfen differentiates via specialized hemostasis diagnostics integrated with laboratory information systems.
Prothrombin time testing measures the extrinsic coagulation pathway using thromboplastin reagents to detect clot formation, typically reported as INR for standardized anticoagulant monitoring in warfarin therapy. The assay requires calcium chloride addition and temperature-controlled incubation at 37°C to ensure reproducible clotting times across clinical settings. Reagent segments command recurring revenue streams through consumable replenishment tied to analyzer placements, while optical detection technology leads instrument architectures due to sensitivity in turbidimetric endpoint determination. Home care channels represent the fastest-growing end-user category as patient self-testing devices gain regulatory clearance for INR management outside clinical facilities.
The US FDA oversees 510(k) premarket notification requirements for PT testing systems, while the EU MDR imposes stricter clinical evidence standards for in vitro diagnostic devices entering European markets. ISO 17511 traceability standards govern calibrator assignment for INR reporting, directly impacting reagent manufacturer market access. Stakeholders must monitor evolving harmonization between FDA and EMA post-market surveillance requirements for coagulation testing devices.
Market Dynamics
Hospital consolidation into integrated delivery networks is concentrating PT testing procurement authority, while point-of-care adoption fragments testing sites into emergency departments, ambulatory surgery centers, and patient homes.
Growth Catalysts
- Perioperative patient management protocols:Surgical volume recovery across tertiary care hospitals is expanding routine coagulation screening requirements. Elective procedure backlogs in the United States and Germany are driving analyzer utilization rates.
- EU MDR Class II device pathways:Streamlined conformity assessment routes for moderate-risk IVDs are accelerating regulatory clearance timelines for novel PT testing platforms. European reference laboratories are upgrading to compliant systems ahead of transition deadlines.
- Thromboplastin reagent standardization:WHO international reference preparations are improving INR harmonization across multi-site anticoagulation clinics. Standardized calibrator traceability is reducing inter-laboratory variability in warfarin monitoring.
Market Restraints
- Reagent input cost volatility:Bovine thromboplastin supply depends on slaughterhouse byproduct streams concentrated in Brazil and Argentina. Tissue extract purification yields fluctuate with livestock commodity cycles.
- Optical detection patent thickets:Turbidimetric endpoint algorithms remain encumbered by expired-but-litigated intellectual property estates. New entrants face freedom-to-operate clearance costs exceeding instrument development budgets.
- Direct oral anticoagulant displacement:Factor Xa inhibitor therapies eliminate routine INR monitoring requirements in atrial fibrillation populations. Warfarin patient volumes are compressing in markets with strong DOAC reimbursement.
Strategic Opportunities
- Patient self-testing channel development:Home INR monitoring devices with Bluetooth connectivity are capturing anticoagulation management outside clinical facilities. Medicare reimbursement expansion in the United States is validating this distribution model.
- Artificial intelligence-enabled result interpretation:Machine learning algorithms trained on coagulation pattern databases are converging with laboratory information systems. Automated flagging of aberrant clotting curves reduces manual review burdens.
- Central and Eastern European laboratory networks:Poland and Romania are consolidating hospital laboratories into regional hub-and-spoke configurations. Greenfield analyzer placements in these networks bypass legacy system replacement cycles.
Industry Challenges
- ISO 17511 calibrator assignment expertise:Metrological traceability implementation requires specialized reference measurement procedure capabilities scarce among mid-tier reagent manufacturers. Competency gaps delay market entry for novel thromboplastin formulations.
- Legacy analyzer integration complexity:Hospital information system interfaces for installed coagulation instruments use proprietary communication protocols. Middleware development for multi-vendor connectivity consumes implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prothrombin Time Testing Market |
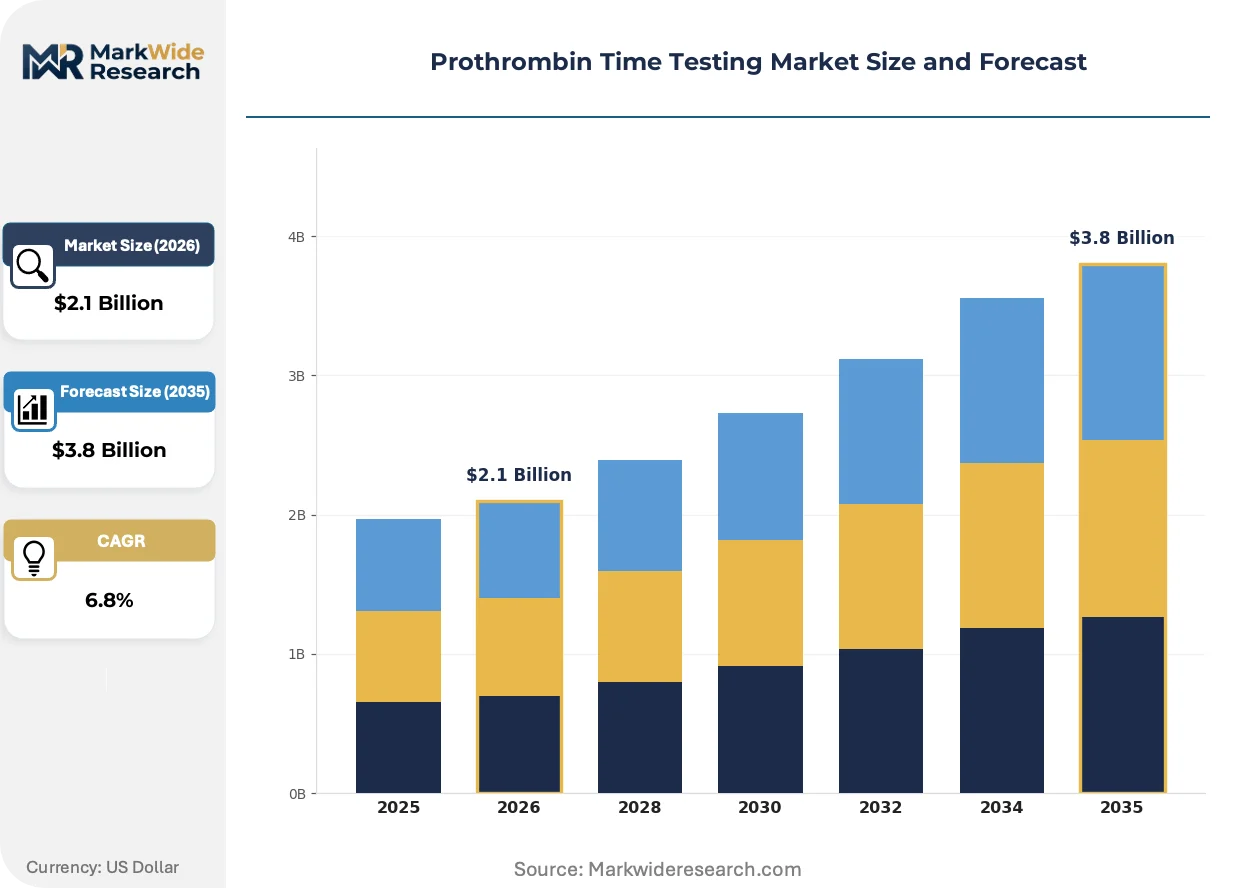
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Analyzers, Consumables, Software End User: Hospitals, Diagnostic Laboratories, Clinics, Home Care Technology: Coagulation Testing, Optical Method, Mechanical Method, Immunoassay Application: Surgical Procedures, Anticoagulant Monitoring, Liver Disease, Cardiovascular Disorders |
| Companies Covered | Siemens Healthineers, Abbott Laboratories, F. Hoffmann-La Roche Ltd, Werfen, Sysmex Corporation, Thermo Fisher Scientific, Beckman Coulter, Instrumentation Laboratory, Mindray Medical International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prothrombin Time Testing Market Evolving Landscape
Microfluidic cartridge architectures are collapsing sample volume requirements while electrochemical detection methods challenge optical turbidimetry dominance in point-of-care segments.
Silicon-chip microfluidic platforms integrate reagent storage, plasma separation, and clot detection into single-use cartridges consuming sub-50 microliter blood volumes. Emergency departments in the United States and Germany are adopting these systems for rapid trauma coagulopathy assessment. The technology is rendering obsolete conventional cuvette-based analyzers requiring centrifuged plasma and skilled operator intervention.
The EU MDR's stricter clinical evidence requirements for Class IIa IVDs are mandating expanded method comparison studies against predicate devices. Reagent manufacturers must generate patient sample data across anticoagulated and normal populations to support INR claim equivalency. European notified bodies are extending review timelines, compressing product launch windows for platforms awaiting conformity assessment.
Anticoagulation clinics are unbundling after-sales service contracts from analyzer procurement, negotiating standalone preventive maintenance agreements with third-party service organizations. Independent service providers in the United States are capturing calibration and quality control support previously captive to original equipment manufacturers. This purchasing behavior shift is most pronounced in multi-site hospital systems seeking vendor diversification.
Prothrombin Time Testing Market Segmentation
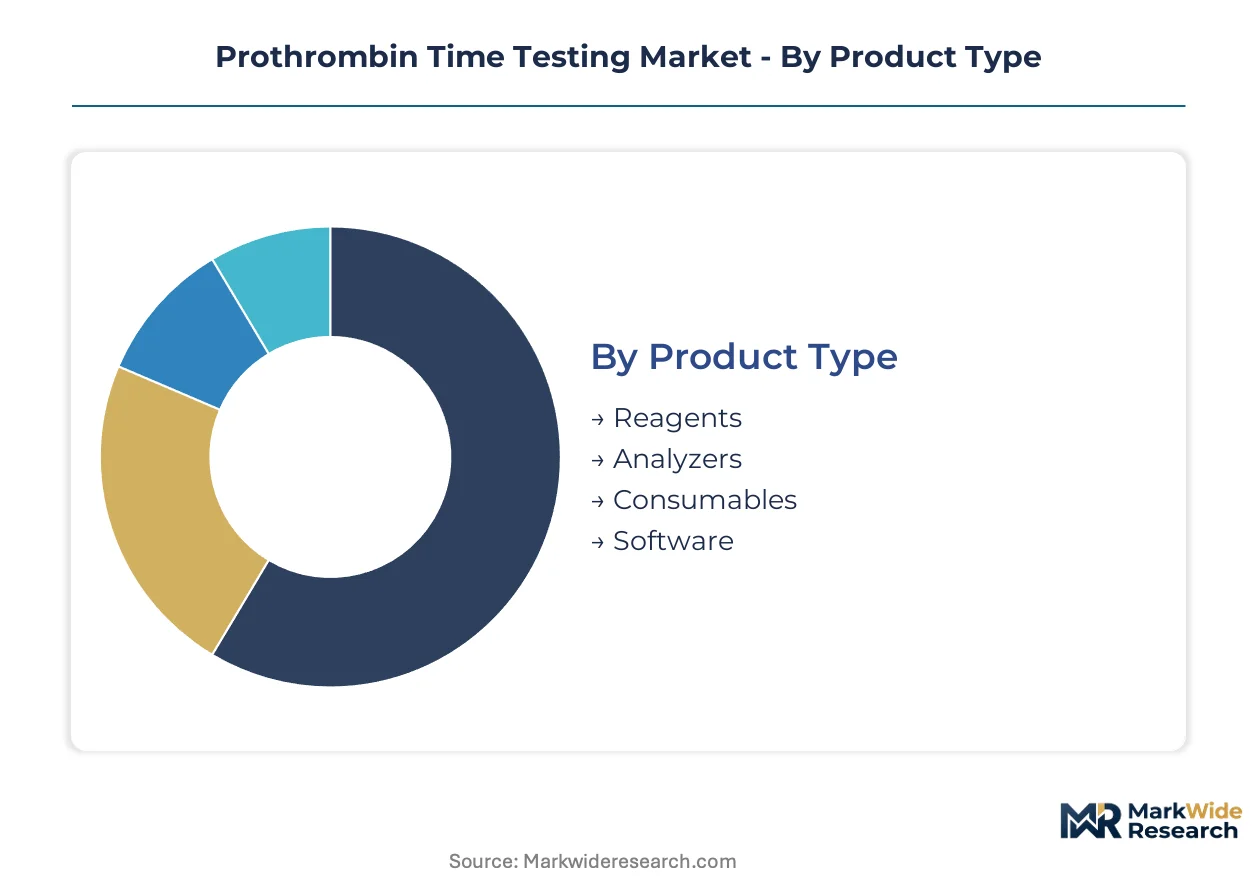
Segmentation in prothrombin time testing reveals distinct procurement cycles and margin profiles across product types, end-user channels, and detection technologies. Understanding these structural differences guides vendor resource allocation and pricing architecture decisions.
Product Type:
Reagent consumables turn over fastest with monthly replenishment cycles, while capital equipment sits on depreciation schedules spanning seven to ten years.
- Reagents:Thromboplastin reagents with calcium chloride activators constitute the recurring revenue foundation. Hospital laboratories in Germany and the United States consume these in high-throughput coagulation analyzers, with procurement tied to analyzer vendor lock-in agreements.
- Analyzers:Optical turbidimetry instruments dominate installed capacity. Central and Eastern European laboratory networks in Poland and Romania are absorbing new placements as regional hub-and-spoke configurations consolidate testing volumes.
- Consumables:Cuvettes, sample cups, and quality control materials follow analyzer placements. Demand concentrates in tertiary care hospitals managing perioperative screening protocols.
- Software:Laboratory information system middleware enables multi-vendor connectivity. ISO 17511 traceability compliance drives upgrade cycles for result management platforms.
Reagents dominate installed base. Software is where expansion concentrates.
End User:
Cost tiers separate capital-intensive hospital laboratories from distributed point-of-care channels with lower per-test infrastructure requirements.
- Hospitals:Integrated delivery networks concentrate purchasing authority for high-volume coagulation laboratories. Elective surgical backlog clearance in the United States and Germany is expanding analyzer utilization rates.
- Diagnostic Laboratories:Reference laboratories process outsourced PT testing for smaller facilities. Centralized networks in Germany leverage statutory health insurance reimbursement to sustain routine monitoring volumes.
- Clinics:Anticoagulation clinics manage warfarin therapy with moderate test frequencies. Medicare reimbursement validation in the United States supports point-of-care adoption in these settings.
- Home Care:Patient self-testing devices with Bluetooth connectivity are gaining regulatory clearance. Medicare expansion is validating this distribution model outside clinical facilities.
Hospitals anchor revenue concentration. Home care is climbing the fastest.
Technology:
Application requirements dictate detection method selection, with trauma settings demanding speed and reference laboratories prioritizing precision.
- Coagulation Testing:Conventional plasma-based assays remain the clinical standard. WHO international reference preparations are improving INR harmonization across multi-site monitoring programs.
- Optical Method:Turbidimetric endpoint detection leads instrument architectures due to sensitivity in clot formation measurement. Patent thickets around detection algorithms constrain new entrant freedom-to-operate.
- Mechanical Method:Viscosity-based detection offers alternative endpoint determination. Microfluidic cartridge architectures are integrating mechanical sensing for point-of-care segments.
- Immunoassay:Factor-specific antibody detection supports specialized hemostasis diagnostics. Werfen integrates these with laboratory information systems for differentiated positioning.
Optical method dominates installed base. Mechanical method is gaining share fastest.
Application:
Volume concentration varies sharply across clinical indications, with surgical screening generating batch demand and chronic monitoring producing predictable recurring flows.
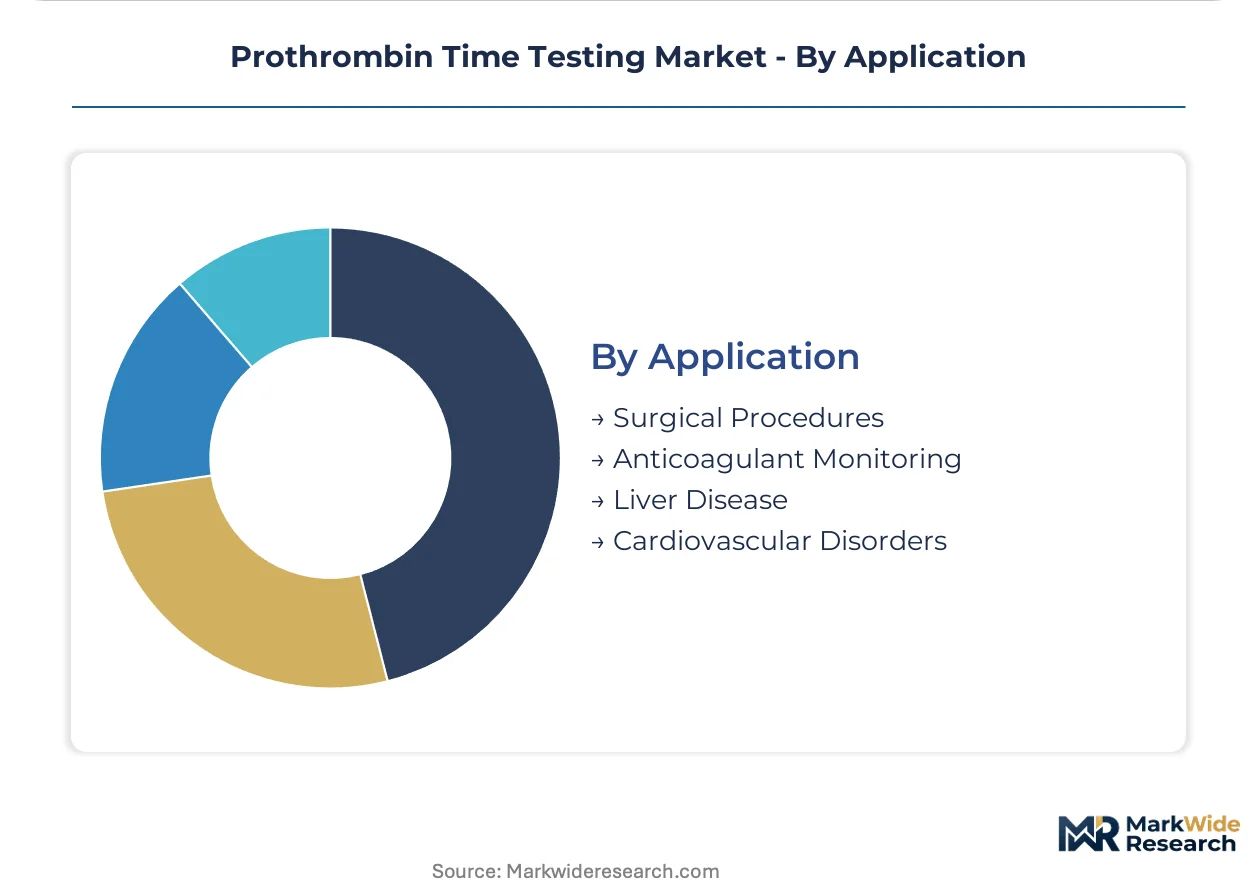
- Surgical Procedures:Perioperative coagulopathy assessment requires rapid turnaround. Emergency departments in the United States and Germany are adopting microfluidic platforms for trauma evaluation.
- Anticoagulant Monitoring:Warfarin therapy management produces steady test demand. Direct oral anticoagulant displacement is compressing patient volumes in markets with strong factor Xa inhibitor reimbursement.
- Liver Disease:Hepatic synthetic function assessment utilizes PT prolongation patterns. Specialized hepatology centers drive concentrated reagent consumption.
- Cardiovascular Disorders:Atrial fibrillation populations require ongoing surveillance. DOAC therapy expansion is restructuring testing requirements in this segment.
Surgical procedures anchor throughput volume. Anticoagulant monitoring is where vendor competition intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes prothrombin time testing through centralized laboratory networks with statutory reimbursement, while the United States fragments demand across hospital laboratories, emergency departments, and emerging home care channels.
United States
Hospital consolidation into integrated delivery networks concentrates procurement authority for high-throughput coagulation analyzers. The FDA's updated Class II device guidance tightens analytical performance requirements for point-of-care platforms. Tertiary care centers in Boston and Houston are clearing elective surgical backlogs, expanding analyzer utilization for perioperative screening protocols.
Germany
Centralized laboratory networks sustain high test volumes through statutory health insurance reimbursement for routine coagulation monitoring. The EU MDR imposes stricter clinical evidence standards for IVD devices entering European markets. Reference laboratories in Munich and Heidelberg are upgrading to compliant systems ahead of regulatory transition deadlines.
China
Domestic IVD manufacturers are scaling reagent production to supply hospital laboratories with localized thromboplastin formulations. The NMPA oversees premarket approval requirements for coagulation testing systems. Production clusters in Shanghai and Shenzhen are absorbing analyzer placements as regional hub-and-spoke configurations consolidate testing volumes.
Poland
Hospital laboratories are consolidating into regional hub-and-spoke networks that bypass legacy system replacement cycles. The country's national pharmaceutical regulator aligns IVD oversight with EU MDR harmonization requirements. Greenfield analyzer placements in Warsaw and Kraków are capturing testing volumes from smaller satellite facilities.
Japan
Reference laboratories prioritize precision in optical turbidimetry systems for standardized INR reporting. The PMDA maintains rigorous post-market surveillance for coagulation testing devices. Industrial clusters in Tokyo and Osaka are integrating AI-enabled result interpretation with laboratory information systems.
Prothrombin Time Testing Market Competitive Landscape
Capability concentration sits with specialized hemostasis diagnostics firms; scale advantage sits with diversified medical technology conglomerates. The market structures around three tiers: global diversified majors with installed base leverage, regional reagent specialists with ISO 17511 traceability expertise, and emerging microfluidic platform innovators. Dominant competitive moves include portfolio diversification into point-of-care segments and strategic partnerships for laboratory information system integration.
Among diversified technology majors, Siemens Healthineers and Abbott Laboratories exemplify contrasting strategic positions. Siemens Healthineers occupies a position anchored in European reference laboratory installed bases, while Abbott Laboratories represents the point-of-care expansion archetype with emergency department platform deployment. Werfen sits within the specialized diagnostics tier, differentiated through hemostasis-specific system integration.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Werfen |
| Sysmex Corporation |
| Thermo Fisher Scientific |
| Beckman Coulter |
| Instrumentation Laboratory |
| Mindray Medical International |
| Others |
Value Network & Pricing Analysis
Bovine thromboplastin extraction in Brazil and Argentina feeds directly into reagent manufacturer margin pools in Germany and the United States. Input cost volatility from livestock commodity cycles compresses pricing power at the consumable tier while analyzer vendors defend premium positioning through service bundling.
Pricing Analysis
Long-term offtake contracts dominate high-volume hospital laboratory procurement, locking in reagent pricing across multi-year analyzer placement agreements. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17511-traceable reagents from regional formulations and private-label alternatives. Cost compression in the economy tier is intensifying because domestic Chinese manufacturers are scaling localized thromboplastin production. Integrated delivery networks exhibit lowest price sensitivity due to consolidated procurement authority, while independent anticoagulation clinics negotiate aggressively on per-test consumables.
Supply Chain Analysis
Bovine lung tissue feedstock draws from slaughterhouse byproduct streams concentrated in Brazil, Argentina, and select facilities in the United States. Thromboplastin reagent production rests on tissue extract purification yields, calcium chloride activator quality, and lyophilization stability protocols. Single-source vulnerability in South American livestock supply creates exposure to commodity price swings and regulatory restrictions on bovine-derived materials. Distribution runs through original equipment manufacturer captive channels, third-party laboratory distributors, and direct hospital contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital consolidation into integrated delivery networks and anticoagulation clinic unbundling of after-sales service contracts. This fragmentation among procurement authorities demands differentiated positioning strategies across vendor tiers.
For Market Incumbents: Harden installed base defenses by deepening ISO 17511 metrological traceability capabilities and capturing multi-vendor laboratory information system middleware contracts. Siemens Healthineers and Abbott Laboratories face emerging microfluidic platform innovators threatening point-of-care segments; vertical integration into thromboplastin reagent production insulates margin pools from input volatility. For New Entrants and Emerging Players: Build out patient self-testing device portfolios with Bluetooth connectivity and Medicare reimbursement pathways as the most penetrable white-space channel. Central and Eastern European laboratory networks in Poland and Romania offer greenfield analyzer placement opportunities bypassing legacy replacement cycles. A go-to-market angle anchored in AI-enabled result interpretation differentiates against incumbent optical turbidimetry platforms. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional reagent specialists possessing ISO 17511 traceability expertise but lacking global distribution infrastructure. The five-to-ten year viability window favors platforms with EU MDR compliance and software companion development capabilities. The signal to watch is DOAC reimbursement expansion compressing warfarin monitoring volumes and triggering analyzer utilization inflections.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Assessment | Accelerates regulatory clearance timelines for novel PT testing platforms in European reference laboratories. |
| Patient Self-Testing Device Launch | Captures anticoagulation management outside clinical facilities with Medicare reimbursement validation. |
| Laboratory Information System Integration | Enables multi-vendor connectivity through ISO 17511-compliant middleware development. |
| Microfluidic Platform Development | Collapses sample volume requirements for emergency department trauma coagulopathy assessment. |
| AI-Enabled Result Interpretation | Reduces manual review burdens through machine learning algorithms trained on coagulation pattern databases. |
Research Methodology
The analysis maps reagent consumables, optical turbidimetry analyzers, microfluidic platforms, and laboratory information system software, each validated through laboratory directors, biomedical engineers, hospital purchasing committee members, and GPO contracts managers. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up instrument placement modeling and top-down reagent consumption estimates triangulate market sizing.
Assumption sets held regulatory transition timelines and surgical volume recovery patterns fixed while varying direct oral anticoagulant displacement rates and patient self-testing adoption curves across the projection horizon. Segmentation dimensions modeled include product type, end-user channel, detection technology, and application indication. CAGRs derive from analyzer utilization rate trajectories and reagent replenishment cycle analysis, with thromboplastin input cost indices and Medicare reimbursement policy shifts as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive pricing moves by domestic Chinese IVD manufacturers or accelerated DOAC therapy expansion would shift outcomes. Cross-checking against hospital capital expenditure surveys and anticoagulation clinic visit volume data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Gamma Glutamyl Transferase Testing Market
Testing Services
Global Helicobacter Pylori (H. Pylori) Non-Invasive Testing Market
Testing Services
Dengue Testing Market
Testing Services
Endocrine Peptides Test Market
Testing Services
Global Legionella Testing Market
Testing Services
Ready-To-Use Laboratory Test Kits Market
Testing Services
Cerebrospinal Fluid (CSF) Testing Market
Testing Services
Passive Dosimetry Equipment and Service Market
Testing Services
Global Direct-To-Consumer (DTC)Testing Market
Testing Services
United States Testing, Inspection, and Certification (TIC) Market
Testing Services
Asia-Pacific Hereditary Cancer Testing Market
Testing Services
Indoor Allergen and Particulate Exposure Assessment Test Devices Market
Testing Services
Global Urinalysis Test Market
Testing Services
Asia Pacific Sterility Testing Market
Testing Services
Global Direct to Consumer Laboratory Testing Market
Testing Services
Toxicology Testing Services Market