
 Metabolic Biomarker Testing Market | 2026-2036
Metabolic Biomarker Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Metabolic Biomarker Testing Market Outlook
Multi-source instrument procurement is consolidating across large reference laboratories and pharmaceutical sponsors seeking to reduce vendor fragmentation in metabolomics workflows. Thermo Fisher Scientific leverages its chromatography-mass spectrometry portfolio to anchor high-throughput profiling contracts with major hospital networks. Danaher Corporation sustains competitive positioning through Beckman Coulter's automated sample prep systems integrated with biochemical assay menus. Waters Corporation differentiates via specialized UPLC-MS platforms optimized for lipidomic and polar metabolite separation.
Metabolic biomarker testing encompasses the quantitative analysis of endogenous small molecules—amino acids, organic acids, lipids, nucleotides, and carbohydrates—typically via mass spectrometry or nuclear magnetic resonance spectroscopy at detection thresholds reaching picomolar concentrations, serving to characterize physiological state, disease progression, or drug response in clinical and research settings. Biochemical assays retain the largest installed base due to lower capital requirements and established reimbursement pathways, while genomic testing commands premium positioning where metabolite-genotype interactions inform therapeutic selection. Lipid profiling exhibits the fastest expansion as cardiovascular and neurodegenerative drug developers prioritize circulating lipid signatures for patient stratification.
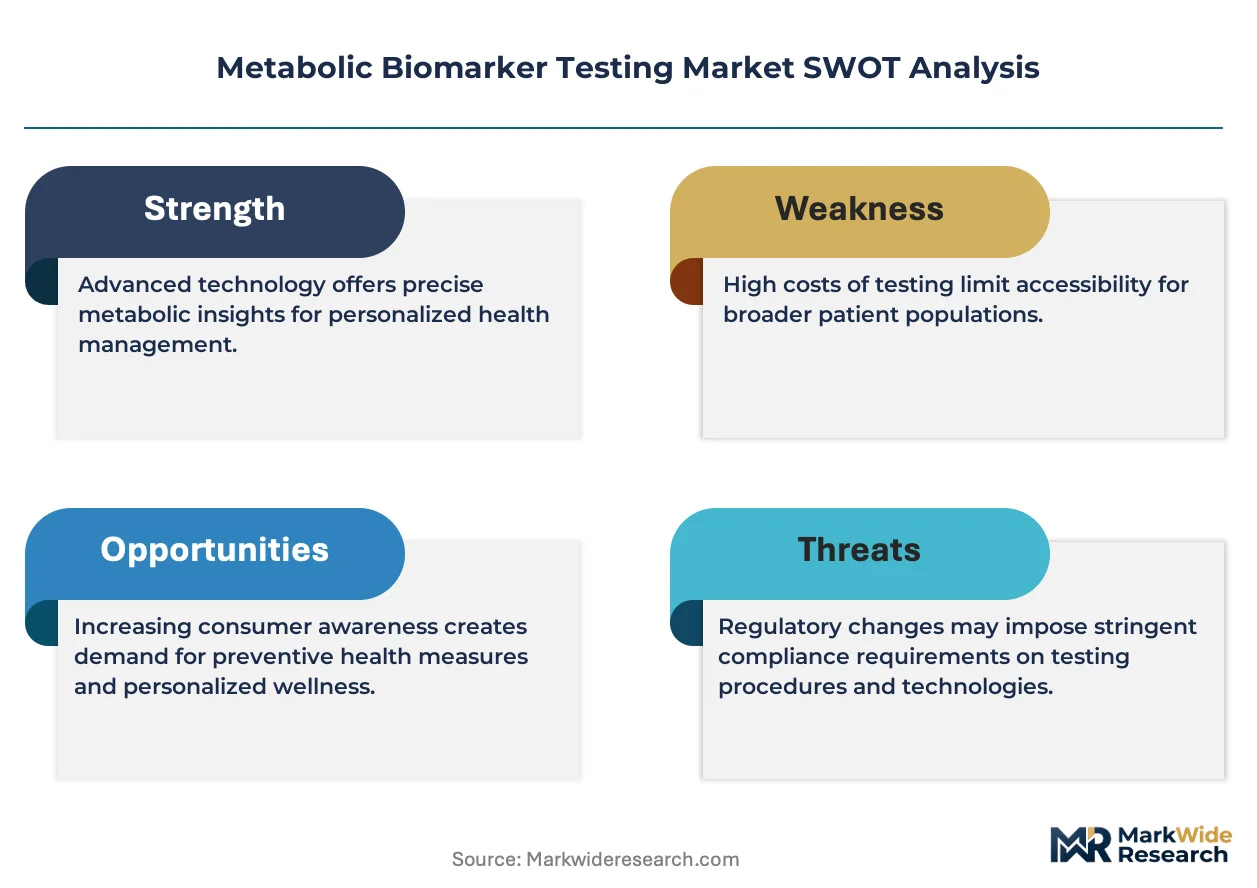
FDA biomarker qualification programs and CLIA laboratory certification standards shape validation burdens and commercialization timelines for test developers seeking clinical adoption. The European Medicines Agency's EMA parallel scientific advice pathway on biomarkers influences multinational trial designs, while ISO 15189 accreditation requirements govern quality management for clinical laboratories processing metabolic panels. Stakeholders must monitor evolving payer coverage determinations for multi-analyte profiling versus single-biomarker reimbursement to align portfolio development with accessible revenue models.
Market Dynamics
Pharmaceutical precision medicine pipelines are consolidating procurement around integrated metabolomics platforms, compressing vendor relationships and reshaping competitive positioning through multi-year service contracts anchored by high-throughput mass spectrometry infrastructure.
Growth Catalysts
- FDA Biomarker Qualification Programs:Accelerated validation pathways for metabolic test commercialization are shortening time-to-market for diagnostic developers targeting oncology and cardiovascular therapeutic areas.
- Lipidomic Profiling Demand:Neurodegenerative drug developers in the United States are prioritizing circulating lipid signatures for patient stratification in clinical trial enrollment.
- Academic Medical Center Clustering:Concentrated research infrastructure around Boston, San Francisco, and Research Triangle Park is generating standardized metabolite reference databases.
Market Restraints
- Mass Spectrometer Supply Concentration:Critical instrumentation components face sourcing bottlenecks from specialized German and Japanese precision engineering suppliers.
- CLIA Laboratory Certification Burden:Multi-analyte metabolic panels require extensive validation documentation, extending commercialization timelines for test developers.
- Biochemical Assay Substitution:Lower-capital enzymatic methods retain reimbursement advantages in routine clinical chemistry, constraining premium MS-based test penetration.
Strategic Opportunities
- EMA Parallel Scientific Advice:Biomarker-integrated trial designs are unlocking streamlined multinational drug development pathways for European sponsors.
- Point-of-Care Metabolite Testing:Miniaturized NMR platforms are penetrating ambulatory settings previously served by centralized reference laboratories.
- Multi-Omics Data Integration:Convergence of metabolomic, proteomic, and genomic datasets is creating differentiated service offerings for precision medicine consortia.
Industry Challenges
- Bioinformatics Talent Scarcity:Computational metabolomics expertise remains concentrated among a limited pool of specialized academic programs.
- ISO 15189 Accreditation Complexity:Quality management system implementation for clinical metabolic panels demands sustained operational investment.
- Inter-Platform Standardization Gaps:Variable metabolite quantification across LC-MS and NMR systems complicates multi-site clinical study data harmonization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metabolic Biomarker Testing Market |
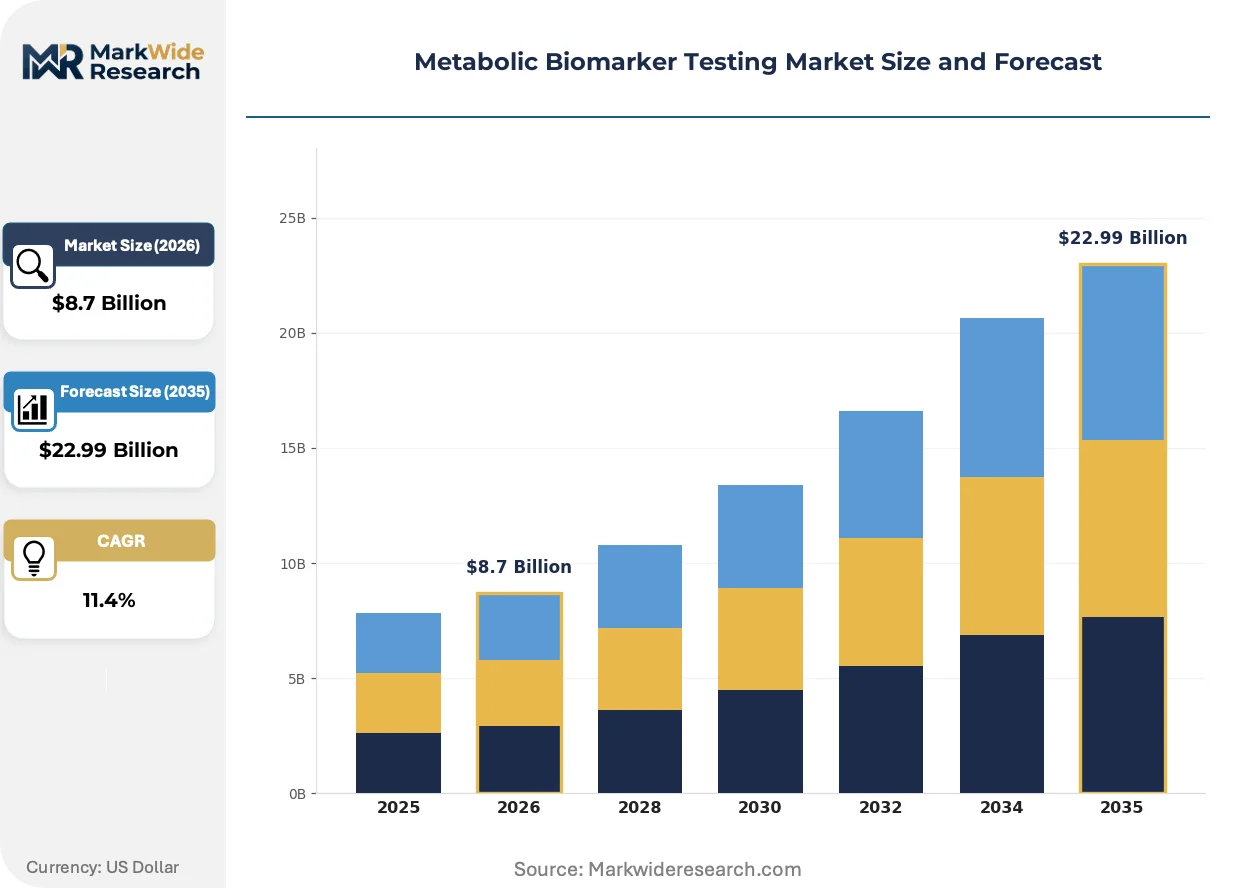
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Biochemical Assays, Genomic Testing, Proteomic Analysis, Lipid Profiling Application Area: Clinical Diagnosis, Nutritional Assessment, Disease Prevention, Drug Development Sample Type: Blood, Urine, Saliva, Tissue End User: Hospitals, Clinical Laboratories, Research Institutions, Pharmaceutical Companies |
| Companies Covered | Waters Corporation, Danaher Corporation, Thermo Fisher Scientific, Merck KGaA, Shimadzu Corporation, Agilent Technologies, Bio-Rad Laboratories, Biocrates Life Sciences AG, Bruker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metabolic Biomarker Testing Market Strategic Shifts
Metabolomics instrumentation and service delivery models are converging around automated, high-throughput platforms that compress analytical turnaround times while expanding detectable analyte coverage for pharmaceutical and clinical research applications.
High-resolution mass spectrometry is absorbing sample preparation bottlenecks through integrated robotic liquid handling systems. Large pharmaceutical sponsors are deploying these platforms across centralized screening facilities. The technology is absorbing previously manual workflow steps, reducing technician intervention and improving inter-batch reproducibility for longitudinal biomarker studies.
EMA's expanded qualification opinion procedures for novel methodologies are formalizing metabolite ratio biomarkers as acceptable primary endpoints. This regulatory development is accelerating sponsor engagement with European regulators during protocol design phases. Cardiovascular and metabolic disease therapeutic areas are responding with dedicated biomarker strategy functions embedded in clinical operations teams.
Consortium-based reference standard development is displacing proprietary in-house metabolite libraries. Academic medical centers and CROs are pooling authenticated reference materials through multi-institutional agreements. This collaborative model is most visible in the United States, where NIH-funded metabolomics cores are federating quality control protocols across geographically distributed analytical sites.
Metabolic Biomarker Testing Market Segmentation
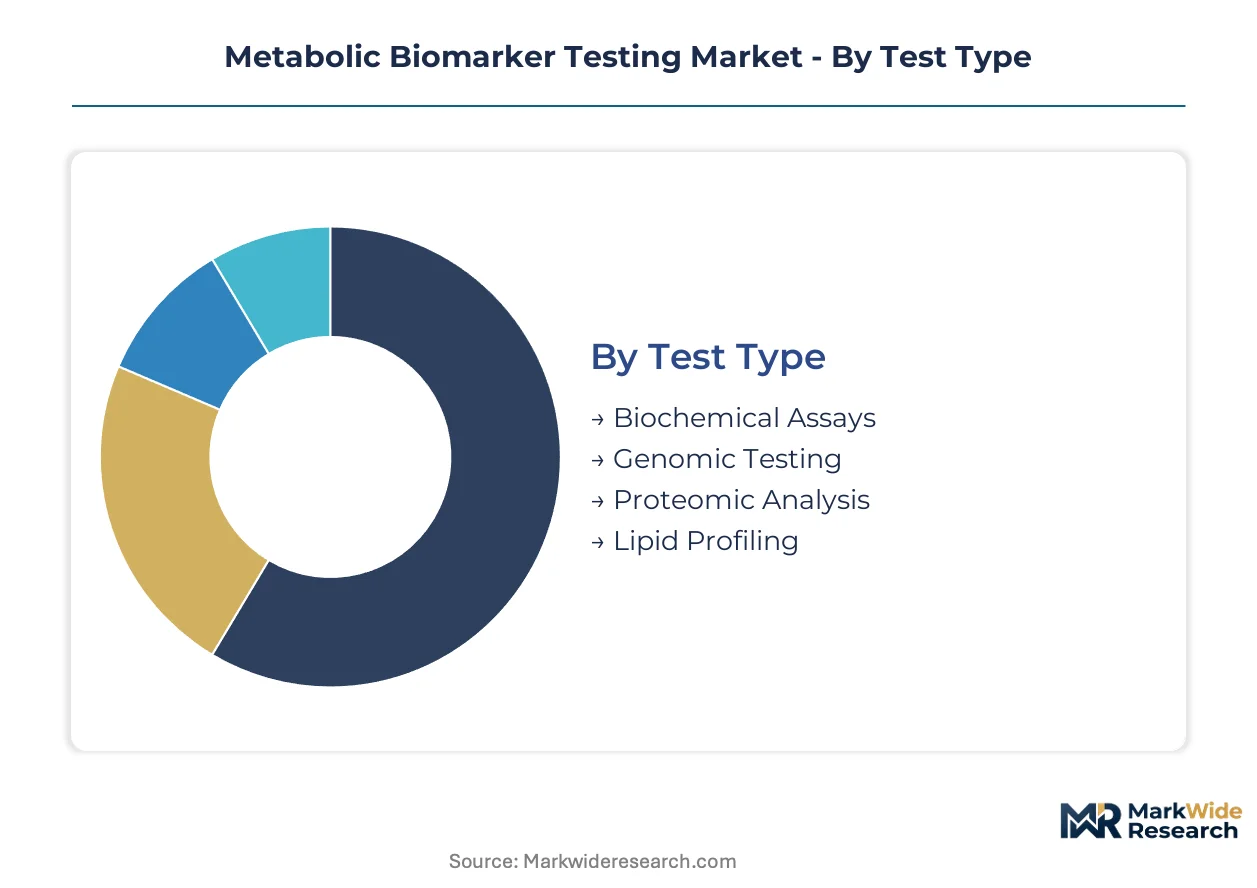
Metabolic biomarker testing segments reflect divergent capital requirements, reimbursement pathways, and analytical complexity that shape vendor portfolio priorities. Test developers must align platform investments with the specific validation burdens and end-user procurement patterns governing each category.
Test Type:
Equipment replacement cycles and platform upgrade timelines vary sharply across detection methodologies, with mass spectrometry systems demanding 5-7 year refresh intervals versus enzymatic analyzers operating on decade-long depreciation schedules.
- Biochemical Assays:Enzymatic and colorimetric methods measuring glucose, cholesterol, and liver enzymes through automated clinical chemistry analyzers. Hospital laboratories in the United States prioritize these systems for their established CPT reimbursement codes and lower per-test operational costs.
- Lipid Profiling:Chromatographic separation of fatty acids, phospholipids, and sterol classes quantified via LC-MS/MS or NMR spectroscopy. Cardiovascular drug developers at academic medical centers are consolidating procurement around high-throughput lipidomic platforms for patient stratification in clinical trials.
- Genomic Testing:Polygenic risk scores and pharmacogenomic panels informing metabolite-genotype interactions.
- Proteomic Analysis:Mass spectrometry-based quantification of circulating protein biomarkers correlated with metabolic dysfunction.
Volume placements concentrate in Biochemical Assays; the faster expansion belongs to Lipid Profiling.
Application Area:
Customer procurement budgets and validation timelines diverge across use cases, with pharmaceutical sponsors commanding multi-year service contracts while clinical diagnostic developers navigate CLIA certification pathways.
- Drug Development:Metabolomic profiling integrated into Phase I-III trials for pharmacokinetic characterization and patient stratification. Contract research organizations cluster demand in Boston and San Francisco, where FDA biomarker qualification programs accelerate validation timelines for metabolic endpoints.
- Clinical Diagnosis:Inborn errors of metabolism, diabetes monitoring, and cardiovascular risk assessment through CLIA-certified laboratory-developed tests. Academic medical centers prioritize multi-analyte panels requiring extensive reference range validation.
- Disease Prevention:Population-scale screening for metabolic syndrome and prediabetes progression.
- Nutritional Assessment:Micronutrient and metabolic efficiency profiling for personalized dietary interventions.
Revenue concentration favors Drug Development; Clinical Diagnosis exhibits the steepest expansion trajectory as reimbursement pathways mature for precision metabolic panels.
Sample Type:
Collection logistics and analyte stability requirements shape platform configuration decisions, with matrix effects and pre-analytical variability demanding specialized extraction protocols.
- Blood:Serum and plasma matrices supporting comprehensive amino acid, organic acid, and lipid quantification via LC-MS platforms. Centralized reference laboratories in the United States process high-volume blood panels through automated sample prep systems integrated with high-resolution mass spectrometry.
- Urine:Non-invasive collection enabling longitudinal metabolic monitoring and renal function assessment.
- Saliva:Cortisol and small-molecule metabolite measurement for ambulatory and point-of-care settings.
- Tissue:Biopsy-derived metabolite imaging for oncology and metabolic disease pathology.
Processing volume concentrates in Blood; Saliva is climbing fastest as miniaturized NMR platforms penetrate decentralized testing environments.
End User:
Procurement authority and technical specification requirements vary across institutional settings, with pharmaceutical companies driving platform customization versus hospitals prioritizing interoperability with existing EHR infrastructure.
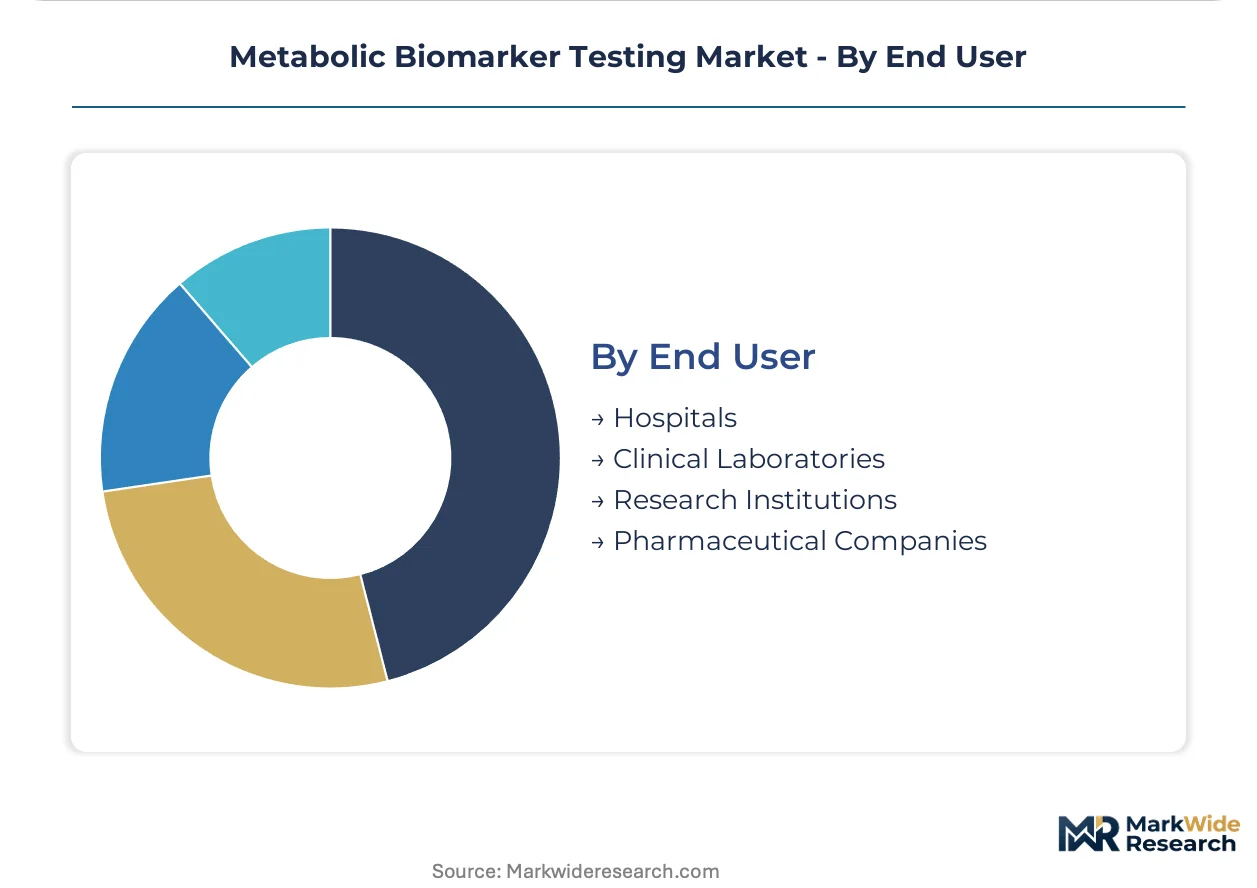
- Pharmaceutical Companies:Sponsors of precision medicine pipelines commissioning multi-year metabolomics service contracts. These organizations anchor demand for high-throughput profiling capacity at centralized screening facilities in Research Triangle Park and San Francisco.
- Hospitals:Integrated delivery networks requiring CLIA-compliant metabolic panels with LIS connectivity and established CPT coding.
- Clinical Laboratories:Independent reference labs and hospital outreach programs competing on turnaround time and test menu breadth.
- Research Institutions:NIH-funded metabolomics cores federating quality control protocols across distributed analytical sites.
Contract value concentrates in Pharmaceutical Companies; Research Institutions are gaining share fastest through consortium-based reference standard development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical procurement of metabolic profiling services concentrates in the United States, where academic medical centers and contract research organizations anchor demand through multi-year service contracts. Boston, San Francisco, and Research Triangle Park host the densest clustering of metabolomics infrastructure and reference laboratory capacity.
United States
FDA biomarker qualification programs and CLIA laboratory certification standards drive validation requirements for commercial test deployment. Academic medical centers in Boston and San Francisco generate standardized metabolite reference databases through NIH-funded metabolomics cores. Research Triangle Park anchors centralized screening facilities for pharmaceutical sponsors seeking high-throughput profiling capacity.
Germany
Precision engineering suppliers from specialized German manufacturers feed critical instrumentation components into global mass spectrometer supply chains. EMA parallel scientific advice pathways on biomarkers influence multinational trial designs incorporating metabolic endpoints. The country's pharmaceutical regulator maintains alignment with FDA qualification standards for metabolite ratio biomarkers.
United Kingdom
London-based CROs integrate metabolomic profiling into Phase I-III trials for pharmacokinetic characterization. The Medicines and Healthcare products Regulatory Agency participates in EMA qualification opinion procedures for novel methodologies. Cambridge and Oxford academic clusters federate quality control protocols through consortium-based reference standard development.
Japan
PMDA regulatory frameworks accommodate metabolite-genotype interaction data for therapeutic selection in precision medicine pipelines. METI industrial policy supports domestic mass spectrometry component manufacturing to reduce import dependency. Tokyo and Osaka metropolitan areas concentrate hospital laboratory networks processing biochemical assay menus.
Switzerland
Swissmedic accreditation requirements govern quality management for clinical laboratories processing multi-analyte metabolic panels. Basel anchors pharmaceutical sponsor demand for lipidomic profiling in cardiovascular and neurodegenerative drug development. The country's precision instrumentation sector supplies chromatography systems to global reference laboratories.
Metabolic Biomarker Testing Market Competitive Environment
Multi-year service contract consolidation dominates the current landscape as pharmaceutical sponsors compress vendor relationships around integrated metabolomics platforms. The vendor base organizes into three tiers: diversified life science conglomerates with chromatography-mass spectrometry portfolios, specialized analytical instrumentation firms with UPLC-MS platforms, and automated sample prep system suppliers. Strategic archetypes include platform-anchored service providers, point solution specialists, and consortium-based reference standard developers. M&A activity and technology licensing agreements represent the primary competitive moves reshaping positioning.
Among diversified conglomerates, Thermo Fisher Scientific and Danaher Corporation exemplify platform-anchored strategies through chromatography-mass spectrometry and automated sample prep integration respectively. Waters Corporation occupies a specialist position within the analytical instrumentation tier, differentiated via UPLC-MS platforms. Biocrates Life Sciences AG represents the focused metabolomics reference standard segment, while Bruker Corporation and Shimadzu Corporation anchor the precision engineering supplier tier serving global instrument demand.
| Leading Market Players |
|---|
| Waters Corporation |
| Danaher Corporation |
| Thermo Fisher Scientific |
| Merck KGaA |
| Shimadzu Corporation |
| Agilent Technologies |
| Bio-Rad Laboratories |
| Biocrates Life Sciences AG |
| Bruker Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive in-house production of precision mass spectrometry components anchors supply positioning for leading diagnostic platform vendors, creating pricing power through controlled scarcity of German and Japanese-sourced ion optics and detector assemblies. Pharmaceutical sponsors absorbing multi-year metabolomics service contracts accept bundled instrument depreciation and technical support fees that compress visible per-test pricing while extending vendor lock-in.
Pricing Analysis
Extended warranty and field service engineering bundles dominate metabolic biomarker testing procurement, with unbundled instrument-only sales confined to research institutions lacking CLIA certification requirements. Three-tier pricing structure across premium, standard, and economy levels separates FDA-qualified assay panels from research-grade profiling and enzymatic clinical chemistry substitutes. Cost compression in high-throughput lipidomic services is intensifying because pharmaceutical sponsors are consolidating vendor relationships around integrated platforms. Academic medical centers exhibit highest price sensitivity due to NIH grant funding constraints, while pharmaceutical companies demonstrate lowest sensitivity given pipeline prioritization of biomarker-integrated trial designs.
Supply Chain Analysis
Regional distribution centers in Massachusetts, California, and North Carolina anchor hub-and-spoke replenishment patterns for reference standard materials and authenticated metabolite libraries. Precision engineering concentration in Germany and Japan feeds critical ion source and mass analyzer subassemblies into global LC-MS instrument assembly lines. Raw material dependencies span high-purity solvents, deuterated internal standards, and specialized chromatography columns. Single-source vulnerability from Japanese detector manufacturers creates structural exposure. Distribution runs through centralized metabolomics cores federating quality control protocols across geographically dispersed analytical sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mass spectrometry-based metabolic profiling is displacing legacy enzymatic clinical chemistry in precision medicine pipelines, with high-resolution platforms absorbing previously manual workflow steps and compressing analytical turnaround times.
For Market Incumbents: Lock in pharmaceutical sponsor relationships through multi-year service contracts anchored by high-throughput LC-MS infrastructure and automated sample prep integration. Defend against biochemical assay substitution by embedding CLIA-compliant assay menus within hospital laboratory workflows. Prioritize backward integration into precision ion optics manufacturing to reduce German and Japanese supplier dependency.
For New Entrants and Emerging Players: Launch via point-of-care miniaturized NMR platforms penetrating ambulatory settings previously served by centralized reference laboratories. Target saliva-based metabolic panels for decentralized testing environments where reimbursement pathways are maturing fastest. Pursue white-space opportunities in nutritional assessment applications through direct-to-consumer subscription models.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform-anchored service providers with established FDA biomarker qualification track records and pharmaceutical sponsor relationships. Long-term viability favors vendors controlling both instrumentation hardware and proprietary metabolite reference databases. Watch for EMA parallel scientific advice pathway expansion as inflection indicator for European market acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Biomarker Qualification Pathway | Accelerates commercial validation timelines for metabolic test developers targeting oncology therapeutic areas. |
| Multi-Omics Data Integration Platform | Creates differentiated service offerings for precision medicine consortia spanning Boston and San Francisco clusters. |
| Automated Sample Prep System Deployment | Reduces technician intervention and improves inter-batch reproducibility for longitudinal biomarker studies. |
| Consortium-Based Reference Standard Development | Pools authenticated metabolite libraries through NIH-funded metabolomics cores across distributed analytical sites. |
| Point-of-Care NMR Miniaturization | Penetrates ambulatory settings with decentralized testing capability outside centralized reference laboratory networks. |
Study Parameters
FDA guidance documents, EMA qualification opinion procedures, and ClinicalTrials.gov metabolic endpoint records formed the secondary backbone for this analysis. Primary interviews with metabolomics core directors, pharmaceutical biomarker strategy leads, CLIA laboratory certification specialists, and hospital procurement managers combined with secondary validation across regulatory filings and instrument vendor technical specifications. Bottom-up test volume modeling and top-down pharmaceutical R&D expenditure triangulation anchored market sizing.
Historical trendline analysis of mass spectrometry instrument placements and biochemical assay menu expansions informed projection frameworks across the analysis window. Segmentation dimensions modeled include test type, application area, sample matrix, and end-user procurement authority. CAGRs derived from weighted average of instrument replacement cycles, pharmaceutical pipeline progression rates, and reimbursement pathway maturation timelines. Forecast inputs incorporated CLIA certification burden estimates and EMA parallel scientific advice engagement frequencies.
Regulatory guidance revisions, mass spectrometer component supply disruptions, and payer coverage determination shifts are the dominant revision risks for metabolic biomarker testing forecasts. Outputs reflect assumptions around FDA biomarker qualification program continuity and pharmaceutical sponsor consolidation patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Friability Tester Market
Testing Services
Human Papilloma Virus Testing Market
Testing Services
Global Mosquito Borne Infections Testing Market
Testing Services
US Pharmaceutical Analytical Testing Outsourcing Market
Testing Services
Toxicology Testing Services Market
Testing Services
Vials Leak Testing Market
Testing Services
ATP Assays Market
Testing Services
Pancreatic Elastase Testing Market
Testing Services
Pancreatic Stone Protein Testing Market
Testing Services
Global Legionella Testing Market
Testing Services
Solid Tumor Testing Market
Testing Services
Cannabis Testing Services Market
Testing Services
North America Newborn Screening Market
Testing Services
Beta-Hydroxybutyrate Testing Market
Testing Services
Gamma Glutamyl Transferase Testing Market
Testing Services
Toxicology Drug Screening Market