
 Leukocyte Count Testing Market | 2026-2036
Leukocyte Count Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Leukocyte Count Testing Market Analytics
North American diagnostic instrument manufacturing is consolidating as health system consolidation drives bulk purchasing agreements for hematology platforms. Sysmex Corporation leverages its installed base of fluorescence flow cytometry systems to sustain recurring reagent revenue streams across integrated delivery networks. Abbott Laboratories anchors point-of-care leukocyte testing in emergency departments with handheld cartridge-based formats. Beckman Coulter competes on high-throughput automation for reference laboratories processing thousands of samples daily.
Leukocyte count testing quantifies white blood cell concentrations in peripheral blood using enumeration principles, with automated analyzers achieving coefficient of variation below 3% at normal ranges through hydrodynamic focusing and multi-parameter light scatter detection. The primary commercial purpose centers on infection surveillance, chemotherapy monitoring, and hematologic disorder screening in clinical workflows. Automated analyzers dominate hospital laboratory capital budgets due to throughput requirements exceeding 100 samples per hour, while point-of-care devices capture fastest growth in ambulatory settings where turnaround time under 15 minutes influences treatment decisions. Flow cytometry technology leads research and oncology monitoring applications with multiparametric leukocyte differentiation capabilities.
FDA 510(k) clearance requirements shape instrument validation timelines and predicate device selection for manufacturers entering the US market, while the Clinical Laboratory Improvement Amendments establish proficiency testing standards that determine acceptable analytical performance. The EU In Vitro Diagnostic Regulation mandates notified body involvement for class C hematology devices, extending certification cycles for European market access. Stakeholders must monitor evolving harmonization between FDA and IVDR quality management expectations as dual-territory submissions become standard practice for major platform launches.
Market Dynamics
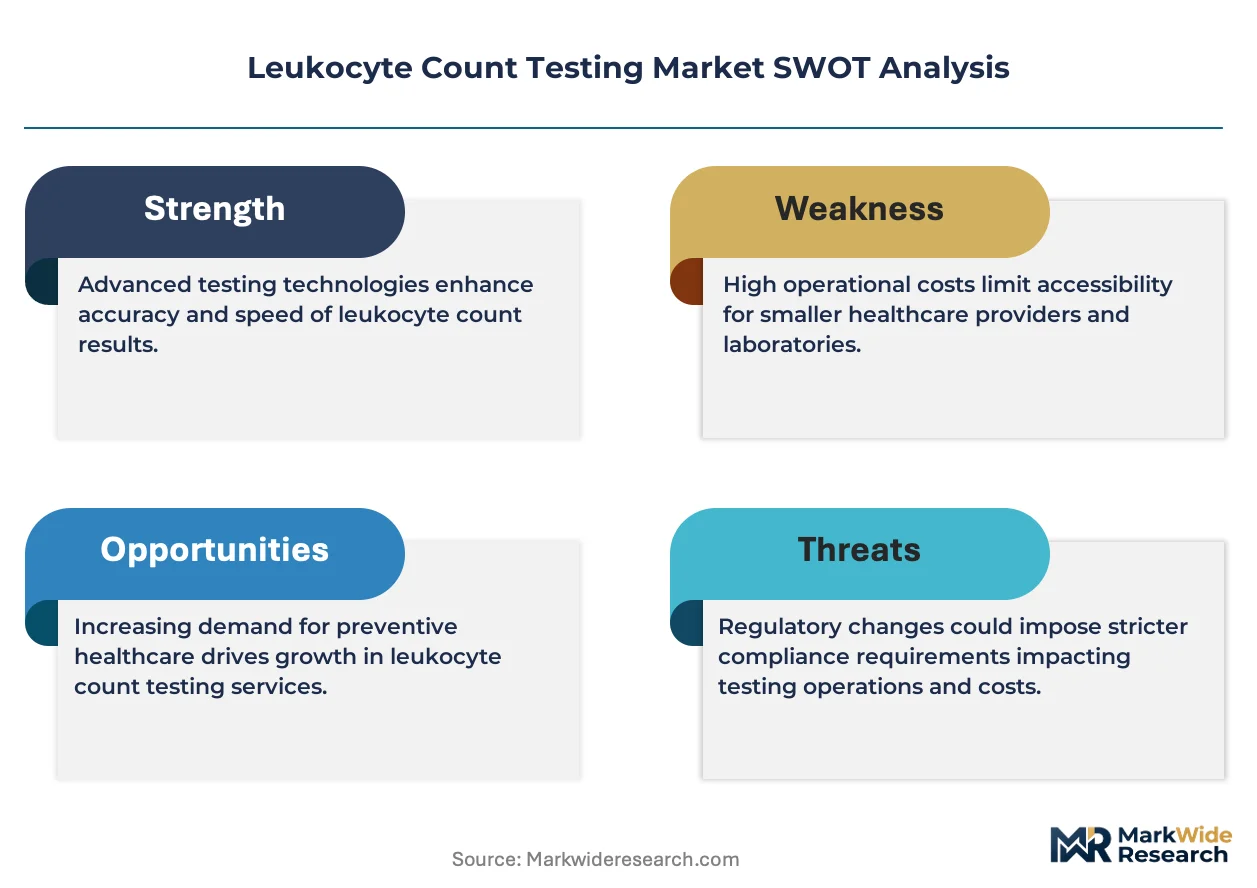
Hospital laboratory consolidation is compressing vendor relationships into multi-year enterprise agreements that bundle hematology analyzers with reagent supply contracts and remote monitoring services.
Growth Catalysts
- Sepsis screening mandates:CMS quality metrics now require rapid leukocyte enumeration for emergency department admissions, forcing hospital systems to deploy automated platforms with sub-30-minute turnaround.
- CLIA proficiency standards:The Clinical Laboratory Improvement Amendments drive replacement cycles for aging analyzers that cannot maintain coefficient of variation below 3% at low leukocyte counts.
- Fluorescence flow cytometry:Research oncology centers demand five-part differential capabilities for minimal residual disease monitoring, expanding the addressable market beyond routine clinical screening.
Market Restraints
- Laser optical component concentration:German and Japanese suppliers control 80% of precision laser diode manufacturing for cytometry modules, exposing instrument makers to single-source supply risk.
- EU IVDR certification timelines:The In Vitro Diagnostic Regulation mandates notified body review for class C hematology devices, extending European market entry by 12-18 months compared to FDA 510(k) pathways.
- Point-of-care accuracy limitations:Impedance-based handheld devices demonstrate elevated false-positive rates at leukocyte counts below 2,000/μL, restricting their utility in neutropenic patient monitoring.
Strategic Opportunities
- India's district hospital network:The country's PLI scheme for medical devices incentivizes local assembly of mid-throughput analyzers serving 700+ district-level laboratories under Ayushman Bharat.
- AI-assisted morphology review:Deep learning algorithms trained on digital cell images are converging with automated analyzers to reduce manual slide review rates from 15% to under 5% of samples.
- Home-based chemotherapy monitoring:Remote leukocyte testing through finger-prick microsampling and mail-in cartridges addresses the 40% of oncology patients residing beyond 50 miles of infusion centers.
Industry Challenges
- Field service engineer scarcity:Vendors struggle to recruit technicians capable of calibrating multi-laser optical benches and troubleshooting hydrodynamic focusing systems in distributed hospital networks.
- LIS integration complexity:Legacy laboratory information systems in mid-sized hospitals lack HL7 FHIR compatibility, requiring costly middleware development for analyzer connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leukocyte Count Testing Market |
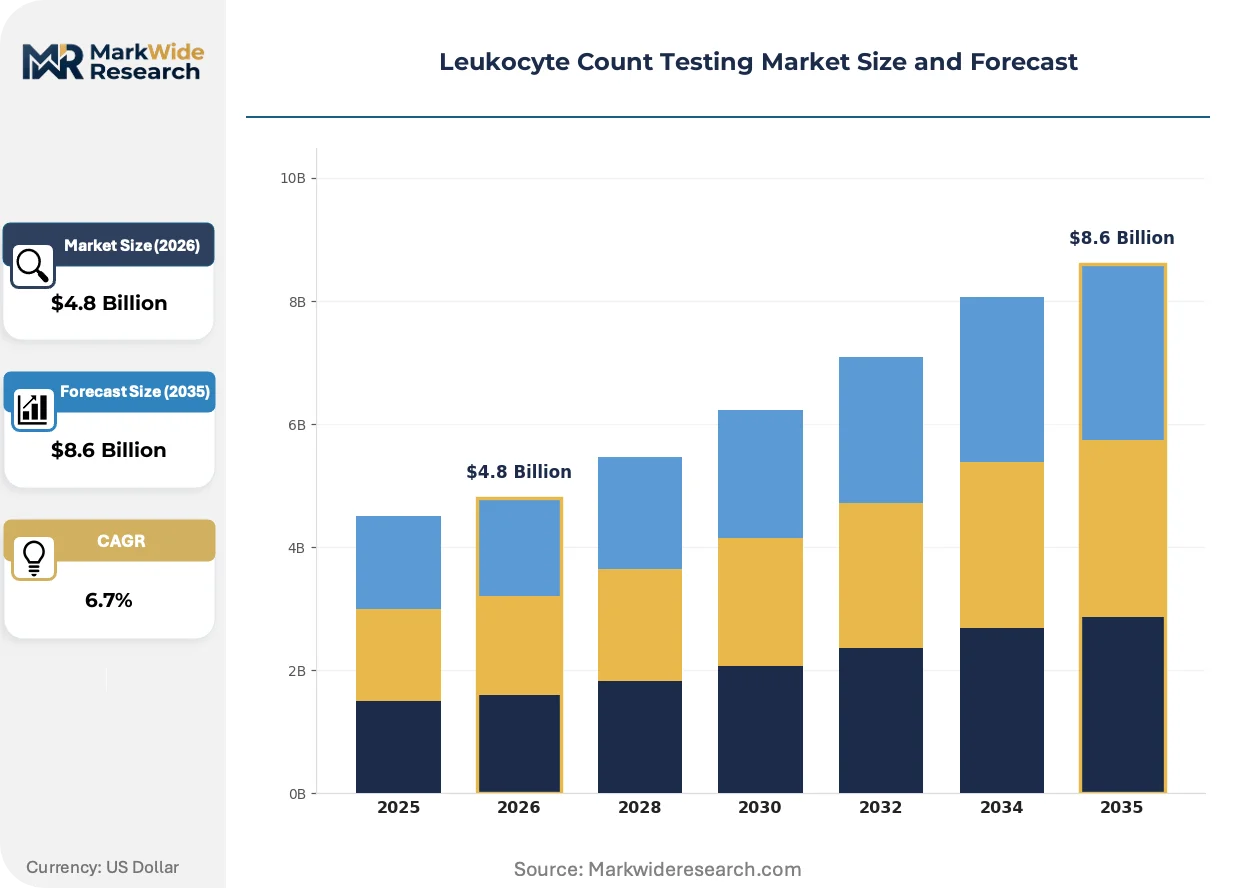
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Analyzers, Manual Count Methods, Point-of-Care Devices, Hemocytometers End User: Hospitals, Clinics, Diagnostic Laboratories, Home Healthcare Technology: Flow Cytometry, Microscopy, Immunoassays, Electrical Impedance Application: Infection Detection, Disease Management, Research Studies, Routine Check-Ups |
| Companies Covered | Hemocue, Sysmex Corporation, Abbott Laboratories, Siemens Healthineers, Beckman Coulter, Mindray, Radiometer Medical ApS, Erma Inc., Shenzhen Prokan Electronics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leukocyte Count Testing Market Evolving Landscape
Multi-parameter light scatter detection architectures are displacing single-angle impedance methods as the dominant technical platform for leukocyte differentiation in high-volume laboratories.
Fluorescence flow cytometry is consolidating research-grade multiparametric capabilities into clinical analyzers previously limited to three-part differentials. Academic medical centers in the United States are deploying these platforms for simultaneous leukocyte enumeration and CD4+ T-cell quantification in HIV monitoring workflows. The technology is consolidating previously separate instrument purchases into single-platform capital decisions, compressing vendor addressable market expansion.
The EU In Vitro Diagnostic Regulation is mandating clinical performance studies for novel hematology parameters that previously qualified under self-certification. Manufacturers must now submit prospective data demonstrating diagnostic accuracy for immature granulocyte reporting and nucleated red blood cell enumeration. European reference laboratories are delaying procurement decisions until 2026 as vendors complete IVDR technical documentation for extended parameter menus.
Integrated delivery networks are unbundling reagent contracts from analyzer placement agreements to pursue competitive bidding for consumable supply. Hospital procurement departments in Texas and California are separating capital equipment financing from per-test reagent pricing, enabling multi-vendor sourcing strategies. This restructuring is most visible in systems operating 15+ laboratory sites where volume aggregation justifies dedicated supply chain personnel.
Leukocyte Count Testing Market Segmentation
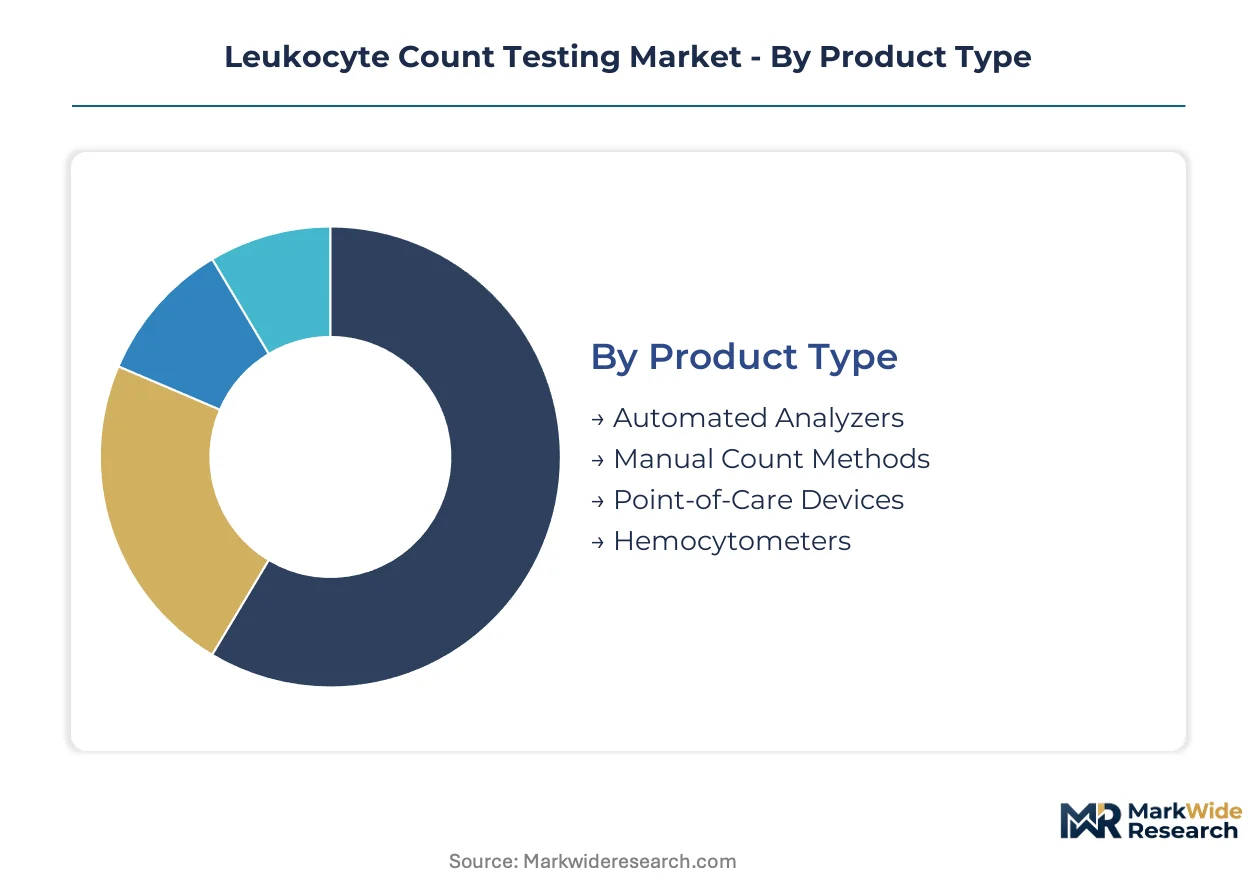
Leukocyte count testing segments diverge sharply by integration depth, with standalone hospital analyzers commanding capital budgets while embedded point-of-care systems penetrate ambulatory workflows. Understanding these structural divisions clarifies where vendors must build service infrastructure versus where portable formats capture volume.
Product Type:
Standalone analyzers dominate integrated health networks, while embedded cartridge systems penetrate distributed care settings.
- Automated Analyzers:High-throughput platforms process 100+ samples hourly using hydrodynamic focusing and multi-parameter light scatter detection. Hospital laboratories in the United States standardize these across multi-site networks to meet CMS sepsis screening mandates requiring sub-30-minute turnaround.
- Point-of-Care Devices:Handheld impedance-based units deliver results under 15 minutes from finger-prick samples. Emergency departments deploy these for triage decisions, though accuracy limitations below 2,000/μL restrict utility in neutropenic monitoring.
- Manual Count Methods:Microscopy-based techniques persist in resource-constrained settings lacking maintenance infrastructure for automated platforms.
- Hemocytometers:Glass chamber devices serve educational institutions and backup verification roles in small clinical laboratories.
Volume placements concentrate in automated analyzers; the faster expansion belongs to point-of-care devices.
End User:
Cost tiers separate capital-intensive hospital installations from leaner clinic and home-based formats.
- Hospitals:Enterprise agreements bundle analyzers with reagent supply contracts and remote monitoring services. Consolidated US health systems leverage 15+ site networks to negotiate unbundled consumable pricing separate from equipment financing.
- Diagnostic Laboratories:Reference laboratories process thousands of samples daily, demanding coefficient of variation below 3% at normal ranges. CLIA proficiency standards drive replacement cycles for aging equipment.
- Clinics:Mid-throughput requirements favor compact analyzers with simplified maintenance protocols.
- Home Healthcare:Remote chemotherapy monitoring through mail-in microsampling cartridges addresses oncology patients residing beyond 50 miles of infusion centers.
Capital deployment concentrates in hospitals; the steepest expansion trajectory runs through home healthcare.
Technology:
Application maturity separates research-grade multiparametric methods from routine clinical enumeration.
- Flow Cytometry:Fluorescence-based systems achieve five-part differential capabilities for minimal residual disease monitoring. Academic medical centers deploy these for simultaneous leukocyte enumeration and CD4+ T-cell quantification in HIV workflows.
- Electrical Impedance:Coulter principle analyzers dominate high-volume screening with proven reliability and lower per-test costs.
- Microscopy:Manual morphological review persists for abnormal flag verification, though AI-assisted algorithms are reducing slide review rates from 15% to under 5%.
- Immunoassays:Antibody-based detection serves specialized research applications requiring specific leukocyte subset identification.
Installed base concentrates in electrical impedance; the technology gaining share fastest is flow cytometry.
Application:
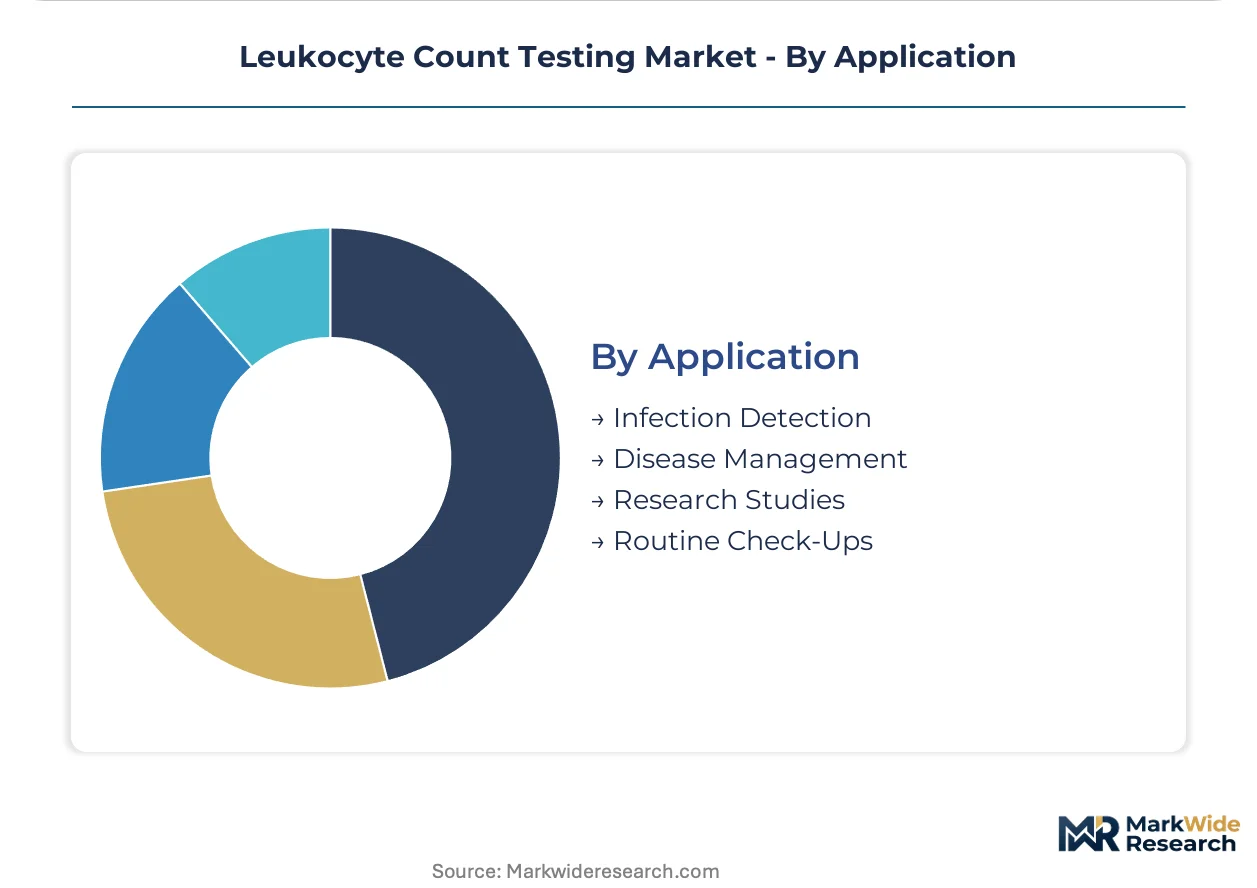
Customer workflows differentiate acute intervention from longitudinal monitoring and investigative use.
- Infection Detection:Emergency department sepsis screening drives demand for rapid turnaround platforms. CMS quality metrics now mandate leukocyte enumeration for admissions, forcing system-wide analyzer deployment.
- Disease Management:Chemotherapy monitoring requires precise tracking of neutropenic thresholds. Oncology centers demand consistent low-count precision that handheld devices often fail to deliver.
- Routine Check-Ups:Annual physical examinations generate steady volume for hospital outpatient laboratories.
- Research Studies:Immature granulocyte and nucleated red blood cell enumeration face new EU IVDR clinical performance study requirements, delaying European procurement decisions.
Test volume concentrates in infection detection; the application climbing the fastest is disease management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision laser diodes from Japanese and German suppliers anchor the geographic distribution of leukocyte testing instrument manufacturing. Health system consolidation and regulatory pathway divergence are reshaping procurement patterns across major national markets.
United States
Integrated delivery networks in Texas and California are unbundling reagent contracts from analyzer placements to enable multi-vendor sourcing strategies. FDA 510(k) clearance timelines for novel electrical impedance platforms are accelerating under updated pathway guidance. The Greater Boston cluster houses reference laboratories demanding coefficient of variation below 3% for high-volume sepsis screening mandated by CMS quality metrics.
Germany
Precision laser diode suppliers in German industrial centers control critical cytometry module components for instrument makers worldwide. EU IVDR mandates for class C hematology devices are extending certification cycles and delaying European procurement decisions until 2026. The Bavaria region concentrates reference laboratory operations awaiting IVDR technical documentation for immature granulocyte reporting capabilities.
Japan
Fluorescence flow cytometry installed bases sustain recurring reagent revenue streams across hospital networks. PMDA regulatory alignment with international standards facilitates domestic market access for multi-parameter analyzers. The Kanto region around Tokyo anchors manufacturing of hydrodynamic focusing systems serving Asia-Pacific distribution channels.
India
Ayushman Bharat's district hospital network is expanding demand for mid-throughput analyzers serving 700+ laboratories. The PLI scheme for medical devices incentivizes local assembly to reduce import dependence for hematology platforms. Maharashtra and Gujarat are emerging as assembly hubs for instruments targeting tier-2 and tier-3 healthcare facilities.
China
Domestic manufacturers are penetrating mid-throughput segments previously dominated by imported platforms. NMPA regulatory harmonization with international standards is streamlining approval pathways for novel hematology parameters. The Yangtze River Delta cluster concentrates production of electrical impedance modules for both domestic consumption and export markets.
Leukocyte Count Testing Market Competitive Landscape
Global majors compete with regional champions across regulatory pathway expertise and installed base maintenance capabilities. The vendor landscape exhibits tiered concentration with premium fluorescence flow cytometry systems, mid-range impedance analyzers, and point-of-care handheld formats occupying distinct competitive bands. Three archetypes dominate: integrated diagnostics conglomerates with multi-modality portfolios, hematology-specialized instrument makers with deep reagent ecosystems, and emerging regional assemblers leveraging local manufacturing incentives. Competitive moves center on unbundling reagent supply contracts from equipment financing and deploying AI-assisted morphology review to reduce manual slide review rates.
Within the integrated diagnostics tier, Siemens Healthineers and Abbott Laboratories exemplify multi-modality platform strategies spanning hospital laboratory and point-of-care environments. Sysmex Corporation occupies a position as a hematology-specialized incumbent with fluorescence flow cytometry expertise. Among emerging regional assemblers, Mindray and Shenzhen Prokan Electronics Inc. represent Chinese manufacturers capturing mid-throughput segments through cost-optimized production and proximity to Asia-Pacific demand centers.
| Leading Market Players |
|---|
| Hemocue |
| Sysmex Corporation |
| Abbott Laboratories |
| Siemens Healthineers |
| Beckman Coulter |
| Mindray |
| Radiometer Medical ApS |
| Erma Inc. |
| Shenzhen Prokan Electronics Inc. |
| Others |
Value Network & Pricing Analysis
Integrated delivery networks operating 15-plus laboratory sites concentrate procurement leverage, driving three-tier pricing structure across premium fluorescence flow cytometry, standard electrical impedance platforms, and economy point-of-care formats. Their unbundling of reagent contracts from analyzer financing reshapes how vendors structure lifetime value capture across hardware and consumable revenue streams.
Pricing Analysis
Warranty and service bundling separates enterprise agreements from transactional sales, with multi-year remote monitoring contracts commanding 15-20% price premiums over bare equipment leases. Price differentiation hinges on CLIA proficiency certification tier and analyzer throughput capacity, with reference laboratories least sensitive due to quality mandates while district hospital networks in emerging markets prioritize capital efficiency. Cost compression in mid-throughput segments intensifies as Chinese manufacturers penetrate price points previously dominated by Japanese and German incumbents.
Supply Chain Analysis
Direct-to-hospital channels handle enterprise fleet deployments, while distributor networks serve smaller clinical laboratories and ambulatory settings. Precision laser diode manufacturing concentrates in Germany and Japan, with hydrodynamic focusing module assembly centered in Japan's Kanto region and China's Yangtze River Delta. Single-source dependency on German and Japanese optical component suppliers exposes instrument makers to tariff and logistics disruption risks. Distribution runs through regional service hubs maintaining field engineer density for calibration and maintenance protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where EU IVDR clinical performance study requirements for novel hematology parameters erect substantial barrier-to-entry moats favoring established players with regulatory affairs infrastructure.
For Market Incumbents: To counter unbundling pressure from procurement departments at Texas and California health systems, deepen captive supply control over reagent manufacturing and deploy AI-assisted morphology review to reduce manual slide review rates below 5%. Anchor enterprise agreements with remote monitoring services that raise switching costs for integrated delivery networks. For New Entrants and Emerging Players: District hospital laboratories under India's Ayushman Bharat scheme represent the most penetrable buyer archetype, with PLI scheme incentives enabling cost-competitive local assembly against imported platforms. Target mid-throughput electrical impedance segments with simplified maintenance protocols and regional service partnerships bypassing incumbent field engineer networks. For Investors and Strategic Acquirers: The window for entry favors hematology-specialized instrument makers with installed base reagent ecosystems over diversified diagnostics conglomerates. Monitor FDA 510(k) clearance acceleration for novel electrical impedance platforms as signal of regulatory pathway efficiency enabling faster value realization. Long-term viability rests on fluorescence flow cytometry consolidation into clinical analyzers previously limited to three-part differentials.| Strategic Initiative | Industry Significance |
|---|---|
| EU IVDR Technical Documentation Completion | Enables European market access for immature granulocyte reporting capabilities in Bavaria reference laboratories. |
| Reagent Contract Unbundling | Allows Texas and California health systems to pursue competitive bidding for consumable supply separate from equipment financing. |
| AI-Assisted Morphology Review Integration | Reduces manual slide review rates from 15% to under 5% in high-volume hospital laboratories. |
| PLI Scheme Local Assembly | Supports mid-throughput analyzer production in Maharashtra and Gujarat for India's 700-plus district laboratories. |
| Fluorescence Flow Cytometry Platform Consolidation | Combines leukocyte enumeration with CD4+ T-cell quantification for HIV monitoring in academic medical centers. |
Research Methodology
Document review covered FDA 510(k) clearance databases, EU IVDR technical documentation filings, and CMS quality metric specifications, complemented by interviews with hospital laboratory directors, biomedical engineers, GPO contracts managers, and hematology analyzer field service engineers. Secondary sources included hospital procurement databases, CLIA proficiency testing records, and trade data on precision laser diode imports. Bottom-up instrument placement modeling and top-down healthcare expenditure allocation were triangulated against reagent consumption estimates.
Unit economics and installed base projections across the analysis window were generated through segmentation by product type, end user tier, technology platform, and application workflow. CAGRs were derived from regression analysis of historical analyzer placement velocity against sepsis screening mandate adoption curves and chemotherapy monitoring volume growth. Model inputs incorporated CLIA proficiency standard compliance costs, IVDR certification timeline assumptions, and district hospital network expansion under India's Ayushman Bharat.
Revisions become necessary when FDA pathway guidance shifts, EU IVDR notified body capacity constraints ease, or precision laser diode supply concentration disrupts manufacturing continuity. Forecasts reflect base-case assumptions regarding health system consolidation pace and fluorescence flow cytometry clinical adoption timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Addison Disease Testing Market
Testing Services
Rift Valley Fever Testing Market
Testing Services
Arthropod-Borne Viral Infections Testing Market
Testing Services
Activated Partial Thromboplastin Test Market
Testing Services
Influenza a/B Combo Testing Market
Testing Services
Germany Testing, Inspection and Certification Market
Testing Services
Global Molecular Quality Controls Market
Testing Services
Rapid Antigen Testing Market
Testing Services
Chromatin Immunoprecipitation Testing Market
Testing Services
North America Antimicrobial Susceptibility Testing Market
Testing Services
Cerebrospinal Fluid (CSF) Testing Market
Testing Services
Drug Tester Market
Testing Services
Pharmaceutical Analytical Testing Market
Testing Services
Test Strips Market
Testing Services
Global Extractables and Leachables Testing Services Market
Testing Services
Global Legionella Testing Market