
 Anticoagulant Therapeutic Drug Monitoring Assay Kits Market | 2026-2036
Anticoagulant Therapeutic Drug Monitoring Assay Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Anticoagulant Therapeutic Drug Monitoring Assay Kits Market Outlook
Modular assay panel bundling is rebalancing procurement decisions across hospital laboratories. Roche Diagnostics leverages its integrated cobas platform ecosystem to sustain high-volume account retention. Abbott Laboratories anchors its position through handheld point-of-care coagulation devices that reduce turnaround times in critical care settings. Siemens Healthineers competes via automated hemostasis workcells that consolidate pre-analytical and analytical workflows.
Anticoagulant therapeutic drug monitoring assay kits comprise in vitro diagnostic reagents and calibrators that quantify drug concentration or coagulation response, typically employing chromogenic substrate or clot-based detection with analytical sensitivity thresholds below 0.1 IU per milliliter for unfractionated heparin. These products enable clinicians to titrate anticoagulant dosing and prevent thrombotic or hemorrhagic complications in patients on warfarin, direct oral anticoagulants, or heparin therapy. The PT/INR segment maintains the largest installed base due to decades of warfarin standardization, while direct thrombin inhibitor assays capture the fastest expansion as dabigatran and argatroban monitoring protocols proliferate in cardiology and surgery departments. Point-of-care delivery mode penetration is deepening in homecare and clinic settings where patient self-testing programs reduce anticoagulation clinic burden.
The FDA regulates these assay kits as Class II medical devices under 21 CFR 862, requiring 510(k) premarket notification with clinical performance data, while ISO 17511 standardizes metrological traceability of calibrator values across manufacturers. The EU In Vitro Diagnostic Regulation intensifies conformity assessment burdens for CE marking, particularly for novel biomarker claims and software-integrated devices. Stakeholders must monitor evolving pharmacogenomic guidance from the Clinical Pharmacogenetics Implementation Consortium, as CYP2C9 and VKORC1 genotyping integration threatens to displace routine INR monitoring in warfarin-managed populations.
Market Dynamics
Hospital laboratory consolidation is compressing vendor relationships toward integrated platform ecosystems that bundle reagent contracts with analyzer placement agreements, reshaping procurement from discrete assay purchases to multi-year consumable commitments.
Growth Catalysts
- Aging cardiovascular patient pools:Germany, Japan, and the United States sustain elevated testing volumes through expanding warfarin and direct oral anticoagulant patient populations requiring routine PT/INR monitoring.
- CLIA laboratory accreditation standards:The FDA's clinical laboratory improvement amendments tighten analytical performance thresholds, forcing laboratories to upgrade assay precision and driving replacement demand for certified reagent systems.
- Point-of-care expansion:Home-based patient self-testing programs for INR monitoring reduce anticoagulation clinic burden and extend addressable demand beyond hospital settings into ambulatory and retail channels.
Market Restraints
- Reagent supply concentration:Chromogenic substrate manufacturing clusters in Switzerland and Germany create single-source dependencies for critical raw materials used in thrombin inhibitor assays.
- Pharmacogenomic substitution threat:CYP2C9 and VKORC1 genotyping integration threatens to displace routine INR monitoring in warfarin-managed populations as precision dosing protocols mature.
- EU IVDR compliance burden:The In Vitro Diagnostic Regulation intensifies conformity assessment requirements for CE marking, extending time-to-market for novel biomarker claims and software-integrated devices.
Strategic Opportunities
- Direct thrombin inhibitor assay white space:Dabigatran and argatroban monitoring protocols proliferate in cardiology and surgery departments, outpacing installed base expansion for traditional PT/INR segments.
- Automated hemostasis workcell consolidation:Pre-analytical and analytical workflow integration creates upgrade pathways for mid-volume laboratories seeking labor efficiency gains.
- ISO 15189 quality management adoption:Medical laboratories pursuing international accreditation drive demand for metrologically traceable calibrator systems and vendor-supported quality control programs.
Industry Challenges
- Specialized coagulation technologist scarcity:Hospital laboratories face recruitment gaps for personnel trained in chromogenic substrate interpretation and heparin anti-Xa assay troubleshooting.
- Legacy analyzer integration complexity:Third-party assay kit validation on non-native instrument platforms demands extensive bridging studies and software compatibility verification.
- Multi-site standardization friction:Health system networks struggle to harmonize reference ranges and quality control protocols across distributed laboratory locations using mixed vendor ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anticoagulant Therapeutic Drug Monitoring Assay Kits Market |
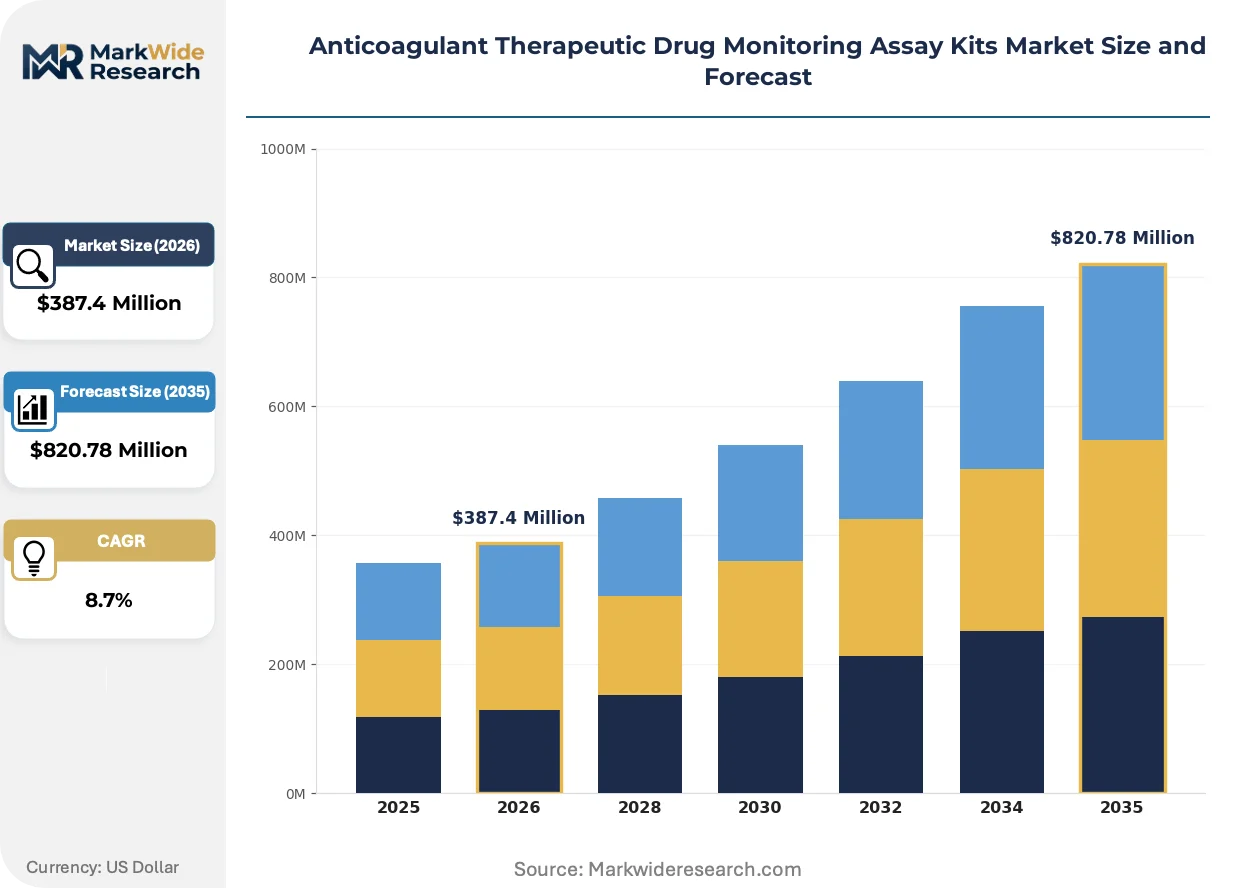
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $820.78 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IFCC, PT/INR, aPTT, Direct Thrombin Inhibitors Application: Cardiology, Hematology, Surgery, Critical Care End User: Hospitals, Laboratories, Clinics, Homecare Delivery Mode: Point-of-Care, Laboratory-Based, Remote Monitoring, Telehealth |
| Companies Covered | Roche Diagnostics, Thermo Fisher Scientific, Abbott Laboratories, Siemens Healthineers, Bio-Rad Laboratories, Sysmex Corporation, Helena Laboratories, Instrumentation Laboratory, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anticoagulant Therapeutic Drug Monitoring Assay Kits Market Strategic Shifts
Assay architecture is fragmenting from monolithic test panels toward configurable module combinations that laboratories assemble based on patient mix and throughput requirements, compressing the traditional one-size-fits-all reagent model.
Multiplexed chromogenic substrate technology is modularizing across high-volume hospital laboratories seeking to consolidate heparin, direct thrombin inhibitor, and DOAC assays onto single analyzer footprints. Academic medical centers in the United States and university hospitals in Germany are adopting these configurations fastest, typically replacing standalone specialty analyzers within 18-month capital cycles. This consolidation is modularizing vendor relationships into platform-centric partnerships that lock in consumable volumes through multi-year reagent rental agreements.
The EU In Vitro Diagnostic Regulation is tightening post-market surveillance obligations and performance documentation requirements for Class C devices including coagulation assays. Manufacturers must now maintain systematic vigilance data and annual safety reports that extend regulatory affairs staffing by 30-40% for CE-marked portfolios. Smaller IVD firms with limited hemostasis portfolios are withdrawing from the European market rather than absorbing compliance costs, concentrating supply among integrated diagnostics conglomerates with dedicated regulatory infrastructure.
Health system procurement departments are unbundling service contracts from reagent supply agreements, separating analyzer maintenance from consumable purchasing to improve cost transparency. Integrated delivery networks in the United States and hospital groups in Japan are driving this disintermediation, using third-party service organizations for instrument upkeep while negotiating direct reagent pricing. This bifurcation is most visible in high-throughput coagulation laboratories where annual consumable spend exceeds $500,000 and procurement leverage justifies dedicated sourcing personnel.
Anticoagulant Therapeutic Drug Monitoring Assay Kits Market Segmentation
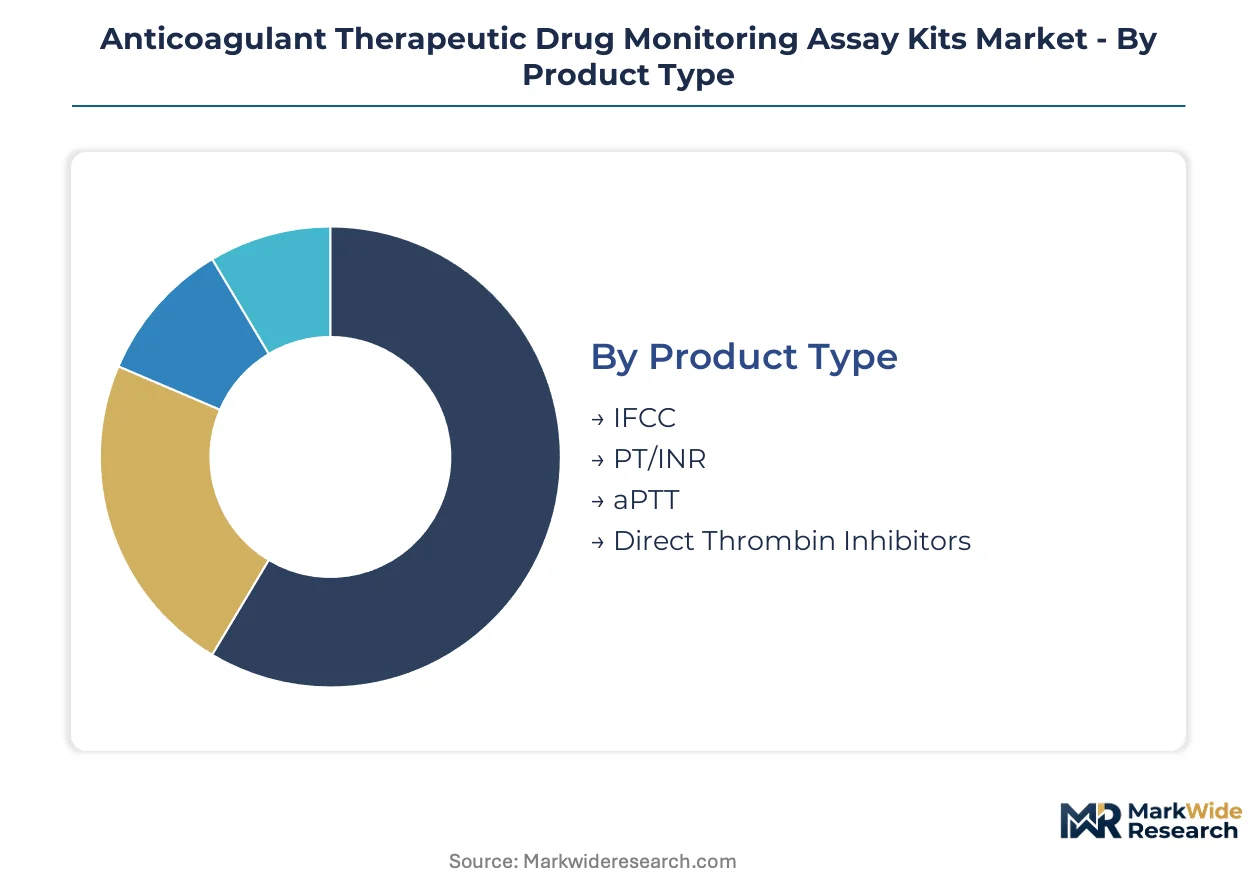
Anticoagulant monitoring assay segmentation reflects divergent clinical workflows across acute care and ambulatory settings. Product architecture, delivery mode, and end-user infrastructure each impose distinct technical specifications and procurement criteria.
Product Type:
Laboratory directors prioritize analytical precision thresholds and regulatory certification status when selecting assay formats for their hemostasis portfolios.
- PT/INR:Clot-based prothrombin time assays calibrated against WHO international reference thromboplastin. Hospital laboratories in the United States and Germany maintain the largest installed bases due to decades of warfarin standardization and CLIA-mandated quality control protocols.
- Direct Thrombin Inhibitors:Chromogenic substrate assays quantifying dabigatran, argatroban, and bivalirudin activity with sub-nanomolar sensitivity. Cardiology departments at academic medical centers drive fastest uptake as direct oral anticoagulant monitoring protocols displace empirical dosing.
- IFCC:Standardized calibrator systems ensuring metrological traceability across manufacturer platforms. Reference laboratories and ISO 15189-accredited facilities require these for inter-laboratory harmonization programs.
- aPTT:Activated partial thromboplastin time reagents for unfractionated heparin therapeutic monitoring. Surgical suites and intensive care units rely on rapid turnaround variants for perioperative anticoagulation management.
Volume sits with PT/INR; growth tilts toward Direct Thrombin Inhibitors.
Application:
Clinical specialty dictates assay throughput requirements, turnaround time tolerances, and integration complexity with electronic medical record systems.
- Cardiology:High-frequency monitoring of atrial fibrillation patients on warfarin or DOAC therapy. Electrophysiology labs require bidirectional LIS connectivity and automated result flagging for supratherapeutic ranges.
- Critical Care:Stat heparin anti-Xa and aPTT testing for ECMO and CRRT patients. German and Japanese tertiary hospitals are consolidating these assays onto automated hemostasis workcells to reduce manual sample handling.
- Surgery:Perioperative coagulation assessment for patients bridging anticoagulation. Pre-operative clinics favor point-of-care INR devices to streamline same-day procedure scheduling.
- Hematology:Specialized coagulation factor assays and lupus anticoagulant detection. Academic referral centers maintain dedicated hemostasis sections with PhD-level technical supervision.
Critical Care commands the highest per-patient test frequency; Cardiology delivers the largest absolute test volume.
End User:
Capital availability and reimbursement pathways segment procurement behavior across institutional settings.
- Hospitals:Integrated delivery networks negotiate multi-year reagent rental agreements tied to analyzer placement. United States health systems exceeding 10 hospitals centralize hemostasis standardization through single-vendor contracts.
- Homecare:Patient self-testing programs for INR monitoring using FDA-cleared handheld devices. Medicare reimbursement for home prothrombin time testing sustains demand among anticoagulation clinics seeking to reduce face-to-face visit burden.
- Laboratories:Commercial reference labs and hospital outreach programs processing specimens from affiliated clinics. ISO 15189 accreditation drives demand for vendor-supported external quality assessment participation.
- Clinics:Anticoagulation management centers in cardiology and internal medicine practices. German hausarzt practices and Japanese clinic chains are adopting compact point-of-care coagulometers for same-visit dosing adjustments.
Hospitals anchor current revenue; Homecare exhibits the steepest expansion trajectory.
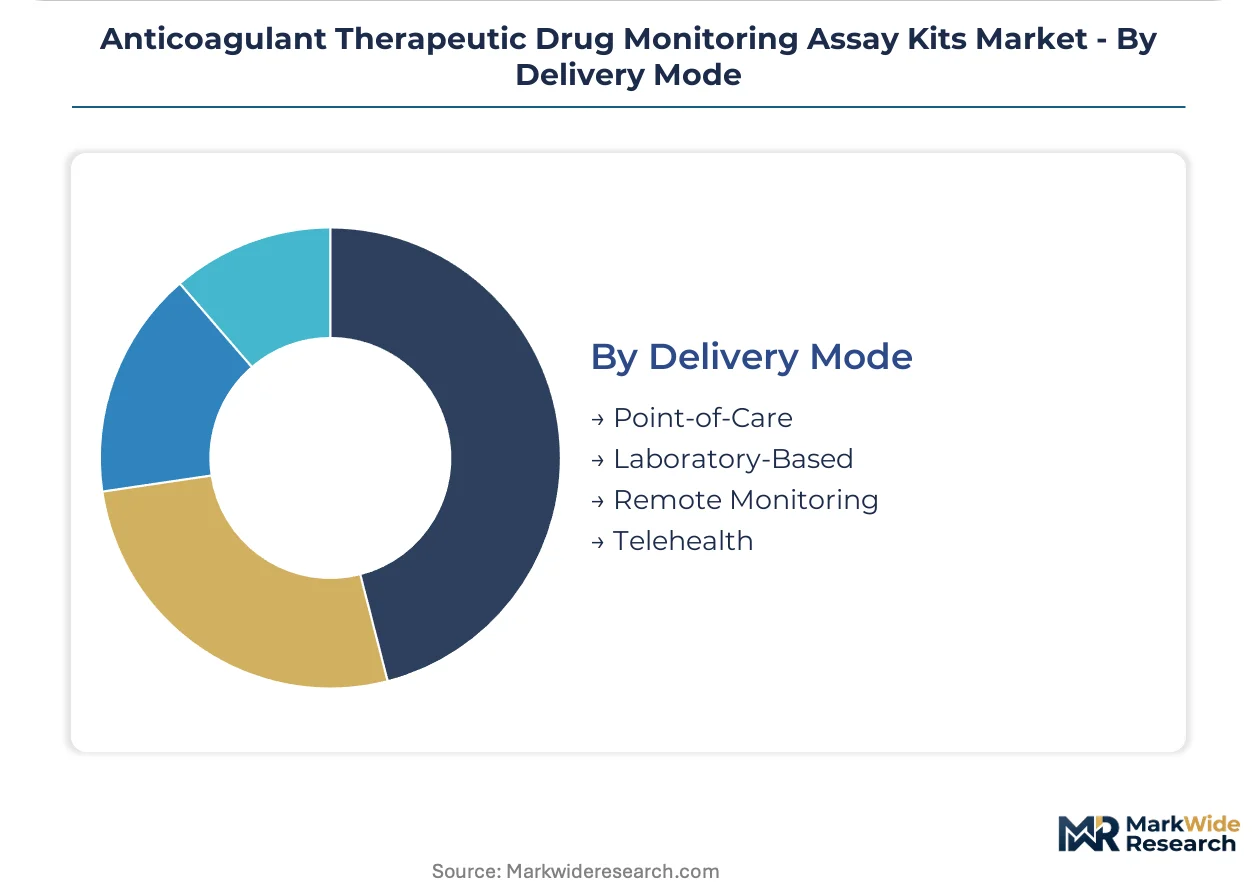
Delivery Mode:
Workflow centralization versus decentralization determines platform selection and service contract structure.
- Laboratory-Based:High-throughput analyzers with automated sample handling and reflex testing algorithms. Core laboratories process 200-400 coagulation specimens daily using consolidated hemostasis workcells.
- Point-of-Care:Handheld or compact benchtop devices for stat testing outside central labs. Critical care units and catheterization laboratories prioritize 2-5 minute turnaround over analytical precision.
- Telehealth:Remote result transmission from home testing devices to centralized monitoring services. United States anticoagulation clinics leverage these platforms for rural patient management.
- Remote Monitoring:Cloud-connected devices with automated dosing algorithm integration. Emerging configurations link patient-generated INR data directly to electronic medical records with clinician alert protocols.
Laboratory-Based systems retain the dominant installed base; Point-of-Care penetration deepens fastest in cardiology and critical care settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chromogenic substrate manufacturing clusters in Switzerland and Germany supply precision reagents to laboratories worldwide, while demand concentrates in aging populations across the United States, Germany, and Japan where cardiovascular disease prevalence sustains testing volumes.
United States
Medicare reimbursement for home prothrombin time testing expands patient self-testing programs beyond anticoagulation clinics. The FDA's clinical laboratory improvement amendments tighten analytical performance thresholds for PT/INR assays. Academic medical centers in Boston and the Mayo Clinic network drive adoption of multiplexed chromogenic substrate configurations.
Germany
University hospitals in Heidelberg and Munich consolidate heparin anti-Xa and direct thrombin inhibitor assays onto automated hemostasis workcells. The national medical devices regulator, BfArM, enforces stringent post-market surveillance under EU IVDR transition timelines. Baden-Württemberg's industrial corridor hosts precision substrate manufacturing for export to European reference laboratories.
Japan
Aging demographics and atrial fibrillation prevalence sustain elevated PT/INR testing volumes in Tokyo and Osaka metropolitan hospitals. PMDA guidance documents harmonize with ISO 15189 quality management standards for medical laboratories. The Kansai region's diagnostic reagent suppliers specialize in calibrator systems for inter-laboratory harmonization programs.
Switzerland
Specialized chromogenic substrate production concentrates in Basel and Zurich for global supply to thrombin inhibitor assay manufacturers. Swissmedic maintains rigorous conformity assessment procedures for Class C in vitro diagnostic devices. The country's precision chemical sector supplies critical raw materials with limited alternative sourcing.
United Kingdom
NHS England's pathology consolidation program drives multi-site standardization across distributed laboratory networks. The MHRA oversees UKCA marking requirements post-Brexit for hemostasis assay kits. London teaching hospitals and the Oxford-Cambridge corridor anchor demand for metrologically traceable calibrator systems.
Anticoagulant Therapeutic Drug Monitoring Assay Kits Market Competitive Environment
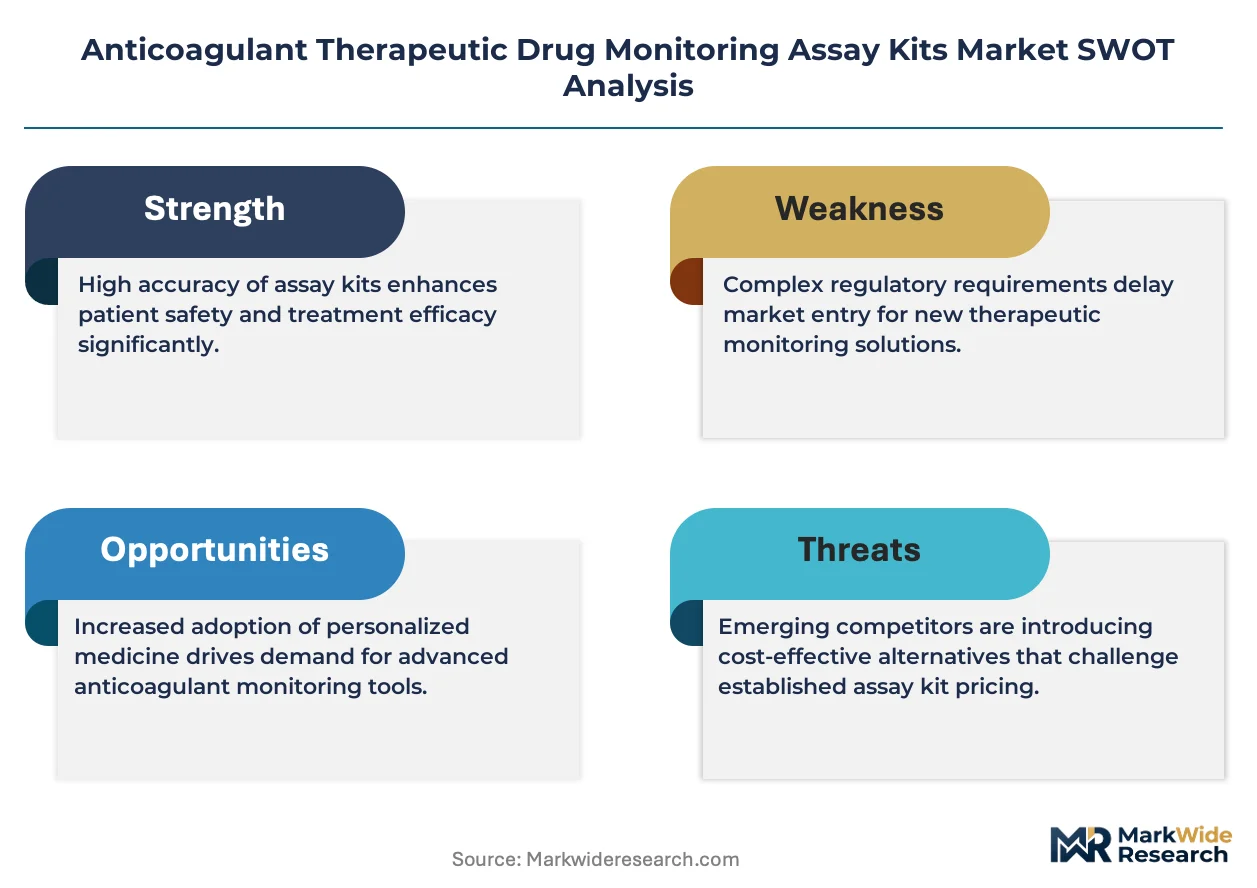
Diversified conglomerates compete with focused pure-play specialists across platform-centric and modular assay segments. The vendor structure tilts toward integrated diagnostics conglomerates with dedicated regulatory infrastructure capable of absorbing EU IVDR compliance burdens. Three archetypes dominate: integrated platform ecosystem providers, handheld point-of-care device specialists, and automated hemostasis workcell manufacturers. Competitive moves concentrate on multi-year reagent rental agreements and service contract unbundling to improve procurement transparency.
Among diversified diagnostics conglomerates, Roche Diagnostics and Abbott Laboratories exemplify platform-centric strategies, while Siemens Healthineers occupies a position emphasizing automated workflow consolidation. These three anchors represent divergent responses to laboratory procurement centralization, with each embedding consumable commitments within analyzer placement agreements to defend account relationships against modular competitors.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Thermo Fisher Scientific |
| Abbott Laboratories |
| Siemens Healthineers |
| Bio-Rad Laboratories |
| Sysmex Corporation |
| Helena Laboratories |
| Instrumentation Laboratory |
| Danaher Corporation |
| Others |
Value Chain & Pricing Dynamics
Specialized coagulation technologist scarcity in the United States and Germany widens pricing-tier spreads between premium certified assays and economy alternatives, as labor-cost differentials for chromogenic substrate interpretation compound reagent pricing power.
Pricing Analysis
Price erosion across economy-grade PT/INR reagents traces to unbundled service contracts and third-party maintenance competition in high-throughput United States health systems. Three-tier pricing structure across premium, standard, and economy levels separates ISO 15189-accredited calibrator systems from CLIA-minimum alternatives. Certification-grade differentiation and volume-scale procurement leverage drive spreads. Hospital laboratories exceeding 10 sites command steepest discounts through multi-year reagent rental agreements, while standalone clinics absorb premium markups for point-of-care consumables.
Supply Chain Analysis
Dual-sourcing mandates from United States hospital procurement departments force manufacturers to qualify secondary chromogenic substrate suppliers beyond Basel and Zurich clusters. Raw material dependencies center on synthetic peptide substrates, recombinant thrombin preparations, and WHO-traceable reference plasma. Single-source vulnerability concentrates in Swiss precision chemical production for sub-nanomolar sensitivity reagents. Distribution runs through regional diagnostic distributors with cold-chain logistics for calibrator stability, anchored by direct contracts for integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anticoagulant therapeutic drug monitoring assay kits market is becoming a vertical-integration race, with manufacturers pursuing captive control over chromogenic substrate production to defend margin structures against raw material cost volatility.
For Market Incumbents: Deepen backward integration into synthetic peptide substrate manufacturing to offset Swiss supply concentration risks. Consolidate analyzer placement agreements with multi-year consumable lock-ins before EU IVDR compliance costs drive smaller competitors from European markets. Pharmacogenomic substitution for warfarin monitoring threatens PT/INR volumes; accelerate direct thrombin inhibitor assay development to capture cardiology department expansion. For New Entrants and Emerging Players: EU IVDR in Europe opens a window for regulatory-native entrants to capture share as diversified conglomerates absorb extended conformity assessment timelines. Target mid-volume German and Japanese hospital laboratories seeking automated hemostasis workcell alternatives to Siemens and Roche ecosystems. Pursue ISO 15189 quality management partnership programs as differentiated service layer beyond commodity reagent supply. For Investors and Strategic Acquirers: The window for entry favors precision chemistry specialists with chromogenic substrate expertise and established ISO 17511 metrological traceability protocols. Long-term viability hinges on regulatory infrastructure capable of sustaining post-market surveillance obligations under tightening FDA and EU frameworks. Watch pharmacogenomic guideline adoption from the Clinical Pharmacogenetics Implementation Consortium as volume displacement signal for traditional INR monitoring segments.| Strategic Initiative | Industry Significance |
|---|---|
| Chromogenic Substrate Backward Integration | Captive supply of synthetic peptides reduces dependency on Swiss chemical manufacturers and stabilizes input costs. |
| EU IVDR Conformity Assessment Investment | Dedicated regulatory affairs infrastructure extends CE-marked portfolio access as smaller competitors withdraw. |
| Point-of-Care Reimbursement Strategy | Medicare home prothrombin time coverage in the United States expands addressable demand beyond hospital settings. |
| Automated Hemostasis Workcell Development | Pre-analytical integration captures mid-volume laboratory upgrade cycles in Germany and Japan. |
| Pharmacogenomic Companion Positioning | CYP2C9 and VKORC1 testing capabilities hedge against INR monitoring displacement in warfarin populations. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with hospital laboratory directors, hemostasis section supervisors, diagnostic reagent procurement managers, and biomedical engineers at academic medical centers. FDA 510(k) premarket notification databases, ISO 15189 accreditation registries, EU IVDR technical documentation, and Medicare reimbursement schedules provided validation benchmarks. Bottom-up assay kit volume estimates triangulated against top-down cardiovascular disease prevalence projections.
Reconciliation of manufacturer shipment data, hospital laboratory purchasing records, and distributor inventory flows informed the analytical framework across the projection horizon. Segmentation modeling incorporated product type, delivery mode, end-user infrastructure, and regional regulatory cluster dimensions. CAGRs derived from logarithmic trend fitting of historical volume trajectories, adjusted for CLIA laboratory accreditation expansion and point-of-care penetration curves.
The model assumes a particular technology adoption path; alternative pathways for pharmacogenomic-guided warfarin dosing would alter the outlook for PT/INR assay demand. Deviation in EU IVDR enforcement timelines or FDA clinical laboratory improvement amendment revisions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Europe Point-Of-Care-Testing (POCT) Market
Testing Services
North America and Europe Preclinical Medical Device Testing Services Market
Testing Services
Global Metabolic Testing Market
Testing Services
Biomarker Testing Services Market
Testing Services
Global at-Home Drug of Abuse (DOA) Testing Market
Testing Services
Antibiotic Susceptibility Testing Market
Testing Services
Global IVD Regulatory Affairs Outsourcing Market
Testing Services
Pneumococcal Testing Market
Testing Services
Sterilization Monitoring Technologies Market
Testing Services
US & Europe Extractable and Leachable Testing Services Market
Testing Services
Cholesterol Test Market
Testing Services
US Pharmaceutical Sterility Testing Market
Testing Services
Aerospace and Life Science Testing Certification Market
Testing Services
Ovulation Testing Kits Market
Testing Services
Pharmaceutical Analytical Testing Outsourcing Market
Testing Services
Urine Testing Cups Market