
 US Tendon Repair Market | 2026-2036
US Tendon Repair Market Size, Share, and Industry Trends Forecast 2026-2036
US Tendon Repair Market Intelligence
Biologic scaffold engineering is reshaping tendon repair by enabling cell-seeded grafts that integrate with native collagen architecture. Stryker leverages its orthobiologics platform to anchor hospital supply contracts across the Sun Belt. Arthrex, Inc. sustains R&D intensity in all-inside arthroscopic systems that reduce OR time. Integra LifeSciences specializes in regenerative matrices that differentiate its portfolio in rotator cuff applications.
Tendon repair encompasses surgical restoration of disrupted collagenous connective tissue linking muscle to bone, typically employing braided polyethylene sutures with tensile strength exceeding 50 pounds and knotless anchor fixation to reapproximate torn ends under physiologic tension. The primary purpose is restoring load-bearing capacity to affected extremities. Orthobiologics leads product type revenue as platelet-rich plasma and amniotic membrane grafts command premium positioning in sports medicine. Arthroscopic surgery dominates technology adoption given its minimally invasive profile and ambulatory surgical center compatibility. Reconstructive surgery application segments concentrate margin pools where complex multi-tendon injuries require staged interventions.
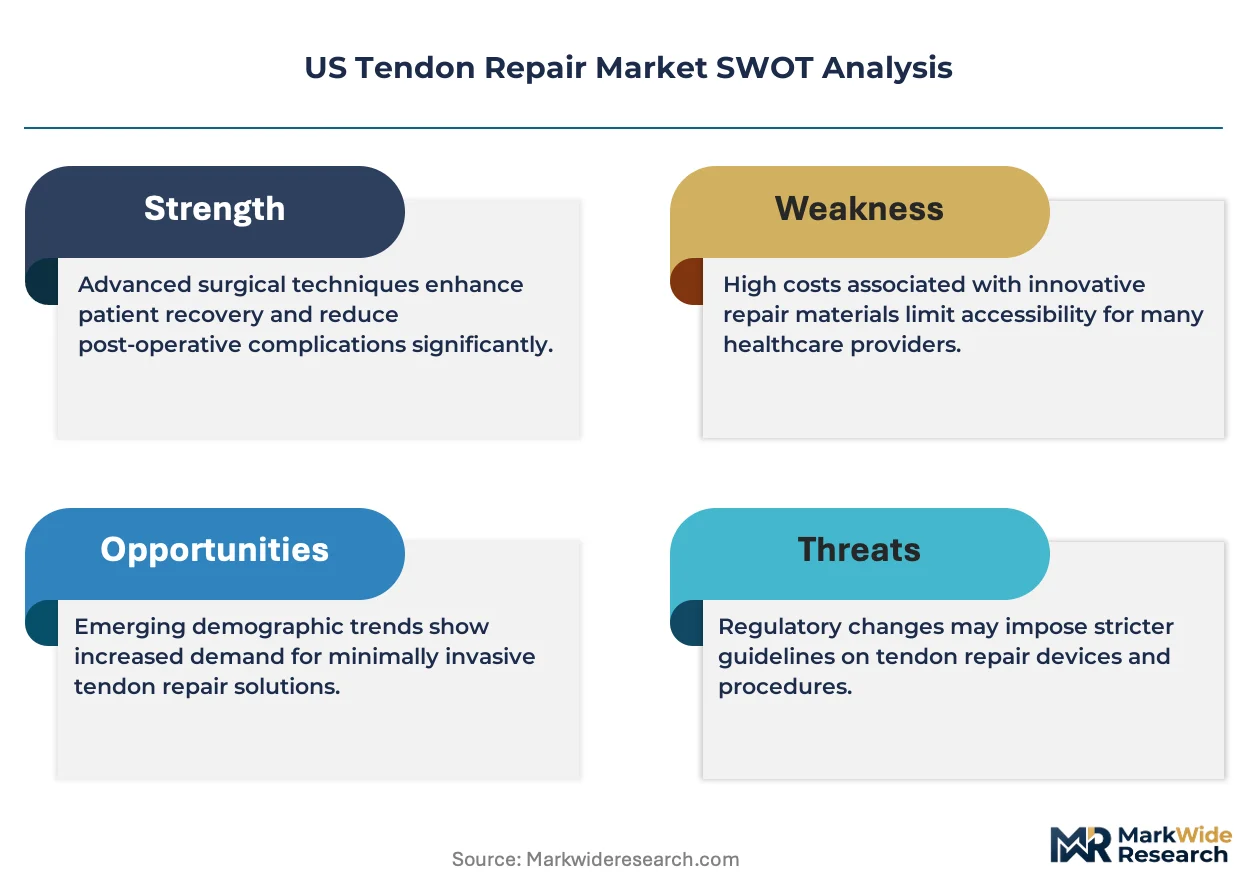
FDA 510(k) premarket notification requirements govern implantable suture anchor classification, while CMS reimbursement determinations for outpatient tendon procedures directly shape ASC investment decisions. State-level certificate-of-need regulations in New York and Illinois constrain hospital capital deployment for robotic-assisted systems. OSHA bloodborne pathogen standards mandate instrument reprocessing protocols that influence disposable versus reusable instrument procurement. Stakeholders must monitor evolving CMS site-neutral payment policies that threaten to compress reimbursement differentials between hospital outpatient departments and freestanding ASCs.
Market Dynamics
Outpatient migration from hospital outpatient departments to ambulatory surgical centers is compressing site-of-care economics and forcing manufacturers to reconfigure distribution and service models around lower-reimbursement environments.
Growth Catalysts
- CMS site-neutral payment policies:Reimbursement parity between hospital outpatient departments and freestanding ASCs accelerates capital deployment into ambulatory tendon repair infrastructure across Texas and Florida.
- Braided polyethylene suture advances:High-tensile knotless fixation systems reduce operative time and enable same-day discharge protocols that align with ASC throughput requirements.
- Aging athlete demographics:Weekend warrior populations in Sun Belt states generate surgical volumes for rotator cuff and Achilles repair procedures.
Market Restraints
- Biologic scaffold input costs:Amniotic membrane and platelet-rich plasma processing expenses constrain margin expansion for regenerative matrix portfolios.
- Certificate-of-need regulations:New York and Illinois CON laws restrict hospital capital deployment for robotic-assisted arthroscopic systems, limiting technology diffusion.
- Allograft substitution pressure:Cadaveric tendon grafts compete with synthetic scaffolds in complex multi-tendon reconstructions, pressuring premium biologic pricing.
Strategic Opportunities
- Underpenetrated ASC clusters:Orthopedic-focused ambulatory centers in Arizona and Nevada lack dedicated tendon repair service lines, creating first-mover positioning for integrated implant-instrument bundles.
- OSHA instrument reprocessing mandates:Bloodborne pathogen standards favor disposable arthroscopic instrument adoption over capital-intensive sterilization infrastructure.
- Cell-seeded graft convergence:Integration of autologous cell therapy with collagen matrices opens regenerative applications in chronic tendinopathy cases previously managed conservatively.
Industry Challenges
- Arthroscopic technician shortages:Specialized OR staff capable of all-inside repair system troubleshooting remain concentrated in major metropolitan academic centers.
- FDA 510(k) pathway variability:Biologic scaffold classification uncertainty extends premarket notification timelines and complicates portfolio planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Tendon Repair Market |
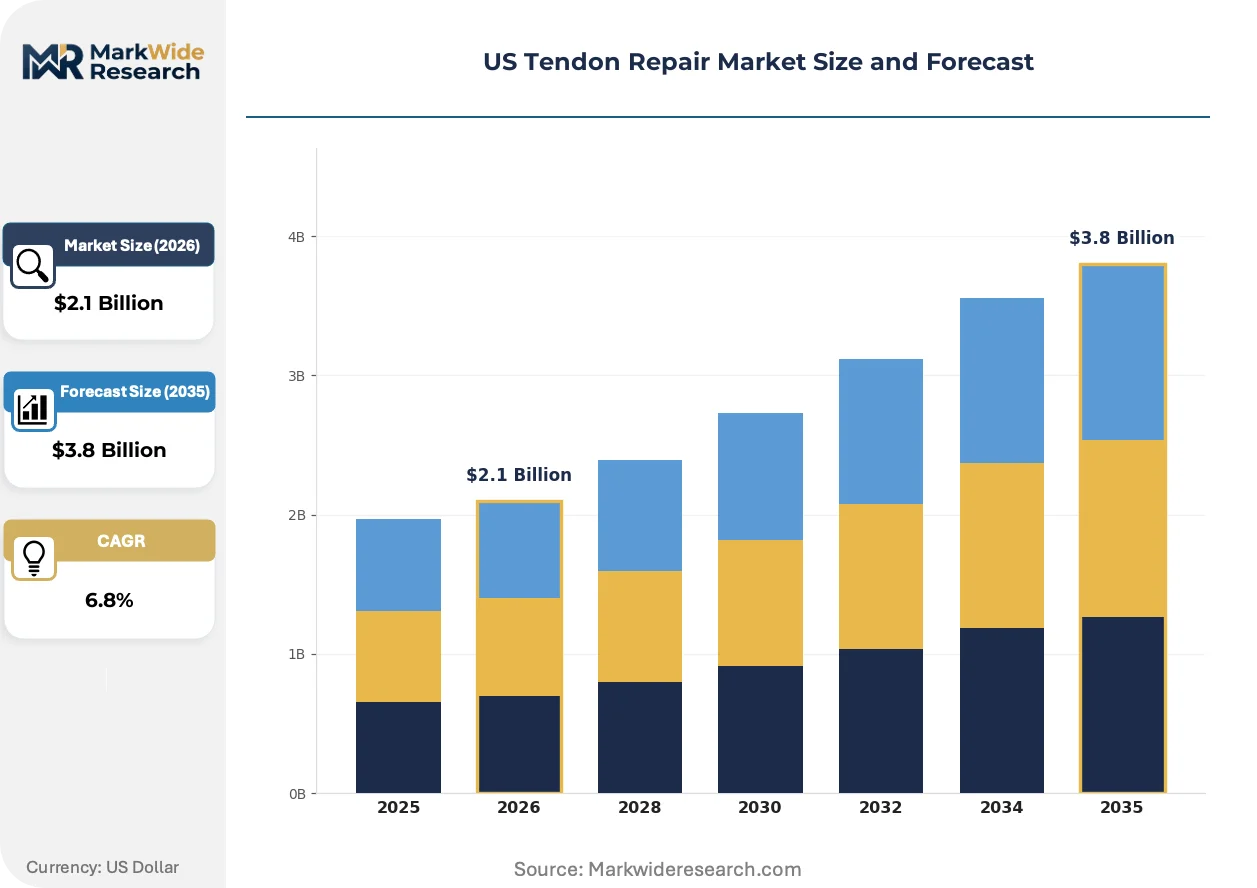
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Orthobiologics, Sutures, Anchors Technology: Open Surgery, Arthroscopic Surgery, Percutaneous Techniques, Biological Enhancements End User: Hospitals, Clinics, Ambulatory Surgical Centers, Rehabilitation Centers Application: Sports Injuries, Traumatic Injuries, Degenerative Conditions, Reconstructive Surgery |
| Companies Covered | Stryker, Arthrex, Inc., CONMED Corporation, Integra LifeSciences, Smith+Nephew, DePuy Synthes, Inc., TendoMend, Alafair Biosciences, MiMedx, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Tendon Repair Market Strategic Shifts & Innovations
Digital surgical planning and point-of-care biologic preparation are collapsing traditional boundaries between diagnosis, intervention, and rehabilitation in tendon repair workflows.
Patient-specific 3D-printed surgical guides derived from MRI-based tendon tear morphology is virtualizing preoperative planning for complex rotator cuff reconstructions. High-volume orthopedic ASCs in California and Texas are adopting these planning tools to standardize anchor placement angles and reduce revision rates. The technology is virtualizing the traditional surgeon-to-sales rep intraoperative consultation model by embedding predictive outcomes data directly into navigation interfaces.
FDA 510(k) premarket notification requirements for implantable suture anchors are tightening evidentiary standards for knotless fixation systems, extending clearance timelines by six to twelve months. Manufacturers are responding with expanded biomechanical testing protocols and prospective registry commitments. Small-to-mid-cap orthobiologics firms without established FDA liaison capabilities face disproportionate compliance burdens relative to diversified strategics.
Hospital supply committees are consolidating vendor relationships around full-procedure bundles that combine implants, disposable instruments, and biologic adjuncts under single-source contracts. This procurement compression displaces standalone suture anchor suppliers who lack orthobiologics portfolios or arthroscopic instrument lines. The shift is most visible in California IDN purchasing coalitions where orthopedic service line standardization drives vendor rationalization decisions.
US Tendon Repair Market Segmentation
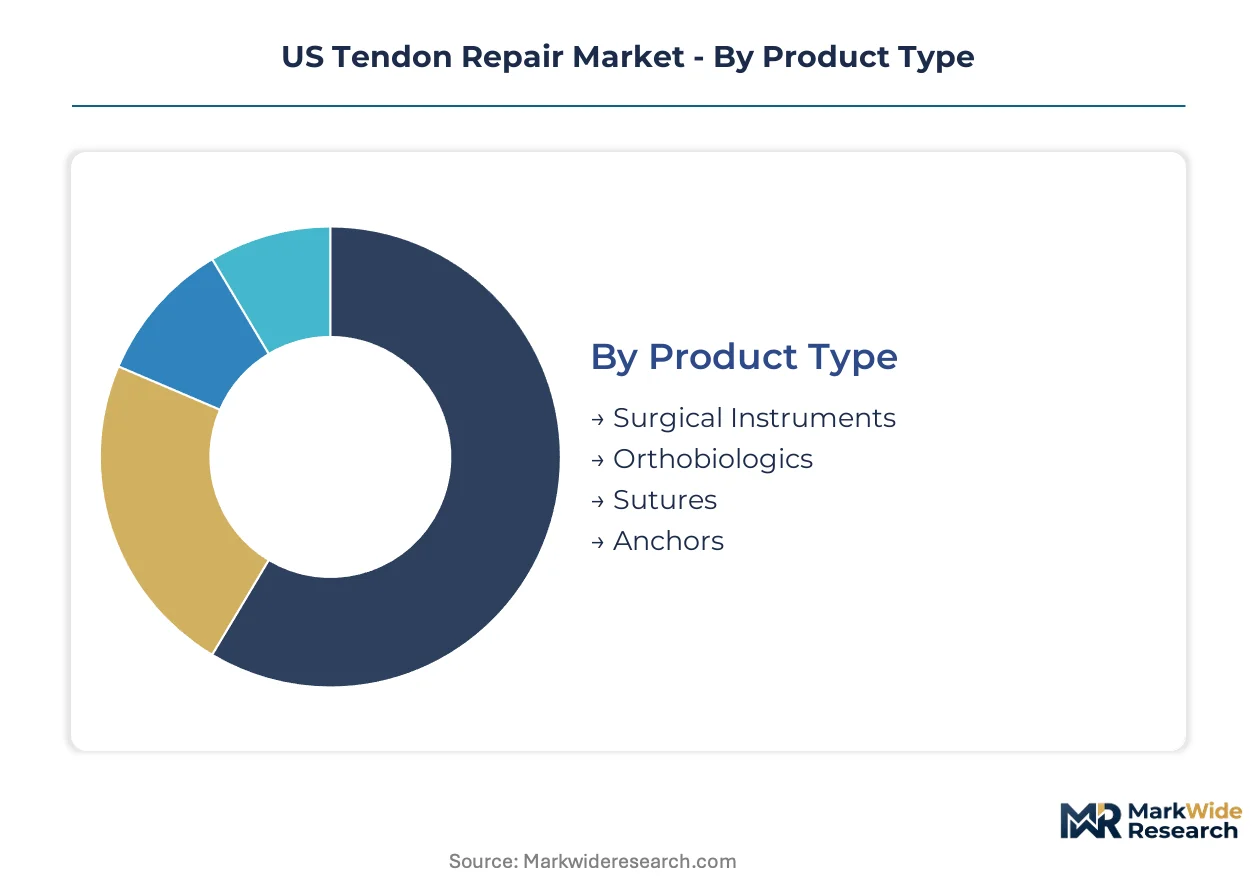
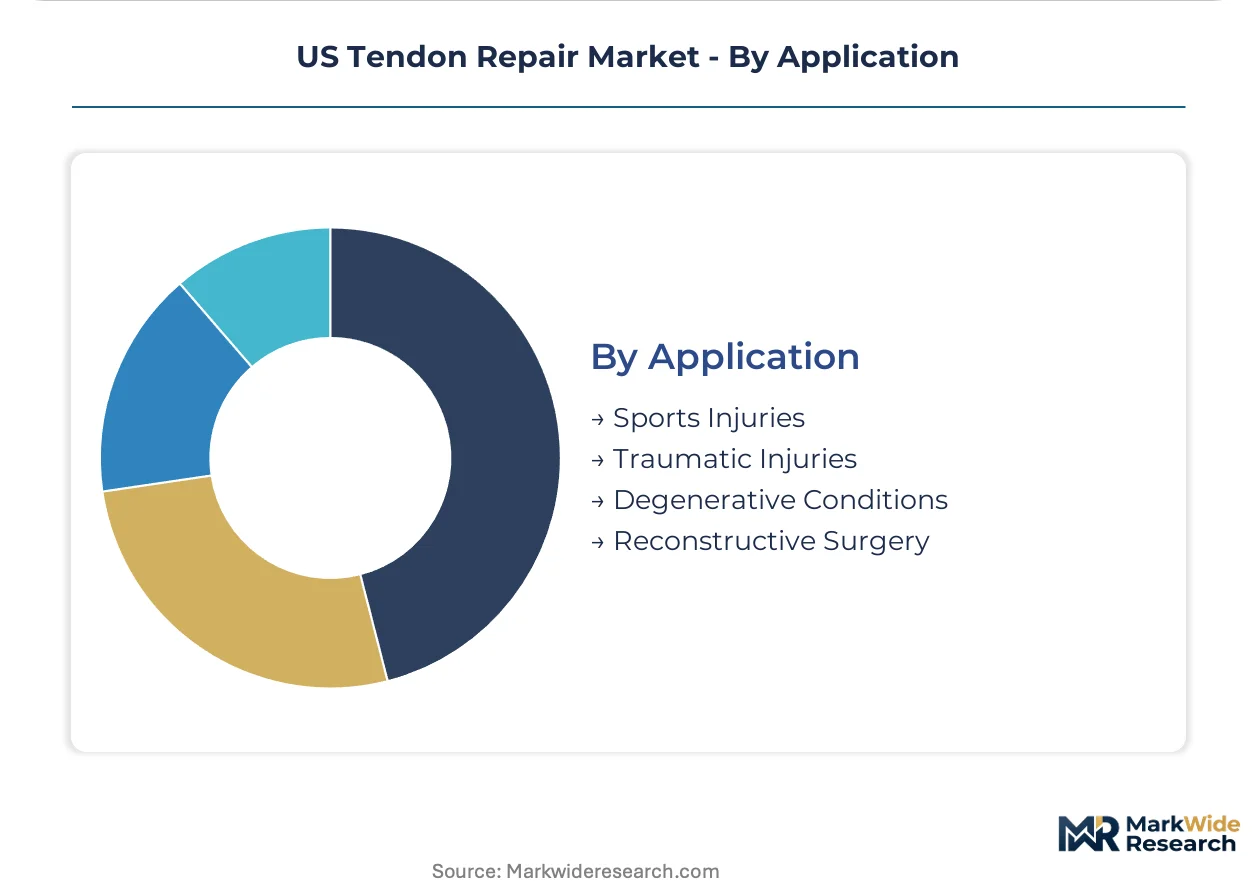
Segmentation in the US tendon repair market reveals distinct procurement rhythms across product categories. Orthobiologics and arthroscopic systems turn over on 18-24 month cycles tied to surgeon preference shifts, while anchor and suture lines refresh more slowly. Understanding these velocity differentials shapes inventory positioning and contract negotiation strategy for manufacturers and distributors alike.
Product Type:
Cycle times vary sharply across this category, with biologic inputs requiring cold-chain logistics and shorter shelf lives compared to metal anchors with multi-year stability windows.
- Orthobiologics:Amniotic membrane grafts and platelet-rich plasma preparations command premium positioning in rotator cuff applications. Demand concentrates in orthopedic ASC clusters across Texas and Florida where sports medicine surgeons prioritize biologic adjuncts for aging athlete populations.
- Anchors:Knotless suture anchor systems with braided polyethylene fixation enable same-day discharge protocols. Procurement volumes track arthroscopic system installations in Sun Belt ambulatory centers where OR throughput drives implant selection.
- Surgical Instruments:Disposable arthroscopic shavers and graspers align with OSHA bloodborne pathogen reprocessing mandates.
- Sutures:Braided polyethylene configurations with tensile strength exceeding 50 pounds anchor tendon-to-bone repair constructs.
Orthobiologics dominates installed base value concentration. Anchors represent where expansion concentrates fastest as ASC infrastructure scales.
Technology:
Cost tier stratification separates capital-intensive robotic platforms from disposable-intensive percutaneous kits, with reimbursement parity across site-of-care settings flattening technology selection criteria.
- Arthroscopic Surgery:Minimally invasive visualization systems with dedicated tendon repair instrument sets enable outpatient migration. California and Texas orthopedic ASCs standardize on all-inside repair configurations that reduce operative time and anesthetic exposure.
- Biological Enhancements:Cell-seeded collagen matrices and autologous therapies integrate with surgical intervention for chronic tendinopathy. Demand clusters in academic medical centers with orthobiologics processing capabilities and IRB-approved regenerative protocols.
- Open Surgery:Traditional tenorrhaphy approaches persist for complex multi-tendon injuries requiring extensile exposure.
- Percutaneous Techniques:Ultrasound-guided minimally invasive methods address Achilles and patellar tendon pathology in select patient subsets.
Arthroscopic surgery commands the largest procedure volume footprint. Biological enhancements are climbing the fastest as FDA 510(k) pathways mature for scaffold-classification products.
End User:
Customer type segmentation maps directly to reimbursement differential capture, with freestanding ASCs extracting margin from site-neutral payment policies that hospital outpatient departments cannot match.
- Ambulatory Surgical Centers:Orthopedic-focused facilities in Arizona and Nevada lack dedicated tendon repair service lines, creating first-mover positioning for integrated implant-instrument bundles. CMS site-neutral reimbursement accelerates capital deployment into these settings.
- Hospitals:Academic medical centers and community hospitals in New York and Illinois face certificate-of-need constraints on robotic system procurement. Tendon repair volumes concentrate in level-one trauma centers managing complex polytrauma with multi-tendon involvement.
- Clinics:Physician office-based settings handle diagnostic workup and conservative management prior to surgical referral.
- Rehabilitation Centers:Postoperative physical therapy facilities manage structured return-to-activity protocols following surgical intervention.
Hospital networks retain the deepest installed base of capital equipment. Ambulatory surgical centers are gaining share fastest as outpatient migration reshapes site-of-care economics.
Application:
Volume concentration in sports-related injuries masks higher margin capture in complex reconstruction cases requiring staged interventions and biologic augmentation.
- Reconstructive Surgery:Complex multi-tendon injuries requiring staged interventions with allograft or synthetic scaffold augmentation. Tertiary referral centers in California and Texas manage these cases through multidisciplinary upper extremity services.
- Sports Injuries:Acute rotator cuff and Achilles ruptures in weekend warrior demographics drive procedural volume. Florida and Arizona retirement communities generate sustained surgical demand from aging athletic populations.
- Traumatic Injuries:Laceration and avulsion mechanisms in occupational and motor vehicle settings.
- Degenerative Conditions:Chronic tendinopathy and attritional tears in older patient cohorts.
Sports injuries anchor the largest procedure volume base. Reconstructive surgery represents the steepest expansion trajectory as biologic scaffold integration enables previously unoperable chronic cases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US tendon repair equipment and biologics flow primarily to domestic ASC clusters, with limited cross-border trade concentrated in specialized allograft tissue from Canadian tissue banks.
Texas
Weekend warrior populations in Dallas-Fort Worth and Houston generate surgical volumes for rotator cuff and Achilles repair procedures. FDA 510(k) clearance pathways for biologic scaffolds accelerate product commercialization timelines for manufacturers serving these markets. Orthopedic ASC clusters across the Texas Medical Center and Austin metro lack dedicated tendon repair service lines, creating first-mover positioning for integrated implant-instrument bundles.
Florida
Aging athlete demographics in retirement communities from Naples to Sarasota sustain demand for arthroscopic tendon interventions. CMS site-neutral payment policies compress reimbursement differentials between hospital outpatient departments and freestanding ASCs, accelerating capital deployment into ambulatory infrastructure. Tampa and Orlando orthopedic centers standardize on all-inside repair configurations that reduce operative time and anesthetic exposure.
California
IDN purchasing coalitions in Los Angeles and San Francisco drive vendor rationalization around full-procedure bundles combining implants, disposable instruments, and biologic adjuncts. OSHA bloodborne pathogen standards mandate instrument reprocessing protocols that influence disposable versus reusable instrument procurement decisions. Patient-specific 3D-printed surgical guides derived from MRI-based tendon tear morphology are virtualizing preoperative planning in high-volume orthopedic ASCs.
Arizona
Underpenetrated orthopedic ASC clusters in Phoenix and Tucson lack dedicated tendon repair service lines, creating positioning opportunities for manufacturers offering integrated solutions. Certificate-of-need regulations do not constrain Arizona hospital capital deployment, enabling faster robotic-assisted system adoption than in regulated states. Sun Belt migration patterns concentrate aging athletic populations seeking active lifestyle preservation through surgical intervention.
New York
State-level certificate-of-need regulations constrain hospital capital deployment for robotic-assisted arthroscopic systems, limiting technology diffusion compared to Sun Belt markets. Academic medical centers in Manhattan and Buffalo manage complex multi-tendon injuries through multidisciplinary upper extremity services. Tertiary referral volumes concentrate in level-one trauma centers managing polytrauma with multi-tendon involvement.
US Tendon Repair Market Key Industry Players
Channel-controlling players compete with product-specialist players across procurement tiers. Hospital supply committees consolidate vendor relationships around full-procedure bundles, displacing standalone suppliers who lack orthobiologics portfolios or arthroscopic instrument lines. Three archetypes dominate: diversified strategics with orthobiologics platforms, arthroscopic system specialists, and regenerative matrix developers. Competitive moves center on M&A for biologic scaffold capabilities and strategic partnerships with ASC management companies.
Among US-based diversified strategics, Stryker, Arthrex, and Integra LifeSciences occupy distinct positioning archetypes. Stryker represents the supply-contract anchor with orthobiologics platform breadth. Arthrex exemplifies the arthroscopic system specialist with R&D intensity in minimally invasive configurations. Integra LifeSciences sits within the regenerative matrix tier, differentiating through chronic tendinopathy applications. Each anchors procurement discussions with IDNs and ASC chains through distinct value propositions.
| Leading Market Players |
|---|
| Stryker |
| Arthrex, Inc. |
| CONMED Corporation |
| Integra LifeSciences |
| Smith+Nephew |
| DePuy Synthes, Inc. |
| TendoMend |
| Alafair Biosciences |
| MiMedx |
| Others |
Cost & Logistics Intelligence
Undercapacity in braided polyethylene suture manufacturing across the Texas Medical Center corridor drives supplier prioritization of high-volume ASC contracts and compresses pricing flexibility for smaller hospital systems. This utilization squeeze tightens both input procurement timelines and implant cost negotiation leverage.
Pricing Analysis
Next-generation knotless anchor systems command 40-60% premiums over prior-generation knotted configurations, while economy-tier allograft substitutes undercut synthetic scaffold pricing by 25-35%. Three-tier pricing structure across premium, standard, and economy levels segments by tensile strength certification and biologic processing grade. Cost compression in standard-tier sutures is intensifying because of allograft substitution pressure. Ambulatory surgical centers demonstrate highest price sensitivity due to CMS site-neutral reimbursement constraints, while academic medical centers show lowest sensitivity given bundled procurement budgets.
Supply Chain Analysis
Extended payment terms from 45 to 90 days characterize supplier financing arrangements for orthopedic ASCs in Arizona and Nevada, straining working capital for mid-cap biologic scaffold manufacturers. Raw material sourcing draws from domestic polyethylene fiber producers, Swiss collagen purification facilities, and South Korean amniotic membrane processors. Single-source vulnerability concentrates in FDA-registered tissue banks supplying allograft tendons. Distribution runs through GPO-affiliated distributors serving IDN purchasing coalitions in California and Texas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face acute substitution defense requirements as allograft tendon processors capture share in complex multi-tendon reconstructions previously dominated by synthetic scaffolds.
For Market Incumbents: Pre-empt allograft substitution by securing exclusive supply contracts with AATB-accredited tissue banks and embedding biologic adjuncts into anchor-suture bundles. Backward integration into amniotic membrane processing insulates margin pools from input cost volatility. Prioritize FDA 510(k) pathway expertise to accelerate scaffold classification clearances ahead of regenerative matrix competitors. For New Entrants and Emerging Players: Pursue white-space positioning in Arizona and Nevada orthopedic ASC clusters lacking dedicated tendon repair service lines. Underpenetrated Sun Belt markets offer first-mover capture of integrated implant-instrument bundles. Go-to-market execution should target ASC management companies with site-neutral reimbursement economics and disposable instrument preferences. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among orthobiologics platforms with hospital supply contract anchoring and cold-chain logistics infrastructure. Long-term viability over the next decade favors diversified strategics with FDA liaison capabilities and multi-product portfolios. Watch FDA 510(k) clearance velocity for scaffold-classification products as the inflection signal for regenerative matrix segment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Biologic scaffold manufacturers compress premarket timelines through expanded biomechanical testing protocols. |
| ASC Management Partnership | Integrated implant-instrument bundles capture outpatient migration in Texas and Florida orthopedic clusters. |
| Orthobiologics Platform Expansion | Amniotic membrane and PRP portfolios differentiate vendor positioning in rotator cuff applications. |
| Disposable Instrument Conversion | OSHA bloodborne pathogen compliance drives shaver and grasper procurement away from reprocessing infrastructure. |
| 3D Surgical Planning Integration | Patient-specific guides from MRI data standardize anchor placement in California high-volume centers. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with orthopedic surgeons, ASC operations directors, hospital purchasing committee members, and GPO contracts managers; and secondary validation against FDA 510(k) clearance databases, CMS reimbursement determinations, hospital procurement records, and state-level certificate-of-need filings. Bottom-up procedure volume estimates triangulated with top-down manufacturer revenue segmentation across product categories.
Forecast inputs span product type, technology platform, end-user facility type, and application severity across the projection horizon. Modeled segmentation dimensions include orthobiologics versus mechanical implants, arthroscopic versus open surgical approach, and ambulatory versus inpatient site-of-care. CAGRs derived from surgical volume trend extrapolation, reimbursement rate trajectory analysis, and biologic scaffold adoption curve modeling. Procedure migration patterns and ASC capital deployment cycles served as industry-specific forecast inputs.
Sensitivities concentrate around CMS site-neutral payment policy implementation timing, FDA 510(k) evidentiary standard tightening, and allograft tissue bank supply disruptions. Forecasts reflect assumptions regarding outpatient migration velocity and biologic scaffold clinical adoption. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Global Personalized 3D Printed Orthopedic Implants Market
Orthopedic Devices
Europe Orthopedic Braces and Support Market
Orthopedic Devices
Europe Orthopedic Navigation Systems Market
Orthopedic Devices
Closed Heel Nursing Shoes Market
Orthopedic Devices
Saudi Arabia Spinal Surgery Devices Market
Orthopedic Devices
Patient Lifts Market
Orthopedic Devices
Polyethylene Orthopaedic Insert Market
Orthopedic Devices
Global Orthopedic Bone Cement Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Devices Market
Orthopedic Devices
Chondroplasty Market
Orthopedic Devices
Kyphoplasty Systems Market
Orthopedic Devices
Prosthetics and Orthotics Market
Orthopedic Devices
Global Spinal Fusion Devices Market
Orthopedic Devices
Medical Crutches Market
Orthopedic Devices
Shoulder Arthroplasty Market
Orthopedic Devices
Orthopedic Splints and Casts Market