
 China Ultrasound Devices Market | 2026-2036
China Ultrasound Devices Market Size, Share, and Industry Trends Forecast 2026-2036
China Ultrasound Devices Market Outlook
Aftermarket service revenue is reconfiguring profit pools across the China ultrasound landscape. Mindray Medical International Limited leverages its domestic manufacturing base to anchor service contracts in provincial hospitals. GE Healthcare competes through localized production facilities that sustain shorter lead times for system upgrades. Siemens Healthineers AG differentiates via AI-integrated imaging platforms that command premium maintenance agreements.
Ultrasound devices generate acoustic images through piezoelectric transducers operating at frequencies from two to fifteen megahertz, with beamforming algorithms processing reflected echoes for real-time tissue visualization. Diagnostic ultrasound systems dominate hospital procurement budgets while portable ultrasound units represent the fastest-expanding product category as point-of-care protocols penetrate county-level clinics. Color Doppler technology captures expanding share in cardiology applications where hemodynamic assessment requirements are intensifying.
NMPA's medical device registration pathways and GB standards for electromagnetic compatibility shape product compliance costs and time-to-market for domestic and imported systems alike. The country's dual carbon goals are pressuring manufacturers to reduce power consumption in next-generation consoles and probes. Stakeholders must monitor how provincial centralized procurement programs rebalance pricing power between multinational suppliers and local champions.
Market Dynamics
Provincial centralized procurement programs are redistributing pricing power between multinational suppliers and domestic manufacturers, compressing margins while expanding volume access across county-level healthcare networks.
Growth Catalysts
- Dual Carbon Goals:Beijing's emissions reduction mandates are accelerating hospital upgrades to energy-efficient ultrasound consoles, creating replacement demand in tertiary facilities.
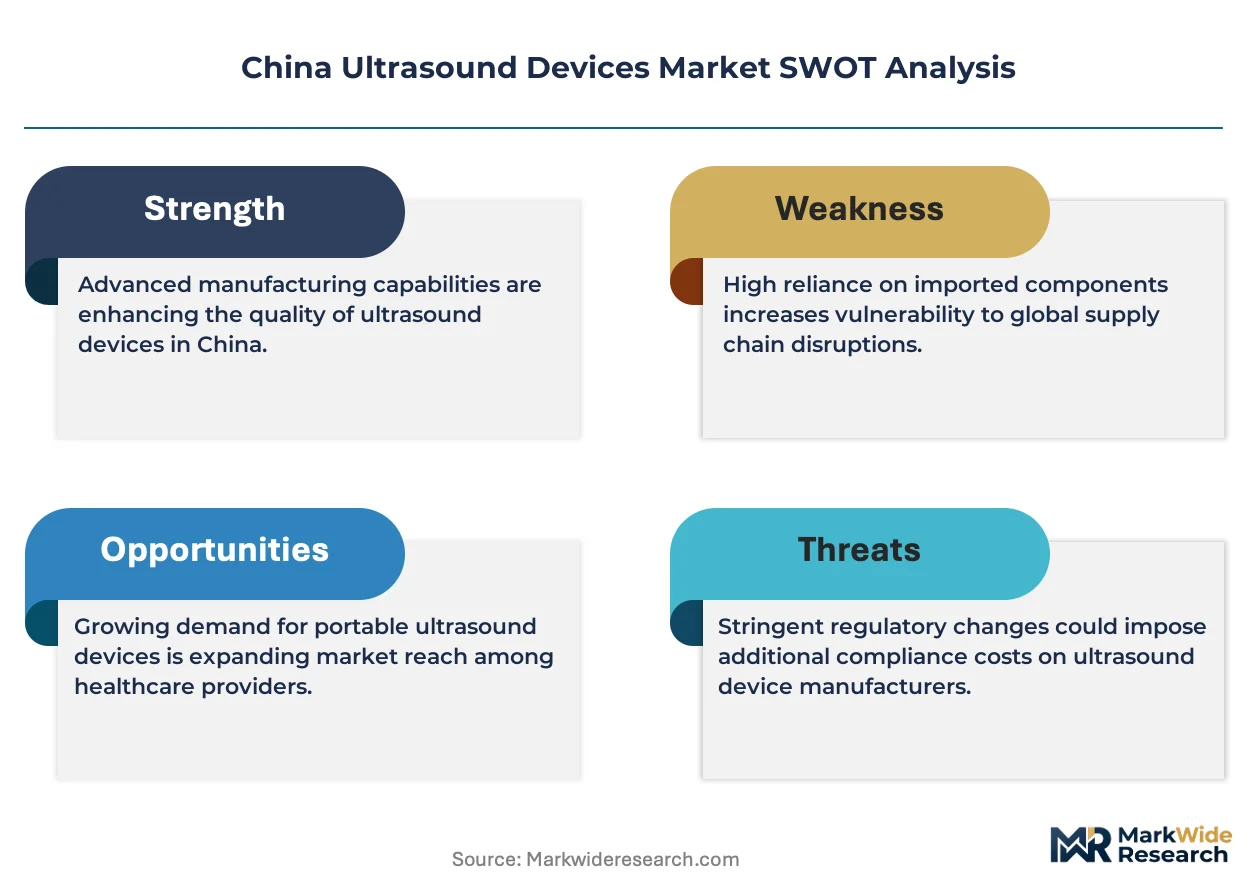
- Point-of-Care Protocols:Portable ultrasound units are penetrating county-level clinics as diagnostic imaging decentralizes beyond urban hospital clusters.
- NMPA Registration Acceleration:Updated medical device classification rules are shortening local registration timelines for domestic and imported systems alike.
Market Restraints
- Piezoelectric Crystal Supply Concentration:Specialty transducer materials concentrate among a limited supplier base, exposing probe manufacturers to input volatility.
- GB Standards Compliance Burden:Electromagnetic compatibility certification requirements extend product development cycles and elevate testing expenditures for new market entrants.
- CT and MRI Substitution:Advanced cross-sectional imaging modalities are capturing complex diagnostic cases that previously defaulted to high-end ultrasound systems.
Strategic Opportunities
- Private Imaging Chain Consolidation:Coastal province roll-ups are creating scaled buyers seeking fleet-standardization agreements with service-embedded pricing.
- AI-Integrated Beamforming:Machine learning algorithms are converging with real-time image processing to enable automated anatomical recognition and measurement protocols.
- MEE Green Procurement Incentives:Environmental ministry guidelines favoring low-power medical equipment are creating preferential purchasing pathways for efficient system designs.
Industry Challenges
- Sonographer Training Bottlenecks:Specialized ultrasound technologist certification programs are failing to keep pace with equipment deployment in expanded care settings.
- Legacy PACS Integration Complexity:New ultrasound systems must bridge incompatible data formats with existing hospital picture archiving infrastructure, extending implementation timelines.
- IP Licensing Friction:Patent thickets around harmonic imaging and elastography algorithms are complicating technology access for second-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Ultrasound Devices Market |
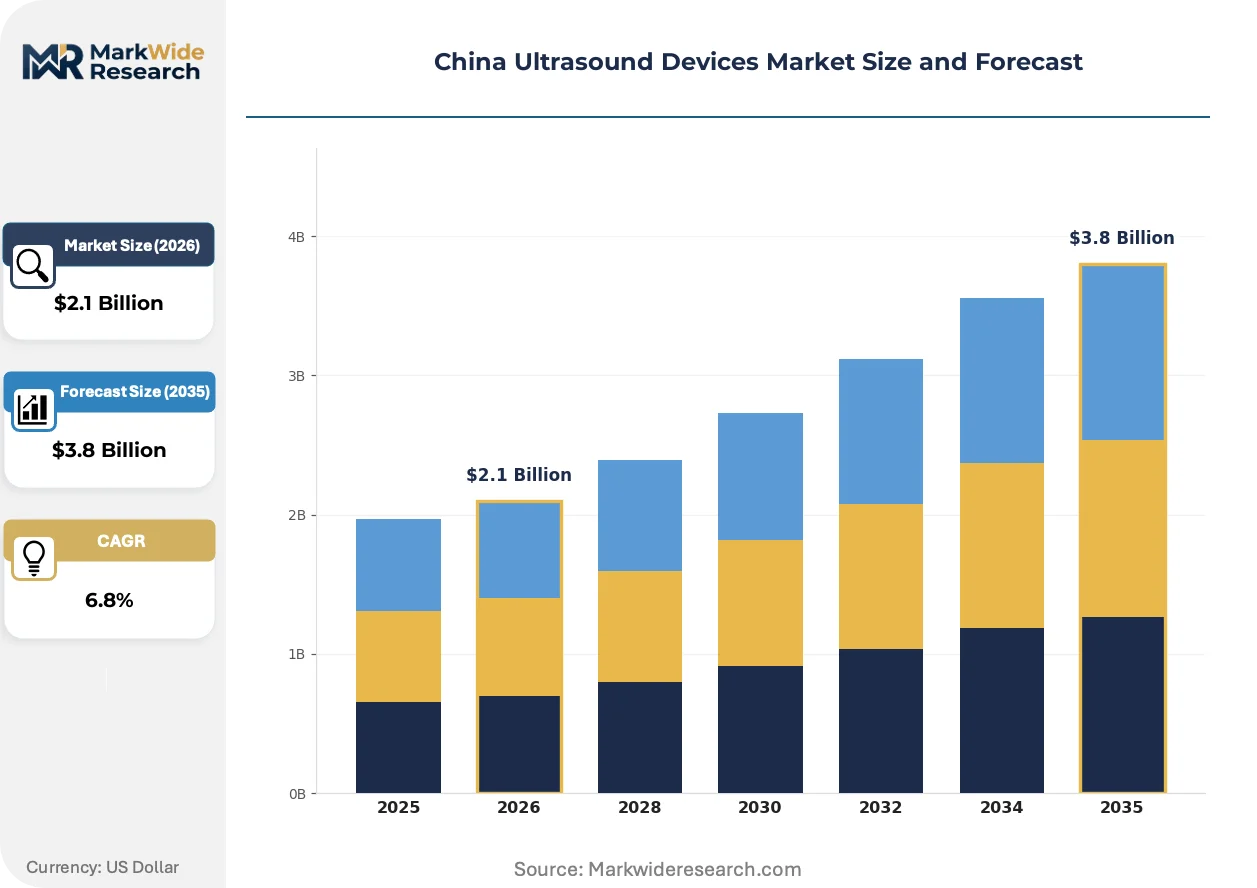
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Ultrasound, Therapeutic Ultrasound, Portable Ultrasound, 3D/4D Ultrasound End User: Hospitals, Diagnostic Imaging Centers, Clinics, Academic Institutions Technology: Digital Ultrasound, Analog Ultrasound, High-Frequency Ultrasound, Color Doppler Ultrasound Application: Cardiology, Obstetrics, Abdominal Imaging, Musculoskeletal |
| Companies Covered | Koninklijke Philips NV, Canon Medical Systems Corporation, Mindray Medical International Limited, SonoScape Medical Corp, Hologic Inc, GE Healthcare, Siemens Healthineers AG, Chison Medical Technologies, Samsung Electronics Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Ultrasound Devices Market Strategic Shifts
Three intersecting developments are compressing product lifecycles and rewiring competitive advantage in China's ultrasound sector: semiconductor-driven processing gains, regulatory pressure on device efficiency, and procurement centralization altering vendor selection criteria.
Shear wave elastography is rendering obsolete manual palpation-based tissue stiffness assessment in hepatology and breast imaging workflows. Tertiary hospital radiology departments in Beijing and Shanghai are adopting these systems at twelve-month refresh cycles. The technology is rendering obsolete conventional B-mode ultrasound for fibrosis staging, compressing the addressable market for basic diagnostic consoles.
NMPA's updated medical device classification rules are elevating software-as-a-medical-device oversight for AI-enabled diagnostic functions. Manufacturers must now submit algorithm validation datasets and performance benchmarking against reference standards. High-end cart-based systems with embedded deep learning modules face the steepest compliance burden, driving some vendors toward detachable compute architectures.
County-level health bureaus are aggregating ultrasound procurement through provincial centralized purchasing platforms, consolidating what were fragmented hospital-level decisions. Equipment vendors must now navigate tender specifications written for standardized fleet deployments rather than individualized site configurations. This behavioral shift is most pronounced in Jiangsu and Zhejiang provinces where private imaging chains have achieved sufficient scale to influence regional purchasing templates.
China Ultrasound Devices Market Segmentation
Ultrasound device segmentation in China reflects divergent procurement cycles across care settings. Tertiary hospitals refresh cart-based systems every three to four years while county clinics extend portable unit lifespans beyond seven years. Understanding these replacement rhythms helps vendors align service contract structures with customer cash flow patterns.
Product Type:
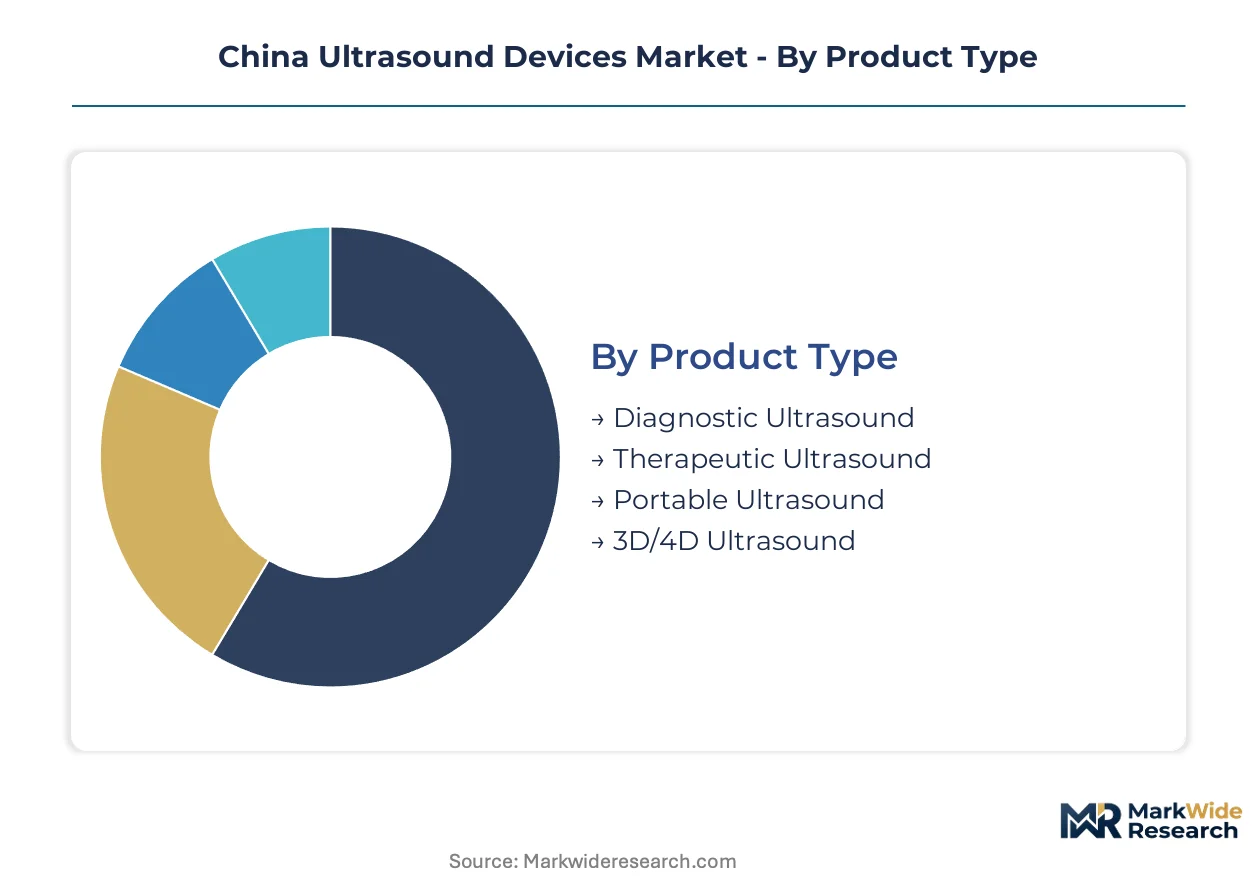
Diagnostic ultrasound systems turn over slowest in provincial hospitals where capital budgets constrain replacement schedules, while portable units cycle fastest as point-of-care protocols multiply across county networks.
- Diagnostic Ultrasound:Cart-based systems with 2-15 MHz transducer arrays and beamforming processors serve as the workhorse modality for radiology departments. Beijing and Shanghai tertiary hospitals anchor procurement volume as these facilities prioritize image resolution for complex case triage.
- Portable Ultrasound:Battery-powered units with wireless probe connectivity enable bedside and field diagnostics outside traditional imaging suites. County-level clinics in Jiangsu and Zhejiang are consolidating demand through provincial procurement platforms that favor lightweight designs.
- Therapeutic Ultrasound:Focused acoustic energy devices for tissue ablation and physiotherapy applications operate at intensities exceeding diagnostic thresholds.
- 3D/4D Ultrasound:Volumetric imaging systems with real-time rendering capabilities command premium positioning in obstetric applications.
Diagnostic ultrasound anchors the volume base while portable ultrasound gains share at the steepest rate.
End User:
Customer type determines pricing tolerance and service attachment rates, with imaging centers pursuing fleet standardization while academic institutions prioritize research functionality over throughput metrics.
- Hospitals:Tertiary facilities with dedicated radiology departments drive procurement of high-end cart systems with AI-embedded diagnostic modules. NMPA registration timelines influence vendor selection as hospitals seek predictable upgrade pathways.
- Diagnostic Imaging Centers:Private chains in coastal provinces aggregate demand for standardized equipment configurations that simplify technician training and maintenance logistics.
- Clinics:Primary care settings with limited imaging infrastructure favor portable units for triage and referral decisions.
- Academic Institutions:Research hospitals require specialized transducer configurations and open software architectures for protocol development.
Hospitals dominate installed base value while diagnostic imaging centers expand most quickly as private capital consolidates fragmented operators.
Technology:
Digital architectures have displaced analog signal chains across all but the most price-sensitive entry tiers, with color Doppler functionality now standard even in mid-range county hospital deployments.
- Digital Ultrasound:Fully digitized beamforming with software-defined image processing enables post-acquisition manipulation and AI algorithm integration. NMPA's software-as-medical-device oversight applies most stringently to these systems.
- Color Doppler Ultrasound:Frequency-shift detection for hemodynamic visualization has become mandatory for cardiology applications where flow assessment determines surgical candidacy.
- Analog Ultrasound:Legacy hardware signal processing persists only in replacement markets for obsolete system maintenance.
- High-Frequency Ultrasound:Specialized transducers above 15 MHz enable superficial tissue and ophthalmic imaging with resolution exceeding standard diagnostic bands.
Digital ultrasound constitutes the mature revenue core while color Doppler functionality penetrates downward through price tiers fastest.
Application:
Clinical use case shapes transducer specification requirements and determines whether AI diagnostic modules justify premium system costs.
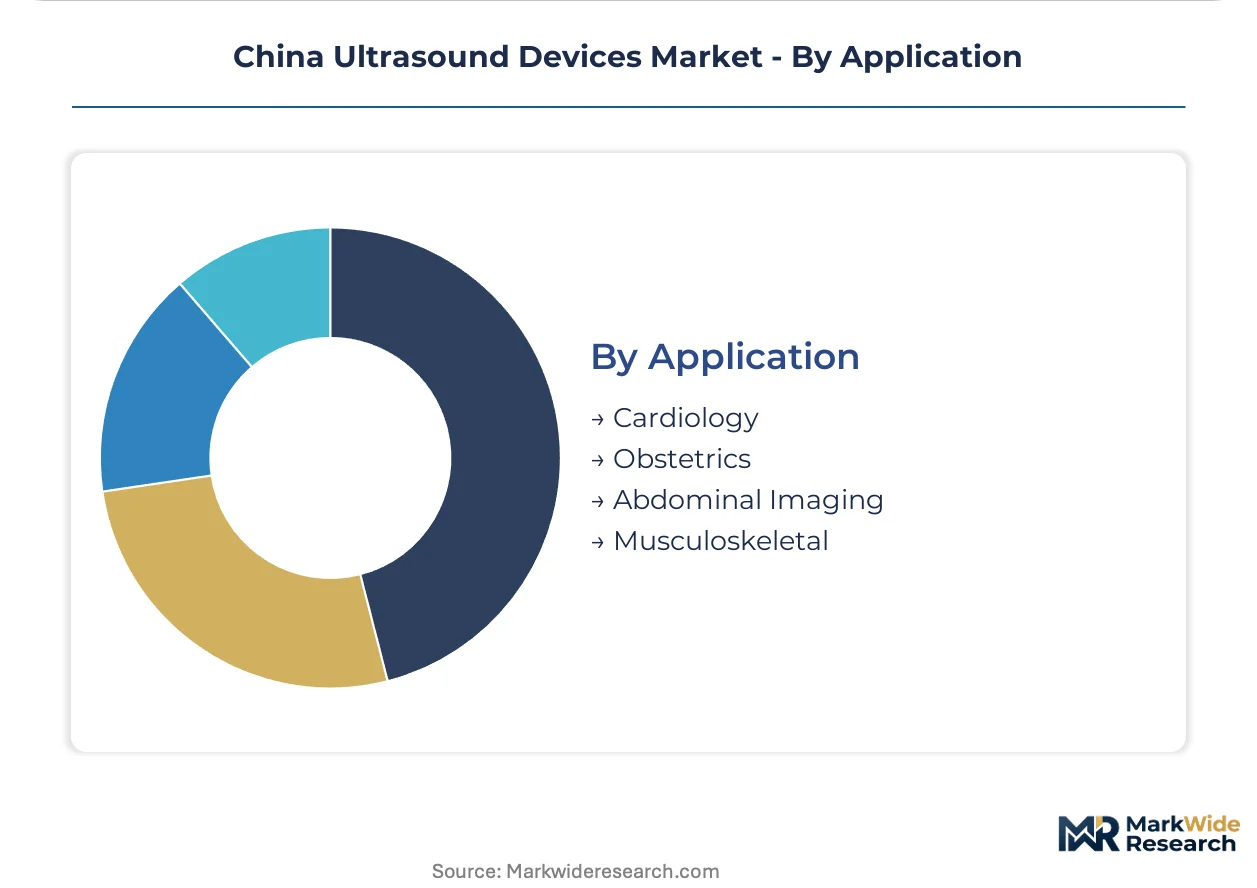
- Cardiology:Echocardiography systems with phased-array probes and Doppler processing handle stress testing and structural assessment. Shear wave elastography is displacing conventional B-mode for fibrosis staging in Beijing liver clinics.
- Obstetrics:3D/4D volumetric imaging for fetal anomaly screening drives replacement demand as expectant parents seek enhanced visualization.
- Abdominal Imaging:General-purpose diagnostic workhorse applications span liver, renal, and pancreatic assessment across hospital departments.
- Musculoskeletal:High-frequency linear probes for tendon, ligament, and joint evaluation serve orthopedic and sports medicine practices.
Cardiology applications anchor system value while obstetrics imaging climbs fastest as private maternity chains expand ultrasound service menus.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Provincial procurement platforms in Jiangsu and Zhejiang demonstrate the lowest price elasticity as consolidated private imaging chains negotiate fleet-standardization agreements, while county-level clinics in western provinces exhibit acute sensitivity to unit cost and service contract terms.
Beijing-Tianjin-Hebei
Tertiary hospitals in Beijing drive replacement demand for AI-embedded cart systems as radiology departments prioritize automated anatomical recognition. NMPA's software-as-medical-device oversight applies most stringently here, elevating compliance costs for algorithm validation. The Beijing municipal health commission's centralized procurement templates favor energy-efficient consoles aligned with dual carbon goals.
Yangtze River Delta
Shanghai's liver clinics adopt shear wave elastography systems at accelerated refresh cycles for fibrosis staging protocols. Provincial centralized purchasing platforms in Jiangsu aggregate demand from consolidating private imaging chains seeking standardized equipment configurations. Suzhou and Hangzhou anchor manufacturing clusters for piezoelectric transducer components serving domestic probe assembly.
Pearl River Delta
Guangdong's county health bureaus expand portable ultrasound deployment through provincial tender specifications favoring lightweight wireless designs. MEE green procurement incentives create preferential pathways for low-power equipment in Shenzhen and Guangzhou public hospitals. Dongguan's electronics manufacturing base supplies beamforming processors to regional system integrators.
Sichuan-Chongqing
County-level clinics in western China extend portable unit lifespans beyond seven years as capital budgets constrain replacement schedules. SAMR's medical device pricing surveillance monitors tender outcomes in Chongqing's municipal procurement platform. Chengdu's medical equipment distribution hubs serve as consolidation points for western province logistics.
Shandong Peninsula
Provincial hospital networks in Jinan and Qingdao balance diagnostic system upgrades with therapeutic ultrasound expansion in rehabilitation departments. GB standards for electromagnetic compatibility extend product development cycles for new market entrants targeting this region. Weihai hosts specialized transducer material suppliers exposed to input volatility from concentrated crystal sourcing.
China Ultrasound Devices Market Competitive Environment
Capability concentration sits with multinational technology licensors holding patent positions in harmonic imaging and elastography algorithms; scale advantage sits with domestic manufacturers leveraging captive supply chains and provincial service networks. The vendor base stratifies across three tiers: integrated conglomerates with diversified medical device portfolios, specialized ultrasound pure-plays, and emerging challengers competing on portable unit cost. Dominant competitive moves include backward integration into transducer crystal sourcing and strategic partnerships with provincial procurement platforms.
Among multinational integrated conglomerates, Koninklijke Philips NV and Siemens Healthineers AG exemplify the capability-intensive archetype through AI-embedded imaging platforms. GE Healthcare occupies a position bridging technology leadership with localized production infrastructure. Within the domestic specialist tier, Mindray Medical International Limited anchors service contract penetration in provincial hospitals through manufacturing proximity. SonoScape Medical Corp and Chison Medical Technologies represent scale-driven challengers consolidating share in county-level portable unit deployment. Canon Medical Systems Corporation and Samsung Electronics Co Ltd occupy intermediate positions leveraging electronics manufacturing scale for beamforming processor supply.
| Leading Market Players |
|---|
| Koninklijke Philips NV |
| Canon Medical Systems Corporation |
| Mindray Medical International Limited |
| SonoScape Medical Corp |
| Hologic Inc |
| GE Healthcare |
| Siemens Healthineers AG |
| Chison Medical Technologies |
| Samsung Electronics Co Ltd |
| Others |
Value Chain & Pricing Dynamics
Suzhou's piezoelectric transducer manufacturing cluster anchors probe assembly capacity for domestic ultrasound manufacturers, concentrating component supply leverage that shapes downstream pricing power across provincial procurement platforms. This geographic concentration of specialty crystal sourcing creates asymmetric bargaining positions between probe suppliers and system integrators, compressing margins for tier-two manufacturers while insulating vertically integrated incumbents.
Pricing Analysis
Aftermarket service contracts drive lifetime value realization across the installed base, with maintenance agreements and probe replacement cycles generating recurring revenue streams that exceed initial system margins. Three-tier pricing structure across premium AI-embedded, standard diagnostic, and economy portable levels segments buyers by certification requirements and image processing sophistication. Cost compression in the economy tier intensifies as county-level clinics consolidate demand through provincial tenders. Imaging centers in Jiangsu and Zhejiang exhibit lowest price sensitivity, while western province county hospitals demonstrate acute unit cost consciousness.
Supply Chain Analysis
Extended payment terms from provincial procurement platforms strain working capital for component suppliers, accelerating supply-chain finance facility adoption among transducer manufacturers. Probe assembly draws from concentrated piezoelectric crystal sourcing in China, Japan, and Germany, with beamforming processors fabricated in Taiwan and South Korea. Single-source vulnerability in high-frequency transducer substrates exposes manufacturers to input disruption. Distribution runs through municipal medical equipment bureaus that aggregate hospital demand before vendor selection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The China ultrasound market sits in early-cycle expansion as point-of-care protocols penetrate county-level networks previously underserved by diagnostic imaging infrastructure. This decentralization tailwind creates white-space opportunities for portable unit deployment beyond legacy urban hospital clusters.
For Market Incumbents: Insulate service contract penetration through backward integration into transducer crystal supply, securing probe replacement revenue streams against third-party component competitors. Anchor AI-embedded system upgrades in Beijing and Shanghai tertiary hospitals where NMPA software-as-medical-device oversight creates compliance barriers for challengers. Deepen manufacturing proximity to provincial procurement decision-makers to sustain fleet-standardization wins. For New Entrants and Emerging Players: Western province county clinics represent the most penetrable geography, with seven-year portable unit refresh cycles creating replacement demand as capital budgets gradually expand. Target therapeutic ultrasound applications in Shandong rehabilitation departments where competitive intensity lags diagnostic imaging. Pursue lightweight wireless designs aligned with Guangdong provincial tender specifications favoring field-deployable equipment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors domestic manufacturers with captive transducer supply and established provincial service networks over multinational pure-plays facing procurement localization pressure. Long-term viability hinges on algorithm validation capabilities for NMPA software oversight compliance. Watch provincial centralized procurement platform expansion as the inflection signal indicating pricing power consolidation toward scaled domestic champions.| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm Validation Investment | NMPA software-as-medical-device compliance secures premium system positioning in Beijing tertiary hospitals. |
| Transducer Crystal Backward Integration | Captive probe supply insulates service margins against concentrated specialty material input volatility. |
| Provincial Procurement Platform Partnership | Fleet-standardization agreements with Jiangsu imaging chains lock in multi-year volume commitments. |
| Portable Wireless Design Development | Lightweight form factors align with Guangdong county health bureau tender specifications favoring field deployment. |
| Shear Wave Elastography Module Integration | Automated fibrosis staging functionality displaces conventional B-mode in Shanghai liver clinic refresh cycles. |
Study Parameters
The analysis maps diagnostic ultrasound, portable ultrasound, therapeutic ultrasound, and 3D/4D system sub-sectors, each validated through hospital procurement managers, biomedical engineers, GPO contracts managers, and provincial health bureau officials. Primary interview findings triangulate against NMPA registration databases, hospital procurement platform tender records, customs trade data for transducer components, and manufacturer SEC disclosures. Bottom-up equipment deployment tracking reconciles with top-down healthcare infrastructure spending allocation across provincial budgets.
Assumptions held fixed include NMPA regulatory framework continuity, dual carbon goal enforcement intensity, and provincial procurement platform consolidation trajectory; variables tested include AI diagnostic module adoption velocity and private imaging chain roll-up pace. Segmentation modeling spans product type, end user category, technology architecture, and clinical application across the projection horizon. CAGRs derive from replacement cycle analysis calibrated to capital budget elasticity by hospital tier, with elasticity coefficients validated against historical tender outcome patterns.
Macroeconomic conditions sit as an overlay; deviation in provincial healthcare expenditure growth or RMB exchange rate stability would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and technology substitution thresholds. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Spain Contraceptive Devices Market
Medical Devices
Global Live Cell Encapsulation Market
Medical Devices
Global Intraosseous Devices Market
Medical Devices
APAC Ablation Devices Market
Medical Devices
EEG Electrodes Market
Medical Devices
Biliary Catheters Market
Medical Devices
Brain Base Knife Package Market
Medical Devices
Europe Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Spinal Needles Market
Medical Devices
Volumetric Arc Therapy Market
Medical Devices
Global Neurovascular Guidewires Market
Medical Devices
Implant Handpiece Market
Medical Devices
Global Holter ECG Market
Medical Devices
Global Stabilometric Platform Market
Medical Devices
Biodegradable Stents Market
Medical Devices
Global Airway Stent/Lung Stent Market