
 Sputum Ejection Machine Market | 2026-2036
Sputum Ejection Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Sputum Ejection Machine Market Analytics
Silicone polymers is rebalancing component economics as manufacturers substitute traditional rubber diaphragms in suction assemblies. Medela AG leverages its Swiss manufacturing heritage to sustain premium positioning in precision suction systems. Philips Healthcare anchors its portfolio through integrated respiratory care platforms that bundle sputum ejection with ventilator ecosystems. Yuwell competes aggressively on cost-engineered portable units for Asia-Pacific price-sensitive procurement channels.
A sputum ejection machine is an electromechanical or pneumatic device engineered to generate controlled negative pressure, typically between 80 and 150 mmHg, for the mechanical aspiration of respiratory secretions from a patient's airways. The device serves the primary clinical purpose of preventing mucus accumulation, reducing infection risk, and maintaining patent airways in patients with compromised cough reflexes. Portable devices dominate unit volume due to homecare migration and ambulatory surgical expansion, while wall-mounted units command higher margin pools in tertiary hospital infrastructure. Electric technology leads installed base metrics, though ultrasonic variants represent the fastest-growing category for cystic fibrosis and bronchiectasis long-term management protocols.
FDA 510(k) premarket notification requirements govern device safety and electromagnetic compatibility for US market entry, while the EU Medical Device Regulation mandates clinical evidence and post-market surveillance through notified body conformity assessment. Japan's PMDA enforces QMS ministerial ordinances that shape design control documentation for manufacturers targeting Japanese hospital procurement tenders. Stakeholders must monitor evolving home reimbursement codes and respiratory therapist scope-of-practice regulations that will determine whether device deployment shifts decisively from inpatient to domiciliary settings.
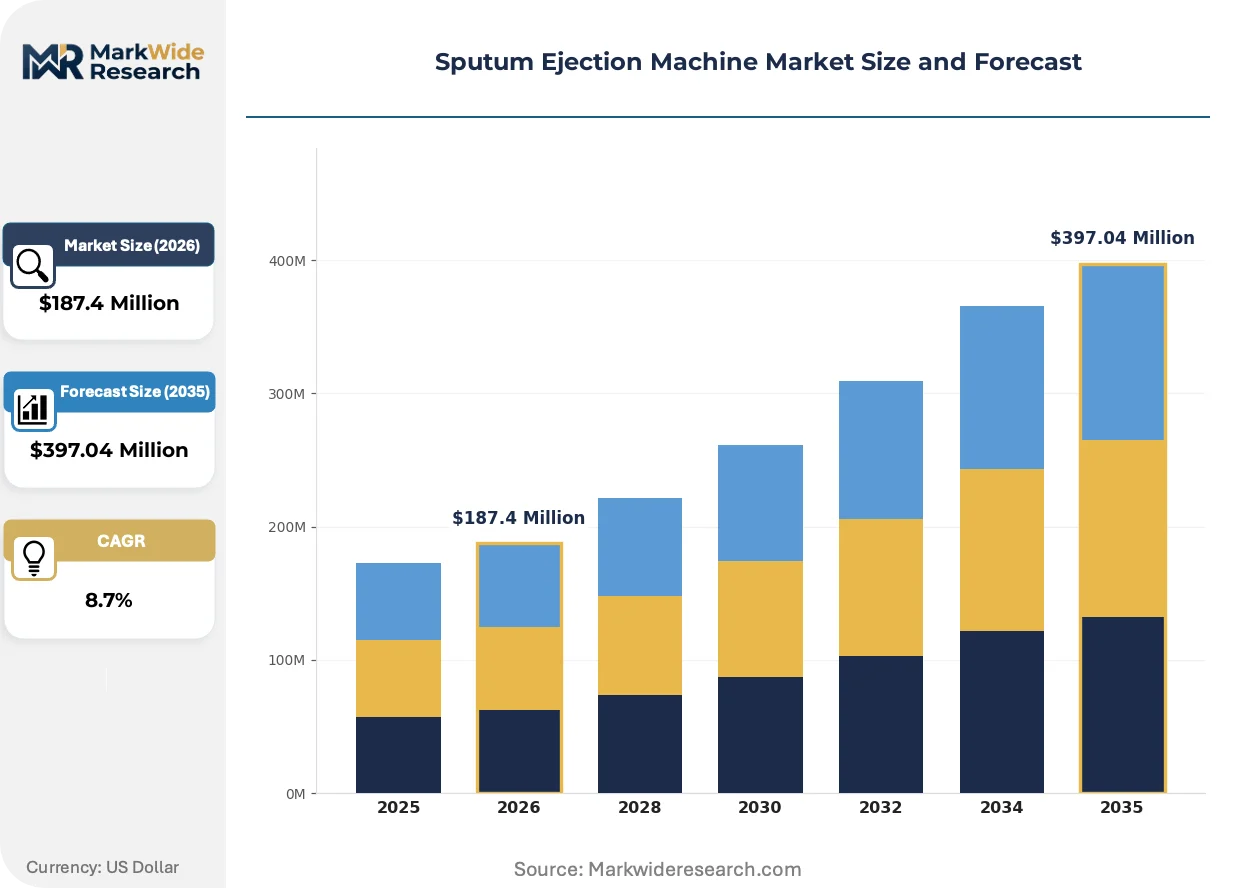
Market Dynamics
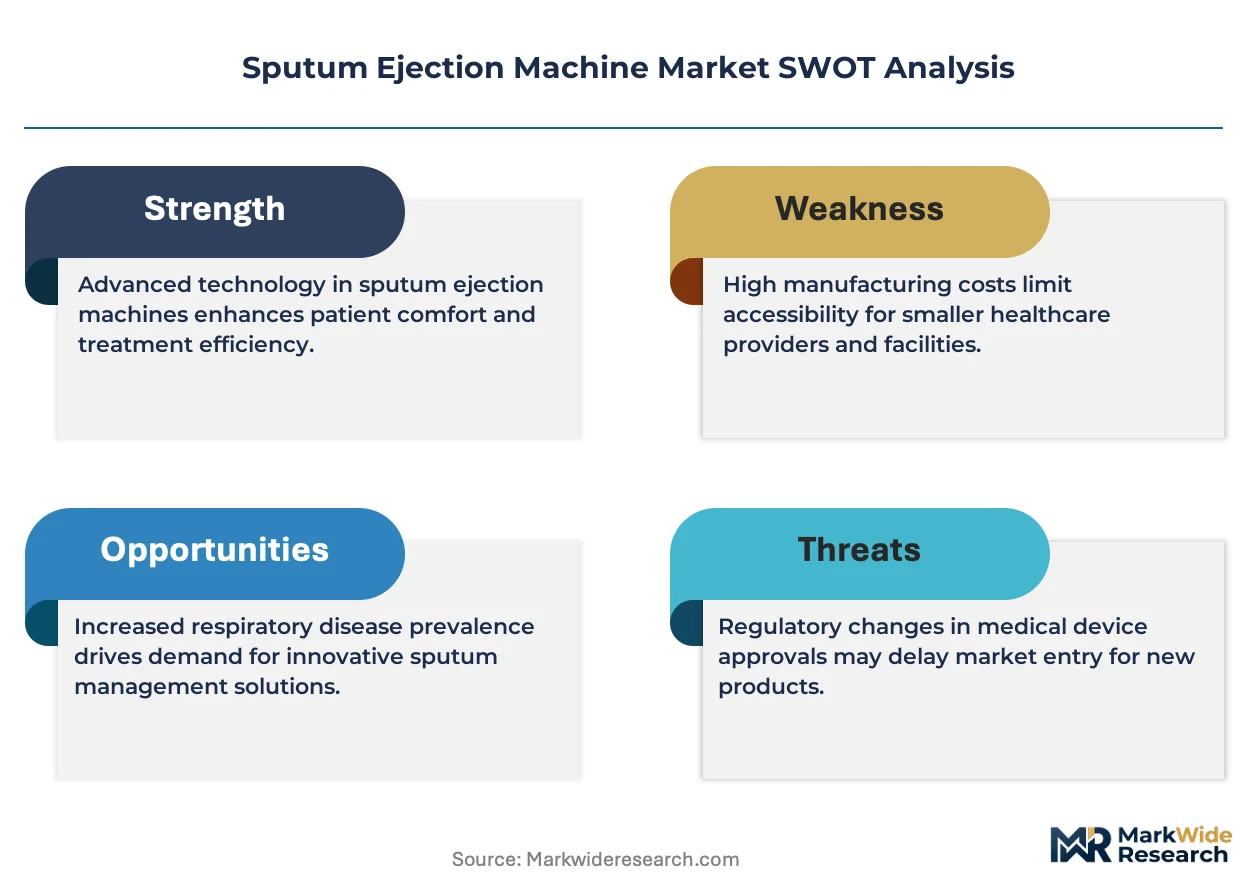
Homecare reimbursement codes are compressing hospital procurement volumes while expanding ambulatory deployment channels across respiratory therapy markets. The FDA 510(k) pathway is tightening electromagnetic compatibility documentation requirements, forcing manufacturers to revalidate legacy suction assemblies.
Growth Catalysts
- Aging Demographics:Japan's PMDA hospital procurement tenders are scaling cystic fibrosis and bronchiectasis long-term management protocols, expanding installed base for ultrasonic variants.
- Material Substitution:Silicone polymers are displacing traditional rubber diaphragms in suction assemblies, reducing component weight and improving sterilization cycle tolerance.
- EU MDR Convergence:Clinical evidence mandates and post-market surveillance requirements through notified body conformity assessment are standardizing quality benchmarks across European distribution channels.
Market Restraints
- Input Cost Volatility:Medical-grade silicone pricing fluctuates with semiconductor feedstock markets, compressing margin pools for cost-engineered portable unit manufacturers.
- Supply Concentration Risk:Precision pump motor production concentrates in German and Swiss industrial clusters, exposing downstream assemblers to single-source dependency.
- Technical Limitation:Battery energy density constraints cap portable device suction duration below wall-mounted unit performance thresholds for ICU-grade secretion clearance.
Strategic Opportunities
- Underpenetrated Geography:India's CDSCO respiratory device registration pathway remains underutilized by Western manufacturers, creating first-mover positioning in tertiary hospital infrastructure expansion.
- Technology Convergence:Integration of ultrasonic secretion disruption with ventilator ecosystem telemetry is enabling predictive suction scheduling in critical care protocols.
- Channel Innovation:Direct-to-home respiratory therapist dispensing models are bypassing durable medical equipment intermediaries in United States Medicare Advantage networks.
Industry Challenges
- Certification Timeline Compression:FDA 510(k) review queue expansion for airway clearance devices is extending time-to-revenue for product line extensions beyond historical norms.
- Legacy System Integration:Wall-mounted suction infrastructure in tertiary hospitals requires pneumatic retrofitting to accommodate electric portable unit docking stations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sputum Ejection Machine Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Device, Fixed Device, Wall-Mounted Unit, Handheld Unit End User: Hospitals, Clinics, Homecare, Emergency Services Technology: Ultrasonic, Electric, Manual, Pneumatic Application: Respiratory Disorders, Surgical Procedures, Rehabilitation, Diagnostics |
| Companies Covered | Medela AG, Philips Healthcare, Laerdal Medical, Yuwell, B. Braun Melsungen AG, Drive DeVilbiss Healthcare, Precision Medical, Olympus Corporation, ResMed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sputum Ejection Machine Market Evolving Landscape
Ultrasonic secretion disruption technology is compressing the performance gap between portable and installed-base suction systems. Regulatory documentation burdens are shifting competitive advantage toward vertically integrated manufacturers with captive clinical evidence generation capabilities.
Ultrasonic piezoelectric transducers generate controlled cavitation pulses that liquefy viscous respiratory secretions without mechanical airway trauma. Cystic fibrosis treatment centers and long-term bronchiectasis management clinics are adopting these systems at accelerating replacement cycles for conventional negative-pressure devices. This modality is rewriting the clinical standard for ambulatory secretion clearance, enabling home-based protocols that previously required hospital admission.
REACH substance restriction candidate lists are pressuring manufacturers to reformulate polymer compounds in patient-contacting suction tubing assemblies. Industrial consequence includes accelerated substitution of phthalate plasticizers with bio-based alternatives and expanded supply chain documentation requirements. German and French notified bodies are enforcing the most stringent interpretation of MDR biocompatibility testing scope, compressing time-to-market for tubing component suppliers.
Respiratory therapy departments are unbundling device procurement from disposable suction catheter supply contracts, reversing historical bundled pricing structures. Hospital purchasing cooperatives are consolidating vendor panels and demanding unit-cost transparency for both capital equipment and consumable categories. This disintermediation is most visible in United States group purchasing organization negotiations and German hospital federation tender processes.
Sputum Ejection Machine Market Segmentation
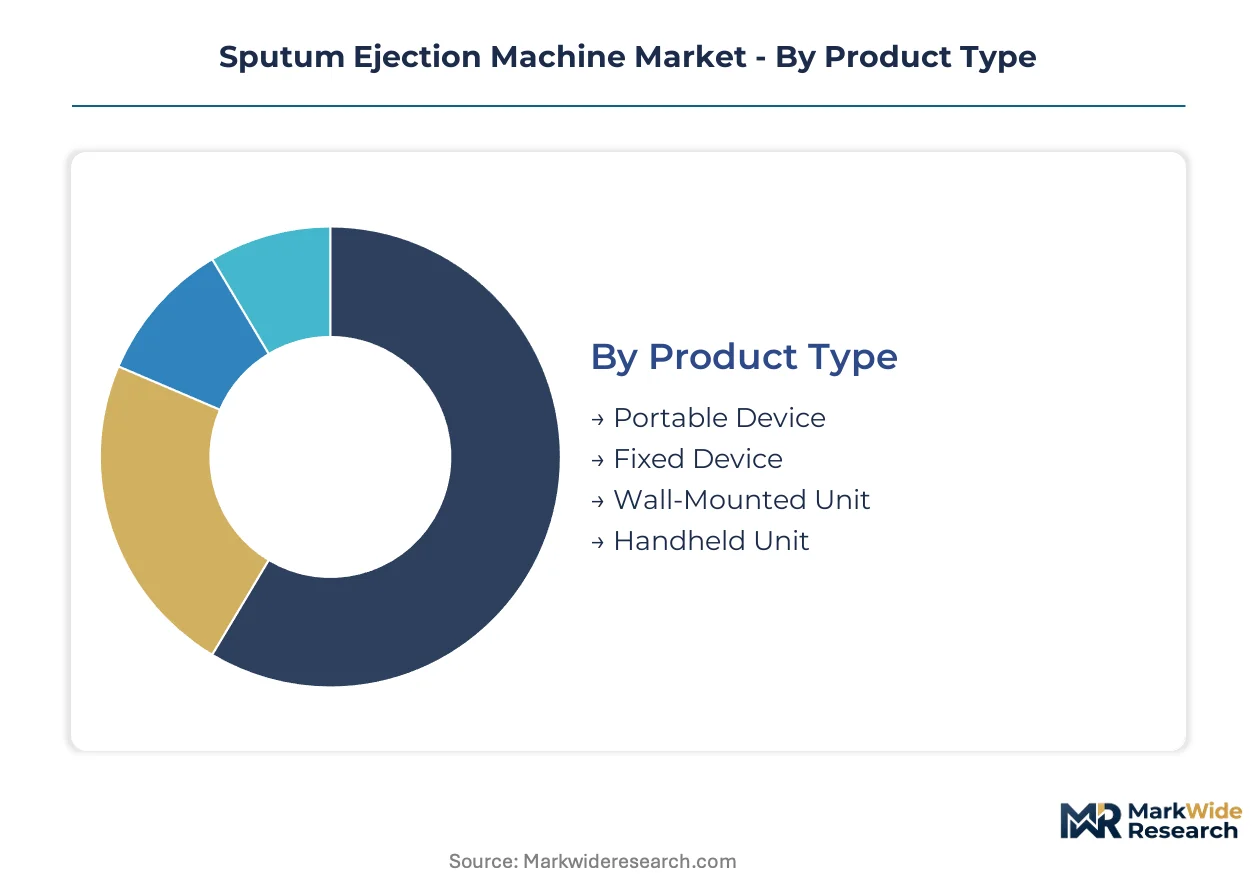
Product configuration dictates reimbursement pathways and procurement economics across respiratory care settings. Technology modality determines whether devices qualify for homecare codes or remain captive to hospital capital budgets.
Product Type:
Replacement cycles diverge sharply between installed-base infrastructure and disposable ambulatory units, reshaping manufacturer revenue recognition patterns.
- Portable Device:Battery-powered negative-pressure systems weighing under 3 kilograms enable domiciliary secretion management. Demand clusters in United States Medicare Advantage networks where respiratory therapists deploy direct-to-home dispensing models, though battery energy density constraints limit suction duration below ICU-grade thresholds.
- Fixed Device:Permanent installation units with continuous AC power deliver sustained 150 mmHg negative pressure for critical care wards. Japanese tertiary hospitals specify these for cystic fibrosis long-term management protocols, with PMDA procurement tenders favoring precision pump motor assemblies from Swiss industrial clusters.
- Wall-Mounted Unit:Pneumatic infrastructure integrated into hospital gas delivery systems requires retrofitting for electric portable docking compatibility.
- Handheld Unit:Single-patient disposable aspirators address emergency field deployment and infection isolation scenarios.
Volume placements concentrate in Portable Device configurations; the faster expansion belongs to Handheld Unit disposables.
End User:
Procurement authority fragmentation across facility types fragments pricing power and contract structures.
- Hospitals:Tertiary respiratory wards and ICU departments specify wall-mounted and fixed installations with bundled catheter supply agreements. United States group purchasing organizations are unbundling these contracts and demanding unit-cost transparency for capital equipment separately from consumables.
- Homecare:Domiciliary settings drive portable and ultrasonic device adoption where reimbursement codes now cover ambulatory secretion clearance. German hospital federation tender processes are beginning to mirror this disintermediation, compressing margin pools for durable medical equipment intermediaries.
- Clinics:Outpatient respiratory therapy centers favor mid-tier electric units for bronchiectasis patient throughput.
- Emergency Services:Pre-hospital care protocols specify lightweight pneumatic or manual backup systems for field airway management.
Revenue concentration sits with Hospitals; Homecare channels are climbing the fastest.
Technology:
Clinical evidence requirements under EU MDR and FDA 510(k) pathways favor modalities with established biocompatibility documentation.
- Ultrasonic:Piezoelectric transducers generate controlled cavitation pulses that liquefy viscous secretions without mechanical trauma. Cystic fibrosis treatment centers in Japan and Germany are accelerating replacement cycles for conventional negative-pressure devices, enabling home-based protocols that previously required admission.
- Electric:Motor-driven piston or rotary vane pumps dominate installed base metrics with proven electromagnetic compatibility profiles. REACH substance restrictions are forcing reformulation of polymer compounds in patient-contacting assemblies, compressing time-to-market for tubing suppliers facing German and French notified body scrutiny.
- Manual:Hand-powered bulb or foot-pump systems serve backup and resource-limited settings without electrical dependency.
- Pneumatic:Compressed gas-driven aspirators integrate with existing hospital infrastructure but face retrofitting costs for electric docking compatibility.
Installed base dominance belongs to Electric systems; Ultrasonic modalities are gaining share fastest.
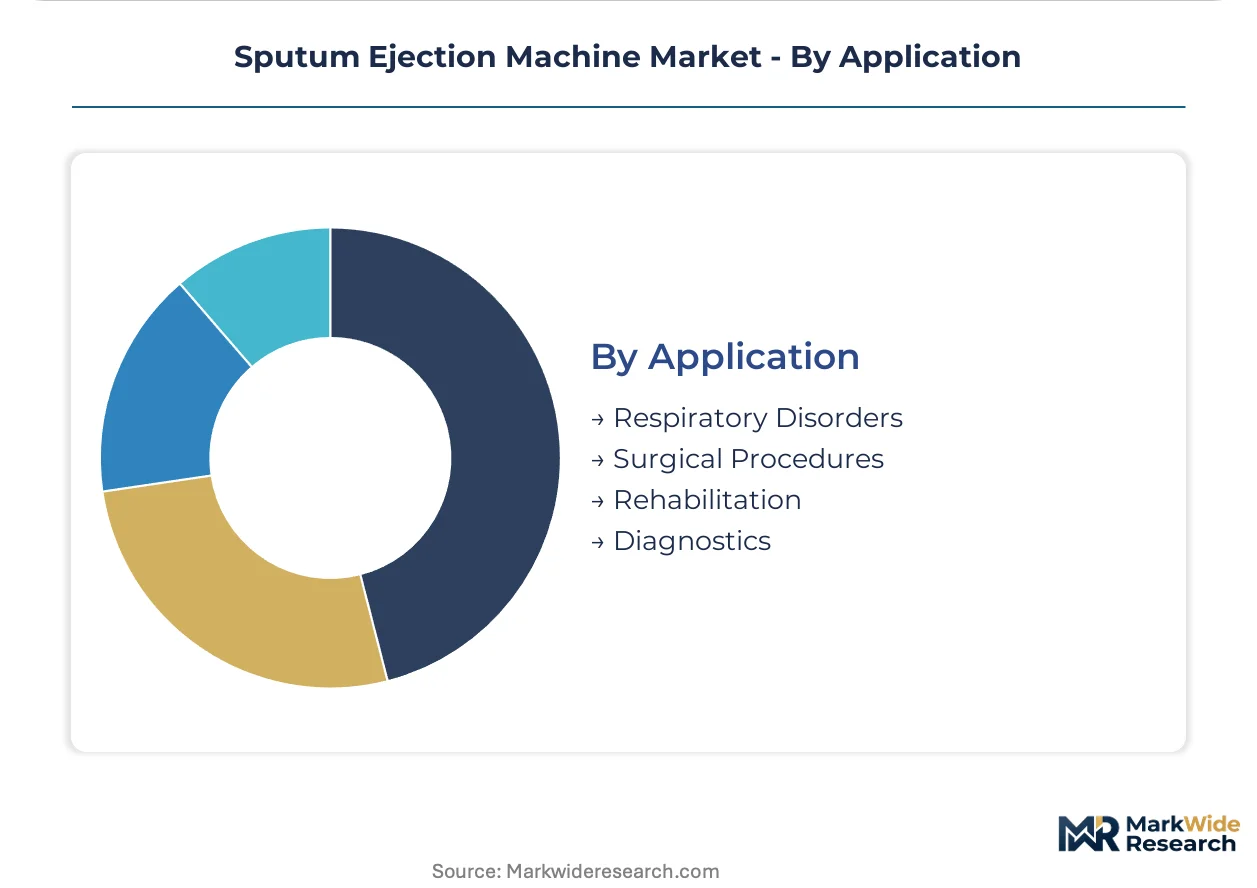
Application:
Indication-specific protocols determine device specification, suction pressure parameters, and disposable compatibility requirements.
- Respiratory Disorders:Chronic obstructive pulmonary disease, bronchiectasis, and cystic fibrosis management protocols require daily or multi-daily secretion clearance. Japan's aging demographic expansion is scaling PMDA hospital procurement tenders for ultrasonic variants in long-term management settings.
- Surgical Procedures:Operating room and post-anesthesia care unit suction demands high-flow capacity with sterile disposable circuits. Ambulatory surgical center expansion in the United States is migrating volume from inpatient to same-day discharge settings.
- Rehabilitation:Post-extubation and neuromuscular weakness protocols employ portable units for gradual weaning from mechanical support.
- Diagnostics:Sputum collection for microbiological analysis requires controlled low-pressure aspiration to preserve cellular morphology.
Procedure volume concentrates in Respiratory Disorders; Rehabilitation applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, Germany, and Japan as aging populations expand chronic obstructive pulmonary disease treatment needs. Hospital respiratory wards in these markets are accelerating procurement of precision suction systems. Regulatory pathways in each jurisdiction are tightening electromagnetic compatibility and clinical evidence requirements.
United States
Medicare Advantage networks are deploying direct-to-home respiratory therapist dispensing models for portable secretion management devices. FDA 510(k) premarket notification requirements govern device safety and electromagnetic compatibility for market entry. Greater Boston and the Pacific Northwest host precision medical device clusters where manufacturers revalidate legacy suction assemblies.
Germany
German hospital federation tender processes are unbundling device procurement from disposable suction catheter supply contracts. EU Medical Device Regulation mandates clinical evidence and post-market surveillance through notified body conformity assessment. Baden-Württemberg and Bavaria concentrate precision pump motor production in industrial clusters supplying downstream assemblers.
Japan
PMDA hospital procurement tenders are scaling cystic fibrosis and bronchiectasis long-term management protocols for ultrasonic variants. Japan's PMDA enforces QMS ministerial ordinances that shape design control documentation for manufacturers. Kanto and Kansai regions anchor tertiary hospital infrastructure where fixed installation units command premium positioning.
India
Tertiary hospital infrastructure expansion is creating first-mover positioning for Western manufacturers in underserved metropolitan markets. CDSCO respiratory device registration pathways remain underutilized relative to patient volume potential. Maharashtra and Karnataka are emerging as procurement hubs where cost-engineered portable units penetrate price-sensitive channels.
Switzerland
Swiss manufacturing heritage sustains premium positioning in precision suction systems for European and Asian export markets. Swissmedic conformity assessment procedures align with EU MDR benchmarks while maintaining distinct documentation requirements. Zurich and Basel industrial corridors concentrate electromechanical component production for integrated respiratory care platforms.
Sputum Ejection Machine Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hospital procurement favoring established names and homecare channels opening to cost-optimized alternatives. The vendor base organizes into three tiers: precision-engineered premium specialists, integrated respiratory platform providers, and volume-oriented portable unit fabricators. Strategic moves concentrate on backward integration into pump motor supply and geographic expansion through regulatory first-mover positioning in underpenetrated jurisdictions.
Among Swiss and German precision specialists, Medela AG and B. Braun Melsungen AG exemplify the premium-engineering archetype with manufacturing heritage positioning. Yuwell occupies a position within the cost-optimized portable tier, competing aggressively on price-engineered units for Asia-Pacific procurement channels. Philips Healthcare anchors the integrated platform archetype, bundling sputum ejection capabilities within broader ventilator ecosystem offerings.
| Leading Market Players |
|---|
| Medela AG |
| Philips Healthcare |
| Laerdal Medical |
| Yuwell |
| B. Braun Melsungen AG |
| Drive DeVilbiss Healthcare |
| Precision Medical |
| Olympus Corporation |
| ResMed |
| Others |
Value Network & Pricing Analysis
Hospital purchasing cooperative consolidation in the United States and German hospital federation tender unbundling are forcing manufacturers to separate capital equipment from disposable catheter pricing, compressing blended margins and redirecting sourcing toward modular component suppliers capable of standalone contract fulfillment.
Pricing Analysis
Portable device volumes dominate unit placements while fixed installations and wall-mounted systems capture premium margin pools. Three-tier pricing structure across precision Swiss-engineered, mid-tier electric, and cost-engineered portable levels reflects certification grade and pump motor origin differentiation. Pricing pressure stems from Medicare Advantage reimbursement compression in domiciliary channels. Homecare procurement shows highest price sensitivity; Japanese PMDA-certified fixed units show lowest.
Supply Chain Analysis
Precision pump motor supply rests on German and Swiss industrial clusters, with silicone polymer feedstock drawing from semiconductor-linked chemical producers in Japan and the United States. Medical-grade silicone diaphragms, piezoelectric transducers, and battery cell assemblies constitute critical input dependencies. Single-source vulnerability concentrates in precision motor winding capabilities. Distribution runs through hospital group purchasing organizations, durable medical equipment intermediaries, and direct-to-home respiratory therapist networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision pump motor production capacity constraints in German and Swiss industrial clusters prop pricing power for manufacturers with captive supply or long-term offtake agreements, sustaining margin premiums despite downstream procurement pressure.
For Market Incumbents: Acquire precision pump motor production capacity or binding supply commitments from Baden-Württemberg and Bavaria industrial clusters. Secure FDA 510(k) premarket notification clearance for ultrasonic variant line extensions before review queue expansion extends time-to-revenue. Counter Yuwell's cost-engineered portable penetration through backward integration into silicone polymer compounding. For New Entrants and Emerging Players: Begin with CDSCO respiratory device registration pathway entry into Indian tertiary hospital infrastructure expansion in Maharashtra and Karnataka. Target price-sensitive Asia-Pacific procurement channels with battery-optimized portable units under 3 kilograms. Pursue direct-to-home respiratory therapist dispensing partnerships bypassing durable medical equipment intermediaries in United States Medicare Advantage networks. For Investors and Strategic Acquirers: The window for entry favors manufacturers with vertical integration into piezoelectric transducer or precision motor supply. Target mid-cap specialists with EU MDR notified body relationships and Japanese PMDA QMS documentation capabilities. Watch FDA 510(k) review queue duration and EU MDR clinical evidence mandate enforcement intensity as inflection indicators for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR notified body conformity assessment accelerates European distribution channel access. |
| Backward Integration | Captive precision pump motor production insulates margin pools from German supply concentration risk. |
| Hospital System Partnership | United States group purchasing organization panel consolidation favors integrated platform vendors. |
| Reimbursement Strategy | Medicare Advantage homecare code expansion enables direct-to-home respiratory therapist dispensing models. |
| Software Companion Development | Ventilator ecosystem telemetry integration enables predictive suction scheduling in critical care protocols. |
Research Methodology
Document review covered FDA 510(k) premarket notification databases, EU MDR notified body conformity assessment records, Japanese PMDA QMS ministerial ordinances, and hospital procurement tender documentation, complemented by interviews with respiratory therapists, biomedical engineers, hospital purchasing committee members, and GPO contracts managers. Secondary sources included CMS Medicare reimbursement code databases, CDSCO respiratory device registration filings, and Swissmedic conformity assessment procedures. Bottom-up unit shipment estimates triangulated against top-down expenditure flow analysis.
Historical shipment trajectories cross-referenced against panel input from procurement directors and regulatory affairs specialists shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass product configuration, technology modality, end-use setting, and geographic regulatory cluster. CAGRs derived from fitted growth curves applied to validated base-year estimates. Forecast inputs incorporated PMDA hospital tender scaling patterns and REACH substance restriction implementation timelines.
Underlying measurement precision varies by segment; electric technology installed base metrics carry tighter precision than emerging ultrasonic category estimates. Forecasts reflect documented assumptions regarding reimbursement code expansion and regulatory review queue dynamics. Regulatory timeline delays, silicone feedstock price volatility, and battery energy density constraint resolution warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Manual Resuscitators Market
Medical Devices
Global Body Composition Analyzers Market
Medical Devices
Global Cerebrospinal Fluid Management Devices Market
Medical Devices
Bilirubin Meters Market
Medical Devices
Global Active Implantable Medical Devices Market
Medical Devices
Intravenous Transportation System Market
Medical Devices
Cerebral Thrombectomy Devices Market
Medical Devices
Australia Drug Delivery Devices Market
Medical Devices
Artificial Vital Organs and Medical Bionics Market
Medical Devices
Rechargeable Medical Battery Market
Medical Devices
Enteral Feeding Devices Market
Medical Devices
South Korea Minimally Invasive Surgery Devices Market
Medical Devices
Middle East and Africa Biomedical Sensors Market
Medical Devices
Global Portable Ultrasound Equipment Market
Medical Devices
Laser Aesthetic Devices Market
Medical Devices
Global Wearable Skin Patch Market