
 Neuro Navigation System Market | 2026-2036
Neuro Navigation System Market Size, Share, and Industry Trends Forecast 2026-2036
Neuro Navigation System Market Insights
Software-defined surgical planning modules is expanding the recurring revenue base for navigation vendors beyond capital equipment sales. Medtronic leverages its installed base of surgical platforms to sustain service contract renewals across major hospital networks. Stryker anchors its competitive stance through R&D intensity in optical tracking subsystems. Brainlab AG specializes in electromagnetic navigation configurations for cranial applications.
A neuro navigation system integrates patient imaging data with real-time instrument tracking to provide spatial guidance during cranial or spinal procedures, typically achieving sub-millimeter accuracy through infrared camera arrays or electromagnetic field generators. The device fuses preoperative CT or MRI datasets with intraoperative positional feedback to enable minimally invasive trajectories. Optical navigation retains the largest installed base among product type categories while robotic navigation represents the fastest-expanding segment due to rising integration with stereotactic platforms. MRI integration technology commands premium positioning in tumor resection workflows where soft-tissue contrast determines surgical margins. Hospitals constitute the dominant end user channel though neurosurgery centers are capturing disproportionate growth in ambulatory settings.
FDA 510(k) clearance pathways and EU MDR conformity requirements shape product development timelines and software documentation burdens for manufacturers seeking market access. ISO 13485 quality management standards and IEC 60601 electrical safety protocols further constrain design choices for electromagnetic field emissions in operating theater environments. Stakeholders must monitor evolving reimbursement coding for image-guided surgery procedures across Medicare and national health service frameworks to anticipate capital budget allocation shifts.
Market Dynamics
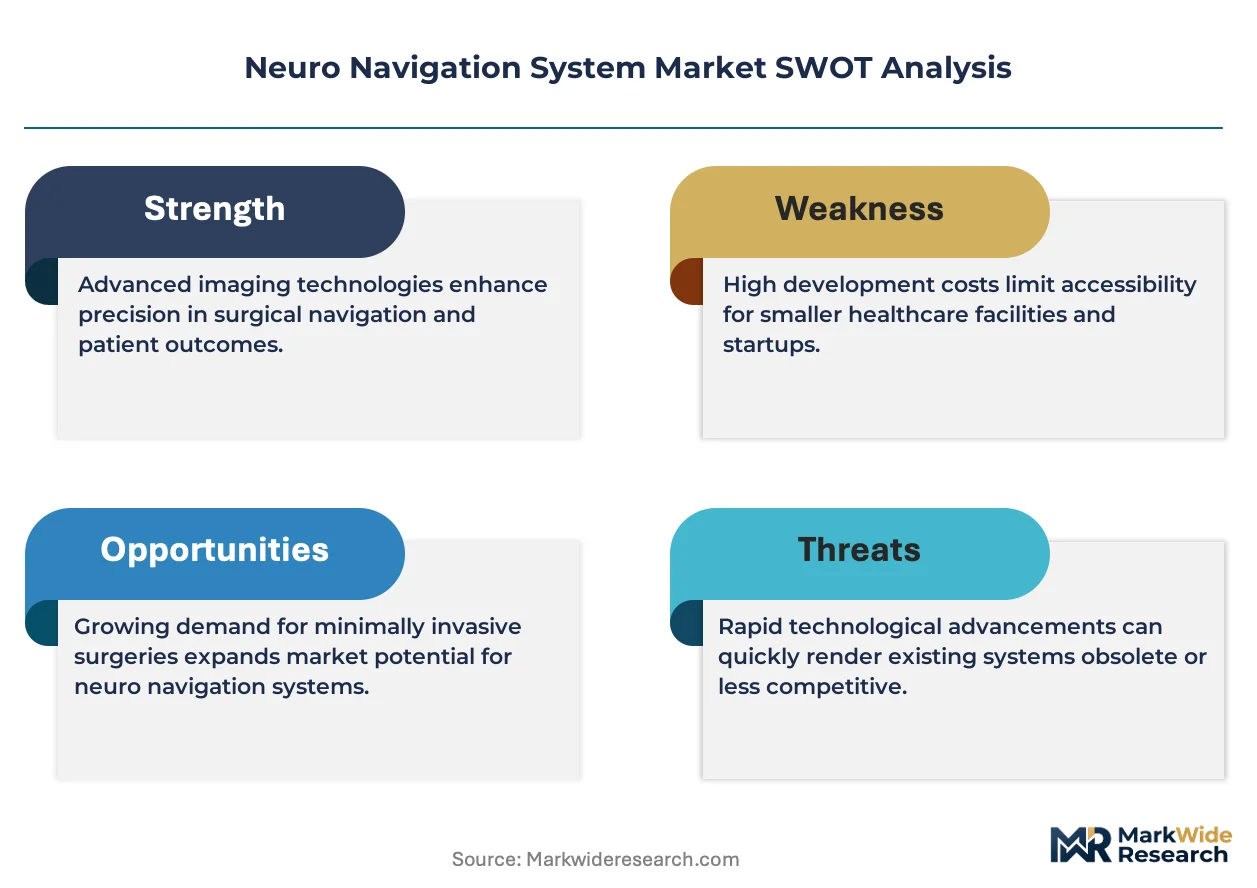
Software validation burdens from FDA 510(k) and EU MDR are elongating product development cycles while hospitals consolidate vendor relationships around platforms with established regulatory track records. This regulatory friction is compressing the competitive field toward incumbents with dedicated compliance infrastructure.
Growth Catalysts
- EU MDR Conformity Assessments:Stricter software documentation requirements for Class IIb surgical navigation devices are filtering out marginal competitors and concentrating procurement among validated suppliers. German hospital networks now mandate MDR-certified platforms for capital allocations.
- Ambulatory Neurosurgery Centers:Freestanding surgical facilities in the United States are installing compact electromagnetic navigation systems to capture outpatient spine procedures shifting from inpatient settings.
- MRI-CT Fusion Algorithms:Real-time multimodal imaging registration is enabling sub-millimeter tumor margin delineation in cranial resections, driving replacement demand for legacy optical-only systems.
Market Restraints
- Electromagnetic Field Interference:IEC 60601 electrical safety protocols constrain field generator power output in operating theaters, limiting tracking volume for large-patient cranial applications.
- Neodymium Magnet Supply Concentration:Rare-earth magnet sourcing dependence on Chinese processing facilities creates input cost volatility for electromagnetic navigation subsystem manufacturers.
- Capital Equipment Replacement Cycles:Seven-to-ten-year depreciation schedules for installed navigation platforms delay upgrade decisions even when accuracy specifications lag current standards.
Strategic Opportunities
- Japan's Aging Surgical Workforce:PMDA fast-track pathways for AI-augmented navigation interfaces address precision deficits from declining resident training hours in Japanese academic medical centers.
- Robotic Stereotactic Convergence:Integration of optical tracking with programmable surgical arms is opening minimally invasive biopsy workflows previously requiring open craniotomy approaches.
- United States Medicare Reimbursement:CPT code expansions for image-guided navigation in spinal fusion procedures are unlocking capital budget releases at community hospitals.
Industry Challenges
- ISO 13485 Quality Management Implementation:Small navigation software developers struggle to resource full design history file documentation for FDA submissions without dedicated regulatory affairs staff.
- Legacy PACS Integration Complexity:Hospital IT departments face extended validation timelines when connecting new navigation platforms to proprietary imaging archive systems from incumbent vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neuro Navigation System Market |
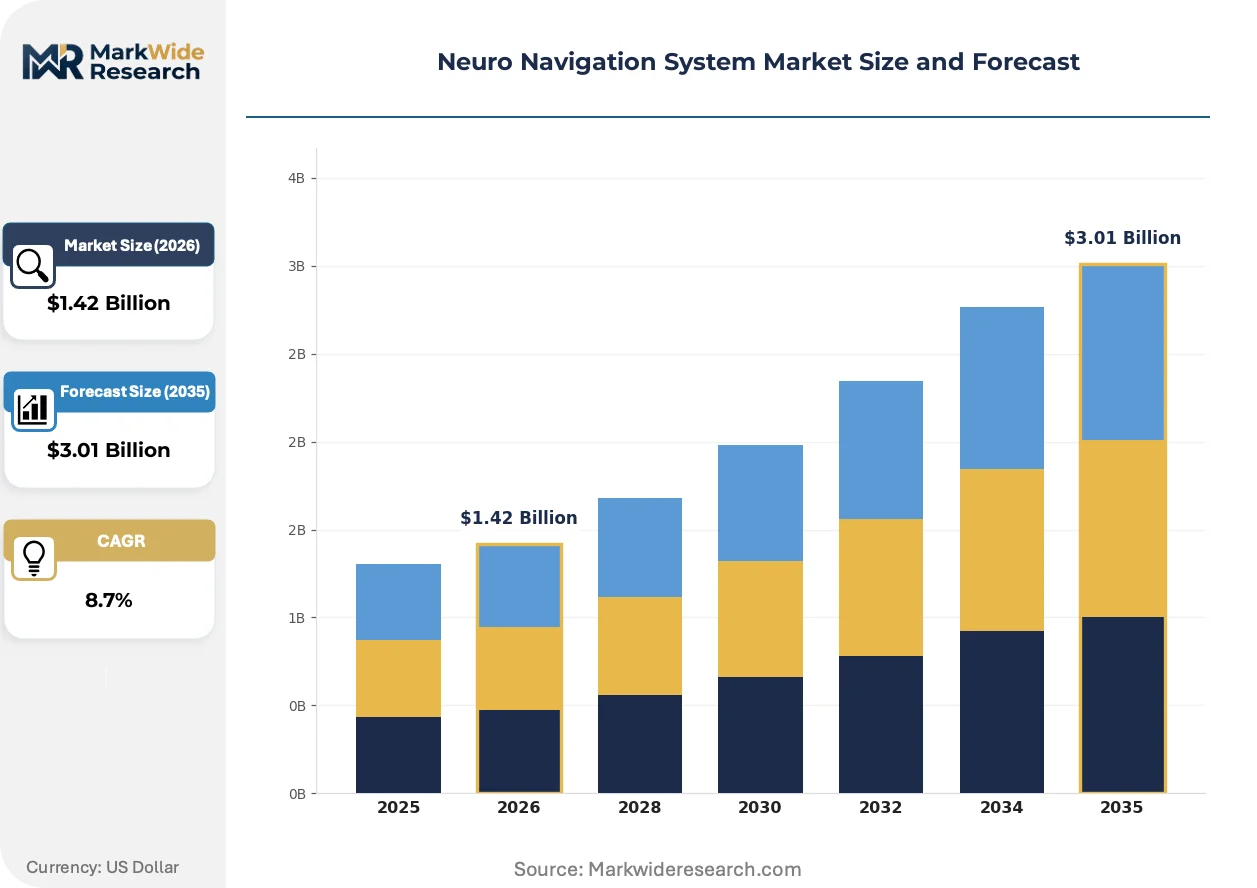
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intraoperative Navigation, Electromagnetic Navigation, Optical Navigation, Robotic Navigation Technology: CT Imaging, MRI Integration, Ultrasound, 3D Imaging End User: Hospitals, Neurosurgery Centers, Research Institutions, Specialty Clinics Application: Spinal Surgery, Tumor Resection, Epilepsy Surgery, Functional Neurosurgery |
| Companies Covered | Medtronic, Stryker, Brainlab AG, Northern Digital Inc., ClaroNav, Synaptive Medical, Zimmer Biomet, 7D Surgical, Parsis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neuro Navigation System Market Trends and Innovations
Real-time computational imaging and machine learning registration algorithms are compressing the gap between preoperative planning and intraoperative adaptation. These advances are redefining accuracy benchmarks and service delivery models simultaneously.
Machine learning-based anatomical segmentation is absorbing the manual landmark identification bottleneck in surgical planning workflows. Academic medical centers in Germany and the United States are deploying these tools for complex cranial base approaches. The technology is absorbing hours of preoperative preparation into automated preprocessing that occurs during image transfer.
FDA's evolving guidance on artificial intelligence-enabled medical devices is requiring adaptive algorithm documentation for navigation software with self-optimizing registration protocols. Manufacturers must now submit predetermined change control plans describing how machine learning models will evolve post-clearance. Optical tracking vendors with embedded AI subsystems face the steepest compliance burden as they retrofit quality management systems for continuous learning oversight.
Hospital procurement committees are unbundling capital equipment acquisitions from mandatory multi-year service contracts that historically subsidized platform pricing. Neurosurgery centers in Japan and select United States metropolitan markets now negotiate tracking hardware and software licenses separately from technical support. This unbundling exposes pure-play navigation vendors to price transparency pressures while favoring diversified suppliers with captive service organizations.
Neuro Navigation System Market Segmentation
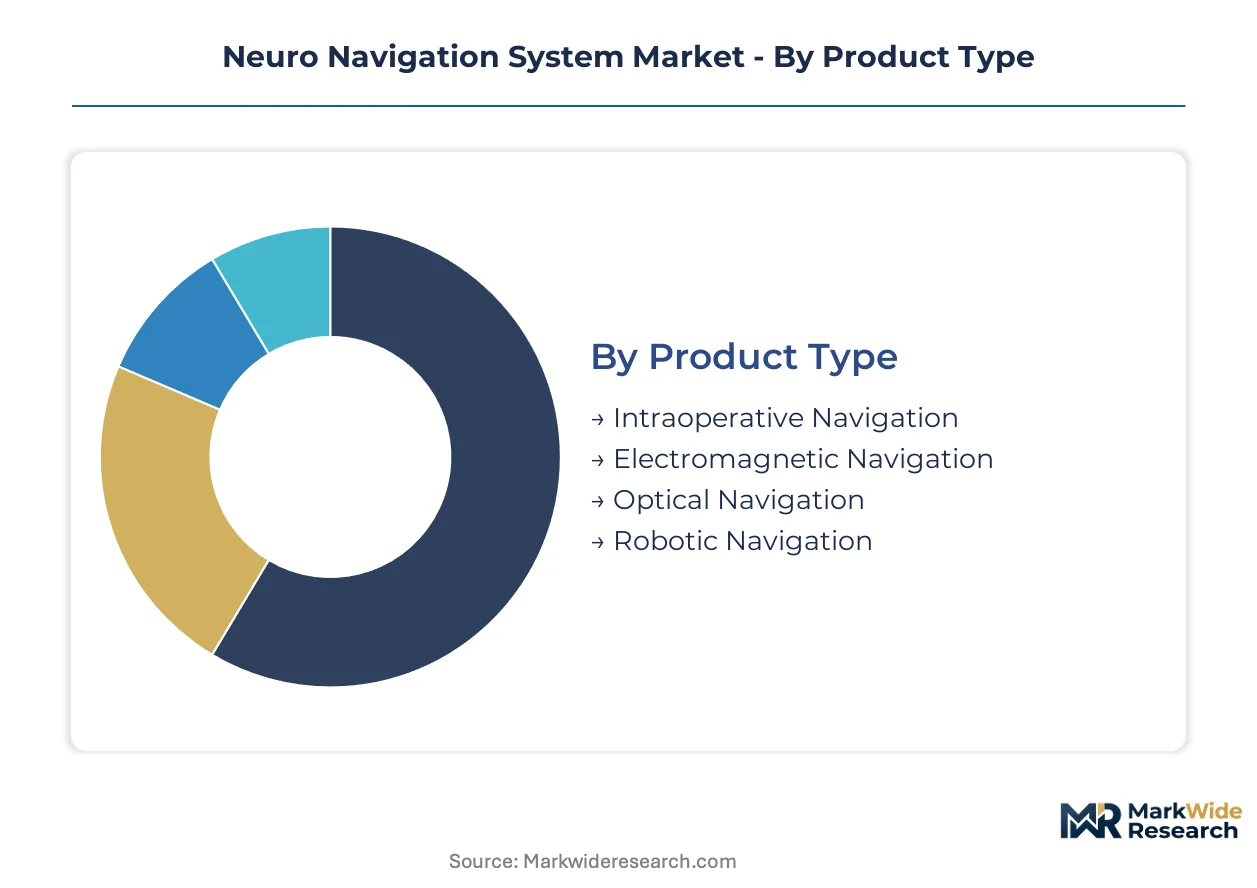
Segmentation in neuro navigation systems reflects divergent capital deployment strategies across healthcare infrastructure tiers. Technology choices determine reimbursement eligibility and regulatory pathway complexity, while end-user concentration shapes vendor go-to-market economics.
Product Type:
Capital intensity varies dramatically across tracking modalities, with electromagnetic and robotic platforms demanding substantially higher upfront investment than optical systems.
- Optical Navigation:Infrared camera arrays triangulate instrument position using reflective markers attached to surgical tools. United States hospital networks concentrate procurement here due to established FDA 510(k) clearance histories and predictable service cost structures.
- Robotic Navigation:Programmable surgical arms integrate with stereotactic frames to execute preplanned trajectories with sub-millimeter repeatability. German neurosurgery centers are deploying these platforms for minimally invasive biopsy workflows previously requiring open approaches.
- Intraoperative Navigation:Real-time imaging fusion platforms enable dynamic surgical plan adjustment during cranial procedures.
- Electromagnetic Navigation:Field generators track instrument position without line-of-sight constraints, suiting compact ambulatory installations.
Optical navigation absorbs the bulk of installed capacity; robotic navigation is expanding most quickly.
Technology:
Imaging modality selection determines soft-tissue resolution capabilities and hardware integration costs for navigation platform manufacturers.
- MRI Integration:Real-time magnetic resonance imaging provides superior contrast for tumor margin delineation during resection procedures. Japanese academic medical centers prioritize this technology for complex cranial base approaches where soft-tissue visualization determines surgical outcomes.
- CT Imaging:Computed tomography delivers rapid bone-structure visualization essential for spinal instrumentation placement. United States community hospitals standardize on CT-based navigation for degenerative spine procedures given Medicare reimbursement alignment.
- 3D Imaging:Volumetric reconstruction enables patient-specific anatomical modeling for preoperative planning.
- Ultrasound:Portable imaging supports intraoperative adaptation without radiation exposure concerns.
CT imaging commands the largest installed base; MRI integration is climbing the fastest as tumor resection volumes rise.
End User:
Procurement authority and budget scale differentiate customer segments, with hospitals consolidating vendor relationships while ambulatory sites prioritize capital efficiency.
- Hospitals:Integrated delivery networks negotiate enterprise-wide navigation platform contracts spanning multiple surgical service lines. United States health systems are unbundling hardware acquisitions from mandatory service agreements, pressuring pure-play vendors.
- Neurosurgery Centers:Freestanding surgical facilities in United States metropolitan markets install compact electromagnetic systems to capture outpatient spine procedures shifting from inpatient settings.
- Research Institutions:Academic medical centers validate emerging navigation algorithms and train surgical residents on advanced platforms.
- Specialty Clinics:Focused practices deploy single-modality navigation for high-volume specific procedures.
Hospitals absorb the bulk of installed capacity; neurosurgery centers are gaining share fastest as ambulatory migration accelerates.
Application:
Procedure complexity and reimbursement coding determine navigation system feature requirements across surgical specialties.
- Tumor Resection:Cranial oncology procedures demand sub-millimeter accuracy for margin delineation near eloquent brain regions. German hospital networks mandate MDR-certified platforms with real-time MRI fusion for these high-stakes interventions.
- Spinal Surgery:Pedicle screw placement and interbody fusion procedures utilize navigation to reduce radiation exposure from fluoroscopic guidance. United States Medicare CPT code expansions are unlocking capital budget releases at community hospitals for these workflows.
- Epilepsy Surgery:Stereotactic electrode placement for seizure focus localization requires precise trajectory planning.
- Functional Neurosurgery:Deep brain stimulation targeting for movement disorders depends on accurate anatomical mapping.
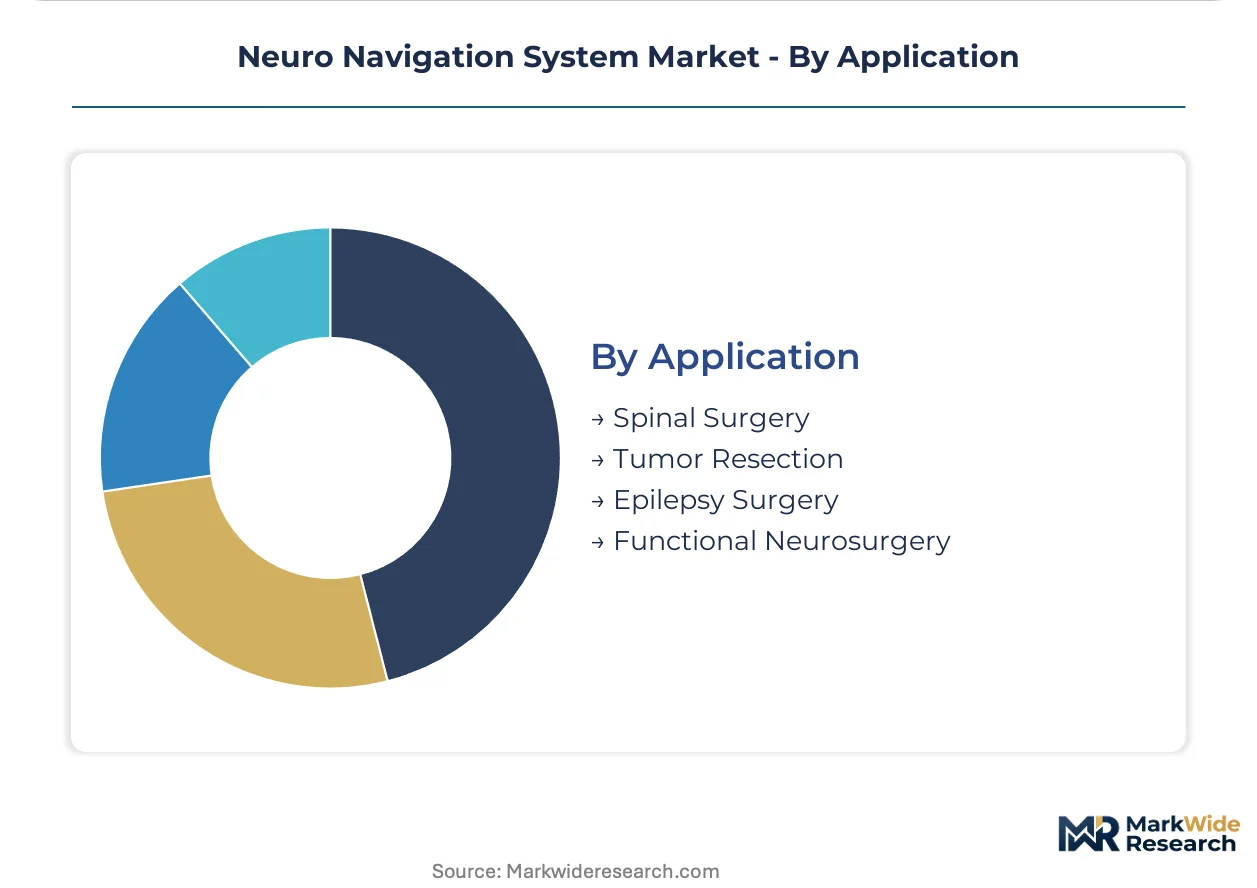
Spinal surgery absorbs the bulk of navigation system utilization; tumor resection is gaining share fastest as oncology volumes expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Navigation system production concentrates among specialized device manufacturers in Germany, Japan, and the United States, while consumption spreads across hospital networks in all three markets plus emerging demand from neurosurgery centers in Canada and Australia.
United States
FDA 510(k) clearance pathways and Medicare CPT code expansions for spinal fusion procedures drive procurement at community hospitals and academic medical centers alike. The agency's evolving guidance on AI-enabled medical devices now requires predetermined change control plans for navigation software with adaptive algorithms. Cleveland Clinic and Mayo Clinic anchor validation networks for emerging registration technologies in Ohio and Minnesota.
Germany
EU MDR conformity assessments for Class IIb surgical navigation devices filter procurement toward validated suppliers with dedicated compliance infrastructure. German hospital networks now mandate MDR-certified platforms for capital allocations, compressing the competitive field. The Munich-Berlin corridor hosts concentrated R&D activity in optical tracking subsystems and MRI fusion technologies.
Japan
PMDA fast-track pathways for AI-augmented navigation interfaces address precision deficits from declining resident training hours in academic medical centers. METI funding programs support domestic development of electromagnetic field generators with reduced interference profiles. Tokyo and Osaka medical districts deploy premium MRI-integrated platforms for complex cranial base tumor resections.
Canada
Health Canada licensing requirements align with FDA validation standards, enabling streamlined cross-border technology transfer from United States manufacturers. Provincial health authorities in Ontario and Quebec consolidate navigation platform procurement through shared service organizations. Toronto's University Health Network validates machine learning-based anatomical segmentation tools for surgical planning workflows.
Australia
TGA conformity assessment procedures for active implantable medical devices extend to navigation systems with electromagnetic field generators. Public hospital procurement in New South Wales and Victoria prioritizes platforms with established ISO 13485 quality management certification. Melbourne's Royal Melbourne Hospital anchors clinical validation partnerships for intraoperative imaging fusion technologies.
Neuro Navigation System Market Competitive Landscape
Top-tier vendors anchor the premium navigation tier, while mid-scale specialists and regional fabricators occupy subordinate positions. The field compresses toward incumbents with dedicated regulatory affairs infrastructure capable of absorbing FDA and EU MDR documentation burdens. Three archetypes dominate: diversified medical technology conglomerates leveraging installed base relationships, pure-play navigation specialists defending technical differentiation, and emerging robotic platform integrators. Competitive moves concentrate on unbundling hardware from service contracts and securing fast-track regulatory pathways for AI-augmented interfaces.
Among diversified medical technology conglomerates, Medtronic and Stryker exemplify archetypes built on sustained service contract renewal engines across major hospital networks. Brainlab AG occupies a distinct position as a specialized navigation vendor with concentrated expertise in electromagnetic configurations for cranial applications.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Brainlab AG |
| Northern Digital Inc. |
| ClaroNav |
| Synaptive Medical |
| Zimmer Biomet |
| 7D Surgical |
| Parsis |
| Others |
Pricing and Supply Chain Analysis
Neodymium magnet sourcing from Chinese processing facilities feeds directly into electromagnetic navigation subsystem costs, cascading through three-tier pricing structures that separate MRI-integrated premium platforms from compact ambulatory systems and refurbished optical installations. This input concentration amplifies margin volatility for mid-scale vendors lacking captive rare-earth supply arrangements.
Pricing Analysis
Cost-down pressure on standard-tier optical systems accelerates because hospital procurement committees now unbundle hardware from mandatory service contracts that historically subsidized platform pricing. Pricing stratifies across premium MRI-fusion configurations, standard CT-based installations, and economy refurbished units, with differentiation anchored in FDA 510(k) clearance tier and ISO 13485 certification depth. Community hospitals in the United States exhibit highest price sensitivity, while Japanese academic medical centers absorb premium positioning for AI-augmented interfaces.
Supply Chain Analysis
Direct-to-hospital channels handle enterprise health system demand, while specialized distributors serve neurosurgery centers and ambulatory installations. Manufacturing concentrates in Germany, Japan, and the United States, with optical tracking subsystems drawing from precision optics clusters in Bavaria and electromagnetic field generators resting on rare-earth magnet processing in China. Single-source vulnerability in neodymium supply creates exposure to export restriction shocks. Distribution runs through GPO contracts at integrated delivery networks and direct vendor relationships at independent surgical facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into software-defined surgical planning modules is becoming the decisive competitive lever as vendors seek recurring revenue streams beyond capital equipment cycles.
For Market Incumbents: Deepen regulatory affairs infrastructure to absorb EU MDR documentation burdens that are filtering marginal competitors from German hospital procurement. Fortify service contract renewal engines through predictive maintenance analytics that reduce customer churn. Consolidate around platforms with established FDA 510(k) clearance histories as hospitals narrow vendor relationships. For New Entrants and Emerging Players: Begin with compact electromagnetic navigation configurations for United States ambulatory neurosurgery centers, where capital efficiency requirements and outpatient spine migration create penetrable white space. Target neurosurgery centers in metropolitan markets with unbundled hardware-plus-software licensing models that bypass incumbent service contract dominance. For Investors and Strategic Acquirers: PMDA fast-track approvals for AI-augmented navigation interfaces are the leading indicator that precision deficits from Japan's aging surgical workforce will sustain premium pricing for algorithm-enabled platforms. Target mid-scale navigation specialists with electromagnetic expertise and MDR compliance infrastructure already in place. Watch Medicare CPT code expansions for spinal fusion navigation as the signal for capital budget release timing at community hospitals.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Investment | EU MDR conformity assessments filter procurement toward validated suppliers in German hospital networks. |
| AI-Algorithm Documentation | FDA predetermined change control plans enable clearance for self-optimizing registration protocols in navigation software. |
| Service Contract Unbundling | Hospital procurement committees now negotiate tracking hardware separately from technical support agreements. |
| Electromagnetic Field Generator Development | METI funding programs support domestic Japanese production with reduced IEC 60601 interference profiles. |
| Reimbursement Strategy Alignment | Medicare CPT code expansions for spinal fusion procedures unlock capital budget releases at United States community hospitals. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with neurosurgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. FDA 510(k) clearance databases, EU MDR conformity assessment records, CMS Medicare reimbursement schedules, and hospital procurement databases provided validation layers. Bottom-up installation counts across optical, electromagnetic, and robotic navigation platforms were triangulated against top-down capital equipment spending estimates from health system financial disclosures.
Segment-level modeling tracked product type, technology, end user, application, and regional regulatory cluster across the projection horizon. CAGRs were derived from fitted growth curves against historical adoption patterns and forward-looking reimbursement trajectory assumptions. Forecast inputs incorporated PMDA fast-track pathway utilization rates, EU MDR transition timelines, and Medicare CPT code revision schedules.
Underlying measurement precision varies by segment; optical navigation installed base estimates carry tighter precision than emerging robotic platform projections. Forecasts reflect assumptions regarding reimbursement coding stability, rare-earth supply continuity, and regulatory pathway durations. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Infant Radiant Warmer Market
Medical Devices
Cerebral Thrombectomy Devices Market
Medical Devices
Global Disability Devices Market
Medical Devices
Global Cardiac Pacemakers Market
Medical Devices
Corneal Cross Linking Devices Market
Medical Devices
Pneumology Digital Stethoscope Market
Medical Devices
Global Non Fusion Spinal Devices Market
Medical Devices
Asia-Pacific Arthroscopy Devices Market
Medical Devices
Coated Endotracheal Tube Market
Medical Devices
Automated CPR Devices Market
Medical Devices
China Ophthalmic Devices Market
Medical Devices
Bluetooth Hearing Aids Market
Medical Devices
Global Urethral Dilator Market
Medical Devices
Global Wearable Healthcare Devices Market
Medical Devices
Medical Mobility Aid Market
Medical Devices
Smart Syringe Market