
 X-Ray Stretchers Market | 2026-2036
X-Ray Stretchers Market Size, Share, and Industry Trends Forecast 2026-2036
X-Ray Stretchers Market Analytics
Modular configuration of X-ray stretchers with detachable imaging plates and interchangeable accessories is restructuring how hospital procurement committees evaluate capital equipment. Stryker Corporation leverages its integrated hospital bed and stretcher portfolio to cross-sell imaging-compatible platforms. Hill-Rom Holdings, Inc. anchors its position through sustained R&D investment in pressure-relief surfaces that maintain radiolucency. Medline Industries, Inc. competes on distribution density, using its direct-to-facility logistics network to displace regional distributors.
An X-ray stretcher is a radiolucent patient transport platform engineered with carbon fiber or aluminum composite decks that permit X-ray beam penetration without repositioning the patient onto a separate imaging table. These devices incorporate load capacities exceeding 225 kg, locking caster systems, and Trendelenburg tilt mechanisms to serve trauma bays, operating suites, and intensive care units. Electric stretchers command premium placement in acute care settings where motorized height adjustment reduces staff injury risk, while manual variants sustain volume leadership in cost-constrained clinics and developing health systems. Carbon fiber decks differentiate on radiolucent clarity and weight reduction, though aluminum dominates procurement budgets across public hospital networks.
The FDA enforces 21 CFR 1020 radiological health standards for imaging system compatibility, while the EU Medical Device Regulation (MDR) mandates clinical evidence and post-market surveillance for patient transport devices marketed in Europe. ISO 13485 quality management certification has become a de facto market access threshold for OEMs supplying integrated health networks. Stakeholders must monitor how FDA guidance on radiological device cybersecurity and the EU's F-Gas Regulation affecting sterile field climate control reshape facility infrastructure requirements and stretcher specification criteria.
Market Dynamics
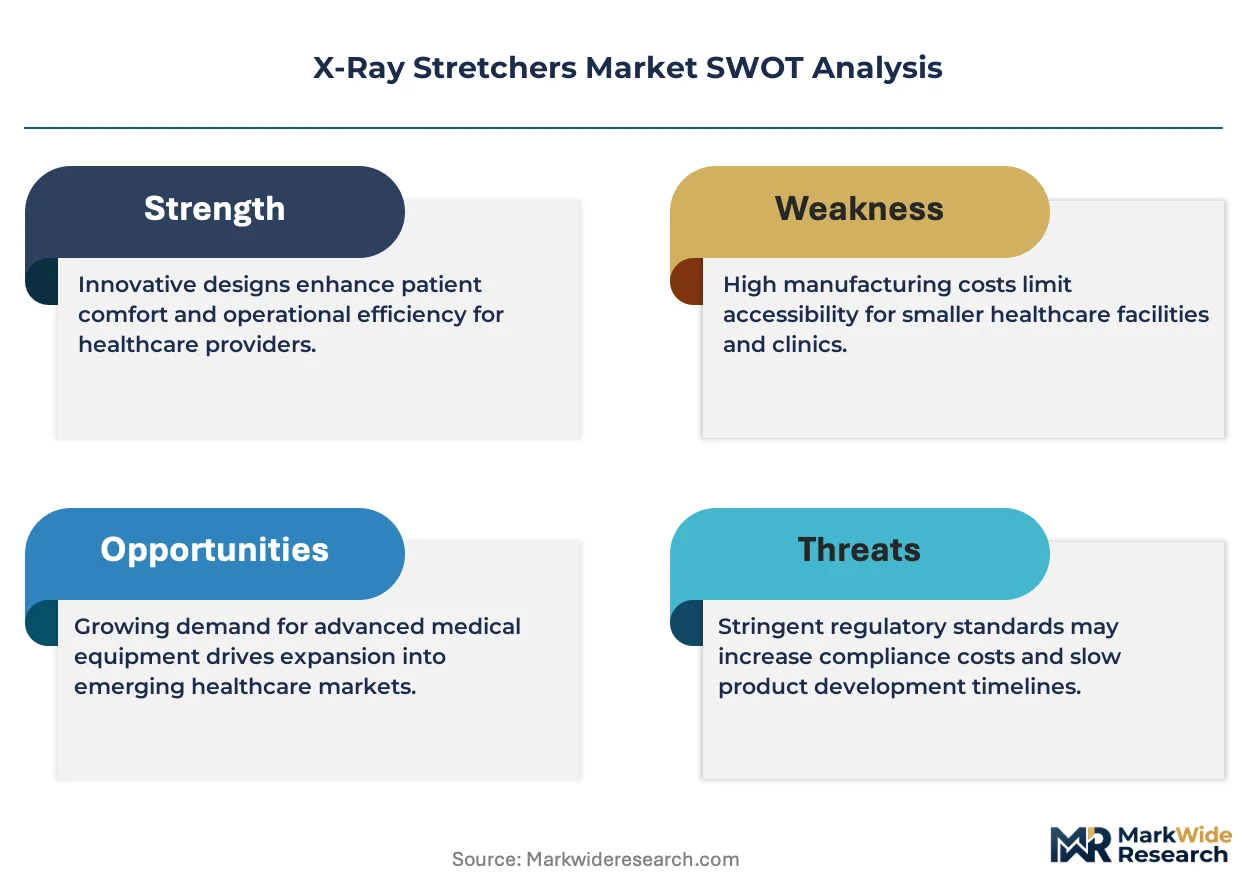
Carbon fiber deck technology is compressing procurement cycles as imaging departments prioritize radiolucent clarity over aluminum cost savings, forcing manufacturers to recalibrate material sourcing strategies and production footprints.
Growth Catalysts
- EU MDR Certification Mandates:European health systems are accelerating replacement of legacy transport equipment to meet clinical evidence requirements, creating pull-through demand for imaging-compatible platforms with documented post-market surveillance.
- Trauma Bay Modernization:United States emergency departments are integrating X-ray stretchers into resuscitation workflows to eliminate patient repositioning during critical care windows.
- Carbon Fiber Manufacturing Scale:Aerospace composite suppliers are repurposing autoclave capacity for medical device components, expanding radiolucent deck availability beyond specialty fabricators.
Market Restraints
- Raw Material Concentration:Toray Industries and Hexcel Corporation control over seventy percent of medical-grade carbon fiber prepreg supply, creating vulnerability to aerospace demand spikes.
- EU F-Gas Regulation:Climate control requirements for sterile imaging suites are raising facility infrastructure costs, stretching capital budgets and delaying stretcher procurement timelines.
- Aluminum Substitution Ceiling:Public hospital networks in developing health systems cannot absorb carbon fiber premiums, locking volume segments into heavier, less radiolucent platforms.
Strategic Opportunities
- India Emergency Infrastructure:The country's PLI scheme for medical devices is attracting contract manufacturers to establish radiolucent component production for domestic and export markets.
- Mobile Imaging Convergence:Integration of portable X-ray systems with motorized stretcher bases is creating new product categories for intra-hospital transport without department transfers.
- Direct-to-Facility Distribution:Bypassing regional distributors through owned logistics networks is capturing margin and capturing real-time usage data for predictive maintenance services.
Industry Challenges
- ISO 13485 Certification Bottlenecks:Notified body capacity constraints in Europe are extending quality management system approval timelines by eight to fourteen months for new market entrants.
- Legacy System Integration:Hospital IT departments struggle to connect smart stretcher telemetry with existing patient monitoring architectures, delaying technology refresh decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | X-Ray Stretchers Market |
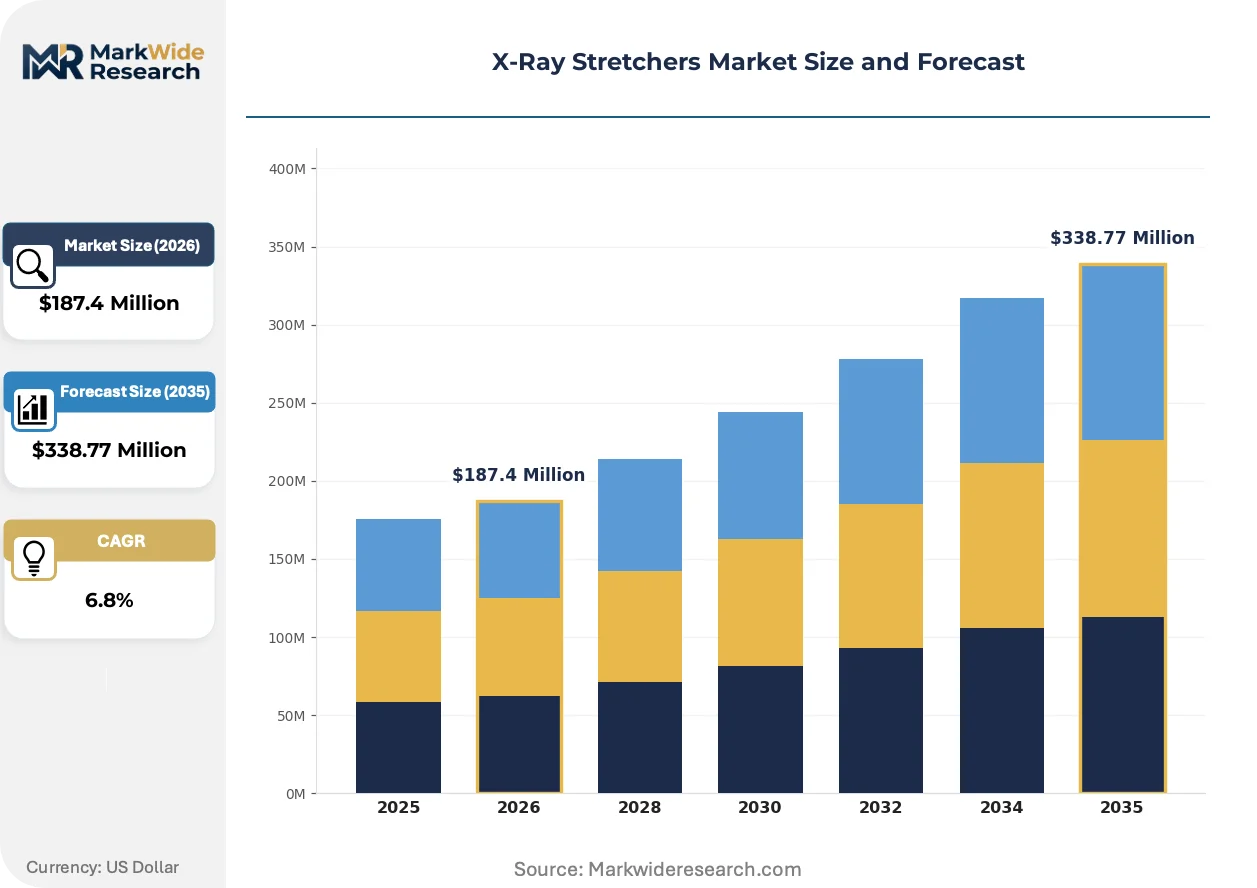
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Stretchers, Manual Stretchers, Foldable Stretchers, Bariatric Stretchers End User: Hospitals, Clinics, Rehabilitation Centers, Emergency Services Material: Aluminum, Stainless Steel, Carbon Fiber, Plastic Technology: Digital Imaging, Analog Imaging, Hybrid Systems, Portable Units |
| Companies Covered | Stryker Corporation, Hill-Rom Holdings, Inc., M.T. Medical Technology S.r.l., Karismedica S.p.A., Medline Industries, Inc., Invacare Corporation, ArjoHuntleigh (Getinge Group), TransMotion Medical, Inc., Anetic Aid Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
X-Ray Stretchers Market Evolving Landscape
Material science breakthroughs and regulatory recalibration are compressing product development cycles while elevating performance benchmarks for imaging-compatible patient transport equipment.
Carbon fiber honeycomb core construction is rewriting durability expectations for radiolucent decks. Trauma centers in Germany and the United States are specifying these platforms for load cycles exceeding fifteen years. The technology is rewriting procurement evaluation criteria as total cost of ownership calculations displace upfront capital constraints.
FDA guidance on radiological device cybersecurity is mandating encrypted data transmission for stretcher-integrated patient monitoring systems. Device manufacturers must embed hardware security modules and demonstrate vulnerability management protocols. Acute care networks in the United States are prioritizing compliant platforms, while European OEMs are adapting MDR technical documentation to anticipate similar requirements.
Hospital procurement committees are consolidating vendor relationships through integrated equipment contracts. Single-source agreements spanning beds, stretchers, and surfaces are displacing category-specific tenders. This concentration is most visible in United States integrated delivery networks, where standardization across fifty-plus facility footprints drives volume commitments in exchange for service bundling and training integration.
X-Ray Stretchers Market Segmentation
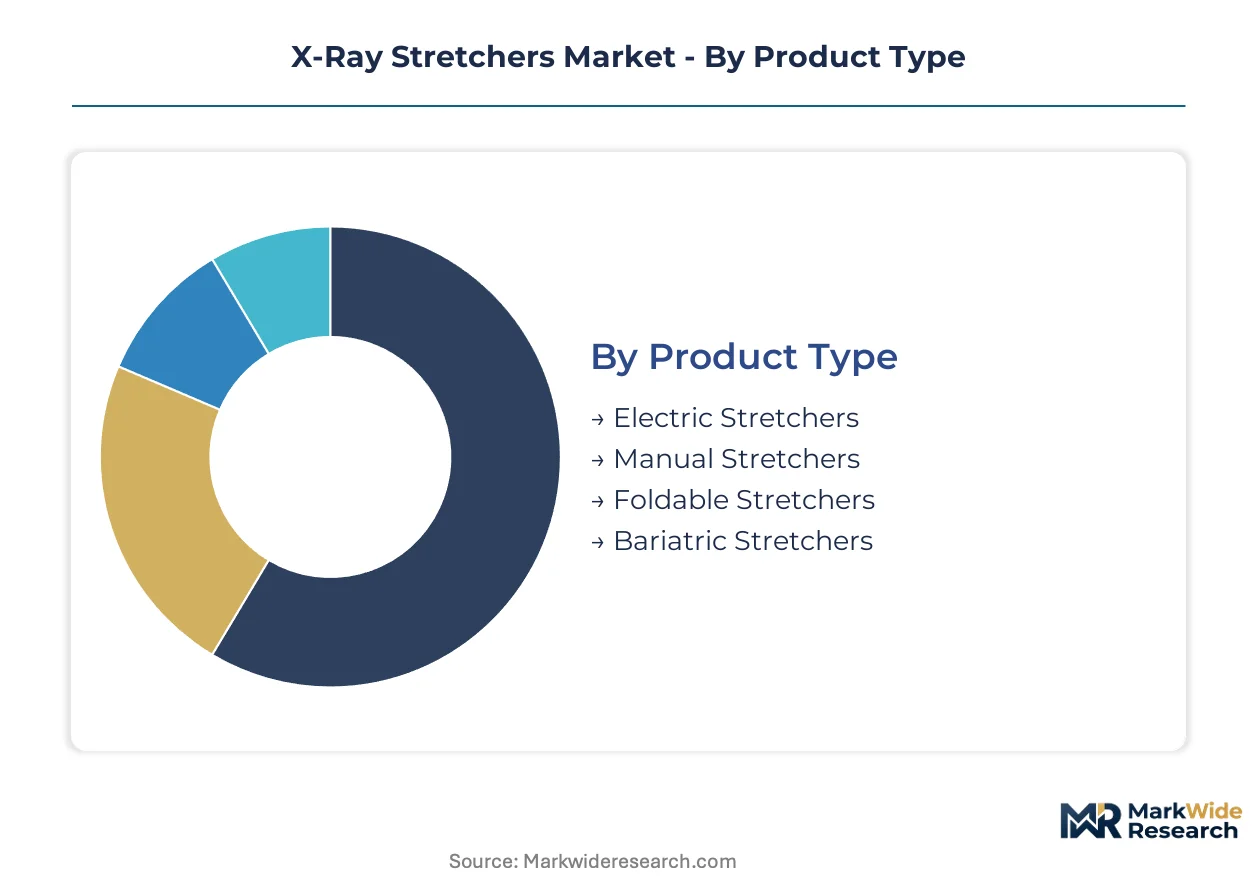
X-ray stretcher segmentation reveals how procurement committees balance imaging performance against total cost of ownership across acute care workflows. Product architecture, material selection, and technology integration each create distinct value tiers that reshape competitive positioning.
Product Type:
Standalone motorized platforms serve integrated diagnostic suites, while manual variants embed into cost-constrained transport fleets.
- Electric Stretchers:Motorized height adjustment and Trendelenburg tilt mechanisms reduce staff injury claims in United States trauma bays. Demand concentrates in Level I emergency departments where workflow velocity justifies capital premiums.
- Manual Stretchers:Hydraulic lift columns and mechanical braking systems dominate developing health system procurement. Public hospital networks in India and Brazil absorb these units for high-volume patient movement without imaging integration.
- Foldable Stretchers:Collapsible aluminum frames serve field emergency response and temporary diagnostic setups.
- Bariatric Stretchers:Reinforced decks exceeding 318 kg capacity address obesity prevalence in North American and Gulf State health systems.
Manual stretchers lead volumes today; electric variants are gaining share fastest in acute care modernization programs.
End User:
Capital intensity and imaging integration depth separate high-acuity purchasers from routine transport buyers.
- Hospitals:Integrated delivery networks in the United States specify radiolucent decks with telemetry compatibility for ICU-to-imaging corridors. These facilities absorb carbon fiber premiums to eliminate patient repositioning during critical care windows.
- Clinics:Outpatient imaging centers in Germany prioritize aluminum decks with detachable imaging plates for cost-controlled expansion. Budget constraints lock these buyers into lighter radiolucency specifications.
- Rehabilitation Centers:Long-term care facilities in Japan emphasize pressure-relief surfaces with basic X-ray compatibility for fracture monitoring.
- Emergency Services:Municipal ambulance fleets across Chinese provinces specify foldable platforms with rapid-deployment locking mechanisms for pre-hospital trauma stabilization.
Hospitals dominate absolute spend; emergency services are expanding most quickly through municipal infrastructure programs.
Material:
Supply concentration and manufacturing scale create divergent cost-performance tradeoffs across procurement tiers.
- Carbon Fiber:Aerospace-grade prepreg construction delivers radiolucent clarity with 40% weight reduction versus metals. German trauma centers and United States academic medical centers specify honeycomb-core decks for fifteen-year service cycles.
- Aluminum:Extruded alloy platforms with anodized finishes sustain volume leadership through public hospital tenders. Chinese and Indian procurement frameworks prioritize aluminum cost structures over imaging performance.
- Stainless Steel:Surgical-grade 304 and 316 alloys serve hybrid operating suites requiring sterilization compatibility alongside basic imaging access.
- Plastic:Glass-reinforced polymer decks address disposable or limited-use scenarios in field military medicine and disaster response stockpiles.
Aluminum retains volume leadership; carbon fiber commands the steepest expansion trajectory in premium acute care segments.
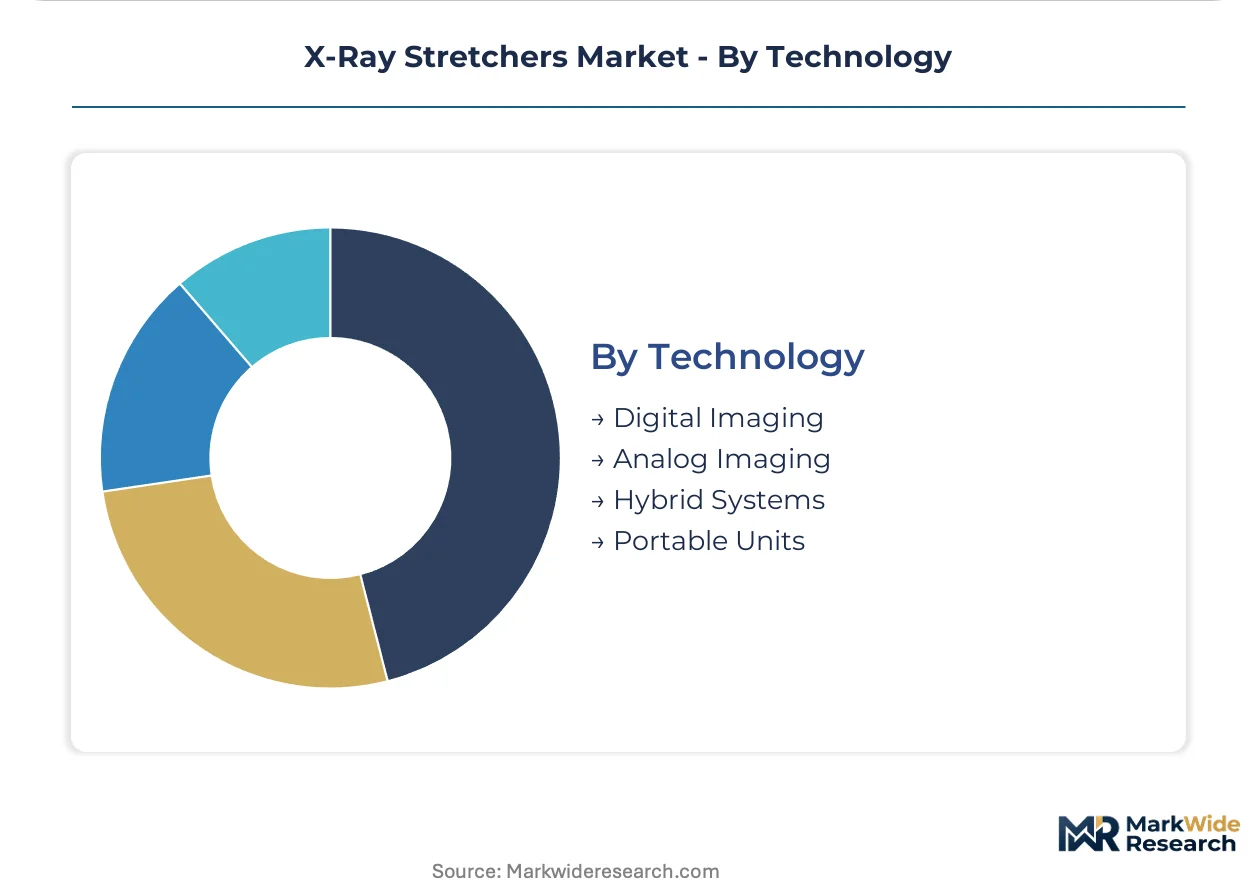
Technology:
Imaging modality integration determines stretcher specification criteria across diagnostic workflow architectures.
- Digital Imaging:DICOM-compatible stretcher bases with embedded patient positioning sensors streamline PACS integration. United States health systems prioritize these platforms for cybersecurity compliance under FDA radiological device guidance.
- Hybrid Systems:Dual analog-digital compatibility serves transitional facilities migrating from film-based to detector-based radiography. European hospitals under EU MDR clinical evidence requirements favor documented hybrid configurations.
- Analog Imaging:Cassette-compatible decks persist in resource-limited settings and backup imaging contingencies.
- Portable Units:Battery-powered X-ray source integration with motorized stretcher bases enables corridor-based imaging without department transfer.
Digital imaging leads replacement cycles; portable unit convergence is climbing the fastest through mobile diagnostic investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The X-ray stretcher industry traces its commercial origins to post-war American hospital modernization, where radiology departments first demanded patient transport platforms compatible with emerging imaging technologies. German engineering subsequently elevated material standards through precision carbon fiber fabrication. Contemporary demand now concentrates in health systems prioritizing trauma workflow efficiency and regulatory compliance.
United States
Level I trauma centers and academic medical centers drive procurement of motorized radiolucent platforms with integrated telemetry. FDA enforcement of 21 CFR 1020 radiological health standards and emerging cybersecurity guidance for connected devices reshape specification criteria. The Texas Medical Center in Houston anchors domestic demand through sustained emergency department expansion and imaging corridor modernization.
Germany
University hospitals in Bavaria and Baden-Württemberg specify honeycomb-core carbon fiber decks for fifteen-year service cycles under total cost of ownership frameworks. EU MDR clinical evidence requirements and post-market surveillance obligations accelerate replacement of legacy transport equipment. The Medical Valley cluster around Erlangen concentrates precision composite fabrication for radiolucent medical components.
China
Municipal infrastructure programs across Jiangsu and Zhejiang provinces expand emergency medical services fleets with foldable imaging-compatible platforms. NMPA medical device registration requirements and GB standards for patient transport equipment elevate quality thresholds for domestic manufacturers. The Yangtze River Delta manufacturing corridor scales aluminum extrusion capacity for cost-sensitive hospital procurement.
India
Public hospital networks in Maharashtra and Karnataka absorb manual stretcher volumes for high-volume patient movement without imaging integration. The PLI scheme for medical devices attracts contract manufacturers to establish radiolucent component production for domestic and export markets. The Delhi-NCR corridor emerges as a distribution hub for emergency services equipment serving northern states.
Japan
Long-term care facilities in the Kanto region emphasize pressure-relief surfaces with basic X-ray compatibility for fracture monitoring in aging populations. METI industrial standards and PMDA quality management requirements sustain premium pricing for durable medical equipment. The Osaka-Kobe manufacturing zone supplies specialized rehabilitation center equipment with extended warranty terms.
X-Ray Stretchers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material certification and regulatory documentation depth. The vendor base stratifies into three tiers: integrated hospital equipment conglomerates with cross-selling leverage, specialized stretcher fabricators with focused R&D investment, and regional distributors competing on logistics density. Consolidation pressure intensifies as procurement committees favor single-source agreements spanning beds, stretchers, and surfaces. Dominant competitive moves include backward integration into carbon fiber prepreg sourcing and direct-to-facility distribution network expansion.
Within the integrated equipment tier, Stryker Corporation and Hill-Rom Holdings, Inc. represent archetypes of portfolio breadth and sustained capital commitment to imaging-compatible platforms. Among specialized fabricators, M.T. Medical Technology S.r.l. and Karismedica S.p.A. occupy positions emphasizing European regulatory compliance and modular configuration expertise. Medline Industries, Inc. exemplifies distribution-scale competitive positioning through logistics network density.
| Leading Market Players |
|---|
| Stryker Corporation |
| Hill-Rom Holdings, Inc. |
| M.T. Medical Technology S.r.l. |
| Karismedica S.p.A. |
| Medline Industries, Inc. |
| Invacare Corporation |
| ArjoHuntleigh (Getinge Group) |
| TransMotion Medical, Inc. |
| Anetic Aid Limited |
| Others |
Value Network & Pricing Analysis
Carbon fiber prepreg manufacturing scale-up from aerospace suppliers is compressing deck production costs while concentrating supply among Toray Industries and Hexcel Corporation, simultaneously lowering premium-tier stretcher pricing and amplifying procurement risk for manufacturers locked out of long-term offtake agreements.
Pricing Analysis
Three-tier pricing structure across premium carbon fiber, standard aluminum, and economy manual configurations stratifies the market by imaging clarity and motorized functionality. Price differentiation hinges on EU MDR certification grade and ISO 13485 quality documentation depth, with acute care networks absorbing carbon fiber premiums while public hospital tenders in India and Brazil gravitate toward aluminum cost structures. Cost compression in manual stretcher tiers is intensifying because Chinese aluminum extrusion capacity is flooding developing health system procurement channels.
Supply Chain Analysis
Medical-grade carbon fiber supply rests on Japanese and American aerospace composite producers who control prepreg formulation and autoclave capacity allocation. Raw material dependencies span Toray T800H carbon fiber, Hexcel HexPly epoxy systems, and 6061-T6 aluminum extrusions from Yangtze River Delta mills. Single-source vulnerability concentrates in aerospace-grade prepreg supply, where defense contract prioritization can displace medical device allocation. Distribution runs through direct-to-facility logistics networks owned by integrated equipment conglomerates and regional medical device distributors serving hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The X-ray stretchers market functions as a regulatory compounder where EU MDR clinical evidence mandates and FDA radiological device cybersecurity guidance are accelerating replacement cycles and elevating certification barriers to entry.
For Market Incumbents: Acquire carbon fiber prepreg offtake capacity from aerospace suppliers to secure material allocation ahead of contract manufacturers entering through India's PLI scheme. Deepen backward integration into honeycomb core fabrication to defend margin position against emerging Chinese aluminum extruders. Lock in multi-year service bundling contracts with United States integrated delivery networks to preempt single-source consolidation by competitors.
For New Entrants and Emerging Players: Launch via direct-to-facility distribution partnerships with German university hospitals seeking modular stretcher configurations with documented post-market surveillance trails. Target India's emergency services infrastructure programs with foldable aluminum platforms priced below Stryker and Hill-Rom landed cost. Exploit ISO 13485 certification bottlenecks by pre-engaging European notified bodies before product development completion.
For Investors and Strategic Acquirers: Roll-up economics work for specialized stretcher fabricators with EU MDR technical documentation depth because hospital procurement committees are consolidating vendor relationships through integrated equipment contracts. Focus on mid-cap European OEMs with honeycomb-core carbon fiber expertise and established clinical evidence portfolios. Watch NMPA registration acceleration in China as inflection indicator for domestic manufacturer competitive emergence.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Clinical evidence portfolios satisfy post-market surveillance obligations for German university hospital procurement. |
| Carbon Fiber Prepreg Backward Integration | Captive supply of aerospace-grade material insulates against Toray and Hexcel allocation disruption. |
| Direct-to-Facility Distribution Buildout | Owned logistics networks capture margin and generate predictive maintenance data from United States IDNs. |
| Portable X-Ray System Convergence R&D | Battery-powered source integration with motorized bases creates corridor imaging category for trauma workflows. |
| India PLI Scheme Manufacturing Entry | Contract production of radiolucent components serves domestic emergency infrastructure and export markets. |
Research Methodology
Multiple input streams — hospital procurement committee interviews, carbon fiber composite supplier discussions, and regulatory affairs consultations — were reconciled with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, and NMPA registration records. Primary engagement spanned biomedical engineers at Level I trauma centers, GPO contracts managers at United States integrated delivery networks, and notified body auditors in Germany and the Netherlands. Secondary sources included hospital capital equipment procurement databases, aerospace composite trade flow data, and medical device quality management certification registries. Bottom-up stretcher shipment modeling and top-down health system capital expenditure triangulation anchored volume and value estimates.
Segment-level projections across electric, manual, foldable, and bariatric product types were reconciled with end-user spend patterns at hospitals, clinics, rehabilitation centers, and emergency services. Material-grade splits between carbon fiber, aluminum, stainless steel, and plastic decks were modeled against procurement budget constraints and imaging performance requirements. Technology adoption curves for digital imaging, hybrid systems, analog compatibility, and portable unit convergence were calibrated to FDA cybersecurity guidance implementation timelines and EU MDR transition deadlines. CAGRs were derived from installed base replacement cycles, trauma bay modernization program announcements, and municipal ambulance fleet expansion commitments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under aerospace carbon fiber supply disruption or extended EU notified body approval bottlenecks. Material deviation in FDA radiological device cybersecurity enforcement intensity or NMPA domestic manufacturer registration acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Artificial Cornea and Corneal Implant Market
Medical Devices
Radiofrequency (RF) Ablation System Market
Medical Devices
Thoracolumbar Stabilization Devices Market
Medical Devices
US Bathroom and Toilet Assist Devices Market
Medical Devices
Stool Management Systems Market
Medical Devices
Ambulatory Aids Market
Medical Devices
Interventional Spine Devices Market
Medical Devices
Global Eye Massage Machine Market
Medical Devices
Software As a Medical Device Market
Medical Devices
Global ECG Cable and ECG Lead Wires Market
Medical Devices
ECG Telemetry Devices Market
Medical Devices
India Static Compression Therapy Market
Medical Devices
Global Microdermabrasion Devices Market
Medical Devices
Middle East Ultrasound Devices Market
Medical Devices
North America Wearable Medical Devices Market
Medical Devices
Sterile Filtration Module Market