
 Australia Hospital Supplies Market | 2026-2036
Australia Hospital Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Hospital Supplies Market Outlook
Hospital-grade sterilization assurance is redrawing competitive boundaries across the Australia Hospital Supplies Market. Becton, Dickinson and Company leverages its integrated manufacturing footprint to supply compliant infusion therapy products under TGA-mandated standards. Ansell anchors the protective gloves segment through specialized nitrile and latex portfolios tailored to Australian surgical protocols. Cardinal Health Inc. competes via extensive distribution networks that reach remote regional hospitals beyond the major metropolitan clusters.
Hospital supplies encompass disposable and reusable medical products used in patient diagnosis, treatment, and surgical intervention, including items manufactured to ISO 13485 quality management standards with biocompatibility testing per ISO 10993. These products serve to maintain sterile environments, monitor vital parameters, and deliver therapeutic agents in acute care settings. Surgical instruments and patient monitoring systems command the largest share of product-type revenue, reflecting sustained capital investment in operating theatre modernization. IV supplies represent the fastest-expanding category as ambulatory and home-based infusion protocols gain traction under digital health integration. Public hospitals dominate end-user procurement volumes, though private hospital chains capture disproportionate margin pools through premium device selection and direct supplier relationships.
TGA registration requirements and the Australian Commission on Safety and Quality in Health Care standards shape product entry pathways, forcing offshore manufacturers to establish local conformity assessment partnerships. The Medical Device Single Audit Program alignment with TGA procedures reduces regulatory duplication but demands sustained documentation investment from suppliers. Stakeholders must monitor evolving digital health reimbursement codes and automation adoption thresholds to align R&D spending with hospital procurement priorities.
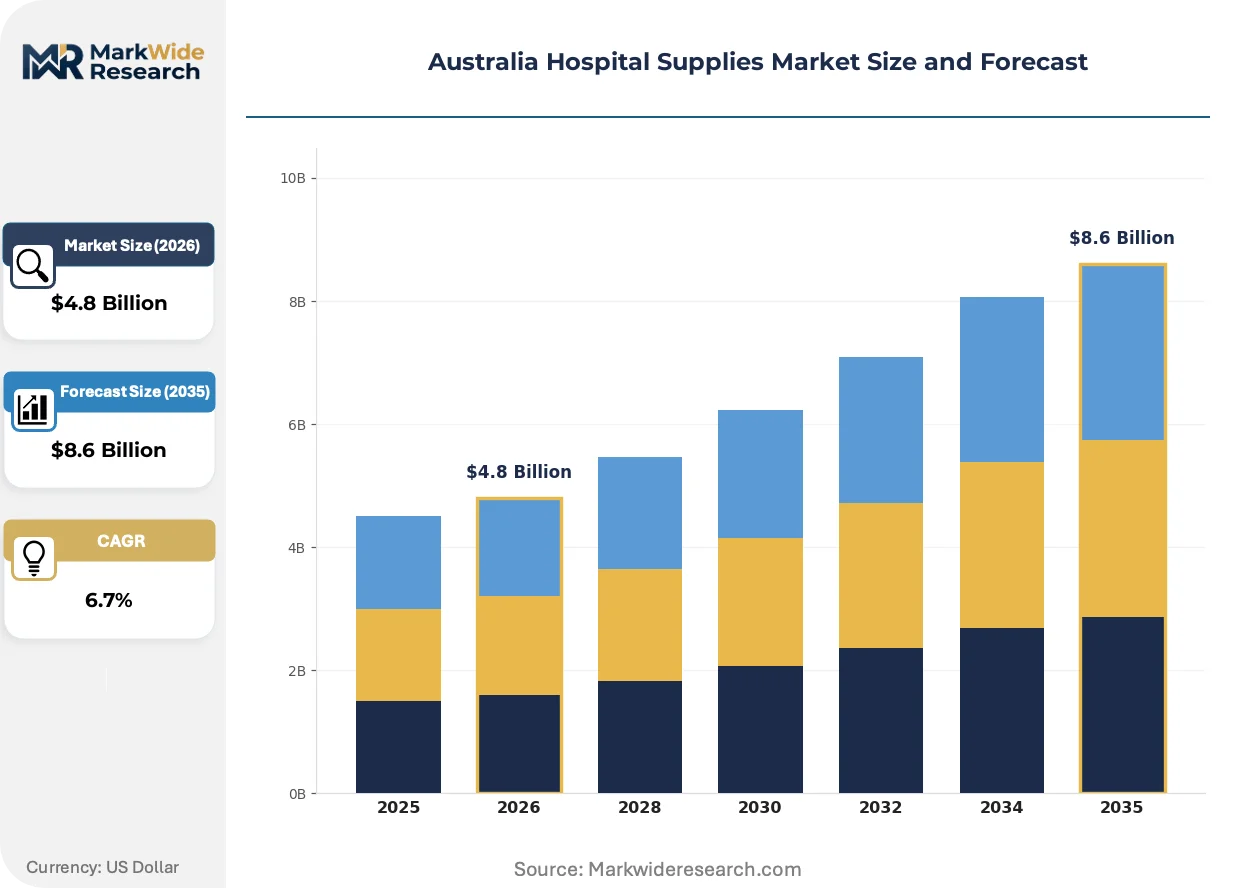
Market Dynamics
TGA sterilization mandates are compressing import pathways while public hospital networks consolidate procurement around domestic-compliant suppliers, redrawing vendor access across New South Wales and Victoria metropolitan clusters.
Growth Catalysts
- Single-use surgical kit protocols:Public hospitals in New South Wales and Victoria are expanding bulk purchasing of disposable kits to eliminate cross-contamination risks in high-volume surgical theatres.
- TGA sterilization alignment:The Therapeutic Goods Administration's tightened import standards are redirecting distributor relationships toward domestic manufacturers with validated sterilization documentation.
- Home infusion expansion:Digital health integration is accelerating ambulatory IV therapy protocols, pulling demand for portable infusion pumps and disposable sets into community care settings.
Market Restraints
- Specialty polymer feedstock volatility:Nitrile and medical-grade latex glove production faces input cost pressure from petrochemical supply fluctuations and energy-intensive processing requirements.
- Import pathway concentration:Heavy reliance on offshore sterilization facilities for finished devices creates compliance vulnerability under TGA's evolving conformity assessment timelines.
- Reusable instrument substitution:Advanced autoclave-compatible alloys and robotic sterilization systems are extending surgical instrument lifecycles, compressing replacement demand in capital-constrained regional facilities.
Strategic Opportunities
- Regional hospital network penetration:Queensland and Western Australia rural health districts remain undersupplied by compliant distributors, creating whitespace for logistics-anchored vendors.
- AI-enabled inventory forecasting:Machine learning demand prediction converging with automated replenishment systems offers procurement efficiency gains for multi-site hospital networks.
- Medical Device Single Audit Program leverage:TGA-MDSAP alignment reduces regulatory duplication costs for suppliers holding concurrent FDA and Health Canada certifications, lowering entry investment for dual-market manufacturers.
Industry Challenges
- ISO 13485 auditor scarcity:Qualified certification bodies for medical device quality management systems face capacity constraints, extending supplier readiness timelines.
- Legacy ERP integration friction:Hospital procurement systems require costly middleware development to connect with supplier digital inventory platforms, delaying automated ordering deployment.
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization studies face laboratory capacity limits, slowing new product registration pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Hospital Supplies Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Diagnostic Equipment, IV Supplies, Patient Monitoring Systems End User: Public Hospitals, Private Hospitals, Specialty Clinics, Home Healthcare Providers Technology: Digital Health, Telemedicine, RFID Tracking, Automation Delivery Mode: Direct Sales, Distributors, Online Platforms, Group Purchasing Organizations |
| Companies Covered | B. Braun Melsungen AG, Becton, Dickinson and Company, Cardinal Health Inc., 3M, ResMed Inc., Ansell, Medline Industries, Stryker, McKesson Australia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Hospital Supplies Market Strategic Shifts
Digital connectivity and sterilization assurance technologies are fragmenting traditional supply relationships while compressing procurement decision cycles across Australian hospital networks.
Smart infusion systems with embedded dose-error reduction software are bifurcating the IV therapy segment. Major metropolitan hospitals in Sydney and Melbourne are adopting these connected pumps at accelerated replacement cycles. The technology is bifurcating vendor relationships between full-platform suppliers and component-only manufacturers, forcing mid-tier distributors to select alliance partners or exit the category.
TGA's alignment with the Medical Device Single Audit Program is streamlining conformity assessment for multi-jurisdiction manufacturers. This regulatory convergence reduces documentation burden for holders of FDA and Health Canada certifications seeking Australian market entry. IV fluid and infusion device suppliers with existing MDSAP scope are capturing faster registration timelines versus single-market applicants.
Hospital procurement departments are consolidating supplier panels around integrated service contracts bundling devices, logistics, and sterilization assurance. Traditional product-only distributors are losing position to vendors offering vendor-managed inventory and consignment stock arrangements. This pattern concentrates in Victoria's metropolitan health networks, where procurement centralization has advanced furthest among Australian states.
Australia Hospital Supplies Market Segmentation
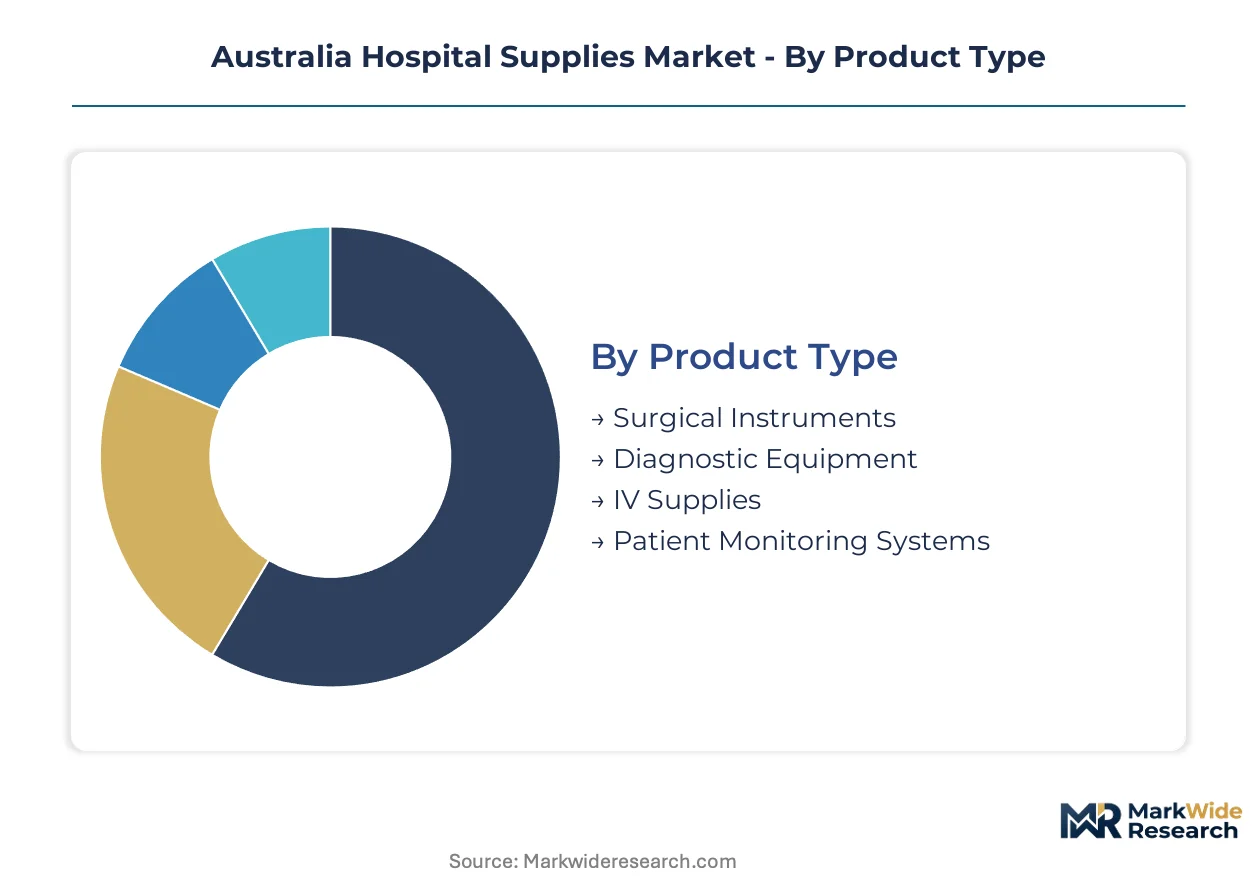
Hospital supplies procurement across Australia fragments along clinical application, institutional purchasing power, and supply chain configuration. Each segmentation axis reveals distinct competitive dynamics between metropolitan bulk buyers and dispersed regional networks.
Product Type:
Surgical instruments and diagnostic equipment concentrate manufacturing relationships with TGA-registered domestic suppliers, while IV supplies draw more heavily from import channels subject to sterilization compliance verification.
- Surgical Instruments:Reusable scalpels, forceps, and retractors manufactured to ISO 13485 standards with biocompatibility testing per ISO 10993. Demand concentrates in New South Wales and Victoria metropolitan hospital networks undertaking operating theatre modernization programs.
- IV Supplies:Infusion pumps, disposable tubing sets, and vascular access devices. Steepest demand expansion runs through ambulatory care settings in Queensland and Western Australia as home-based infusion protocols gain traction under digital health integration.
- Diagnostic Equipment:Point-of-care testing devices and imaging consumables.
- Patient Monitoring Systems:Vital signs monitors and telemetry equipment for acute care wards.
Surgical instruments command the established base. The steepest expansion runs through IV supplies.
End User:
Procurement scale and compliance sophistication vary sharply between publicly funded networks with centralized tendering and private chains exercising direct supplier relationships.
- Public Hospitals:State health department procurement frameworks dominate volume, with New South Wales and Victoria health networks driving bulk purchasing of single-use surgical kits to eliminate cross-contamination risks in high-volume surgical theatres.
- Private Hospitals:Premium device selection and direct manufacturer relationships capture disproportionate margin pools, particularly in metropolitan Sydney and Melbourne where chains negotiate integrated service contracts bundling devices with sterilization assurance.
- Specialty Clinics:Day surgery and endoscopy centers with fragmented purchasing patterns.
- Home Healthcare Providers:Community nursing services and aged care operators sourcing portable infusion equipment.
Public hospitals anchor procurement volumes. Private facilities deliver margin concentration.
Technology:
Adoption intensity splits between capital-rich metropolitan networks and regional facilities constrained by legacy infrastructure integration costs.
- Digital Health:Electronic medical record integration and clinical decision support systems.
- Telemedicine:Remote consultation platforms with limited supply chain implications.
- RFID Tracking:Inventory visibility systems. Queensland and Western Australia rural health districts show rising implementation as automated replenishment reduces stockout risks in remote facilities.
- Automation:Robotic dispensing and sterile supply chain management. Victorian metropolitan networks lead deployment of machine learning demand prediction converging with automated ordering systems.
RFID tracking captures the established automation base. Robotic sterilization and dispensing systems claim the steepest adoption curve.
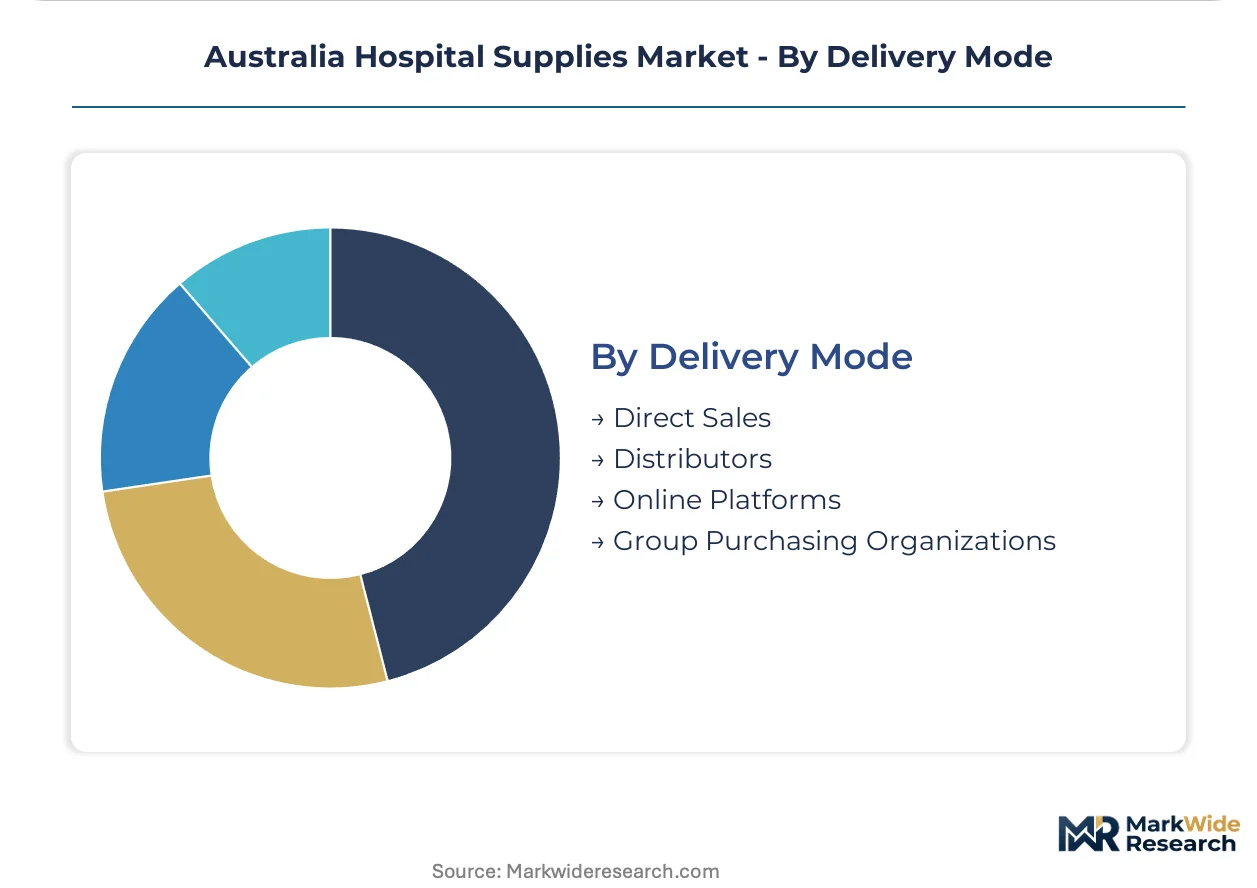
Delivery Mode:
Channel structure reflects geographic concentration of demand and regulatory burden distribution between direct relationships and intermediary compliance management.
- Direct Sales:Manufacturer-to-hospital relationships for high-value capital equipment. Concentrated in private hospital chains with procurement centralization.
- Distributors:Local intermediaries managing TGA conformity assessment documentation. Dominant pathway for imported devices requiring sterilization verification.
- Online Platforms:E-procurement portals for standard consumables with limited regulatory complexity.
- Group Purchasing Organizations:Volume aggregation for public hospital networks. New South Wales and Victoria health departments leverage collective tendering to compress unit costs for disposable surgical supplies.
Distributor networks command the established procurement base. Direct manufacturer relationships are gaining fastest among consolidated private chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's hospital supplies trade leans heavily on import channels for finished devices, with domestic manufacturing concentrated in sterilization services and specialized consumables. State-level procurement centralization creates distinct demand patterns across the federation.
New South Wales
Metropolitan Sydney hospitals drive bulk purchasing of single-use surgical kits through HealthShare NSW procurement frameworks. TGA sterilization mandates redirect distributor contracts toward domestic-compliant suppliers with validated documentation. The Northern Beaches and Westmead hospital clusters anchor surgical instrument modernization programs.
Victoria
Melbourne's consolidated health networks pioneer vendor-managed inventory contracts bundling devices with logistics services. The Australian Commission on Safety and Quality in Health Care standards shape tender specifications for metropolitan purchasing. The Monash and Alfred health precincts deploy automated replenishment systems at scale.
Queensland
Rural health districts in the state's north and west face persistent supply gaps for TGA-registered devices. Queensland Health's decentralized procurement creates whitespace for distributors with regional logistics capabilities. The Townsville and Cairns hospital networks source portable infusion equipment for remote community care expansion.
Western Australia
Perth's metropolitan hospitals concentrate demand for patient monitoring systems while regional facilities rely on fly-in-fly-out supply models. The Therapeutic Goods Administration's import verification requirements complicate delivery timelines to remote sites. The Fiona Stanley Hospital cluster leads adoption of RFID-tracked sterile supply chains.
Australia Hospital Supplies Market Competitive Environment
Concentration sits with diversified multinational healthcare conglomerates possessing integrated manufacturing and distribution footprints. Three archetypes dominate: global device manufacturers with TGA-registered sterilization facilities, specialized protective equipment suppliers with Australian surgical protocol expertise, and logistics-anchored distributors serving regional hospital networks. Competitive moves center on procurement centralization partnerships and sterilization assurance service bundling.
Among the integrated multinational tier, Becton, Dickinson and Company and Cardinal Health Inc. represent the dominant archetypes for infusion therapy and distribution-intensive supply models respectively. Ansell occupies a position exemplifying specialized protective equipment focus. Stryker and 3M sit within the capital equipment and diversified consumables segments. ResMed Inc. and B. Braun Melsungen AG represent European-originated competitors with Australian market presence. McKesson Australia exemplifies the logistics-anchored distributor model serving regional penetration requirements.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Becton, Dickinson and Company |
| Cardinal Health Inc. |
| 3M |
| ResMed Inc. |
| Ansell |
| Medline Industries |
| Stryker |
| McKesson Australia |
| Others |
Value Chain & Pricing Dynamics
TGA sterilization certification gates both supplier qualification and price differentiation across the Australia Hospital Supplies Market, compressing import channels while rewarding domestic-compliant vendors with premium positioning in public hospital tenders.
Pricing Analysis
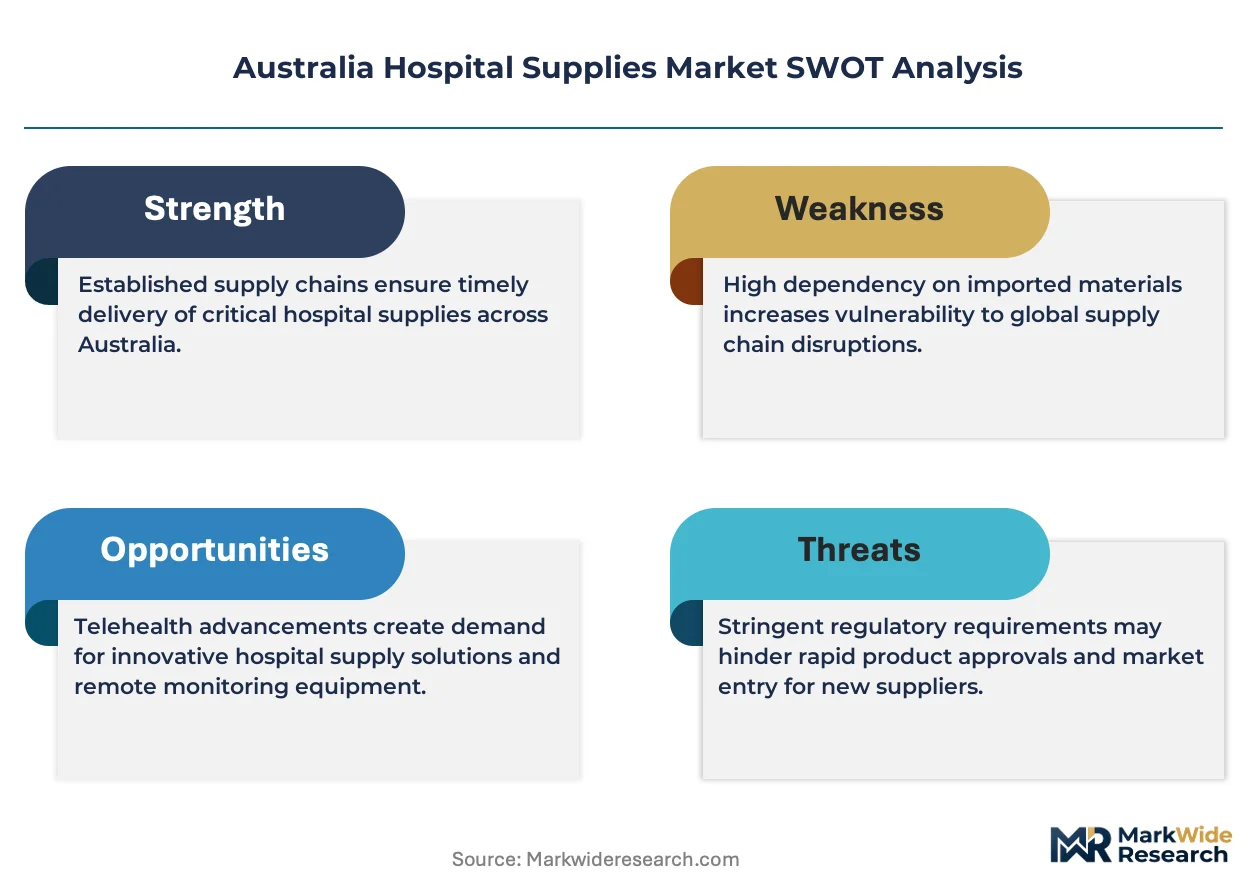
Public hospital procurement committees anchor contract-based long-term offtake pricing for high-volume consumables, with HealthShare NSW and Victorian health networks leveraging collective tendering to compress unit costs. Three-tier pricing structure across premium, standard, and economy levels separates TGA-registered domestic suppliers from import-reliant distributors and non-certified alternatives. Cost compression in the standard tier is intensifying because specialty polymer feedstock volatility feeds through to nitrile glove and IV set production. Regional hospital networks exhibit highest price sensitivity due to capital constraints, while private metropolitan chains absorb premium tier pricing for integrated service bundling.
Supply Chain Analysis
Singapore and Malaysia sterilization facilities constitute a chokepoint for finished device import pathways into Australia, with TGA conformity assessment timelines tethered to third-party audit capacity at these hubs. Domestic manufacturing draws from Malaysian nitrile feedstock, Chinese electronic components for infusion pumps, and German precision alloys for surgical instruments. Single-source vulnerability concentrates in offshore sterilization services, where audit backlogs delay product registration. Distribution runs through logistics-anchored distributors managing TGA documentation for regional hospital networks, with direct manufacturer relationships gaining share among consolidated private chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through state-level procurement centralization in New South Wales and Victoria, fragmenting vendor access for non-compliant suppliers while rewarding integrated service providers with multi-year contract security.
For Market Incumbents: Shield market position through backward integration into TGA-registered sterilization facilities, eliminating audit backlog exposure that threatens import-reliant competitors. Deepen vendor-managed inventory penetration across Victorian metropolitan networks where procurement centralization has advanced furthest. Anchor defensive positioning against emerging AI-enabled inventory forecasting specialists by embedding machine learning capabilities into existing logistics contracts. For New Entrants and Emerging Players: Anchor in Queensland and Western Australia rural health districts where TGA-compliant distributor coverage remains sparse and fly-in-fly-out supply models create service gaps. Target portable infusion equipment for home healthcare expansion in Townsville and Cairns hospital network catchments. Pursue hospital system partnership go-to-market angle with regional health districts seeking automated replenishment solutions for remote facilities. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational healthcare conglomerates divesting non-core distribution assets in Australia amid global portfolio restructuring. Long-term viability hinges on sterilization assurance service bundling rather than product-only margins, favoring targets with captive TGA-registered facilities. Watch Queensland Health decentralization policy signals as inflection indicator for regional distributor acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| TGA Registration Pathway Investment | Validates sterilization documentation for HealthShare NSW and Victorian health network tenders. |
| Vendor-Managed Inventory Partnership | Locks multi-year contracts with Monash and Alfred health precincts in Melbourne. |
| Regional Distribution Footprint Expansion | Captures whitespace in Queensland rural districts beyond Townsville hospital network reach. |
| AI-Enabled Demand Forecasting Integration | Aligns with Fiona Stanley Hospital RFID-tracked sterile supply chain modernization. |
| MDSAP Certification Alignment | Accelerates market entry for FDA- and Health Canada-certified manufacturers via reduced documentation burden. |
Study Parameters
Operator-level perspectives from hospital purchasing committee members, biomedical engineers, GPO contracts managers, and TGA regulatory affairs specialists anchored the qualitative base. Primary interview findings triangulated against hospital procurement databases, GPO contract disclosures, Therapeutic Goods Administration registration filings, and Australian Bureau of Statistics health expenditure data. Bottom-up product-type demand modeling converged with top-down state health department budget allocation analysis.
Sensitivity analysis tested forecast robustness across sterilization audit timeline scenarios and polymer feedstock price volatility assumptions throughout the projection horizon. Segmentation dimensions spanned product type, end-user institution category, technology adoption tier, and delivery mode. CAGRs derived from regression-based trend extrapolation calibrated to historical procurement volume patterns and announced hospital infrastructure investment pipelines. Home infusion protocol expansion rates and digital health reimbursement code evolution served as category-specific demand drivers.
Decision-makers should treat outputs as directional under stable TGA-MDSAP alignment and public hospital capital expenditure continuity assumptions; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as Queensland Health procurement decentralization policy and specialty polymer supply chain reconfiguration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
US Disposable Face Mask Market
Medical Supplies
Europe Custom Procedure Kits Market
Medical Supplies
Lavage Kits Market
Medical Supplies
Flexible Packaging for Healthcare Market
Medical Supplies
United States Face Mask Market
Medical Supplies
Medical Gauze and Tapes Market
Medical Supplies
Oral Dosing Cups Market
Medical Supplies
Pharmacy Bags Market
Medical Supplies
Medical Clothing Market
Medical Supplies
Transfusion Bottles Market
Medical Supplies
Finger Splint Market
Medical Supplies
Safety Needles Market
Medical Supplies
Skin Traction Kits Market
Medical Supplies
Europe Medical Gloves Market
Medical Supplies
Specimen Collection Cards Market
Medical Supplies
Disposable Bed Sheets Market