
 Global Dendritic Cell Cancer Vaccines Market | 2026-2036
Global Dendritic Cell Cancer Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dendritic Cell Cancer Vaccines Market Foresight
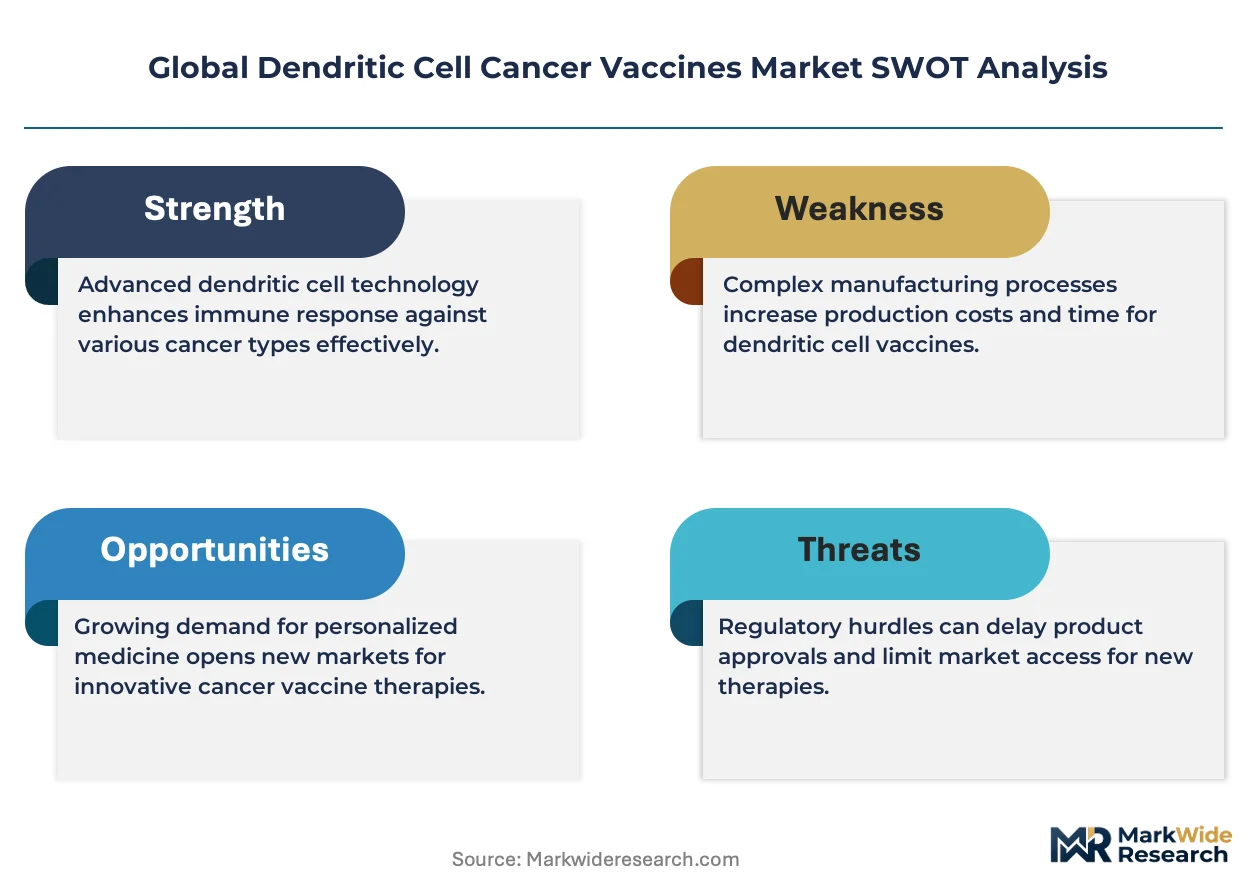
Platform licensing revenue from ex vivo maturation protocols is reshaping how immunotherapy developers monetize intellectual property. Dendreon Pharmaceuticals anchors North American manufacturing capacity through its Seattle-based cell processing infrastructure. BioNTech SE leverages mRNA electroporation expertise to differentiate its pipeline from peptide-based alternatives. Northwest Biotherapeutics specializes in personalized vaccine workflows that extend clinical trial timelines but command premium reimbursement.
Dendritic cell cancer vaccines comprise patient-derived or allogeneic antigen-presenting cells loaded with tumor-associated antigens via electroporation, liposomal fusion, or direct peptide pulsing, then reinfused to prime cytotoxic T-cell responses against malignancies. Autologous vaccines occupy the dominant revenue position due to regulatory familiarity and established reimbursement codes, while mRNA-based delivery technology represents the fastest-expanding segment as electroporation efficiency improves and cold-chain requirements simplify. Melanoma and prostate cancer applications currently lead clinical adoption, though lung cancer represents an emerging target given the prevalence of checkpoint inhibitor combinations.
FDA regenerative medicine advanced therapy designations and EMA priority medicines pathways accelerate approval timelines for autologous platforms, while WHO prequalification standards shape access in lower-income settings. The EU AI Act introduces documentation requirements for algorithm-driven patient selection tools used in personalized vaccine manufacturing. Stakeholders must monitor how GMP inspection harmonization between FDA and EMA evolves, as divergent cell-handling standards threaten to fragment manufacturing scale economics.
Market Dynamics
Platform licensing revenue from ex vivo maturation protocols is reshaping how immunotherapy developers monetize intellectual property, shifting value capture upstream from finished products to manufacturing know-how.
Growth Catalysts
- FDA Regenerative Medicine Advanced Therapy designation:This pathway compresses approval timelines for autologous platforms, accelerating commercialization for Seattle-based and Philadelphia-area developers.
- Electroporation efficiency gains:mRNA loading protocols now achieve transfection rates above 85%, enabling cold-chain simplification that expands reach to community oncology centers.
- Germany's specialized GMP infrastructure:Heidelberg and Munich manufacturing clusters concentrate expertise that reduces batch failure rates for peptide-pulsed vaccines.
Market Restraints
- Patient-derived material volatility:Autologous workflows require 3-4 weeks of leukapheresis-to-infusion time, creating inventory risk if disease progression accelerates.
- Single-source electroporation equipment:Two suppliers dominate closed-system transfection hardware, concentrating price-setting power in Boston and Basel.
- EMA divergent cell-handling standards:Inspection protocols for cryopreservation validation differ from FDA requirements, fragmenting manufacturing scale economics across the Atlantic.
Strategic Opportunities
- Japan's aging oncology population:PMDA's sakigake designation offers priority review for lung cancer applications, an underpenetrated indication relative to melanoma and prostate.
- WHO prequalification pathways:Standardized documentation requirements for lower-income settings open procurement channels previously blocked by site-specific validation.
- Algorithm-driven patient selection:Machine learning tools for predicting neoantigen immunogenicity converge with next-generation sequencing to compress personalized vaccine design timelines.
Industry Challenges
- Vector manufacturing skill scarcity:GMP-compliant lentiviral production expertise concentrates in fewer than 12 facilities worldwide, constraining allogeneic platform expansion.
- Legacy electronic batch record systems:Paper-based deviation tracking at established cell therapy sites impedes real-time release testing integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dendritic Cell Cancer Vaccines Market |
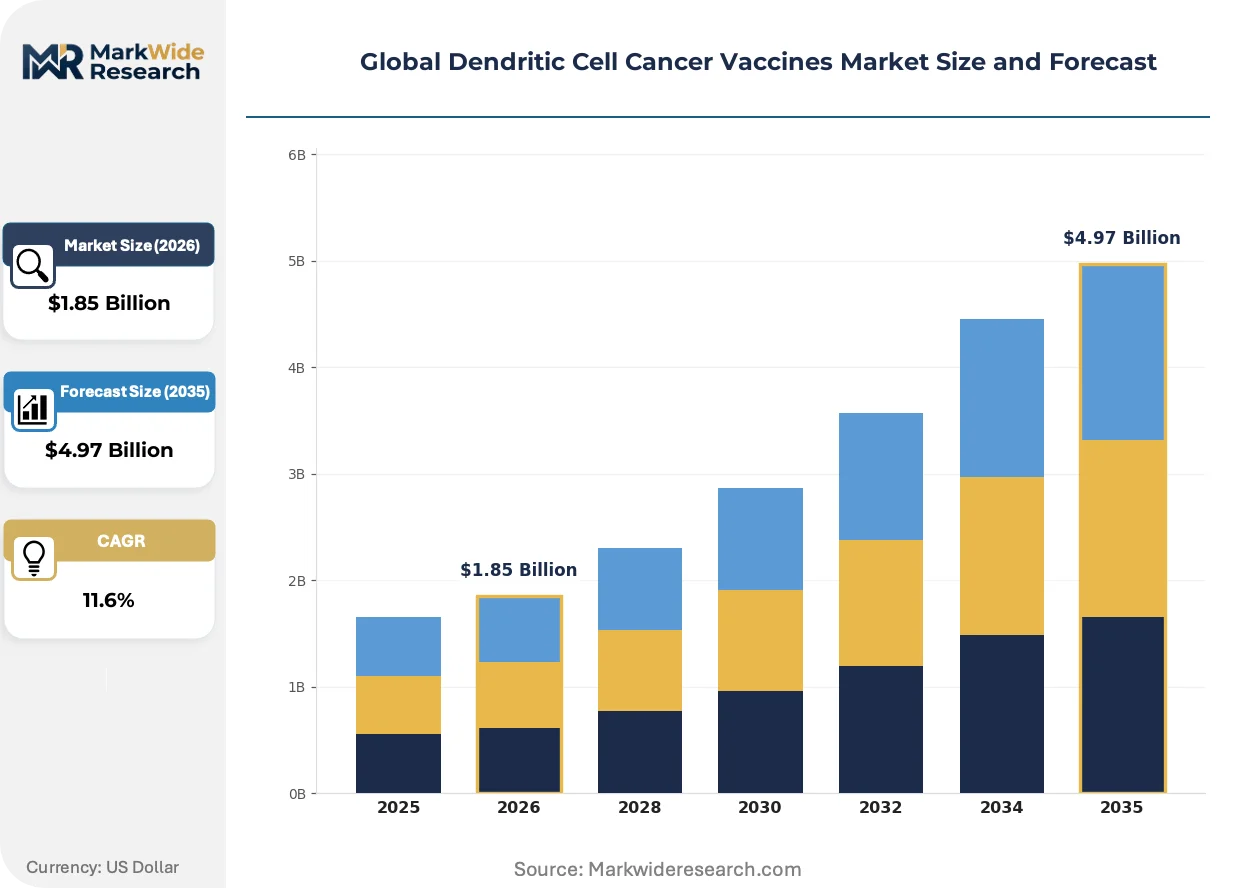
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.97 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autologous Vaccines, Allogeneic Vaccines, Peptide-Pulsed Vaccines, Tumor Lysate-Pulsed Vaccines, mRNA-Based Vaccines Application: Melanoma, Prostate Cancer, Lung Cancer, Pancreatic Cancer, Ovarian Cancer End User: Research Institutes, Biopharmaceutical Firms, Clinical Trial Organizations, Cancer Treatment Centers, Immunotherapy Developers Delivery Technology: Ex Vivo Maturation, In Vivo Targeting, Liposomal Delivery, Electroporation, Nanoparticle-Based Delivery |
| Companies Covered | GlaxoSmithKline plc, Roche (Genentech), Dendreon Pharmaceuticals, Eli Lilly and Company, DanDrit Biotech, Northwest Biotherapeutics, Argos Therapeutics, Immunicum AB, BioNTech SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dendritic Cell Cancer Vaccines Market Shifts & Advancements
Electroporation, mRNA engineering, and computational immunology are converging to compress development timelines while expanding addressable patient populations beyond checkpoint inhibitor-experienced cohorts.
Lipid nanoparticle formulations for dendritic cell loading are hybridizing with traditional peptide-pulsing methods, creating dual-antigen presentation platforms. Academic medical centers in the Netherlands and Switzerland are piloting these hybrid workflows for glioblastoma protocols. The structural consequence is a compression of validation requirements as regulators accept platform comparability rather than product-by-product review.
EMA's priority medicines pathway is accelerating conditional approvals for autologous vaccines in orphan indications, compressing the traditional 12-18 month review window. German and French regulators are harmonizing GMP inspection schedules to reduce redundant site visits. Small and mid-cap developers with limited regulatory affairs staffing are outsourcing compliance documentation to specialized CROs in Copenhagen and Vienna.
Academic medical centers are consolidating procurement authority for cell therapy manufacturing services, displacing department-level vendor selection with centralized contracting offices. This concentration is compressing pricing negotiations and extending payment terms to 90-120 days. The shift is most visible in the United States, where NCI-designated cancer centers are forming regional purchasing consortia.
Global Dendritic Cell Cancer Vaccines Market Segmentation
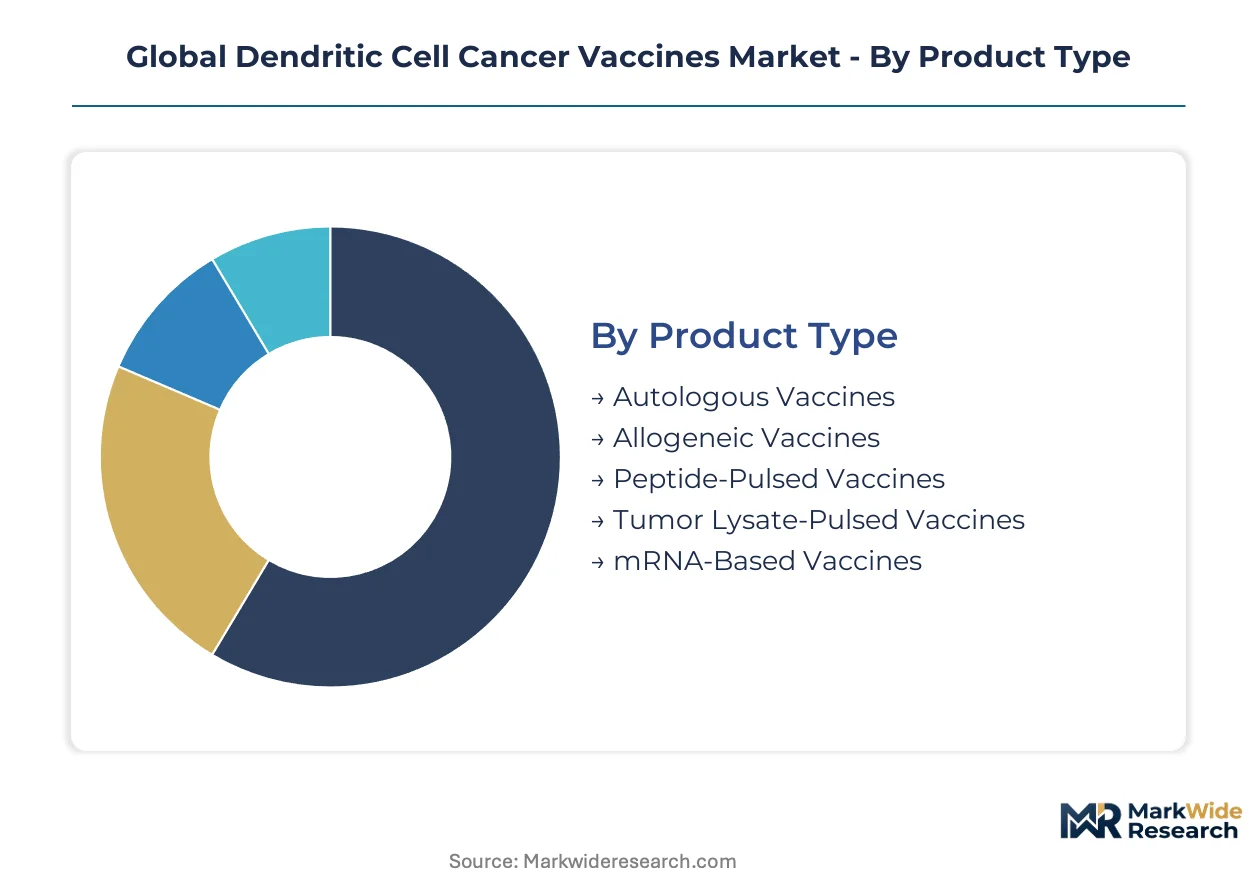
Platform licensing and manufacturing service contracts concentrate revenue capture at the segment level, with autologous workflows demanding intensive technical support while mRNA platforms shift value toward electroporation hardware suppliers. Segmentation reveals how reimbursement codes, GMP inspection protocols, and patient selection algorithms fragment commercial strategies across developer tiers.
Product Type:
After-sales service intensity varies sharply across manufacturing modalities, with autologous platforms requiring leukapheresis coordination and personalized logistics while allogeneic formats standardize into catalog offerings.
- Autologous Vaccines:Patient-derived dendritic cells undergo ex vivo maturation and antigen loading before reinfusion, with each batch tied to individual leukapheresis schedules. Demand clusters at NCI-designated cancer centers in the United States and academic medical centers in Germany where specialized apheresis units and cryopreservation validation protocols reduce batch failure risk.
- mRNA-Based Vaccines:Electroporation efficiency above 85% now enables rapid antigen reprogramming without peptide synthesis lead times. Developers in Switzerland and the Netherlands are prioritizing these platforms for glioblastoma protocols where tumor heterogeneity demands flexible antigen selection.
- Allogeneic Vaccines:Off-the-shelf dendritic cell lines from healthy donors compress manufacturing timelines and enable inventory stocking.
- Peptide-Pulsed Vaccines:Defined antigen cocktails loaded onto mature dendritic cells through direct incubation.
- Tumor Lysate-Pulsed Vaccines:Whole tumor extracts provide broad antigen coverage for poorly characterized malignancies.
The dominant share belongs to Autologous Vaccines, while mRNA-Based Vaccines are closing the gap fastest.
Application:
Clinical trial infrastructure and reimbursement history shape segment economics, with melanoma and prostate cancer offering established pathways while lung cancer demands new checkpoint inhibitor combination protocols.
- Melanoma:Longstanding clinical adoption creates reference sites for training and protocol standardization. United States and Australian treatment centers lead volume given high incidence rates and favorable immunotherapy reimbursement.
- Prostate Cancer:Dendreon's sipuleucel-T established regulatory precedent for autologous cellular immunotherapy in oncology. Medicare coverage determinations in the United States anchor commercial viability for subsequent entrants.
- Lung Cancer:PMDA's sakigake designation in Japan accelerates priority review for non-small cell applications.
- Pancreatic Cancer:Immunologically cold tumor microenvironment challenges efficacy thresholds.
- Ovarian Cancer:Platinum-resistant populations drive interest in combination with PARP inhibitors.
Melanoma retains the largest patient base, though Lung Cancer is expanding most quickly through Japan's accelerated regulatory pathway.
End User:
Procurement centralization at academic medical centers is displacing department-level vendor selection, extending payment terms and compressing pricing negotiations across user categories.
- Cancer Treatment Centers:NCI-designated sites and European comprehensive cancer networks concentrate patient volume for commercial launches. Regional purchasing consortia in the United States now negotiate master service agreements covering apheresis, manufacturing, and infusion logistics.
- Biopharmaceutical Firms:Platform licensing deals transfer manufacturing know-how while retaining royalty streams on commercialized products.
- Research Institutes:Early-stage protocol development depends on academic grant funding and investigator-initiated trial networks.
- Clinical Trial Organizations:Specialized CROs in Copenhagen and Vienna manage regulatory documentation for mid-cap developers.
- Immunotherapy Developers:Cell therapy specialists outsource GMP manufacturing to contract sites in Heidelberg and Munich.
Cancer Treatment Centers command the dominant procurement volume, while Biopharmaceutical Firms are gaining share fastest through platform monetization strategies.
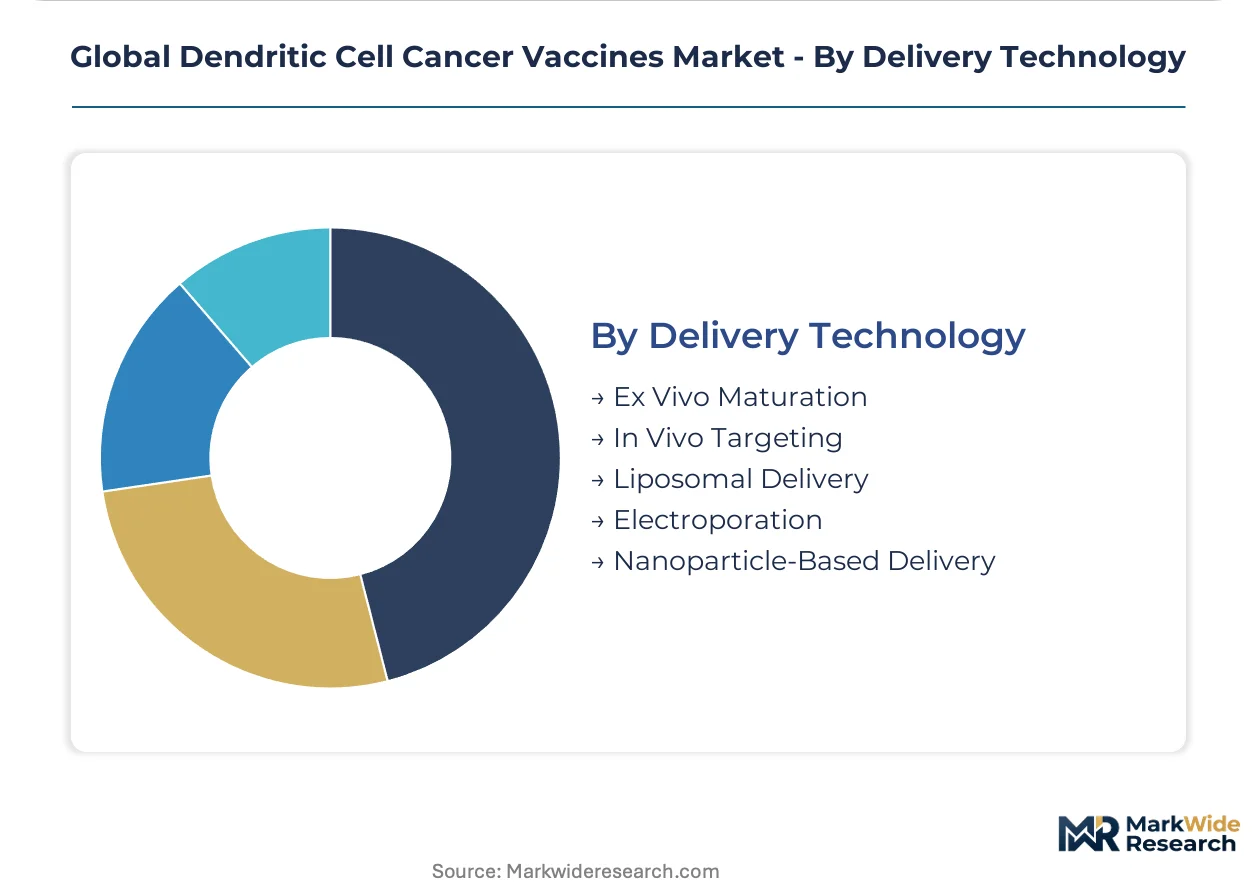
Delivery Technology:
Equipment supplier concentration and validation burden differentiate technology segments, with electroporation hardware dominated by two vendors and liposomal formulations offering regulatory familiarity.
- Electroporation:mRNA transfection rates above 85% enable cold-chain simplification and community oncology center expansion. Closed-system hardware from Boston and Basel suppliers concentrates price-setting power and creates single-source risk for developers.
- Ex Vivo Maturation:Cytokine cocktails in GMP incubators mature immature dendritic cells before antigen loading. Heidelberg and Munich manufacturing clusters reduce batch failure rates through concentrated technical expertise.
- Liposomal Delivery:Lipid nanoparticle formulations hybridize with peptide-pulsing for dual-antigen presentation.
- In Vivo Targeting:Direct dendritic cell activation within the patient eliminates ex vivo processing steps.
- Nanoparticle-Based Delivery:Polymeric carriers enable sustained antigen release kinetics.
Ex Vivo Maturation holds the established position, while Electroporation is climbing the fastest on mRNA platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized GMP manufacturing infrastructure for autologous cell therapies concentrates in three national clusters. FDA, EMA, and PMDA regulatory pathways diverge on cryopreservation validation standards, fragmenting cross-border manufacturing economics.
United States
NCI-designated cancer centers in Seattle and Philadelphia anchor commercial-scale leukapheresis capacity. FDA's regenerative medicine advanced therapy designation compresses approval timelines for autologous platforms. Regional purchasing consortia across academic medical centers now negotiate centralized contracts covering apheresis-to-infusion logistics.
Germany
Heidelberg and Munich manufacturing clusters reduce batch failure rates for peptide-pulsed vaccines through concentrated technical expertise. EMA priority medicines pathways accelerate conditional approvals in orphan indications. The country's specialized GMP infrastructure attracts mid-cap developers outsourcing compliance documentation.
Japan
PMDA's sakigake designation offers priority review for lung cancer applications, an underpenetrated indication relative to melanoma and prostate. Aging oncology populations drive demand for personalized immunotherapy access. Tokyo and Osaka academic medical centers are expanding adoptive cell therapy programs with government research grants.
Switzerland
Swissmedic maintains alignment with EMA inspection protocols while offering accelerated assessment for innovative therapies. Basel concentrates electroporation hardware suppliers and mRNA engineering expertise. Academic medical centers in Geneva and Lausanne pilot hybrid lipid nanoparticle formulations for glioblastoma protocols.
Netherlands
Leiden and Utrecht biotech corridors specialize in algorithm-driven patient selection tools for personalized vaccine design. The EU AI Act introduces documentation requirements for machine learning tools used in manufacturing workflows. Dutch regulators participate in EMA-GMP harmonization initiatives to reduce redundant site inspections.
Global Dendritic Cell Cancer Vaccines Market Competitive Landscape
Platform monetization specialists and integrated manufacturers split the market between licensing revenue and direct commercialization. The competitive structure reflects concentration at the manufacturing technology layer rather than finished product distribution. Two archetypes dominate: developers leveraging mRNA electroporation expertise, and incumbents with established autologous processing infrastructure. Competitive moves center on strategic partnerships for GMP capacity access and geographic expansion through regulatory pathway optimization.
Within the platform licensing tier, BioNTech SE and Dendreon Pharmaceuticals exemplify divergent strategic positioning. BioNTech SE represents the mRNA electroporation archetype with Swiss-German engineering heritage. Dendreon Pharmaceuticals anchors North American autologous manufacturing capacity with Seattle-based cell processing infrastructure. Northwest Biotherapeutics occupies a position between these models, specializing in personalized vaccine workflows that extend clinical timelines. These three entities collectively illustrate how intellectual property monetization is shifting value capture upstream from finished products to manufacturing know-how.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Roche (Genentech) |
| Dendreon Pharmaceuticals |
| Eli Lilly and Company |
| DanDrit Biotech |
| Northwest Biotherapeutics |
| Argos Therapeutics |
| Immunicum AB |
| BioNTech SE |
| Others |
Supply & Pricing Matrix
Boston and Basel suppliers of closed-system electroporation hardware concentrate pricing power upstream, pushing margin pools toward manufacturing service contracts and platform licensing fees downstream. Autologous vaccine developers absorb this cost compression through extended leukapheresis coordination fees and personalized logistics premiums that recapture value from NCI-designated cancer centers.
Pricing Analysis
After-sales service contracts spanning apheresis scheduling, cryopreservation validation, and infusion logistics drive lifetime value beyond the initial manufacturing fee. Three-tier pricing structure across premium, standard, and economy levels segments buyers by GMP certification tier and batch failure guarantee terms. Pricing pressure stems from regional purchasing consortia consolidating procurement authority and extending payment terms to 90-120 days. Academic medical centers exhibit highest price sensitivity due to grant-dependent budgets, while biopharmaceutical firms licensing platforms show lowest sensitivity given royalty-retention structures.
Supply Chain Analysis
Supplier-financing facilities from electroporation hardware vendors extend payment terms to 180 days for qualified GMP manufacturing sites. Supply concentrates in the United States, Germany, and Japan where specialized leukapheresis infrastructure and cryopreservation validation protocols anchor production. Raw material dependencies include recombinant cytokine cocktails, clinical-grade plasmid DNA, and single-use bioreactor components. Single-source vulnerability concentrates in closed-system transfection hardware where two vendors dominate global capacity. Distribution runs through centralized contracting offices at academic medical centers rather than department-level procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where manufacturing coordination and regulatory documentation fees expand faster than the underlying cell processing hardware. Platform licensing revenue from ex vivo maturation protocols now exceeds direct product margins for specialized developers.
For Market Incumbents: Build regulatory documentation moats through investment in FDA master file submissions and EMA quality dossier harmonization. Incumbents should deepen backward integration into electroporation hardware supply through exclusive service contracts with Boston and Basel vendors, while adding cryopreservation validation capacity in Heidelberg to offset EMA inspection fragmentation risk from divergent cell-handling standards. For New Entrants and Emerging Players: Establish a beachhead in lung cancer applications where PMDA's sakigake designation accelerates priority review and reimbursement pathways remain underdeveloped relative to melanoma and prostate. New entrants should target algorithm-driven patient selection tools for personalized vaccine design, partnering with Dutch academic medical centers to compress neoantigen identification timelines while outsourcing GMP manufacturing to established Munich contract sites. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-cap developers holding FDA regenerative medicine advanced therapy designations but lacking commercial manufacturing scale. Long-term viability across the analysis window depends on platform licensing revenue durability rather than single-product market share. Investors should monitor electroporation efficiency benchmarks above 85% as the inflection signal for mRNA platform economics overtaking peptide-pulsed alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA regenerative medicine advanced therapy designation compresses timelines for autologous platforms. |
| Manufacturing Scale-Up | Heidelberg and Munich GMP clusters reduce batch failure rates through concentrated technical expertise. |
| Licensing Agreement | Platform licensing transfers ex vivo maturation know-how while retaining downstream royalty streams. |
| Clinical Trial Advancement | PMDA sakigake designation accelerates lung cancer protocols in Japan's aging oncology population. |
| Pipeline Diversification | mRNA electroporation platforms expand addressable indications beyond checkpoint inhibitor-experienced cohorts. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and GMP inspection databases. Interviews with cell therapy manufacturing executives, regulatory affairs leads at autologous vaccine developers, hospital procurement managers at NCI-designated cancer centers, and payer access specialists informed demand-side assumptions. Bottom-up patient volume estimates by indication triangulate against top-down platform licensing revenue reported in SEC disclosures and European biotech filings.
Forecast inputs include electroporation efficiency trajectories, GMP inspection harmonization progress between FDA and EMA, and regional purchasing consortium formation timelines across academic medical centers. Segmentation dimensions span product type, application, end user, and delivery technology, with additional modeling of regulatory pathway clusters by geography. CAGRs derive from patient population projections weighted by reimbursement code availability and manufacturing capacity expansion schedules. Industry-specific inputs capture cytokine cocktail cost trends and cryopreservation validation protocol adoption rates.
Sensitivities concentrate around electroporation hardware supplier consolidation, EMA-FDA GMP inspection divergence, and checkpoint inhibitor combination trial outcomes. Forecasts reflect documented assumptions regarding leukapheresis capacity expansion and platform licensing revenue recognition patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
RNA Based Therapeutics and Vaccines Market
Cell & Gene Therapy
Cell Therapy Manufacturing Market
Cell & Gene Therapy
Stem Cell Reconstructive Market
Cell & Gene Therapy
Cell Regeneration Medicine Market
Cell & Gene Therapy
Nucleic Acid Therapeutics CDMO Market
Cell & Gene Therapy
Middle East and Africa Viral Vector Purification Market
Cell & Gene Therapy
Stem Cell and Gene Therapy Biological Testing Market
Cell & Gene Therapy
Mrna Therapeutics Contract Development & Manufacturing Market
Cell & Gene Therapy
Global T-Cell Lymphoma Market
Cell & Gene Therapy
CNS Specific Antisense Oligonucleotide Market
Cell & Gene Therapy
Cell Expansion Market
Cell & Gene Therapy
Middle East and Africa Cancer Vaccines Market
Cell & Gene Therapy
Europe Gene Therapy Market
Cell & Gene Therapy
Cryopreservation Cell Lines Market
Cell & Gene Therapy
Stem Cell Concentration System Market
Cell & Gene Therapy
Global Therapeutic Vaccines Market