
 Canine Stem Cell Therapy Market | 2026-2036
Canine Stem Cell Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Canine Stem Cell Therapy Market Analysis
Premium allogeneic stem cell formulations and commodity autologous processing kits is decoupling across the canine therapeutic landscape. VetStem Biopharma anchors the premium tier through proprietary adipose-derived processing platforms deployed across certified veterinary networks. MediVet Biologics competes on accessibility with point-of-care kits that enable same-day autologous harvest and reinfusion in clinical settings. Zoetis extends its animal health portfolio into regenerative modalities, leveraging existing distribution relationships with large veterinary practice groups.
Canine stem cell therapy encompasses the isolation, expansion, and therapeutic administration of multipotent progenitor cells—primarily mesenchymal populations sourced from adipose tissue or bone marrow—to promote tissue repair and modulate inflammatory pathways in dogs. The intervention typically requires aseptic harvest, enzymatic or mechanical digestion, concentration via centrifugation, and direct intra-articular or intravenous delivery at cell densities ranging from 10^6 to 10^7 cells per kilogram of body weight. Mesenchymal stem cells dominate current revenue contribution due to established safety profiles and simpler isolation protocols compared to induced pluripotent alternatives. Orthopedic applications lead absolute procedure volume, though autoimmune disorder protocols represent the fastest-expanding segment as veterinary immunology research advances.
The FDA Center for Veterinary Medicine evaluates cell-based therapies under the animal drug approval framework, requiring demonstration of safety and efficacy through controlled field studies. The EU Veterinary Medicines Regulation and EMA guidelines impose comparable preclinical and clinical validation standards, while ISO 22442 addresses xenogeneic material risk in manufacturing. Stakeholders must monitor evolving regulatory distinctions between minimally manipulated autologous procedures and substantially altered allogeneic products, as classification determines compliance burden and market access timelines.
Market Dynamics
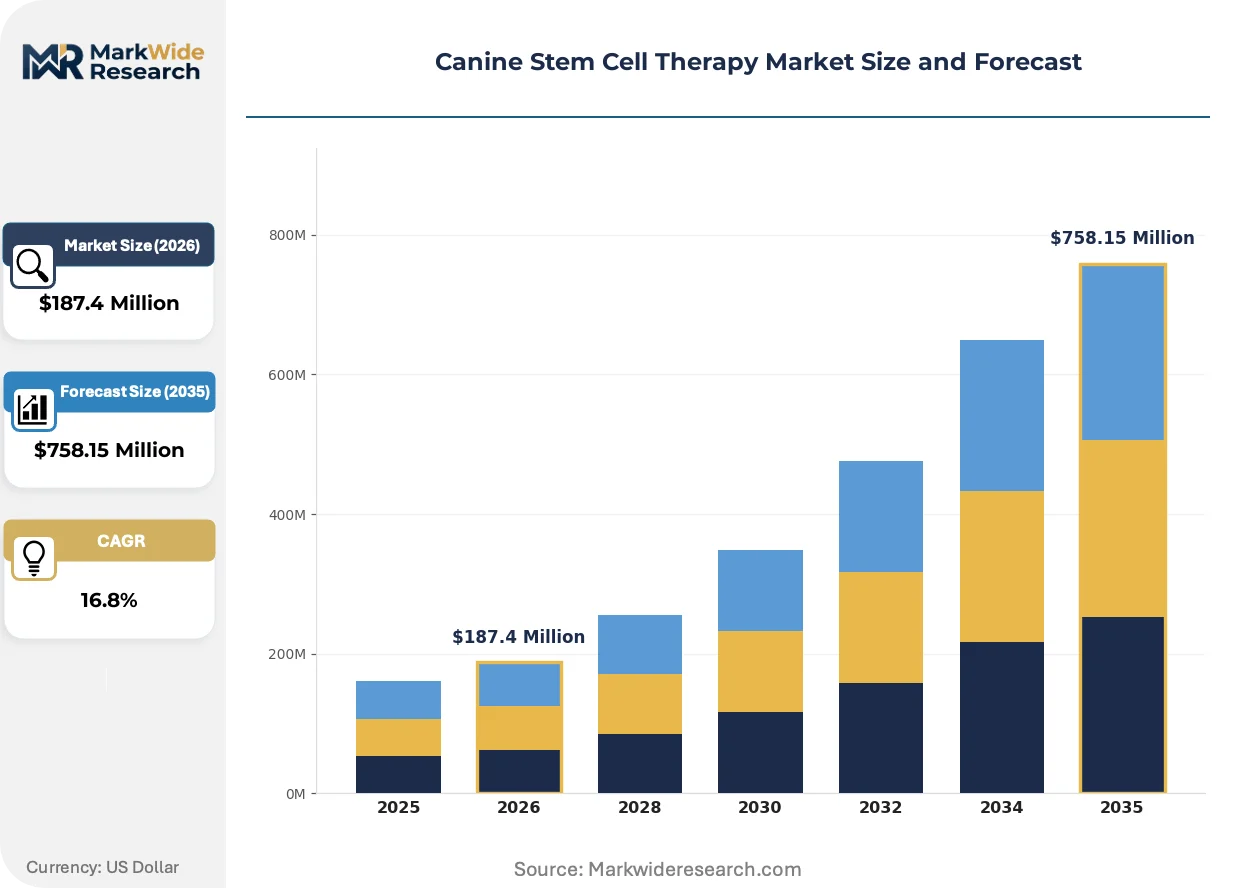
The canine stem cell therapy market is bifurcating sharply between premium allogeneic formulations and accessible autologous processing kits, with regulatory classification thresholds determining commercialization pathways and margin structures for veterinary service providers.
Growth Catalysts
- FDA Center for Veterinary Medicine guidance:Clarified approval frameworks for minimally manipulated autologous procedures accelerate clinic-level adoption without full drug approval burdens.
- Adipose-derived mesenchymal stem cell protocols:Simplified enzymatic digestion and concentration methods reduce processing time from hours to minutes in clinical settings.
- United States pet insurance penetration:Reimbursement coverage for regenerative procedures expands addressable patient populations beyond cash-pay clientele.
Market Restraints
- Allogeneic product manufacturing costs:GMP-compliant cell expansion facilities require capital-intensive cleanroom infrastructure and quality control systems.
- EU Veterinary Medicines Regulation compliance:Substantially altered cell products face centralized marketing authorization timelines extending 24-36 months.
- Autologous harvest variability:Adipose tissue quality and cell yield fluctuate with patient age, breed, and metabolic condition, compromising dose consistency.
Strategic Opportunities
- Autoimmune disorder protocols:Veterinary immunology research expands therapeutic indications beyond orthopedic applications into atopic dermatitis and inflammatory bowel disease.
- Point-of-care kit distribution:Direct-to-clinic logistics models bypass traditional veterinary distributor markups and accelerate same-day procedure availability.
- ISO 22442 xenogeneic material standards:Harmonized international manufacturing guidelines reduce regulatory duplication for multi-jurisdictional product launches.
Industry Challenges
- Cell processing technician certification:Aseptic technique and density gradient centrifugation competency gaps limit service expansion in general practice settings.
- Intellectual property fragmentation:Overlapping patent claims on isolation methods and culture media compositions complicate freedom-to-operate assessments for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canine Stem Cell Therapy Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $758.15 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mesenchymal Stem Cells, Adipose-Derived Stem Cells, Bone Marrow-Derived Stem Cells, Induced Pluripotent Stem Cells Application: Orthopedic Conditions, Autoimmune Disorders, Skin Disorders, Neurological Disorders End User: Veterinary Clinics, Research Institutions, Animal Hospitals, Pet Owners Treatment Type: Injections, Infusions, Surgical Procedures, Regenerative Medicine |
| Companies Covered | VetStem Biopharma, MediVet Biologics, Aratana Therapeutics, Boehringer Ingelheim, Zoetis, Animal Cell Therapies, Regeneus, Celavet Inc., VetCell Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canine Stem Cell Therapy Market Emerging Trajectories
Lyophilized and cryopreserved off-the-shelf stem cell products are compressing treatment preparation timelines while shifting competitive advantage from processing capability to cold-chain logistics and shelf-life stability engineering.
Allogeneic cryopreserved stem cell formulations is overtaking fresh autologous harvest protocols in high-volume specialty clinics. These banked products eliminate same-day surgical harvest requirements and reduce anesthesia exposure for geriatric canine patients. Veterinary orthopedic centers in metropolitan United States markets are consolidating purchasing around characterized cell lines with documented potency assays.
The EU Veterinary Medicines Regulation's distinction between minimally manipulated and substantially altered products is reclassifying previously exempt autologous procedures. Manufacturers of enzymatically digested and culture-expanded formulations now face centralized marketing authorization requirements previously limited to pharmaceutical sponsors. German and French veterinary regulators are interpreting threshold criteria more stringently than southern member states.
Pet owners in United States coastal metropolitan areas are demanding outcome-guaranteed pricing models for osteoarthritis protocols. Specialty clinics are responding with bundled episode-of-care packages that include diagnostic imaging, cell administration, and follow-up assessments. This reimbursement structure is displacing per-procedure fee-for-service billing in high-competition veterinary markets.
Canine Stem Cell Therapy Market Segmentation
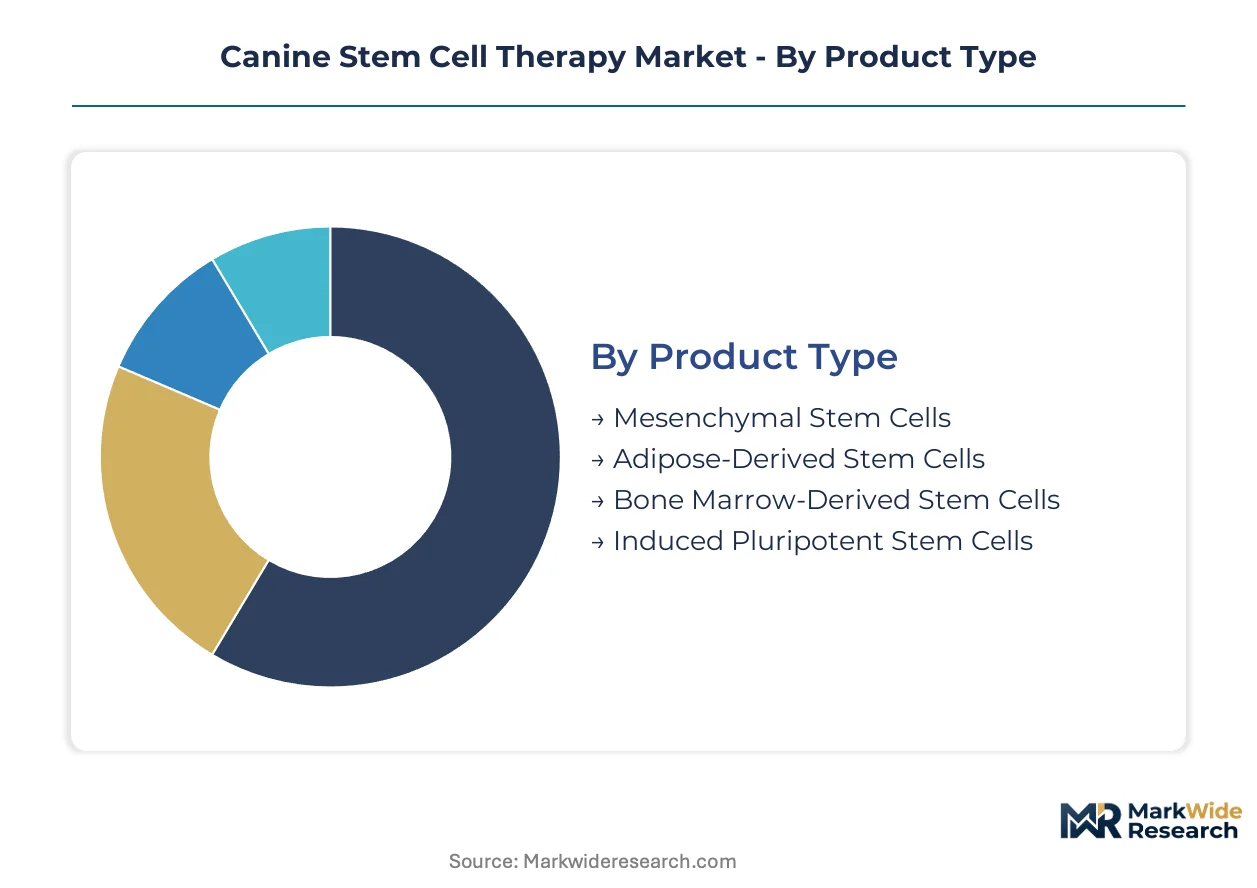
Canine stem cell therapy segments diverge sharply across processing complexity and regulatory burden. Product type determines manufacturing infrastructure requirements, while application focus shapes clinical training investments and reimbursement pathways.
Product Type:
Supply concentration clusters around cell sources with established isolation protocols and documented safety profiles.
- Mesenchymal Stem Cells:Multipotent stromal populations derived from connective tissue sources dominate current therapeutic deployment. Veterinary orthopedic centers in the United States concentrate demand here due to established efficacy data in osteoarthritis protocols and simpler regulatory classification for minimally manipulated preparations.
- Adipose-Derived Stem Cells:Lipoaspirate harvest yields high cell density with minimal donor morbidity. Specialty clinics favor this source for same-day autologous procedures, though enzymatic digestion steps trigger stricter oversight under EU Veterinary Medicines Regulation thresholds.
- Bone Marrow-Derived Stem Cells:Aspirate collection requires general anesthesia and surgical expertise, limiting adoption to university veterinary hospitals.
- Induced Pluripotent Stem Cells:Reprogrammed somatic cell lines face substantial regulatory hurdles and manufacturing complexity, restricting development to research consortia.
Mesenchymal stem cells absorb the bulk of installed capacity; induced pluripotent stem cells are expanding most quickly in preclinical pipelines.
Application:
Cost tier stratification separates high-frequency orthopedic procedures from emerging autoimmune protocols with premium pricing potential.
- Orthopedic Conditions:Osteoarthritis and tendon injuries constitute the procedural backbone of canine regenerative medicine. United States metropolitan specialty practices drive volume through bundled episode-of-care packages covering diagnostics, cell administration, and follow-up imaging.
- Autoimmune Disorders:Atopic dermatitis and inflammatory bowel disease applications leverage mesenchymal stem cell immunomodulatory properties. Veterinary dermatology referral networks in Germany and France are piloting standardized protocols, though outcome variability constrains reimbursement expansion.
- Skin Disorders:Wound healing and graft support applications concentrate in emergency and referral hospitals with surgical capabilities.
- Neurological Disorders:Spinal cord injury and degenerative myelopathy protocols remain investigational, limited to academic veterinary medical centers with advanced imaging infrastructure.
Orthopedic conditions capture the majority of procedure volume; autoimmune disorders are gaining share fastest as immunology research matures.
End User:
Customer type determines service model complexity and margin structure across the value chain.
- Veterinary Clinics:General and specialty practices represent the primary service delivery channel. Point-of-care processing kits enable same-day autologous procedures without external laboratory dependency.
- Research Institutions:University veterinary medical centers conduct pivotal safety and efficacy studies required for regulatory submission.
- Animal Hospitals:Emergency and referral facilities handle complex cases requiring surgical cell implantation or multi-modal therapy integration.
- Pet Owners:Direct-to-consumer channels remain limited by regulatory restrictions on unsupervised cell product administration.
Veterinary clinics anchor current service capacity; research institutions are scaling fastest as pipeline assets advance toward marketing authorization.
Treatment Type:
Volume concentration favors minimally invasive delivery methods compatible with outpatient workflows.
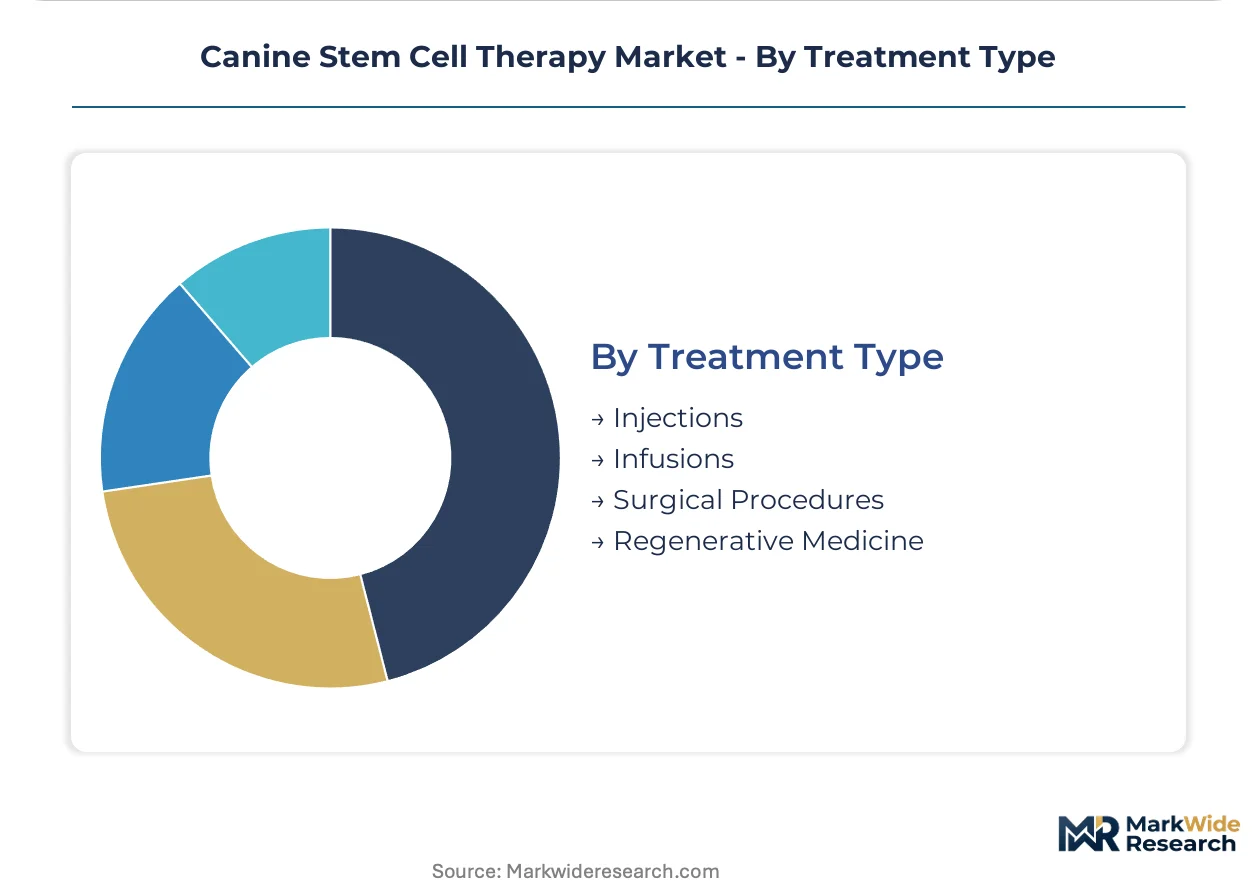
- Injections:Intra-articular and intravenous administration dominates outpatient procedure economics. Ultrasound-guided joint injection protocols standardize dosing accuracy across certified veterinary networks.
- Infusions:Systemic delivery routes target diffuse inflammatory conditions beyond localized orthopedic pathology.
- Surgical Procedures:Direct implantation during orthopedic surgery commands premium pricing but requires specialized training and facility accreditation.
- Regenerative Medicine:Scaffold-based and combination therapies integrate cells with biomaterial carriers, concentrating in research and academic settings.
Injections absorb the bulk of procedure volume; regenerative medicine is climbing the fastest as tissue engineering platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty veterinary clinics in the Greater Boston corridor anchor North American demand for canine regenerative procedures, with metropolitan clusters in the United States and Western Europe driving procedural volume through pet insurance penetration and discretionary spending capacity.
United States
Metropolitan specialty practices in California and New York drive premium allogeneic adoption through bundled episode-of-care pricing. FDA Center for Veterinary Medicine guidance on minimally manipulated autologous procedures accelerates clinic-level deployment without full drug approval burdens. University veterinary medical centers in Colorado and Florida conduct pivotal safety studies for pipeline assets.
Germany
Veterinary dermatology referral networks in Munich and Hamburg pilot standardized autoimmune disorder protocols leveraging mesenchymal stem cell immunomodulatory properties. The EU Veterinary Medicines Regulation imposes centralized marketing authorization timelines of 24-36 months for substantially altered cell products. German regulators interpret threshold criteria more stringently than southern member states.
United Kingdom
London and Southeast England concentrate demand for orthopedic applications in geriatric canine populations. The Veterinary Medicines Directorate aligns with EMA guidelines for preclinical and clinical validation standards. Royal Veterinary College research consortia advance induced pluripotent stem cell pipelines toward regulatory submission.
France
Paris and Lyon metropolitan areas exhibit expanding service menus for soft-tissue injury protocols in sporting and working dog breeds. ANSM oversight of xenogeneic material risk in manufacturing aligns with ISO 22442 harmonized guidelines. French veterinary regulators maintain intermediate stringency on autologous procedure classification thresholds.
Japan
Tokyo and Osaka specialty clinics demonstrate growing procedural volume for spinal cord injury investigational protocols. PMDA evaluation frameworks for animal cell-based therapies require controlled field study demonstrations. Academic veterinary medical centers in Kansai region concentrate advanced imaging infrastructure for neurological disorder research.
Canine Stem Cell Therapy Market Vendor Landscape
Premium-margin players sit above commodity-margin players across processing complexity and regulatory compliance burden, with allogeneic cell banks commanding pricing multiples over point-of-care autologous kits. The vendor base stratifies into three tiers: integrated animal health conglomerates with distribution scale, specialized biopharma developers with proprietary processing platforms, and kit manufacturers competing on accessibility and same-day procedure enablement. Dominant competitive moves include strategic partnerships with certified veterinary networks and geographic expansion through direct-to-clinic logistics models that bypass traditional distributor markups.
Within the specialized biopharma tier, VetStem Biopharma and MediVet Biologics occupy positions representing divergent strategic archetypes. VetStem Biopharma exemplifies the premium allogeneic formulation approach through proprietary adipose-derived processing platforms deployed across certified veterinary networks. MediVet Biologics represents the accessibility-focused vector with point-of-care kits enabling same-day autologous harvest and reinfusion in clinical settings. Zoetis, as an integrated animal health conglomerate, extends existing distribution relationships with large veterinary practice groups into regenerative modalities.
| Leading Market Players |
|---|
| VetStem Biopharma |
| MediVet Biologics |
| Aratana Therapeutics |
| Boehringer Ingelheim |
| Zoetis |
| Animal Cell Therapies |
| Regeneus |
| Celavet Inc. |
| VetCell Therapeutics |
| Others |
Supply Flow & Price Mechanics
Certified cell processing technicians in the Greater Boston corridor command wage premiums that compress margin spreads between premium allogeneic formulations and commodity autologous kits. Labor-cost differentials between GMP-compliant cleanroom operators and general veterinary staff widen pricing-tier spreads across the canine therapeutic landscape.
Pricing Analysis
Outcome-guaranteed episode-of-care pricing anchors metropolitan United States markets, with bundled packages covering diagnostic imaging, cell administration, and follow-up assessments displacing per-procedure fee-for-service billing. Three-tier pricing structure across premium allogeneic banks, standard autologous processing, and economy kit tiers reflects certification grade and cold-chain sophistication. Pricing pressure stems from pet insurance reimbursement rate negotiations constraining cash-pay premiums. General veterinary clinics exhibit highest price sensitivity; specialty orthopedic centers demonstrate lowest sensitivity due to outcome-based client retention.
Supply Chain Analysis
Dual-sourcing requirements from large veterinary practice groups mandate multi-supplier qualification for both allogeneic cell banks and point-of-care processing consumables. Manufacturing concentrates in the United States, Germany, and Japan, with GMP facility certification determining supplier eligibility. Raw material dependencies include clinical-grade enzymes, density gradient media, and cryopreservation solutions. Single-source vulnerability runs through proprietary cell line repositories held by specialized biopharma developers. Distribution runs through direct-to-clinic logistics models that bypass traditional veterinary distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The canine stem cell therapy market reads as a cost-of-compliance story, with the FDA Center for Veterinary Medicine's animal drug approval framework erecting barrier-to-entry moats that favor incumbents with established field study data packages.
For Market Incumbents: Anchor market position through backward integration into GMP-compliant cell expansion facilities and captive supply of characterized cell lines with documented potency assays. Defend against emerging point-of-care kit manufacturers by securing exclusive distribution agreements with certified veterinary networks in high-penetration metropolitan clusters. Invest in ISO 22442 xenogeneic material compliance to preempt regulatory fragmentation across multi-jurisdictional markets. For New Entrants and Emerging Players: Enter via autoimmune disorder protocols in German and French veterinary dermatology referral networks, where standardized immunomodulatory applications remain underpenetrated relative to orthopedic saturation. Target point-of-care kit distribution in United States general practice settings seeking same-day procedure capability without external laboratory dependency. Pursue direct-to-clinic logistics partnerships that displace incumbent distributor relationships. For Investors and Strategic Acquirers: Re-rating potential sits with specialized biopharma developers possessing proprietary adipose-derived processing platforms given accelerating FDA guidance clarity on minimally manipulated autologous procedures. Long-term viability favors assets with demonstrated safety profiles across multi-site pivotal studies and established reimbursement pathways with major pet insurance carriers. Monitor EU Veterinary Medicines Regulation threshold interpretations as inflection indicator for allogeneic product classification risk.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Pivotal field studies with FDA Center for Veterinary Medicine generate marketing authorization precedents for pipeline assets. |
| Regulatory Approval Pathway | EU Veterinary Medicines Regulation centralized authorization unlocks harmonized market access across member state veterinary clinics. |
| Manufacturing Scale-Up | GMP-compliant cleanroom expansion reduces per-dose production costs for cryopreserved allogeneic stem cell banks. |
| Strategic Partnership | Certified veterinary network alliances secure exclusive distribution channels for premium allogeneic formulations. |
| Geographic Expansion | Direct-to-clinic logistics models penetrate underserved metropolitan United States markets beyond coastal corridors. |
Methodological Framework
Independent corroboration across veterinary practice administrators, regulatory affairs specialists at animal health conglomerates, cell processing laboratory directors, and pet insurance reimbursement managers underwrites the qualitative findings. Primary interviews combined with secondary validation from FDA Center for Veterinary Medicine guidance documents, EMA veterinary medicines guidelines, ISO 22442 manufacturing standards, and university veterinary medical center research disclosures establish evidentiary foundations. Bottom-up procedure volume estimates triangulate against top-down market value reconstructions across the analysis window.
Rate-of-change decomposition separates volume growth from price-mix effects across product type, application focus, and end-user segments. Segmentation dimensions modeled include cell source, therapeutic indication, treatment delivery method, and regional regulatory cluster. CAGRs derive from logistic diffusion curves fitted to historical adoption patterns and adjusted for reimbursement expansion trajectories. Industry-specific forecast inputs incorporate pet insurance penetration rates and specialty clinic expansion pipelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EU Veterinary Medicines Regulation reclassification rulings or FDA guidance revisions on minimally manipulated thresholds. Forecasts reflect assumptions regarding continued reimbursement expansion and stable regulatory classification boundaries. A model refresh is warranted upon material change in pet insurance coverage policy for regenerative procedures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Global Viral Vector and Plasmid DNA Manufacturing Market
Cell & Gene Therapy
Cell and Gene Supply Chain Services Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Drugs Market
Cell & Gene Therapy
Stem Cell Therapy Market
Cell & Gene Therapy
Cell Therapy Raw Materials Market
Cell & Gene Therapy
Cell Regeneration Medicine Market
Cell & Gene Therapy
RNA Based Therapeutics and Vaccines Market
Cell & Gene Therapy
Global Neoantigen Cancer Vaccine Market
Cell & Gene Therapy
Stem Cell Manufacturing Market
Cell & Gene Therapy
Rheumatoid Arthritis Stem Cell Therapy Market
Cell & Gene Therapy
North America Stem Cell Therapy Market
Cell & Gene Therapy
Asia-Pacific Viral Vector Purification Market
Cell & Gene Therapy
Regenerative Medicine Market
Cell & Gene Therapy
North America Cancer Vaccines Market
Cell & Gene Therapy
Global Mrna Therapeutics Market
Cell & Gene Therapy
Cell Therapy Technologies Market