
 Leukapheresis Products Market | 2026-2036
Leukapheresis Products Market Size, Share, and Industry Trends Forecast 2026-2036
Leukapheresis Products Market Outlook
Asset-light leasing models for apheresis equipment are reshaping competitive entry in the leukapheresis products space. Fresenius Kabi leverages its dialysis service infrastructure to bundle machine placement with consumable contracts. Haemonetics Corporation anchors its position through captive manufacturing of disposables tied to its proprietary centrifugation platforms. Miltenyi Biotec specializes in magnetic separation workflows that command premium positioning in cell therapy manufacturing.
Leukapheresis products encompass devices, disposables, and reagents designed to selectively extract white blood cells from whole blood through centrifugation, membrane filtration, or immunomagnetic separation, typically processing 1.5 to 3 blood volumes over 2-4 hours to yield 10^9 to 10^10 leukocytes for therapeutic or research applications. Automated systems dominate capital expenditure budgets due to their integration with cell processing software and closed-system compliance, while membrane filtration technology leads clinical throughput for standard mononuclear cell collection. Consumables capture recurring revenue streams with replacement cycles tied to procedure volumes, and immunoaffinity-based approaches represent the fastest-growing technology segment as CAR-T protocols demand higher purity CD3+ or CD34+ starting material.
The FDA regulates leukapheresis devices as Class II or Class III medical products requiring 510(k) clearance or PMA pathways, while the EMA's ATMP framework governs downstream cell therapy applications that drive device utilization. ISO 13485 certification and EU MDR conformity assessments shape supplier qualification for international procurement. Stakeholders must monitor how evolving GMP requirements for cell starting material traceability will redefine equipment validation protocols and service contract structures.
Market Dynamics
Automated leukapheresis systems are displacing manual protocols as CAR-T manufacturing scales demand closed-system compliance and real-time cell quality monitoring integrated with downstream bioprocessing software.
Growth Catalysts
- FDA cell and gene therapy guidance:Evolving ATMP oversight accelerates capital investment in validated collection platforms by contract development organizations seeking pre-approval inspection readiness.
- Academic medical center expansion:United States research hospitals anchor procurement volumes through integrated apheresis-to-manufacturing workflows for autologous cell therapies.
- Immunomagnetic separation:CD3+ and CD34+ purity requirements in CAR-T protocols pull demand toward higher-yield collection technologies with integrated cell selection modules.
Market Restraints
- Single-use consumable concentration:Proprietary disposables tied to specific centrifugation platforms lock buyers into recurring cost structures with limited supplier alternatives.
- Plasma-derived input volatility:Donor availability fluctuations and collection logistics complexity constrain consistent leukapheresis scheduling for commercial-scale cell therapy production.
- EU MDR conformity timelines:Extended notified body assessment periods delay new device market entry and inflate regulatory compliance expenditure for European distribution.
Strategic Opportunities
- India CDSCO pathway acceleration:Emerging local cell therapy manufacturing infrastructure creates first-mover positioning for automated collection platform deployment in academic hospital networks.
- Leasing-plus-consumable bundling:Asset-light equipment placement models reduce capital barriers for mid-tier contract research organizations entering cell therapy support services.
- GMP traceability mandates:Starting material documentation requirements open service revenue streams for validation protocol development and equipment qualification consulting.
Industry Challenges
- Apheresis technician specialization:Shortage of operators trained in both clinical collection and cell therapy manufacturing interface protocols constrains facility throughput expansion.
- Legacy LIS integration:Hospital information system compatibility gaps complicate automated data capture for chain-of-identity documentation required by FDA donor tracking rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leukapheresis Products Market |
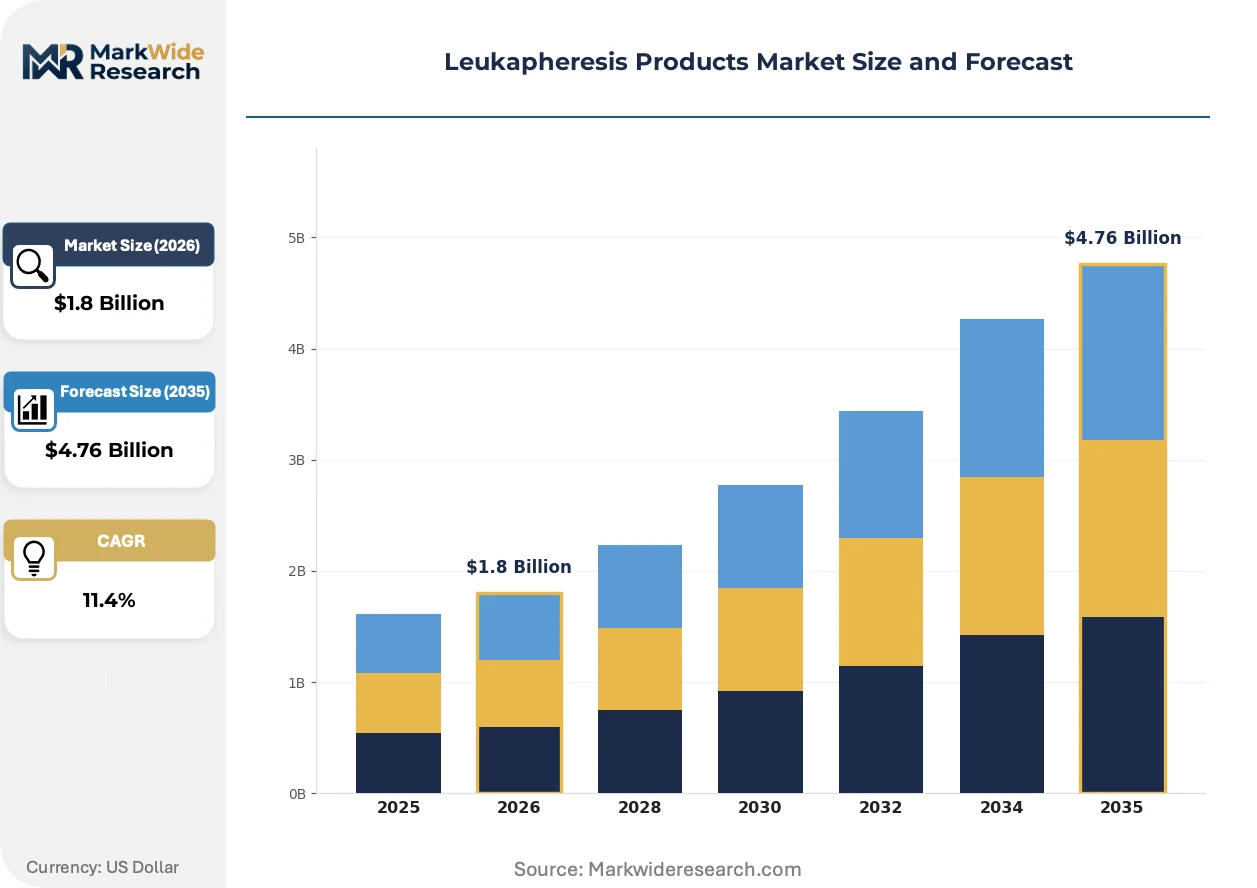
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Systems, Manual Devices, Accessories, Consumables End User: Hospitals, Blood Banks, Research Institutions, Clinics Technology: Membrane Filtration, Centrifugation, Magnetic Separation, Immunoaffinity Application: Oncology, Hematology, Transplantation, Regenerative Medicine |
| Companies Covered | Terumo BCT, Fresenius Kabi, Haemonetics Corporation, Asahi Kasei Medical, Macopharma, Miltenyi Biotec, Nikkiso Co., Ltd., Baxter International, Lonza Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leukapheresis Products Market Strategic Shifts
Closed-system automation and real-time analytics are compressing the collection-to-manufacturing timeline while regulatory documentation requirements reshape equipment validation standards across cell therapy supply chains.
Continuous flow centrifugation with integrated spectroscopic cell counting is rendering obsolete batch-mode collection protocols that require offline quality verification. CAR-T developers in the United States and Germany are adopting these platforms at replacement cycles of 18-24 months. The technology is rendering obsolete the 4-6 hour post-collection hold periods that previously delayed cryopreservation and logistics planning.
EMA's ATMP framework revisions are tightening starting material traceability requirements for leukapheresis-derived cellular products. Device manufacturers must now embed electronic batch records and donor-chain documentation directly into collection software. European contract manufacturers are responding by consolidating procurement around platforms with pre-validated GMP compliance modules rather than retrofitting legacy equipment.
Academic medical centers are unbundling service contracts from equipment acquisition, negotiating standalone validation support and operator training packages. This disintermediation compresses vendor margin capture and shifts revenue toward consumable throughput. The pattern is most visible in United States metropolitan hospital clusters where multiple cell therapy trials create competing demands on shared apheresis suites.
Leukapheresis Products Market Segmentation
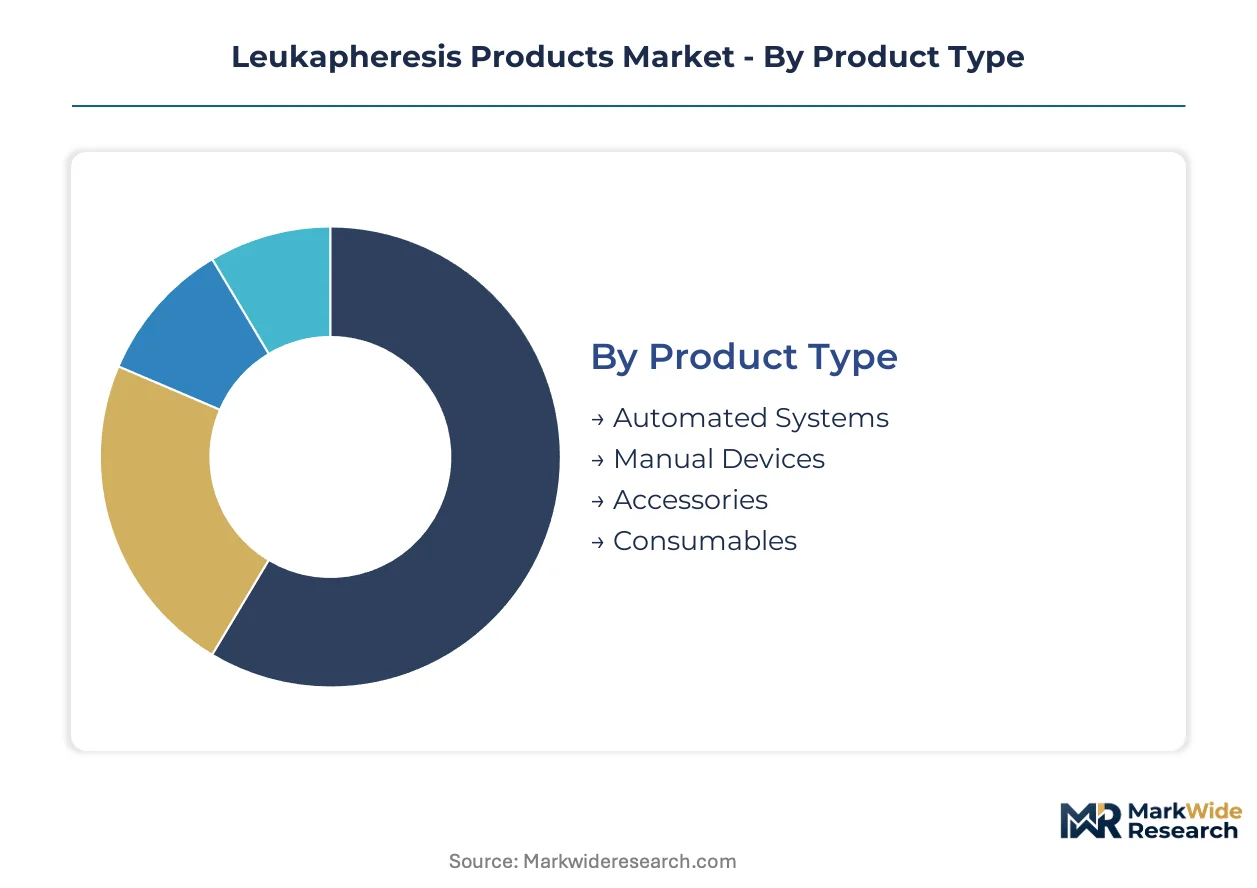
Leukapheresis product configurations diverge sharply based on whether the use case demands closed-system automation for cell therapy manufacturing or cost-efficient manual collection for diagnostic sampling. Procurement patterns in this market split between capital-intensive equipment platforms and recurring consumable streams, with technology choices directly constraining downstream therapeutic applications.
Product Type:
Use-case spectrum spans high-throughput manufacturing environments requiring validated automation to resource-constrained settings prioritizing equipment flexibility.
- Automated Systems:Closed centrifugation platforms integrate with cell processing software to enable real-time quality monitoring and electronic batch documentation required by FDA cell therapy guidance. Academic medical centers in the United States anchor procurement volumes through integrated apheresis-to-manufacturing workflows for autologous CAR-T production.
- Consumables:Single-use disposables including collection sets, separation chambers, and tubing circuits capture recurring revenue tied to procedure volumes. Proprietary formats locked to specific centrifugation platforms constrain buyer switching and inflate lifetime cost structures for high-frequency collection facilities.
- Manual Devices:Semi-automated or gravity-dependent collection systems serve diagnostic leukocyte harvesting and research applications with lower throughput requirements.
- Accessories:Auxiliary components including cell counting interfaces, sample ports, and cryopreservation connectors extend platform functionality without core system replacement.
Established volume favors consumables; emerging adoption favors automated systems.
End User:
Procurement authority concentrates in institutions with integrated cell therapy manufacturing capabilities or high-volume donor collection mandates.
- Hospitals:Academic medical centers with embedded GMP facilities drive specification requirements through combined clinical collection and therapeutic manufacturing workflows. United States metropolitan hospital clusters with multiple concurrent cell therapy trials create competing demands on shared apheresis suite capacity.
- Blood Banks:Collection facilities prioritize membrane filtration throughput for standard mononuclear cell harvesting from volunteer donors. Donor availability fluctuations and collection logistics complexity constrain consistent scheduling for commercial-scale cell therapy production.
- Research Institutions:Preclinical and translational laboratories favor flexible manual devices supporting protocol variation without validated manufacturing overhead.
- Clinics:Outpatient settings with limited apheresis volume deploy leased equipment or third-party collection services to avoid capital commitment.
Revenue concentration sits with hospitals; contract research organizations represent the steepest expansion trajectory.
Technology:
Platform selection hinges on target cell purity specifications and integration requirements with downstream bioprocessing workflows.
- Centrifugation:Continuous flow density-gradient separation dominates clinical throughput for standard mononuclear cell collection, processing 1.5 to 3 blood volumes over 2-4 hour procedures. Fresenius Kabi and Haemonetics Corporation anchor positions through captive manufacturing of disposables tied to proprietary centrifugation platforms.
- Immunoaffinity:CD3+ and CD34+ selection modules command premium positioning in CAR-T manufacturing where starting material purity directly impacts therapeutic efficacy. Magnetic separation workflows from Miltenyi Biotec integrate with automated collection systems to yield 10^9 to 10^10 highly purified leukocytes.
- Membrane Filtration:Cross-flow filtration systems offer rapid processing for large-volume donor collection without density-gradient media.
- Magnetic Separation:Immunomagnetic bead-based selection enables positive or negative cell enrichment with programmable specificity for research and clinical applications.
Clinical throughput favors centrifugation; CAR-T protocol requirements favor immunoaffinity.
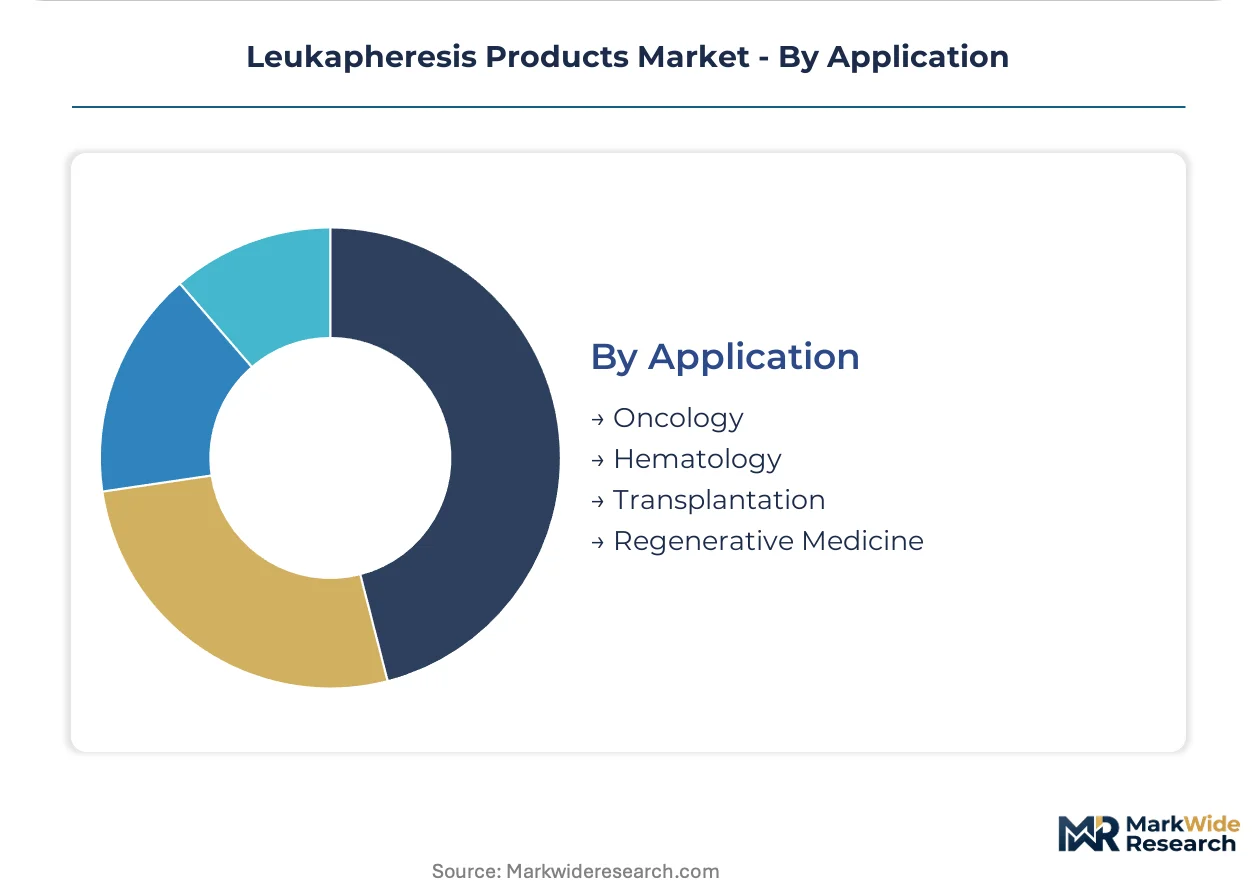
Application:
Therapeutic indication directly determines cell quantity, purity thresholds, and regulatory documentation burdens.
- Oncology:CAR-T and tumor-infiltrating lymphocyte therapies demand highest-purity CD3+ starting material with full chain-of-identity documentation. EMA's ATMP framework revisions tighten starting material traceability requirements, embedding electronic batch records directly into collection software.
- Hematology:Stem cell transplantation protocols require CD34+ progenitor cell collection with viability thresholds dictating cryopreservation timing and logistics coordination.
- Transplantation:Allogeneic donor leukocyte collection for graft manipulation prioritizes volume throughput over subset specificity.
- Regenerative Medicine:Mesenchymal stromal cell and dendritic cell therapies drive demand for flexible collection platforms supporting diverse starting material specifications.
Revenue scale favors oncology; regulatory complexity expansion favors regenerative medicine.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where CAR-T manufacturing density commands premium equipment placement, while European markets face margin compression from extended EU MDR conformity timelines and fragmented procurement.
United States
Academic medical centers in Boston and San Francisco anchor procurement volumes through integrated apheresis-to-manufacturing workflows for autologous cell therapies. FDA's evolving cell and gene therapy guidance accelerates capital investment in validated collection platforms by contract development organizations seeking pre-approval inspection readiness. Metropolitan hospital clusters with multiple concurrent cell therapy trials create competing demands on shared apheresis suite capacity.
Germany
CAR-T developers in Munich and Heidelberg adopt continuous flow centrifugation platforms at replacement cycles of 18-24 months, compressing collection-to-manufacturing timelines. EMA's ATMP framework revisions tighten starting material traceability requirements, embedding electronic batch records directly into collection software. European contract manufacturers consolidate procurement around platforms with pre-validated GMP compliance modules rather than retrofitting legacy equipment.
India
Emerging local cell therapy manufacturing infrastructure creates first-mover positioning for automated collection platform deployment in academic hospital networks. CDSCO pathway acceleration supports device registration timelines shorter than European notified body assessments. Hyderabad and Bangalore clusters attract leasing-plus-consumable bundling models that reduce capital barriers for mid-tier contract research organizations.
Japan
PMDA's alignment with FDA cell therapy guidance streamlines dual-market registration for automated leukapheresis systems. Tokyo and Osaka academic medical centers prioritize membrane filtration throughput for standard mononuclear cell harvesting from volunteer donors. Domestic manufacturers face pressure from European and American platform integrators establishing direct service operations.
Switzerland
Swissmedic's streamlined ATMP oversight attracts cell therapy developers seeking regulatory efficiency for early-phase trials. Basel and Zurich pharmaceutical clusters drive demand for closed-system automation with real-time cell quality monitoring integrated with downstream bioprocessing software. Contract manufacturers negotiate unbundled service contracts separating equipment acquisition from standalone validation support packages.
Leukapheresis Products Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in consumables and separation media. The vendor base concentrates around three to five established centrifugation and magnetic separation technology holders, with mid-tier Asian manufacturers pressuring standard equipment pricing. Two strategic archetypes dominate: diversified medical technology conglomerates leveraging service infrastructure for bundled placement, and pure-play cell therapy specialists commanding premium positioning through immunoaffinity workflows. Competitive moves center on asset-light leasing models and captive manufacturing of proprietary disposables.
Among diversified platform integrators, Fresenius Kabi and Haemonetics Corporation exemplify the conglomerate archetype through dialysis service infrastructure and captive disposable manufacturing respectively. Miltenyi Biotec occupies a specialist position representing magnetic separation workflow expertise. These three anchors demonstrate how competitive positioning splits between scale-driven equipment bundling and premium technology differentiation.
| Leading Market Players |
|---|
| Terumo BCT |
| Fresenius Kabi |
| Haemonetics Corporation |
| Asahi Kasei Medical |
| Macopharma |
| Miltenyi Biotec |
| Nikkiso Co., Ltd. |
| Baxter International |
| Lonza Group |
| Others |
Value Chain & Pricing Dynamics
German and Swiss precision-manufacturing clusters for centrifugation hardware concentrate upstream supply, directing margin capture toward integrated platform providers that bundle consumable contracts with equipment placement. This concentration rewards vendors with captive disposable manufacturing while compressing standalone component suppliers into price-taker positions.
Pricing Analysis
Configured-to-order pricing for GMP-validated automated systems commands a 40-60% premium over standard clinical collection platforms, with the spread widening where FDA cell therapy guidance mandates embedded electronic batch records and chain-of-identity documentation. Three-tier pricing structure across premium, standard, and economy levels segments buyers by validation depth, with academic medical centers in the United States showing lowest price sensitivity due to grant-funded procurement and CAR-T trial timelines. Cost compression in the mid-tier manual device segment is intensifying because Asian manufacturers are entering with membrane filtration systems at disruptive price points. Contract research organizations represent the most price-sensitive buyer archetype, driving leasing-plus-consumable bundling negotiations.
Supply Chain Analysis
Contract manufacturing for precision centrifugation bowls and separation chambers concentrates with specialized metal-forming foundries in Germany, Switzerland, and Japan, with secondary capacity emerging in South Korea for electronic control modules. Final assembly draws from these three supply nodes, with proprietary disposable tubing sets sourced from captive extrusion facilities or qualified polymer converters in the United States and Ireland. Single-source vulnerability runs through German precision-machining houses for high-speed rotor components, where multi-year qualification timelines lock buyers into incumbent relationships. Distribution runs through direct field service organizations for automated systems, with consumables flowing through regional medical device distributors holding GMP warehousing certifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The leukapheresis products market is recovering from a cyclical trough as CAR-T manufacturing capacity buildouts restart following FDA guidance clarity and biotech funding stabilization. This recovery phase favors vendors with pre-validated GMP platforms and punishes those dependent on discretionary research capital.
For Market Incumbents: Pre-empt Asian manufacturer encroachment by accelerating backward integration into proprietary consumable resin formulations that extend switching costs beyond hardware lock-in. Consolidate service contract bundling to capture recurring revenue as academic medical centers unbundle validation support, while investing in CDSCO pre-certification for India market entry before local competitors establish GMP facility relationships.
For New Entrants and Emerging Players: Establish a beachhead in the India CDSCO pathway for automated collection platforms, where regulatory acceleration and leasing appetite create first-mover positioning ahead of European and American incumbents. Target mid-tier contract research organizations in Hyderabad and Bangalore with asset-light equipment placement models, using consumable throughput commitments to secure initial facility access and operator training dependencies.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturers that consolidated European apheresis service capabilities during the 2020-2022 cell therapy boom and now face refinancing pressure. Long-term viability hinges on GMP traceability mandate compliance rather than equipment throughput alone. Watch FDA pre-approval inspection scheduling rates as the inflection signal; acceleration indicates renewed capital deployment by CDMOs seeking validated platform procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| GMP Validation Module Development | EMA's ATMP framework revisions embed electronic batch records directly into collection software, mandating platform upgrades. |
| Leasing-Plus-Consumable Bundling | Asset-light models reduce capital barriers for India-based contract research organizations entering cell therapy support services. |
| CDSCO Pre-Certification Investment | Accelerated Indian regulatory timelines enable first-mover positioning in emerging academic hospital networks. |
| Operator Training Program Expansion | Apheresis technician shortages constrain facility throughput, creating service revenue streams independent of equipment sales. |
| Legacy LIS Integration Partnership | FDA donor tracking rules require automated data capture, opening software companion development opportunities with hospital IT vendors. |
Study Parameters
Operator-level perspectives from apheresis technicians, GMP facility managers, biomedical engineers at academic medical centers, and procurement leads at contract development organizations anchored the qualitative base. These primary interviews combined with secondary validation from FDA 510(k) and PMA filing databases, EMA ATMP framework revision documents, hospital GPO contract repositories, and CDSCO device registration records. Bottom-up procedure volume modeling and top-down equipment installed base estimates were triangulated against consumable shipment data.
Scenario-bracketing framed the analytical approach across the analysis window, with base, upside, and downside cases reflecting CAR-T clinical trial advancement rates and CDMO capital commitment timelines. Segmentation dimensions modeled included product type (automated systems, consumables, manual devices, accessories), end user (hospitals, blood banks, research institutions, clinics), technology (centrifugation, immunoaffinity, membrane filtration, magnetic separation), and application (oncology, hematology, transplantation, regenerative medicine). CAGRs were derived from procedure volume growth tied to cell therapy manufacturing expansion, cross-referenced against equipment replacement cycle data from United States and German academic medical centers.
Macroeconomic conditions sit as an overlay; deviation in biotech venture funding availability, FDA inspection resource allocation, or EU MDR notified body capacity would shift the trajectory. Forecasts reflect assumptions regarding CAR-T commercial manufacturing scale-up timelines and GMP starting material traceability mandate implementation schedules. Quarterly review of CDMO capital expenditure announcements and FDA pre-approval inspection completion rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
EMEA Cancer Biological Therapy Market
Cell & Gene Therapy
Regenerative Medicine Market
Cell & Gene Therapy
Global Lentiviral Vectors Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Therapeutics Market
Cell & Gene Therapy
Europe Cancer Vaccines Market
Cell & Gene Therapy
Cell and Gene Therapy Clinical Trials Market
Cell & Gene Therapy
Oncolytic Virus Therapy Market
Cell & Gene Therapy
Viral Vector Development Market
Cell & Gene Therapy
Gene Electroporators Market
Cell & Gene Therapy
Middle East and Africa Cancer Vaccines Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Treatment Market
Cell & Gene Therapy
Global Dendritic Cell Cancer Vaccines Market
Cell & Gene Therapy
Cellular Immunotherapy Market
Cell & Gene Therapy
Asia Pacific Cancer Biological Therapy Market
Cell & Gene Therapy
Middle East and Africa Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Cell Expansion Market