
 Global Mrna Therapeutics Market | 2026-2036
Global Mrna Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mrna Therapeutics Market Foresight
Lipid nanoparticles are decoupling mRNA therapeutics from cold-chain dependency, slashing distribution costs and expanding addressable patient populations. Moderna leverages integrated manufacturing campuses to control quality from plasmid to finished dose. BioNTech anchors its competitive position through oncology pipeline depth and personalized cancer vaccine platforms. Pfizer sustains scale advantages via commercial infrastructure that reaches hospital systems across dozens of countries.
mRNA therapeutics comprise synthetic nucleic acid sequences encoding functional proteins, manufactured through in vitro transcription using DNA templates, T7 RNA polymerase, and modified nucleosides to evade innate immune detection, with primary purpose of directing patient cells to produce therapeutic antigens or functional proteins for disease treatment or prevention. Non-replicating mRNA dominates current revenue owing to established COVID-19 franchise familiarity and simpler regulatory precedent, while self-amplifying mRNA represents the fastest-expanding technology platform due to dose-sparing potential and lower manufacturing burden per immunized individual. Lipid nanoparticle delivery technology concentrates margin pools through proprietary ionizable lipid composition patents that gate market access for follow-on developers.
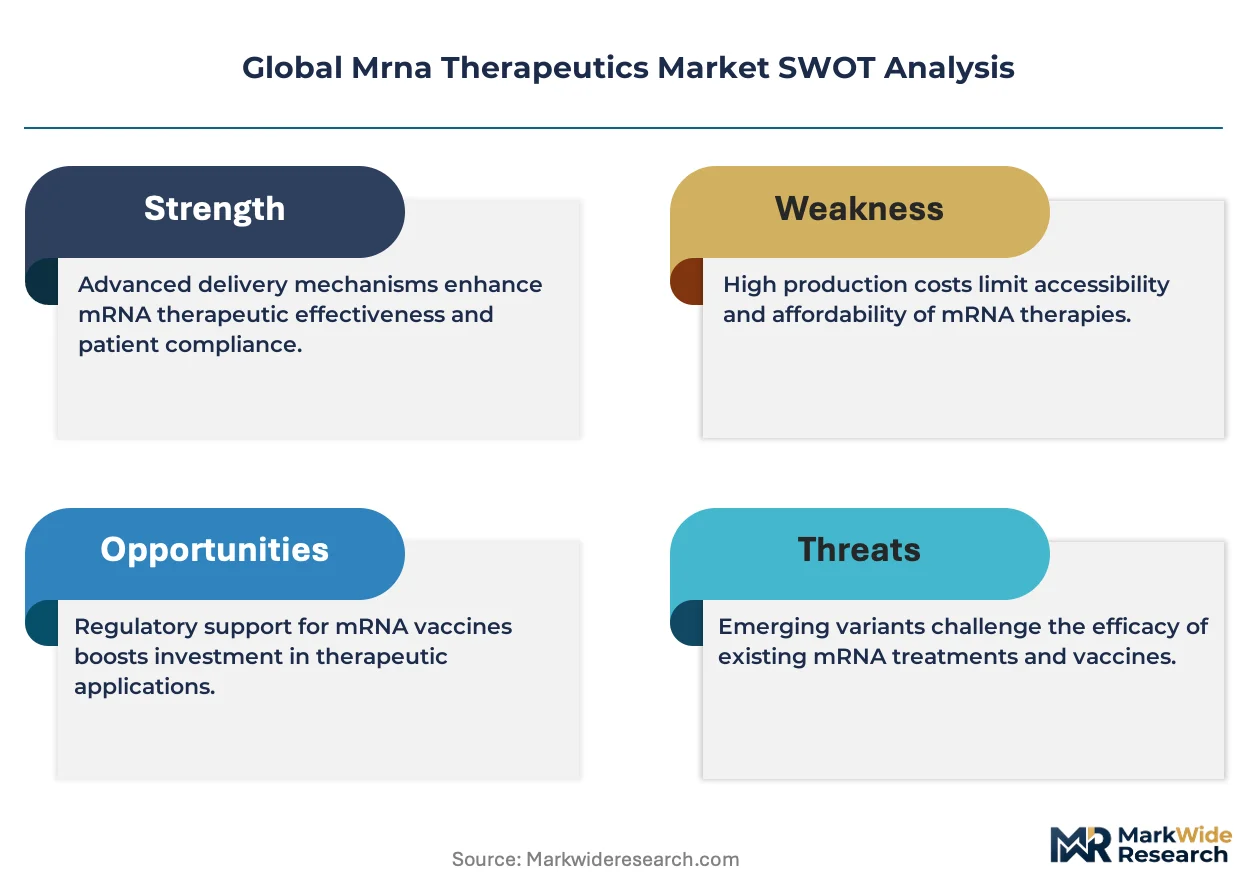
FDA, EMA, and WHO collectively shape mRNA therapeutic standards through chemistry-manufacturing-controls requirements, pharmacovigilance protocols, and pandemic preparedness frameworks that dictate clinical trial design and post-market surveillance obligations. The EU AI Act and FDA guidance on artificial intelligence in drug development are introducing algorithm-validation requirements for sequence-optimization software used in candidate design. Stakeholders must monitor regulatory divergence between jurisdictions on acceptable nucleoside modification profiles, as this determines which platform technologies qualify for accelerated review pathways and which require extended safety databases.
Market Dynamics
Lipid nanoparticle delivery patents are consolidating manufacturing control among holders of ionizable lipid compositions, compressing margins for developers lacking proprietary formulation rights and reshaping competitive entry economics across therapeutic categories.
Growth Catalysts
- FDA Accelerated Approval:Compressed development timelines for oncology mRNA candidates reduce capital-at-risk duration and attract biotechnology investment into personalized cancer vaccines.
- EMA Adaptive Licensing:Staged evidence generation permits earlier patient access while building post-market safety databases, lowering regulatory uncertainty for novel nucleoside modifications.
- Shanghai Manufacturing Clusters:Dense contract manufacturing organization concentration around Zhangjiang Hi-Tech Park reduces plasmid-to-dose production friction for Asia-Pacific commercialization.
Market Restraints
- Cold-Chain Infrastructure Gaps:Ultra-low temperature storage requirements exclude distribution to rural India and sub-Saharan Africa, limiting addressable populations for non-LNP formulations.
- Single-Source Lipid Supply:Proprietary ionizable lipid production concentrates with three specialized chemical manufacturers, creating input bottlenecks during demand surges.
- Innate Immunogenicity Barriers:Unmodified uridine residues trigger TLR7/8 detection, complicating repeat-dosing regimens for chronic disease applications.
Strategic Opportunities
- Brazil Expansion:ANVISA's streamlined biologics pathway and underdeveloped oncology infrastructure create first-mover positioning for metastatic melanoma mRNA vaccines.
- Self-Amplifying RNA Convergence:Integration with replicon technology from alphavirus-derived platforms enables dose-sparing manufacturing economics for seasonal respiratory prophylaxis.
- Direct-to-Hospital Distribution:Bypassing wholesale intermediaries through integrated delivery partnerships with German hospital networks captures margin otherwise lost to channel markups.
Industry Challenges
- RNA Chemist Talent Scarcity:PhD-level expertise in modified nucleoside synthesis and IVT process development concentrates within Boston and Mainz employment pools, constraining scale-up velocity.
- Multi-Site CMC Harmonization:FDA chemistry-manufacturing-controls requirements for plasmid, mRNA, and LNP production across geographically separated facilities complicate quality system integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mrna Therapeutics Market |
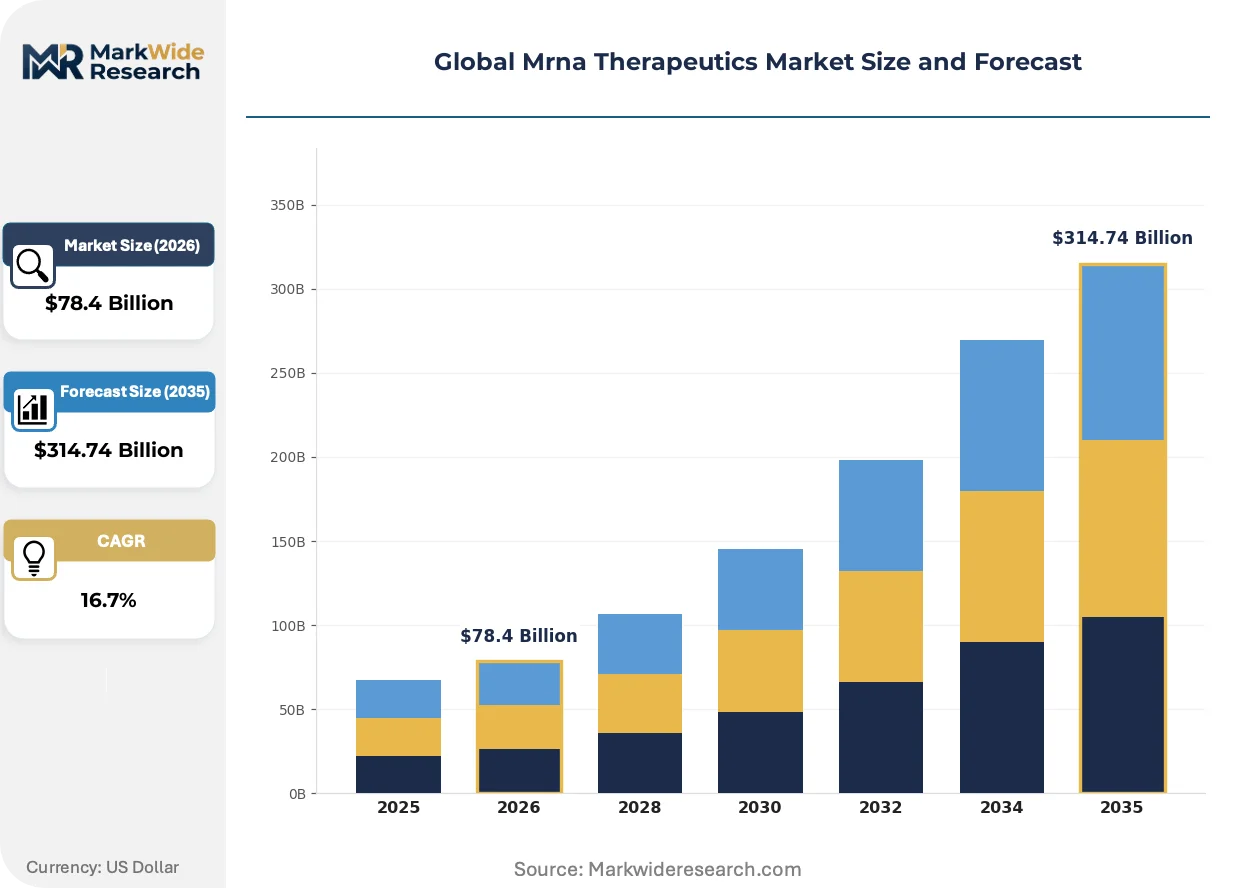
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $314.74 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Amplifying mRNA, Non-Replicating mRNA, Modified mRNA, Unmodified mRNA Therapy Area: Infectious Diseases, Oncology, Cardiovascular Diseases, Rare Genetic Disorders Delivery Technology: Lipid Nanoparticles, Cationic Polymers, Viral Vectors, Exosomes End User: Research Institutes, Contract Development Organizations, Academic Laboratories, Biotechnology Firms |
| Companies Covered | Moderna, BioNTech, Pfizer, CureVac, Arcturus Therapeutics, GSK, Sanofi, AstraZeneca, Translate Bio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mrna Therapeutics Market Shifts & Advancements
Automation of sequence optimization and in vitro transcription monitoring is compressing candidate-to-IND timelines while regulatory frameworks adapt to algorithm-validated drug design methodologies.
Machine learning platforms trained on codon usage bias and secondary structure prediction are automating mRNA sequence engineering that previously required months of iterative laboratory refinement. Contract development organizations in Cambridge and San Diego deploy these tools to reduce lead optimization cycles by half for infectious disease prophylaxis programs. The compression of design timelines is automating portfolio expansion strategies that previously demanded proportional headcount increases.
The EU AI Act's risk-classification framework for medical device software is imposing validation documentation requirements on sequence-optimization algorithms used in candidate selection. Developers must now maintain algorithmic audit trails and performance benchmarking against reference datasets to satisfy notified body scrutiny. German biotechnology firms are responding by establishing dedicated AI quality assurance functions that interface directly with regulatory affairs teams.
Hospital procurement committees are consolidating mRNA therapeutic purchasing through centralized pharmacy and therapeutics committees rather than individual physician preference. This shift concentrates contract negotiation leverage with integrated delivery networks in the United States and NHS trusts in the United Kingdom. Oncology departments within these systems now prioritize formulary placement based on total cost-of-care impact rather than per-dose acquisition cost alone.
Global Mrna Therapeutics Market Segmentation
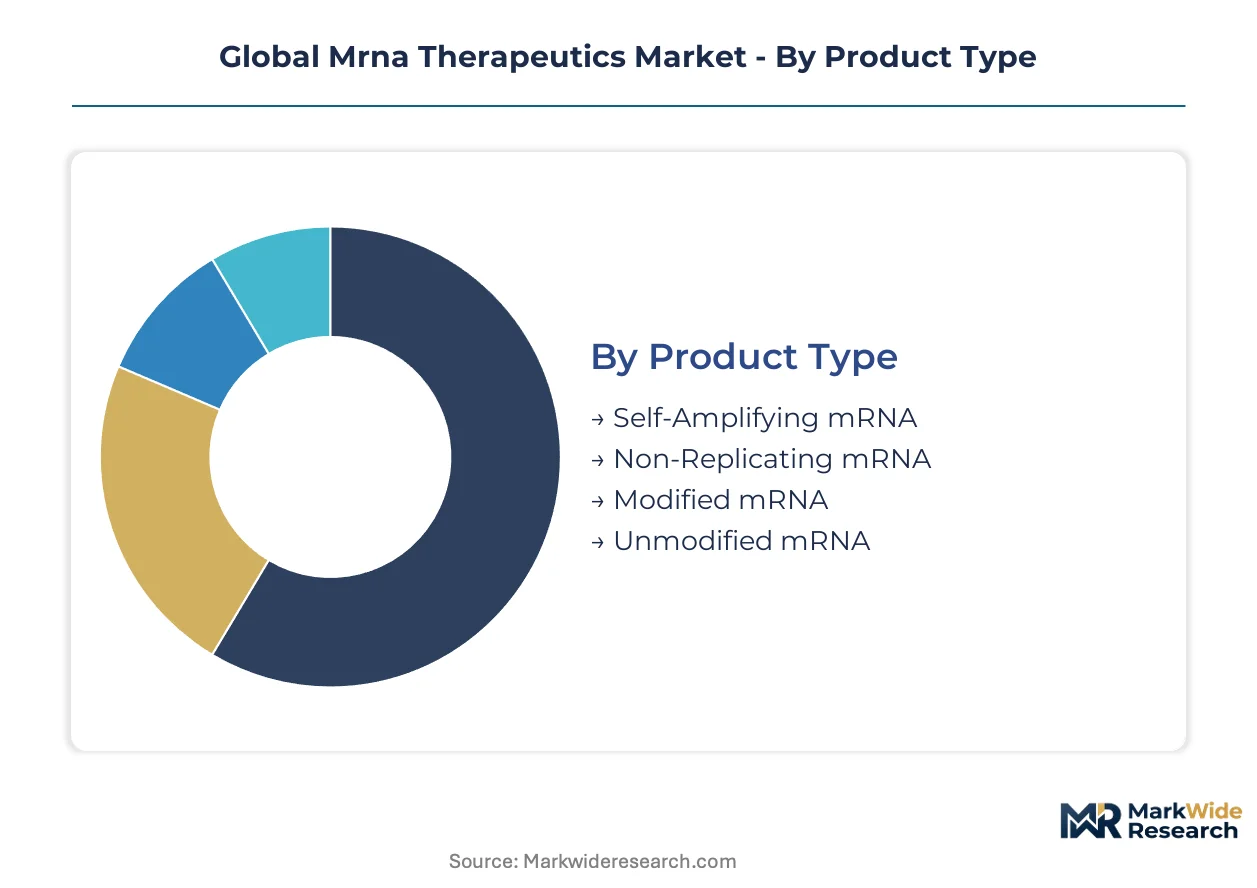
mRNA therapeutics segment across multiple dimensions that determine manufacturing complexity, regulatory pathway, and commercial addressability. Each category reflects distinct technical trade-offs between platform maturity and therapeutic versatility.
Product Type:
Standardization dominates early-phase development while customization intensifies for chronic disease applications requiring repeat dosing optimization.
- Self-Amplifying mRNA:Engineered with viral replicon elements that enable intracellular amplification of the therapeutic transcript, reducing required dose volumes by an order of magnitude. Demand concentrates in German manufacturing clusters where BioNTech and CureVac optimize alphavirus-derived platforms for seasonal respiratory prophylaxis. The dose-sparing economics attract CDMO investment for pandemic preparedness stockpiling.
- Non-Replicating mRNA:Synthetic transcripts lacking self-amplification machinery, manufactured through conventional in vitro transcription with modified nucleosides. United States hospital procurement committees prioritize this modality for oncology vaccines given established FDA chemistry-manufacturing-controls precedents from COVID-19 franchise familiarity.
- Modified mRNA:Incorporates pseudouridine or N1-methyl-pseudouridine substitutions to dampen TLR-mediated innate immune recognition. Enables repeat administration for chronic cardiovascular indications.
- Unmodified mRNA:Retains native uridine composition with simpler manufacturing workflows but restricted to single-dose applications due to immunogenicity barriers.
Most installed capacity flows through Non-Replicating mRNA. Expansion is steepest in Self-Amplifying mRNA.
Therapy Area:
Margin structure varies sharply across acute infectious intervention versus multi-year oncology development timelines.
- Oncology:Personalized cancer vaccines encoding patient-specific neoantigens, manufactured through rapid turnaround from tumor sequencing to GMP release. United States biotechnology firms anchor demand in Boston and San Diego clusters where integrated manufacturing campuses compress plasmid-to-dose timelines. The FDA's accelerated approval pathway for breakthrough-designated candidates reduces capital-at-risk duration.
- Infectious Diseases:Prophylactic vaccines against respiratory pathogens utilizing conserved antigen designs. Chinese manufacturing infrastructure around Shanghai Zhangjiang Hi-Tech Park supports regional commercialization for COVID-19 and influenza programs.
- Cardiovascular Diseases:Encodes angiogenic growth factors or gene-editing constructs for ischemic tissue repair. Faces extended safety database requirements for repeat dosing.
- Rare Genetic Disorders:Enzyme replacement or gene-correction applications in ultra-small populations. EMA adaptive licensing frameworks permit staged evidence generation for earlier patient access.
Revenue concentration sits with Oncology. Volume expansion is climbing the fastest in Infectious Diseases.
Delivery Technology:
Proprietary formulation rights determine competitive entry economics across all therapeutic categories.
- Lipid Nanoparticles:Ionizable lipid compositions encapsulating mRNA for cytosolic delivery, with pH-dependent membrane fusion properties. Three specialized chemical manufacturers concentrate proprietary ionizable lipid production, creating input bottlenecks during demand surges. German and United States patent holders gate market access for follow-on developers.
- Cationic Polymers:Synthetic polycations complexing nucleic acid through electrostatic interaction, offering simpler manufacturing but reduced transfection efficiency compared to LNP systems.
- Viral Vectors:Engineered adenovirus or lentivirus particles delivering mRNA through receptor-mediated entry. Faces pre-existing immunity limitations in repeat dosing.
- Exosomes:Endogenous extracellular vesicles enabling tissue-targeted delivery without synthetic lipid components. Early-stage development in academic laboratories.
Margin pools concentrate in Lipid Nanoparticles. Technical development is advancing most quickly in Exosomes.
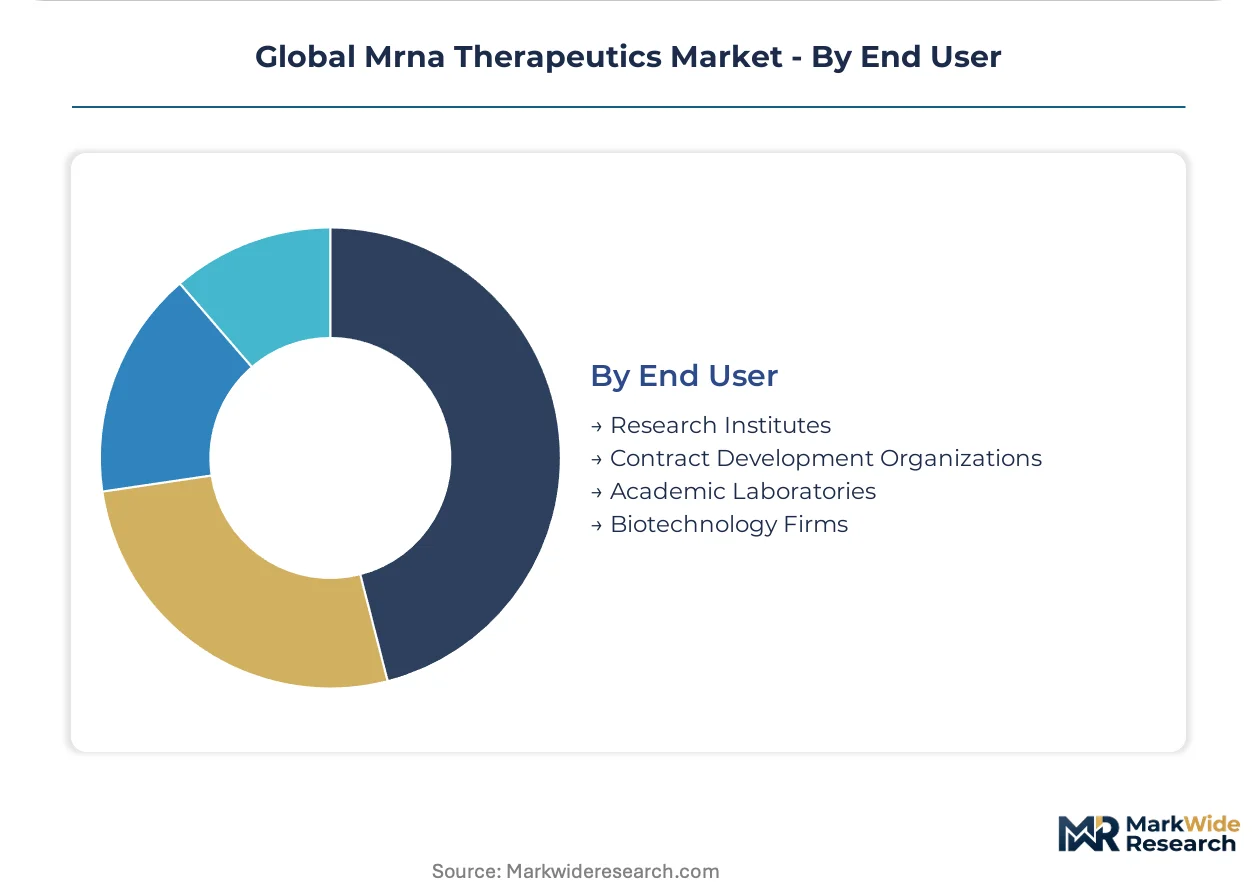
End User:
Procurement sophistication separates integrated manufacturing operations from outsourced development services.
- Biotechnology Firms:Vertically integrated developers controlling plasmid, mRNA, and formulation production through captive manufacturing campuses. Moderna's Norwood facility exemplifies this model with quality control from DNA template to finished dose.
- Contract Development Organizations:Specialized service providers offering GMP manufacturing capacity for developers lacking in-house infrastructure. Cambridge and San Diego clusters deploy machine learning platforms to compress sequence optimization cycles.
- Research Institutes:Early-phase discovery operations utilizing non-GMP material for proof-of-concept studies.
- Academic Laboratories:Investigator-initiated programs exploring novel delivery modalities or disease applications with limited commercial scale.
Capital deployment is heaviest among Biotechnology Firms. Outsourced volume is expanding most rapidly through Contract Development Organizations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors the dominant manufacturing cluster where integrated campuses compress plasmid-to-dose timelines. German and Chinese infrastructure follows with specialized lipid production and regional commercialization capacity.
United States
FDA accelerated approval pathways and hospital procurement consolidation drive biotechnology investment into personalized cancer vaccines. The FDA's chemistry-manufacturing-controls requirements for multi-site production shape quality system design. Greater Boston and San Diego clusters concentrate CDMO capacity with machine learning-enabled sequence optimization platforms.
Germany
EMA adaptive licensing frameworks and oncology pipeline depth attract manufacturing investment for dose-sparing self-amplifying platforms. The EU AI Act imposes algorithm-validation requirements on sequence-optimization software used in candidate design. Mainz anchors production gravity with integrated manufacturing campuses and specialized ionizable lipid supply relationships.
China
NMPA regulatory frameworks and pandemic preparedness stockpiling expand infectious disease prophylaxis manufacturing. Shanghai's Zhangjiang Hi-Tech Park concentrates contract manufacturing organization density for Asia-Pacific commercialization. Local CDMOs deploy automated in vitro transcription monitoring to compress candidate-to-IND timelines.
United Kingdom
NHS trust procurement consolidation shifts formulary placement decisions toward total cost-of-care impact metrics. MHRA alignment with EMA pharmacovigilance protocols simplifies post-market surveillance obligations. London and Cambridge clusters house early-stage discovery operations utilizing non-GMP material for proof-of-concept studies.
Brazil
ANVISA streamlined biologics pathways and underdeveloped oncology infrastructure create positioning opportunities for metastatic melanoma applications. National immunization program expansion drives demand for respiratory prophylaxis with reduced cold-chain dependency. São Paulo and Rio de Janeiro clusters concentrate hospital network purchasing consolidation for imported therapeutic access.
Global Mrna Therapeutics Market Competitive Landscape
Patent licensing dominates the current landscape as ionizable lipid composition holders gate market access for follow-on developers. The vendor base concentrates around three specialized chemical manufacturers controlling proprietary input supply, with biotechnology firms and pharmaceutical majors occupying distinct competitive tiers. Strategic archetypes include vertically integrated developers with captive manufacturing, platform-technology licensors extracting royalty streams, and scale-driven commercializers leveraging existing hospital system relationships. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with algorithm-validation capabilities emerging as a differentiation vector under EU AI Act compliance requirements.
Within the integrated developer tier, Moderna and BioNTech exemplify vertical control from plasmid production through finished dose release, while Pfizer occupies a position leveraging commercial infrastructure that reaches hospital systems across dozens of countries. These three anchors represent contrasting strategic postures: manufacturing-centric quality control, oncology pipeline depth with personalized vaccine platforms, and scale-driven distribution reach respectively.
| Leading Market Players |
|---|
| Moderna |
| BioNTech |
| Pfizer |
| CureVac |
| Arcturus Therapeutics |
| GSK |
| Sanofi |
| AstraZeneca |
| Translate Bio |
| Others |
Supply & Pricing Matrix
Captive manufacturing campuses in Boston and Mainz anchor supply positions for integrated biotechnology developers while concentrating pricing power through in-house control of plasmid-to-dose production. This backward integration into critical inputs insulates incumbents from ionizable lipid supply bottlenecks and compresses cost structures that outsourced competitors cannot match.
Pricing Analysis
Input-cost pass-through from proprietary ionizable lipid suppliers intensifies pricing pressure across non-integrated developers lacking formulation rights. Three-tier pricing structure across premium, standard, and economy levels separates GMP-grade clinical materials from research-use reagents and commercial finished doses. Price differentiation hinges on regulatory certification tier and volume scale, with hospital procurement committees in the United States and NHS trusts in the United Kingdom exhibiting divergent sensitivity—integrated delivery networks prioritize total cost-of-care impact while emerging market buyers face acute price elasticity for cold-chain-dependent formulations.
Supply Chain Analysis
Single-source vulnerability sits with German and United States patent holders of ionizable lipid compositions, concentrating critical input access among three specialized chemical manufacturers. Manufacturing draws from plasmid DNA templates, modified nucleoside substrates, and synthetic lipid stocks sourced primarily from China, Germany, and the United States. Tariff exposure on Chinese-sourced nucleoside precursors compounds logistics chokepoints at ultra-low temperature distribution nodes. Distribution runs through direct-to-hospital partnerships in Germany and wholesale intermediaries in broader European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in mRNA therapeutics rests on dose-sparing self-amplifying platforms and algorithm-validated sequence optimization compressing development timelines. Lipid nanoparticle formulation rights and AI quality assurance capabilities constitute the premium-tier shift enabling sustainable margin capture.
For Market Incumbents: Acquire specialized ionizable lipid formulation patents to consolidate manufacturing control against emerging CDMO competitors. Build FDA chemistry-manufacturing-controls harmonization capabilities across multi-site production to preempt regulatory scrutiny. Defend against self-amplifying RNA platform displacement by accelerating oncology pipeline depth in personalized cancer vaccines. For New Entrants and Emerging Players: Capture ANVISA streamlined biologics pathway positioning in Brazil's underdeveloped oncology infrastructure before incumbent formulary lock-in. Target exosome delivery technology white space where academic laboratory innovation outpaces commercial development. Pursue direct-to-hospital distribution partnerships with German hospital networks to bypass wholesale margin extraction. For Investors and Strategic Acquirers: Roll-up economics work for contract development organizations with machine learning-enabled sequence optimization platforms because algorithm-validation capabilities under EU AI Act compliance requirements create scarce, defensible assets. Five-to-ten year viability hinges on CDMOs capturing pandemic preparedness stockpiling contracts and seasonal respiratory prophylaxis manufacturing. Watch FDA nucleoside modification guidance divergence from EMA adaptive licensing frameworks as the signal indicating which platform technologies qualify for accelerated review pathways versus extended safety database requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm-Validation Investment | EU AI Act compliance requirements impose documentation burdens that gate market access for sequence-optimization software vendors. |
| Self-Amplifying RNA Platform Licensing | Alphavirus-derived replicon technology enables dose-sparing manufacturing economics attractive to pandemic preparedness stockpilers. |
| Direct-to-Hospital Distribution Partnerships | German hospital network integration captures margin otherwise lost to wholesale channel markups in European commercialization. |
| Ionizable Lipid Patent Acquisition | Proprietary formulation rights consolidate manufacturing control and compress competitive entry economics for follow-on developers. |
| Multi-Site CMC Harmonization | FDA chemistry-manufacturing-controls requirements for geographically separated facilities demand integrated quality system architecture. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down revenue triangulation anchored market size estimation across the analysis window.
Segment-weighting approaches distributed value and volume across product type, therapy area, delivery technology, and end user dimensions, with regional regulatory clusters and manufacturing infrastructure concentration treated as cross-cutting analytical layers. CAGRs derived from patent expiry timelines, pipeline progression rates, and capacity expansion announcements rather than extrapolation. Forecast inputs incorporated nucleoside modification regulatory divergence and lipid nanoparticle patent landscape evolution as scenario variables.
Regulatory framework shifts, manufacturing input supply disruptions, and algorithm-validation standardization delays are the dominant revision risks to projection assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Asia-Pacific Stem Cell Therapy Market
Cell & Gene Therapy
Induced Pluripotent Stem Cells Production Market
Cell & Gene Therapy
Hemophilia Treatment Market
Cell & Gene Therapy
Regenerative Medicine Market
Cell & Gene Therapy
Viral Vector Purification Market
Cell & Gene Therapy
Progressive Familial Intrahepatic Cholestasis Type 2 Treatment Market
Cell & Gene Therapy
Adipose Derived Stem Cell Therapy Market
Cell & Gene Therapy
Stem Cell Manufacturing Market
Cell & Gene Therapy
Global Tissue Regeneration Market
Cell & Gene Therapy
Oncolytic Adenovirus Market
Cell & Gene Therapy
Cancer Therapeutics Market
Cell & Gene Therapy
North America Cancer Vaccines Market
Cell & Gene Therapy
Cell Reprogramming Market
Cell & Gene Therapy
North America Stem Cell Market
Cell & Gene Therapy
RNA Based Therapeutics and Vaccines Market
Cell & Gene Therapy
Global Viral Vector and Plasmid DNA Manufacturing Market