
 Oncolytic Virus Therapy Market | 2026-2036
Oncolytic Virus Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Oncolytic Virus Therapy Market Intelligence
Modified herpes simplex virus vectors are restructuring cost structures across the oncolytic virus therapy landscape as engineered viral backbones replace earlier wild-type platforms with improved tumor selectivity and reduced manufacturing complexity. Amgen leverages its established T-VEC infrastructure to sustain commercial distribution across major oncology centers. Oncolytics Biotech specializes in pelareorep combinations for metastatic breast cancer, competing through distinct mechanism-of-action positioning against checkpoint inhibitor monotherapy.
Oncolytic virus therapy employs genetically modified viruses that selectively infect and lyse tumor cells while stimulating systemic anti-tumor immunity through pathogen-associated molecular pattern recognition and dendritic cell activation; these agents require cold-chain distribution at minus eighty degrees Celsius and multi-step purification to remove replication-competent contaminants before patient administration. Intravenous delivery modes are capturing expanded protocol inclusion as vascular administration enables systemic metastatic targeting beyond localized intralesional injection limits. The melanoma indication anchors near-term revenue pools given mature reimbursement pathways, while glioblastoma represents the fastest-expanding clinical development segment driven by blood-brain barrier penetration challenges that viral platforms address through natural neurotropism.
FDA breakthrough therapy designation and EMA priority medicines eligibility are compressing regulatory review timelines for novel oncolytic constructs, while the EU AI Act introduces algorithmic disclosure requirements for AI-driven patient selection tools used in combination trial enrollment. Health Canada and the FDA maintain divergent standards for replication-competent virus environmental release protocols, creating compliance complexity for multi-regional sponsors. Stakeholders must monitor evolving manufacturing consistency standards as regulators tighten potency assay requirements for live biotherapeutic products.
Market Dynamics
The FDA's accelerated approval pathways for breakthrough therapies are compressing development timelines for novel viral platforms, while cold-chain distribution requirements at minus eighty degrees Celsius are restructuring logistics partnerships across the value chain.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The FDA's accelerated review pathway compresses clinical development timelines for novel oncolytic constructs, enabling faster patient access to viral platforms targeting melanoma and glioblastoma.
- Checkpoint Inhibitor Combinations:Cancer hospitals are expanding adoptive cell therapy programs that incorporate oncolytic viruses as combination agents, creating protocol demand beyond monotherapy applications.
- Intravenous Delivery Modes:Vascular administration protocols are capturing expanded clinical trial inclusion, enabling systemic metastatic targeting that transcends localized intralesional injection limits.
Market Restraints
- Replication-Competent Contaminant Removal:Multi-step purification processes to eliminate replication-competent contaminants before patient administration impose manufacturing complexity and batch failure risk.
- Divergent Environmental Release Standards:Health Canada and the FDA maintain incompatible protocols for replication-competent virus environmental release, creating compliance burden for multi-regional sponsors.
- Minus Eighty Cold-Chain Dependency:Live biotherapeutic products require uninterrupted ultra-low temperature distribution infrastructure, limiting site activation to specialized oncology centers with validated storage capacity.
Strategic Opportunities
- Glioblastoma Indication Expansion:Blood-brain barrier penetration challenges that viral platforms address through natural neurotropism position this indication as the fastest-expanding clinical development segment.
- EMA Priority Medicines Eligibility:European regulatory acceleration for innovative therapies creates parallel pathway access for sponsors seeking simultaneous US-EU market entry.
- AI-Driven Patient Selection Tools:Algorithmic enrollment optimization for combination trials presents white space, though the EU AI Act introduces disclosure requirements for such applications.
Industry Challenges
- Potency Assay Standardization:Regulators are tightening manufacturing consistency standards for live biotherapeutic products, forcing sponsors to revalidate release criteria mid-development.
- Dendritic Cell Activation Expertise:Pathogen-associated molecular pattern recognition mechanisms require specialized immunology talent scarce in conventional oncology manufacturing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oncolytic Virus Therapy Market |
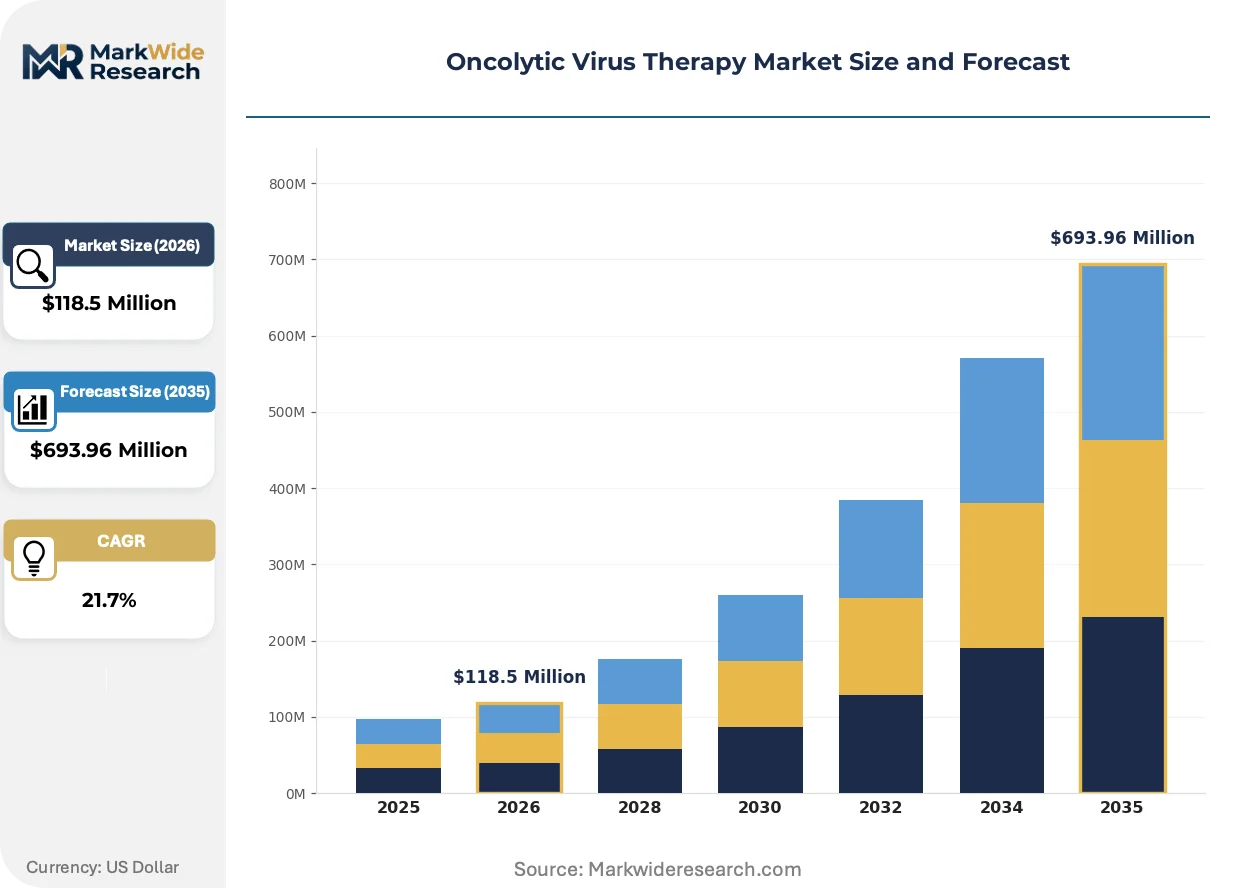
| Market Size in 2026 | $118.5 Million |
| Market Size in 2035 | $693.96 Million |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Talimogene Laherparepvec, Pexa-Vec, CG0070, ONYX-015 Delivery Mode: Intravenous, Intratumoral, Oral, Intra-arterial End User: Hospitals, Research Institutes, Specialized Clinics, Pharmaceutical Companies Indication: Melanoma, Glioblastoma, Pancreatic Cancer, Ovarian Cancer |
| Companies Covered | Amgen, Oncolytics Biotech, Candel Therapeutics, Genelux Corporation, CG Oncology, Transgene SA, SillaJen, Targovax, Lokon Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oncolytic Virus Therapy Market Strategic Shifts & Innovations
Engineered viral backbones are displacing wild-type platforms across the oncolytic landscape, with tumor selectivity improvements and reduced manufacturing complexity driving protocol redesign at major academic medical centers.
Modified herpes simplex virus vectors are rewriting cost structures across the oncolytic virus therapy landscape. Engineered viral backbones replace earlier wild-type platforms with improved tumor selectivity and reduced manufacturing complexity. Amgen leverages this infrastructure to sustain commercial distribution across major oncology centers. The structural consequence is a compression of per-dose production costs while expanding addressable patient populations beyond localized lesion accessibility.
EMA priority medicines eligibility is compressing regulatory review timelines for novel oncolytic constructs. The European framework accelerates assessment for therapies addressing unmet medical need in oncology indications. Sponsors targeting melanoma and glioblastoma are prioritizing parallel EMA submissions to exploit this pathway. The EU AI Act simultaneously introduces algorithmic disclosure requirements for AI-driven patient selection tools used in combination trial enrollment.
Academic medical centers in Boston, Houston, and New York are driving clinical trial enrollment concentration. These institutions command preferred site status through established viral therapy infrastructure and principal investigator density. Community oncology practices face exclusion from early-phase protocols due to cold-chain and biosafety containment requirements. The geographic demand rotation favors established research hubs over distributed care networks for initial commercial uptake.
Oncolytic Virus Therapy Market Segmentation
Oncolytic virus therapy segments diverge sharply by clinical infrastructure requirements and regulatory pathway maturity. Treatment protocols, delivery logistics, and site certification capabilities reshape how sponsors prioritize development investments across viral platforms.
Product Type:
Clinical decision-makers weigh established reimbursement history against novel mechanism differentiation when selecting viral backbones for combination protocols.
- Talimogene Laherparepvec:Modified herpes simplex virus type 1 engineered for GM-CSF expression, administered via intralesional injection into accessible melanoma lesions. Demand concentrates at Amgen's contracted oncology centers across the United States where cold-chain infrastructure and biosafety containment are validated; FDA breakthrough therapy designation underpins commercial traction despite intralesional delivery limitations.
- Pexa-Vec:Vaccinia-based oncolytic virus with dual deletion of thymidine kinase and vaccinia growth factor genes, enabling systemic intravenous administration with reduced host toxicity. Sillajen and Transgene target hepatocellular carcinoma and renal cell carcinoma through this platform; intravenous capability expands addressable patient populations beyond localized lesion accessibility constraints.
- CG0070:Conditionally replicative adenovirus with E2F-1 promoter driving selective replication in Rb pathway-deficient tumor cells, delivered via intravesical instillation for non-muscle invasive bladder cancer. CG Oncology advances this through Phase 3 trials with checkpoint inhibitor combinations.
- ONYX-015:E1B-55K deleted adenovirus with selective replication in p53-deficient tumor cells, historically significant as the first clinically tested oncolytic virus. Oncolytics Biotech and academic collaborators maintain development interest for head and neck cancer indications.
Talimogene Laherparepvec leads on scale through commercial availability; Pexa-Vec leads on momentum through intravenous delivery expansion.
Delivery Mode:
Route of administration determines site activation feasibility and patient eligibility breadth, with vascular protocols commanding premium trial enrollment.
- Intravenous:Systemic vascular delivery enables metastatic targeting beyond localized injection limits, requiring validated cold-chain distribution at minus eighty degrees Celsius and specialized infusion center capabilities. Academic medical centers in Boston, Houston, and New York prioritize intravenous protocols for combination trials with checkpoint inhibitors; vascular administration expands eligible patient populations but demands rigorous replication-competent contaminant removal.
- Intratumoral:Direct lesion injection confines therapy to accessible superficial or image-guided tumors, limiting applicability in deep visceral malignancies. Melanoma and head and neck cancer anchor this delivery mode through established reimbursement pathways; procedural simplicity favors community oncology site participation where biosafety containment is achievable.
- Oral:Enteric delivery of viral platforms remains investigational, with gastrointestinal transit and acid degradation presenting substantial bioavailability challenges. No commercial products currently employ this route.
- Intra-arterial:Regional vascular delivery targets organ-confined malignancies through catheter-directed infusion, applied in hepatocellular carcinoma and pancreatic cancer protocols. Specialized interventional radiology infrastructure restricts site activation to tertiary referral centers.
Intratumoral delivery leads on scale through commercial precedent; intravenous delivery leads on momentum through protocol expansion.
End User:
Site certification requirements and biosafety infrastructure investments stratify access across provider types, concentrating early adoption at research-intensive institutions.
- Hospitals:Comprehensive cancer centers with established viral therapy programs command preferred site status through principal investigator density and validated minus eighty storage capacity. Major academic medical centers drive clinical trial enrollment and early commercial uptake; NCI-designated cancer centers anchor demand concentration in the United States.
- Research Institutes:Academic laboratories and translational research centers advance preclinical viral engineering and early-phase clinical investigation. These institutions generate intellectual property and investigator-sponsored trials that shape platform development priorities.
- Specialized Clinics:Community oncology practices with biosafety containment and cold-chain capabilities participate in later-phase trials and commercial distribution. Site activation lags academic centers due to infrastructure investment requirements.
- Pharmaceutical Companies:Sponsor organizations internalize manufacturing, quality control, and regulatory submission functions. Amgen and emerging biotechs maintain dedicated viral therapy development groups.
Hospitals lead on scale through patient access concentration; research institutes lead on momentum through pipeline generation.
Indication:
Unmet medical need severity and blood-brain barrier penetration challenges redirect viral platform development toward historically refractory malignancies.
- Melanoma:Accessible superficial lesions and established intralesional delivery protocols anchor near-term revenue pools through mature reimbursement pathways. Talimogene Laherparepvec FDA approval validates this indication for oncolytic virus monotherapy; checkpoint inhibitor combination trials expand protocol inclusion across academic medical centers.
- Glioblastoma:Blood-brain barrier penetration challenges that viral platforms address through natural neurotropism position this as the fastest-expanding clinical development segment. Direct intratumoral convection-enhanced delivery and systemic intravenous protocols with tumor-targeted modifications command substantial investigator interest; Phase 2 trials at MD Anderson and Memorial Sloan Kettering drive enrollment concentration.
- Pancreatic Cancer:Desmoplastic stroma and hypoxic tumor microenvironment present delivery barriers that engineered viral backbones attempt to overcome through stroma-degrading modifications. Intra-arterial delivery protocols target locally advanced disease.
- Ovarian Cancer:Intraperitoneal delivery of viral platforms leverages anatomical compartmentalization for peritoneal carcinomatosis targeting. Early-phase trials explore combination with PARP inhibitors and immune checkpoint blockade.
Melanoma leads on scale through commercial availability; glioblastoma leads on momentum through neurotropism exploitation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Major academic medical centers in Boston, Houston, and New York anchor clinical trial enrollment and early commercial uptake for oncolytic virus platforms. The FDA's accelerated approval pathways compress development timelines for novel viral constructs. Cold-chain distribution at minus eighty degrees Celsius concentrates site activation at specialized oncology centers with validated storage infrastructure.
United States
NCI-designated cancer centers in Boston and Houston drive protocol demand for checkpoint inhibitor combinations with oncolytic viruses. The FDA maintains breakthrough therapy designation pathways that accelerate review for melanoma and glioblastoma indications. Memorial Sloan Kettering and MD Anderson anchor enrollment concentration through established viral therapy infrastructure and principal investigator density.
Germany
Heidelberg University Hospital and Charité Berlin command preferred site status for EMA priority medicines eligibility submissions. The German Medicines Act implements accelerated assessment procedures for innovative oncology therapies addressing unmet medical need. The Rhine-Neckar biotechnology cluster concentrates translational research capacity and early-phase clinical investigation for engineered viral backbones.
United Kingdom
The Medicines and Healthcare products Regulatory Agency operates the Innovative Licensing and Access Pathway for promising oncology modalities. Cancer Research UK-funded centers in London and Manchester generate investigator-sponsored trials that shape platform development priorities. The London-Oxford-Cambridge golden triangle concentrates viral vector manufacturing expertise and regulatory science capability.
Japan
PMDA's Sakigake designation system compresses review timelines for oncolytic constructs targeting refractory malignancies. The University of Tokyo Hospital and National Cancer Center Hospital East anchor clinical development for neurotropic viral platforms in glioblastoma. Kanto region academic medical centers prioritize intravenous delivery protocols that enable systemic metastatic targeting.
Canada
Health Canada maintains divergent environmental release standards for replication-competent viruses compared to FDA protocols, creating compliance complexity for multi-regional sponsors. Princess Margaret Cancer Centre in Toronto and BC Cancer in Vancouver concentrate early-phase trial enrollment through established biosafety containment infrastructure. The Canadian regulatory framework requires specialized protocols for live biotherapeutic product manufacturing consistency.
Oncolytic Virus Therapy Market Key Industry Players
Strategic partnerships dominate the current landscape as sponsors seek to combine viral platforms with checkpoint inhibitors and adoptive cell therapies. The vendor base organizes around three tiers: established biopharmaceuticals with commercial infrastructure, emerging biotechs with novel viral engineering platforms, and academic spinouts with specialized indication focus. Archetypes include the integrated commercializer, the mechanism-of-action specialist, and the regional development partner. Technology licensing and geographic co-development agreements represent the dominant competitive moves as companies navigate divergent regulatory requirements across jurisdictions.
Within the mechanism-of-action specialist tier, Oncolytics Biotech exemplifies distinct positioning through pelareorep combinations for metastatic breast cancer. Among integrated commercializers, Amgen anchors the landscape through established T-VEC infrastructure and contracted oncology center networks. CG Oncology occupies a position within the indication-focused archetype, advancing conditionally replicative adenovirus platforms through Phase 3 development.
| Leading Market Players |
|---|
| Amgen |
| Oncolytics Biotech |
| Candel Therapeutics |
| Genelux Corporation |
| CG Oncology |
| Transgene SA |
| SillaJen |
| Targovax |
| Lokon Pharma |
| Others |
Cost & Logistics Intelligence
Ultra-low temperature storage infrastructure costs cascade through oncolytic virus therapy pricing tiers, with minus eighty degrees Celsius cold-chain requirements from viral vector manufacturing through hospital receipt creating three distinct cost bands that separate academic medical centers from community oncology sites.
Pricing Analysis
Input-cost pass-through from specialized purification processes and replication-competent contaminant removal protocols stratifies pricing across manufacturing batches. Pricing stratifies across premium, standard, and economy tiers based on biosafety containment certification level and principal investigator density at receiving sites. Cost compression in the economy tier intensifies because community oncology practices lack validated minus eighty storage capacity and must outsource distribution logistics. Academic medical centers with in-house viral therapy infrastructure exhibit lowest price sensitivity, while specialized clinics face acute margin pressure from infrastructure investment requirements.
Supply Chain Analysis
Reverse-logistics flows for oncolytic virus therapy center on temperature excursion protocols and batch recall procedures for live biotherapeutic products that breach minus eighty degrees Celsius chain of custody. Manufacturing concentrates in the United States, Germany, and the United Kingdom, with viral vector production anchored in Boston, Heidelberg, and Oxford-Cambridge clusters. Production draws from specialized cell culture media, purified plasmid DNA, and cGMP-grade fetal bovine serum inputs. Single-source vulnerability in qualified plasmid suppliers presents structural risk for multi-regional sponsors. Distribution runs through contracted specialty pharmacy networks with validated cryogenic transport capability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oncolytic virus therapy represents a late-cycle quality story as demand consolidates toward premium-tier intravenous delivery protocols that command superior reimbursement and expanded patient eligibility beyond localized lesion accessibility.
For Market Incumbents: Cement leadership in checkpoint inhibitor combination protocols by expanding principal investigator networks at NCI-designated cancer centers and securing preferred site status through dedicated cold-chain infrastructure investments. Threat from emerging biotechs with novel viral engineering platforms demands accelerated regulatory submission timelines to maintain protocol inclusion priority. Vertical integration into in-house viral vector manufacturing reduces batch-to-batch variability and protects margin structure from contract manufacturing organization capacity constraints. For New Entrants and Emerging Players: The price-point gap between premium intravenous protocols and intralesional economy tiers creates white-space opportunity for mid-tier delivery innovation targeting glioblastoma indications with blood-brain barrier penetration advantages. Community oncology practices with emerging biosafety containment capabilities represent the most penetrable segment for site activation partnerships. Go-to-market execution should emphasize investigator-sponsored trial relationships at secondary academic medical centers outside Boston-Houston-New York concentration. For Investors and Strategic Acquirers: Consolidation pressure builds where manufacturing consistency standards for live biotherapeutic products exceed emerging biotech capabilities, forcing revalidation costs that strain development-stage balance sheets. Long-term viability favors platform companies with diversified viral backbone portfolios spanning melanoma, glioblastoma, and solid tumor indications. Acquisition target archetype includes mechanism-of-action specialists with EMA priority medicines eligibility and established checkpoint inhibitor collaboration frameworks. Signal to watch is FDA breakthrough therapy designation frequency for novel neurotropic constructs.| Strategic Initiative | Industry Significance |
|---|---|
| Checkpoint Inhibitor Combination Trials | Amgen's T-VEC infrastructure enables protocol expansion at Memorial Sloan Kettering and MD Anderson. |
| EMA Priority Medicines Submission | Parallel US-EU regulatory pathways compress review timelines for glioblastoma neurotropic platforms. |
| Intravenous Delivery Protocol Development | Vascular administration at Boston academic centers expands eligible patient populations beyond lesion accessibility. |
| Cold-Chain Infrastructure Partnership | Specialty pharmacy networks with validated minus eighty storage reduce site activation barriers for community oncology. |
| AI-Driven Patient Selection Tool Deployment | Algorithmic enrollment optimization triggers EU AI Act disclosure requirements for combination trial recruitment. |
Research Approach
Coverage spans the United States, Germany, the United Kingdom, Japan, and Canada, with primary inputs from each market combining structured interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient-flow modeling and top-down revenue triangulation cross-verify segment-level estimates.
Rate-of-change decomposition separates volume drivers from price-mix effects across the projection horizon. The analytical framework models segmentation dimensions including viral backbone type, delivery mode, end-user site certification tier, indication severity, and regional regulatory cluster. CAGRs derive from fitted growth curves anchored to clinical trial enrollment velocity and commercial uptake trajectories at NCI-designated cancer centers. Forecast inputs incorporate checkpoint inhibitor combination protocol expansion rates and cold-chain infrastructure buildout timelines.
Caveats apply where potency assay standardization revisions or divergent environmental release protocol harmonization between Health Canada and FDA could materially shift the outlook. Forecasts reflect assumptions regarding breakthrough therapy designation frequency and reimbursement pathway maturity for novel indications. Practitioners should monitor regulatory tightening on live biotherapeutic product manufacturing consistency and AI Act compliance requirements for patient selection algorithms as early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Cell Therapy Cryopreservation and Thaw Performance Test Platforms Market
Cell & Gene Therapy
Gene Panel Market
Cell & Gene Therapy
B Cell Maturation Antigen Targeted Therapy Market
Cell & Gene Therapy
Induced Pluripotent Stem Cells Production Market
Cell & Gene Therapy
Adeno Associated Virus Vector Manufacturing Market
Cell & Gene Therapy
Cord Blood Banking Market
Cell & Gene Therapy
Nucleic Acid Based Therapeutics Market
Cell & Gene Therapy
Middle East and Africa Viral Vector Purification Market
Cell & Gene Therapy
Engineered Cell Therapy Market
Cell & Gene Therapy
Global T-Cell Lymphoma Market
Cell & Gene Therapy
Oncolytic Virus Cancer Therapy Market
Cell & Gene Therapy
RNAI Technology Market
Cell & Gene Therapy
Global Umbilical Cord Blood (UCB) Stem Cell Market
Cell & Gene Therapy
Cell and Gene Therapy Manufacturing Market
Cell & Gene Therapy
Gene Electroporators Market
Cell & Gene Therapy
Hemophilia Therapeutics Market