
 Animal Protein Market | 2026-2036
Animal Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Protein Market Analysis
Grass-fed and antibiotic-free certification tiers is bifurcating procurement patterns across the value chain. Tyson Foods Inc. leverages its captive feedlot network to sustain volume consistency in poultry. JBS S.A. anchors South American beef exports through integrated slaughter-to-port logistics. Cargill Incorporated differentiates via alternative protein R&D alongside conventional animal protein operations.
Animal protein encompasses tissue-derived edible proteins from livestock and aquaculture species, typically characterized by complete amino acid profiles with biological value scores exceeding 75% and functional properties including gelation, emulsification, and water-binding capacity essential to formulated foods. Poultry leads product type volumes due to feed conversion efficiency and shorter production cycles, while processed and frozen forms capture expanding margin pools from ready-meal and industrial ingredient channels. The distribution channel structure concentrates in wholesale and supermarket tiers, though online retailers represent the fastest-growing access point for direct-to-consumer premium cuts.
The USDA and FDA jointly oversee slaughter safety and labeling standards in the United States, while the EU enforces EFSA nutritional claims verification and CE-marked processing equipment mandates under its food hygiene package. Brazil's MAPA inspection protocols and China's GB standards for imported meat shape market access conditions for exporters. Stakeholders must monitor divergence between carbon-footprint disclosure requirements and cost-pass-through capacity in downstream pricing.
Market Dynamics
Collagen-derived protein applications in food service menus are restructuring procurement priorities across the value chain, while EU F-Gas Regulation and REACH compliance frameworks force capital reallocation toward processing equipment upgrades.
Growth Catalysts
- Feed conversion efficiency gains:Poultry's superior biological conversion ratios versus ruminant species concentrate investment flows into avian protein infrastructure. Brazil's integrated meatpacking corridors capture expanding export capacity.
- REACH chemical safety mandates:EU processing equipment standards accelerate replacement cycles for legacy rendering systems. CE-marked machinery penetration rises among mid-scale operators.
- Collagen functional properties:Gelation and emulsification performance in formulated foods opens industrial ingredient channels. Food manufacturers specify hydrolyzed collagen for clean-label applications.
Market Restraints
- Input cost volatility:Feed grain price swings transmit directly to protein production economics. Corn and soybean meal futures amplify margin compression risk.
- Supply concentration risk:Brazil's slaughter-to-port logistics dominance creates single-point vulnerability. Integrated meatpacking corridor disruptions ripple through global beef trade.
- Regulatory friction:Divergence between USDA-FDA joint oversight and China's GB import standards fragments compliance architecture. Exporters face dual certification burdens.
Strategic Opportunities
- Online retail channel expansion:Direct-to-consumer premium cut distribution bypasses wholesale margin stacking. Cold-chain logistics investments unlock geographic reach.
- Antibiotic-free certification tiers:Grass-fed procurement patterns command price premiums in North American and European retail. Third-party verification creates brand differentiation.
- Alternative protein R&D convergence:Hybrid formulations blending animal and fermentation-derived proteins attract venture capital. Functional property matching drives formulation partnerships.
Industry Challenges
- Carbon-footprint disclosure compliance:Scope 3 emissions tracking demands supplier data integration. Downstream cost-pass-through capacity limits pricing recovery.
- Slaughter safety certification timelines:USDA inspection protocol backlogs delay facility commissioning. Pre-operational approval cycles extend capital deployment periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Protein Market |
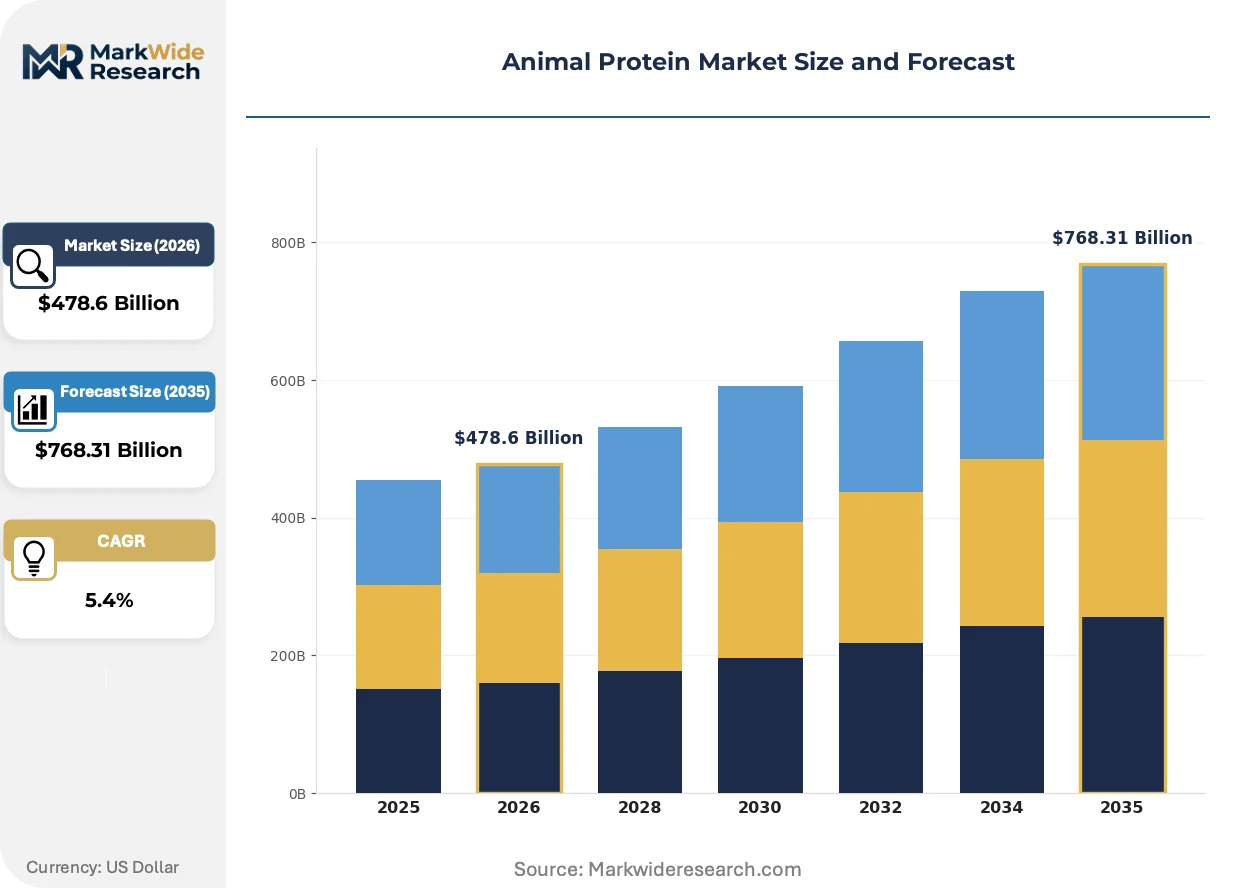
| Market Size in 2026 | $478.6 Billion |
| Market Size in 2035 | $768.31 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Pork, Poultry, Seafood Form: Fresh, Frozen, Processed, Dried Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Wholesale End User: Households, Restaurants, Food Services, Exporters |
| Companies Covered | Cargill Incorporated, Arla Foods amba, Tyson Foods Inc., JBS S.A., Darling Ingredients Inc., Fonterra Co-operative Group, Kerry Group Plc, BRF S.A., Nitta Gelatin Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Protein Market Emerging Trajectories
Processing technology miniaturization and regulatory disclosure mandates are compressing equipment replacement cycles while reshaping how buyers evaluate protein sourcing credentials across channels.
Precision fermentation for collagen scaffolding is miniaturizing production footprints previously requiring industrial-scale rendering facilities. Mid-sized food service distributors adopt compact bioreactor systems for on-site protein hydrolysate generation. This distributed processing architecture is compressing cold-chain requirements and enabling fresher ingredient delivery windows.
EU F-Gas Regulation phase-down schedules force refrigeration system retrofits across processing plants. Equipment manufacturers accelerate natural refrigerant technology deployment to maintain market access. Poultry processing facilities in Northern Europe face the steepest compliance timelines due to existing ammonia infrastructure age.
Clean-label certification preferences rotate procurement specifications toward third-party verified supply chains. Industrial ingredient buyers now require antibiotic-free documentation for formulated product eligibility. This verification burden concentrates supplier relationships among integrated operators with captive traceability systems.
Animal Protein Market Segmentation
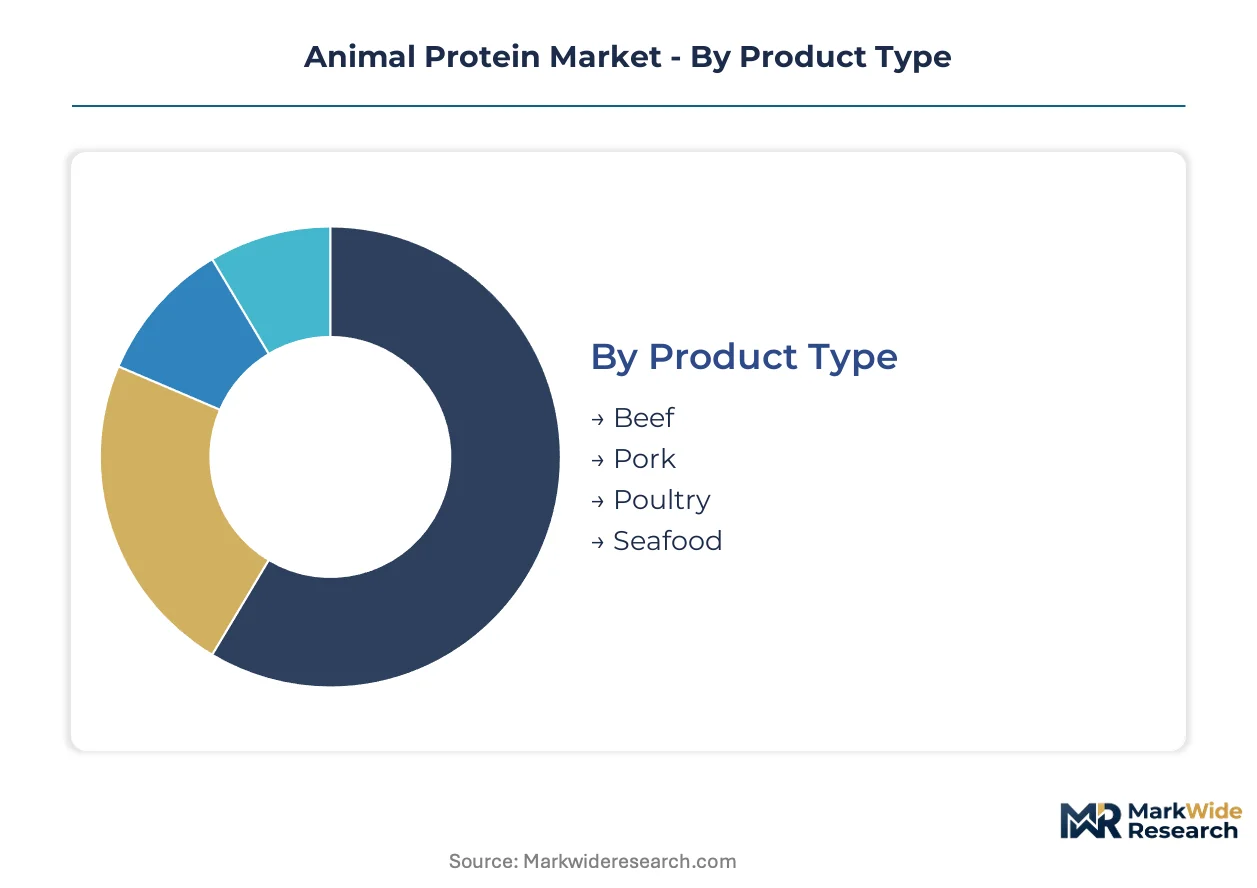
Animal protein segmentation reveals where plant-based and precision-fermentation substitutes exert the greatest displacement pressure. Product type and form dimensions determine margin vulnerability, while distribution channel and end-user splits expose pricing power concentration.
Product Type:
Substitution pressure varies sharply across livestock categories, with ruminant proteins facing stronger alternative-protein competition than avian species due to carbon-intensity differentials.
- Beef:High-biological-value protein from cattle with complete amino acid profiles and myoglobin-driven color stability. Demand concentrates in Brazilian export corridors serving Middle Eastern importers, constrained by EU deforestation-free supply chain mandates under EUDR.
- Poultry:White meat protein characterized by superior feed conversion ratios and shorter production cycles versus ruminants. Broiler integration in Thailand and Poland is displacing pork in European retail prepared-meal formulations.
- Pork:Versatile muscle protein with high myosin content enabling emulsion stability in processed applications. Chinese GB standards for imported pork shape access conditions for Danish and Spanish exporters.
- Seafood:Aquaculture-derived proteins with omega-3 fatty acid differentiation and lower land-use footprints. Norwegian salmon farming corridors face MOWI and Lerøy capacity expansion.
Poultry retains volume leadership; seafood holds the steepest expansion curve.
Form:
Cost tier stratification separates commodity bulk formats from value-added preparations commanding formulation premiums in industrial channels.
- Fresh:Unprocessed chilled protein with minimal shelf life and maximum sensory integrity. Supermarket butcher counters in Germany and France specify fresh-only procurement for premium private-label lines.
- Processed:Value-added preparations including cured, smoked, and emulsified products with extended stability. Deli meat demand from US food service distributors drives hydrolyzed collagen inclusion for texture modification.
- Frozen:Blast-frozen protein preserved at minus 18 degrees Celsius for extended distribution reach. Cold-chain infrastructure in Vietnam and Indonesia enables frozen poultry penetration into traditional wet markets.
- Dried:Moisture-reduced protein with ambient stability for emergency relief and military ration applications. Chinese jerky and South African biltong production clusters serve regional snack channels.
Processed forms dominate margin capture; frozen formats are climbing the fastest in emerging market penetration.
Distribution Channel:
Customer type fragmentation splits procurement between price-sensitive institutional buyers and experience-driven direct purchasers.
- Supermarkets:Multi-format retail with dedicated meat counters and pre-packaged case-ready sections. Carrefour and Ahold Delhaize antibiotic-free specifications reshape upstream supplier certification requirements.
- Online Retailers:Direct-to-consumer platforms with subscription-based premium cut delivery. Cold-chain last-mile investments by FreshDirect and Ocado unlock geographic expansion beyond traditional wholesale territories.
- Wholesale:Volume-dominant channel serving institutional food service and further-processing manufacturers. Sysco and US Foods consolidation concentrates buyer power over mid-scale slaughter operators.
- Convenience Stores:Grab-and-go prepared protein formats for immediate consumption occasions. Japanese 7-Eleven and Lawson rotisserie chicken programs drive processed poultry specification.
Wholesale maintains volume dominance; online retailers are gaining share fastest in premium tier distribution.
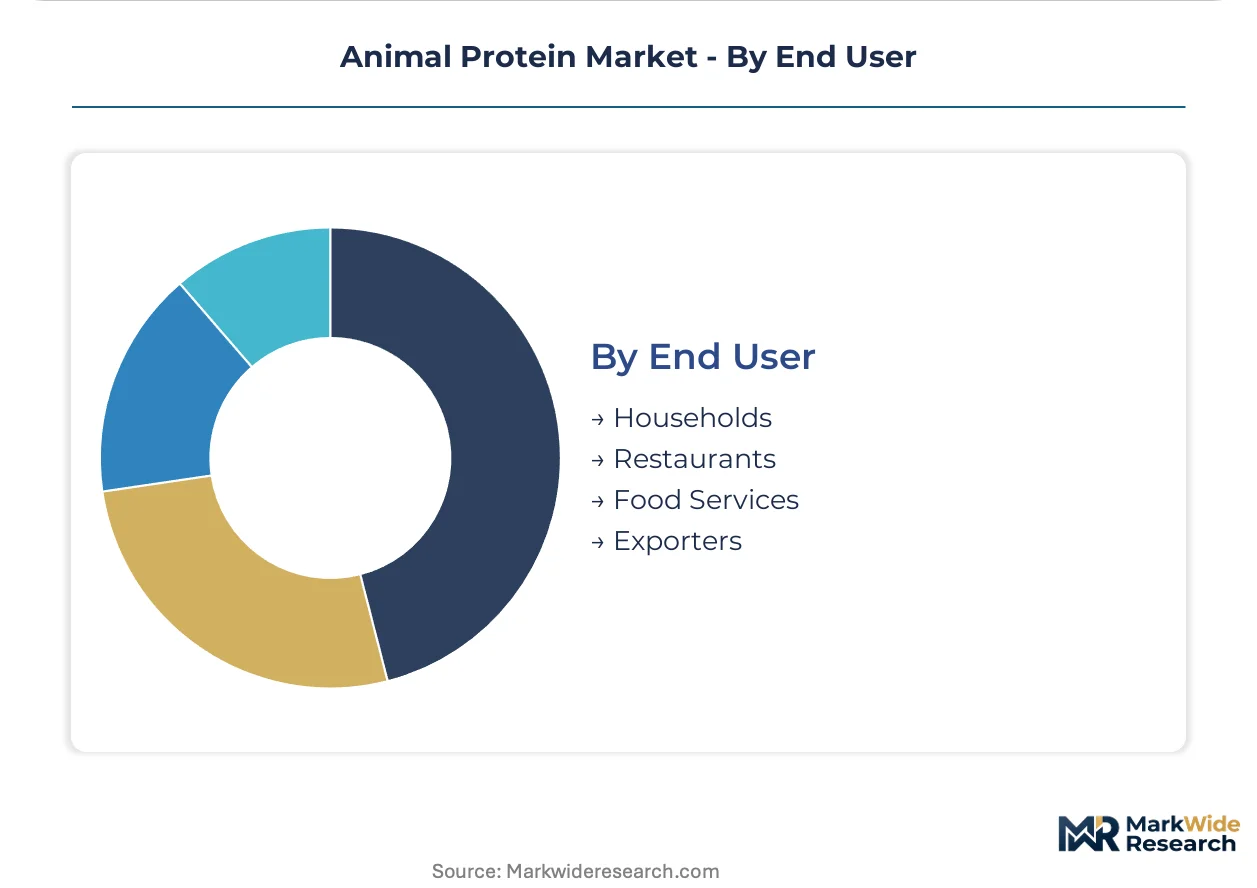
End User:
Application maturity separates established household consumption from emerging industrial ingredient demand.
- Restaurants:Food service operators specifying protein for menu execution with consistency and labor-efficiency priorities. McDonald's and Burger King procurement contracts drive poultry breast specification standardization.
- Food Services:Institutional catering and contract management requiring bulk delivery with HACCP documentation. Sodexo and Compass Group sustainability scorecards incorporate Scope 3 emissions tracking.
- Households:Retail purchasers selecting protein for home preparation with price and convenience trade-offs. US and UK consumers shift toward smaller pack sizes and value-added marinades.
- Exporters:Trade intermediaries navigating dual certification for multiple destination market access. Brazilian meatpackers manage MAPA inspection protocols alongside Saudi SFDA and Chinese GB standard compliance.
Restaurants anchor volume absorption; food services are expanding most quickly in sustainability-linked contract growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's integrated meatpacking corridors dominate export capacity, while regulatory divergence between USDA-FDA frameworks and China's GB standards fragments compliance architecture for trade intermediaries.
United States
Poultry feed conversion efficiency and captive feedlot networks concentrate investment flows into avian protein infrastructure. USDA and FDA joint oversight of slaughter safety and labeling standards shapes facility commissioning timelines. Tyson Foods leverages its Arkansas and Georgia processing clusters to sustain volume consistency across retail and food service channels.
Brazil
Beef export demand from Middle Eastern importers flows through MAPA-inspected slaughter-to-port logistics. EUDR deforestation-free supply chain mandates constrain sourcing flexibility for European-bound shipments. JBS S.A. anchors South American exports through integrated corridors in Mato Grosso and Paraná state packing facilities.
China
GB standards for imported pork and beef shape market access conditions for Danish, Spanish, and Brazilian exporters. Domestic pork consumption recovery drives cold-chain infrastructure investment in provincial wholesale markets. Yangtze River Delta processing clusters face dual certification burdens for simultaneous USDA and EU-bound export qualification.
Germany
EU F-Gas Regulation phase-down schedules force refrigeration retrofits across Northern European poultry plants. EFSA nutritional claims verification and CE-marked processing equipment mandates elevate capital requirements. North Rhine-Westphalia rendering facilities accelerate natural refrigerant technology deployment to maintain market access.
Thailand
Broiler integration displaces pork in European retail prepared-meal formulations due to shorter production cycles. Cold-chain infrastructure expansion enables frozen poultry penetration into Vietnamese and Indonesian traditional wet markets. Bangkok-centered processing clusters capture margin pools from ready-meal ingredient channels.
Animal Protein Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the animal protein value chain. Integrated meatpacking operators with captive feedlot and rendering capabilities dominate volume tiers, while specialized collagen and gelatin processors command formulation premiums in industrial ingredient channels. Three archetypes define competitive positioning: scale-driven integrators controlling slaughter-to-port logistics, functional protein specialists supplying hydrolyzed collagen for clean-label applications, and diversified agribusiness conglomerates blending conventional and alternative protein R&D portfolios. Consolidation through slaughter capacity acquisition and backward integration into feed grain sourcing represent the dominant competitive moves.
Within the integrated meatpacking tier, JBS S.A. and Tyson Foods Inc. exemplify scale-driven operators with geographic diversification across multiple protein species. Cargill Incorporated occupies a position bridging conventional animal protein operations with alternative protein R&D convergence, representing the diversified conglomerate archetype. These three entities anchor the competitive structure through their respective control of Brazilian export corridors, North American poultry integration, and multi-platform protein portfolios.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Arla Foods amba |
| Tyson Foods Inc. |
| JBS S.A. |
| Darling Ingredients Inc. |
| Fonterra Co-operative Group |
| Kerry Group Plc |
| BRF S.A. |
| Nitta Gelatin Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Brazilian meatpackers and Middle Eastern importers lock in both supply access and price visibility, insulating integrated operators from spot market volatility while exposing non-integrated processors to feed grain cost transmission. These contractual structures concentrate pricing power among JBS S.A. and BRF S.A. through their captive slaughter-to-port logistics, leaving smaller exporters to absorb margin compression from corn and soybean meal futures swings.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across Northern European processing facilities by forcing capital recovery through equipment surcharges. Three-tier pricing structure across premium, standard, and economy levels separates antibiotic-free certified cuts from conventional and commodity bulk formats. Pricing pressure stems from Scope 3 emissions tracking costs that downstream buyers resist passing through to retail shelves. Food service distributors exhibit highest price sensitivity due to thin menu-margin economics, while direct-to-consumer online retailers absorb premiums for provenance-verified product.
Supply Chain Analysis
Brazil and Thailand anchor global animal protein supply through integrated meatpacking corridors and broiler integration clusters respectively. Raw material flows draw from Argentine soybean meal, US corn exports, and Norwegian fish feed formulations. Single-source vulnerability concentrates in Brazil's Mato Grosso slaughter-to-port logistics where MAPA inspection protocol disruptions ripple through beef trade. Distribution runs through Sysco and US Foods consolidation at wholesale tier, with cold-chain last-mile investments by Ocado and FreshDirect fragmenting premium segment access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. USDA-FDA joint oversight and EU REACH compliance frameworks create certification barriers that entrench integrated incumbents while raising capital thresholds for new facility commissioning.
For Market Incumbents: Fortify slaughter-to-port logistics control through backward integration into feed grain sourcing in Mato Grosso and Paraná corridors. Invest in CE-marked rendering equipment ahead of F-Gas Regulation phase-down deadlines to capture competitor displacement. Precision fermentation R&D partnerships with collagen specialists hedge against alternative protein substitution in industrial ingredient channels.
For New Entrants and Emerging Players: Differentiate on antibiotic-free certification tiers targeting Carrefour and Ahold Delhaize private-label procurement specifications. Penetrate Vietnamese and Indonesian frozen poultry markets where cold-chain infrastructure gaps exclude incumbent Brazilian exporters. Launch direct-to-consumer subscription models for premium cuts bypassing wholesale margin stacking.
For Investors and Strategic Acquirers: Functional protein specialists with hydrolyzed collagen capabilities and clean-label verification systems offer acquisition exposure to formulation premium capture. Long-term viability centers on hybrid protein R&D convergence blending animal and fermentation-derived inputs. Watch for USDA inspection protocol backlog resolution as facility commissioning velocity inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feed Grain Sourcing | Captive supply of Brazilian soybean meal insulates JBS from commodity futures volatility. |
| CE-Marked Processing Equipment Deployment | Natural refrigerant retrofits unlock EU market access under F-Gas Regulation timelines. |
| Antibiotic-Free Certification Investment | Third-party verification secures shelf placement at Carrefour and Ahold Delhaize. |
| Direct-to-Consumer Channel Expansion | Cold-chain last-mile investments by FreshDirect fragment wholesale pricing power. |
| Precision Fermentation R&D Partnership | Collagen scaffolding capabilities attract venture capital for hybrid formulation development. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of USDA inspection records, MAPA compliance filings, EU EFSA nutritional claims databases, and trade flow customs data. Interviews with meatpacking operations directors, food service procurement managers, supermarket category buyers, and rendering facility engineers informed demand-side and supply-side validation. Bottom-up volume modeling across product type, form, and distribution channel dimensions triangulates against top-down macroeconomic consumption indicators.
Segmentation dimensions modeled span livestock species, processing form, channel structure, and end-user application across the analysis window. CAGRs derive from historical trajectory analysis adjusted for regulatory intervention timing and capital deployment cycles. Feed conversion efficiency benchmarks and cold-chain infrastructure penetration curves serve as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under stable regulatory enforcement and feed grain price regime assumptions; material deviation would warrant model refresh. Specific risk factors include EUDR deforestation-free supply chain mandate expansion, Chinese GB standard revision, and Scope 3 emissions disclosure mandate acceleration. Recalibration cycles align with material shifts in EU F-Gas Regulation phase-down schedules and Brazilian MAPA inspection protocol modernization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
United Arab Emirates Red Meat Market
Meat Products
GCC Red Meat Market
Meat Products
Europe Animal Protein Market
Meat Products
United States Red Meat Market
Meat Products
Shark Meat Market
Meat Products
Chicken Buckets Market
Meat Products
Brisket Market
Meat Products
India Animal Protein Market
Meat Products
Vegan Meatball Market
Meat Products
United Arab Emirates Edible Meat Market
Meat Products
Bacon Market
Meat Products
Organic Chicken Market
Meat Products
China Processed Meat Market
Meat Products
North America Processed Poultry Meat Market
Meat Products
Low-Fat Chorizo Market
Meat Products
United States Edible Meat Market