
 Bovine Collagen Peptide Market | 2026-2036
Bovine Collagen Peptide Market Size, Share, and Industry Trends Forecast 2026-2036
Bovine Collagen Peptide Market Analytics
Brazil's expanding abattoir-to-peptide processing corridor is reshaping raw material flows for the industry. Gelita AG leverages captive hide sourcing across South American tanneries to sustain cost advantages at scale. PB Leiner anchors European pharmaceutical-grade output through its Belgian extraction network. Darling Ingredients Inc. dominates North American bovine byproduct valorization, converting slaughterhouse waste into collagen precursors at volume.
Bovine collagen peptide comprises partially hydrolyzed protein fractions extracted from bovine hides and bones, typically yielding molecular weights below 10 kDa for optimal bioavailability in human absorption. Manufacturers deploy enzymatic hydrolysis followed by spray-drying to preserve triple-helix fragments essential for signaling biological activity. Hydrolyzed collagen occupies the largest value share among product types due to its solubility across beverage and powder formats. Nutraceuticals leads application demand as aging populations in East Asia seek joint and skin health formulations. Powder form commands premium shelf positioning in direct-to-consumer channels despite liquid alternatives gaining traction in ready-to-drink functional beverages.
FDA GRAS self-affirmation requirements and EFSA novel food opinions shape market access timelines for new entrants launching bovine-derived ingredients in the United States and European Union. China's SAMR enforces stricter origin documentation for imported bovine peptides following zoonotic disease protocols, extending registration cycles for foreign suppliers. ISO 17025-accredited testing for heavy metals and microbiological contaminants now functions as a non-negotiable procurement filter for multinational food manufacturers. Stakeholders must monitor evolving country-of-origin labeling mandates and build redundant supplier qualifications across multiple regulatory jurisdictions.
Market Dynamics
Enzymatic hydrolysis technology from German equipment suppliers is tightening peptide yield consistency, compressing batch-to-batch variation and forcing mid-tier processors to upgrade or exit. This technological tightening concentrates production advantage among capitalized operators with captive hide sourcing.
Growth Catalysts
- EFSA novel food opinions:Clearance pathways for bovine-derived ingredients accelerate European nutraceuticals launches, reducing regulatory uncertainty for formulation partners.
- Senior demographics in East Asia:Aging populations in Japan and South Korea drive joint and skin health formulations, expanding the addressable consumer base for hydrolyzed collagen powders.
- Brazilian cattle-processing belt concentration:Proximity of abattoirs to São Paulo-state extraction facilities shortens raw material transit and preserves collagen integrity.
Market Restraints
- Hide and bone input cost volatility:Tannery byproduct pricing fluctuates with leather demand cycles, squeezing processor margins when automotive and furniture sectors soften.
- China SAMR origin documentation:Extended registration cycles for foreign suppliers following zoonotic disease protocols delay market entry by 12-18 months.
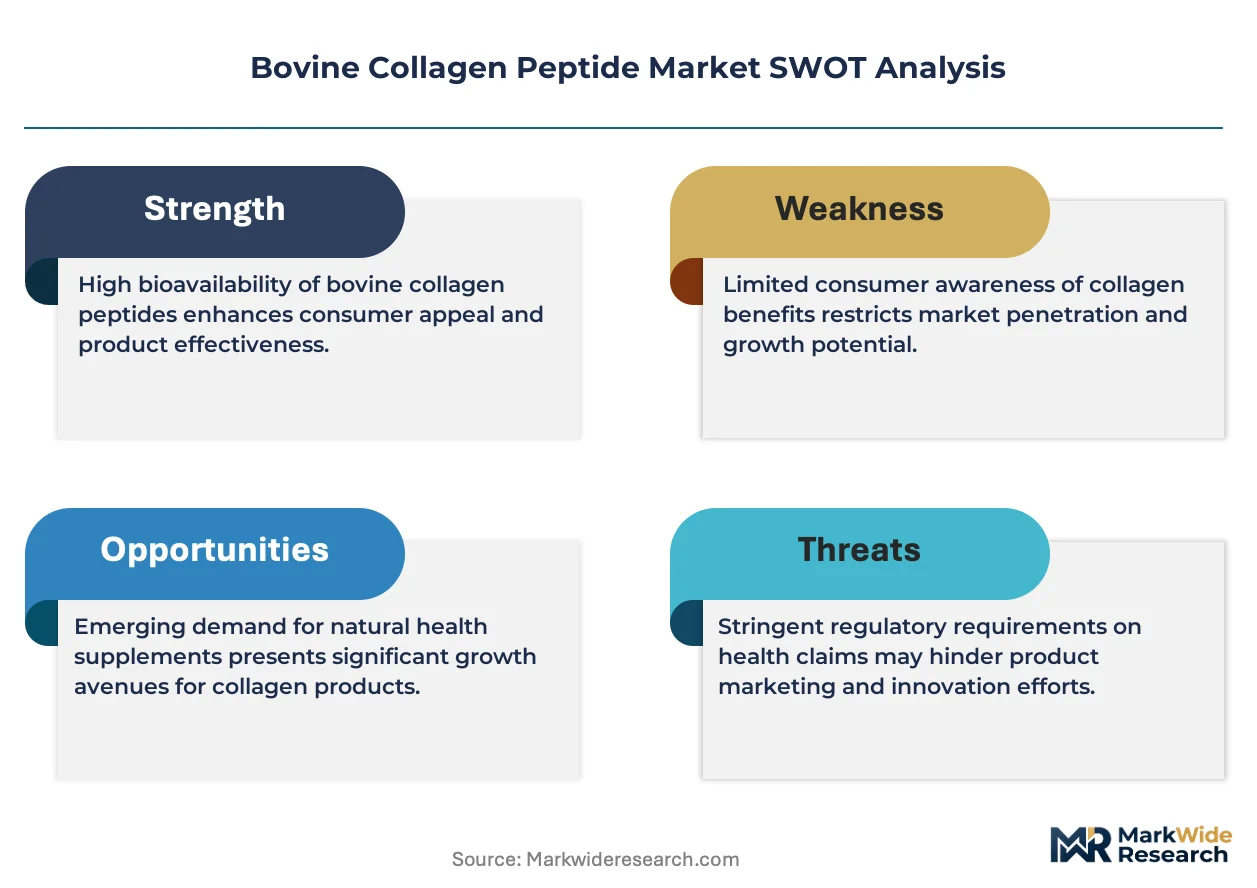
- Plant-based protein substitution:Pea and rice protein isolates capture share in clean-label beverage applications where animal origin creates formulation friction.
Strategic Opportunities
- Ready-to-drink functional beverages:Liquid collagen formats gain shelf space in convenience channels, opening incremental volume beyond traditional powder sachets.
- Pharmaceutical-grade certification:USP and EP monograph compliance enables prescription-adjacent positioning in wound healing and surgical applications.
- ISO 17025-accredited testing integration:In-house analytical capabilities become a procurement differentiator for multinational food manufacturers screening heavy metals and microbiological contaminants.
Industry Challenges
- Enzyme optimization expertise scarcity:Formulation chemists capable of tuning protease specificity for targeted molecular weight distributions command premium compensation.
- Spray-drying capex intensity:Food-grade atomization systems with nitrogen blanketing require seven-figure capital deployment, constraining capacity expansion for regional processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bovine Collagen Peptide Market |
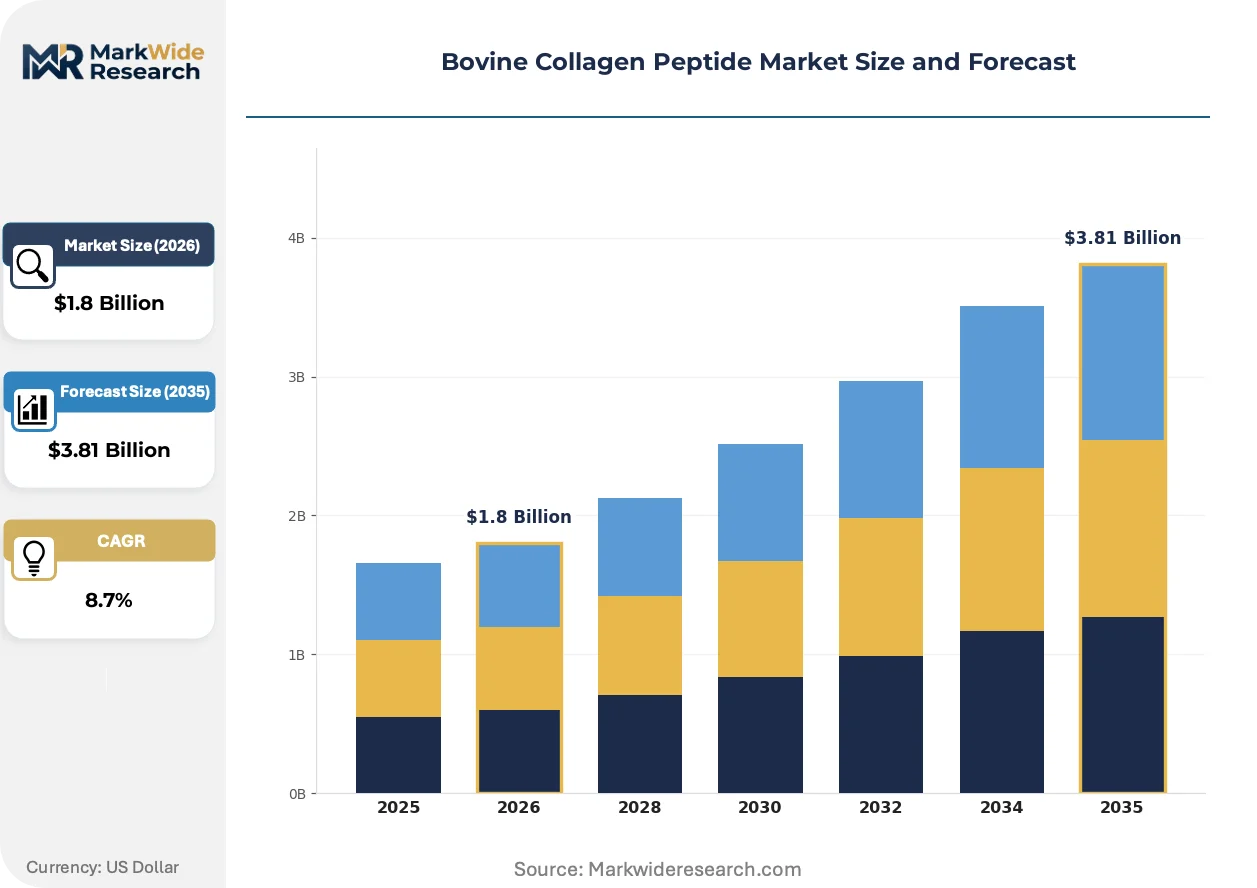
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Native Collagen, Gelatin, Collagen Peptides Application: Nutraceuticals, Cosmeceuticals, Functional Foods, Pharmaceuticals Form: Powder, Liquid, Capsule, Tablet End User: Healthcare Providers, Food Manufacturers, Personal Care Brands, Fitness Enthusiasts |
| Companies Covered | Gelita AG, Nitta Gelatin Inc., PB Leiner, Rousselot, Darling Ingredients Inc., Weishardt Group, Bioiberica S.A.U., Lapi Gelatine Spa, Tessenderlo Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bovine Collagen Peptide Market Evolving Landscape
Digital process control and biosensor integration are compressing quality assurance timelines from days to hours. These innovations reshape competitive differentiation around consistency certification rather than commodity pricing.
Continuous enzymatic membrane reactors from GEA and Alfa Laval are virtualizing batch processing economics. Nutraceuticals contract manufacturers adopt these systems to reduce cleaning downtime and water consumption. The technology is virtualizing unit cost structures that previously favored mass-volume commodity producers, enabling smaller facilities to achieve comparable yield efficiency.
China's SAMR enforcement of stricter origin documentation following zoonotic disease protocols extends foreign supplier registration cycles. Multinational brands respond by qualifying redundant manufacturing sites across multiple regulatory jurisdictions. Brazilian and Argentine processors capture displaced volume as European suppliers face documentation bottlenecks.
Direct-to-consumer subscription models displace traditional wholesale distribution for premium collagen powders. Wellness brands bypass pharmacy and mass retail intermediaries, capturing margin and consumer data. This channel compression concentrates marketing spend on influencer partnerships and personalized nutrition algorithms in North American and Australian markets.
Bovine Collagen Peptide Market Segmentation
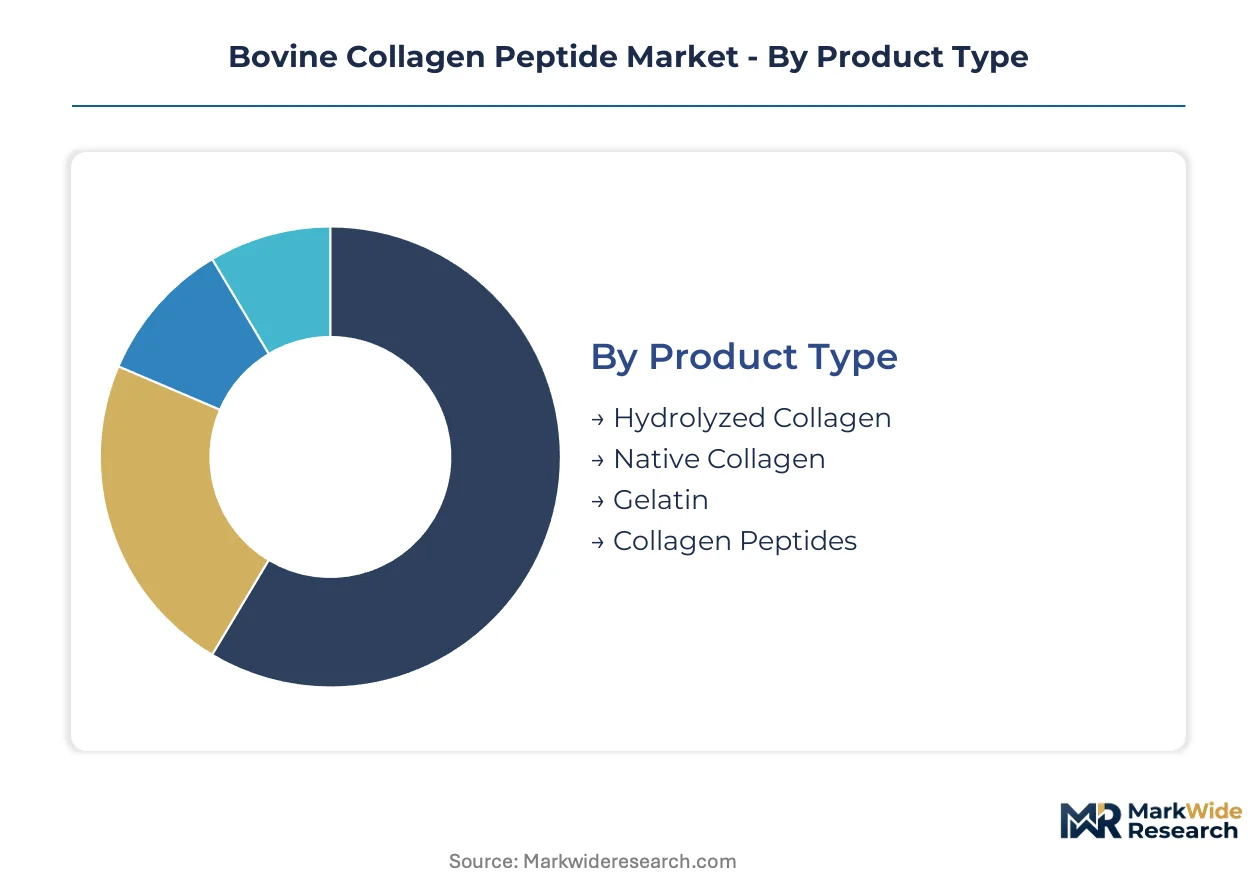
Segmentation in bovine collagen peptides reveals how formulation chemistry, delivery format, and buyer sophistication create distinct margin architectures. Each category carries different capital intensity, regulatory burden, and inventory velocity that reshape competitive positioning.
Product Type:
Hydrolyzed collagen turns inventory fastest with standardized enzymatic processing, while native collagen and pharmaceutical-grade peptides tie up working capital through extended purification cycles.
- Hydrolyzed Collagen:Partially hydrolyzed protein fractions yielding molecular weights below 10 kDa for optimal bioavailability. Demand concentrates in East Asian nutraceuticals as aging populations in Japan and South Korea seek joint and skin health formulations, with enzymatic hydrolysis tightening batch-to-batch variation through German equipment advances.
- Native Collagen:Triple-helix structures preserved in undenatured form for specific biomedical applications. European pharmaceutical-grade output through Belgian extraction networks anchors demand, though extended registration cycles with China's SAMR constrain foreign supplier entry timelines.
- Gelatin:Partially hydrolyzed collagen with broader molecular weight distribution serving food and photographic industries.
- Collagen Peptides:Highly refined fractions targeting bioactive signaling applications in functional nutrition.
Hydrolyzed collagen dominates installed base. Native collagen and pharmaceutical-grade fractions are where expansion concentrates.
Application:
Application segments separate by regulatory pathway complexity and clinical substantiation requirements, with pharmaceutical positioning demanding the steepest investment but yielding the longest contract durations.
- Nutraceuticals:Dietary supplements and functional nutrition products targeting wellness positioning. Aging demographics across East Asia drive joint and skin health formulations, with direct-to-consumer subscription models displacing traditional wholesale distribution in North American and Australian markets.
- Cosmeceuticals:Topical and ingestible beauty formulations bridging cosmetic and therapeutic claims. South Korean personal care brands integrate collagen peptides into sheet masks and ampoules, leveraging K-beauty export momentum into Southeast Asian retail channels.
- Functional Foods:Ready-to-drink beverages and fortified food matrices requiring solubility across temperature and pH ranges.
- Pharmaceuticals:Wound healing, surgical, and regenerative medicine applications requiring USP and EP monograph compliance.
Nutraceuticals commands the largest revenue share. Functional foods in ready-to-drink formats are climbing the fastest.
Form:
Form factors distinguish by manufacturing capex, with spray-dried powder requiring nitrogen-blanketed atomization systems while liquid formats demand aseptic filling infrastructure.
- Powder:Spray-dried particulates commanding premium shelf positioning in direct-to-consumer channels. Brazilian processors near São Paulo-state extraction facilities leverage proximity to cattle-processing belts for raw material freshness.
- Liquid:Ready-to-drink functional beverages gaining traction in convenience retail. North American wellness brands bypass pharmacy intermediaries through influencer partnerships and personalized nutrition algorithms.
- Capsule:Encapsulated doses targeting precision supplementation protocols.
- Tablet:Compressed formats for mass-market pharmacy distribution.
Powder dominates installed base. Liquid formats are where expansion concentrates.
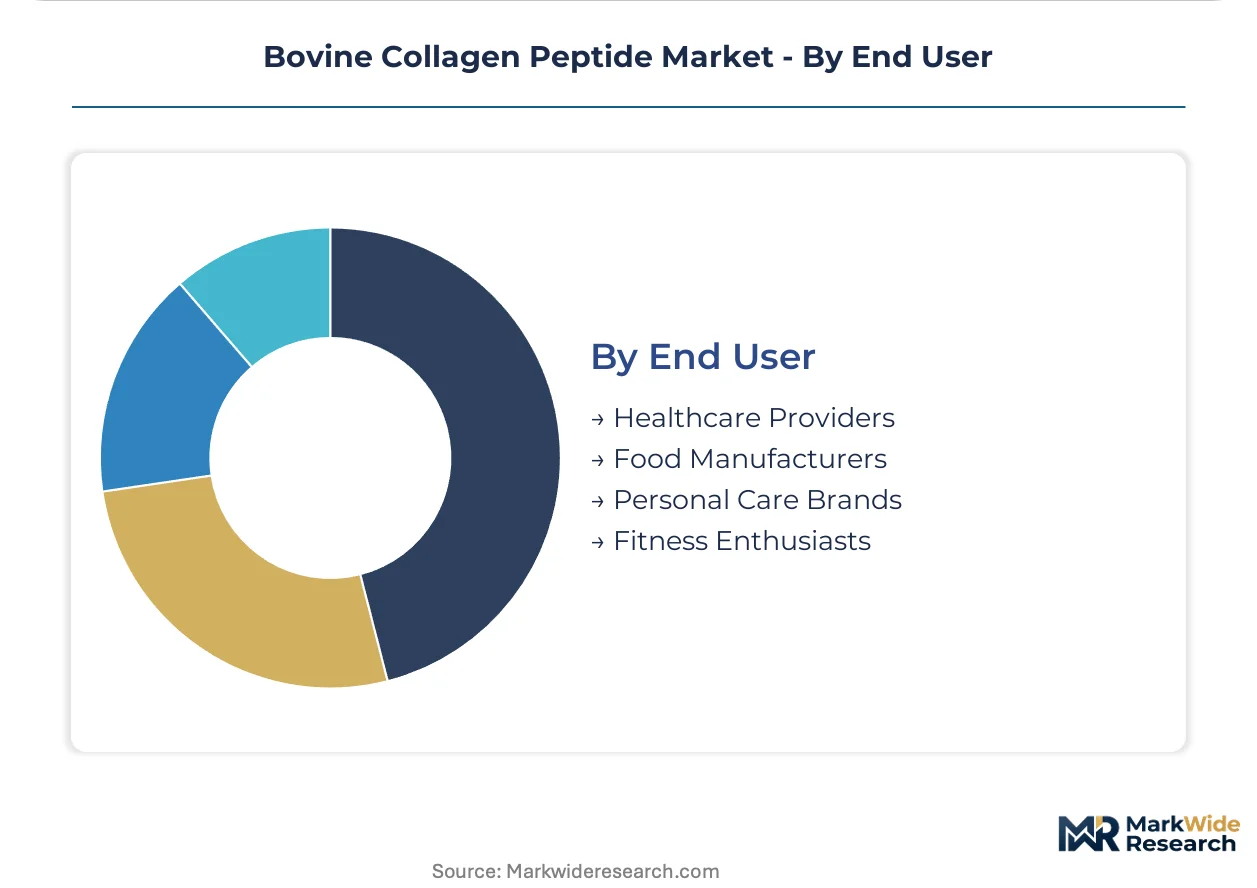
End User:
End user categories separate by procurement sophistication, with healthcare providers and multinational food manufacturers imposing ISO 17025-accredited testing filters that exclude regional processors.
- Healthcare Providers:Hospitals, clinics, and medical practices sourcing pharmaceutical-grade peptides for wound healing applications. FDA GRAS self-affirmation requirements and EFSA novel food opinions shape market access timelines for new entrants in the United States and European Union.
- Food Manufacturers:Multinational brands screening heavy metals and microbiological contaminants through accredited testing protocols. Darling Ingredients Inc. dominates North American bovine byproduct valorization, converting slaughterhouse waste into collagen precursors at volume.
- Personal Care Brands:Cosmetic and skincare formulators seeking bioactive claims substantiation.
- Fitness Enthusiasts:Direct-to-consumer purchasers through subscription and e-commerce channels.
Food manufacturers dominate installed base. Healthcare providers and pharmaceutical positioning are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. East Asian buyers prioritize nutraceutical powders for aging-related joint support, while North American demand tilts toward ready-to-drink functional beverages and direct-to-consumer subscriptions. European procurement emphasizes pharmaceutical-grade certification for wound healing applications.
United States
FDA GRAS self-affirmation pathways accelerate ingredient launches for nutraceutical formulators. The agency's dietary supplement enforcement discretion shapes compliance investment thresholds. Darling Ingredients anchors North American bovine byproduct valorization through slaughterhouse waste conversion networks concentrated in Midwestern cattle-processing corridors.
Germany
Equipment suppliers in Bavaria and Baden-Württemberg tighten peptide yield consistency through advanced enzymatic hydrolysis systems. EFSA novel food opinions reduce regulatory uncertainty for bovine-derived ingredient launches. German fabricators export processing technology to Brazilian and Argentine facilities, capturing value from equipment licensing rather than commodity production.
China
SAMR enforces stricter origin documentation for imported bovine peptides following zoonotic disease protocols, extending foreign supplier registration cycles. Aging demographics in coastal provinces drive joint and skin health formulation demand. Yangtze River Delta nutraceutical contract manufacturers qualify redundant supplier sites across multiple regulatory jurisdictions to circumvent documentation bottlenecks.
Brazil
São Paulo-state extraction facilities leverage proximity to the cattle-processing belt for raw material freshness and collagen integrity preservation. ANVISA registration requirements shape import substitution dynamics as European suppliers face documentation delays. Gelita AG deploys captive hide sourcing across South American tanneries to sustain cost advantages at scale.
Japan
Senior demographics drive sustained demand for hydrolyzed collagen powders targeting joint mobility and skin elasticity claims. PMDA consultation pathways for functional food substantiation impose clinical evidence requirements that favor established suppliers. Kanto region nutraceutical brands integrate collagen peptides into aging-focused product portfolios for domestic and Southeast Asian export markets.
Bovine Collagen Peptide Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. Premium-tier players command pharmaceutical-grade certification and captive raw material sourcing, while mid-scale processors compete on batch consistency and regional logistics. Three archetypes dominate: integrated hide-to-peptide operators with tannery partnerships, equipment-technology licensors extracting value from yield optimization, and pure-play nutraceutical formulators relying on toll manufacturing. Consolidation pressure intensifies through enzymatic hydrolysis technology upgrades and spray-drying capacity expansion.
Among European-anchored multinationals, Gelita AG exemplifies integrated supply chain control through South American hide sourcing networks. PB Leiner occupies a position within the pharmaceutical-grade certification tier, leveraging Belgian extraction infrastructure for monograph-compliant output. Darling Ingredients Inc. represents the North American byproduct valorization archetype, converting slaughterhouse waste streams into collagen precursors at volume scale.
| Leading Market Players |
|---|
| Gelita AG |
| Nitta Gelatin Inc. |
| PB Leiner |
| Rousselot |
| Darling Ingredients Inc. |
| Weishardt Group |
| Bioiberica S.A.U. |
| Lapi Gelatine Spa |
| Tessenderlo Group |
| Others |
Value Network & Pricing Analysis
São Paulo-state extraction facilities anchor downstream pricing power through proximity to Brazil's cattle-processing belt, compressing raw material transit windows and preserving collagen integrity that commands premium positioning in nutraceutical formulations. German enzymatic hydrolysis equipment tightens batch-to-batch yield consistency, forcing capitalized operators to capture margin through scale while mid-tier processors face upgrade-or-exit pressure.
Pricing Analysis
Long-term offtake contracts dominate pharmaceutical-grade supply relationships, while spot purchasing persists for commodity hydrolyzed collagen in functional food applications. Price differentiation separates USP and EP monograph-certified peptides from standard nutraceutical grades, with volume scale and captive hide sourcing as secondary drivers. Cost compression in mid-tier hydrolyzed collagen is intensifying because Brazilian processors leverage integrated tannery partnerships. Food manufacturers exhibit highest price sensitivity due to formulation cost constraints, whereas healthcare providers prioritize certification tier over unit economics.
Supply Chain Analysis
Bovine hides and bones feed from Brazil, Argentina, and North American Midwestern slaughterhouse corridors, with tannery byproduct flows fluctuating against leather demand cycles. Raw material dependencies center on enzymatic proteases from Danish and German suppliers, nitrogen-blanketed spray-drying infrastructure, and ISO 17025-accredited testing capacity. Single-source vulnerability concentrates around German equipment fabricators for continuous membrane reactor technology. Distribution runs through direct-to-consumer subscription channels displacing traditional wholesale in premium powder segments, while bulk ingredient flows serve multinational food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate plant-based protein substitution threatening clean-label beverage applications, where pea and rice protein isolates capture share from animal-origin formulations. Defensive positioning requires reinforcing supply security and certification moats before alternative proteins erode addressable demand.
For Market Incumbents: Entrench pharmaceutical-grade certification through USP and EP monograph compliance investments, locking in prescription-adjacent wound healing contracts. Secure captive hide sourcing across South American tannery networks to insulate margin from leather demand volatility. Plant-based protein substitution in ready-to-drink beverages represents the priority threat requiring formulation diversification or acquisition of clean-label peptide positioning. For New Entrants and Emerging Players: Pursue liquid collagen ready-to-drink formats in North American convenience channels, where wellness brands bypass pharmacy intermediaries through influencer partnerships. Target Brazilian ANVISA registration pathways to capture volume displaced from European suppliers facing China's SAMR documentation bottlenecks. White-space penetration concentrates in pharmaceutical-grade certification tiers where incumbent capacity constraints create supply gaps for surgical and regenerative medicine applications. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated hide-to-peptide operators with enzymatic optimization expertise and redundant regulatory jurisdiction qualifications. Long-term viability across the analysis window hinges on backward integration depth and ISO 17025 in-house analytical capabilities. Acquisition screening should prioritize Brazilian and Argentine processors with ANVISA registrations and São Paulo-state extraction infrastructure. The signal to watch is SAMR documentation clearance velocity for foreign suppliers, indicating market share redistribution timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tannery Partnerships | Gelita AG's South American hide sourcing networks demonstrate margin protection against leather demand cycles. |
| Pharmaceutical-Grade Certification Investment | PB Leiner's Belgian extraction infrastructure enables USP and EP monograph compliance for wound healing applications. |
| Continuous Membrane Reactor Adoption | GEA and Alfa Laval systems reduce cleaning downtime and water consumption for nutraceutical contract manufacturers. |
| Direct-to-Consumer Channel Expansion | North American wellness brands capture margin and consumer data through subscription models displacing wholesale distribution. |
| Redundant Regulatory Site Qualification | Multinational brands circumvent China's SAMR documentation bottlenecks by qualifying manufacturing across multiple jurisdictions. |
Research Methodology
Initial hypotheses were tested against primary input from nutraceutical formulation chemists, tannery procurement managers, pharmaceutical regulatory affairs leads, and food manufacturer quality directors and refined through secondary validation against FDA GRAS filings, EFSA novel food opinions, SAMR registration databases, and ANVISA approval records. Bottom-up demand modeling across hydrolyzed collagen, native collagen, and pharmaceutical-grade peptide tiers triangulated with top-down supply capacity assessments from Brazilian and European extraction facilities.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled by product type, application, form factor, and end-user procurement sophistication. CAGRs were derived from volume trajectory analysis incorporating East Asian senior demographic expansion, enzymatic hydrolysis yield improvements, and ready-to-drink format adoption curves. Forecast inputs included hide and bone availability projections tied to leather industry cycles and pharmaceutical-grade certification pipeline clearance rates.
Sensitivities concentrate around SAMR documentation enforcement intensity, plant-based protein substitution velocity in clean-label applications, and enzymatic equipment supplier concentration risk. Forecasts reflect assumptions regarding regulatory pathway stability and tannery byproduct pricing continuity. Cross-checking against customs trade data for bovine-derived ingredient flows and hospital procurement database trends for wound healing applications is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Europe Digestive Health Supplements Market
Nutritional Supplements
Microalgae DHA Market
Nutritional Supplements
Medium-Chain Triglycerides Market
Nutritional Supplements
Cod Liver Oil Market
Nutritional Supplements
Natural Vitamin E Product Market
Nutritional Supplements
North America Prenatal Supplements Market
Nutritional Supplements
Europe Collagen Supplements Market
Nutritional Supplements
Vitamin B3 Market
Nutritional Supplements
Biotin Supplement Market
Nutritional Supplements
Diet Pills Market
Nutritional Supplements
Global Protein Market
Nutritional Supplements
Water Soluble Vitamin and Mineral Feed Supplements Market
Nutritional Supplements
Asia-Pacific Arachidonic Acid Market
Nutritional Supplements
Choline Supplement Market
Nutritional Supplements
Africa Nutraceutical Market
Nutritional Supplements
CBD Nutraceuticals Market