
 United States Red Meat Market | 2026-2036
United States Red Meat Market Size, Share, and Industry Trends Forecast 2026-2036
United States Red Meat Market Analytics
Prime and Choice grade premiums is unwinding across retail and food service channels as consumers trade up on at-home dining occasions. Tyson Foods leverages its integrated feedlot-to-retail infrastructure to capture margin at every production stage. JBS sustains geographic dominance through large-scale beef and pork processing complexes in Nebraska and Colorado. Cargill competes via direct rancher procurement networks that secure consistent fed cattle supply.
United States red meat encompasses muscle tissue from cattle, swine, sheep, and goats, typically processed under USDA-inspected facilities with carcass chilling requirements below 40°F to inhibit pathogen proliferation; it serves as a primary dietary protein source and industrial input for prepared foods manufacturing. Beef occupies the largest value pool among product types due to extended finishing periods and grain-fed mar premiums, while pork differentiates through lean yield efficiency and faster turnover cycles. Vacuum-packed fresh formats lead packaging type value capture by extending case-ready shelf life and reducing retail labor costs.
USDA Agricultural Marketing Service grading standards, FSIS pathogen reduction and HACCP mandates, and EPA Clean Water Act discharge permits for packing facilities collectively elevate compliance costs and favor capital-intensive operators. These frameworks shape demand by channeling product through federally inspected plants and restricting direct-to-consumer volumes in certain states. Stakeholders must monitor evolving antibiotic use restrictions and California Proposition 12 compliance thresholds as these rules redefine supply chain eligibility and geographic market access.
Market Dynamics
USDA grading standards and FSIS inspection protocols are compressing margin capture for non-integrated processors while concentrating value accrual among operators with captive feedlot supply and federally inspected cold-chain infrastructure.
Growth Catalysts
- Proposition 12 Compliance Thresholds:California's animal housing density mandates are redirecting supply chain investment toward certified production systems, opening premium shelf-space access for qualifying pork and veal processors.
- Food Service Menu Expansion:Full-service restaurants and fast-casual chains are widening protein variety beyond chicken, pulling additional primals through case-ready distribution channels.
- Texas-Oklahoma Feedlot Corridors:Concentrated finishing capacity near Amarillo and the Texas Panhandle reduces transportation shrink and accelerates harvest-to-chill timelines for grain-fed cattle.
Market Restraints
- Feed Grain Input Volatility:Corn and soybean meal price swings transmit directly to cost-of-gain calculations, eroding forward-margin visibility for non-hedged cattle feeders.
- Midwest Packing Concentration:Nebraska, Iowa, and Kansas together host disproportionate kill capacity, creating regional supply bottlenecks when weather or labor disruptions idle major complexes.
- Plant-Based Protein Substitution:Pea and soy protein isolates are capturing flexitarian trial in retail ground meat categories, pressuring volume throughput for commodity beef trim.
Strategic Opportunities
- Direct-to-Consumer Channel Expansion:Rancher-owned e-commerce platforms and subscription box models are bypassing traditional packer-retailer markups in Texas Hill Country and Montana ranching communities.
- Antibiotic-Free Certification Tailwinds:USDA Process Verified shield programs for raised-without-antibiotics protocols are commanding shelf-space premiums in natural grocery channels.
- Blockchain-IoT Convergence:Distributed ledger traceability layered with cold-chain sensor networks is enabling source-verified origin claims for export-qualified carcasses.
Industry Challenges
- Skilled Meat Cutter Shortage:Fabrication floor talent pipelines have narrowed as vocational programs contract, constraining harvest line speeds and value-added processing expansion.
- Legacy ERP Integration Friction:Mid-scale packers face costly system overhauls to synchronize lot-tracking with FSIS electronic data interchange mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Red Meat Market |
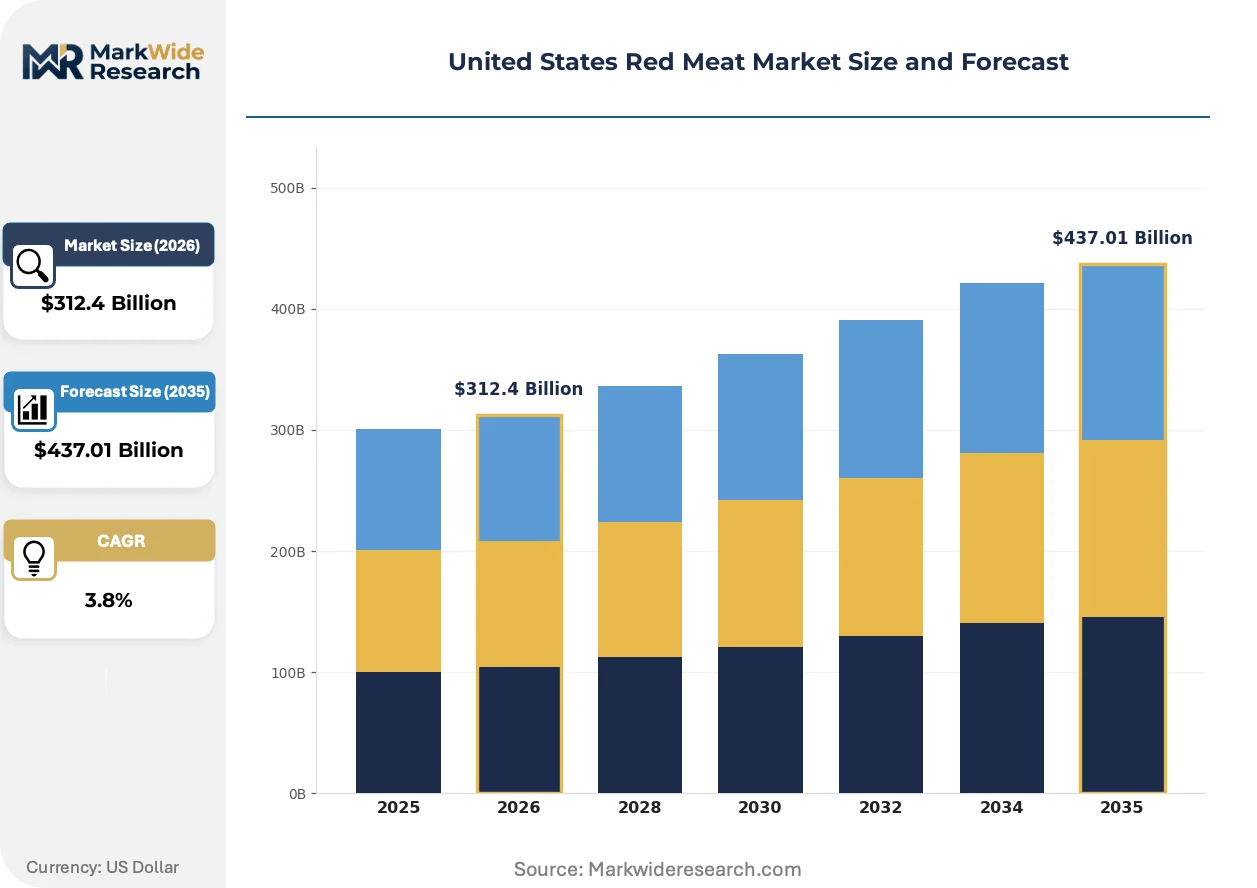
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $437.01 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Pork, Lamb, Goat Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Wholesale Packaging Type: Vacuum Packs, Canning, Frozen, Fresh End User: Restaurants, Households, Food Services, Institutions |
| Companies Covered | Tyson Foods, Cargill, JBS, National Beef Packing, Hormel Foods, Smithfield Foods, Perdue Farms, Seaboard Foods, WH Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Red Meat Market Evolving Landscape
Precision livestock monitoring and alternative protein co-manufacturing are fragmenting traditional procurement hierarchies while regulatory traceability mandates accelerate digital infrastructure deployment across the value chain.
Advanced carcass imaging systems using hyperspectral cameras and machine-learning algorithms are bifurcating quality assessment protocols. Large packers in the Midwest are adopting inline grading automation to reduce labor dependency and standardize yield predictions. This technology is bifurcating the market into data-rich integrated operators and conventional visual-grading facilities struggling to justify capital outlays.
California Proposition 12 implementation is forcing multistate pork supply chain reconfiguration. Out-of-state producers must retrofit sow housing or forfeit access to the country's largest state market. Interstate packers are responding by segregating compliant and non-compliant product flows, adding handling complexity and certification audit costs.
Retailers are consolidating case-ready procurement under fewer, larger suppliers capable of managing inventory risk and promotional volatility. This concentration is displacing traditional boxed-beef spot purchasing in supermarket meat departments. The shift is most visible in Texas and Florida retail markets where centralized distribution centers now dominate protein replenishment decisions.
United States Red Meat Market Segmentation
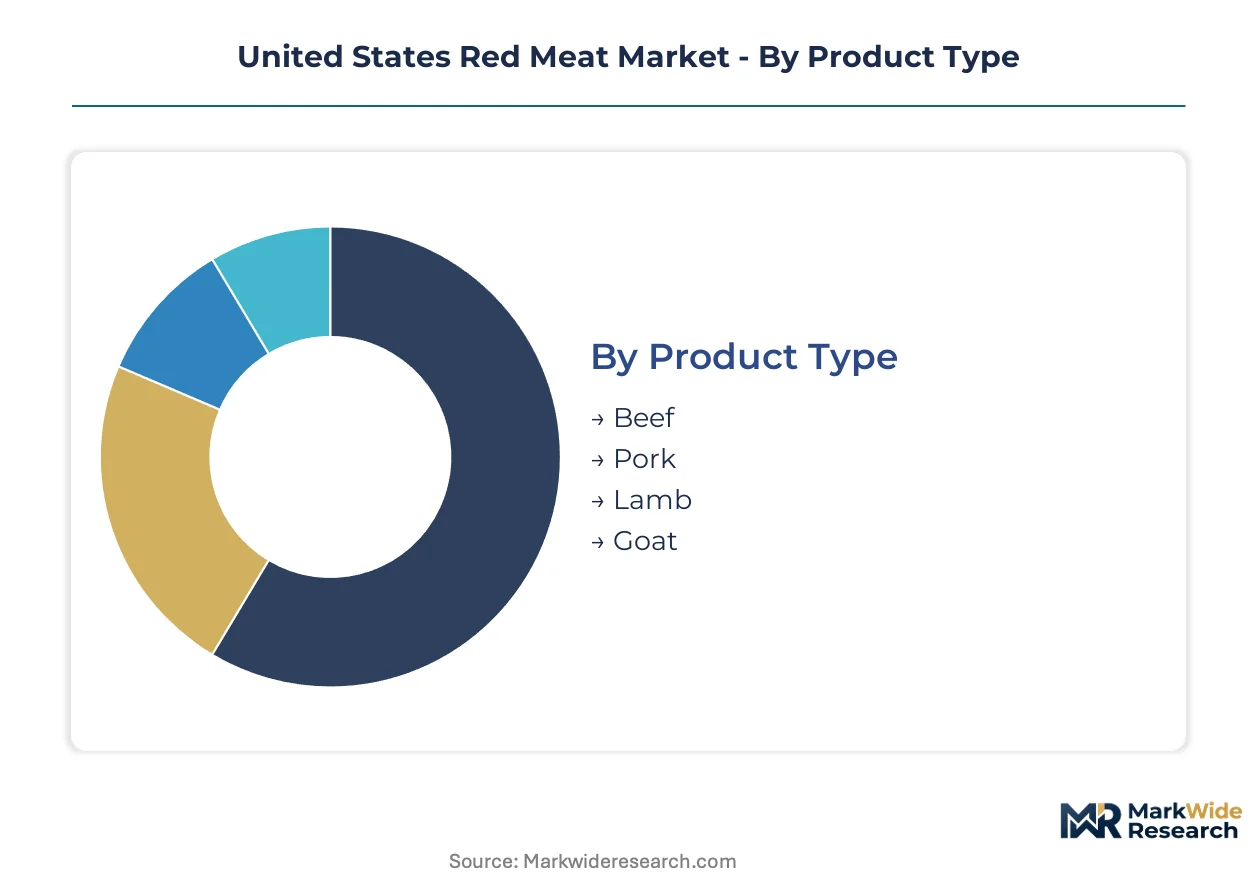
Segmentation in the United States red meat market exposes how value migrates across species, channels, and packaging formats. Understanding these divides reveals where capital deployment and procurement strategy generate differential returns.
Product Type:
Margin pools concentrate in grain-fed beef due to extended finishing cycles and USDA Prime premiums, while pork competes on lean yield efficiency and faster inventory turnover.
- Beef:Muscle tissue from cattle finished on grain rations in Texas Panhandle and Midwest feedlots, graded USDA Prime through Select based on marbling scores. Demand concentrates in full-service restaurants and premium retail cases where Prime and Choice cuts command price separation from Select. Feed grain input volatility and extended 16-24 month production cycles elevate working capital requirements.
- Pork:Carcass meat from swine raised under confinement systems optimized for lean muscle development and rapid 6-month market weight achievement. Iowa, Minnesota, and North Carolina packing plants process the majority of domestic volume. California Proposition 12 compliance mandates are redirecting sow housing investment toward certified production systems.
- Lamb:Meat from sheep typically finished on forage-based systems in Colorado, Texas, and California mountain ranges. Ethnic grocery channels and food service operators in metropolitan areas drive procurement volume.
- Goat:Chevron from animals raised on browse-based management systems, concentrated in Texas Hill Country and Southeastern states. Direct-to-consumer sales and ethnic market distributors handle most domestic supply.
Beef holds installed capacity across federally inspected packing complexes. Pork is rotating up the share rankings through lean yield efficiency and faster turnover cycles.
Distribution Channel:
Channel selection determines working capital intensity and price discovery mechanisms, with centralized procurement displacing traditional spot purchasing in protein categories.
- Supermarkets:Chain retailers operating case-ready meat departments with centralized distribution centers managing inventory risk and promotional volatility. Texas and Florida markets exhibit the strongest consolidation under fewer, larger suppliers capable of managing replenishment decisions.
- Wholesale:Boxed-beef and primal distribution to independent retailers, food service distributors, and further processors. Nebraska, Iowa, and Kansas packing concentration creates regional supply bottlenecks when labor or weather disruptions idle major complexes.
- Convenience Stores:Limited SKU protein offerings targeting immediate consumption and grab-and-go meal solutions. Pre-cooked and value-added formats dominate this channel's refrigerated case space.
- Online Retail:Rancher-owned e-commerce platforms and subscription box models bypassing traditional packer-retailer markups. Cold-chain logistics and last-mile delivery costs constrain margin capture in this emerging channel.
Supermarkets maintain the deepest cold-chain infrastructure. Online Retail is climbing the fastest as direct-to-consumer platforms capture trial in premium segments.
Packaging Type:
Packaging technology directly influences shelf-life extension, labor cost reduction, and export qualification for destination markets with strict residue and traceability requirements.
- Vacuum Packs:Modified atmosphere packaging removing oxygen to inhibit microbial growth and extend case-ready shelf life. Retailers reduce labor costs through centralized fabrication and pre-priced retail units.
- Frozen:Blast-chilled and stored product for inventory management, export shipment, and institutional procurement with extended delivery windows. Cold storage capacity constraints in peak harvest periods create logistical bottlenecks.
- Fresh:Refrigerated product maintained below 40°F through FSIS-compliant cold chain for immediate retail or food service consumption. Shorter shelf life demands precise demand forecasting and rapid inventory turnover.
- Canning:Thermally processed shelf-stable product for emergency preparedness, military procurement, and institutional feeding programs. Limited growth trajectory compared to refrigerated formats.
Vacuum Packs dominate value capture in retail channel expansion. Frozen is gaining share fastest through export market development and inventory risk management.
End User:
End-user segmentation reveals divergent quality specifications, volume contracting patterns, and certification requirements across food service and retail consumption occasions.
- Restaurants:Full-service and fast-casual operators specifying USDA grade, portion control, and consistent supply for menu execution. Menu expansion beyond chicken is pulling additional beef and pork primals through case-ready distribution channels.
- Food Services:Contract feeding operations, hospitality, and institutional procurement with standardized specifications and volume commitments. Cost management priorities favor lean yield efficiency over premium grade premiums.
- Households:Retail consumers purchasing for at-home preparation, with trading patterns shifting between premium grade splurge occasions and value-focused commodity selections. Plant-based protein substitution is pressuring ground beef volume in this segment.
- Institutions:Schools, hospitals, and correctional facilities with mandated nutritional requirements and competitive bidding procurement. Lowest-cost compliant product dominates purchasing decisions.
Restaurants command grade premiums and supply consistency. Food Services is expanding most quickly through contract feeding and hospitality sector recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across U.S. red meat demand corridors. Texas Panhandle feedlot operators absorb grain cost swings with minimal margin compression, while Northeast retail buyers trade down grades during inflationary periods. California's regulatory premium creates a bifurcated procurement landscape.
Texas-Oklahoma Panhandle
Amarillo and Hereford feedlots finish over five million head annually, drawing on local milo and distiller's grain rations. EPA Clean Water Act discharge permits constrain expansion near the Ogallala Aquifer. JBS and Cargill operate adjacent packing complexes in Plainview and Friona, capturing transportation cost advantages on grain-fed cattle.
Nebraska-Iowa Corridor
Boxed beef fabrication dominates in Grand Island, Lexington, and Sioux City plants serving Chicago and East Coast distribution. USDA Agricultural Marketing Service graders staff these facilities continuously. Labor availability at harvest floors limits line speed optimization despite automation investments.
California Central Valley
Proposition 12 compliance mandates reshape sow housing investment for pork processors accessing Los Angeles and San Francisco retail. California Department of Food and Agriculture inspectors enforce additional state-level welfare audits. Valley Meat Company and regional packers segregate compliant product flows through dedicated cold-chain infrastructure.
Southeast Atlantic
Florida and Georgia retail consolidation under Publix and Kroger banners concentrates procurement decisions in Jacksonville and Atlanta distribution centers. FSIS-inspected case-ready suppliers compete on promotional flexibility and inventory risk absorption. Smithfield Foods operates processing capacity in North Carolina to serve this channel.
Pacific Northwest
Portland and Seattle natural grocery channels command antibiotic-free and grass-fed premiums. Oregon and Washington state environmental regulations restrict feedlot expansion in Willamette Valley watersheds. Direct-to-consumer rancher platforms in Montana and Idaho bypass traditional packer markups for this buyer segment.
United States Red Meat Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the U.S. red meat value chain. The market structure concentrates kill capacity among four integrated packers controlling over eighty percent of federally inspected beef and pork volume. Two strategic archetypes dominate: vertically integrated feedlot-to-retail operators capturing margin at every production stage, and specialized pork processors optimizing lean yield efficiency through rapid inventory turnover. Competitive moves center on captive supply integration and cold-chain infrastructure expansion.
Among integrated beef and pork operators, Tyson Foods, JBS, and Cargill occupy positions spanning feedlot ownership, packing capacity, and branded retail distribution. Tyson Foods exemplifies the feedlot-to-retail archetype with infrastructure across the Texas Panhandle and Midwest. JBS represents geographic scale concentration through large-scale processing complexes in Nebraska and Colorado. Cargill anchors direct rancher procurement networks securing consistent fed cattle supply outside auction market volatility.
| Leading Market Players |
|---|
| Tyson Foods |
| Cargill |
| JBS |
| National Beef Packing |
| Hormel Foods |
| Smithfield Foods |
| Perdue Farms |
| Seaboard Foods |
| WH Group |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Texas Panhandle feedlots and Midwest packing complexes lock in supply access and price visibility, insulating integrated operators from auction market volatility while compressing margin capture for non-integrated cattle feeders. These arrangements concentrate pricing power among operators with captive supply and federally inspected cold-chain infrastructure.
Pricing Analysis
USDA grading standards dictate the pricing tier structure across Prime, Choice, and Select quality levels, with marbling scores driving price separation at retail and food service channels. Certification premiums for antibiotic-free and Proposition 12-compliant production add further differentiation layers. Cost compression in commodity Select-grade beef is intensifying because of plant-based protein substitution in ground meat categories. Households exhibit the highest price sensitivity, trading down during inflationary periods, while full-service restaurants maintain grade inelasticity for menu execution.
Supply Chain Analysis
Inventory cycles spanning 16-24 months from calf birth to harvest create extended lead times that amplify working capital intensity and margin risk exposure. Geographic supply concentration centers on Texas, Nebraska, and Iowa, where feedlot finishing capacity and packing infrastructure cluster within 500-mile corridors. The system draws from corn and soybean meal inputs, live cattle procurement, and cold-chain logistics networks. Single-source vulnerability exists in Midwest packing concentration, where weather or labor disruptions at major complexes create regional bottlenecks. Distribution runs through federally inspected plants to case-ready retail and food service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States red meat market functions as a defensive-moat industry where regulatory entrenchment through USDA inspection mandates and FSIS compliance protocols creates steep barriers to entry for new packers.
For Market Incumbents: Compound geographic dominance by expanding captive feedlot capacity in Texas-Oklahoma corridors and securing additional Proposition 12-compliant sow housing for California market access. Plant-based protein substitution threatens commodity beef trim volumes, demanding investment in branded premium tiers and direct-to-consumer channel control to defend margin position.
For New Entrants and Emerging Players: Anchor in direct-to-consumer subscription models serving Pacific Northwest natural grocery channels and Texas Hill Country ranching communities, where antibiotic-free and grass-fed premiums bypass traditional packer markups. The online retail segment offers the most penetrable white space, with cold-chain logistics partnerships as the critical go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale packers with Process Verified shield certification and existing feedlot integration, positioned for acquisition by larger integrated operators seeking geographic expansion. Long-term viability hinges on regulatory compliance infrastructure and cold-chain asset ownership. The signal to watch is California Proposition 12 enforcement intensity as a proxy for compliance cost escalation and market access restriction.
| Strategic Initiative | Industry Significance |
|---|---|
| Feedlot Capacity Expansion | Captive supply integration in Texas Panhandle reduces transportation shrink and harvest-to-chill timelines. |
| Proposition 12 Compliance Investment | Sow housing retrofitting secures shelf-space access in California's premium retail channels. |
| Direct-to-Consumer Channel Launch | Rancher-owned e-commerce platforms bypass traditional packer-retailer markup structures. |
| Blockchain-IoT Traceability Deployment | Distributed ledger systems enable source-verified origin claims for export-qualified carcasses. |
| Antibiotic-Free Certification Program | USDA Process Verified protocols command premiums in natural grocery channels. |
Research Methodology
A spread of perspectives from feedlot operators, packing complex managers, retail meat buyers, and USDA Agricultural Marketing Service graders converged on the working assumptions underpinning this analysis. Primary fieldwork with these stakeholders combined with secondary validation against USDA livestock and grain market reports, FSIS inspection data, EPA discharge permit filings, and state-level agricultural statistics. Bottom-up volume modeling across species and product types triangulated with top-down value aggregation from channel and end-user segmentation.
Segmentation dimensions modeled include product type, distribution channel, packaging format, and end-user category across the projection horizon. CAGRs were derived from historical volume trajectories adjusted for regulatory compliance cost escalations and channel shift dynamics. Forecast inputs incorporated feed grain price volatility assumptions and Proposition 12 implementation timelines without specific year anchoring.
Material uncertainties — feed grain input spikes, labor disruption at Midwest packing complexes, and accelerated plant-based protein substitution — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Organic Chicken Market
Meat Products
North America Edible Meat Market
Meat Products
Lab-Grown Meat Market
Meat Products
Saudi Arabia Red Meat Market
Meat Products
Organic Meat Market
Meat Products
Meat Tenderizer Market
Meat Products
Meat Packaging Market
Meat Products
Hot Dog and Sausages Market
Meat Products
Dehydrated Meat Products Market
Meat Products
Pork Flavors Market
Meat Products
Non-Veg Rte and Rtc Market
Meat Products
Global Poultry Meat Market
Meat Products
Low-Fat Ham Market
Meat Products
Pork Belly Meat Market
Meat Products
Kosher Beef Market
Meat Products
Saudi Arabia Edible Meat Market