
 Commercial Rotisserie Oven Market | 2026-2036
Commercial Rotisserie Oven Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Rotisserie Oven Market Outlook
The capital-intensity divergence between automated spit systems and manual batch units is unwinding competitive dynamics across the commercial rotisserie oven landscape. The Middleby Corp. leverages its broad foodservice platform to bundle rotisserie lines with kitchen automation ecosystems. Alto Shaam Inc. anchors its position through low-temperature halo heat technology that extends holding life without quality degradation. Fri-Jado BV competes on compact vertical designs optimized for European retail delis with severe space constraints.
A commercial rotisserie oven is a motorized cooking appliance that rotates meat on horizontal or vertical spits while applying controlled radiant or convection heat, typically operating between 250°F and 450°F to achieve uniform browning and internal temperature compliance. Its primary commercial purpose is high-volume production of roasted poultry and proteins for retail display or immediate service in foodservice environments. Electric units dominate urban installations where venting restrictions limit gas combustion, while hybrid configurations are gaining traction among catering operators seeking fuel flexibility across event venues. Floor-model sizes sustain the bulk of revenue given their throughput alignment with supermarket deli counters and high-volume chicken chains, though compact countertop variants are carving share in food truck and ghost kitchen deployments.
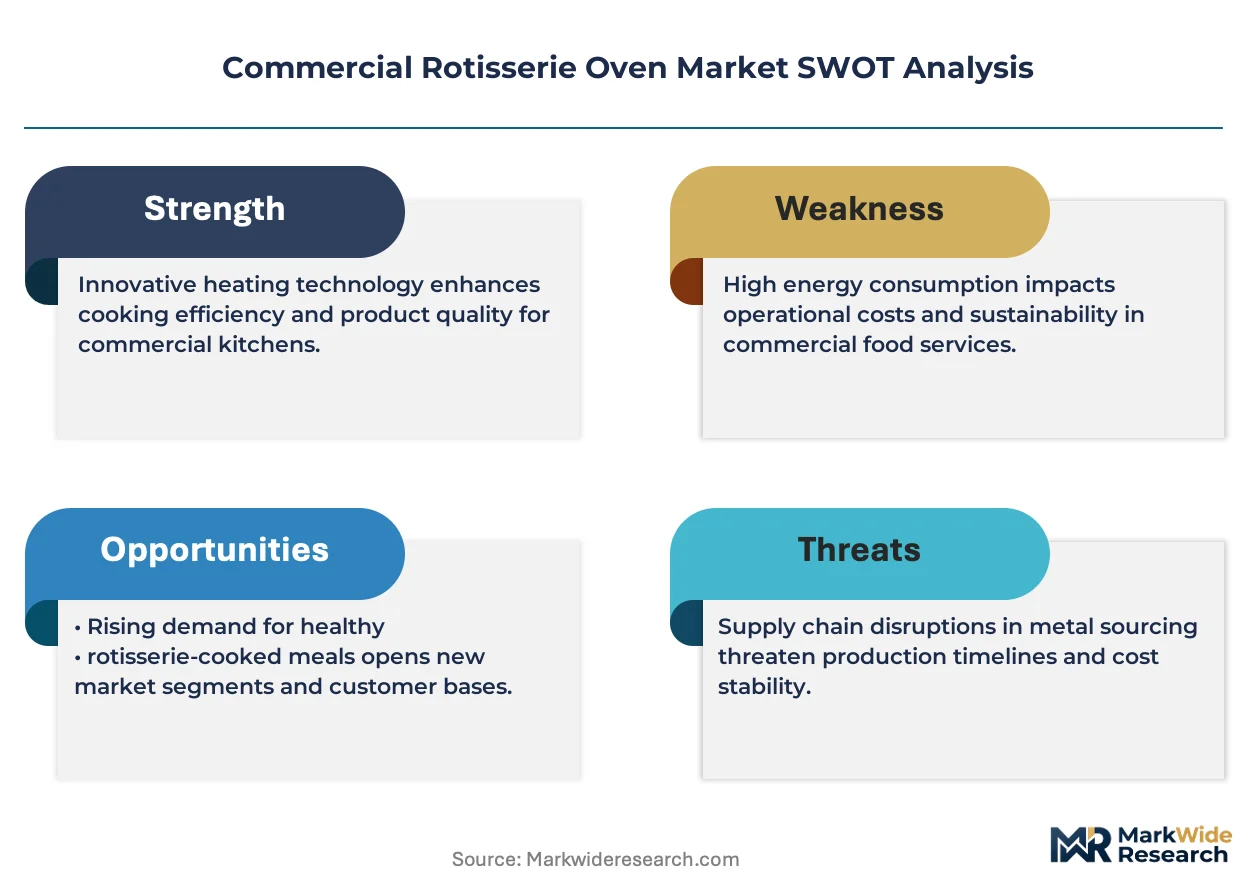
NSF International sanitation standards govern equipment approval for North American foodservice operations, while the EPA's ENERGY STAR program and EU Ecodesign requirements are tightening thermal efficiency minimums that favor infrared and combination heating technologies over traditional radiant systems. The FDA Food Code provisions on time-temperature controls and HACCP compliance further shape oven specification sheets for multi-unit restaurant buyers. Stakeholders must monitor how evolving carbon reduction mandates in California and the EU Green Deal's embodied carbon tracking will alter material sourcing and end-of-life obligations for stainless steel chassis and insulation components.
Market Dynamics
NSF International certification requirements and evolving ENERGY STAR efficiency thresholds are compressing equipment replacement cycles while favoring infrared and combination heating architectures over legacy radiant systems.
Growth Catalysts
- Quick-service restaurant chain expansion:North American and European fast-casual chicken chains are adding rotisserie SKUs to capture deli-style positioning, pulling floor-model throughput capacity into new construction pipelines.
- EU Ecodesign thermal efficiency mandates:Tightening minimum performance standards are accelerating retirement of pre-2020 radiant units and redirecting procurement toward hybrid infrared-convection platforms.
- Supermarket deli counter automation:High-volume retail operators in the United States are consolidating protein cooking into centralized rotisserie banks to reduce labor touchpoints and extend holding windows.
Market Restraints
- Stainless steel input volatility:Fluctuations in nickel and chromium prices squeeze fabrication margins for chassis and door assemblies, compressing OEM pricing flexibility.
- Venting infrastructure limitations:Urban municipalities with strict emissions codes block gas combustion installations, forcing costly electrical service upgrades or limiting site eligibility.
- Combitherm oven substitution:Multi-function convection-steam units from competing equipment categories capture budget allocations in institutional kitchens seeking menu versatility over protein specialization.
Strategic Opportunities
- Ghost kitchen penetration:Delivery-only food production facilities in dense metropolitan zones present untapped demand for compact countertop rotisserie configurations with rapid heat recovery.
- California carbon reduction mandates:The state's embodied carbon tracking requirements for commercial foodservice equipment create first-mover positioning for manufacturers with recycled-content chassis and low-GWP insulation.
- IoT-enabled predictive maintenance:Convergence of temperature logging sensors and cloud-based HACCP documentation platforms opens recurring revenue streams through subscription monitoring services.
Industry Challenges
- NSF field certification timelines:Third-party sanitation approval processes for custom configurations extend product launch windows by four to eight months, delaying revenue recognition.
- Legacy kitchen management system integration:New rotisserie controls must interface with entrenched POS and inventory platforms, requiring costly middleware development for multi-unit rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Rotisserie Oven Market |
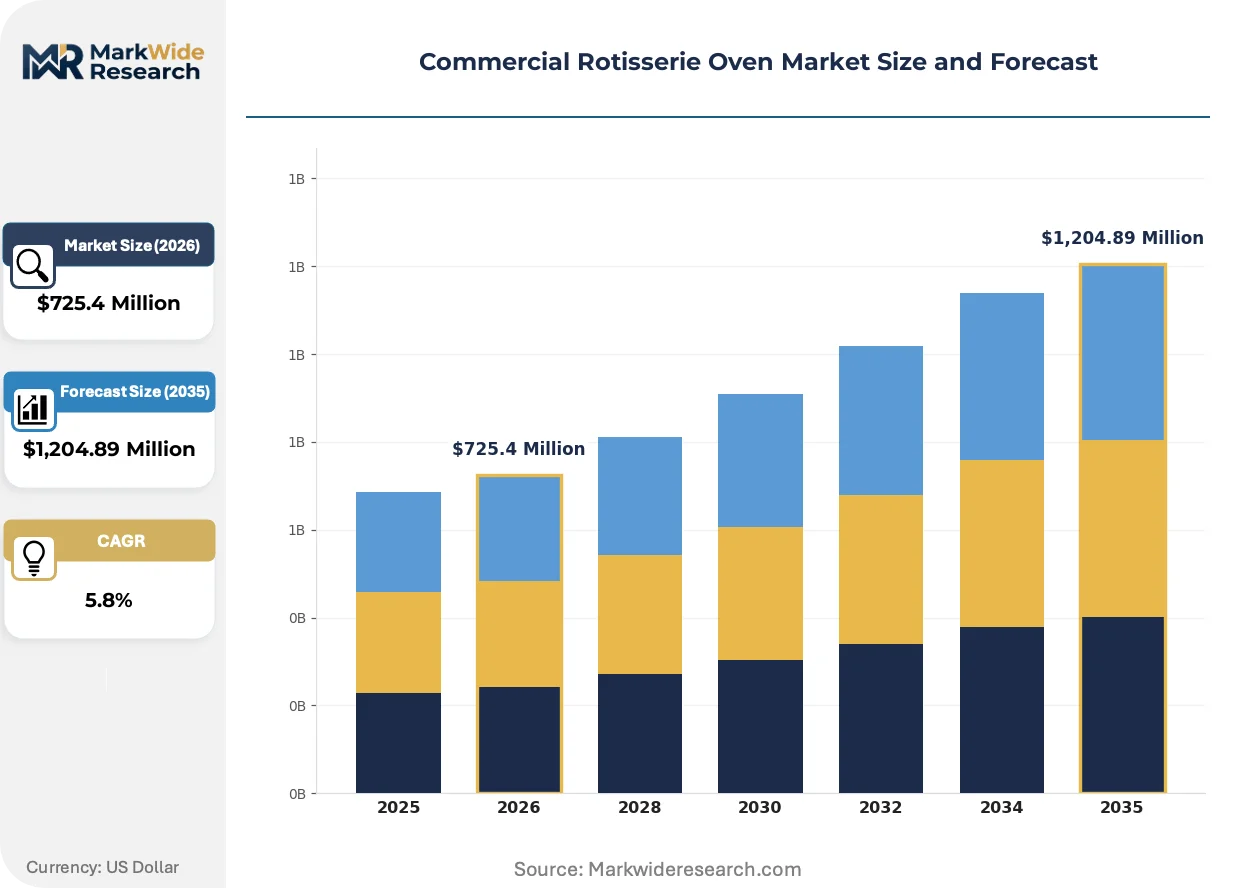
| Market Size in 2026 | $725.4 Million |
| Market Size in 2035 | $1,204.89 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas, Electric, Hybrid, Charcoal End User: Restaurants, Catering Services, Supermarkets, Food Trucks Heating Technology: Radiant, Convection, Infrared, Combination Size: Countertop, Floor Model, Compact, Large Capacity |
| Companies Covered | The Vollrath Co. LLC, Hickory Industries Inc., Alto Shaam Inc., American Range Corp., Fri-Jado BV, The Middleby Corp., Rotisol SA, J and R Manufacturing LLC, Henny Penny Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Rotisserie Oven Market Strategic Shifts
Equipment architecture is bifurcating between high-throughput automated spit systems for supermarket delis and compact vertical designs optimized for space-constrained European retail and North American ghost kitchen deployments.
Infrared emitter technology is miniaturizing. Ceramic and quartz infrared elements now deliver radiant heat density previously requiring larger combustion chambers, enabling reduced cavity footprints without sacrificing browning uniformity. Food truck operators and stadium concessionaires are adopting these compact platforms at accelerating rates. The technology is miniaturizing equipment form factors and opening addressable demand in venues previously excluded by spatial constraints.
EPA ENERGY STAR Version 3.0 commercial cooking specifications are tightening idle energy limits and test procedure rigor. Manufacturers must redesign insulation packages and control algorithms to maintain certification eligibility. Floor-model electric units targeting supermarket deli chains face the steepest compliance burden, driving accelerated R&D spending on vacuum panel insulation and adaptive fan control.
Buyers are unbundling after-sales service from equipment procurement. Multi-unit restaurant groups now contract independent service organizations for preventive maintenance rather than accepting OEM service bundles. This fragmentation concentrates in the United States, where third-party technician networks have achieved density sufficient to undercut factory service pricing by twenty to thirty percent. OEMs respond with remote diagnostics subscriptions to retain customer touchpoints.
Commercial Rotisserie Oven Market Segmentation
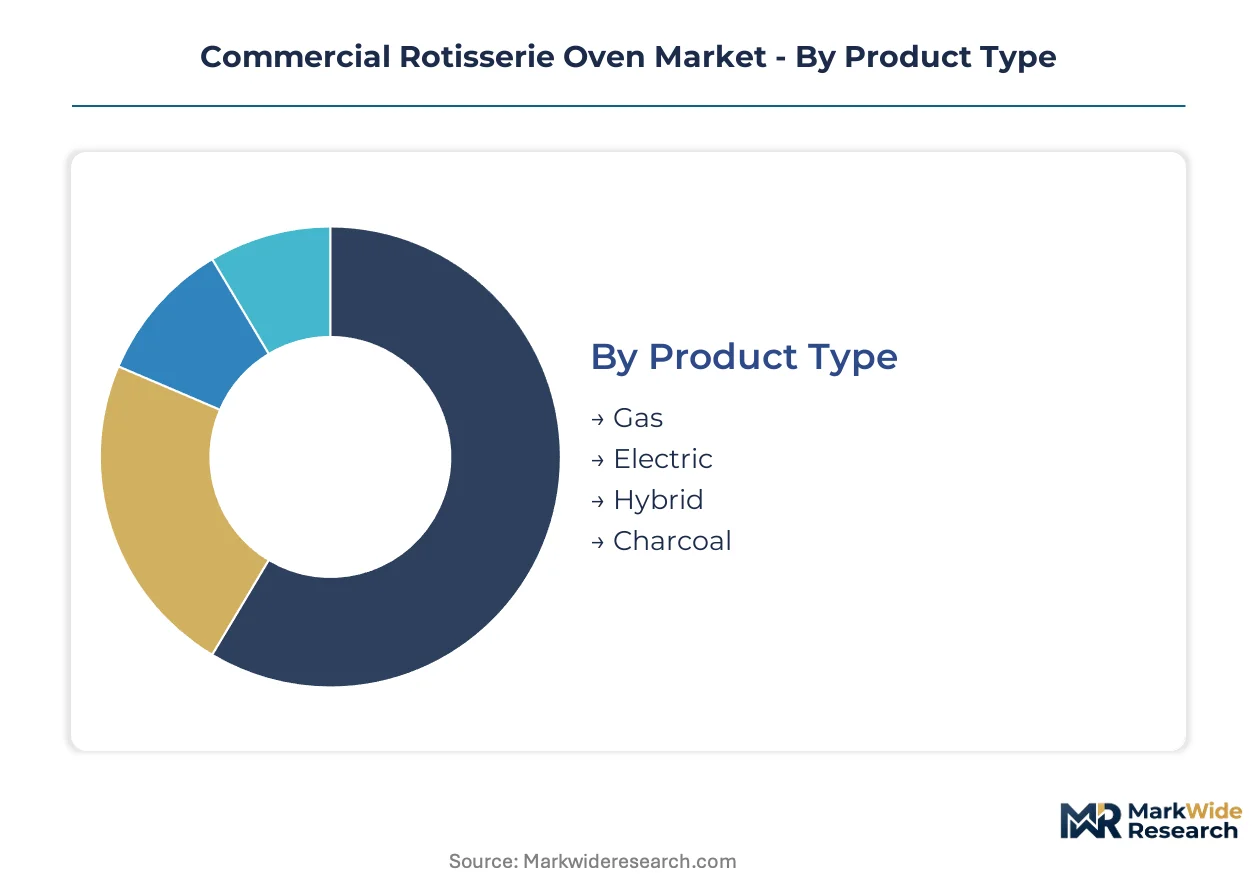
Segmentation in the commercial rotisserie oven market reveals how equipment specifications align with operational constraints across distinct venue types. Buyers prioritize fuel access, throughput requirements, and spatial limitations when selecting configurations, creating tiered margin pools that favor specialized manufacturers.
Product Type:
Margin pools concentrate in electric and hybrid configurations where regulatory compliance and fuel flexibility command pricing premiums.
- Electric:These units rely on resistive or infrared heating elements powered by grid electricity, eliminating combustion venting requirements. Urban supermarkets in the United States favor electric floor models where municipal emissions codes restrict gas infrastructure, though electrical service upgrades add installation cost.
- Gas:Propane or natural gas combustion delivers faster heat recovery and lower operating costs in regions with favorable utility rates. High-volume chicken chains in Texas and the Southeast deploy gas units where venting permits remain accessible and throughput demands justify the infrastructure investment.
- Hybrid:Dual-fuel architectures allow operators to switch between gas and electric heating based on venue constraints or utility pricing. Catering companies serving multiple event locations value this adaptability when site conditions vary unpredictably.
- Charcoal:Traditional combustion of hardwood charcoal imparts distinct smoke flavor profiles prized by specialty barbecue concepts. Limited commercial adoption outside niche ethnic restaurant segments constrains volume.
The dominant share belongs to electric units, while hybrid configurations are closing the gap fastest as fuel flexibility becomes a procurement priority.
End User:
Volume concentration and replacement frequency diverge sharply across venue types, with supermarkets and chain restaurants driving the bulk of equipment turnover.
- Restaurants:Fast-casual chicken chains and independent rotisserie concepts require consistent batch capacity for menu execution. Chains with 50-plus locations standardize on floor-model specifications to simplify training and maintenance protocols.
- Supermarkets:Deli counter operations demand high-throughput automated systems with extended holding capabilities. United States retail operators consolidate protein cooking into centralized rotisserie banks to reduce labor touchpoints.
- Catering Services:Mobile and event-based food production prioritizes equipment portability and rapid setup. Rental fleets and independent caterers favor compact units with quick heat recovery between service periods.
- Food Trucks:Severe spatial constraints and electrical load limitations shape specification requirements. Operators in dense metropolitan zones adopt compact vertical designs or infrared miniaturized platforms previously excluded by footprint.
Supermarket deli operations anchor procurement volume, though food truck deployments are expanding most quickly as mobile foodservice proliferates.
Heating Technology:
Technology selection determines energy efficiency certification eligibility and operating cost profiles across regulatory jurisdictions.
- Infrared:Ceramic and quartz emitters deliver radiant heat density with reduced cavity volume requirements. EPA ENERGY STAR Version 3.0 specifications favor infrared architectures for their superior idle energy performance.
- Combination:Hybrid infrared-convection platforms merge radiant browning with forced-air circulation for accelerated cook times. EU Ecodesign mandates are redirecting procurement toward these systems as minimum thermal efficiency standards tighten.
- Radiant:Traditional metal-sheathed heating elements or gas burners provide baseline performance at lower capital cost. Pre-2020 radiant units face accelerated retirement as efficiency thresholds rise.
- Convection:Forced-air circulation systems reduce cook times through enhanced heat transfer coefficients. Institutional kitchens sometimes substitute combination ovens for dedicated rotisserie units when menu versatility outweighs protein specialization.
Combination systems hold the technology lead, while infrared miniaturization is gaining share fastest in space-constrained deployments.
Size:
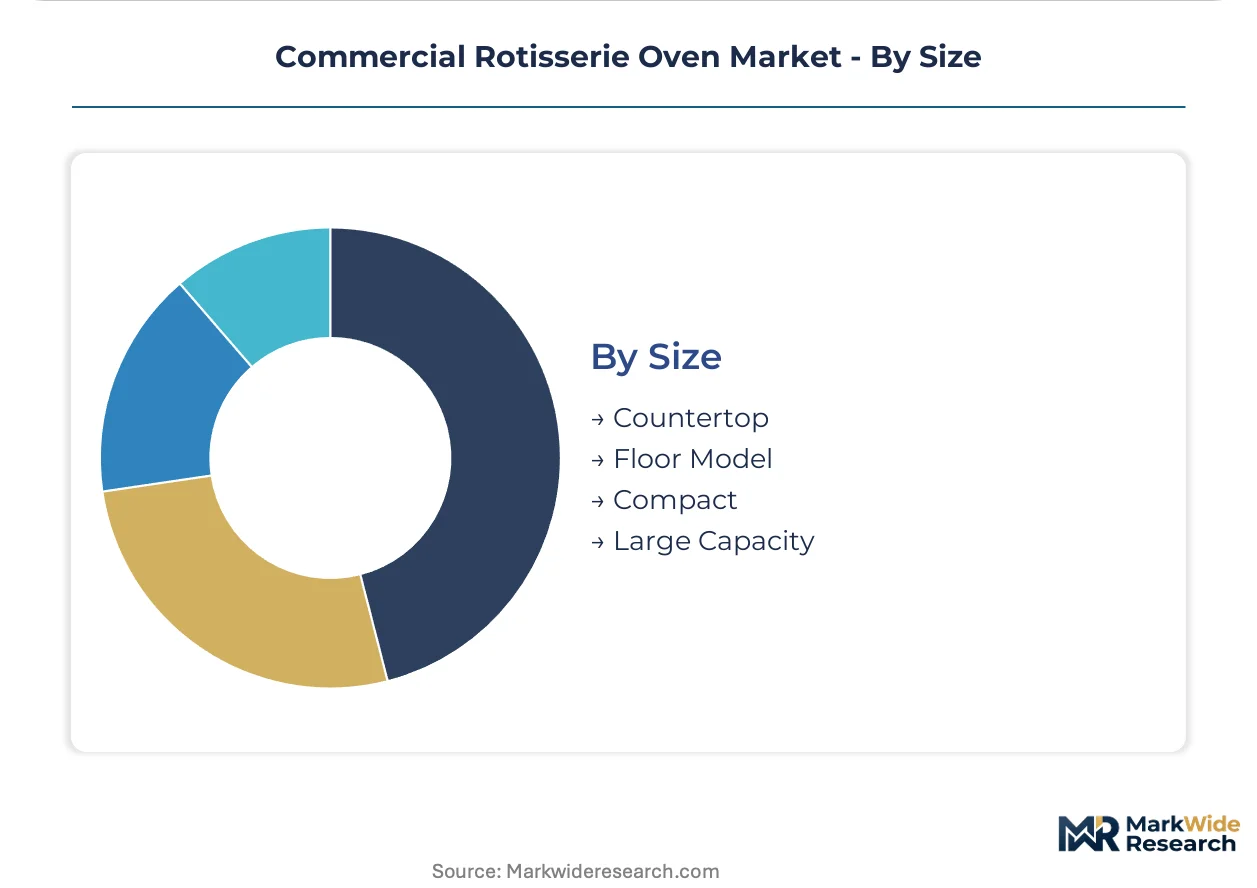
Physical form factor dictates addressable venue types and installation complexity, with floor models sustaining revenue concentration.
- Floor Model:Full-height units with multiple spit capacity serve high-volume production environments. United States supermarket chains and fast-casual chicken operators specify these configurations for throughput alignment.
- Compact:Reduced-footprint vertical designs optimize for European retail delis with severe space constraints. Ghost kitchen operators in dense metropolitan zones are adopting these formats for delivery-only production.
- Countertop:Surface-mounted units with limited capacity suit low-volume or auxiliary cooking applications. Food trucks and stadium concessionaires deploy these where spatial constraints exclude larger equipment.
- Large Capacity:Industrial-scale systems with automated loading and batch sequencing serve centralized commissary operations. Limited buyer pool constrains segment expansion.
Floor models dominate installed base, though compact formats are climbing the fastest as urban real estate costs reshape venue economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States supermarket deli operators deploy floor-model rotisserie banks for centralized protein production, while European retailers favor compact vertical units that navigate tighter spatial constraints. This consumption-mix differential reflects divergent real estate economics and labor models across Atlantic markets.
United States
Fast-casual chicken chains and supermarket deli counters drive equipment turnover, with chains standardizing specifications across 50-plus locations. EPA ENERGY STAR Version 3.0 idle energy limits accelerate replacement of pre-2020 radiant units. Texas and Southeast regional operators maintain gas combustion preference where venting permits remain accessible.
Germany
Retail deli operators in dense urban centers prioritize compact electric configurations compliant with municipal emissions codes. EU Ecodesign thermal efficiency mandates redirect procurement toward hybrid infrared-convection platforms. Industrial equipment fabricators in Baden-Württemberg supply precision-engineered chassis to OEMs serving pan-European distribution.
United Kingdom
Supermarket chains consolidate hot food production into centralized commissary rotisserie operations, reducing in-store labor touchpoints. CE marking and UKCA post-Brexit conformity requirements extend product launch timelines for imported equipment. Greater London ghost kitchen operators pilot countertop infrared miniaturized platforms for delivery-only production.
France
Specialty poultry retailers and upscale supermarket banners maintain demand for traditional rotisserie presentation formats. REACH chemical safety regulations govern insulation material specifications and stainless steel surface treatments. Île-de-France catering operators adopt hybrid dual-fuel units for event venue flexibility across unpredictable site conditions.
Netherlands
Compact vertical designs dominate retail deli installations where severe space constraints limit equipment footprint. EU Green Deal embodied carbon tracking requirements create procurement preference for manufacturers with recycled-content chassis. Randstad region equipment distributors maintain dense service technician networks that undercut OEM factory service pricing.
Commercial Rotisserie Oven Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrated among platform players bundling rotisserie lines with broader kitchen automation ecosystems. The middle tier fragments across heating technology specialists, compact design innovators, and regional fabrication houses serving localized certification requirements. Three archetypes define competitive positioning: integrated platform providers, low-temperature holding technology specialists, and space-optimized vertical design experts. M&A activity concentrates on automation capability acquisition, while R&D investment flows toward IoT-enabled predictive maintenance and ENERGY STAR compliance redesign.
Within the integrated platform tier, The Middleby Corp. exemplifies scale-driven ecosystem bundling. Among specialists, Alto Shaam Inc. occupies a position anchored by proprietary low-temperature holding technology. Fri-Jado BV represents the compact vertical design archetype optimized for European spatial constraints. These three companies illustrate how divergent technical specializations carve defensible positions despite overlapping end-user segments.
| Leading Market Players |
|---|
| The Vollrath Co. LLC |
| Hickory Industries Inc. |
| Alto Shaam Inc. |
| American Range Corp. |
| Fri-Jado BV |
| The Middleby Corp. |
| Rotisol SA |
| J and R Manufacturing LLC |
| Henny Penny Corp. |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts with stainless steel mills lock in chassis material access and insulate OEMs from nickel price volatility. These agreements extend twelve to thirty-six months and bind rotisserie manufacturers to minimum volume commitments in exchange for fixed input pricing.
Pricing Analysis
After-sales service contracts drive lifetime value beyond equipment sale margins. Three-tier pricing structure across premium NSF-certified, standard commercial-grade, and economy non-certified levels separates buyers by operational scale and regulatory exposure. Pricing pressure stems from third-party service organizations undercutting OEM maintenance bundles by twenty to thirty percent in dense metropolitan markets. Independent restaurant groups exhibit highest price sensitivity due to capital constraints, while supermarket chains prioritize total cost of ownership over upfront equipment cost.
Supply Chain Analysis
Inventory buffers for ceramic infrared emitters and quartz heating elements stretch lead times when Asian component suppliers face production constraints. Stainless steel chassis fabrication centers on China, Italy, and the United States, with control systems and sensor assemblies sourcing from Taiwan and Germany. Supply chain risk concentrates in single-source dependency for specialized high-temperature insulation materials. Distribution runs through regional foodservice equipment dealers and direct OEM sales forces serving multi-unit chain accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commercial rotisserie oven market sits in early-cycle recovery as post-pandemic foodservice capital expenditure resumes across North American and European markets.
For Market Incumbents: Compound defensive positioning by acquiring IoT-enabled predictive maintenance capabilities before independent service organizations capture recurring revenue streams. Deepen backward integration into stainless steel chassis fabrication to offset nickel price volatility squeezing margins. Prioritize ENERGY STAR Version 3.0 certification investment to maintain eligibility for supermarket procurement pipelines. For New Entrants and Emerging Players: Anchor in ghost kitchen infrastructure buildouts across dense metropolitan zones where compact vertical rotisserie configurations face limited incumbent saturation. Target California's carbon reduction mandates with recycled-content chassis and low-GWP insulation to capture first-mover positioning against legacy OEMs. Pursue equipment-as-a-service subscription models to bypass upfront capital barriers constraining independent restaurant buyers. For Investors and Strategic Acquirers: Capital is best deployed toward compact-design specialists with proven European retail penetration and adaptable manufacturing footprints. Over a five-to-ten-year horizon, equipment automation capabilities and regulatory compliance expertise determine acquisition value. Monitor NSF field certification timeline compression as signal of operational scalability among target assets.| Strategic Initiative | Industry Significance |
|---|---|
| IoT-Enabled Predictive Maintenance Platform | Cloud-based HACCP documentation creates recurring revenue streams independent of equipment sales cycles. |
| Recycled-Content Chassis Development | EU Green Deal embodied carbon tracking requirements favor manufacturers with circular material sourcing. |
| Compact Vertical Design Expansion | European retail delis and North American ghost kitchens face severe spatial constraints excluding floor models. |
| Hybrid Infrared-Convection R&D Investment | EU Ecodesign thermal efficiency mandates redirect procurement away from legacy radiant heating architectures. |
| Third-Party Service Network Partnership | Independent technician density in the United States undercuts OEM service pricing and fragments customer touchpoints. |
Study Parameters
Initial hypotheses were tested against primary input from supermarket deli operations directors, fast-casual chain procurement executives, foodservice equipment dealers, and aftermarket service technicians and refined through secondary validation against NSF International certification databases, EPA ENERGY STAR product listings, EU Ecodesign regulatory filings, and customs trade data on stainless steel component flows. Bottom-up equipment shipment estimates triangulated against top-down foodservice construction spending patterns.
Variance decomposition across product type, heating technology, end-user venue, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segmented growth rate reconciliation against macro foodservice capital expenditure trends. Forecast inputs incorporated ENERGY STAR compliance redesign timelines and EU Green Deal carbon tracking implementation phases.
Decision-makers should treat outputs as directional under assumptions of stable nickel pricing and continued municipal emissions code tightening; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Automatic Popcorn Machine Market
Food Service Equipment
Warewashing Professional Equipment Market
Food Service Equipment
Global Frozen Drink Machines Market
Food Service Equipment
Gas Smoker Market
Food Service Equipment
Cooking Hood Market
Food Service Equipment
Food Service Equipment Market
Food Service Equipment
Combi Cooler Market
Food Service Equipment
Sheet Pan Racks Market
Food Service Equipment
Electric Commercial Deep Fryers Market
Food Service Equipment
Germany Countertop Ice Makers Market
Food Service Equipment
North America Commercial Dishwashers Market
Food Service Equipment
Popcorn Machine Market
Food Service Equipment
Slow Cooker and Sous Vide Market
Food Service Equipment
Scroll Chiller Market
Food Service Equipment
Global Refrigerated Display Cases and Chilled Rooms Market
Food Service Equipment
Europe Commercial Dishwashers Market