
 United Arab Emirates Edible Meat Market | 2026-2036
United Arab Emirates Edible Meat Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Edible Meat Market Analytics
Supermarket distribution in the UAE is fragmenting as e-commerce platforms and specialty halal butchers capture share from traditional retail. Al Islami Foods leverages its vertically integrated supply chain to sustain freshness guarantees across Emirates. Tanmiah Food Company anchors its position through controlled-environment poultry farming in Saudi Arabia with cross-border distribution into the UAE. Americana Group competes via centralized procurement for its quick-service restaurant network.
Edible meat in the UAE context encompasses fresh, chilled, frozen, and processed protein derived from halal-slaughtered livestock and aquaculture, governed by Islamic dietary law and microbial safety thresholds. The primary commercial purpose centers on supplying protein to a population where per capita consumption ranks among the highest in the Middle East. Chicken dominates product type volume due to price accessibility and shorter production cycles, while beef commands concentrated margin pools in premium retail and hotel channels. The food service end user segment exhibits the fastest structural expansion, driven by Dubai's hospitality project pipeline and inbound tourism recovery.
MOHAP enforces halal certification and veterinary inspection protocols for all imported and domestically produced meat, while the UAE's General Secretariat of the Executive Council coordinates federal food security mandates that incentivize local aquaculture and poultry capacity. These frameworks elevate compliance costs for entrants but protect incumbent suppliers with established certification infrastructure. Stakeholders must monitor evolving import dependency ratios and domestic production subsidy thresholds to calibrate capacity investments against policy-driven supply shifts.
Market Dynamics
The UAE's edible meat sector is restructuring around federal food security mandates that incentivize domestic poultry and aquaculture capacity while import dependency ratios remain elevated. This tension between localization targets and established supply corridors defines competitive positioning for incumbents and entrants alike.
Growth Catalysts
- Dubai's hospitality project pipeline:Hotel and resort construction is expanding procurement volumes for premium beef and lamb, with food service distributors scaling cold-chain capacity to serve new properties.
- MOHAP halal certification harmonization:Streamlined veterinary inspection protocols for cross-border meat shipments are reducing clearance times at Jebel Ali and Abu Dhabi ports.
- Controlled-environment poultry farming:Investment in climate-controlled production facilities is shortening supply chains for fresh chicken and reducing refrigeration costs.
Market Restraints
- Feed grain import dependency:Domestic poultry operations rely on soybean and corn shipments from Argentina and Brazil, exposing margins to currency fluctuations and shipping disruptions.
- Water scarcity constraints:Aquaculture expansion faces hard limits from groundwater depletion and desalination energy costs, capping local fish production scale.
- Land availability for ruminant farming:Cattle and sheep production remains structurally constrained by desert geography, perpetuating reliance on Australian and Indian live imports.
Strategic Opportunities
- Ras Al Khaimah food security zone:Federal subsidies for processing and logistics infrastructure in northern emirates offer lower-cost entry points than Dubai or Abu Dhabi.
- Cell-cultured protein regulatory pathway:MOHAP's emerging framework for novel protein approval creates first-mover positioning for alternative meat developers.
- E-commerce halal butchery platforms:Direct-to-consumer subscription models for fresh meat delivery are capturing share from supermarket deli counters.
Industry Challenges
- Veterinary microbiologist talent pipeline:MOHAP certification requirements for halal slaughter supervision outpace local training program output, creating hiring bottlenecks.
- Cold-chain capex intensity:Blast freezing and controlled-atmosphere storage requirements for premium beef aging demand capital commitments that strain mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Edible Meat Market |
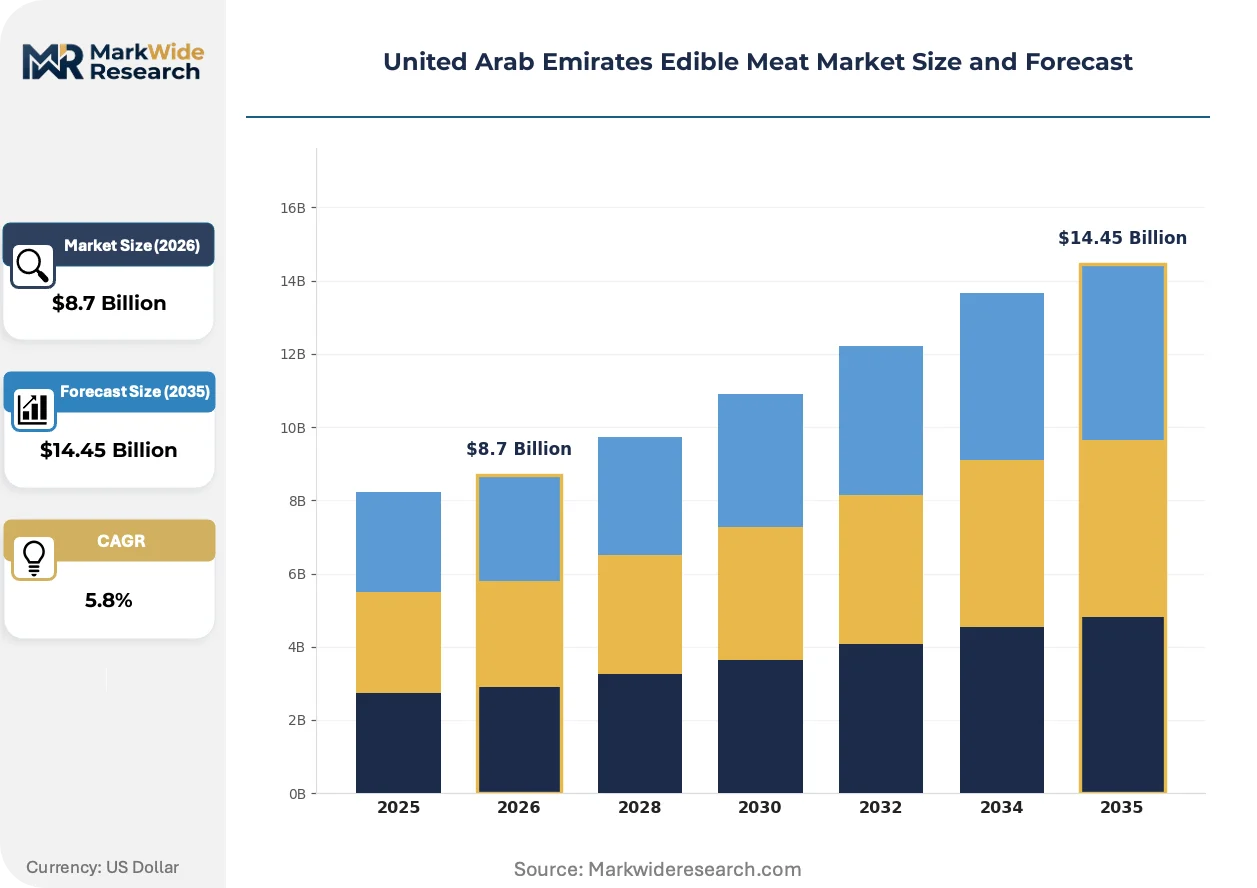
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Chicken, Lamb, Fish End User: Retailers, Restaurants, Food Service, Households Distribution Channel: Supermarkets, Online, Wholesale, Specialty Stores Packaging Type: Vacuum Sealed, Canned, Tray Pack, Bulk |
| Companies Covered | Al Islami Foods, Tanmiah Food Company, Al Ain Farms, The Savola Group, Siniora Food Industries Company, BRF S.A., Americana Group, Al Kabeer, JBS S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Edible Meat Market Evolving Landscape
Technology adoption and regulatory evolution are compressing traditional supply timelines while new distribution channels fragment established retail hierarchies. Three forces are actively restructuring how protein reaches UAE consumers.
Blockchain-enabled halal traceability platforms are rendering obsolete paper-based certification chains that previously required multiple intermediaries. Emirates-based logistics providers are deploying distributed ledger systems to verify slaughter-to-shelf compliance for hotel procurement teams. This transparency compression is eliminating information asymmetry premiums that legacy traders commanded.
MOHAP's 2023 microbial safety threshold revisions for chilled meat imports are forcing suppliers to upgrade packaging and temperature monitoring equipment. The regulation tightens allowable variance in cold-chain documentation, with Dubai Municipality conducting spot inspections at hotel receiving docks. Australian and Brazilian exporters are responding by investing in real-time IoT sensors for container shipments.
Hotel group procurement teams are consolidating supplier relationships around vertically integrated halal processors capable of certifying entire product lines. This buyer concentration is squeezing fragmented traders who previously mixed sources. The shift is most visible in Dubai's luxury hospitality segment, where procurement directors now mandate single-source traceability for banquet and restaurant operations.
United Arab Emirates Edible Meat Market Segmentation
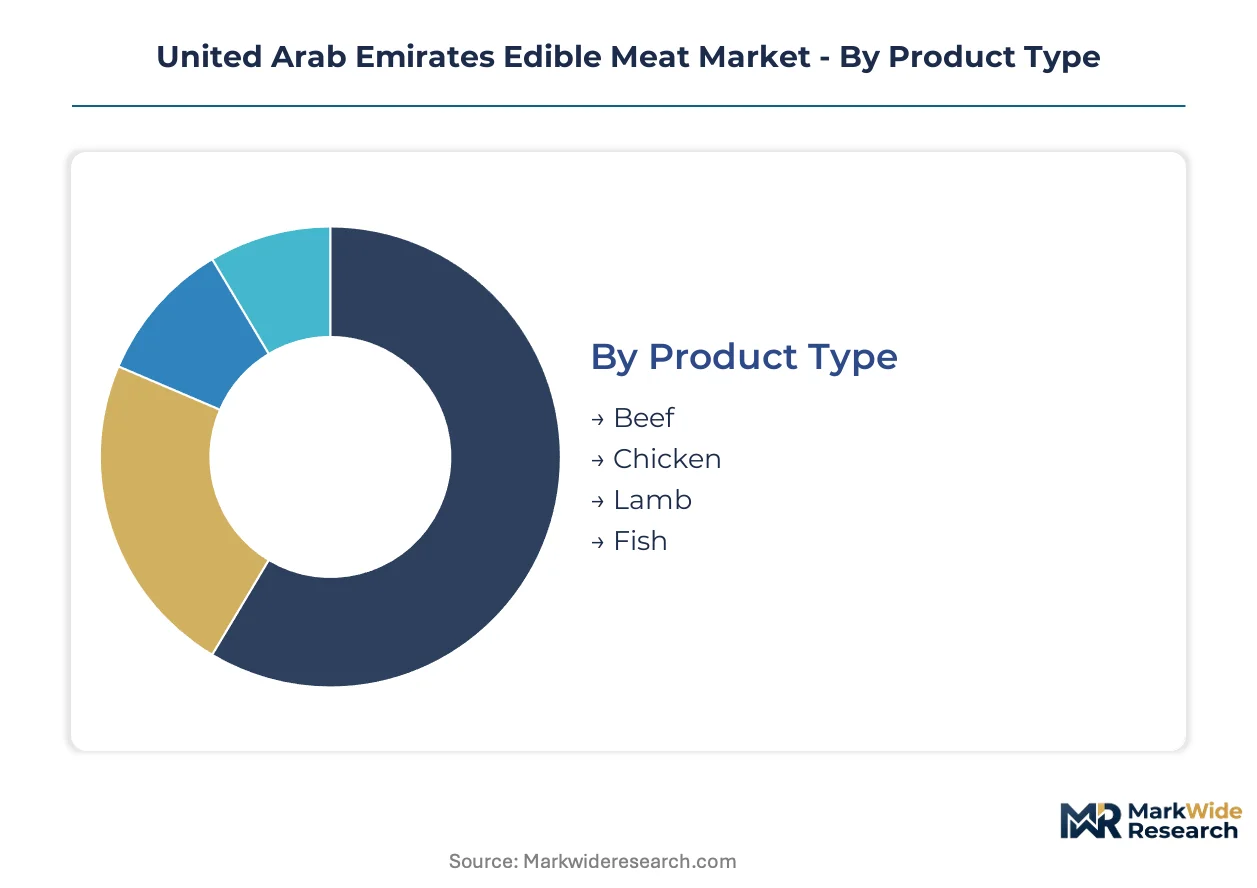
Segmentation in the UAE edible meat market reveals how protein flows through distinct procurement channels, each governed by halal certification requirements, cold-chain infrastructure, and buyer concentration patterns. Understanding these divisions exposes where margin pools concentrate and where supply-side investments yield defensive positioning.
Product Type:
Cost tier differentiation separates commodity proteins from premium-margin categories, with production cycle length and import dependency shaping competitive dynamics.
- Beef:Grain-fed and grass-fed varieties command concentrated margin pools in Dubai's luxury hotel channels. Australian and Brazilian chilled beef dominates premium retail, with dry-aging requirements extending value-added processing opportunities for local distributors serving Jumeirah and Downtown Dubai properties.
- Chicken:Broiler production cycles of 35-42 days enable price accessibility that anchors volume across all Emirates. Domestic controlled-environment farming in Al Ain and cross-border supply from Saudi operations are compressing clearance times for fresh slaughter, displacing frozen imports in supermarket channels.
- Lamb:Australian live imports and Indian mutton supply religious festival demand peaks.
- Fish:Local aquaculture in Fujairah and Umm Al Quwain supplies hamour and seabream to food service.
Chicken commands the established base. The steepest expansion runs through beef as hospitality procurement scales.
End User:
Application-based demand concentration shows how protein specifications diverge between institutional buyers with traceability mandates and price-sensitive household consumers.
- Restaurants:Fine-dining and casual-dining operators in Dubai's DIFC and City Walk districts specify halal-certified aged beef and bespoke cuts. Central kitchen procurement for multi-outlet groups is consolidating supplier relationships around single-source traceability platforms.
- Food Service:Hotel banquet operations and airline catering require volume-scale halal certification with documented cold-chain custody. Jebel Ali-based distributors are scaling blast-freezing capacity to serve Emirates airline and international hotel group procurement teams.
- Retailers:Supermarket deli counters and e-commerce platforms compete on freshness guarantees and delivery speed.
- Households:Traditional souk purchases and bulk buying during Ramadan concentrate in Deira and Sharjah corridors.
Food Service commands the established base. The steepest expansion runs through Restaurants as Dubai's hospitality project pipeline matures.
Distribution Channel:
Customer-type fragmentation across procurement interfaces is compressing legacy supermarket dominance as digital platforms and specialized halal butchers capture share.
- Supermarkets:Carrefour, Lulu, and Union Coop anchor volume through chilled meat counters and private-label frozen lines. These retailers are defending position by integrating blockchain traceability displays that verify slaughter-to-shelf compliance for MOHAP audit readiness.
- Online:Direct-to-consumer subscription models and quick-commerce platforms are capturing urban household demand in Dubai Marina and Abu Dhabi Reem Island. Same-day delivery guarantees for fresh halal chicken are displacing weekly supermarket trips among expatriate professionals.
- Wholesale:Jebel Ali Free Zone traders supply food service distributors and re-export markets.
- Specialty Stores:Independent halal butchers in Satwa and Al Ain serve ethnic community preferences for specific slaughter methods.
Supermarkets command the established base. The steepest expansion runs through Online as last-mile cold-chain infrastructure densifies.
Packaging Type:
Supply concentration across packaging formats reflects shelf-life extension requirements and retail presentation standards that vary by protein type and destination channel.
- Vacuum Sealed:Modified-atmosphere packaging extends chilled beef and lamb retail shelf life from 7 to 21 days, enabling Australian and Brazilian exporters to serve UAE premium retail without frozen degradation. MOHAP's microbial safety threshold revisions are accelerating IoT sensor integration for temperature variance documentation.
- Tray Pack:Polystyrene and recyclable fiber trays with absorbent pads dominate fresh chicken presentation in supermarket deli counters. Local poultry processors in Al Ain are automating tray-sealing lines to match European retail presentation standards for Carrefour and Lulu private-label programs.
- Canned:Corned beef and luncheon meat supply emergency stockpiling and military procurement.
- Bulk:Frozen blocks and carcass quarters serve wholesale redistribution and food service processing.
Vacuum Sealed commands the established base. The steepest expansion runs through Tray Pack as domestic poultry automation scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal food security incentives are reshaping procurement geography across the Emirates, concentrating investment in processing infrastructure and controlled-environment production zones. Dubai and Abu Dhabi anchor demand volume, while northern emirates capture subsidy-driven capacity expansion.
Dubai
Hospitality procurement from Jumeirah and Downtown Dubai properties drives premium beef and lamb volumes. Dubai Municipality enforces MOHAP-aligned cold-chain inspections at hotel receiving docks. Jebel Ali Free Zone distributors are scaling blast-freezing capacity to serve Emirates airline and international hotel group procurement teams.
Abu Dhabi
Government-backed food security investments concentrate in Al Ain controlled-environment poultry facilities. The Abu Dhabi Agriculture and Food Safety Authority coordinates federal subsidy programs for local protein production. Khalifa Industrial Zone processing plants serve retail chains across the emirate with automated tray-sealing operations.
Sharjah
Traditional souk corridors and bulk Ramadan purchasing sustain household demand for fresh chicken and mutton. The Sharjah Chamber of Commerce supports SME halal butcheries through logistics infrastructure grants. Industrial zones near Sharjah International Airport host re-export cold storage serving GCC markets.
Northern Emirates
Ras Al Khaimah food security zone subsidies attract lower-cost processing entrants than Dubai or Abu Dhabi. Federal incentives for aquaculture expansion target Fujairah and Umm Al Quwain hamour and seabream production. Local fish farms supply food service distributors with same-day freshness guarantees.
United Arab Emirates Edible Meat Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated halal processors capable of certifying entire product lines. Three strategic archetypes dominate: domestic poultry operators with controlled-environment farms, GCC-based cross-border distributors leveraging Saudi production capacity, and multinational traders supplying frozen commodity proteins. Competitive moves center on cold-chain infrastructure investment and single-source traceability platform deployment.
Within the vertically integrated tier, Al Islami Foods and Tanmiah Food Company exemplify supply chain control strategies. Al Islami leverages Emirates-based processing infrastructure to sustain freshness guarantees across retail channels. Tanmiah anchors positioning through Saudi-controlled poultry farming with cross-border distribution into UAE food service. Americana Group occupies the food service procurement vector through centralized sourcing for its quick-service restaurant network.
| Leading Market Players |
|---|
| Al Islami Foods |
| Tanmiah Food Company |
| Al Ain Farms |
| The Savola Group |
| Siniora Food Industries Company |
| BRF S.A. |
| Americana Group |
| Al Kabeer |
| JBS S.A. |
| Others |
Value Network & Pricing Analysis
Feed grain import dependency from Argentina and Brazil determines both margin compression in domestic poultry operations and the three-tier pricing structure separating premium Australian chilled beef from standard Saudi-cross-border chicken and economy frozen block imports. This single-source agricultural exposure forces local processors to absorb currency-driven cost volatility while hotel procurement teams extract traceability premiums at the top tier.
Pricing Analysis
Halal certification tier creates the primary spread between Jumeirah hotel-grade Australian dry-aged beef and supermarket private-label frozen lines. Three-tier pricing structure across premium, standard, and economy levels stratifies by cold-chain documentation depth, with blockchain-verified single-source products commanding substantial premiums over blended-origin alternatives. Cost compression in the standard tier is intensifying because Brazilian exporters are upgrading IoT sensor infrastructure to meet MOHAP's tightened microbial safety thresholds. Household consumers in Deira and Sharjah corridors exhibit the highest price sensitivity, while Dubai luxury hospitality procurement teams prioritize documented slaughter-to-shelf custody over per-kilogram cost.
Supply Chain Analysis
Tariff exposure between Brazil and the UAE dominates risk planning for frozen beef traders operating through Jebel Ali Free Zone. Geographic supply concentration centers on Australia for premium chilled beef, Saudi Arabia for cross-border fresh poultry, and Brazil for frozen commodity proteins. Raw material dependencies draw from Argentine soybean meal, Brazilian corn shipments, and Australian live sheep. Single-source vulnerability persists in veterinary microbiologist talent for MOHAP slaughter supervision. Distribution runs through vertically integrated halal processors serving hotel procurement directly, bypassing fragmented traditional traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MOHAP's emerging cell-cultured protein regulatory pathway signals a technological inflection that will restructure competitive boundaries and create first-mover premiums for alternative protein developers.
For Market Incumbents: Entrench market position through backward integration into controlled-environment poultry farming in Al Ain and Ras Al Khaimah food security zones. Invest in blockchain-enabled halal traceability platforms to defend against e-commerce halal butcheries capturing urban household demand. Prioritize certification infrastructure that streamlines MOHAP veterinary inspection protocols. For New Entrants and Emerging Players: Northern Emirates aquaculture capacity offers the most penetrable white-space target, with federal subsidies for Fujairah and Umm Al Quwain hamour production reducing capital barriers versus Dubai or Abu Dhabi entry costs. Target food service distributors seeking same-day freshness guarantees for hotel banquet operations. Deploy direct-to-consumer subscription models for fresh chicken delivery in Dubai Marina and Abu Dhabi Reem Island. For Investors and Strategic Acquirers: Halal-certified cold-chain logistics specialists with established MOHAP relationships represent the optimal acquisition target archetype for capturing hospitality procurement consolidation. Long-term viability hinges on positioning ahead of domestic production subsidy threshold adjustments and import dependency ratio shifts. Monitor Ras Al Khaimah food security zone subsidy allocation announcements as the critical inflection signal for capacity investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Controlled-Environment Farming | Al Ain poultry facilities shorten supply chains and reduce refrigeration costs for fresh slaughter. |
| Blockchain Traceability Platform Deployment | Emirates logistics providers verify slaughter-to-shelf compliance for Jumeirah hotel procurement teams. |
| Cell-Cultured Protein Regulatory Engagement | Early MOHAP framework participation secures first-mover positioning in novel protein approval. |
| Northern Emirates Processing Capacity Expansion | Ras Al Khaimah subsidies offer lower-cost entry points than Dubai or Abu Dhabi infrastructure. |
| Direct-to-Consumer Subscription Model Launch | Same-day fresh halal chicken delivery captures share from Carrefour and Lulu deli counters. |
Research Methodology
Cross-validation between MOHAP regulatory filings and UAE General Secretariat of the Executive Council food security mandate documentation anchors the qualitative findings. Primary interviews with hotel procurement directors, Jebel Ali Free Zone distributors, Al Ain poultry facility operators, and MOHAP veterinary inspection officers combined with secondary validation from customs trade records, hospitality project pipeline databases, and federal subsidy allocation disclosures. Bottom-up segment sizing and top-down macroeconomic calibration triangulate volume estimates.
Calibration against historical import dependency ratios and domestic production capacity buildouts shapes the projection framework across the analysis window. Segmentation dimensions modeled include product type tier, end-user procurement channel, distribution interface, and packaging format specifications. CAGRs derive from trend extrapolation of hospitality project pipelines, e-commerce penetration curves, and controlled-environment farming investment cycles. Industry-specific inputs incorporate MOHAP microbial safety threshold compliance costs and blockchain traceability adoption rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Saudi cross-border poultry operators or Brazilian chilled beef exporters would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Hot Dog and Sausages Market
Meat Products
Bacon Slicers Market
Meat Products
United States Poultry Meat Market
Meat Products
3D Printed Meat Market
Meat Products
Poultry Processing Meat Market
Meat Products
Organic Pork Market
Meat Products
North America Poultry Meat Market
Meat Products
Nitrate-Free Bacon Market
Meat Products
Europe Canned Meat Market
Meat Products
Meat-Based FPP Market
Meat Products
Meat Emulsions Market
Meat Products
Meat Flavors Market
Meat Products
South Africa Processed Meat Market
Meat Products
Kosher Beef Market
Meat Products
Emulsified Meat Market
Meat Products
Low-Fat Chorizo Market