
 China Processed Meat Market | 2026-2036
China Processed Meat Market Size, Share, and Industry Trends Forecast 2026-2036
China Processed Meat Market Analysis
China's dual carbon goals is recalibrating investment priorities across the processed meat value chain, compelling processors to retrofit facilities and adopt cleaner thermal technologies. WH Group Limited leverages its vertically integrated hog supply to secure cost advantages in raw material procurement. Jinluo Group anchors its position through dominant distribution networks across lower-tier cities and rural townships. Shandong Delisi Group specializes in premium cured product lines that command shelf space in eastern province supermarket chains.
Processed meat encompasses animal proteins subjected to salting, curing, fermentation, smoking, or thermal treatment to extend shelf stability and enhance sensory properties, with water activity typically controlled below 0.85 for ambient-stable products and sodium nitrite inclusion regulated for color fixation and botulism inhibition. The category serves retail, food service, and industrial food manufacturing channels requiring consistent portion control and predictable yield rates. Sausages occupy the largest volume share within product type segmentation, reflecting their ubiquity in hot pot, street food, and home cooking applications across Chinese provinces. Modified atmosphere packaging is gaining traction among premium deli meats and sliced bacon lines, as retailers seek to reduce shrinkage and extend case-ready display life without frozen distribution. Vacuum pack formats dominate mass-market ham and bulk sausage segments where price sensitivity shapes procurement decisions.
SAMR enforces national food safety standards for additive limits and labeling accuracy, while GB standards specify microbiological criteria and residue thresholds that determine market access for domestic and imported products alike. MEE oversight of carbon intensity benchmarks and wastewater discharge permits is reshaping capital allocation toward cleaner rendering and chilling operations. Processors must monitor evolving GB standard revisions and provincial environmental enforcement intensity to anticipate compliance costs and facility upgrade timelines.
Market Dynamics
China's dual carbon goals under MEE oversight are forcing processors to retrofit rendering and chilling infrastructure, redirecting capital from capacity expansion toward compliance-driven equipment upgrades and energy-efficient cold chain investments.
Growth Catalysts
- Urban convenience demand:Quick-service restaurant chains are scaling processed protein procurement as Yangtze River Delta consumers prioritize meal solutions over traditional wet-market purchases.
- Modified atmosphere packaging:Premium deli meat lines are adopting gas-flush systems to extend case-ready shelf life without frozen distribution, reducing retail shrinkage.
- GB standards harmonization:SAMR enforcement of unified additive limits and microbiological criteria is consolidating domestic production quality, easing interprovincial trade flows.
Market Restraints
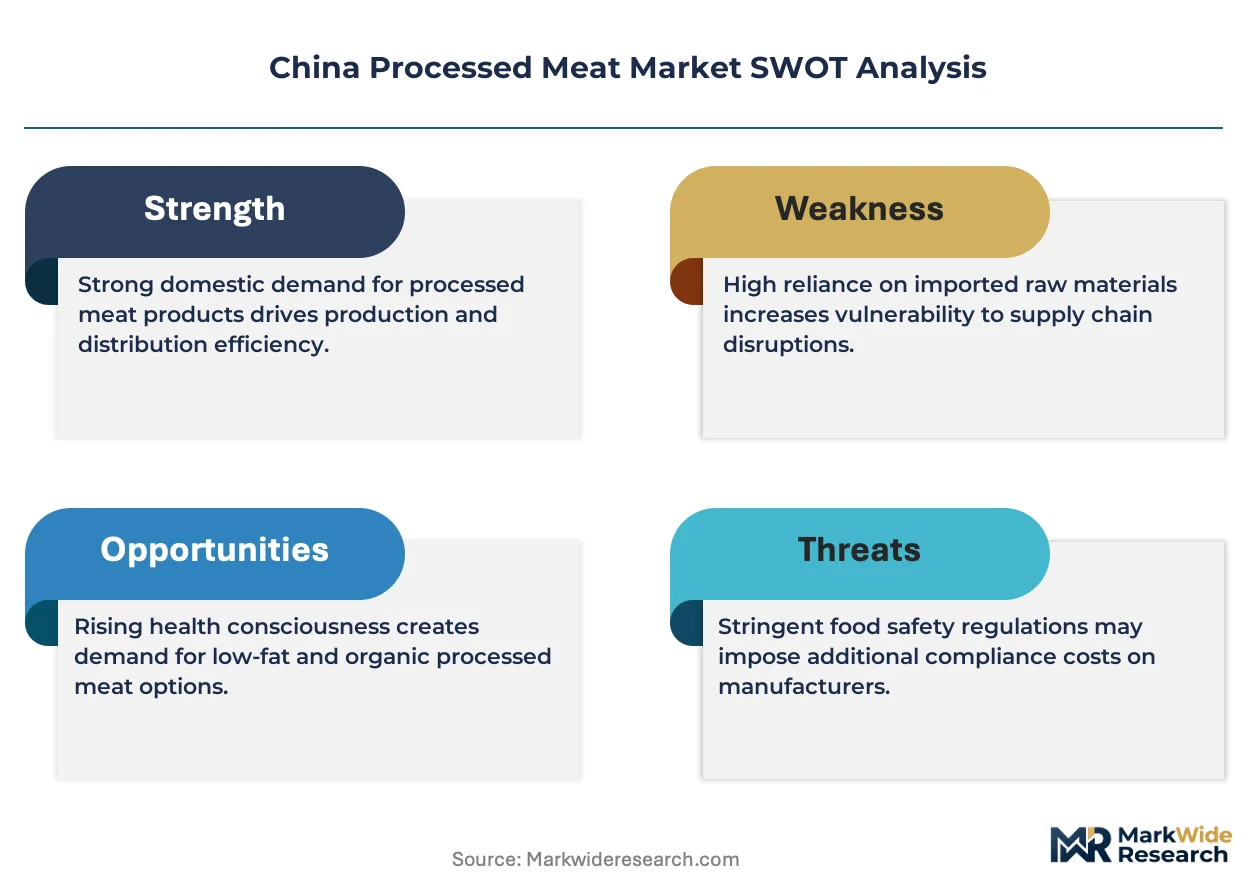
- Hog price volatility:Raw material costs swing with African swine fever recovery cycles, compressing processor margins and destabilizing procurement planning.
- Environmental compliance capex:MEE wastewater discharge permits and carbon intensity benchmarks require facility retrofits that strain mid-tier processor balance sheets.
- Plant-based substitution:Soy and pea protein analogs are capturing share in hot pot and street food channels where processed sausages historically dominated.
Strategic Opportunities
- Lower-tier city penetration:Distribution networks in rural townships and county-level cities remain fragmented, creating whitespace for organized players to consolidate shelf space.
- Clean thermal technology:Heat pump rendering and solar-assisted chilling systems qualify for provincial green financing under dual carbon incentive frameworks.
- Premium cured specialization:Eastern province supermarket chains are expanding facings for artisanal ham and dry-aged product lines that command price premiums over commodity sausages.
Industry Challenges
- Cold chain engineering talent:Facility operators face scarcity of technicians trained in ammonia-alternative refrigeration systems and intelligent temperature monitoring.
- Legacy equipment integration:Retrofitting existing smokehouses and thermal processing lines with MEE-compliant emissions controls creates production downtime and yield inconsistency.
- Labeling compliance velocity:SAMR revisions to nutritional disclosure and origin marking rules demand rapid packaging redesign cycles that outpace supplier response capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Processed Meat Market |
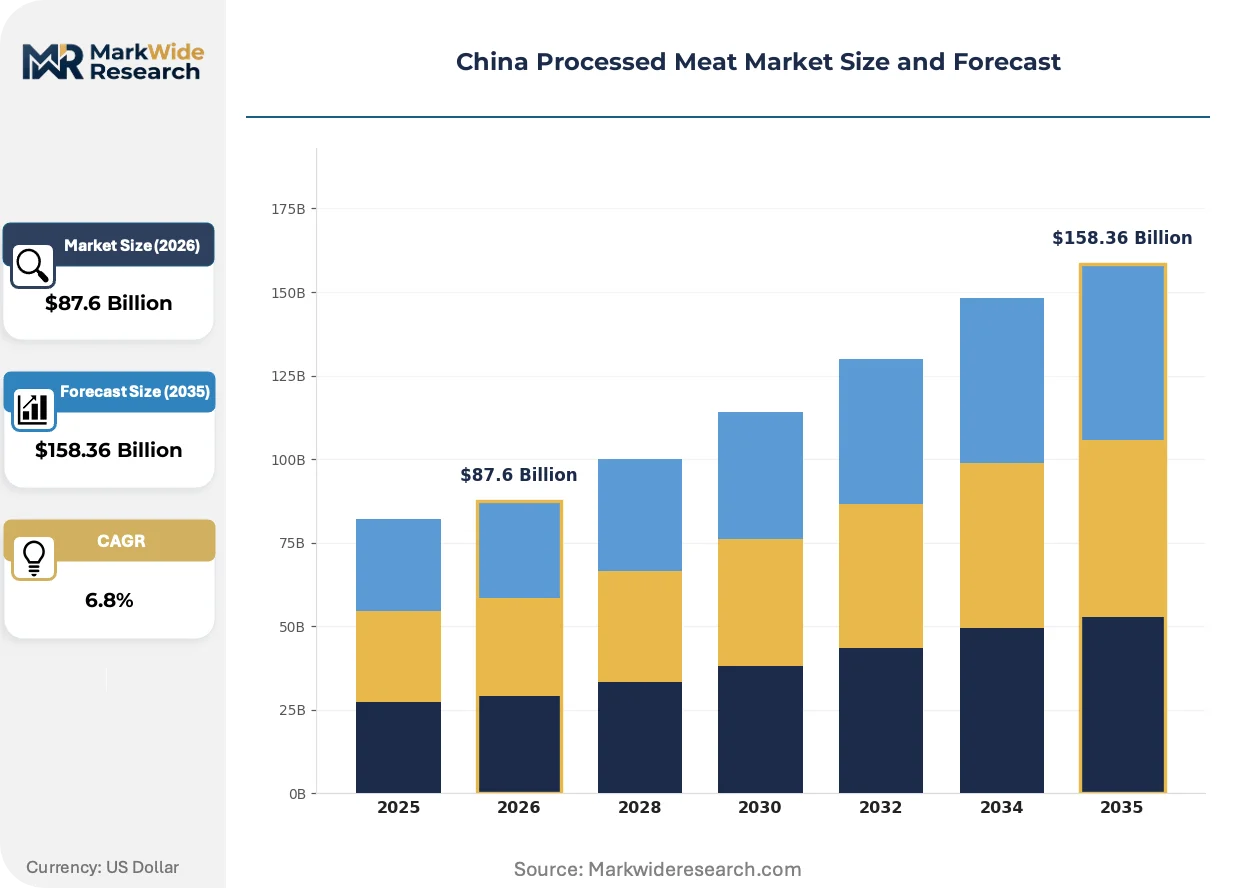
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
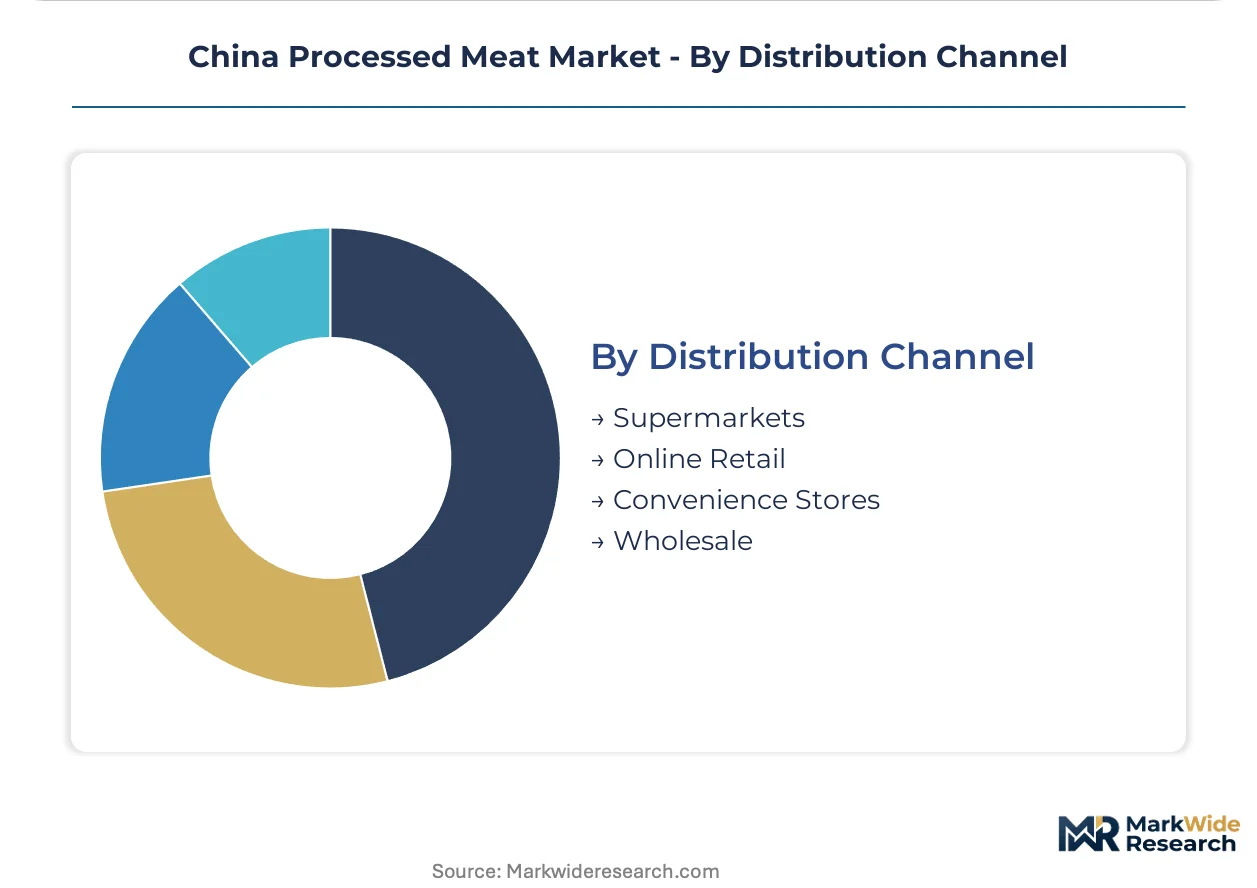
| Segmentation | Product Type: Sausages, Ham, Bacon, Deli Meats Packaging Type: Vacuum Pack, Modified Atmosphere Pack, Canning, Tray Pack End User: Retail, Food Service, Households, Food Processing Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesale |
| Companies Covered | Jinluo Group, Shandong Delisi Group, WH Group Limited, NH Foods, Hormel Foods Corporation, Tyson Foods, COFCO Meat Holdings, Zhucheng Waimao, China Yurun Food Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Processed Meat Market Emerging Trajectories
Processor investment is pivoting from volume expansion toward precision-controlled production environments that simultaneously satisfy SAMR safety mandates and MEE carbon benchmarks.
Intelligent chilling systems using IoT-enabled temperature telemetry are electrifying cold chain operations across Yangtze River Delta distribution hubs. Third-party logistics providers serving supermarket chains are retrofitting fleets with electric refrigeration units to meet provincial emissions deadlines. This infrastructure shift is compressing energy costs per pallet-mile while enabling real-time compliance documentation for MEE audits.
MEE oversight of carbon intensity benchmarks is tightening discharge permit thresholds for rendering and wastewater treatment operations. Processors in Jiangsu and Zhejiang provinces are installing anaerobic digestion systems to capture biogas from organic effluent. Facility operators now sequence production runs to optimize thermal load balancing against time-of-use electricity pricing.
Urban households are displacing daily wet-market meat purchases with weekly stockpiling of vacuum-packed ham and sliced bacon from supermarket deli counters. E-commerce platforms are capturing share through subscription boxes delivering portion-controlled sausage assortments to Shanghai and Hangzhou apartments. This channel rotation favors processors with MAP-equipped packaging lines and direct-to-consumer fulfillment infrastructure.
China Processed Meat Market Segmentation
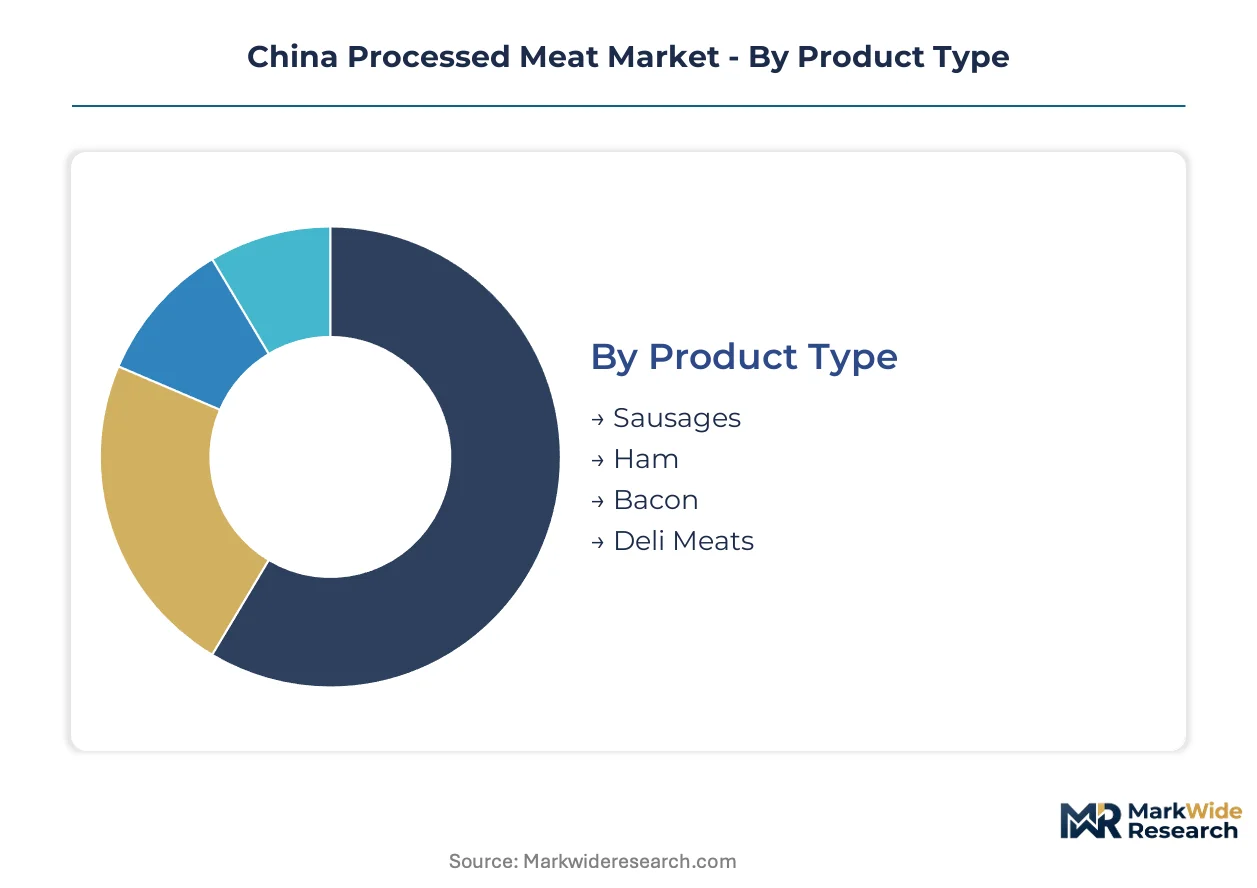
Segmentation in China's processed meat market reveals how regulatory requirements, channel economics, and consumption patterns create distinct operational profiles across product lines. Processors must align certification pathways and capital deployment with the specific demands of each segment to optimize margin capture.
Product Type:
SAMR enforces divergent additive limits and microbiological thresholds across cured versus fresh-processed categories, with sodium nitrite ceilings and water activity benchmarks varying by thermal treatment intensity.
- Sausages:Ground meat emulsions stuffed into casings undergo thermal processing to achieve water activity below 0.85 for ambient stability. Demand concentrates in hot pot restaurants and street food stalls across Sichuan and Chongqing provinces, where mala flavor integration drives procurement volumes. SAMR's GB standards for residual nitrite content impose batch testing burdens that favor processors with in-house laboratory capacity.
- Ham:Cured pork leg sections rely on controlled salt diffusion and extended aging to develop texture and flavor profiles. Eastern province supermarket chains in Jiangsu and Zhejiang command premium shelf space for bone-in and boneless formats, with consumers paying price premiums for Jinhua-origin provenance claims. MEE discharge permits for brine wastewater treatment create compliance cost differentials between artisanal and industrial producers.
- Bacon:Belly sections cured with salt and smoke deliver consistent sliceability for breakfast and hot pot applications. Breakfast-oriented QSR chains in Shanghai and Beijing drive institutional procurement volumes.
- Deli Meats:Sliced ready-to-eat products require MAP-equipped packaging lines and strict cold chain maintenance for Listeria control. Hotel breakfast buffets and corporate catering channels absorb premium-priced assortments.
Leading the category by volume: Sausages. Growing fastest: Deli Meats.
Packaging Type:
Packaging selection directly determines shelf-life extension, cold chain requirements, and retail channel access, with capital intensity escalating from vacuum formats through MAP systems.
- Vacuum Pack:Oxygen exclusion through barrier films achieves 30-90 day refrigerated shelf life for ham and bulk sausage segments. Mass-market supermarket channels in lower-tier cities prioritize unit cost over display aesthetics, sustaining dominant share for this format. Equipment payback periods of 18-24 months suit mid-tier processors with constrained capex budgets.
- Modified Atmosphere Pack:Gas-flush systems replacing oxygen with nitrogen and carbon dioxide extend case-ready deli meat display life to 10-14 days without frozen distribution. Premium supermarket chains in Shanghai and Hangzhou mandate MAP for private-label sliced products, reducing shrinkage and enabling facings expansion. MEE carbon intensity benchmarks favor electric over gas-powered thermal forming equipment.
- Canning:Retort sterilization delivers multi-year ambient stability for military, emergency stockpile, and rural distribution applications. State procurement programs maintain baseline demand volumes.
- Tray Pack:Overwrapped foam or fiber trays serve fresh sausage and bacon segments with 5-7 day refrigerated windows. Wet market vendors and small-format convenience stores favor this lowest-cost option.
Volume concentration: Vacuum Pack. Margin expansion: Modified Atmosphere Pack.
End User:
End-user segmentation maps procurement scale, specification stringency, and payment term structures that reshape processor sales force deployment and production scheduling.
- Retail:Supermarket and hypermarket channels demand consistent portion control, barcode-compliant labeling, and promotional calendar alignment. Yangtze River Delta chains specify MAP formats and origin-marking compliance that strain supplier technical capabilities.
- Food Service:QSR chains, hot pot restaurants, and institutional caterers prioritize predictable yield rates and bulk pricing for sausage and bacon lines. Central kitchen procurement in Shanghai and Beijing concentrates volumes with processors offering national distribution networks.
- Households:E-commerce subscription boxes and supermarket deli counter purchases are displacing daily wet-market buying patterns among urban dual-income families. Weekly stockpiling behavior favors vacuum-packed ham and portion-controlled sausage assortments with extended refrigerated windows.
- Food Processing:Industrial manufacturers of frozen dumplings, instant noodles, and ready meals source emulsified meat preps with specified particle size and protein content. Specification adherence outweighs price in supplier selection.
Procurement scale leader: Food Service. Channel rotation momentum: Households.
Distribution Channel:
Channel selection determines geographic reach, working capital intensity, and brand control, with fragmentation in lower-tier markets creating consolidation opportunities for organized players.
- Supermarkets:Hypermarket and supermarket chains dominate volume in eastern provinces, with category management teams dictating packaging formats and promotional frequencies. Slotting fees and shrinkage guarantees compress net margins for processors lacking direct store delivery infrastructure.
- Online Retail:E-commerce platforms capture growing share through cold-chain fulfillment centers serving Shanghai, Hangzhou, and Nanjing apartment deliveries. Subscription sausage assortments and flash-sale ham promotions require MAP-equipped packaging and direct-to-consumer labeling compliance.
- Convenience Stores:Small-format urban outlets prioritize grab-and-go sliced products and single-serve sausage packs with 3-5 day turnover. Distribution economics favor processors with dedicated route-to-market partnerships.
- Wholesale:Traditional wet market aggregators and food service distributors serve rural townships and county-level cities with minimal packaging and cash-based transactions. Credit risk and price volatility concentrate with this channel.
Volume concentration: Supermarkets. Expansion trajectory: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors processed meat distribution across the Yangtze River Delta, commanding premium shelf space and cold chain infrastructure that radiates outward to Jiangsu and Zhejiang provinces.
Yangtze River Delta
Urban convenience demand concentrates in Shanghai, Hangzhou, and Nanjing supermarket chains. SAMR enforces GB standards for additive limits and labeling accuracy across this cluster. Cold chain logistics providers in Suzhou and Ningbo are electrifying refrigeration fleets to meet MEE carbon intensity deadlines.
Pearl River Delta
Guangzhou and Shenzhen food service channels absorb institutional volumes for breakfast-oriented QSR chains. MEE wastewater discharge permits constrain rendering operations in Foshan and Dongguan. Processors in Zhuhai are installing anaerobic digestion systems to capture biogas from organic effluent.
Beijing-Tianjin-Hebei
Corporate catering and hotel breakfast buffets in the capital drive deli meat procurement. SAMR microbiological criteria determine market access for products crossing provincial boundaries. Cold storage operators in Tianjin port zone are retrofitting ammonia-alternative refrigeration systems.
Sichuan-Chongqing
Hot pot restaurants and street food stalls in Chengdu and Chongqing generate sausage demand through mala flavor integration. Provincial environmental enforcement intensity shapes facility upgrade timelines for local processors. Distribution networks in county-level cities remain fragmented, creating whitespace for organized players.
Shandong Peninsula
Industrial food manufacturers in Qingdao and Yantai source emulsified meat preps for frozen dumpling and instant noodle production. MEE oversight of carbon benchmarks is pushing processors toward cleaner thermal technologies. Artisanal ham producers in Jinhua-origin supply chains command eastern province supermarket facings.
China Processed Meat Market Vendor Landscape
Premium-margin players sit above commodity-margin players across packaging sophistication and distribution reach, with MAP-equipped lines and direct-to-consumer infrastructure separating tiers. The vendor base clusters around three strategic archetypes: vertically integrated hog suppliers controlling raw material costs, dominant distribution network operators penetrating lower-tier cities, and premium cured specialists commanding eastern province shelf space. Competitive moves concentrate on M&A to secure cold chain assets and strategic partnerships with e-commerce platforms for subscription fulfillment.
Within the integrated supply tier, WH Group Limited and Jinluo Group exemplify divergent scale strategies, with the former representing captive hog production advantages and the latter anchoring rural township penetration. Shandong Delisi Group occupies a position among premium cured specialists, reflecting artisanal product line concentration in coastal province retail channels. These three entities collectively illustrate how procurement control, distribution density, and specialization depth define competitive positioning under tightening SAMR and MEE compliance frameworks.
| Leading Market Players |
|---|
| Jinluo Group |
| Shandong Delisi Group |
| WH Group Limited |
| NH Foods |
| Hormel Foods Corporation |
| Tyson Foods |
| COFCO Meat Holdings |
| Zhucheng Waimao |
| China Yurun Food Group |
| Others |
Supply Flow & Price Mechanics
QSR procurement concentration in the Yangtze River Delta anchors value-based pricing around yield consistency and portion-control reliability rather than commodity spot benchmarks. SAMR additive compliance costs and MEE carbon retrofit requirements feed directly into processor margin structures, compressing mid-tier players while rewarding MAP-equipped premium specialists.
Pricing Analysis
Yield-rate guarantees to central kitchen operators anchor value-based pricing for bulk sausage and bacon contracts. Three-tier pricing structure across premium, standard, and economy levels separates MAP-equipped deli lines from vacuum-packed mass-market ham and tray-pack wet-market formats. Cost compression in economy tiers is intensifying because hog price volatility compresses processor margins. Wet-market vendors and small-format convenience stores exhibit highest price sensitivity; hotel breakfast buffets and corporate catering channels absorb premium markups with minimal elasticity.
Supply Chain Analysis
Dual-sourcing requirements from supermarket chains and QSR central kitchens mandate multi-processor qualification for critical ham and sausage SKUs. Domestic hog farming in Shandong and Henan provinces combines with imported pork from Brazil and Spain to diversify raw material exposure. The supply chain draws from temperature-controlled rendering facilities, sodium nitrite additive suppliers, and barrier film packaging producers. Single-source vulnerability concentrates in ammonia-refrigerated cold storage infrastructure facing MEE phase-out deadlines. Distribution runs through electrified Yangtze River Delta logistics hubs radiating to county-level wholesale aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The China processed meat market is becoming a vertical-integration race where captive hog supply and in-house MAP packaging lines determine margin capture. Players are pursuing upstream control over breeding operations and downstream direct-to-consumer fulfillment infrastructure as the decisive competitive lever.
For Market Incumbents: Extend backward integration into captive hog breeding facilities to insulate procurement from African swine fever recovery cycles. Acquire cold chain logistics assets in Jiangsu and Zhejiang provinces to secure MEE-compliant distribution capacity before provincial emissions deadlines tighten. Plant-based substitution threats from soy and pea protein analogs demand defensive premium positioning in artisanal cured lines. For New Entrants and Emerging Players: County-level city distributors in Sichuan and Shandong provinces represent an underserved buyer archetype with fragmented incumbent coverage. White-space exists in solar-assisted chilling systems qualifying for provincial green financing under dual carbon incentive frameworks. E-commerce subscription boxes for portion-controlled sausage assortments offer a direct-to-consumer go-to-market angle bypassing slotting-fee barriers. For Investors and Strategic Acquirers: The window for entry favors processors with installed MAP capacity and SAMR-certified laboratory infrastructure. Long-term viability hinges on exposure to premium cured specialization rather than commodity sausage volume. Acquisition targets should display anaerobic digestion systems for biogas capture and intelligent chilling telemetry. The signal to watch is MEE enforcement intensity accelerating facility upgrade timelines beyond mid-tier balance sheet capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hog Breeding | Captive supply from Shandong facilities insulates WH Group from ASF price volatility. |
| MAP Packaging Line Installation | Gas-flush systems extend case-ready shelf life for Shanghai supermarket private-label contracts. |
| Anaerobic Digestion System Deployment | Biogas capture from organic effluent satisfies Jiangsu provincial MEE discharge permit thresholds. |
| Direct-to-Consumer E-commerce Launch | Subscription sausage assortments bypass hypermarket slotting fees in Hangzhou and Nanjing. |
| Cold Chain Electrification Partnership | Electric refrigeration fleet retrofits qualify Suzhou logistics providers for dual carbon incentives. |
Methodological Framework
Document review covered SAMR regulatory filings, MEE environmental enforcement bulletins, and provincial agricultural statistics, complemented by interviews with cold chain logistics operators, supermarket category buyers, and processor plant managers. Primary fieldwork engaged QSR procurement directors in Shanghai and Beijing, alongside hog farm operators in Shandong and Henan. Secondary sources included customs trade records for imported pork volumes, GB standard revision notices, and provincial energy pricing disclosures. Bottom-up processor capacity assessments triangulated against top-down channel volume estimates.
Cross-referencing historical production data against expert panel input established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated product type, packaging format, end-user channel, and regional regulatory cluster dimensions. CAGRs were derived from trend extrapolation moderated by compliance cost absorption capacity. Forecast inputs weighted hog price cycle recovery patterns, MEE retrofit capital requirements, and MAP adoption velocity in eastern province retail channels.
Revisions become necessary when African swine fever resurgence, MEE enforcement acceleration, or plant-based substitution breakthroughs materialize beyond baseline assumptions. Deviation in hog supply stability or provincial green financing availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Pork Meat Market
Meat Products
Global Poultry Meat Market
Meat Products
Reconstituted Meat Market
Meat Products
GCC Edible Meat Market
Meat Products
Beef Tallow Market
Meat Products
Low Fat Sausage Market
Meat Products
Raw Chicken Feet Market
Meat Products
Organic Beef Meat Market
Meat Products
Meat Market
Meat Products
Middle East Poultry Meat Market
Meat Products
Rendered Poultry Products Market
Meat Products
North America Processed Meat Market
Meat Products
Low-Fat Ham Market
Meat Products
Low Fat Beef Market
Meat Products
Asia-Pacific Low Fat Sausage Market
Meat Products
Beef Jerky Market