
 Low-Fat Chorizo Market | 2026-2036
Low-Fat Chorizo Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Fat Chorizo Market Analytics
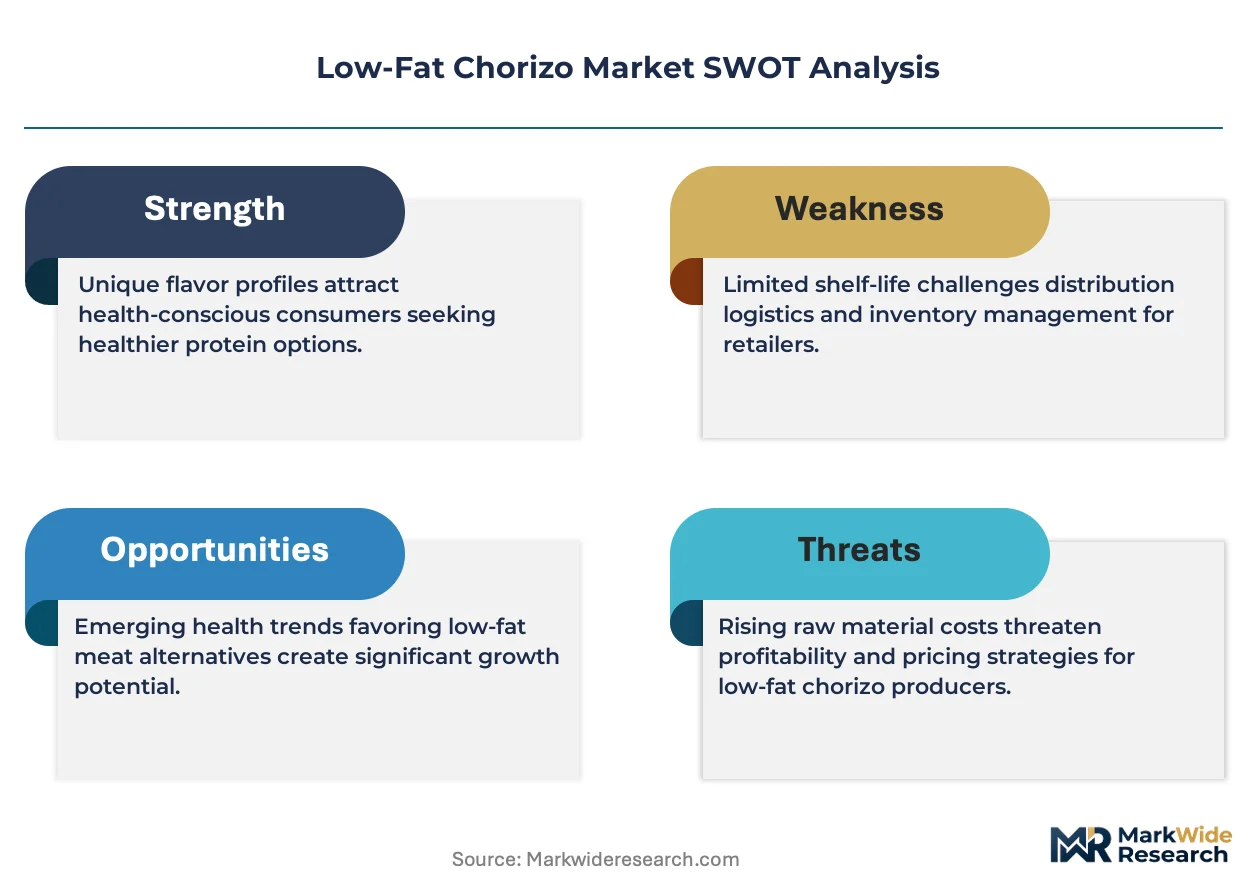
Buyer concentration among food service distributors is broadening as regional restaurant chains and independent taquerias diversify their protein sourcing beyond legacy suppliers. Hormel Foods Corporation leverages its refrigerated foods infrastructure to secure broad retail placement. Johnsonville LLC. anchors its position through specialized sausage production expertise. Beyond Meat Inc. competes with plant-based formulations targeting health-conscious consumers seeking traditional flavor profiles.
Low-fat chorizo denotes a reduced-lipid emulsified sausage typically manufactured with lean meat trimmings, controlled fat percentages below standard chorizo specifications, and spice blends incorporating paprika, garlic, and vinegar for authentic flavor retention. The product serves commercial kitchens and retail consumers requiring lower-calorie alternatives without sacrificing cultural recipe authenticity. Pork-based variants dominate current volume given established supply chains and consumer familiarity, while turkey formulations represent the fastest-expanding segment driven by health positioning. Online retailers capture expanding margin pools as direct-to-consumer subscription models reduce intermediary costs for specialty meat producers.
USDA FSIS oversight governs fat-content labeling and nutritional claims, compelling manufacturers to validate reduced-fat assertions through standardized testing protocols. FDA nutrition labeling requirements further constrain health-related marketing language, shaping how brands communicate comparative benefits to consumers. Mexico's COFEPRIS and the European Union's EFSA standards create additional compliance layers for cross-border product movement. Stakeholders must monitor evolving clean-label expectations and alternative protein regulatory classifications that could redefine competitive boundaries in reduced-fat cured meats.
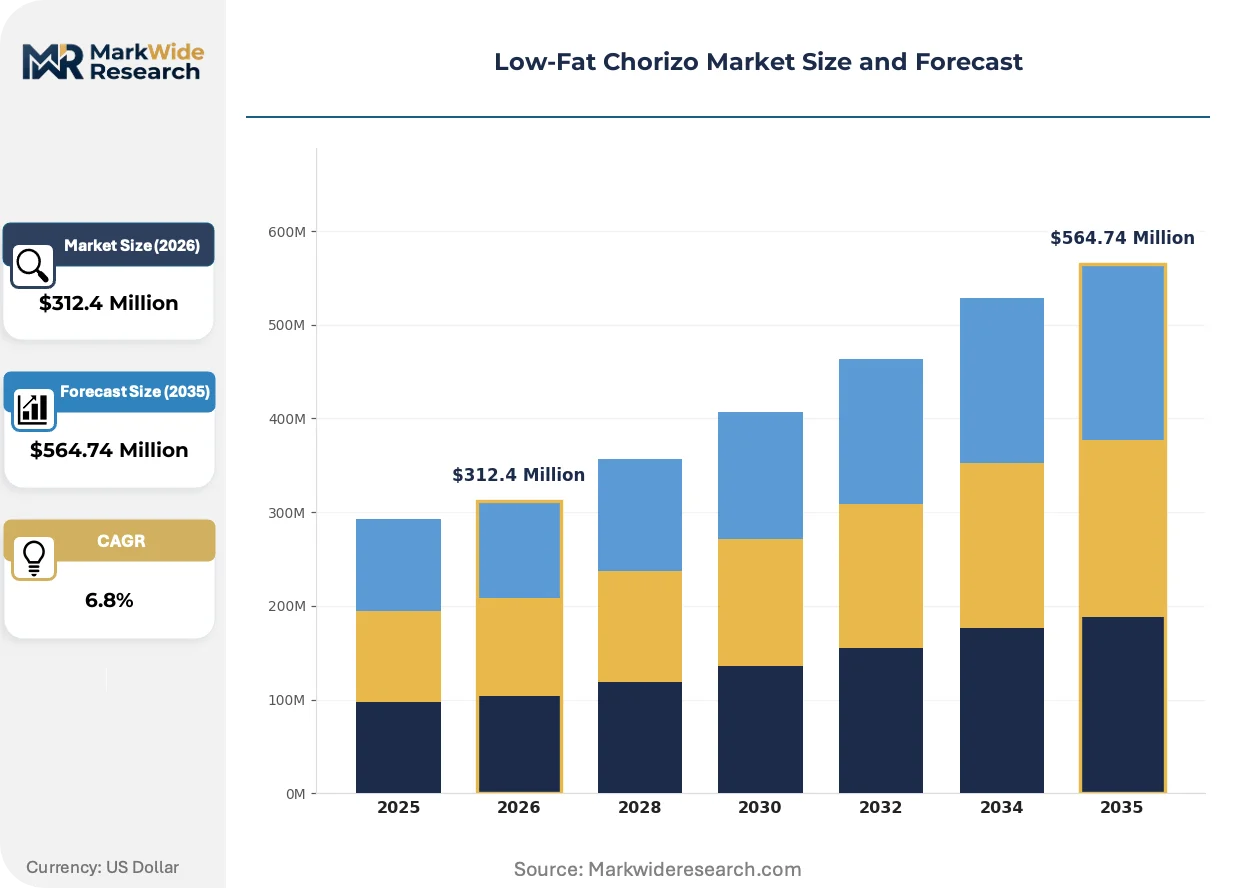
Market Dynamics
USDA FSIS fat-content labeling requirements are compressing formulation flexibility while supermarket chains expand shelf space, creating a structural squeeze between compliance costs and retail access for reduced-fat sausage producers.
Growth Catalysts
- Clean-label ingredient mandates:FDA nutrition labeling requirements are accelerating reformulation investments toward recognizable spice blends and natural casings that satisfy consumer transparency demands.
- Food service distributor consolidation:Regional restaurant chains and independent taquerias are diversifying protein sourcing beyond legacy suppliers, opening procurement pathways for specialty low-fat chorizo entrants.
- Direct-to-consumer subscription infrastructure:Online retailers are capturing expanding margin pools as specialty meat producers bypass intermediary costs through recurring delivery models.
Market Restraints
- Lean meat input volatility:Pork trim price fluctuations constrain margin stability for manufacturers dependent on consistent lean-to-fat ratios.
- Cross-border regulatory friction:Mexico's COFEPRIS and the European Union's EFSA standards create compliance layering that delays product registration for exporters.
- Plant-based protein substitution:Beyond Meat and similar alternative protein formulations are capturing health-conscious consumers seeking traditional flavor profiles without animal content.
Strategic Opportunities
- Southwestern United States culinary corridor:Arizona, New Mexico, and Texas represent underpenetrated retail zones where chorizo holds deep cultural recipe integration.
- Turkey-based formulation expansion:Health-positioned variants are displacing pork-based volume in fitness-oriented consumer segments seeking leaner protein sources.
- Refrigerated foods infrastructure leverage:Cold-chain investments by established processors enable rapid geographic expansion without capital-intensive facility construction.
Industry Challenges
- Standardized fat-content testing protocols:USDA validation requirements demand laboratory infrastructure that smaller specialty producers struggle to maintain.
- Flavor-authenticity technical gaps:Paprika, garlic, and vinegar spice blend optimization for reduced-fat matrices requires sensory science capabilities concentrated at larger manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Fat Chorizo Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Pork, Turkey, Chicken Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Convenience Stores End User: Households, Restaurants, Catering Services, Food Manufacturers Packaging Type: Vacuum Packs, Cans, Pouches, Trays |
| Companies Covered | Beyond Meat Inc., Hormel Foods Corporation, Johnsonville LLC., El Burrito Food Products, Denmark Foods, Cantella's, Ranchero, H & H, San Manuel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Fat Chorizo Market Evolving Landscape
Product formulation and distribution channels are undergoing parallel transformation as regulatory precision meets evolving procurement preferences in reduced-fat cured meats.
High-pressure processing technology is expanding into low-fat chorizo manufacturing to extend refrigerated shelf life without chemical preservatives. Regional supermarket chains are adopting this capability to reduce shrinkage in premium sausage categories. The technology is expanding into private-label programs that previously relied on frozen distribution.
EU EFSA standards for nutritional claims are tightening evidentiary requirements for reduced-fat assertions across member states. Manufacturers must now submit compositional analysis through designated reference laboratories before market placement. Spanish and Portuguese exporters face particular scrutiny given chorizo's protected designation origin complexities.
Direct sourcing contracts between specialty processors and independent taquerias are compressing traditional distributor margins. Southwestern United States restaurant operators are negotiating volume commitments in exchange for exclusive formulation access. This pattern is most visible in Phoenix and Albuquerque metropolitan clusters where regional chain density supports consolidated procurement.
Low-Fat Chorizo Market Segmentation
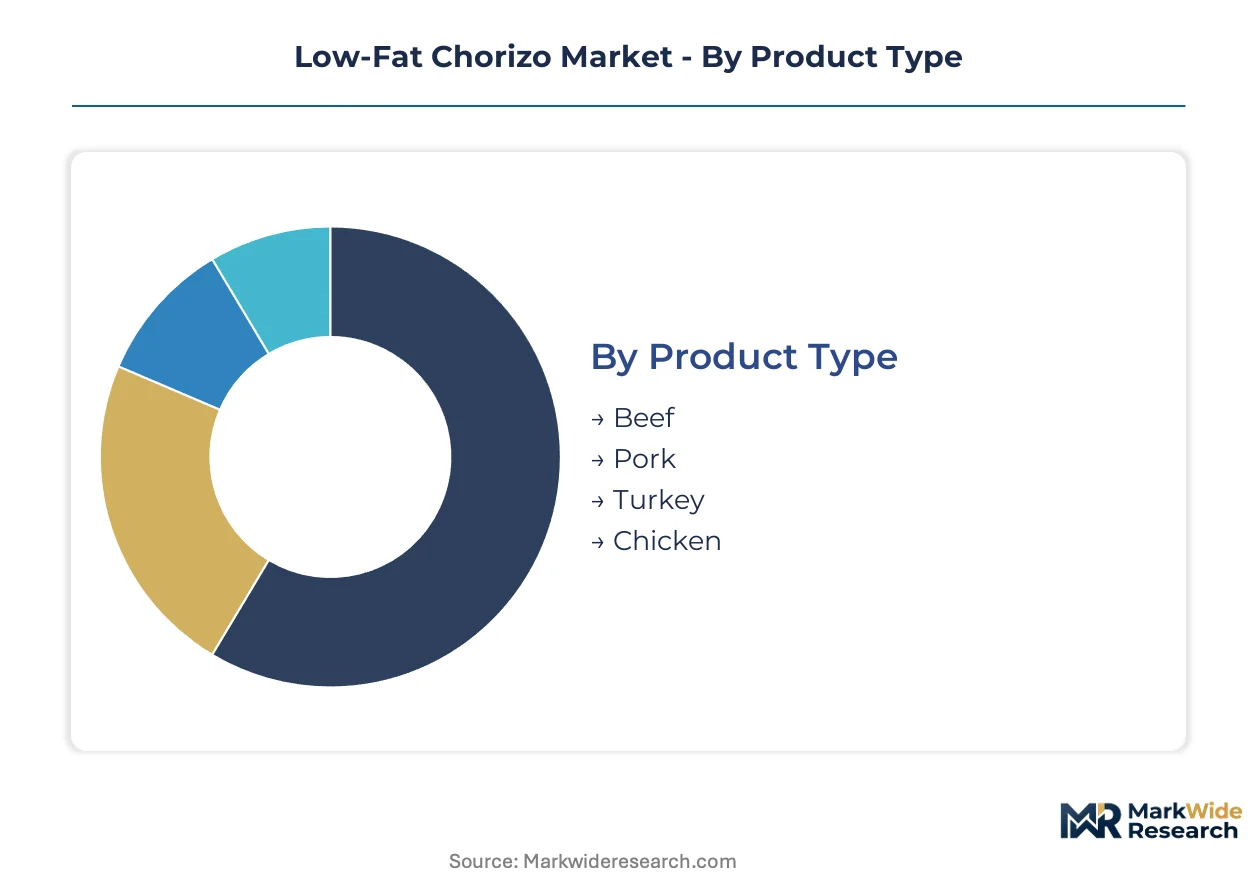
Low-fat chorizo manufacturers configure production assets around protein sourcing economics and cold-chain distribution reach. Segment boundaries reflect divergent capital requirements for livestock procurement, processing technology, and retail channel access.
Product Type:
Pork and turkey formulations demand the heaviest upfront investment in specialized grinding equipment and lean-trimming infrastructure.
- Pork:Manufactured from shoulder and ham trimmings with controlled fat emulsification, this variant anchors volume in Mexico and Texas where traditional recipe adherence dominates household and restaurant procurement. USDA FSIS fat-content validation requirements compel dedicated laboratory infrastructure at processing facilities.
- Turkey:Lean white-meat base requires supplemental fat replacement systems and modified spice binding agents to achieve texture parity with pork alternatives. Health-positioned demand concentrates in California and Arizona fitness-oriented consumer segments seeking reduced-calorie protein sources.
- Beef:Utilizes chuck and round trimmings with adjusted paprika ratios for flavor density compensation.
- Chicken:Relies on thigh meat for moisture retention in reduced-fat matrices.
Pork absorbs the bulk of installed capacity; turkey is expanding most quickly.
Distribution Channel:
Channel selection determines working capital intensity through inventory holding periods and payment term structures.
- Supermarkets:Refrigerated shelf space expansion by regional chains in New Mexico and Arizona creates placement competition requiring slotting fee commitments and promotional fund reserves. Cold-chain compliance and shrinkage liability concentrate risk with manufacturers.
- Online Retailers:Direct-to-consumer subscription models bypass intermediary margins but demand fulfillment infrastructure investment. Specialty meat producers capture expanded margin pools through recurring delivery relationships with health-conscious households.
- Specialty Stores:Independent Hispanic grocers in Phoenix and Albuquerque metropolitan clusters negotiate exclusive formulation access.
- Convenience Stores:Frozen distribution dominates given limited refrigerated capacity at retail.
Supermarkets command the largest revenue share; online retailers are climbing the fastest.
End User:
User category shapes batch size requirements and specification tolerance thresholds.
- Restaurants:Independent taquerias and regional chains across the Southwestern United States negotiate volume commitments for consistent spice blend supply. Direct sourcing contracts compress traditional distributor margins while demanding just-in-time delivery reliability.
- Households:Retail consumers prioritize recognizable ingredient labels and vacuum-sealed freshness indicators. FDA nutrition labeling requirements constrain comparative health claim communication.
- Catering Services:Bulk procurement emphasizes portion consistency and extended hold times.
- Food Manufacturers:Ingredient-grade supply for frozen prepared meals requires customized fat specifications.
Restaurants absorb the bulk of procurement volume; households are gaining share fastest.
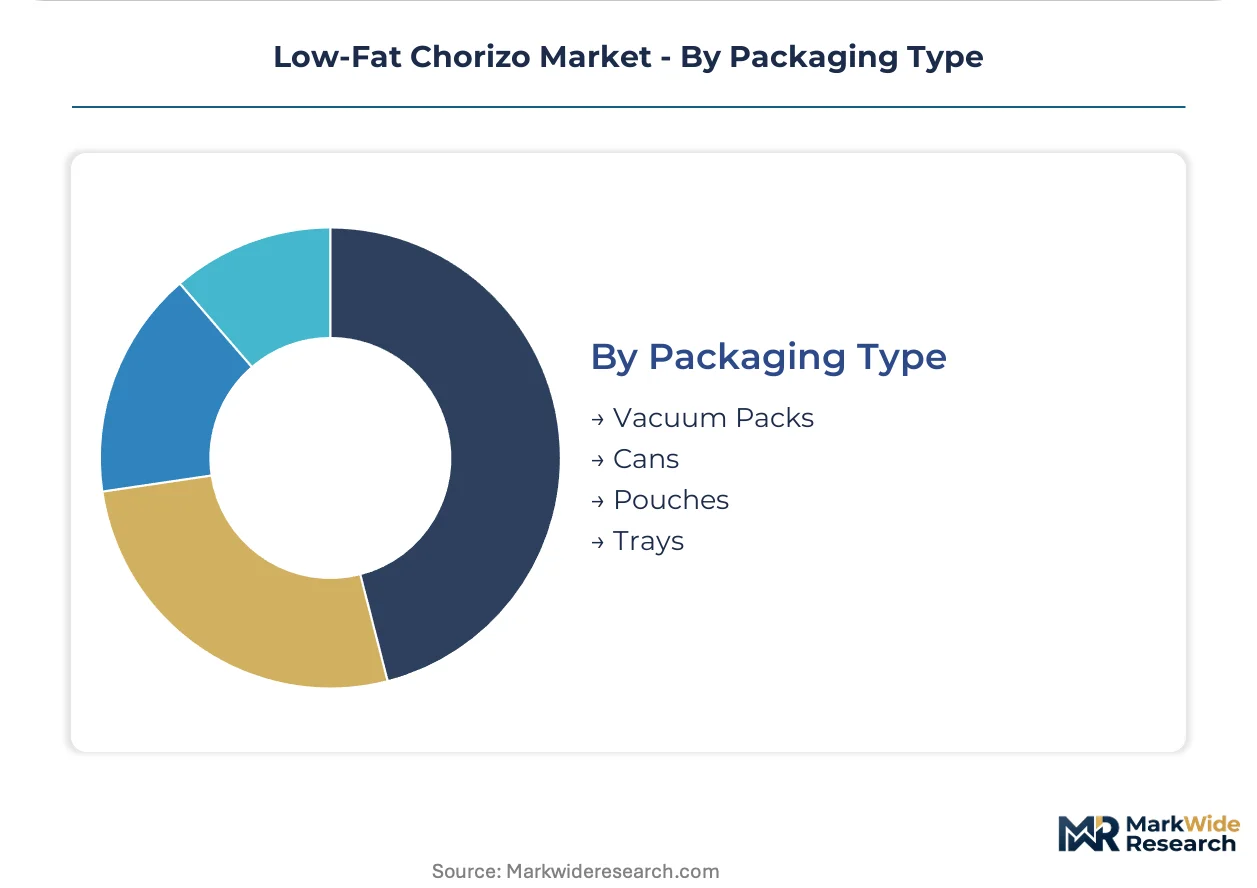
Packaging Type:
Packaging technology investment separates shelf-life extension capabilities from commodity positioning.
- Vacuum Packs:Modified atmosphere systems extend refrigerated shelf life without chemical preservatives. High-pressure processing technology adoption concentrates among premium private-label programs reducing shrinkage exposure.
- Pouches:Flexible format suits direct-to-consumer subscription logistics with reduced shipping weight.
- Cans:Shelf-stable positioning serves food service emergency stock requirements.
- Trays:Overwrap presentation dominates supermarket fresh meat cases.
Vacuum packs hold the largest installed base; pouches are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumer demand for reduced-fat chorizo concentrates in Mexico and the southwestern United States, where culinary tradition sustains household and restaurant procurement of spice-forward sausage alternatives.
United States
Supermarket chains in Arizona and New Mexico are expanding refrigerated shelf space for reduced-fat sausage alternatives. USDA FSIS fat-content labeling requirements compel manufacturers to maintain dedicated laboratory infrastructure for standardized testing protocols. The Phoenix and Albuquerque metropolitan clusters host direct sourcing negotiations between specialty processors and independent taquerias.
Mexico
Traditional recipe adherence dominates household procurement of pork-based chorizo across central and southern states. COFEPRIS regulatory standards create compliance layering for cross-border product registration that delays exporter market entry. Mexico City anchors volume consumption while Jalisco and Nuevo León process lean-trimming operations for regional distribution.
Spain
Protected designation origin complexities surrounding chorizo production constrain formulation flexibility for reduced-fat variants. EU EFSA standards for nutritional claims tighten evidentiary requirements through designated reference laboratories before market placement. The Castile and León region maintains curing expertise while Catalonia tests high-pressure processing technology for shelf-life extension.
Canada
Health Canada oversight of nutritional claims shapes how brands communicate comparative benefits to consumers seeking lower-calorie protein sources. Cold-chain investments by established processors enable rapid geographic expansion into Ontario and Quebec retail corridors. Toronto and Vancouver metropolitan areas concentrate fitness-oriented demand for turkey-based formulations.
Germany
EFSA standards for reduced-fat assertions apply stringent compositional analysis requirements across member state distribution. German retailers are adopting vacuum-pack modified atmosphere systems to reduce shrinkage in premium sausage categories. Bavaria and North Rhine-Westphalia host private-label program development for refrigerated distribution networks.
Low-Fat Chorizo Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue plant-based alternatives and direct-to-consumer subscription models. The vendor base spans multinational refrigerated foods specialists, regional sausage fabricators, and alternative protein developers. Three archetypes dominate: legacy meat processors with cold-chain infrastructure, specialty chorizo producers with spice-blend expertise, and plant-based formulators targeting health-conscious segments. Capacity expansion and portfolio diversification represent the dominant competitive moves as participants respond to clean-label mandates and retail placement competition.
Within the legacy processor tier, Hormel Foods Corporation and Johnsonville LLC occupy positions anchored by refrigerated foods infrastructure and specialized sausage production expertise respectively. Beyond Meat Inc. exemplifies the alternative protein archetype competing for health-conscious consumers seeking traditional flavor profiles without animal content. These three entities represent the competitive spectrum from conventional meat processing through plant-based formulation.
| Leading Market Players |
|---|
| Beyond Meat Inc. |
| Hormel Foods Corporation |
| Johnsonville LLC. |
| El Burrito Food Products |
| Denmark Foods |
| Cantella's |
| Ranchero |
| H & H |
| San Manuel |
| Others |
Value Network & Pricing Analysis
Specialized sausage-grinding technicians in Jalisco and Nuevo León anchor production economics, with labor-cost differentials between Mexican processing hubs and U.S. border facilities widening pricing-tier spreads across premium private-label and economy frozen segments.
Pricing Analysis
Volume concentrates in pork-based supermarket tiers while margins pool in direct-to-consumer subscription channels. Three-tier pricing structure across premium vacuum-packed, standard refrigerated, and economy frozen levels separates Hormel and Johnsonville placements from private-label alternatives. Pricing pressure stems from Beyond Meat's plant-based substitution in California fitness segments. Independent taquerias show highest price sensitivity; specialty Hispanic grocers accept premium positioning for exclusive formulations.
Supply Chain Analysis
Direct sourcing contracts between Arizona processors and Phoenix metropolitan taquerias bypass traditional food service distributors. Lean pork trimmings feed from Iowa and Minnesota livestock operations; paprika supply draws from Spanish and Hungarian spice houses. Single-source vulnerability concentrates in COFEPRIS-certified Mexican facilities serving cross-border export demand. Cold-chain distribution runs through regional supermarket refrigerated networks and online retailer fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laboratory infrastructure scarcity for USDA FSIS fat-content validation props pricing power among incumbent processors, constraining specialty entrant expansion.
For Market Incumbents: Anticipate Beyond Meat's flavor-technology advancement by securing exclusive spice-blend supplier contracts and expanding high-pressure processing capacity in Texas. Backward integration into lean-trimming operations insulates margin stability against pork input volatility. Channel control through direct taqueria relationships defends placement against distributor consolidation. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer lowest barrier-to-entry for turkey-based formulation specialists targeting Arizona and California fitness segments. Underpenetrated independent Hispanic grocers in Albuquerque metropolitan clusters present white-space procurement pathways. Go-to-market leverage rests on COFEPRIS compliance expertise enabling cross-border product registration speed. For Investors and Strategic Acquirers: The window for entry favors cold-chain infrastructure owners with USDA laboratory certification. Long-term viability hinges on refrigerated foods network density and clean-label formulation capabilities. Watch EFSA evidentiary requirement tightening as signal for European export opportunity contraction.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Adoption | Extends refrigerated shelf life for premium private-label programs without chemical preservatives. |
| Direct Sourcing Contract Expansion | Compresses distributor margins while securing volume commitments from Southwestern taqueria chains. |
| Turkey Formulation R&D Investment | Captures fitness-oriented demand displacement in California and Arizona health-conscious segments. |
| COFEPRIS Compliance Infrastructure | Accelerates cross-border registration timelines for Mexican market access and export positioning. |
| Clean-Label Ingredient Reformulation | Satisfies FDA transparency mandates while differentiating against plant-based flavor-profile competitors. |
Research Methodology
Multi-period observation of refrigerated shelf-space expansion, direct-to-consumer subscription growth, and COFEPRIS registration timelines anchored the trend analysis, supplemented by interviews with sausage processing plant managers, supermarket category buyers, independent taqueria operators, food service distribution procurement leads, and USDA FSIS compliance officers. Secondary validation drew from FDA nutrition labeling databases, USDA FSIS fat-content testing protocols, Nielsen retail audit data, and SEC refrigerated foods segment disclosures. Bottom-up production capacity estimates triangulated against top-down consumer expenditure flows.
Segment-weighting across protein type, distribution channel, and end-user category shaped volume and value outputs across the projection horizon. CAGRs derived from fitted growth curves applied to historical procurement patterns and regulatory compliance cost trajectories. Modeled inputs included pork trim price volatility indices, EFSA evidentiary requirement evolution, and high-pressure processing technology adoption rates.
The model holds under stable USDA labeling enforcement and intact cold-chain infrastructure; deviation in COFEPRIS regulatory stringency or Beyond Meat flavor-technology breakthroughs would shift competitive boundaries. Forecasts embed assumptions regarding clean-label mandate progression and supermarket slotting fee structures. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
North America Low Fat Sausage Market
Meat Products
Beef Bone Broth Market
Meat Products
Reduced Fat Meat Market
Meat Products
China Processed Meat Market
Meat Products
Beef Tallow Market
Meat Products
North America Processed Poultry Meat Market
Meat Products
Sausage Premixes Market
Meat Products
Grassfed Jerky Market
Meat Products
United States Bacon Market
Meat Products
Kosher Beef Market
Meat Products
Pork Belly Meat Market
Meat Products
India Edible Meat Market
Meat Products
Non-Veg Rte and Rtc Market
Meat Products
Bacon Slicers Market
Meat Products
Asia-Pacific Red Meat Market
Meat Products
Smokehouse Market