
 GCC Red Meat Market | 2026-2036
GCC Red Meat Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Red Meat Market Foresight
Veterinary and halal-slaughter skilled labor scarcity across the Gulf is unwinding capacity expansion timelines at domestic processing facilities. Almarai Company leverages its integrated dairy-to-protein platform to sustain chilled distribution dominance across Saudi Arabia. JBS S.A. anchors its GCC position through Brazilian beef supply lines calibrated to Gulf import specifications. Tanmiah Food Company differentiates via captive poultry and red meat processing assets that reduce third-party reliance.
GCC red meat encompasses bovine, ovine, and caprine muscle tissue harvested under halal protocols and distributed through temperature-controlled channels for human consumption; carcass grading follows fat-score and age-classification systems that determine culinary suitability and price realization. Beef commands the largest value share within product type segmentation due to its centrality in hospitality menus and premium retail assortments across the Gulf. Lamb and mutton segments attract higher per-kilogram margins during Ramadan and Hajj seasons when household and institutional procurement surges. The distribution channel split between chilled and frozen formats reflects infrastructure disparities: the UAE and Saudi Arabia sustain chilled networks while smaller Gulf states rely more heavily on frozen imports.
Saudi Food and Drug Authority halal standards, UAE Ministry of Climate Change and Food Safety import protocols, and GCC Standardization Organization technical regulations collectively govern market access, product labeling, and cold-chain compliance across the six member states. These frameworks elevate compliance costs for non-regional exporters while creating protected terrain for domestic processors that certify under multiple national schemes. Stakeholders must monitor how Saudi Arabia's Local Content and Government Procurement Authority rules on food sector localization reshape procurement preferences for state-affiliated hospitality and healthcare foodservice contracts.
Market Dynamics
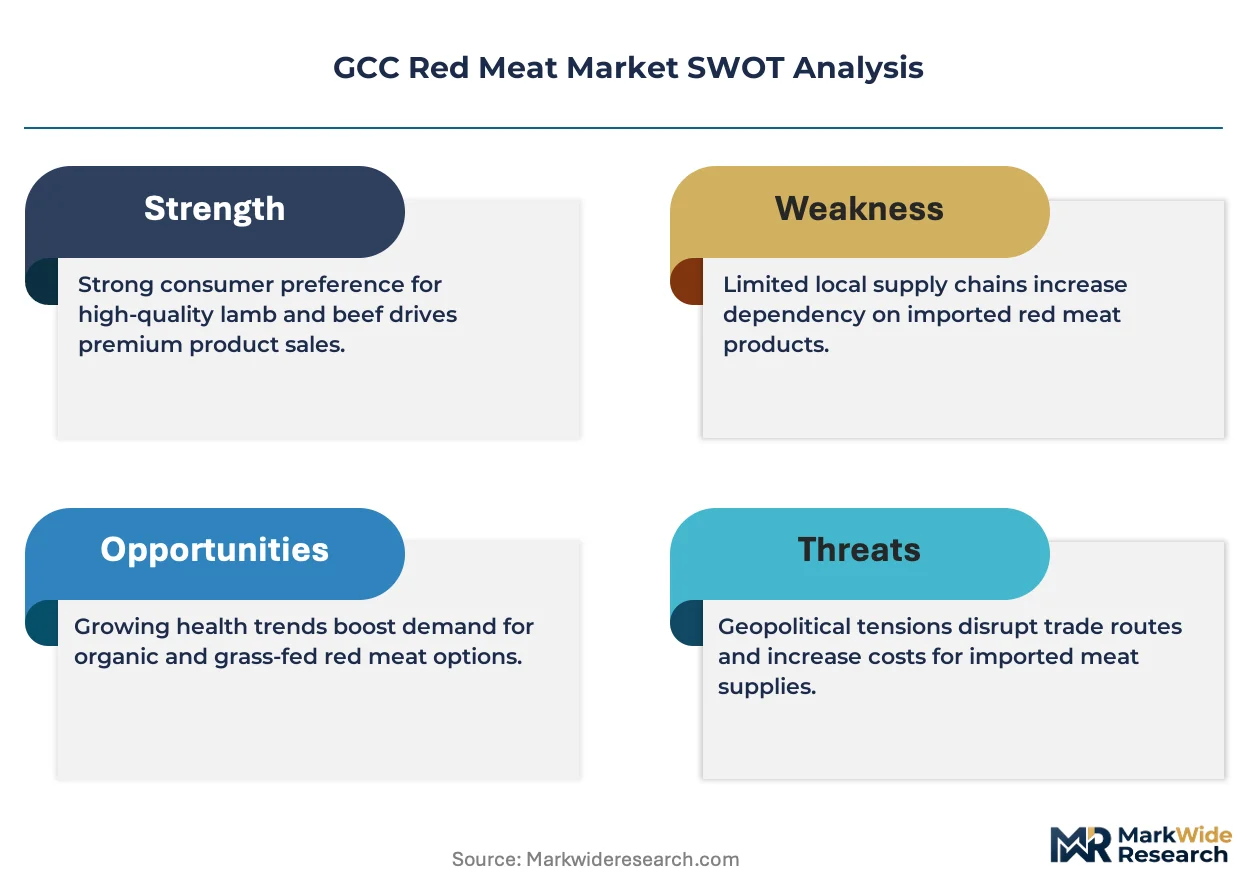
Saudi Arabia's Local Content and Government Procurement Authority rules are redirecting state-affiliated hospitality and healthcare foodservice contracts toward domestic processors, compressing import-dependent business models while rewarding certified local supply chains.
Growth Catalysts
- SFDA Halal Protocol Harmonization:The Saudi Food and Drug Authority's tightened certification standards are consolidating compliant supplier bases and elevating premium positioning for accredited domestic facilities.
- Chilled Distribution Infrastructure:Cold-chain investments across Riyadh and Jeddah corridors are enabling fresh-cut penetration into large-format retail and hotel procurement channels.
- Seasonal Institutional Procurement:Ramadan and Hajj pilgrimage cycles generate predictable surges in ovine and bovine volume absorption by catering and hospitality operators.
Market Restraints
- Feed Input Cost Volatility:Barley and alfalfa import dependence exposes domestic processors to Black Sea and Australian supply disruptions and currency fluctuation.
- Veterinary Labor Scarcity:Gulf-wide shortage of halal-slaughter certified technicians is extending facility commissioning timelines at greenfield processing plants.
- Frozen Format Lock-in:Bahrain, Kuwait, Oman, and Qatar lack chilled last-mile networks, forcing reliance on lower-margin frozen import economics.
Strategic Opportunities
- UAE Hospitality Contract Localization:Dubai and Abu Dhabi hotel development pipelines offer captive offtake for processors achieving MOHAP dual-certification alongside Saudi standards.
- Blockchain Traceability Integration:Combining distributed ledger systems with IoT temperature monitoring is opening premium export positioning into Southeast Asian halal markets.
- Backward Integration into Breeding:Controlled environment agriculture and feedlot technology transfers from Australian partners are reducing third-party live import dependence.
Industry Challenges
- Multi-Jurisdiction Certification Complexity:Parallel Saudi SFDA, UAE MOHAP, and GCC Standardization Organization compliance requirements extend product registration timelines and inflate quality assurance staffing.
- Legacy Cold-Chain Asset Stranding:Frozen-dominant distributors in smaller Gulf states face capex burdens to retrofit chilled capabilities without guaranteed volume commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Red Meat Market |
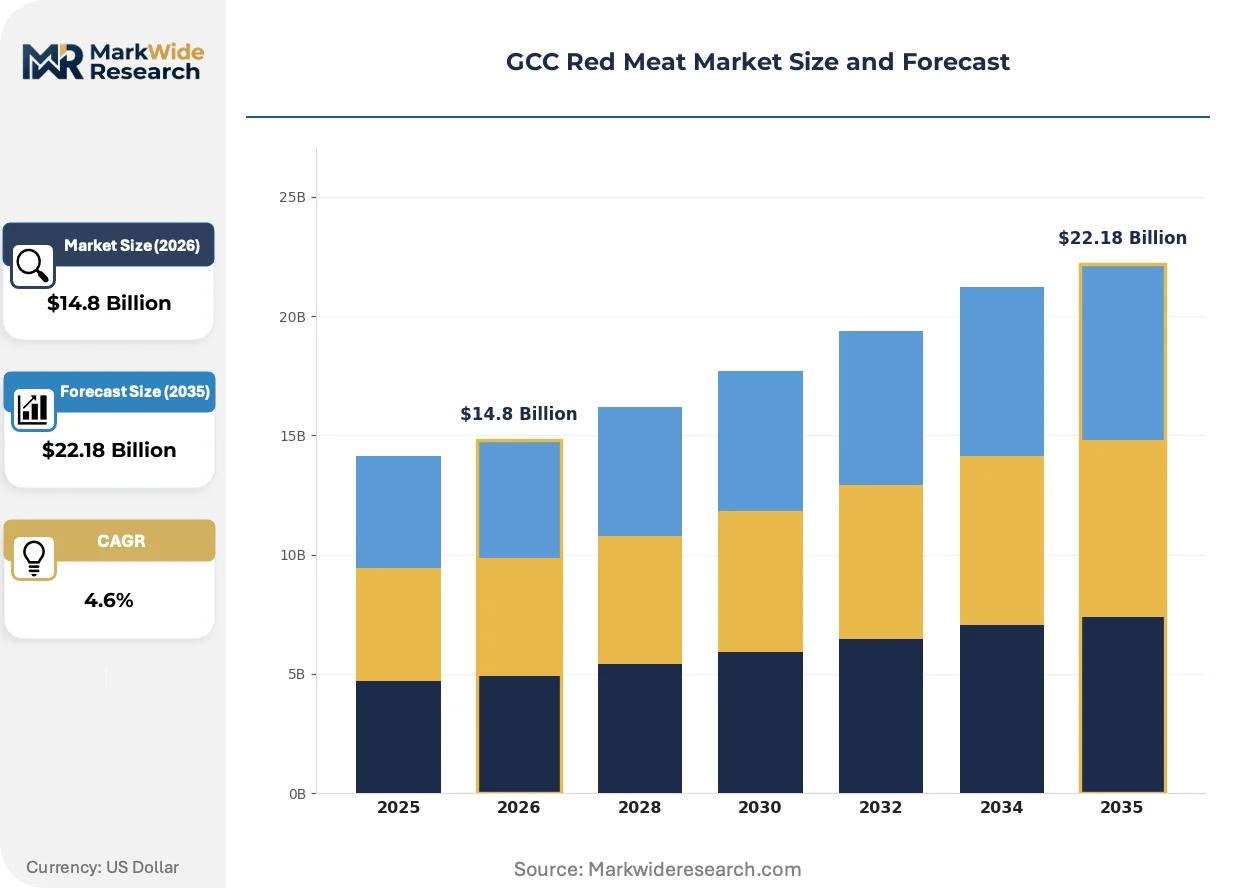
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Lamb, Mutton, Goat End User: Restaurants, Supermarkets, Butcheries, Households Sales Channel: Online, Retail, Wholesale, Direct Sales Distribution Channel: Chilled, Frozen, Fresh, Canned |
| Companies Covered | The Savola Group, The Organic Meat Company Ltd, BRF S.A., Golden Gate Meat Company, Kibsons International LLC, JBS S.A., Almunajem Foods, Almarai Company, Tanmiah Food Company, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Red Meat Market Shifts & Advancements
Digital traceability platforms and automated slaughter compliance systems are displacing paper-based halal verification, while procurement consolidation among Saudi hospital and hotel groups is compressing supplier counts.
Blockchain-enabled halal provenance tracking is bifurcating the supplier base. Saudi retail conglomerates and UAE hospitality groups are adopting distributed ledger verification at scale. This technology is bifurcating premium chilled segments from commodity frozen imports based on auditable slaughter-to-shelf documentation.
SFDA's 2023 cold-chain technical regulations are mandating real-time temperature logging for all fresh meat imports. The rules impose telemetry hardware costs on Brazilian and Australian exporters while creating protected terrain for domestic processors with integrated IoT infrastructure. Saudi large-format retailers are responding by consolidating procurement around certified domestic suppliers.
Hospital and hotel group purchasing organizations are consolidating red meat supplier panels. Traditional fragmented distributor networks are losing share to direct processor contracts. This concentration is most visible in Riyadh's healthcare and hospitality corridors where Aramco-affiliated and sovereign wealth-funded projects specify single-source protein supply agreements.
GCC Red Meat Market Segmentation
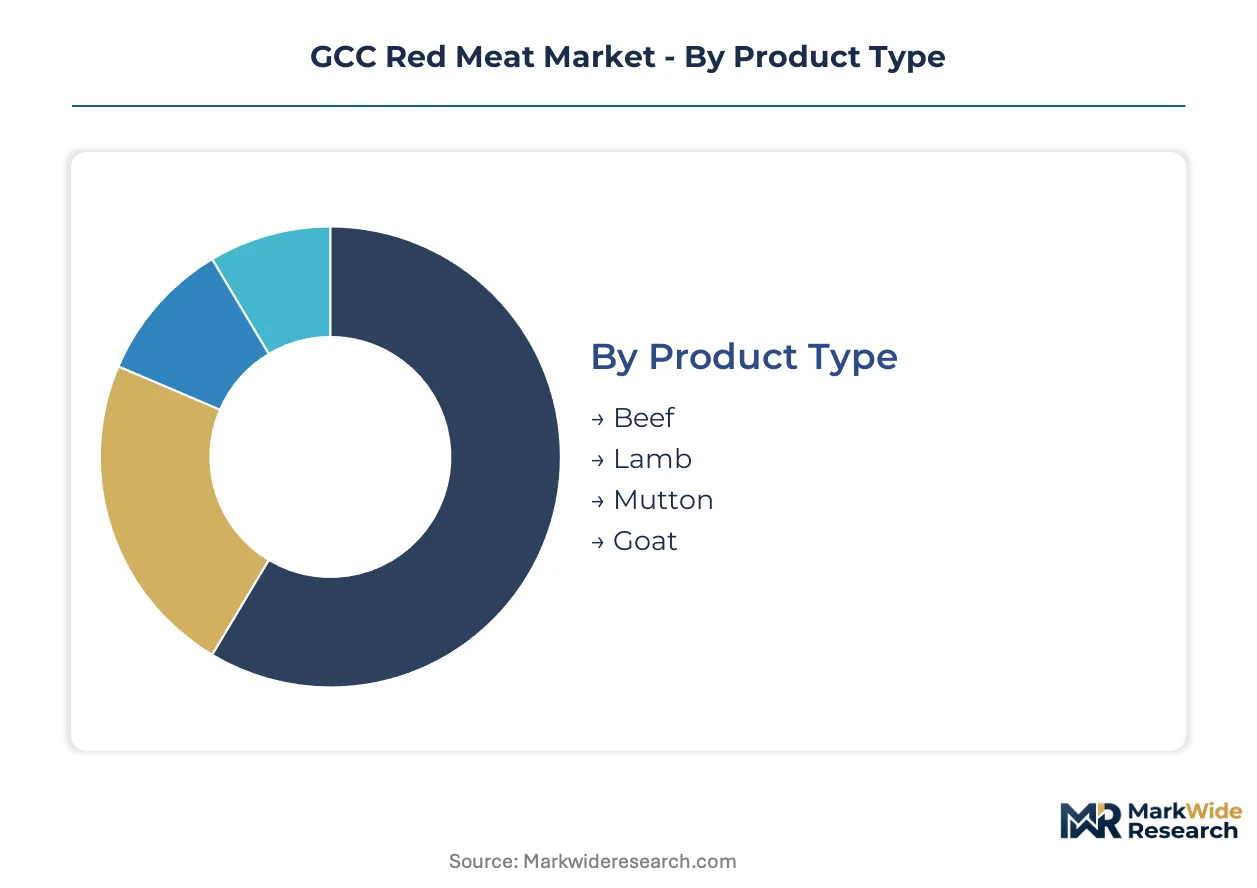
Segmentation in the GCC red meat market reveals how halal certification tiers, temperature-controlled logistics capabilities, and institutional procurement patterns allocate volume across distinct commercial channels. Understanding these divides exposes where margin pools concentrate and where infrastructure investments unlock access.
Product Type:
Chilled beef moves through Saudi Arabia's Riyadh and Jeddah hotel and hospital procurement channels, while frozen lamb fills Ramadan and Hajj seasonal surges in mass retail.
- Beef:Bovine muscle tissue graded by fat-score and age-classification systems determines culinary suitability for hospitality menus. Demand concentrates in Saudi Arabia's sovereign wealth-funded hospitality projects and UAE hotel development pipelines where premium chilled cuts command procurement preference.
- Lamb:Ovine meat harvested under halal protocols attracts higher per-kilogram margins during religious observance periods. Household and institutional procurement in Riyadh and Jeddah corridors absorbs volumes through large-format retail and catering operators.
- Mutton:Older ovine tissue serves price-sensitive segments and processed meat applications. Frozen format dominance in Bahrain, Kuwait, Oman, and Qatar channels volume through wholesale networks lacking chilled last-mile infrastructure.
- Goat:Caprine meat occupies niche ethnic and traditional cuisine segments. Smaller volume flows through specialist butcheries and direct sales channels serving specific demographic communities.
Beef dominates installed base. Lamb is where expansion concentrates.
End User:
Cost tier stratification separates premium hospitality procurement from household volume, with margin compression accelerating in fragmented retail layers.
- Restaurants:Full-service and quick-service operators source chilled primal cuts through consolidated processor contracts. Dubai and Abu Dhabi hotel development pipelines offer captive offtake for dual-certified suppliers meeting MOHAP and SFDA standards.
- Supermarkets:Large-format retail chains in Saudi Arabia are consolidating procurement around certified domestic suppliers with integrated IoT cold-chain infrastructure. Real-time temperature logging mandates from SFDA technical regulations favor vertically integrated processors.
- Butcheries:Traditional fragmented distributor networks serve fresh-cut preferences in communities lacking supermarket penetration. These operators face margin pressure from direct processor contracts and hospital group purchasing organization consolidation.
- Households:End consumers access product through retail and online channels with seasonal spikes during Ramadan and Hajj periods. Procurement shifts toward traceable chilled formats as blockchain-enabled halal provenance tracking gains adoption.
Restaurants capture premium pricing tiers. Supermarkets represent the steepest expansion trajectory as cold-chain infrastructure matures.
Sales Channel:
Customer type determines service intensity, with institutional buyers demanding direct relationships and households accepting standardized digital interfaces.
- Online:Digital platforms aggregate household demand with blockchain traceability integration opening premium positioning. Saudi retail conglomerates are adopting distributed ledger verification at scale for direct-to-consumer chilled delivery.
- Retail:Brick-and-mortar supermarkets and hypermarkets remain the dominant volume channel for fresh and frozen formats. Store-level refrigeration investments in Riyadh and Jeddah enable chilled penetration previously constrained by infrastructure gaps.
- Wholesale:Frozen-dominant distributors in smaller Gulf states rely on lower-margin import economics through bulk procurement. These operators face capex burdens to retrofit chilled capabilities without guaranteed volume commitments from consolidating buyers.
- Direct Sales:Processor-to-institution contracts bypass traditional distributor networks. Aramco-affiliated and sovereign wealth-funded projects in Saudi Arabia specify single-source protein supply agreements compressing supplier counts.
Retail commands current volume. Online is climbing the fastest as digital traceability platforms displace paper-based verification.
Distribution Channel:
Supply concentration in temperature-controlled logistics creates protected terrain for domestic processors with integrated infrastructure against import-dependent frozen operators.
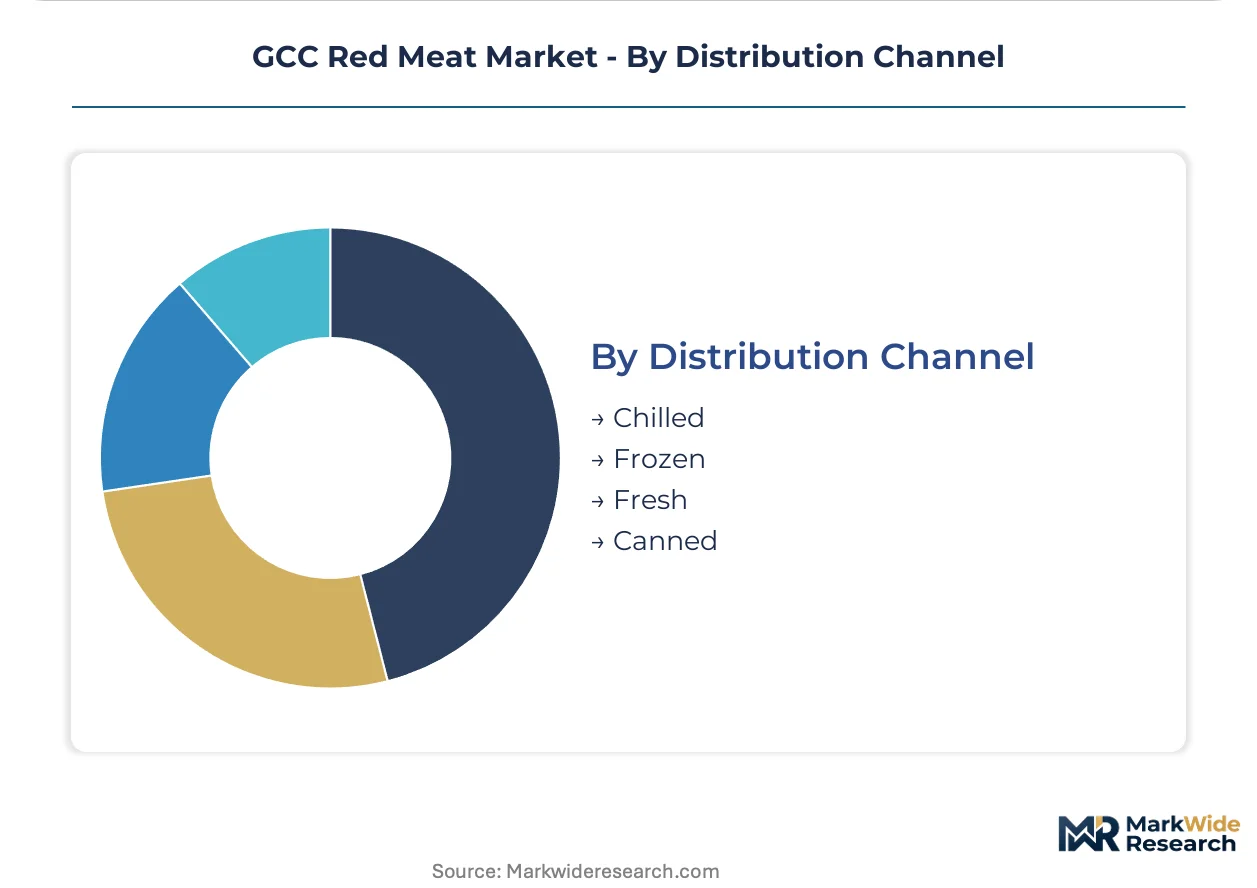
- Chilled:Temperature-controlled distribution between 0-4°C preserves freshness for premium retail and hospitality segments. SFDA's technical regulations mandate real-time temperature logging, imposing telemetry hardware costs on Brazilian and Australian exporters while benefiting domestic facilities.
- Frozen:Blast-frozen product at -18°C enables long-haul import economics and inventory buffering. Bahrain, Kuwait, Oman, and Qatar remain locked into this format due to last-mile infrastructure limitations.
- Fresh:Same-day or next-day distribution from slaughter facilities serves traditional butchery channels. Halal-slaughter certified technician scarcity across the Gulf extends facility commissioning timelines and constrains fresh capacity expansion.
- Canned:Thermally processed and shelf-stable product occupies emergency stockpiling and specific institutional catering niches. Limited volume flows through government procurement and military supply chains.
Frozen dominates installed base. Chilled is gaining share fastest as infrastructure investments reshape import requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia commands pricing power over chilled beef and lamb corridors, while Bahrain, Kuwait, Oman, and Qatar remain anchored to frozen import economics. This asymmetry reflects infrastructure maturity gaps and regulatory enforcement intensity across the six member states.
Saudi Arabia
Riyadh and Jeddah corridors absorb premium chilled volumes through sovereign wealth-funded hospitality and healthcare projects. The Saudi Food and Drug Authority's 2023 cold-chain technical regulations mandate real-time temperature logging, consolidating procurement around domestic processors with integrated IoT infrastructure. NEOM Northwest development pipelines specify single-source protein supply agreements that compress traditional distributor networks.
United Arab Emirates
Dubai and Abu Dhabi hotel development pipelines offer captive offtake for dual-certified suppliers meeting MOHAP and SFDA standards. The UAE Ministry of Climate Change and Food Safety import protocols elevate compliance costs for Brazilian and Australian exporters while protecting domestic processors. Jebel Ali logistics clusters enable re-export positioning into Southeast Asian halal markets through blockchain-enabled traceability platforms.
Qatar
Doha's hospitality sector procurement concentrates around FIFA World Cup legacy hotel assets and healthcare foodservice contracts. Frozen format dominance persists due to last-mile chilled infrastructure gaps, forcing reliance on lower-margin import economics. The Qatar National Food Security Program is evaluating controlled environment agriculture partnerships to reduce live import dependence.
Kuwait
Kuwait City retail and institutional procurement channels remain fragmented across traditional distributor networks. The country's national food regulator maintains parallel import specifications that extend product registration timelines for non-regional exporters. Jahra and Ahmadi industrial zones host limited domestic processing capacity constrained by veterinary labor scarcity.
Oman
Muscat and Salalah corridors serve hospitality and retail segments through frozen-dominant supply chains. The Sultanate's port infrastructure investments at Duqm are positioning for regional re-export hub status pending chilled logistics retrofit completion. Domestic feedlot development programs are attracting Australian technology transfer partners to reduce third-party live import exposure.
GCC Red Meat Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the GCC red meat supply base. The market structure bifurcates between vertically integrated domestic processors with captive cold-chain infrastructure and import-dependent distributors locked into frozen format economics. Three archetypes dominate: integrated protein platforms spanning dairy-to-meat operations, Brazilian supply line specialists calibrated to Gulf halal specifications, and captive poultry-red meat processors reducing third-party reliance. Competitive moves concentrate on backward integration into breeding assets and blockchain traceability certification for premium export positioning.
Within the integrated platform tier, Almarai Company and Tanmiah Food Company exemplify domestic processors leveraging captive distribution networks to sustain chilled market dominance. JBS S.A. anchors the Brazilian supply line specialist archetype, its S.A. corporate structure reflecting the scale-driven export orientation that defines this competitive position. These three entities represent distinct strategic responses to SFDA and MOHAP certification complexity: integrated infrastructure investment, regional processing asset control, and origin-country supply line calibration.
| Leading Market Players |
|---|
| The Savola Group |
| The Organic Meat Company Ltd |
| BRF S.A. |
| Golden Gate Meat Company |
| Kibsons International LLC |
| JBS S.A. |
| Almunajem Foods |
| Almarai Company |
| Tanmiah Food Company |
| Others |
Supply & Pricing Matrix
Scale economies at integrated Saudi processing facilities compress per-unit cold-chain costs below what fragmented importers can achieve, concentrating margin capture among domestic operators with captive distribution networks while anchoring price floors to feedlot input volatility rather than finished-product premiums.
Pricing Analysis
The customization-premium spread between configured-to-order chilled cuts and standard frozen formats runs wide in GCC red meat, with three-tier pricing structure across premium, standard, and economy levels anchored to halal certification grade and real-time traceability integration. Price differentiation hinges on SFDA cold-chain compliance tier and volume scale in institutional procurement contracts. Pricing pressure stems from feed barley import cost spikes driven by Black Sea supply disruptions. Hospital group purchasing organizations exhibit lowest price sensitivity, while fragmented traditional butcheries face acute margin compression.
Supply Chain Analysis
Inventory lead times stretch 45-60 days for Brazilian and Australian exporters navigating multi-jurisdiction halal certification, compressing freshness windows and elevating working capital requirements. Geographic supply concentration centers on Brazil, Australia, and domestic Saudi feedlot operations. Raw material dependencies rest on imported barley, alfalfa, and live animal shipments. Single-source vulnerability pervades veterinary technician labor pools. Distribution runs through vertically integrated processor networks in Saudi Arabia and UAE logistics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated procurement panels at Saudi sovereign wealth-funded hospitality projects and UAE hospital group purchasing organizations, compressing supplier counts and elevating contract scale thresholds for market access.
For Market Incumbents: Shield market position by deepening backward integration into controlled-environment feedlot assets to reduce live import exposure, and accelerate blockchain traceability certification to capture premium positioning in Southeast Asian halal re-export channels. The threat of Brazilian supply line disruption from currency fluctuation demands captive breeding capacity. Certification investment represents the critical lever for contract retention. For New Entrants and Emerging Players: Differentiate on IoT-enabled cold-chain transparency to penetrate Qatar and Kuwait frozen-dominant markets where chilled infrastructure gaps create white-space opportunity. Target Oman's Duqm port corridor for regional re-export hub positioning. A direct-processor-to-institution go-to-market angle bypasses entrenched distributor networks in Riyadh healthcare corridors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated protein platforms with captive distribution infrastructure over import-dependent frozen distributors facing stranded asset risk. Long-term viability across the projection horizon rests on backward integration depth and multi-jurisdiction certification capability. The signal to watch is SFDA localization mandate expansion into government procurement rules.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Breeding Assets | Reduces live import dependence and secures supply continuity against Australian shipment volatility. |
| Blockchain Traceability Certification | Opens premium export positioning into Southeast Asian halal markets through auditable provenance documentation. |
| Multi-Jurisdiction Halal Certification | Enables contract access to Saudi SFDA and UAE MOHAP procurement panels simultaneously. |
| IoT Cold-Chain Infrastructure Deployment | Satisfies real-time temperature logging mandates and consolidates retail procurement relationships. |
| Controlled Environment Agriculture Partnership | Transfers Australian feedlot technology to reduce third-party input exposure and stabilize margin profiles. |
Research Methodology
A standing panel of halal certification auditors, cold-chain logistics directors, hospitality procurement managers, and feedlot operations specialists provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against SFDA regulatory filings, GCC Standardization Organization technical regulations, customs and trade flow databases, and sovereign wealth fund project procurement disclosures. Bottom-up volume modeling and top-down value triangulation ensured cross-verification of outputs.
Consistency checks against external benchmarks validated analytical framework outputs across the analysis window. Segmentation dimensions modeled include product type, distribution temperature format, end-user category, and national regulatory cluster. CAGRs derived from fitted growth curves applied to baseline volume estimates. Industry-specific forecast inputs incorporated feed barley price indices and hospitality development pipeline tracking.
The analysis sits within stated boundaries; outcomes outside sustained cold-chain infrastructure investment and stable halal certification labor availability would require recalibration. Forecasts reflect documented assumptions about regulatory enforcement intensity and import protocol stability. Specific risk factors include veterinary technician scarcity extension, feed input cost spikes, and multi-jurisdiction compliance complexity escalation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Middle East Poultry Meat Market
Meat Products
Global Beef Market
Meat Products
Bacon Flavors Market
Meat Products
Global Processed Pork Meat Market
Meat Products
Ham Slicers Market
Meat Products
United States Poultry Meat Market
Meat Products
Beef Jerky Market
Meat Products
China Processed Meat Market
Meat Products
Binders and Scaffolders for Meat and Meat Substitutes Market
Meat Products
Oman Poultry Meat Market
Meat Products
Beef Bone Broth Market
Meat Products
Middle-East and Africa Animal-Based Meat and Dairy Products Market
Meat Products
GCC Edible Meat Market
Meat Products
Middle East Red Meat Market
Meat Products
United States Red Meat Market
Meat Products
US Meat Market