
 Qatar Poultry Meat Market | 2026-2036
Qatar Poultry Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Poultry Meat Market Insights
Aftermarket service revenue from cold-chain logistics and halal certification compliance is tilting margin pools away from raw commodity trading toward value-added distribution. A'Saffa Food S.A.O.G. leverages its fully integrated Omani-Qatari supply chain to control freshness windows from farm to retail shelf. Hassad Food Company anchors sovereign wealth-backed procurement through its strategic grain and feedstock partnerships. Almarai Company extends its GCC dairy logistics infrastructure into chilled poultry distribution, competing on route density rather than farm ownership alone.
Qatar poultry meat encompasses broiler chicken and turkey products raised under controlled-environment farming systems, typically processed to halal standards with specified pH, moisture retention, and temperature parameters for shelf-stable distribution. The primary commercial purpose is to supply protein for household consumption, foodservice operations, and institutional catering across a desert economy with limited domestic agricultural capacity. Whole chicken and chicken cut-ups dominate volume throughput in supermarkets and hypermarkets, where tray packs and vacuum-sealed formats command premium positioning over bulk packs. Specialty cuts and online retail represent the fastest-expanding margin pools, as catering services and restaurant chains seek portion-controlled, labor-saving inputs.
Qatar's Ministry of Municipality and Environment enforces live animal import quarantines and slaughterhouse licensing that directly constrain supply velocity and elevate compliance costs for cross-border traders. The national food security strategy, administered through the Ministry of Commerce and Industry, mandates strategic reserve thresholds that reshape procurement calendars and storage infrastructure investment. Stakeholders must monitor how biosecurity certification reciprocity with Saudi Arabia and the UAE evolves, as this determines whether GCC-integrated supply chains or import-dependent spot markets prevail as Qatar's dominant sourcing architecture.
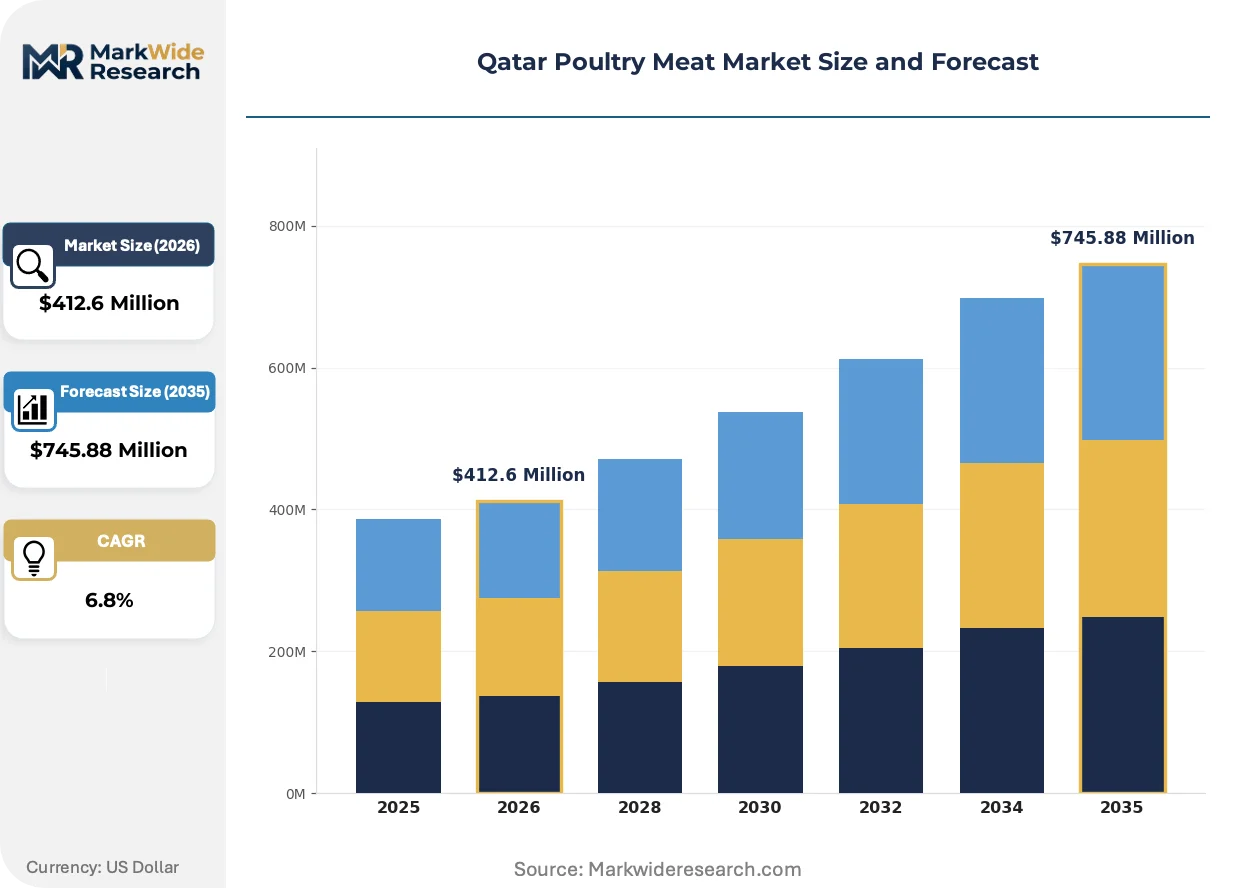
Market Dynamics
Qatar's poultry meat sector operates under sovereign wealth-backed procurement mandates that compress import dependency while channeling investment into controlled-environment farming infrastructure and strategic reserve warehousing across Doha and Al Wakrah.
Growth Catalysts
- Food Security Agenda:The Ministry of Commerce and Industry mandates strategic reserve thresholds that institutionalize procurement calendars and expand cold-chain storage capacity in the capital corridor.
- Hospitality Corridor Expansion:FIFA legacy tourism and expatriate population concentration in Doha sustain elevated foodservice demand for halal-certified portion-controlled poultry products.
- Biosecurity Protocol Harmonization:Reciprocity negotiations with Saudi Arabia and the UAE on live bird import certification accelerate GCC-integrated supply chain development versus spot-market sourcing.
Market Restraints
- Feedstock Import Dependency:Qatar's desert climate eliminates domestic grain production, binding operational margins to international soybean and corn price volatility routed through Jebel Ali transshipment.
- Live Bird Quarantine Friction:Ministry of Municipality and Environment import quarantines extend lead times for cross-border traders, constraining supply velocity during demand spikes.
- Fresh Product Substitution:Chilled and frozen imported cuts from Brazilian and Ukrainian processors compete on price against domestically raised whole birds in retail channels.
Strategic Opportunities
- Online Retail Channel Development:E-commerce platforms serving Doha's dense expatriate corridors enable direct-to-consumer distribution of vacuum-sealed specialty cuts bypassing traditional hypermarket intermediaries.
- Controlled-Environment Farming Scale-Up:Vertical integration into climate-controlled broiler houses reduces biosecurity exposure and shortens farm-to-shelf freshness windows for premium positioning.
- Halal Certification Export Alignment:Standardization with GCC mutual recognition frameworks positions Qatari processors for re-export into underserved markets across the broader Middle East.
Industry Challenges
- Veterinary Specialist Scarcity:The shallow talent pool for avian disease management and flock health optimization constrains expansion timelines for new controlled-environment facilities.
- Multi-Jurisdiction Compliance Burden:Simultaneous adherence to Ministry of Municipality and Environment slaughterhouse licensing, halal certification body requirements, and GCC import reciprocity protocols elongates product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Poultry Meat Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Chicken, Chicken Cut-ups, Chicken Breasts, Specialty Cuts Distribution Channel: Supermarkets, Hypermarkets, Online Retail, Local Markets Packaging Type: Tray Packs, Bulk Packs, Vacuum Sealed, Canned End User: Households, Restaurants, Catering Services, Food Processing |
| Companies Covered | A'Saffa Food S.A.O.G., Americana Group, BRF S.A., Hassad Food Company, JBS S.A., Mazzraty, Al-Watania Poultry, Almarai Company, Arab Qatari Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Poultry Meat Market Trends and Innovations
Automation and climate engineering are compressing production cycles while regulatory tightening around biosecurity and traceability reconfigures competitive advantage toward integrated operators with captive supply chains.
Controlled-environment poultry housing is hybridizing evaporative cooling systems with automated feeding and waste management infrastructure to maintain optimal flock density in Qatar's extreme heat. Industrial-scale operators in Doha and Al Wakrah are deploying these integrated systems to reduce mortality rates and standardize carcass weights for foodservice procurement. This technology convergence is hybridizing traditional open-house farming into precision livestock operations that command premium shelf positioning in retail channels.
The Ministry of Municipality and Environment's tightened biosecurity protocols for live bird imports now mandate extended quarantine periods and enhanced veterinary documentation for all cross-border shipments. This regulatory friction elevates compliance costs for spot-market traders while benefiting integrated domestic producers with captive breeding programs. Foodservice operators and hotel chains are responding by consolidating procurement around certified local suppliers with verified traceability systems rather than diversified import portfolios.
Foodservice buyers are consolidating procurement relationships around integrated distributors offering bundled halal certification, portion-controlled processing, and refrigerated logistics rather than fragmented spot sourcing. Restaurant chains across Doha's hospitality corridor now specify farm-to-fork traceability requirements that displace commodity traders lacking captive supply chain visibility. This concentration pattern is most visible in the capital's FIFA legacy tourism zone, where procurement managers prioritize supplier consolidation to reduce vendor management overhead and compliance audit burden.
Qatar Poultry Meat Market Segmentation
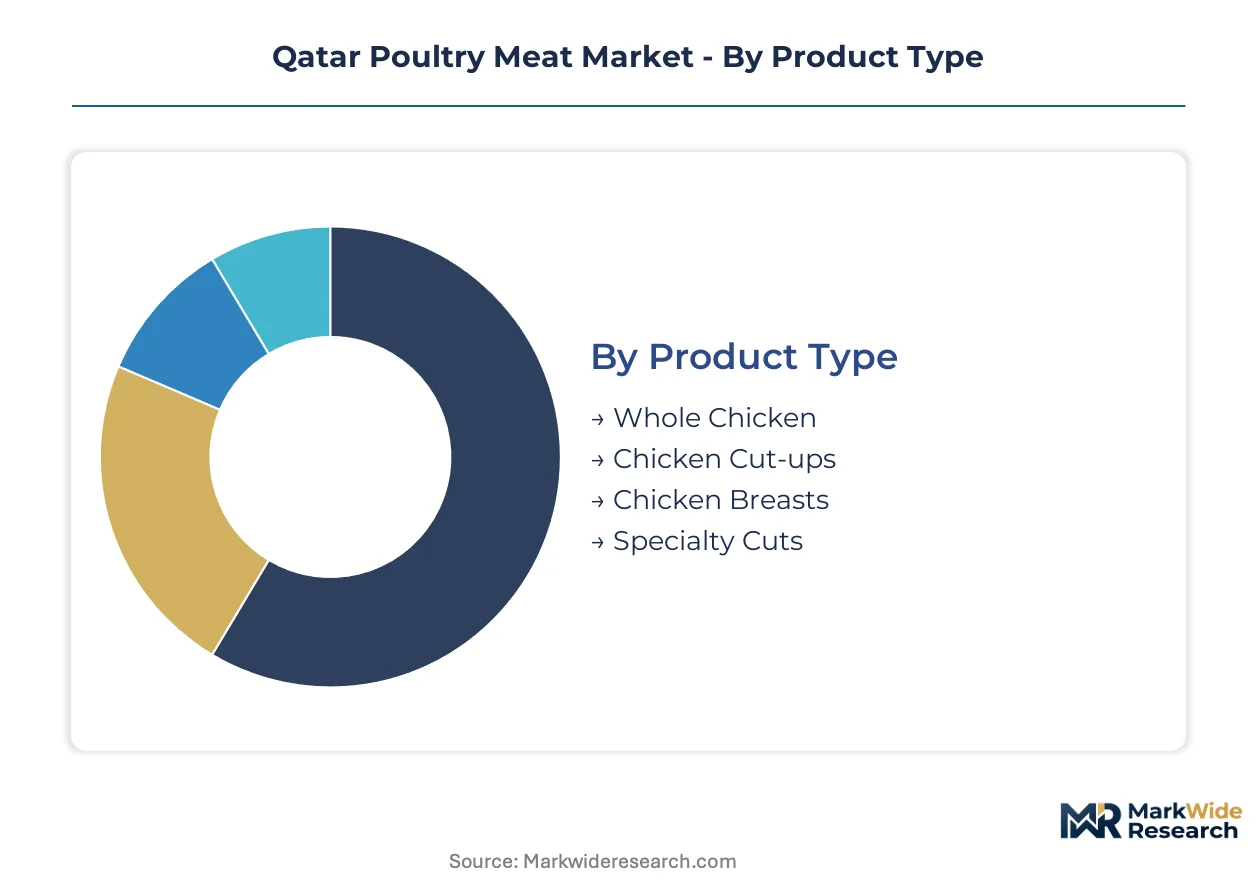
Segmentation in Qatar's poultry meat market reveals how halal certification requirements, cold-chain infrastructure, and hospitality procurement patterns create distinct margin pools across product formats and channel tiers. Understanding these divides exposes where sovereign wealth investment and food security mandates concentrate commercial opportunity.
Product Type:
After-sales service intensity varies sharply across product categories, with whole birds demanding minimal processing support while specialty cuts require sustained technical consultation on portion control and inventory rotation.
- Whole Chicken:Intact carcasses processed to halal standards with specified pH and moisture retention parameters serve traditional household preparation methods across Doha's Qatari and expatriate communities. Supermarkets in the capital corridor move highest volumes during Ramadan and FIFA legacy tourism peaks when extended-family dining elevates demand for roasting formats.
- Chicken Cut-ups:Standardized portioned pieces—drumsticks, thighs, wings—reduce kitchen labor for foodservice operators while maintaining yield consistency. Restaurant chains along Doha's hospitality corridor specify cut-up procurement for menu standardization, though these segments compete directly with Brazilian frozen imports on price.
- Chicken Breasts:Lean protein portions dominate health-conscious retail and catering segments.
- Specialty Cuts:Marinated, deboned, or value-added preparations command premium positioning in online retail.
Whole chicken holds the largest share; momentum sits with specialty cuts.
Distribution Channel:
Channel cost tiers separate capital-intensive cold-chain operators from fragmented spot-market traders, with margin structures reflecting compliance burden and inventory risk allocation.
- Supermarkets:Controlled-environment display cases with temperature monitoring and halal certification documentation serve daily household replenishment across Doha and Al Wakrah. Lulu Hypermarket and Carrefour Qatar anchor this channel, leveraging existing fresh produce logistics for tray-pack poultry distribution.
- Hypermarkets:Large-format stores with dedicated poultry sections and in-house butchery services capture bulk purchasing occasions. These outlets concentrate in Doha's retail corridors, where expatriate families and institutional buyers source volume for freezer stocking ahead of demand spikes.
- Online Retail:E-commerce platforms with vacuum-sealed delivery and subscription models gain traction among time-constrained professionals.
- Local Markets:Traditional souks and neighborhood traders serve price-sensitive segments with limited cold-chain requirements.
Supermarkets hold the largest share; online retail is climbing the fastest.
Packaging Type:
Packaging margin structures reflect supply concentration among integrated processors with captive slaughterhouse and film-sealing capabilities versus commodity traders reliant on third-party conversion.
- Tray Packs:Modified-atmosphere packaging with absorbent pads and clear film lidding extends shelf life for retail display while enabling visual quality assessment. This format dominates Lulu and Carrefour poultry sections, where presentation standards and halal certification labeling command price premiums over bulk alternatives.
- Vacuum Sealed:Barrier-film evacuation eliminates oxygen exposure, doubling refrigerated shelf life for online retail and export-oriented processors. A'Saffa Food and Almarai Qatar deploy this format for specialty cuts targeting Doha's premium hospitality procurement.
- Bulk Packs:Unsealed polybags for institutional and food processing buyers prioritize cost over presentation.
- Canned:Thermally processed poultry in brine serves emergency reserve and military catering requirements.
Tray packs hold the largest share; vacuum sealed is gaining share fastest.
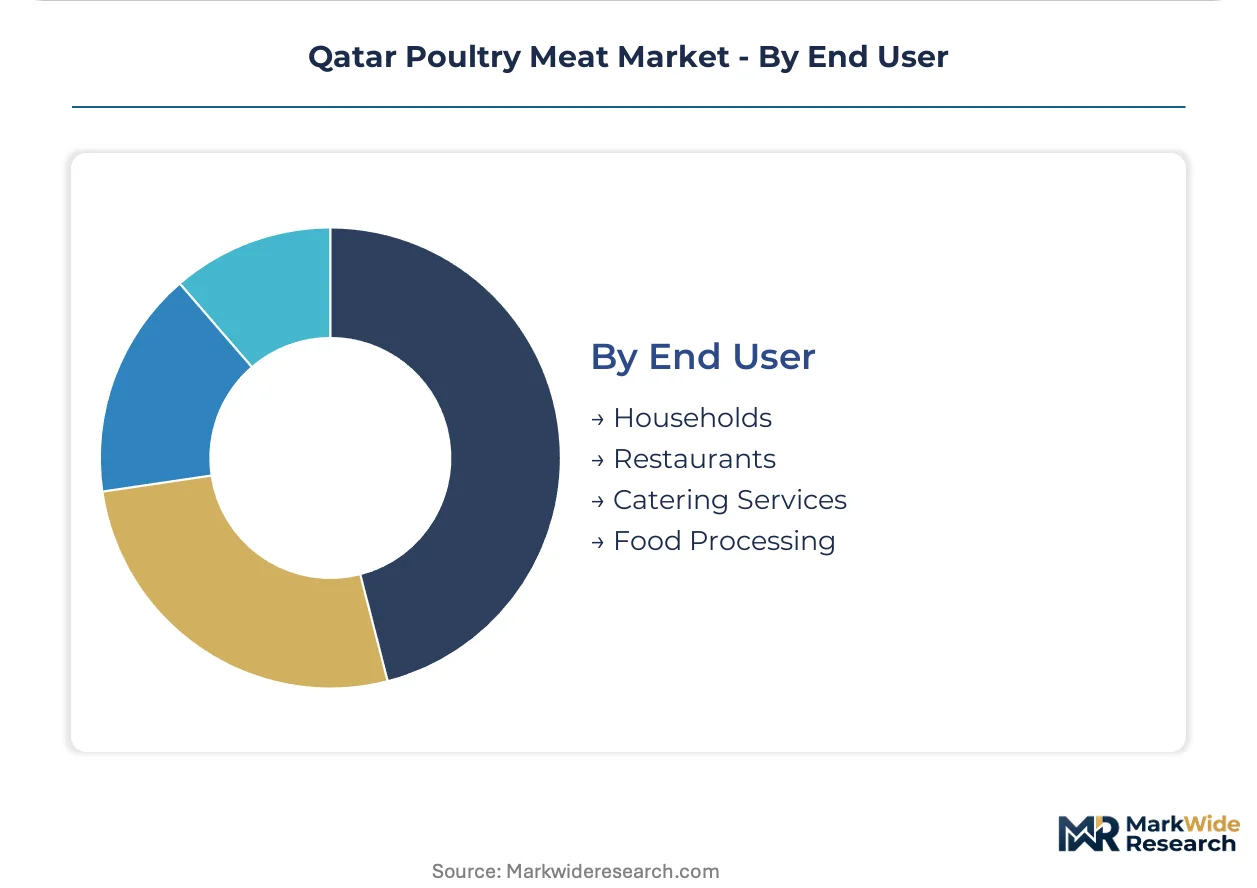
End User:
Customer type maturity separates established hospitality procurement with formal tender processes from fragmented household purchasing with minimal supplier loyalty.
- Restaurants:FIFA legacy tourism and expatriate population concentration sustain elevated demand for halal-certified, portion-controlled inputs with farm-to-fork traceability. Chains in Doha's West Bay and The Pearl districts specify cut-up and specialty formats to reduce kitchen labor and standardize plate costs across outlets.
- Catering Services:Institutional feeding for corporate events, airlines, and government functions requires volume consistency and just-in-time delivery windows. These buyers consolidate procurement around integrated distributors offering bundled halal certification and refrigerated logistics rather than fragmented spot sourcing.
- Households:Daily consumption across Qatari nationals and expatriate communities drives whole bird and cut-up demand.
- Food Processing:Further-manufacturing inputs for ready-meal and snack production represent a developing segment.
Restaurants hold the largest share; catering services show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity across Qatar's sub-regions varies sharply, with Doha's hospitality corridor absorbing premium pricing while Al Wakrah and northern municipalities remain sensitive to Brazilian import competition.
Doha Capital Corridor
FIFA legacy tourism and expatriate population density sustain elevated foodservice demand for halal-certified portion-controlled poultry. The Ministry of Municipality and Environment enforces live bird import quarantines that extend lead times for cross-border traders. West Bay and The Pearl districts concentrate procurement consolidation among hotel chains seeking farm-to-fork traceability.
Al Wakrah Industrial Zone
Controlled-environment farming infrastructure clusters here to exploit lower land costs while maintaining Doha market access. Strategic reserve warehousing mandated by the Ministry of Commerce and Industry anchors cold-chain investment in this corridor. Integrated processors deploy automated feeding systems to standardize carcass weights for institutional catering contracts.
Al Khor Northern Municipality
Price-sensitive household consumption dominates retail purchasing patterns in this sub-region. Traditional souk channels persist with limited cold-chain requirements, competing directly with Brazilian frozen cut-up imports. Feedstock import dependency through Jebel Ali transshipment binds operational margins to international grain price volatility.
Umm Salal Central Belt
Logistics intermediaries cluster along the Doha-Al Khor highway to exploit route density for chilled distribution. Biosecurity certification reciprocity negotiations with Saudi Arabia and the UAE determine whether GCC-integrated supply chains or spot-market sourcing prevails. Veterinary specialist scarcity constrains expansion timelines for new controlled-environment facilities.
Al Shamal Northern Peninsula
Remote location limits fresh product penetration, creating reliance on frozen inventory and extended shelf-life formats. Military and institutional catering represent concentrated demand pockets with emergency reserve requirements. Online retail platforms with vacuum-sealed delivery gain traction among time-constrained professionals in this underserved corridor.
Qatar Poultry Meat Market Competitive Landscape
Capability concentration sits with integrated operators controlling captive supply chains; scale advantage sits with diversified GCC conglomerates leveraging existing logistics infrastructure. Sovereign wealth-backed procurement mandates reshape competitive positioning toward domestic production capacity rather than import trading relationships. Three archetypes dominate: fully integrated farm-to-retail operators, logistics-extended dairy conglomerates, and sovereign wealth-backed food security vehicles. Capacity expansion in controlled-environment housing and strategic partnerships for feedstock security represent the dominant competitive moves.
Within the integrated operator tier, A'Saffa Food S.A.O.G. exemplifies cross-border supply chain control through its Omani-Qatari infrastructure, while Hassad Food Company anchors sovereign wealth-backed procurement archetype. Almarai Company represents logistics-extended diversification, deploying GCC dairy cold-chain infrastructure into chilled poultry distribution. These three occupy positions that align with Qatar's food security agenda while competing on distinct capability vectors.
| Leading Market Players |
|---|
| A'Saffa Food S.A.O.G. |
| Americana Group |
| BRF S.A. |
| Hassad Food Company |
| JBS S.A. |
| Mazzraty |
| Al-Watania Poultry |
| Almarai Company |
| Arab Qatari Company |
| Others |
Pricing and Supply Chain Analysis
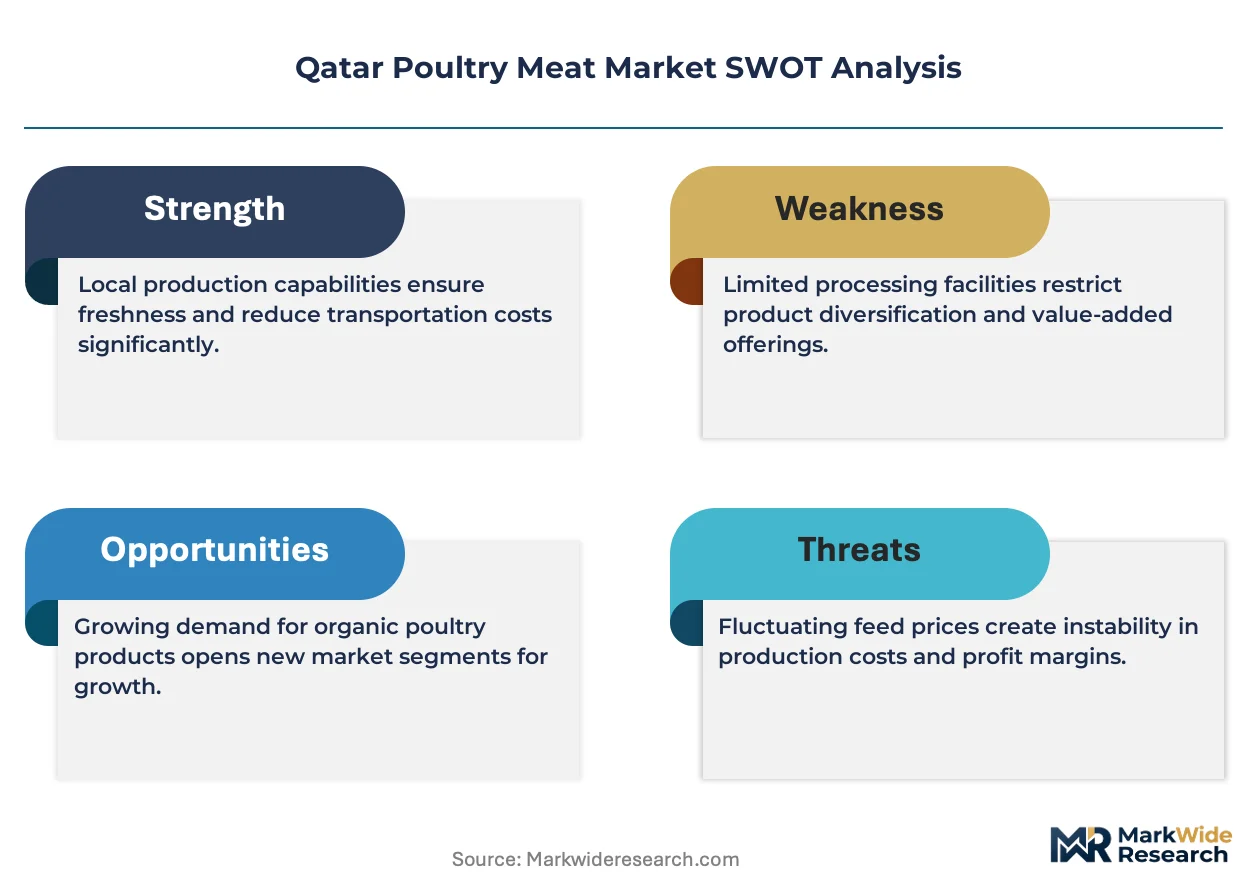
Controlled-environment farming overcapacity in Al Wakrah is compressing farm-gate margins while elevating cold-chain logistics premiums, forcing integrated processors to arbitrage freshness windows against Brazilian import spot pricing in Doha's retail corridors.
Pricing Analysis
After-sales service revenue from halal certification compliance and refrigerated logistics contracts drives lifetime value more than raw commodity trading. Three-tier pricing structure across premium vacuum-sealed specialty cuts, standard tray-pack retail formats, and economy bulk packs for institutional buyers stratifies the market. Cost compression in the standard tier is intensifying because Brazilian frozen cut-ups compete directly on landed cost. Households in Al Khor and northern municipalities exhibit highest price sensitivity, while FIFA legacy hotel chains in West Bay absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Feedstock import dependency through Jebel Ali transshipment exposes Qatar's poultry sector to international soybean and corn price volatility routed from Brazil, Argentina, and the United States. Operational margins rest on grain futures hedging and strategic reserve warehousing mandated by the Ministry of Commerce and Industry. Single-source vulnerability concentrates in live breeding stock imports subject to Ministry of Municipality and Environment quarantine extensions. Distribution runs through integrated operators with captive slaughterhouse-to-retail cold chains rather than fragmented spot-market traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with online retail channel development as Doha's expatriate professionals shift procurement toward subscription-based vacuum-sealed delivery bypassing traditional hypermarket intermediaries.
For Market Incumbents: Entrench control by expanding controlled-environment farming capacity in Al Wakrah to capture sovereign wealth-backed procurement mandates, while deepening backward integration into feedstock security through strategic grain partnerships that neutralize Brazilian import price competition. Certification investment in GCC halal mutual recognition frameworks creates defensive moats against emerging Omani and Saudi integrated operators. For New Entrants and Emerging Players: Al Shamal Northern Peninsula's underserved corridor offers white-space penetration where frozen inventory reliance and limited fresh product access create vacuum-sealed delivery opportunity. Target time-constrained professionals in remote institutional catering pockets with direct-to-consumer platforms. A go-to-market angle anchored in emergency reserve procurement specifications for military and government functions bypasses entrenched retail channel competition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across controlled-environment housing infrastructure as automated feeding and climate engineering systems displace open-house farming. Long-term viability favors acquisition of integrated operators with captive breeding programs and verified traceability systems rather than import-dependent trading entities. The signal to watch as inflection indicator is biosecurity certification reciprocity progression with Saudi Arabia and the UAE.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Environment Farming Scale-Up | Al Wakrah infrastructure expansion reduces mortality rates and standardizes carcass weights for institutional contracts. |
| Halal Certification Export Alignment | GCC mutual recognition frameworks position Qatari processors for re-export into underserved Middle Eastern markets. |
| Online Retail Channel Development | E-commerce platforms with vacuum-sealed delivery bypass traditional hypermarket intermediaries in Doha's dense expatriate corridors. |
| Feedstock Security Partnership | Strategic grain alliances through Jebel Ali transshipment neutralize international soybean and corn price volatility exposure. |
| Cold-Chain Logistics Integration | Refrigerated distribution networks from Al Wakrah to West Bay hospitality corridors capture premium freshness-window positioning. |
Research Methodology
A spread of perspectives from poultry farm operations managers, Ministry of Municipality and Environment veterinary inspectors, hotel procurement directors in Doha's West Bay corridor, and hypermarket category buyers converged on the working assumptions. Primary interviews with controlled-environment housing equipment suppliers and halal certification body auditors combined with secondary validation from Qatar Chamber of Commerce trade statistics, Ministry of Commerce and Industry food security policy documents, and GCC customs harmonization frameworks. Bottom-up triangulation across farm-level capacity data and top-down cross-checks against sovereign wealth procurement mandates anchored volume estimates.
Demand-supply-balance framing modeled consumption patterns across the projection horizon, with segmentation dimensions including product format, packaging type, distribution channel tier, and end-use customer maturity. CAGRs derived from trend extrapolation of FIFA legacy tourism flows, expatriate population concentration shifts, and biosecurity protocol evolution scenarios. Industry-specific forecast inputs incorporated feedstock import cost trajectories through Jebel Ali and controlled-environment farming mortality rate improvements from automation deployment.
Macroeconomic conditions sit as an overlay; deviation in international grain futures, GCC currency peg stability, or regional tourism recovery velocity would shift the trajectory. Forecasts reflect working assumptions about regulatory reciprocity timelines and infrastructure investment continuity that continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Reduced Fat Meat Market
Meat Products
Mexico Meat Products Market
Meat Products
India Animal Protein Market
Meat Products
United States Processed Pork Meat Market
Meat Products
United Arab Emirates Edible Meat Market
Meat Products
Organic Pork Market
Meat Products
Bacon Slicers Market
Meat Products
United Arab Emirates Red Meat Market
Meat Products
Global Beef Market
Meat Products
Grass Fed Beef Market
Meat Products
Global Canned Meat Market
Meat Products
Western Europe Ready-To-Eat Meat Market
Meat Products
US Meat Market
Meat Products
Europe Processed Meat Market
Meat Products
Animal Protein Market
Meat Products
Canned Chicken Market