
 Bacon Market | 2026-2036
Bacon Market Size, Share, and Industry Trends Forecast 2026-2036
Bacon Market Intelligence
A widening capital-intensity gap between integrated pork processors and regional packers is reorganizing competitive tiers in the bacon industry. Smithfield Foods leverages vertical integration from farm to sliced retail packs, sustaining cost advantages in raw material procurement. Hormel Foods differentiates through branded value-added lines like Applewood-smoked varieties, while Tyson Foods competes on manufacturing scale across multiple protein categories.
Bacon comprises cured and smoked pork belly strips, typically processed with salt, nitrates or nitrites, and thermal treatment to achieve specific moisture-to-protein ratios and shelf stability for commercial food preparation. Pork bacon dominates volume across retail and foodservice channels, while turkey bacon anchors the fastest-growing segment as health-conscious households and restaurant chains seek reduced-fat alternatives. Vacuum-sealed packaging commands premium shelf positioning in supermarkets, whereas bulk formats serve high-volume restaurant and institutional buyers where margin pools concentrate on price-per-pound efficiency.
USDA FSIS labeling standards and FDA sodium reduction initiatives shape product formulation decisions and marketing claims for domestic manufacturers. The EU EFSA and national regulators enforce stricter nitrite limits and animal welfare specifications that constrain export-oriented production configurations. Stakeholders must monitor evolving clean-label preferences against the technical requirements of cured meat preservation to align R&D investment with shifting retail buyer specifications.
Market Dynamics
USDA FSIS sodium reduction mandates and FDA nitrite labeling requirements are compressing formulation flexibility for domestic processors while accelerating clean-label R&D investment cycles across the cured meats sector.
Growth Catalysts
- Quick-service restaurant breakfast expansion:Chains like McDonald's and Wendy's are embedding bacon into permanent and limited-time morning menus, pulling volume through foodservice procurement channels.
- Turkey bacon health positioning:Reduced-fat alternatives are capturing households and institutional buyers seeking to meet FDA dietary guidelines without eliminating cured meat categories entirely.
- Clean-label curing technologies:Celery juice powder and natural nitrate sources are supplanting synthetic nitrites in premium retail lines, satisfying buyer specifications at Whole Foods and regional natural grocers.
Market Restraints
- Feed grain cost volatility:Corn and soybean price swings transmit directly into pork belly input costs, squeezing processor margins without contracted supply agreements.
- Midwestern packing concentration:Iowa and Minnesota slaughter capacity dominates domestic supply, creating geographic vulnerability to disease outbreaks and logistics disruptions.
- EU EFSA nitrite limits:Stricter European additive ceilings constrain export-oriented production configurations, fragmenting formulation standards between domestic and international lines.
Strategic Opportunities
- Plant-based bacon white space:Pea protein and mycelium formulations are penetrating flexitarian households, opening shelf positioning beyond traditional pork and turkey segments.
- Direct-to-consumer subscription channels:Artisanal smokehouses are bypassing retail slotting fees through monthly cured meat boxes, capturing lifetime value from enthusiast segments.
- USDA organic certification tailwind:Premium pricing for certified organic bacon is expanding as Costco and Target allocate dedicated cooler space to differentiated protein tiers.
Industry Challenges
- Smokehouse operator skill scarcity:Traditional hardwood smoking expertise is aging out of the workforce faster than vocational programs can replenish qualified technicians.
- Clean-label shelf-life compression:Natural curing methods reduce water activity control precision, forcing faster inventory turns and tighter cold-chain coordination with distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bacon Market |
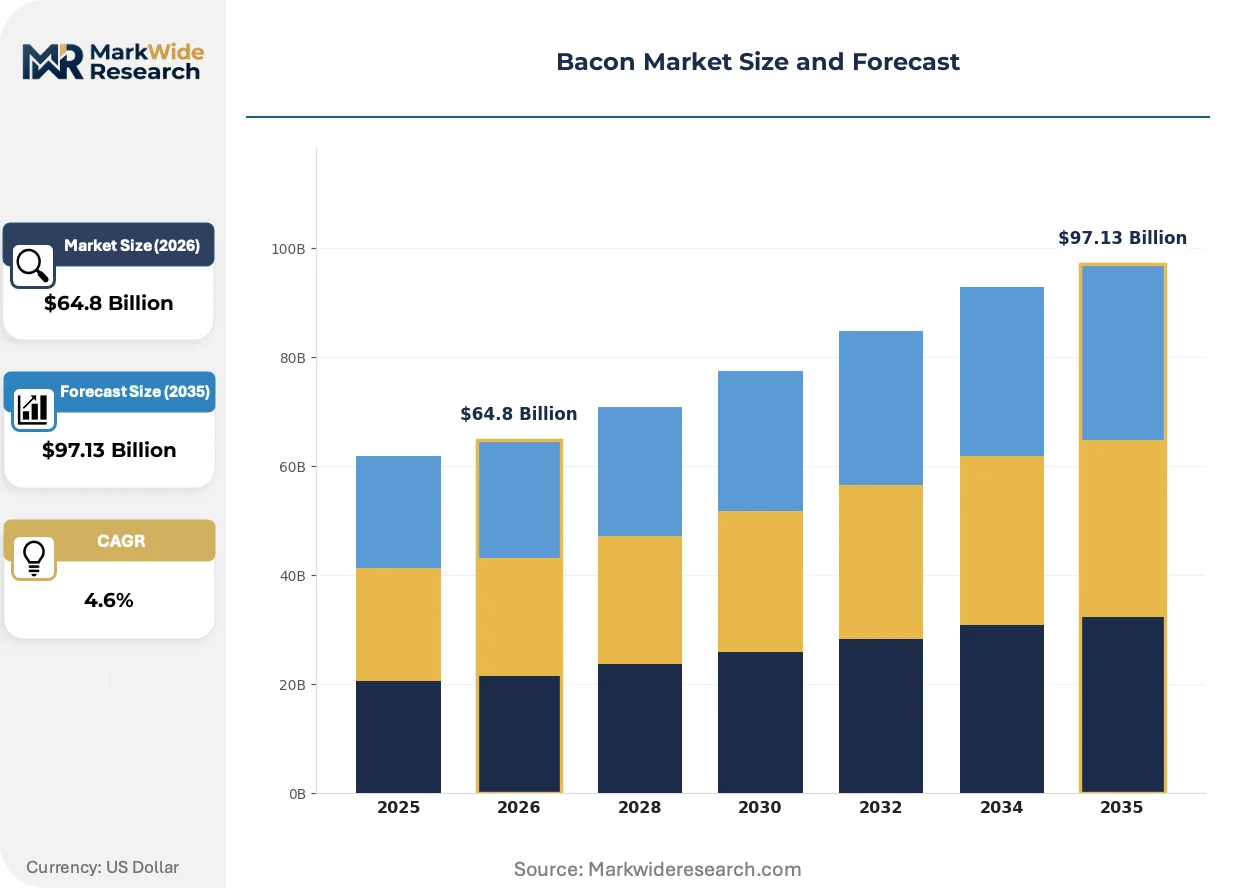
| Market Size in 2026 | $64.8 Billion |
| Market Size in 2035 | $97.13 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pork Bacon, Turkey Bacon, Beef Bacon, Veggie Bacon Processing Method: Smoked, Cured, Uncured, Fried Packaging Type: Vacuum-Sealed, Plastic Wrap, Skewered, Bulk End User: Households, Restaurants, Food Service, Retailers |
| Companies Covered | Maple Leaf Foods Inc., Smithfield Foods Inc., Tyson Foods Inc., Sugar Creek Packing Co., Fresh Mark Inc., Hormel Foods Corporation, JBS SA, Seaboard Corporation, The Kraft Heinz Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bacon Market Strategic Shifts & Innovations
Processing technology, regulatory compliance architecture, and procurement channel structure are simultaneously transforming how cured pork products move from slaughter to final preparation.
High-pressure processing (HPP) is supplanting traditional thermal pasteurization in premium sliced bacon packs, extending refrigerated shelf life without sodium escalation. Regional processors in California and Vermont are adopting HPP lines to meet retailer demands for extended code dates on clean-label products. This technology is compressing the advantage previously held by mass-market brands with superior distribution velocity.
EU EFSA is tightening nitrosamine risk assessments, forcing reformulation across export-oriented production and influencing FDA deliberation timelines. Manufacturers serving both markets are converging on lower nitrite ceilings to maintain single-SKU efficiency. Small-batch processors in Denmark and Italy are already marketing sub-50ppm residual nitrite lines as compliance-ready ahead of anticipated rulemaking.
Foodservice buyers are consolidating procurement through broadline distributors, squeezing direct relationships between packers and independent restaurants. Sysco and US Foods are capturing bacon category management decisions previously made by individual operators. This concentration is most visible in the Southeast, where regional chain expansion is accelerating volume commitments to national distribution contracts.
Bacon Market Segmentation
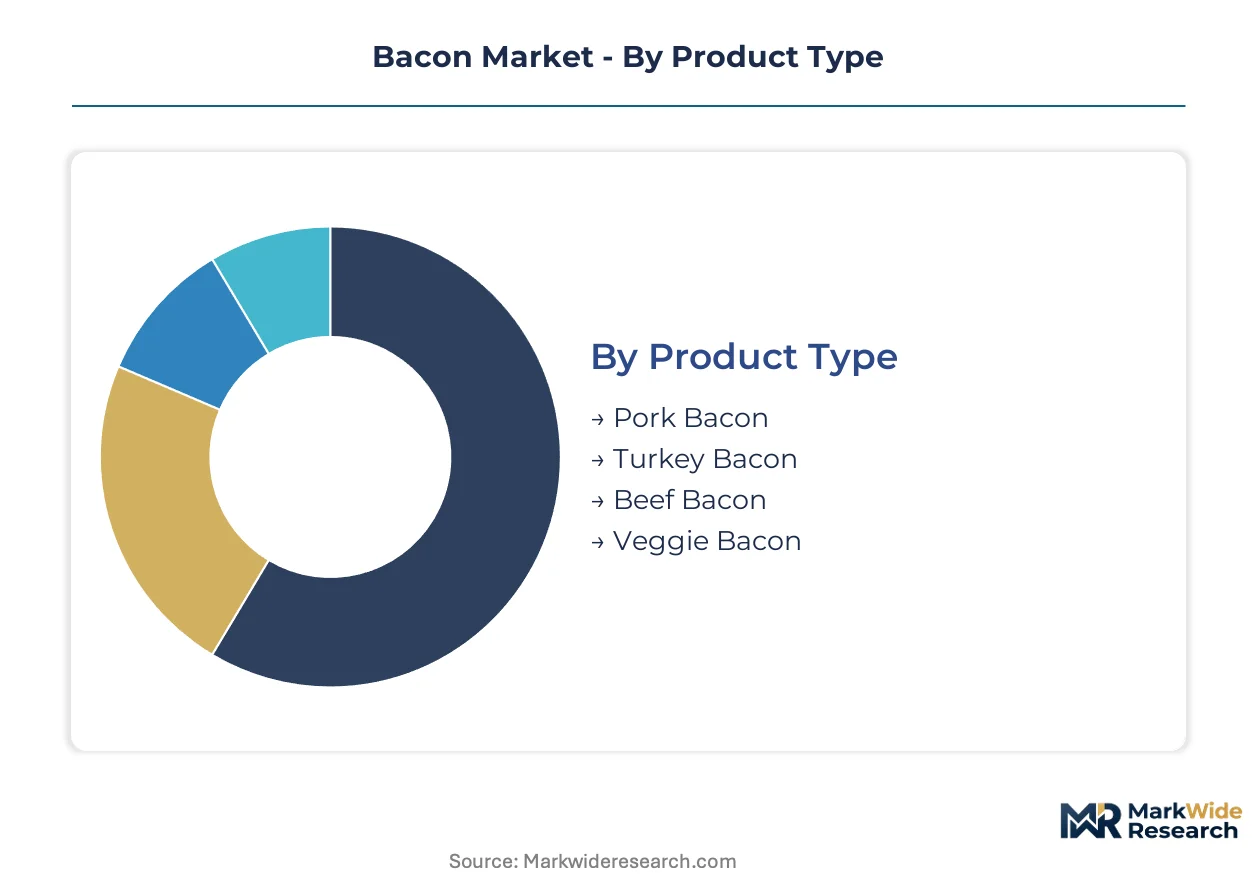
Bacon market segmentation reveals distinct margin architectures across product types, processing methods, packaging formats, and end-user channels. Each dimension carries specific procurement patterns and regulatory exposure that reshape competitive positioning.
Product Type:
Pork bacon commands the deepest margin pools through branded premium positioning and foodservice contract premiums, while turkey bacon captures health-conscious substitution demand at elevated unit economics.
- Pork Bacon:Cured and smoked pork belly strips processed with salt, nitrates or nitrites, and thermal treatment to achieve specific moisture-to-protein ratios. United States households and quick-service restaurant chains anchor demand, with USDA FSIS oversight tightening sodium reduction and nitrite labeling standards that compress formulation flexibility.
- Turkey Bacon:Mechanically separated turkey meat formed into strips with smoke flavoring and curing agents, delivering reduced fat content versus pork alternatives. Health-conscious households and institutional buyers seeking FDA dietary guideline compliance without eliminating cured meat categories entirely are expanding procurement.
- Beef Bacon:Cured beef belly or plate cuts smoked over hardwood, offering halal-compliant positioning for specific demographic segments and Middle Eastern export markets.
- Veggie Bacon:Plant-based formulations using pea protein, soy, or mycelium to replicate texture and umami profiles for flexitarian households.
Pork bacon holds installed capacity. Turkey bacon is rotating up the share rankings.
Processing Method:
Cost tier stratification separates artisanal smokehouse operations from industrial thermal processing, with uncured premium positioning capturing shelf-space allocation at Whole Foods and regional natural grocers.
- Smoked:Traditional hardwood smoking over applewood, hickory, or maple imparts distinctive flavor compounds through controlled temperature and humidity exposure. Regional smokehouses in Vermont and California leverage this method for clean-label retail differentiation.
- Cured:Synthetic nitrite or natural nitrate sources combined with salt and thermal treatment achieve shelf stability and characteristic pink coloration. USDA and FSIS oversight of sodium reduction mandates is accelerating reformulation investment cycles.
- Uncured:Celery juice powder and natural nitrate sources replace synthetic additives, satisfying buyer specifications for clean-label positioning while compressing water activity control precision.
- Fried:Pre-cooked strips finished to specified crispness for foodservice operational efficiency and reduced kitchen labor.
Smoked processing anchors artisanal premium tiers. Uncured methods are climbing the fastest.
Packaging Type:
Volume concentration in foodservice procurement channels favors bulk formats, while retail premium positioning concentrates in vacuum-sealed configurations with extended code dates.
- Vacuum-Sealed:Modified atmosphere packaging removes oxygen to inhibit microbial growth and extend refrigerated shelf life. High-pressure processing adoption in California and Vermont enables clean-label products to meet retailer demands for extended code dates.
- Plastic Wrap:Standard overwrap configurations for immediate-consumption retail packs with shorter inventory turns and lower unit cost.
- Skewered:Pre-portioned strips on wooden or bamboo sticks for appetizer and catering applications.
- Bulk:Foodservice cases and institutional totes serving high-volume restaurant and institutional buyers where margin pools concentrate on price-per-pound efficiency.
Bulk packaging holds foodservice procurement scale. Vacuum-sealed formats are rotating up the share rankings.
End User:
Customer type determines channel margin capture, with broadline distributor consolidation squeezing direct packer relationships and subscription channels bypassing retail slotting fees.
- Households:Retail grocery and club store purchasers selecting branded or private-label packs for home preparation. Costco and Target allocation of dedicated cooler space to certified organic tiers is expanding premium pricing capture.
- Restaurants:Independent operators and chain accounts sourcing through Sysco and US Foods broadline distribution, with category management decisions shifting from individual operators to distributor procurement teams.
- Food Service:Institutional cafeterias, healthcare facilities, and educational institutions procuring through contracted supply agreements with specification compliance requirements.
- Retailers:Supermarket chains, club stores, and natural grocers managing slotting fees, planogram positioning, and private-label development.
Restaurant channels hold broadline distribution scale. Direct-to-consumer subscription models are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States outstrips Canadian and Mexican markets by double-digit percentage points on premium branded lines. European consumers resist comparable price elevation due to stricter nitrite ceilings and welfare standards. Asian demand remains nascent, with Japan and South Korea importing select premium cuts rather than building domestic processing scale.
United States
Quick-service restaurant breakfast expansion and club-store organic allocation pull disproportionate volume through domestic channels. USDA FSIS sodium reduction mandates and FDA nitrite labeling requirements compress formulation flexibility while accelerating clean-label R&D investment cycles. Iowa and Minnesota slaughter capacity anchors supply concentration, with disease outbreaks and logistics disruptions creating geographic vulnerability.
Canada
Health Canada oversight of processed meat sodium content shapes product formulation decisions for cross-border retail lines. Maple Leaf Foods anchors integrated pork processing from farm to retail pack, sustaining cost advantages in raw material procurement. Ontario and Quebec packing plants serve both domestic distribution and US export channels under USMCA tariff preferences.
Germany
EFSA nitrosamine risk assessments and stricter additive ceilings constrain export-oriented production configurations for processors serving EU markets. Bavarian and North Rhine-Westphalian smokehouses market sub-50ppm residual nitrite lines as compliance-ready ahead of anticipated rulemaking. German consumers demonstrate willingness to pay premiums for welfare-certified pork, though price elasticity limits branded bacon expansion.
United Kingdom
Post-Brexit regulatory divergence from EU EFSA standards creates formulation complexity for processors maintaining continental export relationships. British Retail Consortium specifications on clean-label positioning drive celery juice powder adoption in premium supermarket lines. East Anglian and Yorkshire processing clusters concentrate on domestic foodservice contracts rather than continental retail penetration.
Japan
Foodservice buyers in Tokyo and Osaka metropolitan areas import select US premium bacon for hotel and restaurant applications rather than developing domestic curing infrastructure. Ministry of Health, Labour and Welfare standards on processed meat additives limit nitrite levels below North American ceilings. Japanese per-capita consumption remains fractional versus Western markets, constraining processor investment in localized production.
Bacon Market Key Industry Players
Concentration sits with integrated pork processors controlling captive hog supply and national distribution networks. Smithfield Foods and Tyson Foods exemplify scale-driven archetypes leveraging manufacturing capacity across multiple protein categories. Hormel Foods occupies a branded value-added position through Applewood-smoked differentiation. Two dominant competitive moves define current positioning: backward integration into hog farming to secure raw material cost stability, and portfolio diversification into turkey and plant-based alternatives to capture health-conscious substitution demand.
Among North American integrated processors, Smithfield Foods, Tyson Foods, and Hormel Foods exemplify the three strategic archetypes shaping competitive dynamics. Smithfield represents vertical control from farm to retail pack. Tyson anchors multi-protein manufacturing scale. Hormel occupies branded premium positioning through specialty smokehouse lines. Each sits within a distinct margin architecture: captive supply efficiency, volume throughput optimization, or price-premium capture through differentiation.
| Leading Market Players |
|---|
| Maple Leaf Foods Inc. |
| Smithfield Foods Inc. |
| Tyson Foods Inc. |
| Sugar Creek Packing Co. |
| Fresh Mark Inc. |
| Hormel Foods Corporation |
| JBS SA |
| Seaboard Corporation |
| The Kraft Heinz Company |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between Iowa-based packers and quick-service restaurant chains lock in hog supply visibility while insulating procurement teams from spot-market belly price swings. These agreements concentrate margin capture among integrated processors with captive slaughter capacity, leaving regional smokehouses exposed to feed grain cost transmission.
Pricing Analysis
Configured-to-order pricing for Applewood-smoked and certified organic strips commands a 40-60% premium over standard retail packs, with three-tier pricing structure across premium, standard, and economy levels stratifying the market. Price differentiation rests on USDA organic certification and smokehouse labor intensity as primary drivers. Cost compression in economy-tier private-label lines is intensifying because corn and soybean price volatility transmits directly into pork belly input costs. Quick-service restaurant chains exhibit the highest price sensitivity due to food-labor cost ratios, while direct-to-consumer subscription buyers show the least.
Supply Chain Analysis
Midwestern packing concentration creates a chokepoint where Iowa and Minnesota slaughter capacity processes over 60% of domestic hog supply, tethering national bacon output to geographic disease and logistics risk. Raw material flows draw from corn belt feed operations, Canadian feeder hog imports, and rendered fat suppliers. Single-source vulnerability concentrates in the JBS and Smithfield packing plant networks, where fire or disease shutdowns disrupt belly availability within days. Distribution runs through Sysco and US Foods broadline networks to restaurant chains, with Costco and Target capturing retail volume through direct packer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bacon market expansion sits in early-cycle penetration for plant-based and clean-label alternatives, with flexitarian household adoption accelerating faster than industry capacity buildout.
For Market Incumbents: Fortify hog supply control through backward integration into Iowa and Minnesota finishing operations, insulating against feed cost transmission and disease disruption. Expand HPP-equipped processing lines to meet Whole Foods and Target extended code-date specifications, defending shelf positioning against regional natural-grocers. Celery juice powder curing expertise represents a scarce capability worth acquiring through targeted smokehouse partnerships. For New Entrants and Emerging Players: Anchor in direct-to-consumer subscription channels to bypass retail slotting fees and capture lifetime value from enthusiast segments. Turkey bacon and mycelium-based alternatives offer the most penetrable white-space, with health-conscious households seeking FDA dietary guideline compliance without pork elimination. Launch through monthly cured meat boxes with heritage breed storytelling to build brand equity before retail expansion. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap smokehouses with USDA organic certification and established HPP infrastructure, positioned for Costco and Target cooler allocation expansion. Long-term viability hinges on clean-label curing technology mastery and distributor relationship depth. Monitor EU EFSA nitrosamine rulemaking timelines as an inflection signal for reformulation investment cycles and export-oriented production reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hog Farming | Smithfield and Tyson captive supply agreements insulate belly cost exposure from corn price volatility. |
| Clean-Label Curing Technology Investment | Celery juice powder adoption satisfies Whole Foods buyer specifications while compressing water activity control. |
| High-Pressure Processing Line Expansion | HPP-equipped California and Vermont processors meet retailer demands for extended code dates on uncured lines. |
| Direct-to-Consumer Channel Launch | Artisanal smokehouses bypass Sysco and US Foods consolidation to capture enthusiast segment lifetime value. |
| USDA Organic Certification Pursuit | Certified organic positioning unlocks dedicated cooler space allocation at Costco and Target premium tiers. |
Research Approach
Cross-validation between USDA slaughter data and FSIS inspection records anchors the qualitative findings, with primary interviews involving smokehouse operators, quick-service restaurant procurement directors, and broadline distributor category managers informing operational dynamics. Secondary validation draws from FDA sodium reduction guidance documents, EFSA nitrosamine risk assessments, and Nielsen retail audit data. Bottom-up modeling of processor capacity and top-down demand triangulation from foodservice procurement channels converge on volume estimates.
Sensitivity analysis across feed grain price scenarios and disease outbreak probabilities tests forecast robustness throughout the projection horizon. Segmentation dimensions include product type, processing method, packaging format, and end-user channel, with geographic regulatory clusters modeled separately. CAGRs derive from trend extrapolation of per-capita consumption patterns and quick-service restaurant menu expansion rates, incorporating HPP adoption curves and clean-label SKU growth as industry-specific inputs.
Material uncertainties — EU EFSA nitrite limit revisions, African swine fever geographic spread, and plant-based formulation breakthroughs — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory timelines and substitution elasticity. Practitioners should keep alternative scenarios live as clean-label shelf-life compression and smokehouse operator skill scarcity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Middle East Edible Meat Market
Meat Products
Qatar Poultry Meat Market
Meat Products
Europe Bacon Market
Meat Products
Global Duck Meats Market
Meat Products
United States Red Meat Market
Meat Products
Asia-Pacific Edible Meat Market
Meat Products
Poultry Processing Meat Market
Meat Products
Saudi Arabia Red Meat Market
Meat Products
Europe Canned Meat Market
Meat Products
United Arab Emirates Edible Meat Market
Meat Products
3D Printed Meat Market
Meat Products
North America Red Meat Market
Meat Products
Western Europe Ready-To-Eat Meat Market
Meat Products
Global Beef Market
Meat Products
United States Animal Protein Market
Meat Products
North America Processed Pork Meat Market