
 Organic Chicken Market | 2026-2036
Organic Chicken Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Chicken Market Analysis
Portion-controlled and value-added packaging is hardening as the dominant configuration pattern, shifting buyer choice from commodity whole birds toward pre-cut, marinated, and ready-to-cook offerings. Tyson Foods, Inc. leverages its vertically integrated supply chain to dominate fresh and frozen organic SKUs across mass retail. Perdue Farms, Inc. differentiates through its no-antibiotics-ever positioning and controlled-atmosphere packaging investments. Bell & Evans sustains premium shelf space by specializing in air-chilled processing and extended shelf-life formats.
Organic chicken denotes poultry raised on certified organic feed without antibiotics or synthetic hormones, with birds accessing outdoor space and meeting specific stocking density thresholds; the USDA Organic seal mandates compliance with National Organic Program standards covering feed, living conditions, and processing. The primary commercial purpose centers on supplying protein to health-conscious consumers, institutional food service, and premium retail channels seeking verified clean-label attributes. Whole chicken remains the volume anchor in club and discount formats, while chicken breasts command the deepest margin pools in specialty retail and direct-to-consumer channels. USDA Organic certification functions as the baseline market-access credential, though Animal Welfare Approved and Non-GMO Project Verified labels are carving out defensible premium tiers in coastal and urban markets.
USDA enforces the National Organic Program through accredited certifying agents, auditing feed sourcing, outdoor access compliance, and slaughter facility separation from conventional operations. EPA oversight of poultry waste management and water discharge permits constrains expansion geography for large-scale organic operations. The EU Green Deal's Farm to Fork strategy and REACH-aligned feed additive restrictions create parallel compliance frameworks for exporters serving European buyers. Stakeholders must monitor evolving certifier interpretations of outdoor access rules and the pace at which quick-service chains codify organic sourcing into procurement mandates.
Market Dynamics
The organic chicken sector is restructuring around feed cost volatility and certifier enforcement of outdoor access rules, forcing producers to absorb margin compression or exit certification programs entirely.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Export-oriented producers are securing premium shelf space in German and French retail by aligning with REACH-aligned feed additive restrictions and animal welfare benchmarks.
- Quick-service restaurant procurement mandates:Chains in the United States are codifying organic poultry into supply agreements, pulling volume through contracted grower networks.
- Air-chilled processing technology:Extended shelf-life formats are penetrating direct-to-consumer channels and specialty retail, reducing cold-chain spoilage rates.
Market Restraints
- Organic feed grain price volatility:Corn and soybean meal costs swing with drought cycles in the US Midwest and Argentine export disruptions, compressing producer margins.
- Slaughter facility concentration:USDA-inspected organic kill capacity clusters in Pennsylvania, Georgia, and Arkansas, creating geographic bottlenecks for western growers.
- Conventional antibiotic-free chicken substitution:"No antibiotics ever" positioning at lower price points siphons price-sensitive buyers from certified organic SKUs.
Strategic Opportunities
- Japan's aging consumer base:Health-conscious seniors in Tokyo and Osaka are demonstrating sustained willingness to pay premium prices for verified clean-label protein.
- Controlled-atmosphere packaging convergence:Modified atmosphere and vacuum-skin technologies are extending case-ready product windows for retail delis.
- USDA Organic certification tailwind:The National Organic Program's updated livestock standards are creating first-mover advantages for early compliance investments.
Industry Challenges
- Veterinary talent scarcity:Poultry veterinarians trained in organic health management protocols remain concentrated near land-grant university extension programs.
- Multi-certification compliance timelines:Stacking Animal Welfare Approved, Non-GMO Project Verified, and USDA Organic audits extends approval cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Chicken Market |
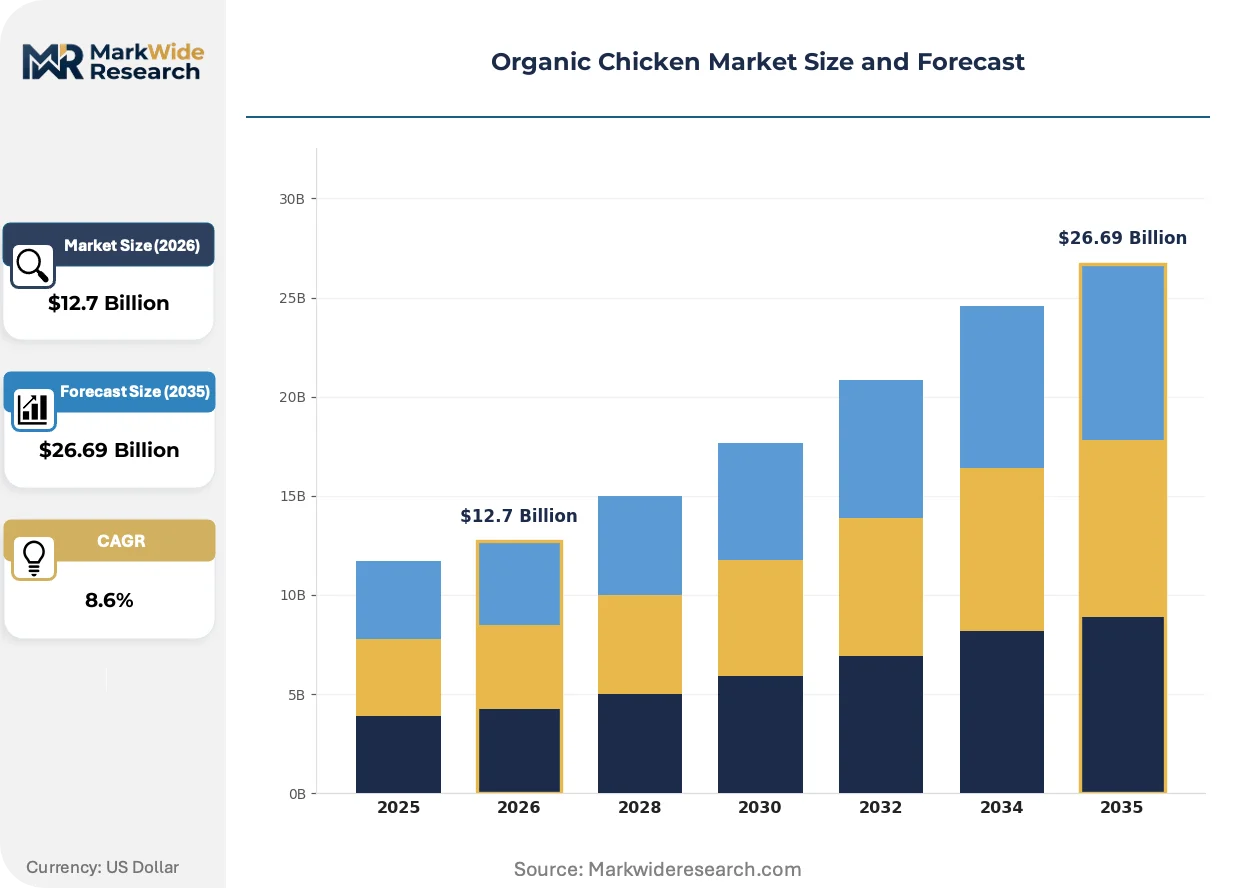
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $26.69 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Chicken, Chicken Breasts, Chicken Thighs, Chicken Wings Distribution Channel: Supermarkets, Online Retailers, Farmers' Markets, Specialty Stores End User: Households, Restaurants, Food Service Companies, Retail Chains Certification: USDA Organic, Non-GMO Project Verified, Animal Welfare Approved, Others |
| Companies Covered | Tyson Foods, Inc., Perdue Farms, Inc., Sanderson Farms, Foster Farms, Bell & Evans, Plainville Farms LLC, Murray's Organic Chicken, Pilgrim's, Tecumseh Poultry LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Chicken Market Emerging Trajectories
Processing technology and packaging formats are compressing traditional wholesale-distributor relationships while regulatory enforcement tightens around living-condition verification. These forces are reshaping who captures value in the supply chain.
Air-chilled processing is consolidating market share against conventional water-chilled methods by reducing moisture uptake and enabling precise portion control. Mass retail buyers and club formats are specifying air-chilled birds for private-label organic lines. This technology is consolidating margin capture with processors who invested early in dedicated air-chilling tunnels.
USDA's National Organic Program is intensifying audits of outdoor access compliance and feed-source documentation, raising the cost of certification maintenance. Accredited certifying agents are conducting unannounced inspections of pasture stocking density and feed mill separation protocols. Small-scale producers in the Northeast are responding by forming cooperative inspection pools to share compliance costs.
Direct-to-consumer subscription models are displacing traditional distributor relationships in coastal urban markets. Specialty retail and meal-kit channels are capturing younger demographics with pre-cut, recipe-ready organic chicken portions. This shift is most visible in California and New York metro areas where delivery logistics density supports cold-chain economics.
Organic Chicken Market Segmentation
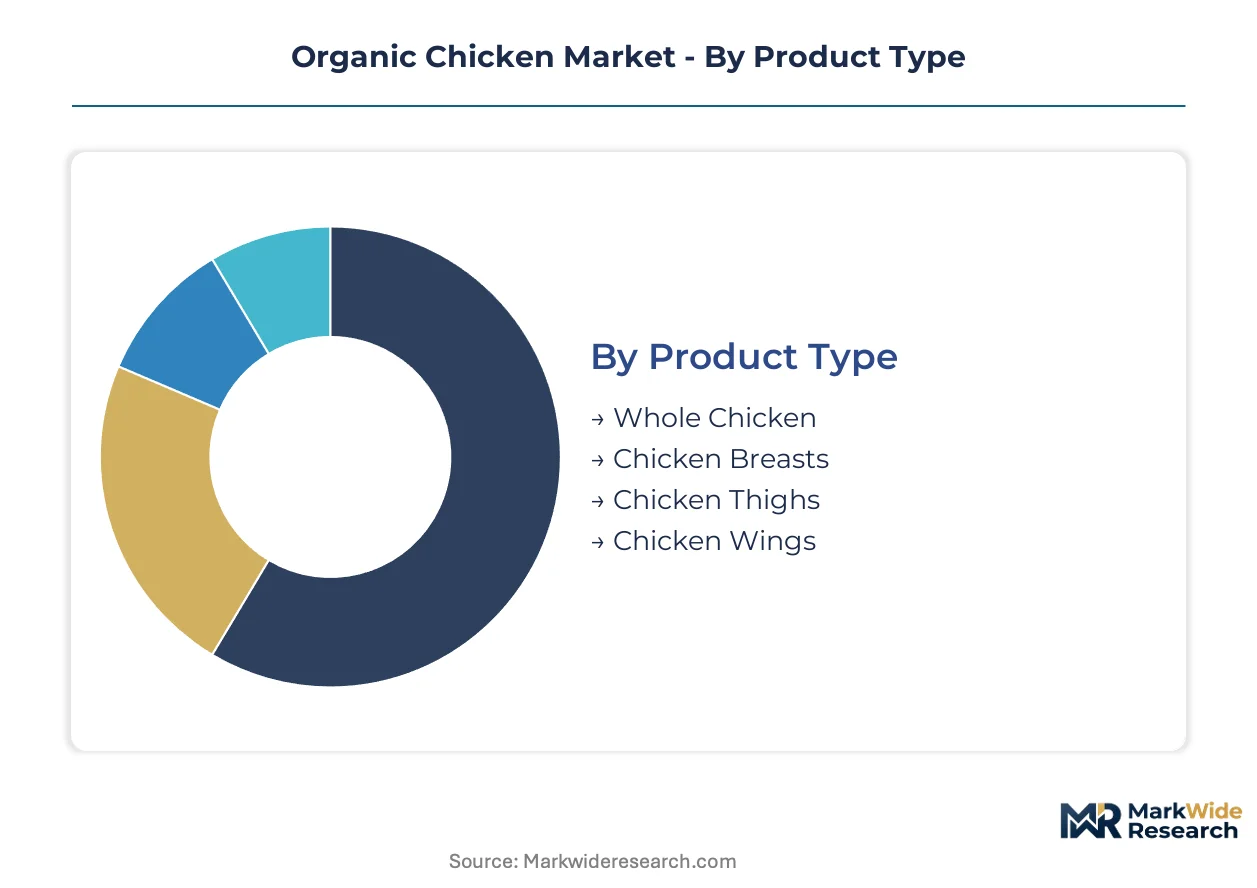
Organic chicken segmentation reveals how certification tiers and distribution formats fragment value capture across supply chains. Product configuration and channel choice determine margin pools more than geographic expansion alone.
Product Type:
Standalone whole birds serve price-conscious bulk buyers while portioned cuts embed into prepared meal systems and food service specifications.
- Whole Chicken:Volume anchor for club formats and discount retail, typically sold at lower per-pound price points with minimal processing overhead. Demand concentrates in US Midwest and Southern households prioritizing cost-per-serving over convenience, constrained by limited shelf-life extension without further processing.
- Chicken Breasts:Lean protein specification drives premium positioning in specialty retail and direct-to-consumer channels. Health-conscious buyers in Germany and Japan demonstrate sustained willingness to pay markup for skinless, boneless cuts with verified clean-label attributes.
- Chicken Thighs:Dark meat segment gaining traction in restaurant applications seeking flavor depth and cost efficiency.
- Chicken Wings:Sports-bar and casual dining channel staple with seasonal demand spikes around major sporting events.
Whole chicken leads volumes today; chicken breasts are gaining share fastest.
Distribution Channel:
Channel selection maps directly to customer acquisition cost and cold-chain investment requirements, with digital platforms displacing traditional wholesale relationships in dense urban markets.
- Supermarkets:Mass retail anchor commanding private-label organic lines and case-ready formats. US chains like Kroger and Albertsons specify air-chilled processing and controlled-atmosphere packaging to reduce shrink and extend retail windows.
- Online Retailers:Subscription and direct-to-consumer models penetrating coastal metros with pre-portioned, recipe-ready offerings. California and New York delivery density supports viable unit economics for cold-chain logistics.
- Farmers' Markets:Local producer channel emphasizing freshness narrative and direct producer-consumer relationships.
- Specialty Stores:Premium retail format stacking multiple certifications and supporting higher price realization for differentiated products.
Supermarkets dominate transaction volume; online retailers are expanding most quickly.
End User:
End-use segmentation separates household discretionary purchases from institutional procurement mandates with contractually locked volumes.
- Households:Individual consumers purchasing for home preparation, with preference shifting toward pre-cut and marinated formats reducing time-to-table.
- Restaurants:Quick-service chains in the United States are codifying organic poultry into supply agreements, pulling contracted volume through grower networks at specified quality grades.
- Food Service Companies:Institutional buyers including schools, hospitals, and corporate cafeterias with sustainability procurement criteria.
- Retail Chains:Private-label program operators specifying processing standards and packaging formats for shelf-ready presentation.
Households anchor current demand; restaurants are climbing the fastest on procurement mandate expansion.
Certification:
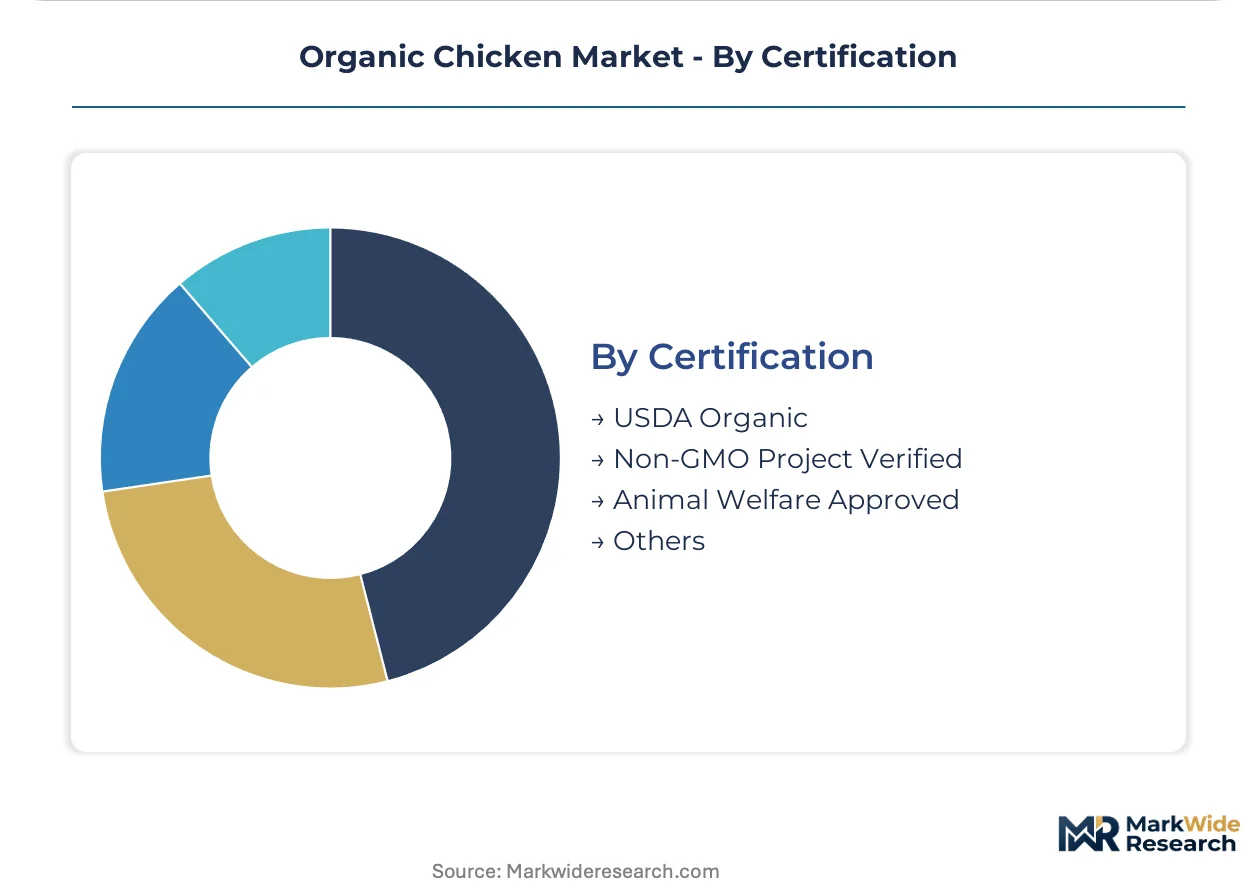
Certification stacking creates tiered price realization with each additional audit layer filtering addressable market size upward.
- USDA Organic:Baseline market-access credential enforced through accredited certifying agents auditing feed sourcing and outdoor access compliance. National Organic Program standards mandate separation from conventional operations at slaughter facilities.
- Non-GMO Project Verified:Feed-chain verification targeting coastal and urban buyers concerned with genetic modification transparency, commanding shelf space premiums in specialty retail.
- Animal Welfare Approved:Pasture-based certification with stringent stocking density requirements, primarily penetrating premium tiers in German and French retail aligned with EU Green Deal animal welfare benchmarks.
- Others:Regional and retailer-specific programs including Certified Humane and Global Animal Partnership ratings.
USDA Organic holds dominant share; Animal Welfare Approved shows steepest expansion trajectory in European export channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Organic poultry production first achieved commercial scale in the United States during the 1990s as the National Organic Program formalized certification standards. Germany and Japan subsequently developed parallel demand centers through distinct regulatory pathways. Today the market distributes across concentrated production clusters in North America, Western Europe, and East Asia.
United States
Quick-service restaurant procurement mandates and club-format retail expansion drive volume growth. USDA National Organic Program enforcement through accredited certifying agents maintains baseline compliance costs. Pennsylvania and Georgia host the densest slaughter facility clusters, with Georgia processors supplying southeastern retail chains and food service distributors.
Germany
Retail buyers demonstrate sustained willingness to pay premium prices for Animal Welfare Approved and EU Organic dual-certified products. The EU Green Deal Farm to Fork strategy tightens feed additive restrictions through REACH-aligned regulations. Bavarian producers concentrate near Munich and Nuremberg metro areas, supplying domestic discount and specialty retail channels.
Japan
Health-conscious seniors in Tokyo and Osaka metropolitan areas anchor demand for verified clean-label protein with extended shelf-life requirements. METI oversight of organic import standards and JAS certification alignment shapes market access for foreign suppliers. Kanto region distribution hubs handle cold-chain logistics for premium retail and direct-to-consumer channels.
France
Coastal urban markets in Paris, Lyon, and Marseille stack multiple certifications including EU Organic and regional welfare labels. ANSM and DGCCRF enforcement of feed traceability and slaughter facility standards raises compliance barriers for imported product. Brittany and Pays de la Loire host integrated breeder-processor operations serving domestic retail and export channels.
Canada
Health Canada and CFIA harmonization with USDA Organic standards facilitates cross-border supply integration. Ontario and Quebec poultry belts concentrate certified organic grower networks supplying Toronto and Montreal retail corridors. Vancouver and Calgary metropolitan areas demonstrate accelerating demand through meal-kit and subscription channel penetration.
Organic Chicken Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification stacking and processing technology dimensions. The vendor base distributes across three tiers: vertically integrated conglomerates controlling feed-to-retail supply chains, mid-scale specialists investing in air-chilled and controlled-atmosphere packaging, and regional cooperatives pooling certification compliance costs. Dominant competitive moves include backward integration into certified organic feed milling and strategic partnerships with quick-service restaurant chains seeking locked supply volumes.
Within the scale-driven tier, Tyson Foods, Inc. and Perdue Farms, Inc. occupy positions reflecting decades of supply chain consolidation. Bell & Evans exemplifies the specialist archetype through air-chilled processing investments. These three entities anchor the competitive structure while smaller cooperatives and regional brands fill geographic and certification niches.
| Leading Market Players |
|---|
| Tyson Foods, Inc. |
| Perdue Farms, Inc. |
| Sanderson Farms |
| Foster Farms |
| Bell & Evans |
| Plainville Farms LLC |
| Murray's Organic Chicken |
| Pilgrim's |
| Tecumseh Poultry LLC |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between USDA Organic baseline and Animal Welfare Approved premium tiers manifests in both pricing power and supply chain configuration, with stacked-audit producers commanding shelf space premiums while single-certification operators absorb feed cost volatility in the United States, Germany, and Japan.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification depth and processing technology. Price differentiation rests on air-chilled versus water-chilled methods and outdoor access verification intensity. Cost compression in the economy tier is intensifying because conventional antibiotic-free chicken siphons price-sensitive buyers. Quick-service restaurant chains demonstrate lowest price sensitivity due to procurement mandate lock-in, while Midwest club-format households exhibit highest elasticity.
Supply Chain Analysis
Certified organic feed grain supply rests on United States, Argentina, and Brazil production clusters vulnerable to drought cycles and export disruptions. Raw material dependencies include non-GMO corn, soybean meal, and organic vitamin premixes. Single-source vulnerability concentrates in Pennsylvania and Georgia slaughter facilities, creating geographic bottlenecks for western growers. Distribution runs through contracted grower networks supplying quick-service chains and mass retail private-label programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The organic chicken market functions as a stable compounder anchored by quick-service restaurant procurement mandates that pull contracted volume through grower networks regardless of feed cost cycles.
For Market Incumbents: Deploy backward integration into certified organic feed milling to capture margin from volatile grain inputs. Lock long-term supply agreements with quick-service chains to defend against conventional antibiotic-free substitution. Expand air-chilled processing capacity in Pennsylvania and Georgia to consolidate geographic advantage. For New Entrants and Emerging Players: Direct-to-consumer subscription channels in California and New York metro areas offer lowest customer acquisition friction. Target meal-kit partnerships with pre-portioned, recipe-ready formats. Penetrate specialty retail in coastal urban markets through Animal Welfare Approved certification stacking. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-certification compliance timelines extend approval cycles and strain small-scale producer economics. The five-to-ten-year viability window favors mid-scale specialists with existing air-chilled infrastructure. Acquisition targets include regional cooperatives pooling inspection costs in the Northeast. Watch certifier enforcement intensity on outdoor access rules as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feed Milling | Captures margin from volatile organic grain costs in US Midwest supply basins. |
| Air-Chilled Processing Investment | Extends shelf-life for direct-to-consumer channels in California and New York metros. |
| Quick-Service Supply Agreement | Locks volume through grower networks as procurement mandates harden. |
| Multi-Certification Stacking | Commands premium shelf space in German and French retail aligned with EU Green Deal. |
| Controlled-Atmosphere Packaging Deployment | Reduces retail shrink for Kroger and Albertsons private-label organic lines. |
Methodological Framework
Direct dialogue with poultry veterinarians, feed mill operators, quick-service procurement directors, and USDA-accredited certifying agents grounded qualitative insights. Secondary validation drew from USDA National Organic Program enforcement records, EPA water discharge permits, EU Green Deal Farm to Fork strategy documents, and customs trade data. Bottom-up grower network analysis and top-down retail channel sizing were triangulated against accredited certifier audit volumes.
Segmented outputs across product type, distribution channel, end user, and certification tier were generated across the analysis window. CAGRs were derived from feed cost trajectory modeling and procurement mandate diffusion curves. Forecast inputs incorporated organic corn and soybean meal price volatility, slaughter facility capacity expansion plans, and quick-service chain sourcing commitment timelines.
The model assumes a particular technology adoption path; alternative pathways for air-chilled processing penetration would alter the outlook. Forecasts reflect assumptions on certifier enforcement consistency and feed grain supply stability. Material deviation in USDA outdoor access rule interpretation or Argentine export disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Reduced Fat Meat Market
Meat Products
Lab-Grown Meat Market
Meat Products
Canned Pork Market
Meat Products
Organic Meat Market
Meat Products
France Meat Products Market
Meat Products
Nitrate-Free Bacon Market
Meat Products
Pork Flavors Market
Meat Products
Saudi Arabia Red Meat Market
Meat Products
Beef Liver Market
Meat Products
Pepperoni Foods Market
Meat Products
Europe Processed Meat Market
Meat Products
Meat Flavors Market
Meat Products
North America Low Fat Sausage Market
Meat Products
Global Lab-Based Meat Market
Meat Products
Rendered Poultry Products Market
Meat Products
Raw Chicken Feet Market