
 Vegan Meatball Market | 2026-2036
Vegan Meatball Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Meatball Market Insights
Market Context
European production capacity for plant-based proteins is reshaping supply dynamics for vegan meatball manufacturers worldwide. Beyond Meat leverages vertical integration from pea protein sourcing through finished product distribution to sustain margin control across volatile commodity cycles. Nestlé anchors European retail presence through its Garden Gourmet brand, while Impossible Foods competes aggressively in North American foodservice channels with its heme-based formulation technology.
Technical Definition and Segment Structure
Vegan meatballs are composed of textured plant proteins, binding agents, and lipid systems engineered to replicate the chew, moisture retention, and Maillard browning of conventional meatballs, serving commercial foodservice and retail prepared-meal applications. Frozen products dominate current volume due to extended shelf stability and established cold-chain logistics, though fresh formulations are capturing premium positioning in direct-to-consumer channels. Pea protein isolates lead ingredient sourcing for allergen-friendly positioning, while wheat gluten occupies cost-sensitive segments where elastic texture takes priority over clean-label claims.
Regulatory Environment
The FDA governs labeling standards and GRAS determinations for novel plant proteins in the United States, while the EU Green Deal's Farm to Fork strategy and EFSA novel food assessments shape European market entry requirements for fermented and cultivated protein ingredients. REACH compliance for processing aids and the EU's pending front-of-pack nutritional labeling scheme will force reformulation decisions across multinational portfolios. Stakeholders must monitor evolving allergen threshold regulations as manufacturers diversify beyond soy into emerging protein sources.
Market Dynamics
European production capacity for plant-based proteins is reshaping supply dynamics for vegan meatball manufacturers worldwide, with cold-chain infrastructure investments and novel protein fermentation scaling as the dominant structural forces compressing lead times and reformulation cycles.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Mandates for 25% organic farming land and protein diversification targets are accelerating public procurement of plant-based proteins across German, Dutch, and Danish institutional foodservice channels.
- Quick-service restaurant expansion:Major chains across the United States and Canada are dedicating permanent menu board space to plant-based meatballs, normalizing trial among omnivore consumers.
- Precision fermentation:Commercial-scale mycoprotein and heme ingredient production is reducing dependency on commodity crop price volatility for texture and flavor replication.
Market Restraints
- Pea protein supply concentration:North American and Canadian pea processing infrastructure limits isolate availability during drought cycles, forcing manufacturers into wheat gluten fallback formulations.
- EFSA novel food assessment timelines:18-to-24-month approval windows for fermented protein ingredients delay European product launches and tie up R&D capital.
- Clean-label cost premiums:Binding agents like methylcellulose and natural lipid systems carry 3-4x the ingredient cost of conventional egg and breadcrumb systems.
Strategic Opportunities
- Indian foodservice penetration:Untapped quick-service and railway catering channels present volume potential for halal-certified, allergen-free formulations adapted to local spice profiles.
- Direct-to-consumer fresh delivery:Subscription meal kits and refrigerated e-commerce platforms are bypassing frozen retail slotting fees and capturing premium household trial.
- USDA BioPreferred procurement mandates:Federal and state institutional purchasing preferences for biobased products are opening school lunch and military feeding contracts.
Industry Challenges
- Food technologist scarcity:Formulation expertise spanning protein chemistry, lipid oxidation control, and extrusion processing remains concentrated among a handful of specialized consultancies and retired meat industry veterans.
- Dual certification complexity:Simultaneous pursuit of organic, non-GMO, and kosher certifications creates documentation bottlenecks and supplier audit backlogs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Meatball Market |
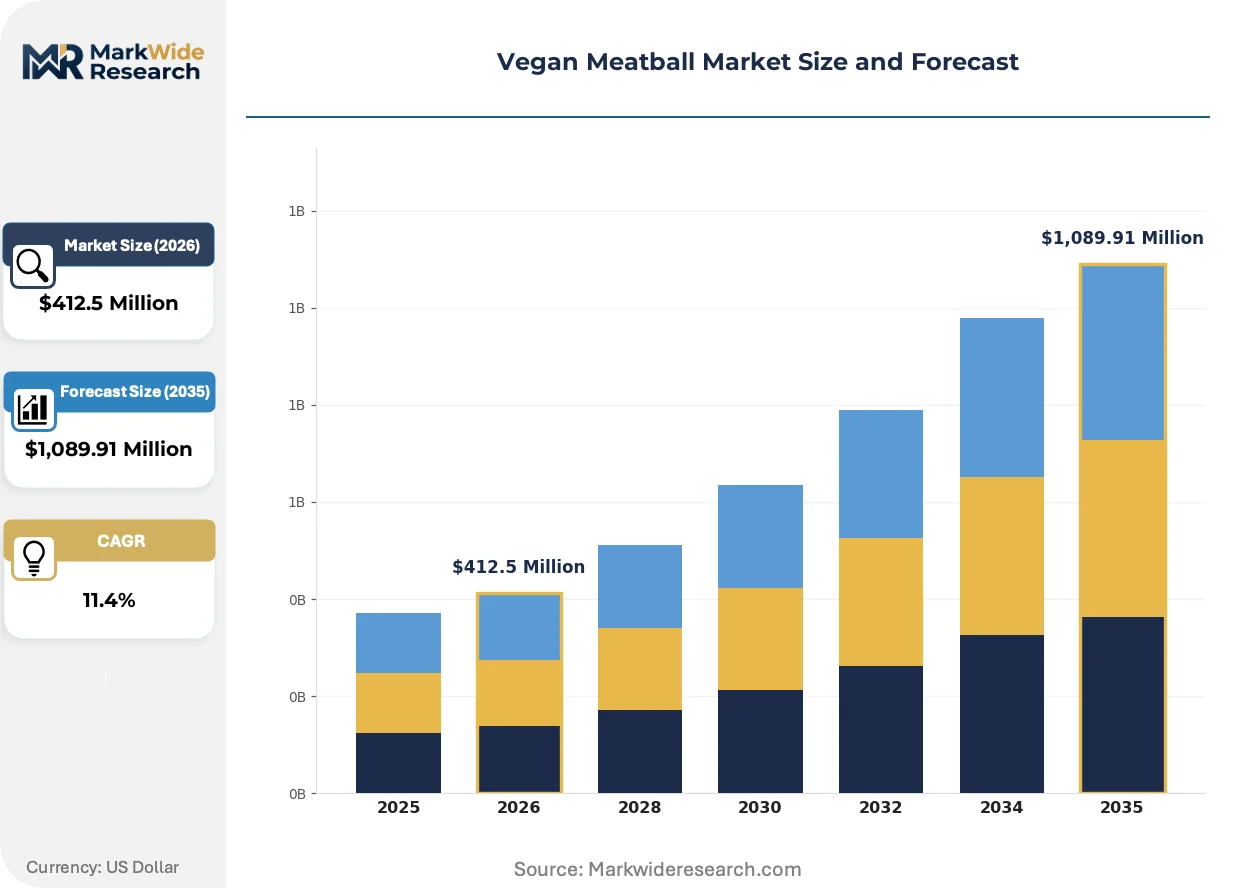
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,089.91 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen, Fresh, Dry, Ready-to-Cook Ingredient Source: Pea Protein, Soy Protein, Wheat Gluten, Lentils Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Convenience Stores Target Consumer: Vegans, Vegetarians, Flexitarians, Health-Conscious Consumers |
| Companies Covered | Beyond Meat, Impossible Foods, Nestlé, Kellogg Company, IKEA Food Services, Quorn Foods, Lightlife Foods, The Vegetarian Butcher, Conagra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Meatball Market Trends and Innovations
Ingredient technology convergence and regulatory labeling clarity are compressing product development cycles while channel fragmentation is forcing manufacturers to maintain parallel formulation portfolios for foodservice and retail specifications.
Extrusion technology is hybridizing with shear-cell processing to create fibrous textures without the energy intensity of traditional high-moisture extrusion. Mid-sized manufacturers in Germany and the Netherlands are piloting these hybrid systems to reduce capital barriers to entry. The technology is hybridizing equipment sourcing decisions, with used meat processing machinery retrofitting emerging as a cost-competitive alternative to purpose-built plant-protein lines.
The FDA's updated guidance on labeling plant-based meat alternatives is clarifying compliance pathways for manufacturers using standardized term definitions and nutrient disclosure frameworks. This reduces litigation exposure for companies using terms like "meatball" on packaging. Foodservice distributors in the United States are the most affected segment, accelerating menu descriptor standardization to preempt state-level labeling preemption battles.
Foodservice procurement teams are consolidating supplier relationships around full-line protein vendors capable of delivering both animal and plant-based SKUs through unified distribution contracts. This displaces specialty vegan distributors and compresses margin expectations for standalone plant-based brands. The shift is most visible in United States contract management companies and German hospital catering consortia.
Vegan Meatball Market Segmentation
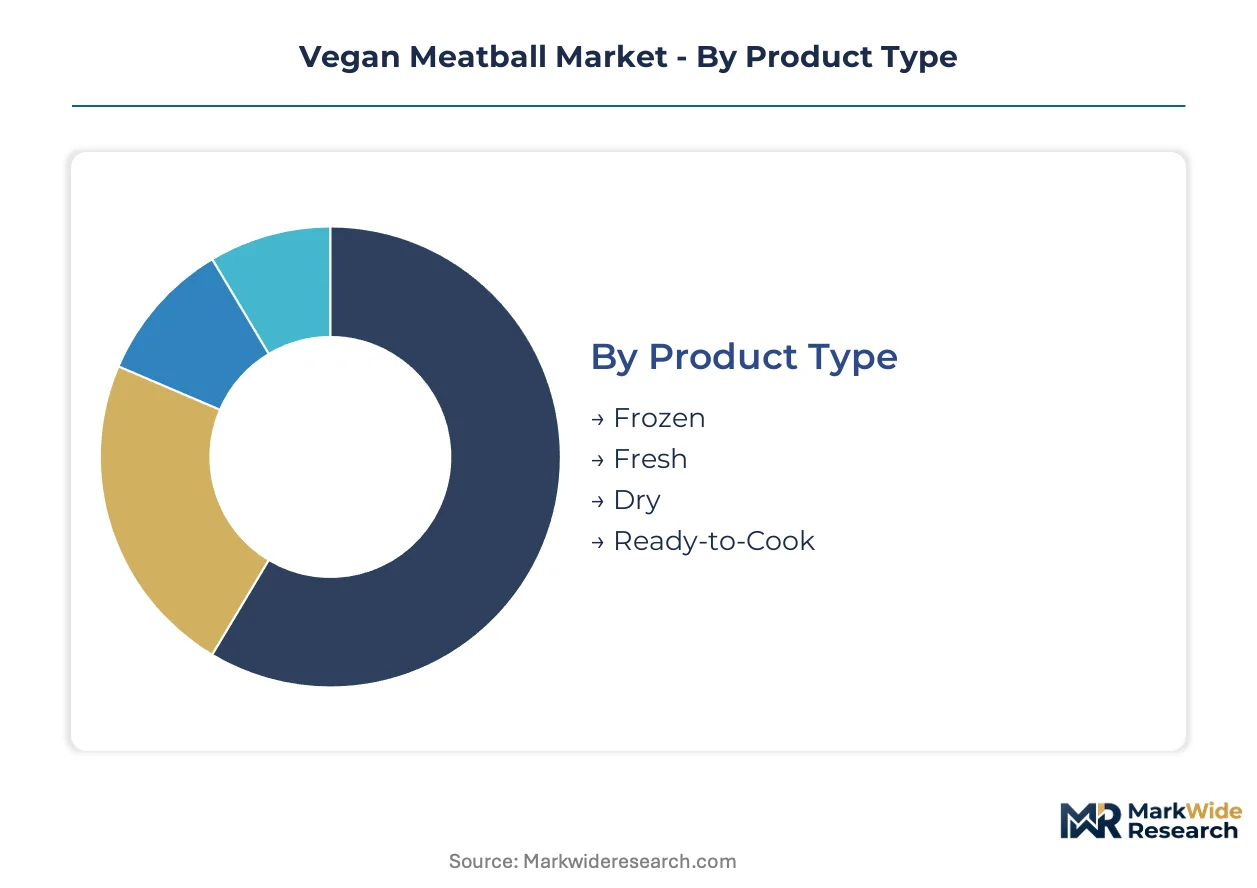
Vegan meatball segmentation reveals distinct formulation, sourcing, and channel strategies that manufacturers must balance against cold-chain infrastructure and certification costs. Each dimension carries implications for margin structure and geographic expansion feasibility.
Product Type:
The use-case spectrum spans institutional foodservice batch preparation through premium household convenience, with shelf stability and preparation time as the decisive variables.
- Frozen:Extended shelf stability and established cold-chain logistics dominate current volume. Quick-service restaurant chains across the United States and Canada rely on frozen formats for inventory predictability and food safety compliance.
- Fresh:Refrigerated formulations with shorter shelf life capture premium positioning in direct-to-consumer subscription channels. German retail chains have expanded dedicated chilled plant-protein sections to accommodate this segment's growth.
- Dry:Dehydrated concentrates requiring hydration before cooking serve camping, military, and emergency preparedness markets with minimal cold-chain dependency.
- Ready-to-Cook:Pre-sauced or seasoned formats reduce preparation friction for time-constrained households, though they carry higher packaging and spoilage costs.
The dominant share belongs to Frozen, while Fresh is closing the gap fastest.
Ingredient Source:
Cost tier differentiation separates allergen-positioned premium formulations from commodity-scale elastic texture systems.
- Pea Protein:Isolate and concentrate forms enable allergen-friendly clean-label positioning with neutral flavor profiles. Dutch and German manufacturers prioritize pea sourcing for EU Green Deal-aligned procurement contracts.
- Soy Protein:Mature supply infrastructure and lowest unit cost sustain volume leadership in Asian foodservice and cost-sensitive European retail.
- Wheat Gluten:Seitan-derived elastic textures occupy economy segments where chew replication outweighs clean-label claims, particularly in German discount retail.
- Lentils:Whole-food positioning and fiber content appeal to health-conscious flexitarians, though batch consistency challenges limit scale.
Pea Protein holds the dominant position, while Lentils are expanding most quickly on whole-food positioning.
Distribution Channel:
Volume concentration tracks cold-chain maturity and slotting fee structures across retail formats.
- Supermarkets:Mainstream retail placement normalizes trial among omnivore consumers through dedicated plant-based protein aisles. German chains have expanded frozen shelf space significantly.
- Health Food Stores:Specialty retailers command premium pricing for certified organic and non-GMO formulations, with knowledgeable staff driving conversion among committed vegan households.
- Online Retailers:Direct-to-consumer platforms bypass frozen slotting fees and enable subscription models for fresh formulations, though last-mile cold-chain costs constrain margin.
- Convenience Stores:Limited refrigeration and grab-and-go positioning favor shelf-stable dry formats, with penetration concentrated in Japanese urban markets and US college corridors.
Supermarkets maintain the dominant share, while Online Retailers are gaining share fastest on subscription model adoption.
Target Consumer:
Application intensity varies from ethical commitment through health optimization to occasional substitution.
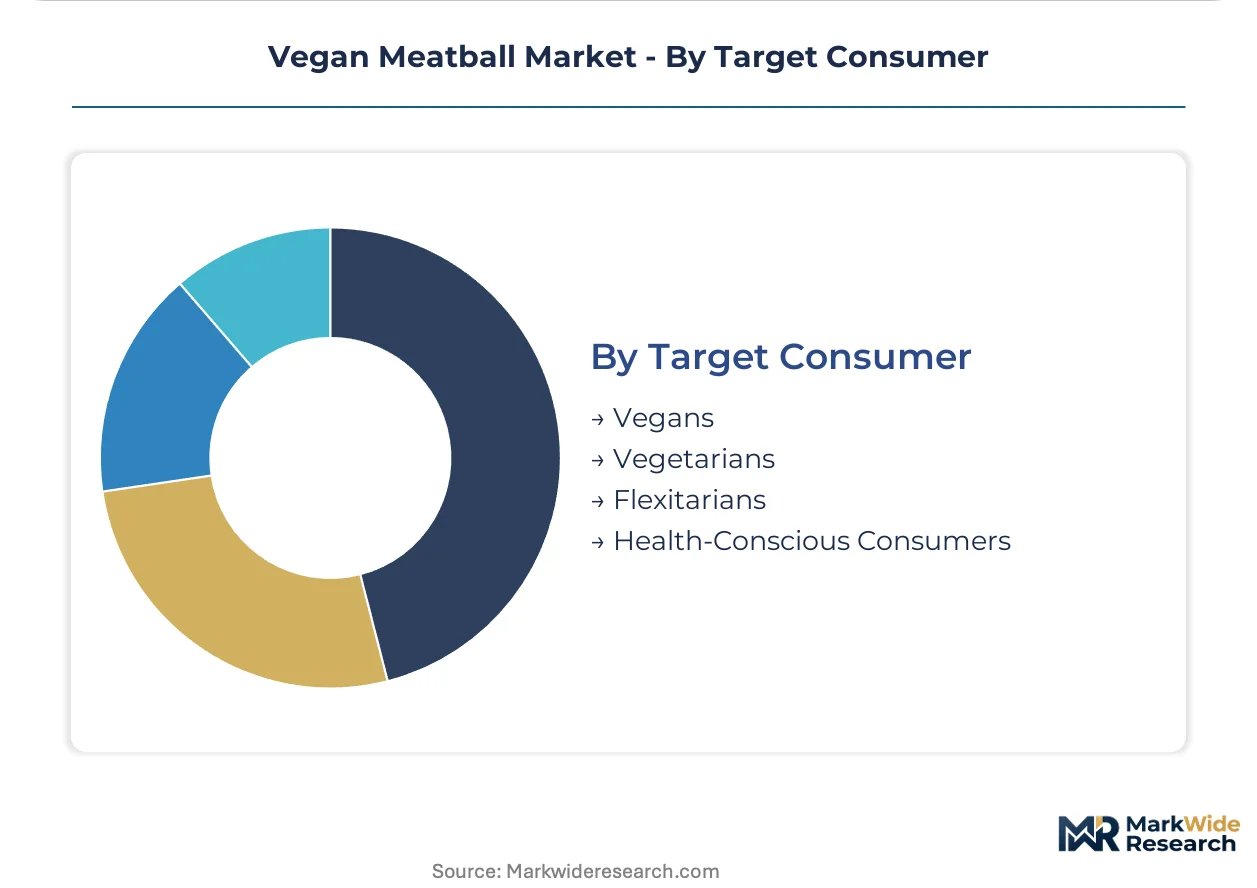
- Vegans:Strict exclusion of animal products drives demand for certified vegan production facilities and cross-contamination controls, with price sensitivity offset by ethical premium tolerance.
- Vegetarians:Longstanding plant-based diets sustain stable demand for familiar meat-replacement formats, particularly in Indian foodservice and European institutional catering.
- Flexitarians:Occasional meat reduction creates the largest addressable population, with taste parity and convenience as primary purchase drivers over ideological alignment.
- Health-Conscious Consumers:Saturated fat reduction and fiber content priorities favor lentil and whole-food formulations, with label scrutiny extending to sodium and additive content.
Flexitarians represent the dominant share, while Health-Conscious Consumers are climbing the fastest on cardiometabolic wellness positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA labeling guidance for plant-based alternatives anchors United States market entry clarity, while EFSA novel food assessments and EU Green Deal procurement mandates reshape European competitive positioning. Cold-chain infrastructure investments and protein fermentation scaling compress lead times across manufacturing clusters.
United States
Quick-service restaurant chains dedicate permanent menu board space to plant-based meatballs, normalizing trial among omnivore consumers. FDA updated guidance on standardized term definitions reduces litigation exposure for manufacturers using traditional meat nomenclature. Chicago and Los Angeles metropolitan areas concentrate foodservice distributor consolidation around full-line protein vendors capable of unified animal and plant-based SKU delivery.
Germany
Retail chains have expanded dedicated chilled plant-protein sections and frozen shelf space significantly as consumer preference shifts accelerate. EU Green Deal Farm to Fork strategy mandates for protein diversification targets drive public procurement across institutional foodservice channels. Berlin and Hamburg anchor manufacturing clusters where mid-sized producers pilot hybrid extrusion-shear-cell processing systems to reduce capital barriers.
Netherlands
Dutch manufacturers prioritize pea protein sourcing for EU Green Deal-aligned procurement contracts and allergen-friendly clean-label positioning. EFSA novel food assessment timelines for fermented protein ingredients delay product launches and tie up R&D capital. Wageningen University corridor concentrates precision fermentation expertise and mycoprotein commercial-scale production facilities.
Canada
Pea protein processing infrastructure limits isolate availability during drought cycles, forcing manufacturers into wheat gluten fallback formulations. Health Canada and PMRA regulate novel plant protein safety assessments and labeling compliance for cross-border trade. Saskatchewan and Manitoba prairie provinces concentrate pea cultivation and primary processing capacity serving North American ingredient demand.
India
Untapped quick-service and railway catering channels present volume potential for halal-certified, allergen-free formulations adapted to local spice profiles. FSSAI governs plant-based protein safety standards and front-of-pack labeling requirements for domestic market entry. Maharashtra and Karnataka industrial corridors concentrate contract manufacturing capacity for export-oriented frozen and dry format production.
Vegan Meatball Market Competitive Landscape
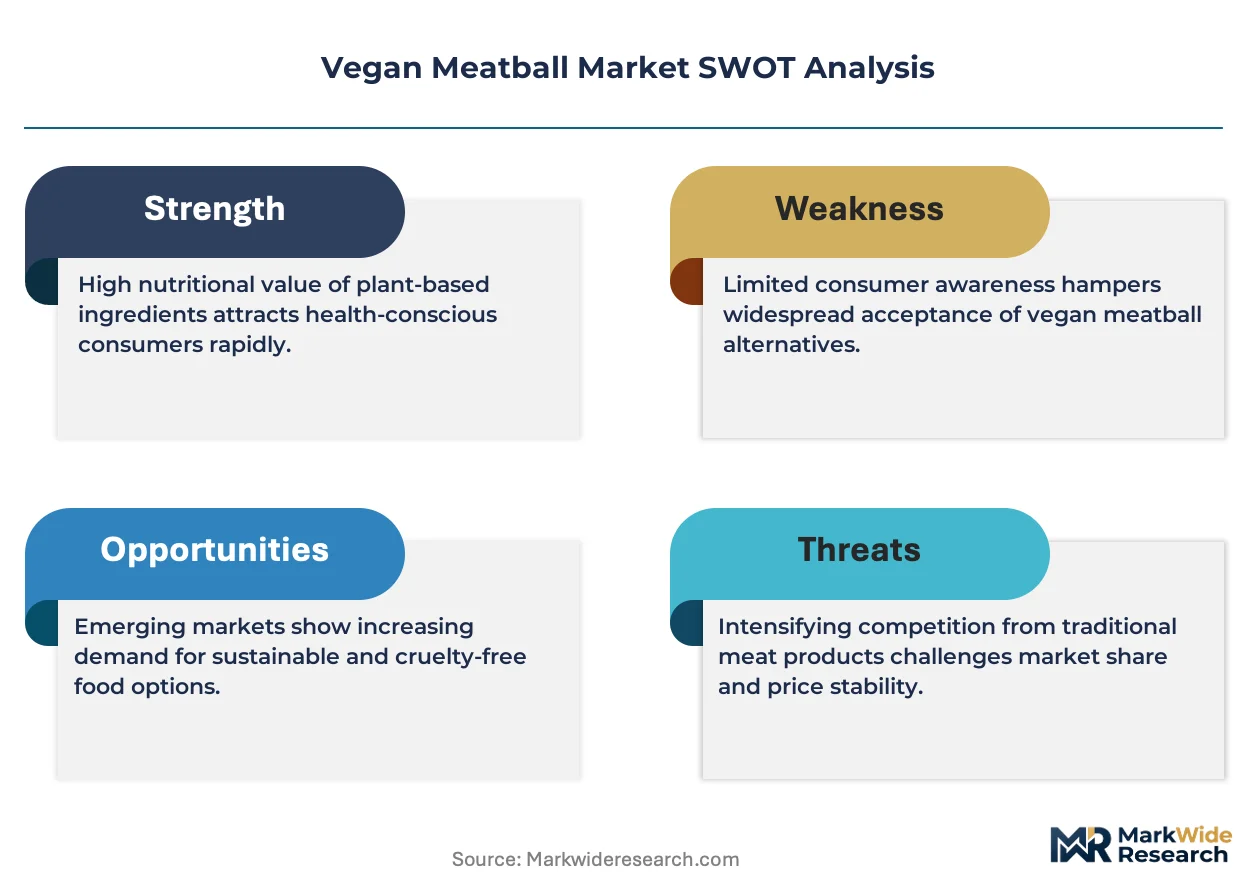
Capability concentration sits with specialized plant-protein formulators possessing extrusion chemistry and lipid system expertise; scale advantage sits with diversified food conglomerates leveraging existing cold-chain distribution and retail slotting relationships. The vendor base separates into three strategic archetypes: venture-backed technology disruptors with novel protein platforms, legacy meat processors retrofitting lines for hybrid portfolios, and private-label manufacturers serving retailer-owned brands. Dominant competitive moves include backward integration into pea protein sourcing and strategic partnerships with foodservice distributors seeking unified protein procurement contracts.
Within the technology-disruptor tier, Beyond Meat and Impossible Foods exemplify divergent platform strategies—Beyond Meat leverages captive supply of pea protein isolates while Impossible Foods anchors heme-based formulation differentiation. Nestlé S.A. occupies a position representing legacy conglomerate scale advantage through its Garden Gourmet brand presence in European retail channels. These three entities collectively illustrate the competitive tension between novel ingredient IP and established distribution infrastructure that defines current market structure.
| Leading Market Players |
|---|
| Beyond Meat |
| Impossible Foods |
| Nestlé |
| Kellogg Company |
| IKEA Food Services |
| Quorn Foods |
| Lightlife Foods |
| The Vegetarian Butcher |
| Conagra |
| Others |
Pricing and Supply Chain Analysis
Rotterdam-Antwerp freight corridors transmit cost volatility from pea protein processing hubs to downstream price differentiation across frozen and fresh format tiers. Supply concentration in Dutch and German extrusion facilities amplifies pricing power for allergen-friendly isolates while compressing margins on wheat gluten alternatives.
Pricing Analysis
Geographic price spreads between North American foodservice contracts and European retail shelf placements reflect cold-chain cost differentials and certification premiums. Three-tier pricing structure across premium, standard, and economy levels separates organic-certified fresh formats from conventional frozen bulk and discount private-label offerings. Price differentiation centers on clean-label ingredient sourcing and dual organic-kosher certification status. Pricing pressure stems from slotting fee escalation in German supermarket chains, with contract foodservice buyers exhibiting lowest price sensitivity due to procurement consolidation around full-line vendors.
Supply Chain Analysis
EU REACH restrictions on methylcellulose processing aids and novel protein fermentation inputs constrain ingredient flows from non-compliant third-country suppliers. Manufacturing gravity draws from Canadian prairie pea cultivation, Dutch isolate processing, and German extrusion finishing. Raw material dependencies rest on pea protein isolates, wheat gluten, and mycoprotein biomass. Single-source vulnerability concentrates in Saskatchewan pea crushing capacity during drought cycles. Distribution runs through unified foodservice procurement contracts displacing specialty vegan distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated foodservice management companies and German hospital catering consortia, fragmenting supplier negotiation leverage across standalone plant-based brands.
For Market Incumbents: Harden formulation IP through captive mycoprotein fermentation partnerships and in-house production of lipid binding systems. Deepen channel control by anchoring unified protein procurement contracts with contract management companies before legacy meat processors retrofit hybrid lines. Certification investment in EU organic and non-GMO tiers defends margin position against private-label encroachment. For New Entrants and Emerging Players: Establish a beachhead in Indian railway catering and quick-service channels through halal-certified, allergen-free formulations adapted to regional spice profiles. Target direct-to-consumer fresh subscription models bypassing frozen retail slotting barriers. Go-to-market execution hinges on precision fermentation partnerships for texture differentiation without capital-intensive extrusion infrastructure. For Investors and Strategic Acquirers: FDA updated guidance on plant-based meat alternative labeling reshapes the acquisition landscape by reducing litigation exposure for standardized term usage. Long-term viability favors mid-sized manufacturers with hybrid extrusion-shear-cell pilot capacity and established EU Green Deal procurement relationships. Acquisition targets include specialized formulators with lipid oxidation control expertise and existing German retail shelf placements. Watch EFSA novel food assessment timeline compression as inflection signal for fermented protein platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pea Protein Sourcing | Captive supply from Saskatchewan and Manitoba isolates reduces commodity price volatility exposure. |
| Hybrid Extrusion-Shear-Cell Technology Adoption | German and Dutch pilot systems lower capital barriers for fibrous texture replication. |
| Direct-to-Consumer Fresh Channel Launch | Subscription models bypass frozen retail slotting fees and capture premium household trial. |
| Dual Organic-Kosher Certification Investment | Documentation bottlenecks create defensive moats against private-label competition. |
| Precision Fermentation Partnership | Wageningen corridor mycoprotein access reduces dependency on commodity crop inputs. |
Research Methodology
Cross-validation between trade association procurement data and foodservice distributor contract disclosures anchors the qualitative findings on buyer consolidation patterns. Primary interviews with plant-protein formulators, foodservice procurement directors, retail category buyers, and cold-chain logistics operators combined with secondary validation from FDA guidance documents, EFSA novel food registers, EU Green Deal procurement databases, and customs trade flows. Bottom-up SKU-level volume builds and top-down sector expenditure estimates triangulate market sizing.
Calibration against historical volume trajectories in adjacent plant-based protein categories informs elasticity assumptions across the projection horizon. Segmentation dimensions modeled include product format, ingredient source, distribution channel, and target consumer archetype. CAGRs derive from regression analysis of penetration rates against protein price differentials and regulatory procurement mandates. Forecast inputs incorporate EFSA approval timeline distributions and quick-service restaurant menu placement velocity.
Sensitivities concentrate around EFSA novel food assessment delays, drought-induced pea protein supply disruptions, and foodservice distributor consolidation timing. Forecasts reflect documented assumptions on cold-chain infrastructure expansion and clean-label cost premium sustainability. Material shifts in EU front-of-pack nutritional labeling implementation or FDA enforcement posture would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Pepperoni Foods Market
Meat Products
Global Lab-Based Meat Market
Meat Products
Hot Dog and Sausages Market
Meat Products
United States Frozen Meat Market
Meat Products
Edible Offal Market
Meat Products
France Meat Products Market
Meat Products
Europe Canned Meat Market
Meat Products
Meat Mincers Market
Meat Products
Beef Bone Broth Market
Meat Products
North America Processed Meat Market
Meat Products
Nitrate-Free Bacon Market
Meat Products
Emulsified Meat Market
Meat Products
Global Canned Meat Market
Meat Products
Bacon Flavors Market
Meat Products
North America Processed Poultry Meat Market
Meat Products
Sausage Premixes Market