
 Brisket Market | 2026-2036
Brisket Market Size, Share, and Industry Trends Forecast 2026-2036
Brisket Market Analysis
Market Context
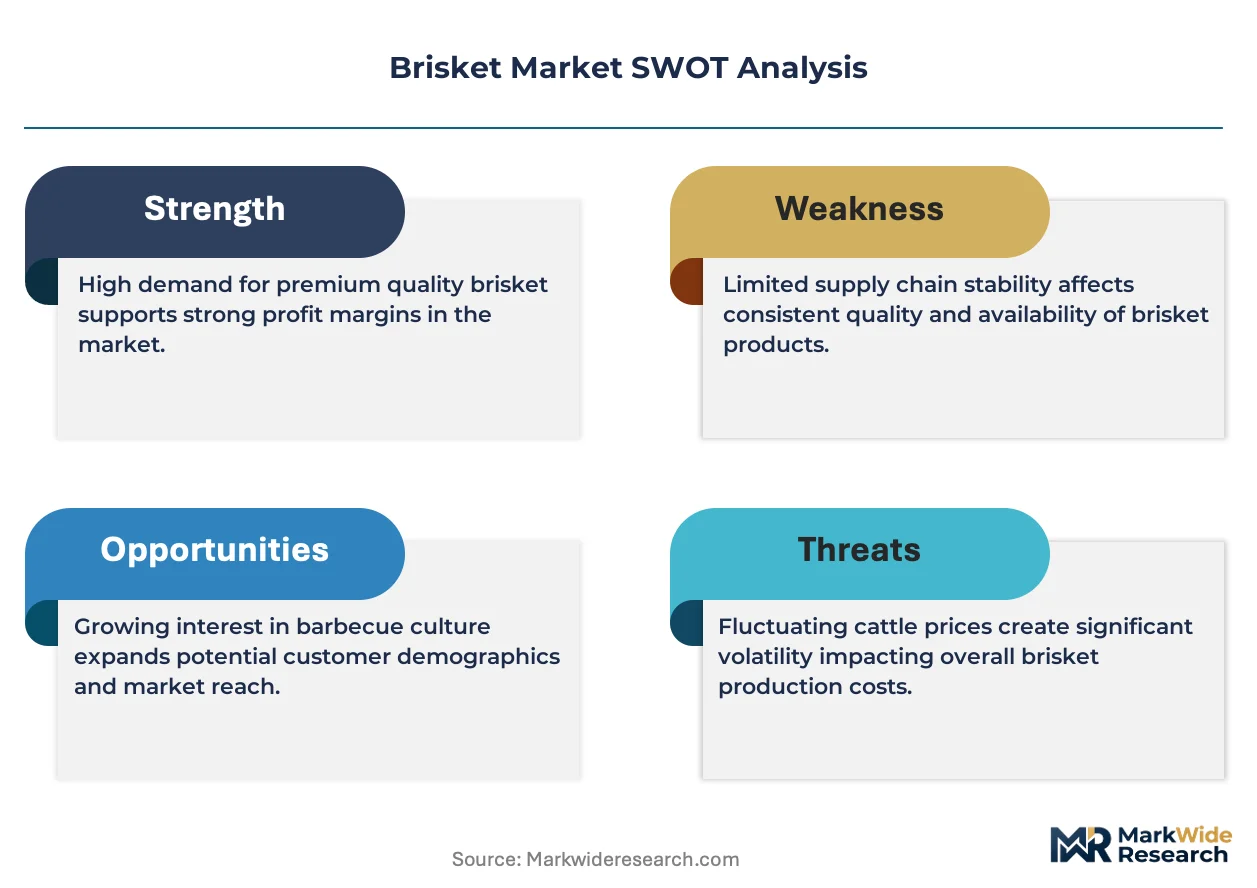
Texas cattle feedlot capacity is decoupling from traditional seasonal patterns as drought resilience investments reshape supply timing. Tyson Foods leverages vertical integration from feed yards to case-ready processing, sustaining margin capture across volatile cattle cycles. JBS USA Holdings anchors its competitive stance through geographic dominance in southern Plains processing corridors. Hormel Foods Corporation differentiates via specialized smoked and seasoned product lines targeting foodservice distributors.
Technical Definition and Structural Segments
Brisket comprises the pectoral muscle of cattle, a fibrous cut requiring low-temperature collagen breakdown through smoking or braising to achieve tenderness, and serves as the foundational input for barbecue cuisine, corned beef production, and institutional foodservice programs. Fresh brisket occupies the largest volume share as raw material for pit-style barbecue restaurants and institutional kitchens, while smoked brisket commands premium positioning in retail and foodservice channels where labor substitution drives value. Online retail represents the fastest-growing distribution channel as direct-to-consumer platforms and meat subscription services bypass traditional wholesale tiers.
Regulatory Frame and Outlook
USDA grading standards and FSIS inspection protocols shape product classification, labeling requirements, and interstate commerce access for beef processors across the United States. The EPA's Clean Water Act enforcement and OSHA workplace safety mandates add compliance layers to slaughter and fabrication operations. Stakeholders must monitor evolving USDA organic certification pathways and state-level animal welfare regulations that could restructure sourcing requirements and processing cost structures.
Market Dynamics
USDA grading standard tightening for Prime and Choice classifications is compressing certified supply availability while restaurant chains accelerate smoked brisket menu placements, creating a structural squeeze between upstream cattle procurement and downstream foodservice demand.
Growth Catalysts
- FSIS inspection protocol harmonization:Streamlined interstate commerce access enables multi-state restaurant chains to consolidate supplier bases under unified safety standards.
- Direct-to-consumer subscription platforms:Online retail bypasses traditional wholesale tiers, capturing margin previously allocated to distributor networks.
- Texas and Kansas City restaurant expansion:Regional barbecue chain density concentrates demand pull for consistent Prime-grade supply contracts.
Market Restraints
- Cattle feedlot input volatility:Drought resilience investments decouple seasonal supply timing, creating unpredictable raw material availability windows.
- Southern Plains processing concentration:Geographic dominance of major packers in limited corridors amplifies disruption risk from localized weather or labor events.
- Collagen breakdown labor substitution limits:Smoked brisket premium positioning depends on skilled pitmaster labor that resists full automation.
Strategic Opportunities
- Australia export supply zone development:Emerging critical supply source for international foodservice buyers seeking non-US origin diversification.
- Brazil feedlot-to-processing integration:Geographic expansion of integrated operations creates new export-grade supply for Asian markets.
- State-level animal welfare pathway evolution:California and Massachusetts welfare mandates are creating certified supply premiums that reward early compliance investment.
Industry Challenges
- Pitmaster skill pipeline constriction:Traditional barbecue craftsmanship requires multi-year training that institutional foodservice programs struggle to replicate at scale.
- Case-ready processing capex intensity:Vertical control from feed yards to fabrication demands sustained capital deployment across volatile cattle price cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brisket Market |
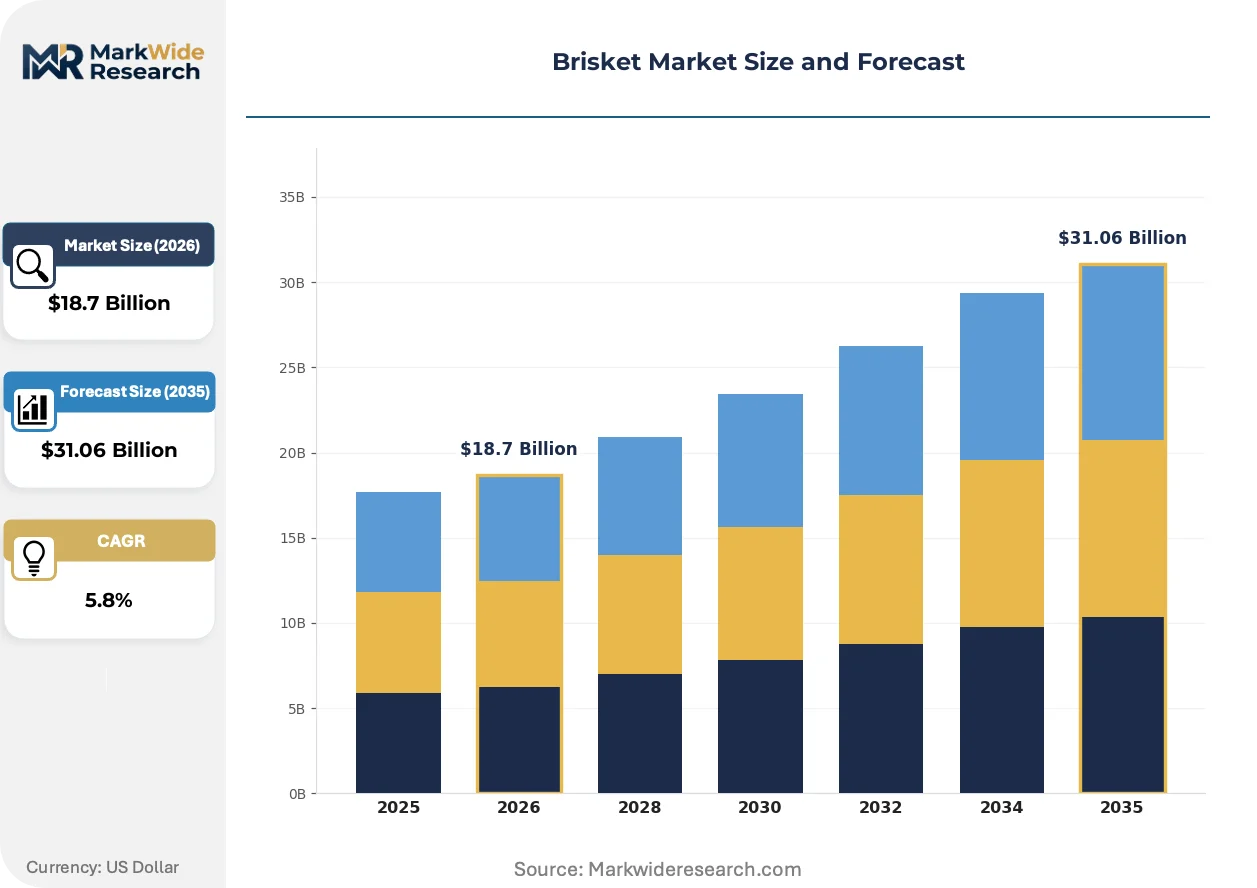
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Brisket, Smoked Brisket, Packaged Brisket, Seasoned Brisket Distribution Channel: Supermarkets, Online Retail, Butcher Shops, Foodservice End User: Restaurants, Households, Caterers, Food Trucks Preparation Method: Grilling, Smoking, Braising, Roasting |
| Companies Covered | Tyson Foods, Conagra Brands, Hormel Foods Corporation, Cargill, JBS USA Holdings, National Beef Packing Company, Smithfield Foods, Freirich Foods, Pilgrim’s Pride Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brisket Market Emerging Trajectories
Smoking technology and supply chain digitization are compressing traditional barbecue production timelines while regulatory compliance requirements reshape competitive positioning across processor tiers.
Pellet smoker systems with precision temperature control and remote monitoring capabilities are automating the collagen breakdown process that previously required constant human oversight. Mid-scale barbecue restaurants and ghost kitchen operators are adopting these systems fastest, reducing labor hours per brisket by eliminating overnight fire-tending shifts. This automation is compressing the skill barrier that historically protected independent pitmasters from chain competition.
The EPA's Clean Water Act enforcement intensification is mandating wastewater treatment upgrades at slaughter and fabrication facilities. Compliance costs are falling disproportionately on smaller regional processors without existing treatment infrastructure. Southern Plains operations with pre-installed anaerobic digesters are absorbing volume shifts from non-compliant competitors.
Foodservice distributors are unbundling after-sales support from commodity brisket contracts, shifting toward specification-grade procurement with certified origin documentation. Large barbecue chains are bypassing broadline distributors for direct processor relationships with lot-traceability guarantees. This pattern is most visible in Texas and Kansas City where chain density supports dedicated supply contracts.
Brisket Market Segmentation
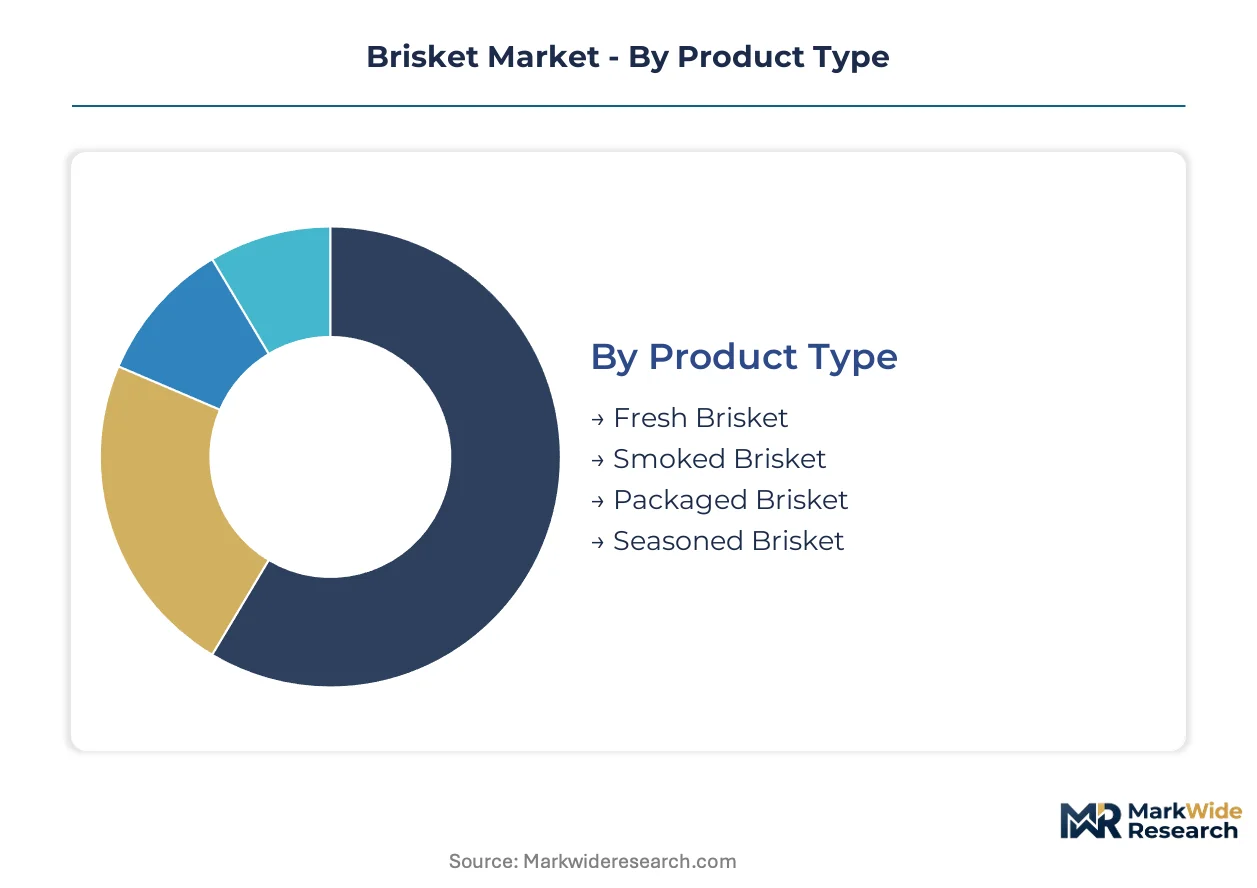
Brisket segmentation reveals how collagen breakdown requirements, labor substitution economics, and distribution infrastructure reshape procurement patterns across foodservice tiers. Understanding these divides exposes where margin capture concentrates and which buyer types drive specification-grade demand.
Product Type:
Buyers differentiate primarily by labor capacity—those with pitmaster expertise source raw material, while labor-constrained operators pay premiums for pre-processed inputs.
- Fresh Brisket:Untrimmed pectoral muscle requiring 12-16 hour collagen breakdown through controlled heat application. Demand concentrates in Texas and Kansas City pit-style restaurants where USDA Prime and Choice certification commands supplier loyalty programs. Drought-resilient feedlot investments are compressing seasonal availability windows, forcing long-term contract structures.
- Smoked Brisket:Post-collar breakdown product with rendered fat cap and established bark formation, ready for service after reheating. Regional barbecue chains in the southern Plains are consolidating procurement under direct processor relationships, bypassing broadline distributors for lot-traceability guarantees. Pellet smoker automation is eroding the skill barrier that historically protected this segment's premium positioning.
- Packaged Brisket:Vacuum-sealed retail formats with extended shelf stability through modified atmosphere packaging.
- Seasoned Brisket:Pre-rubbed formulations targeting ghost kitchen operators seeking flavor consistency without spice inventory investment.
Fresh brisket leads volumes today; smoked brisket is gaining share fastest.
Distribution Channel:
Channel selection tracks buyer scale and specification complexity, with large-volume operators disintermediating traditional tiers.
- Supermarkets:Case-ready retail formats with USDA grade labeling for household consumers. Texas and Kansas City grocery chains are expanding dedicated barbecue sections as regional cuisine migrates beyond traditional consumption zones. Shelf-space competition is intensifying between commodity Select grade and certified Prime tier placement.
- Online Retail:Direct-to-consumer platforms and meat subscription services with origin documentation and temperature-controlled logistics. This channel is climbing the fastest as millennial households seek pit-quality results without equipment investment, capturing margin previously allocated to distributor networks.
- Butcher Shops:Custom fabrication with whole-packer breakdown and trim specification control.
- Foodservice:Broadline and specialty distributors serving institutional kitchens with portion-controlled formats.
Foodservice dominates transaction volume; online retail shows the steepest expansion trajectory.
End User:
User type determines specification stringency, from traceability mandates in chain restaurants to flexibility demands in mobile operations.
- Restaurants:Fixed-location operators with consistent volume forecasting and grade-certification requirements. Texas-based regional chains are accelerating smoked brisket menu placements as USDA standards tighten, creating structural squeeze between procurement targets and certified supply availability.
- Households:Residential consumers purchasing through retail or subscription channels, with demand bifurcating between raw material for home smoking enthusiasts and fully-cooked heat-and-serve formats.
- Caterers:Event-based volume with fluctuating specifications and seasonal demand spikes.
- Food Trucks:Mobile operators prioritizing yield efficiency and holding stability over grade certification.
Restaurants anchor procurement volume; households are expanding most quickly through digital channels.
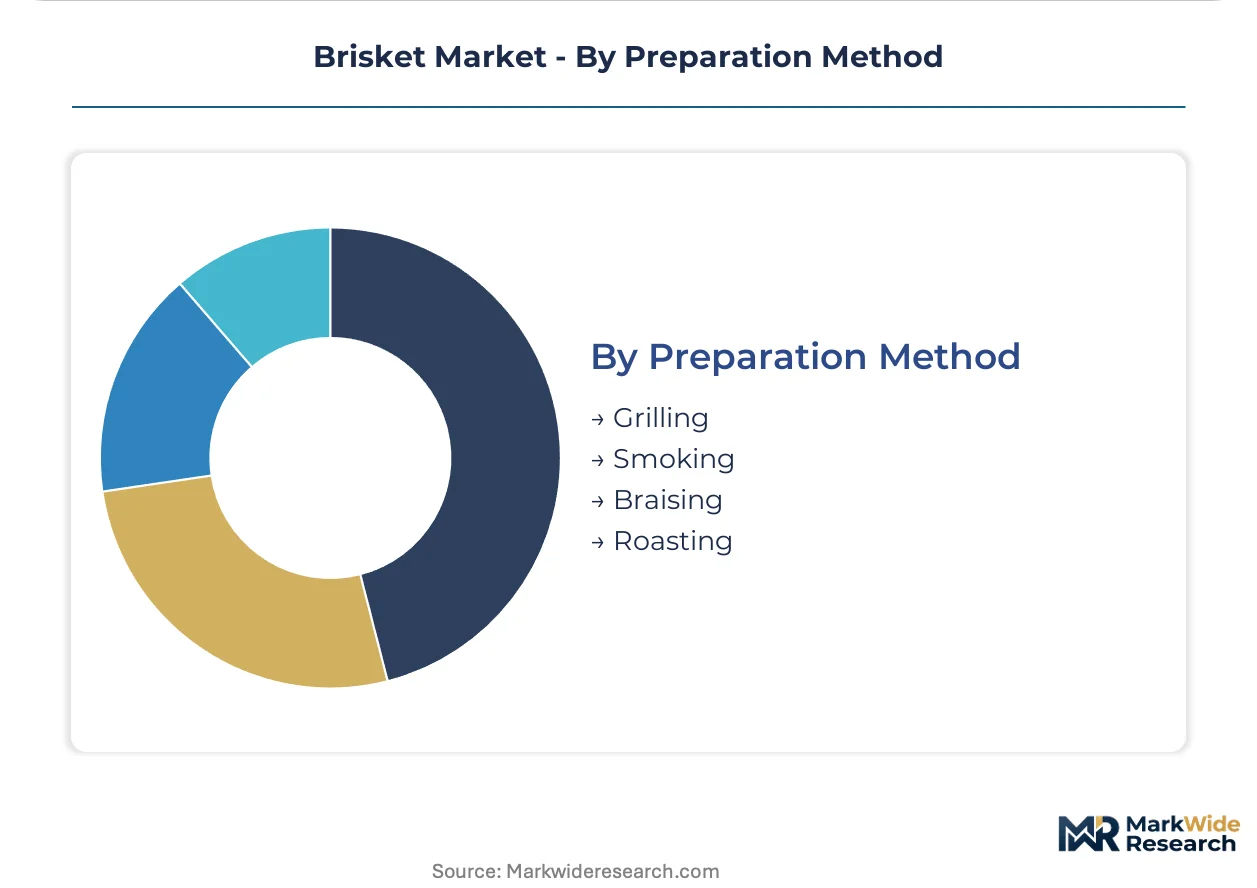
Preparation Method:
Method selection reflects equipment capital intensity and labor hour allocation, with traditional techniques competing against accelerated alternatives.
- Smoking:Low-temperature hardwood combustion producing bark formation and smoke ring penetration through myoglobin reaction. Pellet systems with precision temperature control are automating overnight fire-tending shifts, reducing labor hours per unit and compressing the skill barrier that protected independent pitmasters.
- Braising:Moist-heat collagen breakdown in enclosed vessels, common in institutional settings without dedicated smoking infrastructure.
- Grilling:Direct high-heat application for thin-sliced applications with shorter cook cycles.
- Roasting:Dry-heat oven preparation yielding softer bark and reduced smoke penetration.
Smoking commands the premium tier; braising dominates institutional volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping brisket production geography as compliance cost differentials between jurisdictions redirect capital toward regions with streamlined inspection protocols and favorable feedlot economics. Processors are migrating operations to exploit gaps in environmental enforcement capacity while maintaining USDA-equivalent safety standards for export eligibility.
United States
Texas and Kansas City restaurant chains are accelerating smoked brisket menu placements as USDA grading standards tighten for Prime and Choice classifications. The EPA's Clean Water Act enforcement intensifies compliance burdens at slaughter facilities, favoring southern Plains operators with pre-installed anaerobic digesters. Tyson Foods leverages vertical integration from feed yards to case-ready processing across the Texas-Oklahoma corridor.
Brazil
Integrated feedlot-to-processing operations are expanding export-grade supply for Asian foodservice buyers seeking non-US origin diversification. The country's national agricultural regulator enforces sanitary standards aligned with international trade requirements. Geographic expansion of captive supply chains in Mato Grosso and São Paulo states creates new certified export capacity.
Australia
Emerging critical supply zone status for international foodservice buyers is driving processor investment in lot-traceability systems. The national food standards authority maintains equivalence protocols with USDA grading for seamless market access. Queensland and New South Wales processing clusters are consolidating under direct export contracts with North American distributors.
Canada
Alberta and Prairie Provinces feedlot capacity is capturing volume shifts from drought-stressed US southern Plains operations. Health Canada inspection protocols enable cross-border supply integration under harmonized safety frameworks. Regional processors are expanding case-ready fabrication capacity to serve Pacific Northwest restaurant demand.
Germany
Specialized corned beef production for European foodservice channels leverages EFSA-compliant processing infrastructure. REACH chemical safety mandates shape packaging material specifications for modified atmosphere retail formats. Bavarian meat processing clusters are developing premium smoked product lines targeting Central European barbecue restaurant expansion.
Brisket Market Vendor Landscape
United States producers anchor one tier; Brazil and Australia specialists hold export-grade positioning. The vendor base concentrates around integrated packers with captive feedlot supply and regional processors dependent on spot cattle markets. Three archetypes dominate: vertically integrated giants controlling upstream supply, mid-scale smoked product specialists, and commodity-focused broadline distributors. Competitive moves center on direct-to-processor contract consolidation and geographic expansion of case-ready fabrication capacity.
Among US-based integrated packers, Tyson Foods, JBS USA Holdings, and Hormel Foods Corporation exemplify contrasting strategic positions. Tyson Foods represents the feedlot-to-retail integration archetype with southern Plains geographic dominance. JBS USA Holdings anchors the scale-driven processing tier through corridor concentration in cattle supply zones. Hormel Foods Corporation occupies the specialized product tier via seasoned and smoked line differentiation targeting foodservice distributors.
| Leading Market Players |
|---|
| Tyson Foods |
| Conagra Brands |
| Hormel Foods Corporation |
| Cargill |
| JBS USA Holdings |
| National Beef Packing Company |
| Smithfield Foods |
| Freirich Foods |
| Pilgrim's Pride Corporation |
| Others |
Supply Flow & Price Mechanics
Pellet smoker automation is compressing labor hours per brisket while simultaneously shifting margin capture from skilled pitmasters toward equipment manufacturers and processor-direct channels. This technology transition rewards operators with capital deployment capacity while squeezing independent restaurants dependent on traditional fire-tending economics.
Pricing Analysis
Distributor margin layers in foodservice channels are compressing as large barbecue chains bypass broadline networks for direct processor relationships with lot-traceability guarantees. Three-tier pricing structure across USDA Prime, Choice, and Select grades separates certified supply from commodity tiers, with Prime premiums widening as grading standards tighten. Pricing pressure stems from drought-driven feedlot input volatility that destabilizes cost predictability for raw material procurement. Independent pit-style restaurants exhibit highest price sensitivity due to limited contract volume leverage, while institutional foodservice programs absorb premiums through standardized portion-control economics.
Supply Chain Analysis
Reverse-logistics flows for temperature-controlled brisket returns are minimal given perishability constraints, though processor credit programs for quality failures create implicit feedback loops into production planning. Supply concentrates in the United States, Australia, and Brazil, with southern Plains processing corridors anchoring North American volume. Raw material dependencies center on corn and soybean feed inputs, cattle genetics for marbling consistency, and hardwood supply for traditional smoking operations. Single-source vulnerability runs through concentrated southern Plains packer geography where localized weather or labor disruptions cascade rapidly. Distribution runs through foodservice broadline networks for mid-scale operators and direct-processor contracts for large chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The brisket market has entered a late-cycle quality phase where USDA Prime and Choice certification scarcity commands supplier loyalty premiums as restaurant chains accelerate smoked brisket menu placements.
For Market Incumbents: Anchor competitive position through captive feedlot supply agreements that buffer cattle price volatility while securing Prime-grade certification access. Invest in anaerobic digester infrastructure ahead of EPA Clean Water Act enforcement intensification to absorb volume shifts from non-compliant regional processors. Defend against pellet smoker automation threats by embedding proprietary seasoning formulations and smoke profiles that resist equipment commoditization. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable entry vector, capturing millennial household demand for pit-quality results without equipment investment. Target ghost kitchen operators seeking pre-rubbed seasoned brisket with flavor consistency guarantees and minimal spice inventory requirements. Pursue white-label processor partnerships that bypass distributor margin extraction while building lot-traceability credentials for eventual chain restaurant supply qualification. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale smoked product specialists because fragmented regional barbecue chains are consolidating procurement under unified specification standards that reward scaled suppliers. The 5-to-10-year viability window favors processors with pre-installed environmental compliance infrastructure and direct export contracts to Asian foodservice buyers. Monitor Australia and Brazil export supply zone development as the inflection signal for non-US origin diversification demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Feedlot-to-Processing Integration | Tyson Foods leverages captive cattle supply across the Texas-Oklahoma corridor to sustain margin capture through volatile price cycles. |
| Pellet Smoker Technology Adoption | Mid-scale barbecue restaurants reduce overnight labor shifts through precision temperature control systems that automate collagen breakdown. |
| Direct-to-Consumer Channel Launch | Online retail platforms bypass traditional wholesale tiers, capturing margin previously allocated to broadline distributor networks. |
| Environmental Compliance Infrastructure | Southern Plains operators with pre-installed anaerobic digesters absorb volume shifts from EPA non-compliant competitors. |
| Export Supply Zone Development | Australian processors invest in lot-traceability systems to serve North American distributors seeking non-US origin diversification. |
Methodological Framework
Direct dialogue with pitmaster operators, foodservice procurement directors, USDA grading officials, and meat processing plant managers grounded the qualitative foundation of this study. Secondary validation drew from USDA Agricultural Marketing Service reports, EPA enforcement disclosures, FSIS inspection protocols, and trade data from the National Cattlemen's Beef Association. Bottom-up demand modeling across restaurant chain expansion plans and top-down supply assessment from feedlot capacity data were triangulated for coherence.
Segmented volume and value trajectories emerged from disaggregated modeling across product type, distribution channel, end user, and preparation method dimensions throughout the projection horizon. CAGRs were derived from fitted growth curves applied to historical consumption patterns and projected menu placement acceleration. Key forecast inputs included drought resilience investment timelines in Texas feedlots and pellet smoker adoption rates in mid-scale restaurant operations.
The model assumes a particular technology adoption path for smoking automation; alternative pathways where traditional pitmaster craftsmanship retains premium positioning would alter the outlook for labor substitution economics. Forecasts reflect assumptions about USDA grading standard stability and EPA enforcement continuity that regulatory shifts could revise. Practitioners should monitor Australia export contract volumes and Brazil integrated operation expansion for early signals of supply geography reconfiguration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
United States Frozen Meat Market
Meat Products
Beef Fat Powder Market
Meat Products
Grass Fed Beef Market
Meat Products
Europe Animal Protein Market
Meat Products
India Animal Protein Market
Meat Products
Meat Products Market
Meat Products
United States Red Meat Market
Meat Products
United States Bacon Market
Meat Products
Asia-Pacific Low Fat Sausage Market
Meat Products
Canned Beef Market
Meat Products
North America Red Meat Market
Meat Products
North America Bacon Market
Meat Products
Western Europe Ready-To-Eat Meat Market
Meat Products
Saudi Arabia Edible Meat Market
Meat Products
Poultry Processing Meat Market
Meat Products
Meat Mincers Market