
 Shark Meat Market | 2026-2036
Shark Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Shark Meat Market Outlook
The price-performance gap between premium line-caught fillets and commodity trawled product is broadening across wholesale channels. Wenzhou Haideli Shark Products Co. Ltd. anchors its position through captive cold-chain infrastructure from Zhejiang ports. Maruha Nichiro Corporation leverages decades of Japanese distribution relationships to sustain premium positioning in East Asian retail. Thai Union Group competes on scale, operating multi-species processing lines that absorb volume fluctuations across global export markets.
Shark meat comprises the striated muscle tissue of elasmobranch species, typically processed at sea through immediate gutting and chilling to control urea conversion and ammonia development. Its primary commercial purpose centers on human consumption across fresh, frozen, dried, and smoked formats, with secondary use in fishmeal and pet food applications. Frozen product dominates value retention across long-haul export routes, while fresh fillets command concentrated margin pools in coastal food service channels. Dried and smoked segments serve established demand in East African and Northeast Asian ethnic markets where preservation extends shelf life without refrigerated logistics.
The EU IUU Regulation and CITES Appendix II listings for hammerhead and oceanic whitetip sharks constrain legal supply access, forcing processors to document chain-of-custody through every transfer point. NOAA Fisheries in the United States enforces shark finning prohibitions under the Shark Fin Sales Elimination Act, redirecting domestic landings toward whole-carcass utilization. China's Ministry of Agriculture and Rural Affairs implements seasonal fishery closures in the South China Sea that directly constrain raw material availability for Fujian and Zhejiang processors. Stakeholders must monitor how escalating traceability mandates reshape procurement economics between certified sustainable sources and conventional supply lines.
Market Dynamics
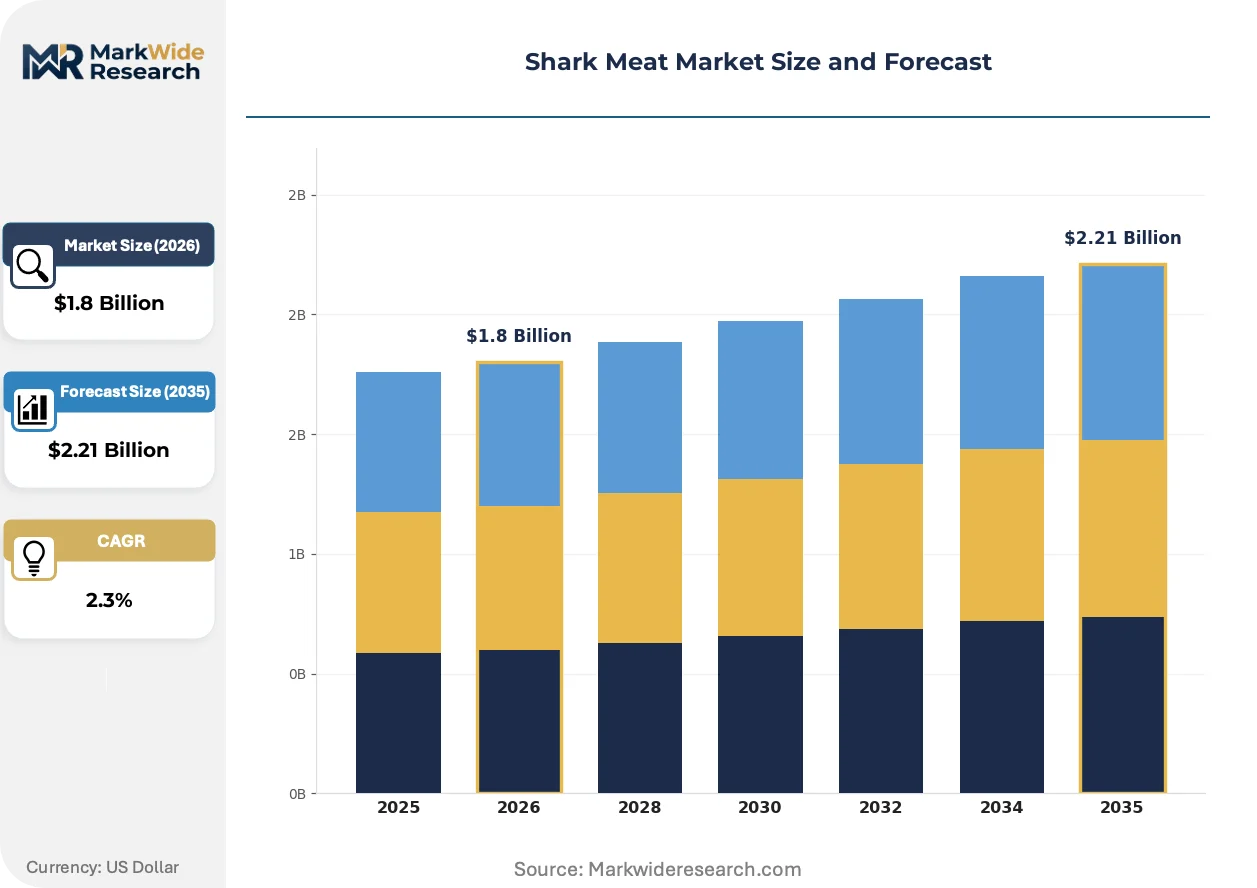
Traceability mandates from EU IUU Regulation and CITES Appendix II listings are compressing legal supply access while concentrating processing capacity in certified Chinese coastal clusters. This regulatory scaffolding forces processors to document chain-of-custody through every transfer point, reshaping procurement economics between sustainable sources and conventional supply lines.
Growth Catalysts
- Food service channel expansion:Southeast Asian restaurant networks absorb frozen fillet volumes as shark fin substitutes gain menu traction in Thailand and Vietnam.
- EU IUU Regulation compliance infrastructure:Certified processors capture margin premiums through documented sustainable sourcing that satisfies European import documentation requirements.
- Whole-carcass utilization mandates:NOAA Fisheries enforcement of the Shark Fin Sales Elimination Act redirects US domestic landings toward meat processing rather than fin-only harvests.
Market Restraints
- Raw material volatility:China's Ministry of Agriculture seasonal closures in the South China Sea constrain Fujian and Zhejiang processor throughput during peak demand windows.
- Supply concentration risk:Processing gravity centers on Wenzhou and Xiamen port clusters, creating single-point vulnerability for frozen export logistics.
- Substitution pressure:Tilapia and pangasius fillets displace shark meat in price-sensitive African and Latin American markets where consumers prioritize cost over species provenance.
Strategic Opportunities
- East African dried segment penetration:Kenya and Tanzania ethnic markets sustain demand for smoked product without refrigerated distribution infrastructure.
- Pet food application expansion:Fishmeal processors in Peru and Chile formulate shark-derived protein into premium pet nutrition lines.
- Blockchain traceability integration:Distributed ledger systems enable real-time catch documentation that satisfies EU IUU and emerging US import transparency requirements.
Industry Challenges
- Cold-chain capex intensity:Immediate gutting and chilling at sea requires vessel-level refrigeration retrofit investment that strains small-scale operator balance sheets.
- CITES permit timeline compression:Hammerhead and oceanic whitetip Appendix II documentation delays create inventory gaps for processors dependent on these species.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shark Meat Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.21 Billion |
| CAGR (2026 – 2036) | 2.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Frozen, Dried, Smoked End User: Retail, Wholesale, Food Service, Export Processing Method: Filleting, Marinating, Canning, Drying Distribution Channel: Direct Sales, Online Retail, Grocery Stores, Seafood Markets |
| Companies Covered | Aquafin Trade Inc., Wenzhou Haideli Shark Products Co. Ltd., Thai Union Group, ALL EASY GO FROZEN SEAFOOD CO., LTD, Fujian Haoyuan Food Co. Ltd., Maruha Nichiro Corporation, East Coast Seafood LLC, Talleys, Nippon Suisan Kaisha, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shark Meat Market Strategic Shifts
Digital traceability systems and preservation technology advances are compressing the gap between harvest documentation and retail shelf presentation. These shifts reduce information asymmetry while extending viable distribution radius for perishable product.
Blockchain-enabled catch documentation is unifying vessel-level data with port-of-entry customs systems in real time. EU import inspectors and large-scale retail buyers in Germany and France are adopting these verification protocols fastest. This unifying infrastructure collapses the documentation burden that previously delayed clearance at Rotterdam and Hamburg entry points.
REACH-compliant cold-chain packaging mandates from ECHA are forcing processors to phase out legacy refrigerants in favor of low-global-warming-potential alternatives. This industrial consequence raises unit logistics costs for frozen fillet exports to European markets. Spanish and Italian importers are responding by consolidating purchase volumes through fewer, larger-certified suppliers to amortize compliance overhead.
Direct procurement from certified vessel operators is displacing traditional auction-house intermediation in Japanese and South Korean wholesale channels. Large-scale food service distributors in Osaka and Busan now contract directly with Indonesian and Philippine longline fleets. This pattern is most visible in premium sashimi-grade blue shark segments where provenance documentation commands measurable price premiums.
Shark Meat Market Segmentation
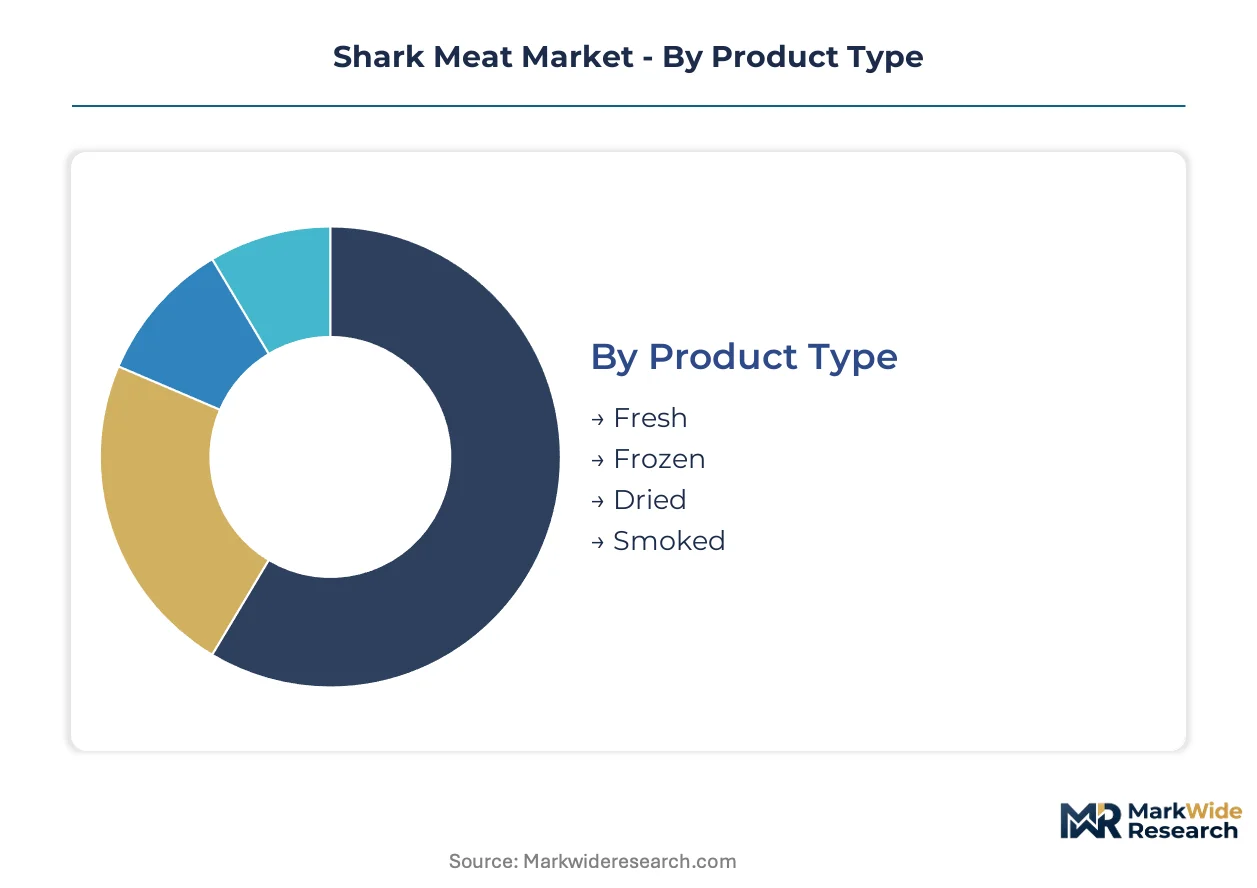
Segmentation in the shark meat market tracks how preservation state, buyer type, and channel structure determine margin capture and regulatory exposure. Each dimension reveals distinct procurement economics and cold-chain investment requirements.
Product Type:
Integration depth varies sharply: frozen and fresh segments demand continuous refrigeration infrastructure, while dried and smoked products function as standalone shelf-stable formats.
- Frozen:Immediate blast-freezing at -18°C locks in texture and arrests urea degradation for transoceanic shipment. Demand concentrates in European import channels where ECHA REACH-compliant packaging mandates raise logistics costs but sustain premium positioning for certified sustainable fillets.
- Fresh:Unfrozen striated muscle requires vessel-level chilling within hours of harvest and maintains viability only through direct air freight to coastal food service buyers. Japanese and South Korean wholesale channels absorb the highest volumes, with Osaka distributors contracting directly with Indonesian longline fleets for sashimi-grade blue shark.
- Dried:Salt-cured and air-dried product eliminates refrigeration dependency entirely.
- Smoked:Thermal processing extends shelf life for East African ethnic markets in Kenya and Tanzania.
Volume placements concentrate in Frozen; the faster expansion belongs to Fresh.
End User:
Cost tier stratification separates commodity absorption from value-added processing, with each buyer type imposing distinct documentation and handling requirements.
- Food Service:Restaurants and institutional kitchens in Thailand and Vietnam drive frozen fillet uptake as shark fin substitutes gain menu traction. Southeast Asian channel expansion absorbs volumes that European retailers reject due to traceability documentation gaps.
- Export:Cross-border movement to EU and US markets demands CITES permits for hammerhead and oceanic whitetip species, with Rotterdam and Hamburg entry points adopting blockchain verification fastest.
- Retail:Supermarket chains in coastal Chinese provinces stock fresh and frozen formats for household consumption.
- Wholesale:Auction-house intermediation in Wenzhou and Xiamen port clusters feeds downstream processors.
Margin capture peaks in Food Service; Export channels face the steepest compliance cost escalation.
Processing Method:
Geographic clustering of capability determines which methods dominate regional supply bases, with filleting and canning concentrating in industrial zones.
- Filleting:Precision cutting of striated muscle into standardized portions for food service and retail packaging. Fujian and Zhejiang processing clusters in China anchor global capacity, with Wenzhou Haideli operating captive cold-chain infrastructure from port to export.
- Canning:Thermal sterilization in retort pouches creates shelf-stable protein for African and Latin American price-sensitive markets where tilapia and pangasius substitution pressure is strongest.
- Marinating:Acid or enzyme treatment for texture modification in specialty ethnic products.
- Drying:Moisture reduction for preservation without refrigerated distribution.
Throughput dominance sits with Filleting; Canning offers the most defensible cost position against substitute species.
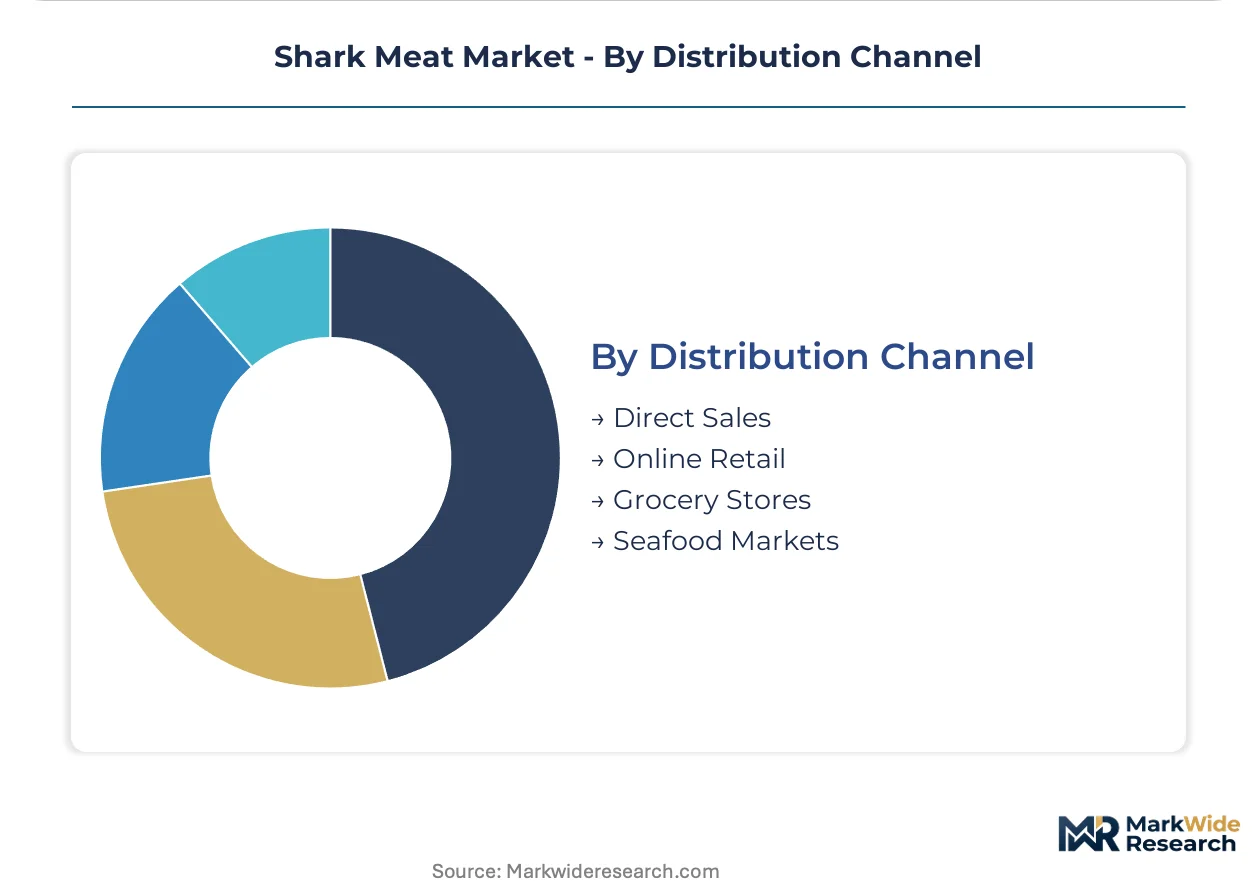
Distribution Channel:
Customer type and purchase scale separate direct procurement relationships from fragmented retail access, reshaping margin distribution across the value chain.
- Direct Sales:Large-scale food service distributors in Osaka and Busan now contract directly with certified vessel operators, bypassing traditional auction intermediation. This pattern commands measurable price premiums where provenance documentation satisfies EU IUU and emerging US import transparency requirements.
- Seafood Markets:Wet markets in Xiamen and Wenzhou handle fresh product for immediate local consumption, with seasonal closures from China's Ministry of Agriculture constraining throughput during peak demand windows.
- Grocery Stores:Coastal supermarket chains stock frozen and fresh formats for household buyers.
- Online Retail:E-commerce platforms move dried and smoked products to dispersed ethnic consumers.
Relationship intensity peaks in Direct Sales; Online Retail is climbing the fastest as traceability technology enables remote verification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wenzhou and Xiamen port clusters in China's Zhejiang and Fujian provinces anchor global processing capacity, with captive cold-chain infrastructure feeding frozen fillet exports to European and East Asian buyers. These coastal agglomerations concentrate filleting, blast-freezing, and documentation compliance under one roof.
China
Food service networks in Thailand and Vietnam absorb frozen fillet volumes as shark fin substitutes gain menu traction. China's Ministry of Agriculture seasonal closures in the South China Sea constrain Fujian and Zhejiang processor throughput during peak demand windows. Wenzhou Haideli Shark Products operates captive cold-chain infrastructure from port to export terminal.
Japan
Osaka distributors contract directly with Indonesian longline fleets for sashimi-grade blue shark, bypassing traditional auction intermediation. METI import standards enforce documentation requirements that favor established trading relationships. Kansai wholesale channels sustain premium positioning for provenance-verified product.
United States
NOAA Fisheries enforcement of the Shark Fin Sales Elimination Act redirects domestic landings toward whole-carcass meat processing rather than fin-only harvests. East Coast Seafood LLC and regional operators absorb redirected supply volumes. Gloucester and New Bedford ports handle the bulk of Atlantic landings.
Spain
REACH-compliant cold-chain packaging mandates from ECHA raise unit logistics costs for frozen fillet imports. Spanish importers consolidate purchase volumes through fewer, larger-certified suppliers to amortize compliance overhead. Vigo and Barcelona entry points adopt blockchain verification protocols fastest among Mediterranean ports.
Indonesia
Longline fleets in the Java Sea and Arafura Sea supply sashimi-grade blue shark to Japanese and South Korean buyers. Direct procurement contracts with Osaka and Busan distributors displace traditional auction-house intermediation. Surabaya and Jakarta ports function as consolidation points for export documentation.
Shark Meat Market Competitive Environment
Capital-heavy producers compete with asset-light traders across a bifurcated structure where cold-chain infrastructure ownership separates margin capture tiers. The vendor base clusters around three archetypes: integrated processors with captive port facilities, diversified seafood conglomerates operating multi-species lines, and specialized traders focusing on ethnic dried segments. Consolidation pressure favors larger operators capable of amortizing EU IUU compliance costs across volume bases. Dominant competitive moves include backward integration into vessel operations and geographic diversification of sourcing to mitigate seasonal closure impacts.
Among Chinese integrated processors, Wenzhou Haideli Shark Products Co. Ltd. exemplifies the captive infrastructure archetype, while Fujian Haoyuan Food Co. Ltd. occupies a position within the same coastal cluster. Japanese trading houses Maruha Nichiro Corporation and Nippon Suisan Kaisha represent diversified seafood conglomerates with decades of distribution relationships sustaining premium positioning in East Asian retail channels. These named entities anchor industry-level commentary without implying specific strategic actions beyond observable market patterns.
| Leading Market Players |
|---|
| Aquafin Trade Inc. |
| Wenzhou Haideli Shark Products Co. Ltd. |
| Thai Union Group |
| ALL EASY GO FROZEN SEAFOOD CO., LTD |
| Fujian Haoyuan Food Co. Ltd. |
| Maruha Nichiro Corporation |
| East Coast Seafood LLC |
| Talleys |
| Nippon Suisan Kaisha |
| Others |
Value Chain & Pricing Dynamics
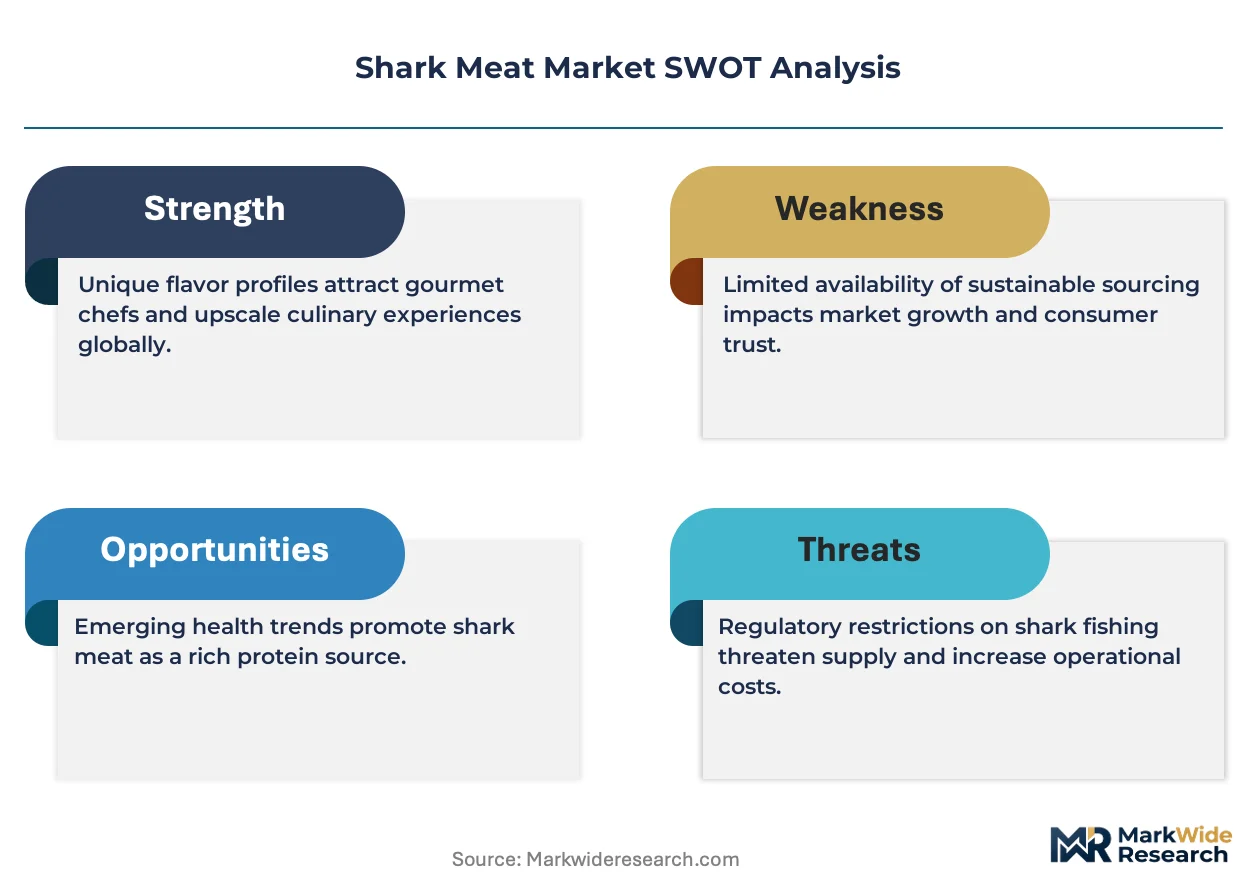
Premium line-caught fillet certification against commodity trawled product creates a bifurcation that manifests in divergent cold-chain investment requirements and procurement contract structures. This tier divergence forces buyers to choose between documented sustainable sourcing with margin premiums and conventional supply lines facing escalating EU IUU compliance costs.
Pricing Analysis
Yield-retention pricing anchors value capture, with blast-frozen sashimi-grade blue shark commanding measurable premiums based on texture preservation and ammonia control performance. Certification tier and vessel-level documentation separate premium positioning from commodity trawled product, while cost compression in African and Latin American export channels intensifies due to tilapia and pangasius substitution pressure. Food service buyers in Southeast Asia exhibit highest price sensitivity, whereas Japanese wholesale distributors in Osaka demonstrate lowest sensitivity where provenance verification sustains premium absorption.
Supply Chain Analysis
Skilled vessel crew availability in Indonesia and the Philippines determines longline fleet operational capacity for sashimi-grade harvest. Raw material flows draw from Java Sea and Arafura Sea landing points, with Fujian and Zhejiang processing clusters in China and Japanese trading houses as downstream nodes. Single-source vulnerability concentrates in Wenzhou and Xiamen port clusters where blast-freezing infrastructure feeds European export channels. Distribution runs through direct procurement contracts displacing traditional auction-house intermediation in Japanese and South Korean wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream vessel operations and captive cold-chain infrastructure represent the decisive margin-capture lever. Players are pursuing backward integration into longline fleet operations to secure documented supply access under tightening CITES and EU IUU traceability mandates.
For Market Incumbents: Hedge against raw material volatility by diversifying sourcing geography beyond South China Sea zones subject to seasonal closure. Secure multi-year direct procurement contracts with Indonesian and Philippine vessel operators to lock in sashimi-grade supply ahead of CITES permit timeline compression. Invest in blockchain-enabled catch documentation systems to sustain EU import channel access as Rotterdam and Hamburg entry points accelerate verification protocol adoption. For New Entrants and Emerging Players: E-commerce platforms for dried and smoked product distribution offer the most penetrable route into dispersed ethnic consumer bases without refrigerated logistics infrastructure. Target Kenya and Tanzania ethnic markets where smoked shark meat sustains demand absent cold-chain investment. Pursue pet food application partnerships with Peruvian and Chilean fishmeal processors as a volume-absorption channel with lower traceability documentation requirements. For Investors and Strategic Acquirers: Re-rating potential sits with certified processors possessing captive cold-chain infrastructure given escalating EU IUU compliance cost amortization advantages. Long-term viability favors operators capable of sustaining documented sustainable sourcing relationships across multi-year windows. Watch CITES Appendix II listing expansion deliberations as the critical inflection signal for legal supply access constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Longline Fleet Operations | Captive supply access secures documented provenance required for EU IUU compliance and Japanese METI import standards. |
| Blockchain Traceability System Deployment | Real-time catch documentation satisfies emerging US import transparency requirements and Rotterdam customs verification protocols. |
| REACH-Compliant Cold-Chain Packaging Transition | ECHA mandates force phase-out of legacy refrigerants, raising unit logistics costs that favor volume consolidation through larger certified suppliers. |
| Direct Procurement Contract Structuring | Osaka and Busan distributors bypass auction intermediation to capture measurable price premiums for provenance-verified sashimi-grade product. |
| Pet Food Application Formulation Partnership | Peruvian and Chilean fishmeal processors absorb shark-derived protein volumes into premium pet nutrition lines with lower documentation burden. |
Study Parameters
Multi-period observation of CITES permit issuance patterns, EU import clearance volumes at Rotterdam and Hamburg, and South China Sea seasonal closure impacts anchored the trend analysis, supplemented by interviews with longline fleet operators in Indonesia, processing plant managers in Fujian and Zhejiang, seafood procurement directors at Japanese trading houses, EU import compliance officers, and East African dried product distributors. Secondary validation drew from customs trade databases, ECHA REACH regulatory filings, NOAA Fisheries enforcement reports, and METI import standard documentation. Bottom-up vessel-level landing estimates and top-down export value flows were triangulated to constrain projection bands.
Segment-weighting across preservation state, buyer type, and channel structure determined margin capture allocation in the analytical framework across the analysis window. Product type segmentation modeled frozen, fresh, dried, and smoked formats; end-user segmentation tracked food service, export, retail, and wholesale channels; distribution channel segmentation captured direct sales, seafood markets, grocery stores, and online retail. CAGRs were derived from historical volume trajectories adjusted for regulatory intervention impacts. Forecast inputs incorporated China's Ministry of Agriculture seasonal closure schedules and EU IUU documentation adoption curves.
Inputs from Indonesian and Philippine fisheries departments, Chinese customs authorities, and Japanese trading house disclosures were available through the study window; gaps in illegal unreported unregulated landing estimates and blockchain verification adoption timelines introduce uncertainty bands around supply-side projections. Forecasts reflect documented assumptions regarding CITES listing stability and EU regulatory enforcement intensity. A small set of triggers—Appendix II expansion to additional shark species, major cold-chain infrastructure investment announcements in competing processing clusters, and US import transparency mandate finalization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Organic Pork Market
Meat Products
Meat Emulsions Market
Meat Products
India Poultry Meat Market
Meat Products
Chicken Fat Market
Meat Products
Middle-East and Africa Animal-Based Meat and Dairy Products Market
Meat Products
Bahrain Poultry Meat Market
Meat Products
United States Frozen Meat Market
Meat Products
Smokehouse Market
Meat Products
Low Fat Beef Market
Meat Products
India Animal Protein Market
Meat Products
India Edible Meat Market
Meat Products
Fresh Organic Chicken Market
Meat Products
Emulsified Meat Market
Meat Products
Western Europe Ready-To-Eat Meat Market
Meat Products
Saudi Arabia Red Meat Market
Meat Products
Sausage Premixes Market