
 Europe Animal Protein Market | 2026-2036
Europe Animal Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Animal Protein Market Foresight
Precision fermentation for alternative proteins is fragmenting traditional supply relationships between livestock processors and ingredient buyers. Gelita leverages its century-old gelatin expertise to sustain pharmaceutical-grade collagen dominance across German and Belgian production sites. Koninklijke FrieslandCampina NV anchors whey protein isolate supply for infant nutrition and sports applications through Dutch dairy cooperative scale. Darling Ingredients Inc. competes in rendering-derived protein meals, converting animal by-products into feed and pet food ingredients across its European operating network.
Europe animal protein encompasses collagen, gelatin, whey, casein, and insect-derived isolates extracted through enzymatic hydrolysis, acid or alkali processing, and mechanical separation, with functional parameters including bloom strength, protein content, and amino acid profile determining suitability for food, pharmaceutical, or feed applications. Poultry leads product type volume due to cost-efficient conversion ratios and shorter production cycles, while pork anchors gelatin and collagen output through integrated slaughter-to-extraction operations in Spain and Denmark. Nutraceuticals application commands premium positioning as aging European populations drive demand for joint health and skin elasticity supplements, whereas feed application faces margin compression from EU deforestation regulation compliance costs.
EMA pharmaceutical standards, EFSA novel food authorizations, and EU Green Deal nitrogen reduction targets collectively constrain raw material sourcing while elevating traceability requirements across the value chain. REACH chemical safety protocols and F-Gas Regulation phase-outs further reshape processing technology investments for cold-chain-dependent protein fractions. Stakeholders must monitor how CSRD sustainability disclosure rules will reallocate capital between conventional livestock operations and fermentation-based protein platforms.
Market Dynamics
The EU Green Deal's nitrogen emission ceilings are forcing livestock processors to reconfigure supply relationships around precision fermentation platforms and insect-based alternatives, fragmenting century-old procurement patterns between slaughterhouses and ingredient buyers.
Growth Catalysts
- Clean-label functional peptides:Food processors in Germany and France are expanding procurement of collagen peptides for reformulations that eliminate synthetic additives while maintaining texture and shelf stability.
- EMA pharmaceutical standards:Aging European populations drive nutraceutical demand for joint health and skin elasticity supplements, tightening quality specifications that favor established extraction expertise.
- Auvergne-Rhône-Alpes cluster density:Co-location of meat processors, dairy protein facilities, and pharmaceutical gelatin consumers in this French region reduces logistics costs and accelerates just-in-time ingredient supply.
Market Restraints
- Input cost volatility:Feed grain prices and energy costs for cold-chain-dependent whey and casein fractions compress margins for dairy cooperative processors.
- Supply concentration risk:Rendering-derived protein meals depend on a limited network of slaughterhouse partnerships in Spain and Denmark, creating vulnerability to livestock disease outbreaks.
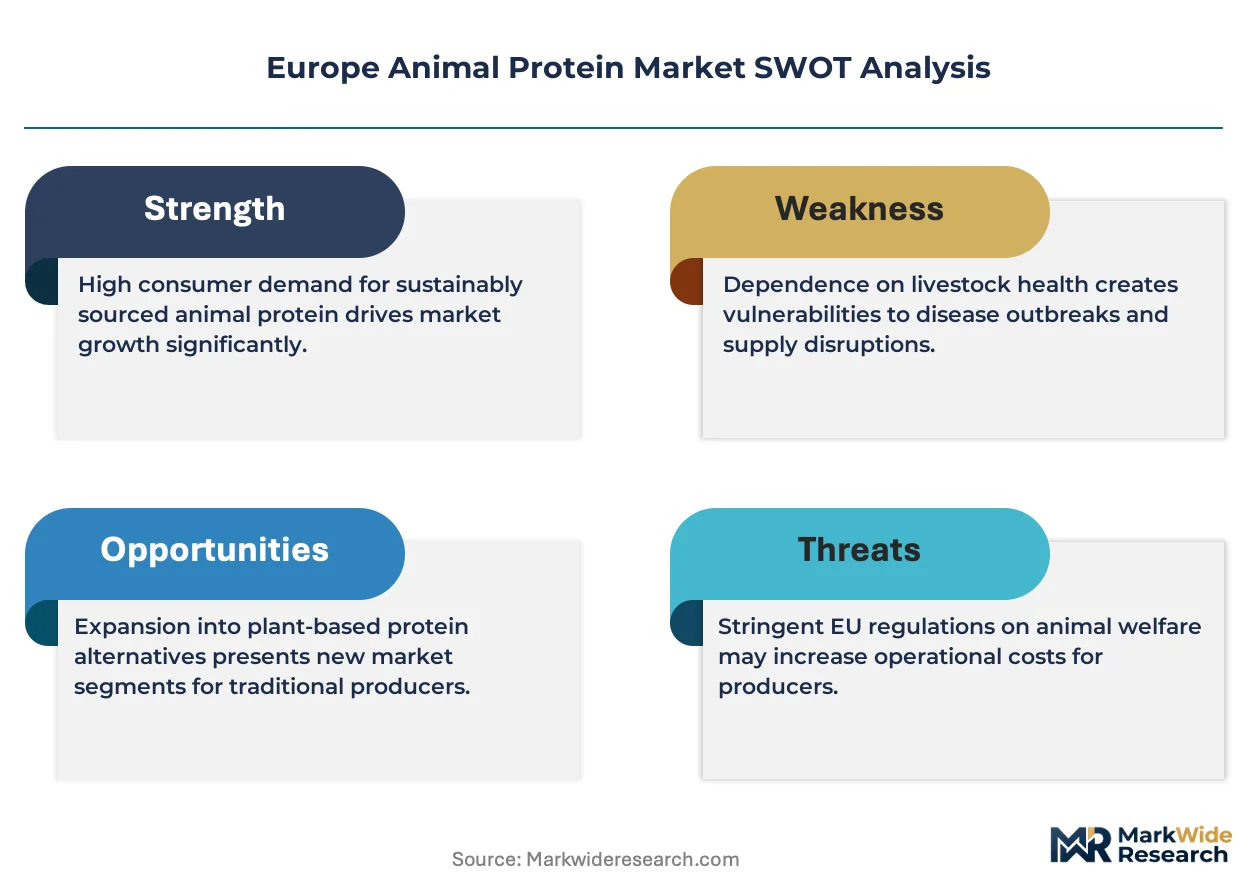
- Regulatory friction:EFSA novel food authorization timelines for insect-based proteins extend commercialization cycles by months, delaying revenue recognition for fermentation startups.
Strategic Opportunities
- Underpenetrated Baltic states:Estonia, Latvia, and Lithuania lack integrated collagen extraction infrastructure, creating entry points for processors with enzymatic hydrolysis capabilities.
- CSRD sustainability disclosure rules:Mandatory supply chain transparency requirements will reallocate capital toward traceable fermentation platforms and away from conventional livestock operations.
- Sports nutrition channel innovation:Direct-to-consumer whey protein isolate brands are bypassing traditional pharmaceutical distributors, capturing margin previously absorbed by wholesale intermediaries.
Industry Challenges
- Bioprocess engineering talent scarcity:Precision fermentation scale-up requires specialized expertise in metabolic pathway optimization that European universities currently underproduce.
- Legacy system integration friction:Conventional rendering facilities face technical complexity retrofitting acid and alkali processing lines to handle novel insect biomass feedstocks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Animal Protein Market |
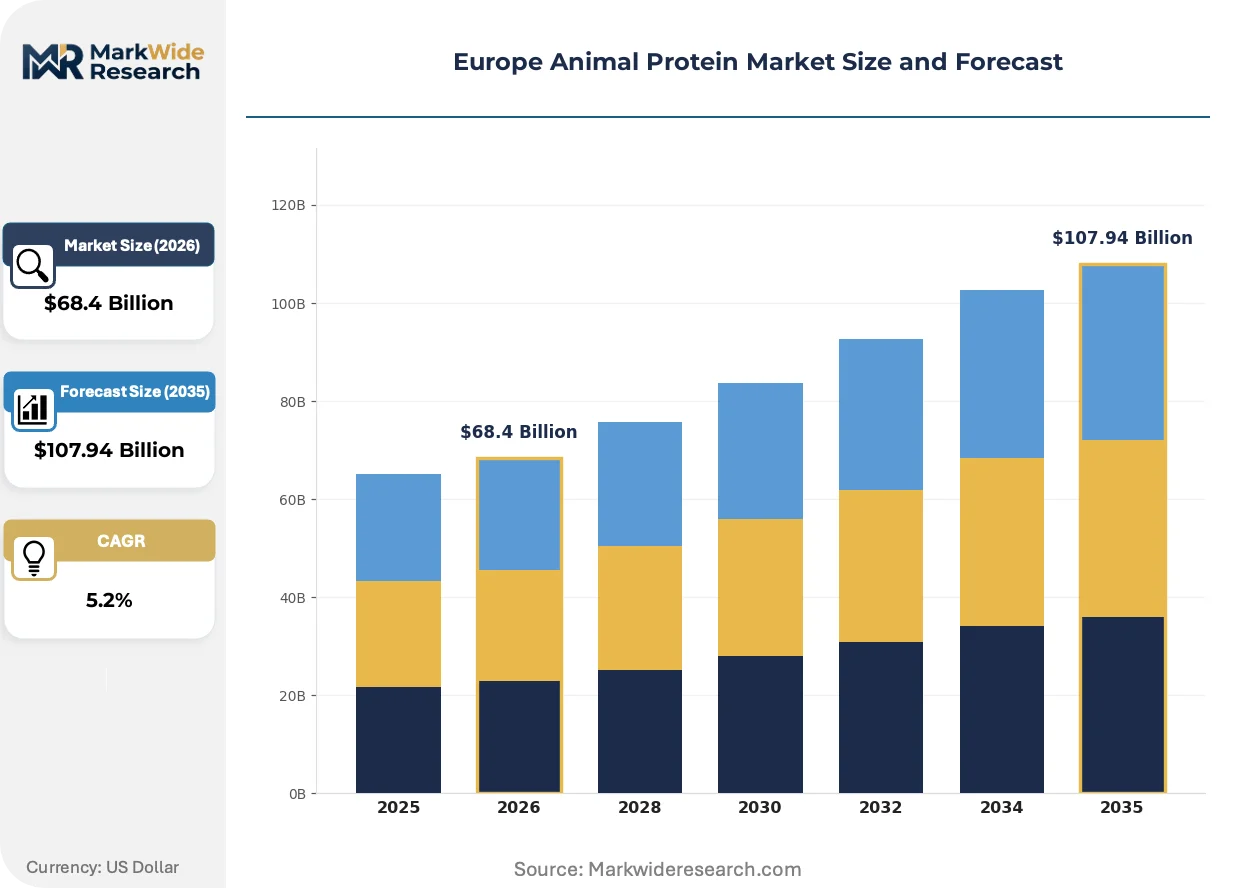
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $107.94 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Pork, Poultry, Lamb End User: Household, Food Service, Retail, Food Processing Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale Application: Food, Feed, Nutraceuticals, Others |
| Companies Covered | Gelita, SAS Gelatines Weishardt, Koninklijke FrieslandCampina NV, Essentia Protein Solutions, Agrial Enterprise, Darling Ingredients Inc., Lactalis Ingredients, Ÿnsect, Arla Foods amba, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Animal Protein Market Shifts & Advancements
Biotechnology platforms are reconfiguring how animal-derived and alternative proteins enter formulated products, with regulatory pressure and buyer behavior shifts accelerating adoption timelines beyond conventional industry cycles.
Precision fermentation for recombinant collagen and whey proteins is virtualizing traditional livestock-dependent supply chains. Pharmaceutical and nutraceutical formulators in Belgium and the Netherlands are adopting these ingredients at pilot scale now, with commercial volumes projected within regulatory approval windows. This technology is virtualizing the need for integrated slaughter-to-extraction operations, compressing capital requirements for new market entrants.
REACH chemical safety protocols and F-Gas Regulation phase-outs are reshaping processing technology investments across cold-chain-dependent protein fractions. Manufacturers must retrofit solvent-based extraction equipment or face operational restrictions. Whey protein isolate producers in the Netherlands and Denmark are most affected, accelerating capital deployment toward aqueous enzymatic alternatives.
Buyer concentration among food processing multinationals is compressing supplier qualification timelines and demanding consolidated ingredient portfolios. Mid-sized collagen and gelatin processors in Germany face consolidation pressure as procurement teams reduce vendor counts. France's Auvergne-Rhône-Alpes cluster demonstrates this most visibly, where integrated meat and dairy protein facilities now supply single-source contracts to pan-European formulation houses.
Europe Animal Protein Market Segmentation
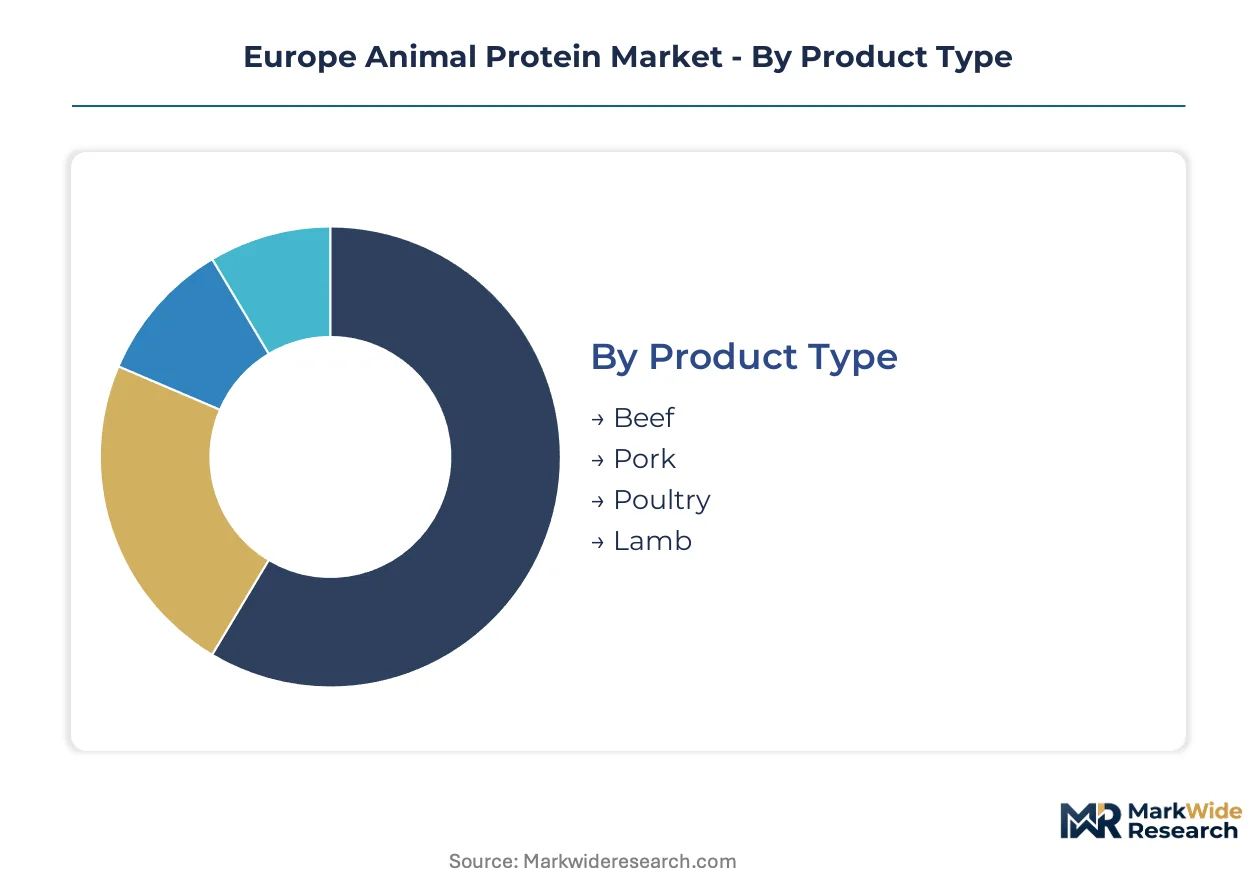
Segmentation in the Europe animal protein market reveals how regulatory pressure and buyer consolidation are reallocating volume across traditional livestock categories and novel extraction platforms. Understanding these divisions exposes where margin concentrates and where capital is migrating.
Product Type:
Mature slaughter-to-extraction operations coexist with emerging fermentation platforms across Europe's protein landscape.
- Pork:Integrated operations in Spain and Denmark convert carcasses into pharmaceutical-grade gelatin and collagen through acid and alkali processing lines. Demand from EMA-regulated nutraceutical formulators in Belgium tightens bloom strength specifications, favoring established extractors with century-old expertise.
- Poultry:Cost-efficient feed conversion ratios and shortened production cycles drive volume leadership. French and German processors supply clean-label collagen peptides to food manufacturers eliminating synthetic texturizers under EU Green Deal reformulation pressures.
- Beef:Premium bovine-derived collagen isolates serve orthopedic and wound-care applications through Italian and German medical device channels.
- Lamb:Niche output from Mediterranean basin processors targets halal-certified nutraceutical segments with specific amino acid profile requirements.
Pork handles the majority of throughput; poultry is the fastest mover on share.
End User:
Procurement sophistication varies sharply across customer types, with consolidated buyers extracting supply chain transparency concessions unavailable to fragmented purchasers.
- Food Processing:German and French formulation houses demand consolidated ingredient portfolios with CSRD-compliant traceability documentation. These buyers compress supplier qualification timelines and negotiate single-source contracts spanning collagen, whey, and emerging insect isolates.
- Food Service:Contract caterers and restaurant groups in the Netherlands prioritize cost-stable protein meals for menu planning, rendering-derived supplies from Darling Ingredients' European network.
- Retail:Supermarket private-label programs in Poland and Romania source commodity-grade packaged proteins with limited functional specification requirements.
- Household:Direct consumption of unprocessed cuts persists in Southern European markets with strong traditional butchery cultures.
Food processing commands the steepest expansion trajectory; food service anchors baseline volume stability.
Distribution Channel:
Cold-chain infrastructure investment and regulatory compliance costs are reshaping which channels can profitably handle temperature-sensitive protein fractions.
- Supermarkets:Controlled-environment distribution networks across France and Germany maintain whey protein isolate integrity for sports nutrition shelf placement.
- Wholesale:Pan-European ingredient distributors in the Auvergne-Rhône-Alpes cluster consolidate meat, dairy, and pharmaceutical gelatin supply to reduce logistics costs for just-in-time delivery.
- Online Retail:Direct-to-consumer whey isolate brands bypass traditional pharmaceutical distributors, capturing margin previously absorbed by wholesale intermediaries in Dutch and Belgian markets.
- Specialty Stores:Independent health food retailers in Scandinavia curate premium collagen peptide assortments for aging demographics seeking joint health solutions.
Wholesale maintains throughput dominance; online retail is climbing the fastest on penetration metrics.
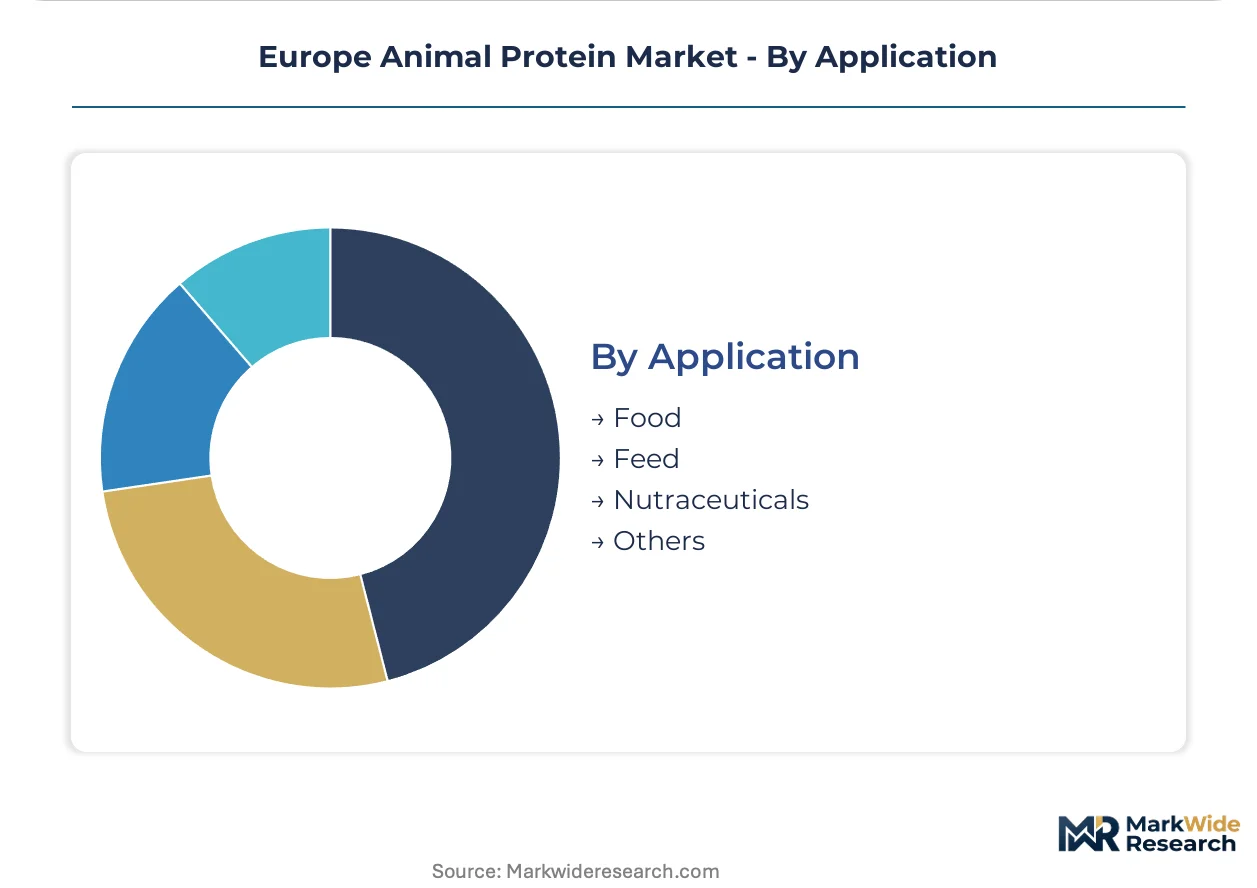
Application:
Margin structure diverges dramatically between regulated pharmaceutical pathways and commodity feed channels facing compliance cost compression.
- Nutraceuticals:Aging European populations drive premium positioning for joint health and skin elasticity supplements. EMA pharmaceutical standards tighten quality specifications, rewarding Gelita's German and Belgian extraction expertise with sustained dominance.
- Food:Clean-label reformulations eliminate synthetic additives while maintaining texture through functional collagen peptides. French and German processors expand enzymatic hydrolysis capacity to meet this specification shift.
- Feed:EU deforestation regulation compliance costs compress margins for rendering-derived protein meals. Darling Ingredients converts animal by-products across its European network into feed and pet food ingredients facing regulatory friction.
- Others:Cosmetic and industrial gelatin applications persist in Italian leather processing and photographic film manufacturing with declining volume trajectories.
Food commands current volume leadership; nutraceuticals is gaining share fastest on value metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement teams at German and French food processing multinationals concentrate demand for functional collagen peptides and whey isolates, while pharmaceutical formulators in Belgium and the Netherlands tighten quality specifications for gelatin-derived nutraceuticals.
Germany
Clean-label reformulation mandates from the EU Green Deal drive food processors toward enzymatic hydrolysis capacity for synthetic additive replacement. REACH chemical safety protocols force solvent-based extraction retrofits or operational restrictions. The Baden-Württemberg cluster hosts integrated gelatin extractors supplying EMA-regulated pharmaceutical channels with century-old processing expertise.
France
Aging demographics expand nutraceutical demand for joint health supplements with specific amino acid profiles. EFSA novel food authorization timelines delay insect-based protein commercialization for fermentation startups. The Auvergne-Rhône-Alpes concentration co-locates meat processors, dairy protein facilities, and pharmaceutical gelatin consumers for just-in-time supply consolidation.
Netherlands
Dairy cooperative scale anchors whey protein isolate supply for infant nutrition and sports applications facing cold-chain integrity requirements. F-Gas Regulation phase-outs reshape processing technology investments for temperature-sensitive fractions. Rotterdam-Antwerp logistics corridors consolidate pan-European distribution for rendering-derived protein meals.
Spain
Integrated pork slaughter-to-extraction operations convert carcasses into pharmaceutical-grade gelatin through acid and alkali processing lines. EU deforestation regulation compliance costs compress margins for conventional livestock processors. Catalonia and Aragon host rendering facilities supplying Darling Ingredients' European network with animal by-product feedstocks.
Belgium
Pharmaceutical formulators adopt precision fermentation collagen at pilot scale ahead of commercial volume projections. EMA pharmaceutical standards tighten bloom strength specifications that favor established extractors. The Flanders biotech corridor anchors recombinant protein platform development with metabolic pathway optimization capabilities.
Europe Animal Protein Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply relationships. Consolidation pressure intensifies as procurement teams reduce vendor counts and demand single-source contracts spanning collagen, whey, and emerging insect isolates. Three archetypes dominate: century-old gelatin extractors with pharmaceutical-grade expertise, dairy cooperative processors leveraging cooperative scale, and fermentation startups commercializing recombinant alternatives. Dominant competitive moves include backward integration into rendering operations and capacity expansion for enzymatic hydrolysis lines.
Within the established extractor tier, Gelita and SAS Gelatines Weishardt represent archetypes of pharmaceutical-grade dominance sustained through EMA-compliant production heritage. Koninklijke FrieslandCampina NV occupies a position exemplifying cooperative-scale dairy protein supply. Darling Ingredients Inc. anchors rendering-derived protein meal conversion across European operating networks. Ÿnsect sits within the fermentation startup archetype navigating EFSA novel food authorization timelines.
| Leading Market Players |
|---|
| Gelita |
| SAS Gelatines Weishardt |
| Koninklijke FrieslandCampina NV |
| Essentia Protein Solutions |
| Agrial Enterprise |
| Darling Ingredients Inc. |
| Lactalis Ingredients |
| Ÿnsect |
| Arla Foods amba |
| Others |
Supply & Pricing Matrix
Denmark and Spain's integrated pork slaughter-to-extraction operations concentrate upstream supply for pharmaceutical-grade gelatin, anchoring margin pools downstream with EMA-regulated nutraceutical formulators in Belgium who pay premiums for bloom strength certification.
Pricing Analysis
Cost-plus contracts with feed grain and energy indexation dominate whey protein isolate procurement between Dutch dairy cooperatives and infant nutrition manufacturers. Price differentiation rests on EMA pharmaceutical certification tier and cold-chain logistics capability, with feed-grade protein meals facing acute cost compression from EU deforestation regulation compliance. Pharmaceutical-grade collagen peptides command the least price sensitivity due to EMA quality specifications, while commodity feed ingredients face intense buyer pressure.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from pan-European ingredient distributors have become standard for just-in-time delivery to Auvergne-Rhône-Alpes cluster buyers. Raw material sourcing draws from Danish pork by-products, Dutch whey streams, and emerging French insect biomass feedstocks. Single-source vulnerability concentrates in Spain and Denmark's rendering facility network. Distribution runs through Rotterdam-Antwerp logistics corridors consolidating pan-European protein fraction movements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bioprocess engineering talent scarcity constrains precision fermentation scale-up, with European universities underproducing metabolic pathway optimization expertise that commercial recombinant protein platforms require.
For Market Incumbents: Pre-empt fermentation startup encroachment by acquiring enzymatic hydrolysis capabilities in underpenetrated Baltic states before EFSA novel food authorizations mature. Backward integration into rendering operations secures captive supply of animal by-product feedstocks against Darling Ingredients' network expansion. EMA pharmaceutical certification investments defend margin position against recombinant collagen displacement. For New Entrants and Emerging Players: Mid-market food processors in Poland and Romania represent the most penetrable entry point for commodity-grade collagen peptides lacking EMA certification requirements. Direct-to-consumer sports nutrition channels in Dutch and Belgian markets bypass wholesale margin absorption. Partner with Auvergne-Rhône-Alpes cluster distributors for just-in-time supply credibility. For Investors and Strategic Acquirers: Capital is best deployed toward century-old gelatin extractors with EMA-compliant production heritage and established bloom strength expertise that precision fermentation cannot immediately replicate. Long-term viability favors processors with dual capability in conventional extraction and enzymatic hydrolysis platform retrofit. Watch EFSA novel food authorization timelines for insect-based proteins as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Hydrolysis Capacity Expansion | Meets EU Green Deal clean-label reformulation mandates for synthetic additive replacement in German food processing. |
| Backward Integration into Rendering | Secures captive animal by-product supply against concentration risk in Spain and Denmark slaughterhouse networks. |
| Precision Fermentation Platform Development | Virtualizes traditional livestock-dependent supply chains for recombinant collagen and whey protein production. |
| EMA Pharmaceutical Certification Investment | Sustains premium positioning against nutraceutical formulators tightening bloom strength specifications in Belgium. |
| Baltic States Geographic Expansion | Captures underpenetrated collagen extraction infrastructure opportunity in Estonia, Latvia, and Lithuania markets. |
Research Methodology
Operator-level perspectives from gelatin extraction plant managers, dairy cooperative procurement leads, pharmaceutical formulation scientists, and EFSA regulatory affairs specialists anchored the qualitative base. Secondary validation drew from EMA pharmaceutical filings, EFSA novel food authorization databases, EU Green Deal implementation trackers, and customs trade data for protein fraction movements. Bottom-up capacity assessments triangulated against top-down demand modeling across nutraceutical, food, and feed application channels.
Scenario-bracketing around EU nitrogen emission ceiling compliance timelines and EFSA authorization velocity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user procurement sophistication tier, application regulatory pathway, and regional production cluster density. CAGRs derived from installed capacity expansion schedules, buyer consolidation patterns, and substitution elasticity between conventional and fermentation-derived protein platforms.
Macroeconomic conditions sit as an overlay; deviation in feed grain prices, natural gas costs for cold-chain operations, or eurozone industrial demand would shift the trajectory. Forecasts reflect documented assumptions about regulatory implementation pacing and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Meat Packaging Market
Meat Products
Global Beef Market
Meat Products
Bahrain Poultry Meat Market
Meat Products
Low-Fat Ham Market
Meat Products
Meat Emulsions Market
Meat Products
GCC Edible Meat Market
Meat Products
Europe Processed Meat Market
Meat Products
India Poultry Meat Market
Meat Products
Grass Fed Beef Market
Meat Products
Grassfed Jerky Market
Meat Products
Brazil Meat Products Market
Meat Products
Organic Meat Market
Meat Products
South Africa Processed Meat Market
Meat Products
United States Bacon Market
Meat Products
Edible Offal Market
Meat Products
Middle East Edible Meat Market