
 North America Processed Poultry Meat Market | 2026-2036
North America Processed Poultry Meat Market Size, Share, and Industry Trends Forecast 2026-2036
North America Processed Poultry Meat Market Insights
Automation in deboning and portioning is fragmenting traditional processing economics across the supply chain. Tyson Foods leverages captive breeding-to-retail integration to sustain margin control. Koch Foods anchors its position through specialized further-processing capacity in the Midwest. Perdue Farms differentiates via antibiotic-free and organic product lines that command premium positioning.
Processed poultry meat encompasses mechanically separated, formed, cured, or cooked chicken and turkey products typically containing standardized moisture-to-protein ratios, phosphate additives for water retention, and sodium levels governed by USDA labeling standards. These products serve commercial foodservice operators and retail consumers seeking protein convenience with reduced preparation time. Frozen chicken and deli meat represent mature volume categories where margin pools have compressed, while chicken sausages and value-added nuggets capture faster expansion as retailers expand private-label alternatives and foodservice chains reformulate menus. Distribution through food service channels and supermarkets concentrates volume, though online retail and convenience stores are gaining traction for smaller-format, ready-to-cook offerings.
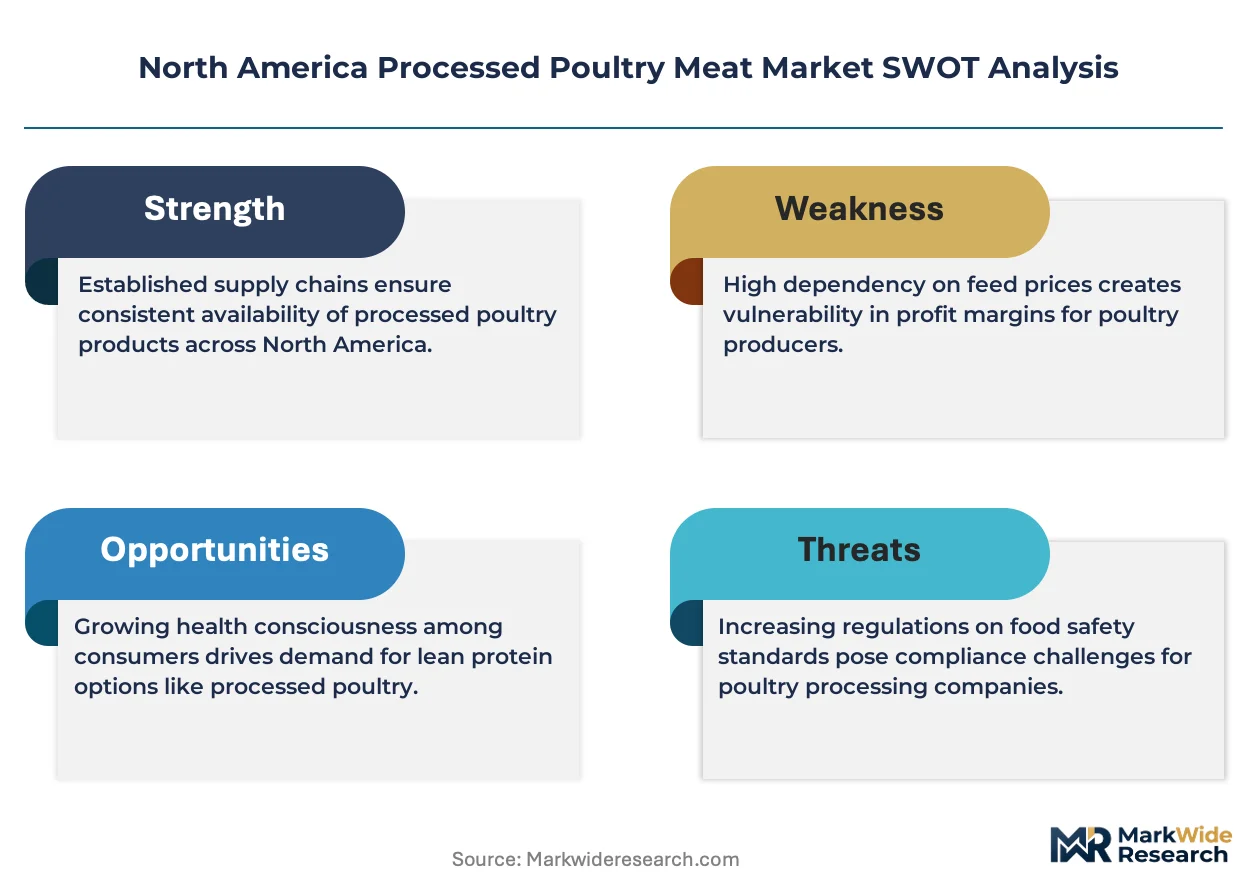
USDA FSIS inspection protocols, FDA food safety modernization requirements, and OSHA workplace safety standards collectively elevate capital requirements and operational compliance costs for processors. The USDA's Salmonella performance standards for raw poultry products are tightening, forcing facilities to invest in pathogen detection and intervention technologies. Stakeholders must monitor how pending label transparency rules and state-level cage-free mandates reshape sourcing requirements and consumer price sensitivity across the value chain.
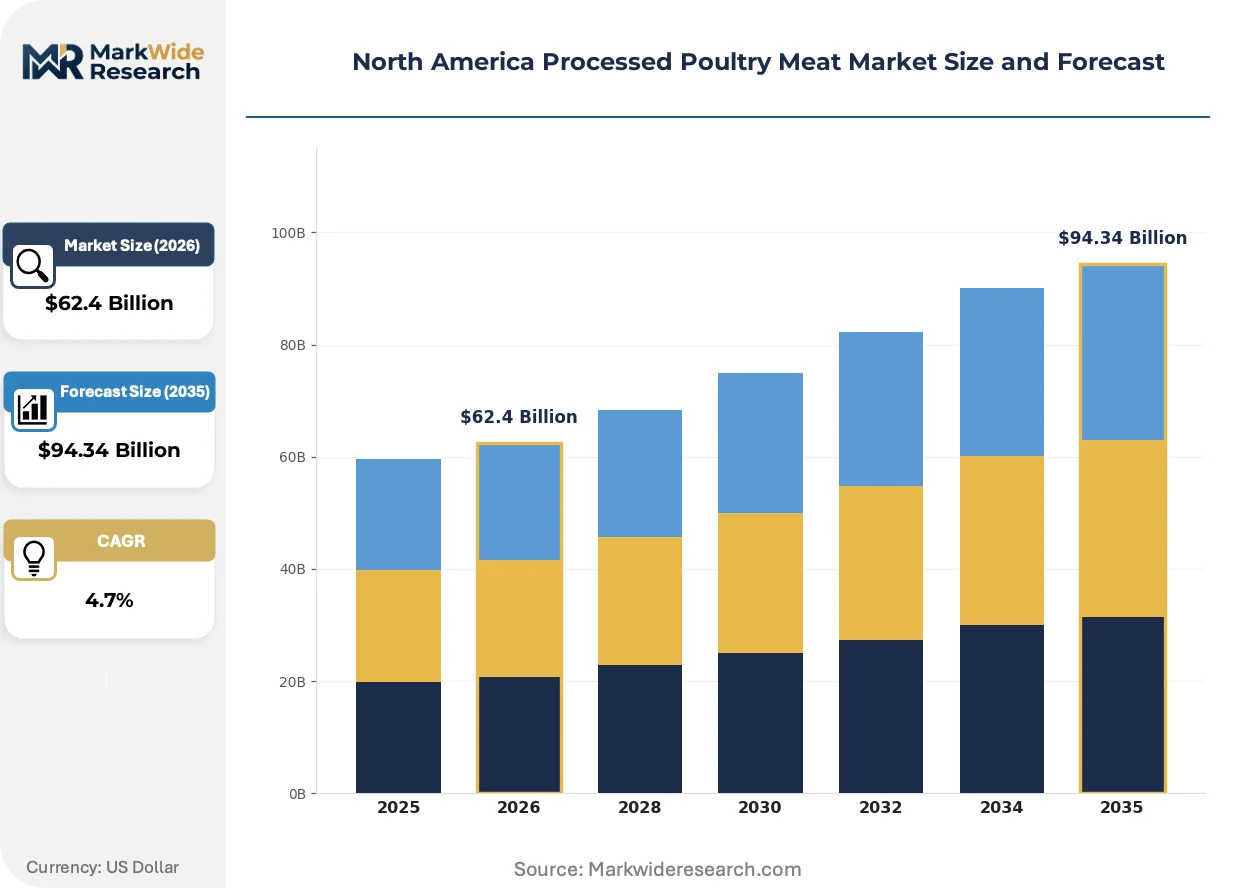
Market Dynamics
USDA FSIS inspection protocol revisions are compressing processing economics and forcing capital redeployment toward pathogen intervention systems. The updated Salmonella performance standards are eliminating marginal operators while rewarding facilities with integrated detection infrastructure.
Growth Catalysts
- QSR menu expansion:Quick-service chains across the United States and Canada are accelerating poultry-centric product launches, pulling volume through further-processing facilities.
- USDA automation incentives:Modernized inspection rules reduce line-speed restrictions for facilities deploying camera-based defect detection, compressing labor cost structures.
- Southeast cluster concentration:Georgia, Alabama, and Arkansas host vertically integrated breeding-to-processing operations that minimize logistics friction and cold-chain breakage.
Market Restraints
- Feed input volatility:Corn and soybean meal price swings transmit directly to live bird costs, compressing processor margins without forward-contract coverage.
- Midwest processing concentration:Koch Foods and similar operators anchor capacity in Illinois and Indiana, creating supply vulnerability during regional logistics disruptions.
- Plant-based substitution:Pea and mycoprotein alternatives are capturing shelf-space in California and Pacific Northwest retail, pressuring conventional volume growth.
Strategic Opportunities
- Canadian market underpenetration:Ontario and Quebec retail channels show lower private-label poultry penetration than U.S. equivalents, offering white-space for branded entry.
- Online direct-to-consumer channels:Subscription meal-kit platforms and refrigerated e-commerce are bypassing traditional distributor markups for premium antibiotic-free lines.
- State cage-free mandates:California's Proposition 12 and similar state laws are forcing supply-chain reconfiguration that rewards early compliance with premium shelf placement.
Industry Challenges
- Automation technician scarcity:Robotic deboning and vision-system maintenance require skill sets absent in traditional meat-cutting labor pools, inflating recruitment costs.
- Legacy ERP integration:Real-time yield tracking and FSIS-compliant lot traceability demand overlaying new sensor infrastructure onto decades-old plant control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Processed Poultry Meat Market |
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $94.34 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chicken Nuggets, Chicken Sausages, Deli Meat, Frozen Chicken Distribution Channel: Supermarkets, Online Retail, Food Service, Convenience Stores End User: Households, Restaurants, Cafeterias, Catering Services Packaging Type: Vacuum Packs, Canned, Tray Packs, Resealable Bags |
| Companies Covered | Tyson Foods, Perdue Farms, Koch Foods, JBS USA Holdings, Cargill, Smithfield Foods, Conagra Brands, Hormel Foods Corporation, Foster Farms, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Processed Poultry Meat Market Trends and Innovations
Digital infrastructure is virtualizing physical processing workflows, compressing decision latency from days to minutes. Three interconnected shifts are restructuring how value is captured across the supply chain.
Computer vision and machine learning systems are virtualizing quality control functions previously executed by human inspectors. Tyson Foods and Perdue Farms are deploying camera arrays on evisceration and trim lines to detect defects at line speeds exceeding human perceptual limits. This technology is virtualizing the traditional USDA inspector presence model, enabling higher throughput with reduced labor headcount while generating granular yield data for real-time optimization.
USDA FSIS finalized its Salmonella framework for raw poultry products, establishing enforceable pathogen limits that displace the prior performance-standard approach. Facilities must now implement validated intervention technologies or face enforcement action including suspension of inspection. Further-processed products with kill-step cooking are less exposed, but raw comminuted items face elevated compliance costs and potential supply contraction.
Foodservice procurement is consolidating toward direct-processor relationships that displace broadline distributor intermediaries. Chains like Chick-fil-A and Popeyes are negotiating specification-based contracts with Tyson and Pilgrim's Pride for proprietary product formats. This pattern is most visible in the U.S. Southeast, where processor-proximity enables just-in-time delivery and custom formulation without distributor inventory carrying costs.
North America Processed Poultry Meat Market Segmentation
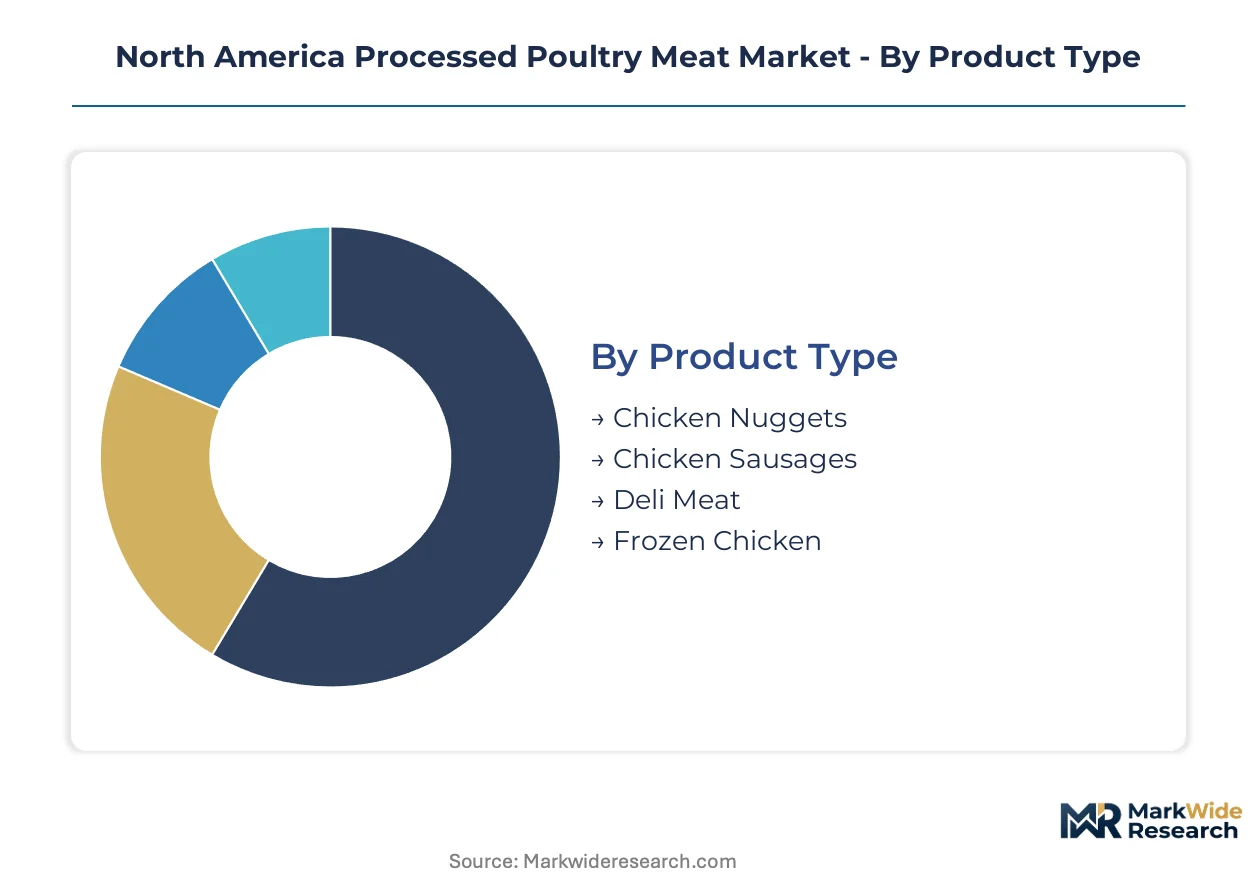
Processed poultry meat markets fragment across multiple dimensions that determine margin capture and capital allocation. Product form, channel access, and end-use specifications each create distinct competitive arenas with diverging growth trajectories and compliance burdens.
Product Type:
Cost tier differentiation separates commoditized frozen formats from value-added further-processed lines with ingredient premiums.
- Chicken Nuggets:Formed and breaded products containing mechanically separated meat with standardized moisture-to-protein ratios. Quick-service chains in the U.S. Southeast are expanding proprietary nugget specifications, pulling volume through dedicated further-processing lines with custom breading profiles.
- Chicken Sausages:Comminuted and encased products incorporating spice matrices, phosphate additives for water retention, and natural or synthetic casings. Retail channels in Ontario and Quebec show lower private-label penetration than U.S. equivalents, creating white-space for branded entry with antibiotic-free positioning.
- Deli Meat:Cured or cooked whole-muscle products sliced for sandwich applications. Mature volume category where margin pools have compressed under retailer pricing pressure.
- Frozen Chicken:Raw or minimally processed cuts in bulk formats for foodservice and institutional procurement. Frozen chicken anchors volume throughput in vertically integrated breeding-to-processing operations.
Frozen chicken holds installed capacity. Chicken sausages are rotating up the share rankings.
Distribution Channel:
Application context determines packaging specifications, temperature requirements, and margin structures across the value chain.
- Supermarkets:Branded and private-label retail formats with refrigerated display case placement and promotional calendar dependency. California and Pacific Northwest supermarkets are expanding shelf-space for plant-based alternatives alongside conventional poultry.
- Online Retail:Direct-to-consumer and third-party platform distribution requiring cold-chain integrity through last-mile delivery. Subscription meal-kit platforms are bypassing traditional distributor markups for premium antibiotic-free lines in metropolitan U.S. markets.
- Food Service:Broadline distributor and direct-processor supply to commercial operators. Chick-fil-A and Popeyes negotiate specification-based contracts with processors for proprietary formats, displacing distributor intermediaries.
- Convenience Stores:Smaller-format, ready-to-cook offerings targeting immediate consumption and meal replacement. Gaining traction for single-serve and grab-and-go poultry products.
Food service holds installed capacity. Online retail is rotating up the share rankings.
End User:
Customer type dictates volume scale, specification complexity, and procurement sophistication across demand segments.
- Households:Retail consumers seeking protein convenience with reduced preparation time. Price sensitivity concentrates in standard frozen and deli categories while premium antibiotic-free lines command shelf placement in coastal U.S. markets.
- Restaurants:Commercial operators ranging from independent establishments to chain accounts with proprietary specifications. USDA FSIS Salmonella performance standards are elevating compliance costs for raw comminuted items supplied to quick-service chains.
- Cafeterias:Institutional feeding operations in schools, hospitals, and corporate facilities with cost-driven procurement and nutritional compliance requirements.
- Catering Services:Event-based and contract foodservice with variable volume forecasting and specialized portioning needs.
Households hold installed capacity. Restaurants are rotating up the share rankings.
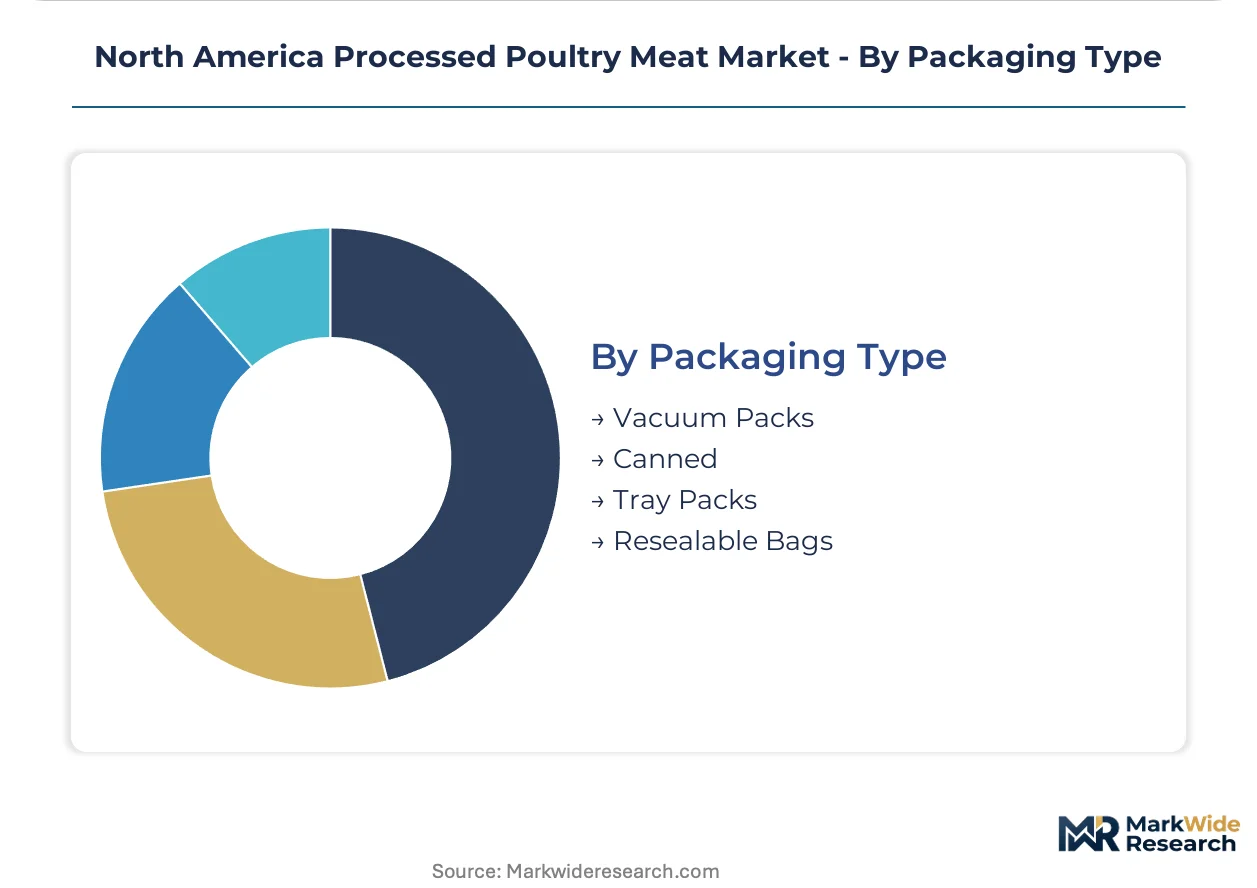
Packaging Type:
Supply concentration in modified atmosphere and vacuum technologies shapes shelf-life extension and logistics economics.
- Vacuum Packs:Oxygen-excluded barrier films extending refrigerated shelf life through anaerobic preservation. Dominates deli meat and portioned retail formats where oxidation control determines quality retention.
- Canned:Thermally processed shelf-stable products with retort sterilization enabling ambient distribution. Limited to specialized applications given consumer preference for fresh and refrigerated alternatives.
- Tray Packs:Modified atmosphere packaging with gas-flushed headspace for retail display optimization. Standard for fresh chicken parts and value-added further-processed items.
- Resealable Bags:Multi-use convenience packaging with zipper closures for portion control and storage flexibility. Expanding in club store and bulk retail channels.
Vacuum packs hold installed capacity. Resealable bags are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foodservice procurement concentration in the United States Southeast and retail private-label expansion in Ontario and Quebec define buyer archetype distribution across North America. Quick-service restaurant chains anchor volume demand in integrated processing corridors. Canadian retail channels present underpenetrated white-space for branded entry.
United States
Quick-service chains including Chick-fil-A and Popeyes pull volume through dedicated further-processing lines with proprietary specifications. USDA FSIS finalized Salmonella performance standards force raw comminuted facilities to deploy validated pathogen intervention technologies. Georgia, Alabama, and Arkansas host vertically integrated breeding-to-processing clusters that minimize cold-chain breakage.
Canada
Ontario and Quebec supermarkets show lower private-label poultry penetration than U.S. equivalents, creating entry opportunity for antibiotic-free branded lines. Health Canada and CFIA enforcement of Safe Food for Canadians Regulations elevates traceability requirements for imported U.S. product. Toronto and Montreal distribution hubs concentrate cold-chain logistics for eastern Canadian retail.
Mexico
Quick-service restaurant expansion in Mexico City and Monterrey metro areas accelerates demand for standardized further-processed formats. SENASICA inspection protocols align with USDA equivalence standards for cross-border trade facilitation. Querétaro and Jalisco processing zones attract U.S. processor co-investment for duty-advantaged export production.
North America Processed Poultry Meat Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered margin pools. The vendor base concentrates around vertically integrated breeding-to-retail operators and specialized further-processing facilities. Three archetypes dominate: integrated protein conglomerates with captive supply chains, regional further-processing specialists, and diversified packaged food portfolios with poultry divisions. Competitive moves center on direct-processor foodservice contracting and automation-enabled capacity expansion.
Among U.S.-based integrated operators, Tyson Foods and Perdue Farms exemplify archetype differentiation through supply chain configuration. Koch Foods occupies a position among regional further-processing specialists with Midwest concentration. These three entities anchor the competitive structure through distinct channel access strategies rather than overlapping segment competition.
| Leading Market Players |
|---|
| Tyson Foods |
| Perdue Farms |
| Koch Foods |
| JBS USA Holdings |
| Cargill |
| Smithfield Foods |
| Conagra Brands |
| Hormel Foods Corporation |
| Foster Farms |
| Others |
Pricing and Supply Chain Analysis
Feed input volatility in corn and soybean markets transmits directly to live bird costs, compressing processor margins and forcing tiered pricing stratification across premium antibiotic-free, standard commodity, and economy frozen categories while reshaping geographic sourcing footprints toward Southeast cluster concentration.
Pricing Analysis
Cost-plus contracts indexed to Chicago Board of Trade corn and soybean meal futures dominate processor-procurement relationships, passing through 60-80% of feed cost swings within 90-day adjustment windows. Price differentiation separates USDA Organic and Certified Humane tiers commanding 35-50% premiums from conventional commodity lines where retailer pricing pressure intensifies. Cost compression in frozen chicken and deli meat categories is accelerating because of private-label expansion and QSR specification tightening. Independent restaurants and institutional cafeterias exhibit highest price sensitivity, while quick-service chains with proprietary formulations show lowest sensitivity due to menu-price pass-through capacity.
Supply Chain Analysis
USDA FSIS export-control equivalence requirements for Canadian and Mexican cross-border shipments restrict technology transfer of certain pathogen-intervention systems, fragmenting equipment vendor participation across North American facilities. Geographic supply concentration centers on Georgia, Alabama, and Arkansas for breeding-to-processing integration, with Illinois and Indiana hosting further-processing specialization. Raw material dependencies rest on Midwest corn and soybean meal, Southeast hatchery supply, and imported phosphate additives for water retention. Single-source vulnerability concentrates in automated deboning equipment where two European vendors dominate. Distribution runs through integrated processor direct-delivery networks displacing broadline distributors in the Southeast, with refrigerated trucking and cold-storage warehousing constituting downstream infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
USDA FSIS Salmonella performance standards and automation incentives are compressing legacy operator economics while rewarding capital-intensive facilities, creating a high-growth disruption favoring technology-forward processors with integrated detection infrastructure.
For Market Incumbents: Entrench position through backward integration into captive hatchery and feed-milling capacity to isolate margin from commodity volatility, while deploying camera-based defect detection systems to secure line-speed advantages under modernized inspection rules. Prioritize certification investment in USDA Organic and Certified Humane tiers to defend shelf placement against plant-based substitution pressure in California and Pacific Northwest retail.
For New Entrants and Emerging Players: Ontario and Quebec retail channels show underpenetration relative to U.S. private-label density, offering white-space entry for antibiotic-free branded lines with Health Canada traceability compliance. Target subscription meal-kit platforms and refrigerated e-commerce in Toronto and Montreal metropolitan markets, bypassing traditional distributor markups through direct-to-consumer fulfillment infrastructure.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-cap further-processing specialists with automation-enabled capacity and direct-processor foodservice relationships. Long-term viability over the coming decade hinges on regulatory compliance infrastructure rather than commodity scale alone. Monitor USDA enforcement actions against raw comminuted facilities as inflection indicator for supply contraction and margin recovery timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Automation-Enabled Capacity Expansion | Camera-based defect detection secures line-speed advantages under modernized USDA FSIS inspection protocols. |
| Direct-Processor Foodservice Contracting | Proprietary nugget and tender specifications with Chick-fil-A and Popeyes displace broadline distributor intermediaries. |
| Antibiotic-Free Certification Investment | USDA Organic and Certified Humane tiers command premium positioning in coastal U.S. and Canadian retail. |
| Backward Integration into Feed Supply | Captive corn and soybean meal sourcing isolates processor margins from Chicago Board of Trade volatility. |
| Cross-Border Canadian Market Entry | Ontario and Quebec retail channels offer branded white-space with lower private-label penetration than U.S. equivalents. |
Research Methodology
Cross-validation between processor procurement executives and QSR supply chain directors anchors the qualitative findings, supplemented by secondary validation through USDA FSIS enforcement records, SEC 10-K filings of publicly traded protein companies, and trade flow data from U.S. Census Bureau and Statistics Canada. Bottom-up and top-down triangulation reconciles facility-level capacity assessments with aggregate production statistics across Georgia, Alabama, Arkansas, Illinois, and Indiana processing corridors.
Calibration against historical price transmission patterns and regulatory implementation timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product form tier, distribution channel structure, end-use customer type, and packaging technology. CAGRs were derived from supply-demand balance projections incorporating feed cost trajectories, automation adoption curves, and cage-free mandate compliance schedules as poultry-specific forecast inputs.
Practitioners should monitor USDA FSIS enforcement intensity, corn and soybean futures volatility, and plant-based alternative shelf-space gains for early signals. Forecasts reflect assumptions regarding regulatory stability and input cost normalization. Material shifts in Salmonella performance standard stringency or feed input price regimes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Middle-East and Africa Animal-Based Meat and Dairy Products Market
Meat Products
Germany Meat Products Market
Meat Products
Meat Packaging Market
Meat Products
Rendered Poultry Products Market
Meat Products
Global Edible Meat Market
Meat Products
Lab-Grown Meat Market
Meat Products
Beef Fat Powder Market
Meat Products
Reconstituted Meat Market
Meat Products
Low Fat Beef Market
Meat Products
Meat Ingredients Market
Meat Products
United States Bacon Market
Meat Products
Beef Bouillon Market
Meat Products
Mechanically Separated Meat Market
Meat Products
Europe Animal Protein Market
Meat Products
Pork Flavors Market
Meat Products
Europe Processed Meat Market