
 Protein Hydrolysate Market | 2026-2036
Protein Hydrolysate Market Size, Share, and Industry Trends Forecast 2026-2036
Protein Hydrolysate Market Analysis
Pharmaceutical-grade protein hydrolysate specifications is redrawing competitive boundaries across the value chain. Merck KGaA leverages its bioprocessing heritage to dominate high-purity clinical nutrition supply. Fonterra Co-operative Group anchors Oceania's premium whey hydrolysate output through integrated dairy processing. Cargill competes in plant-based alternatives by extending its pea protein fractionation capabilities into specialized hydrolysate grades.
Protein hydrolysates are proteins enzymatically or chemically cleaved into peptides and free amino acids, typically achieving molecular weights below 10 kDa to enhance bioavailability and reduce allergenicity; manufacturers control degree of hydrolysis via pH-stat or osmometry to target specific functional properties for infant formula, medical foods, and performance nutrition. Whey protein hydrolysate leads value generation due to its superior leucine content and rapid gastric emptying profile, while pea protein hydrolysate emerges as the fastest-growing source category as food brands reformulate away from major allergens. Clinical nutrition applications command the deepest margin pools owing to stringent pharmacopeial compliance and hospital procurement consolidation.
FDA GRAS notifications and EPA effluent guidelines shape US manufacturing compliance costs, while EFSA novel food opinions and REACH chemical safety registrations govern European market access for new hydrolysate entrants. China's NMPA and GB standards for food-grade peptides impose additional testing protocols on imported concentrates. Stakeholders must monitor regulatory divergence between pharmacopeial-grade and food-grade classification thresholds as this boundary determines pricing power and channel eligibility.
Market Dynamics
Enzymatic hydrolysis technology maturation is compressing batch cycle times from 8 hours to under 4 hours, forcing legacy acid-hydrolysis capacity into early obsolescence across major manufacturing clusters.
Growth Catalysts
- Sports Nutrition Procurement:Professional cycling and endurance running teams now specify hydrolysate-based recovery formulations in multi-year supply contracts, locking in volume commitments that exceed clinical nutrition channel offtake.
- REACH Chemical Safety:European pre-registration dossiers for novel peptide sequences accelerate market access for hydrolysate innovators, reducing time-to-revenue for new entrants targeting EFSA novel food pathways.
- Pea Protein Fractionation:Wet-milling infrastructure expansion in the Canadian Prairies and Northern France is generating captive hydrolysate feedstock for allergen-free infant formula applications.
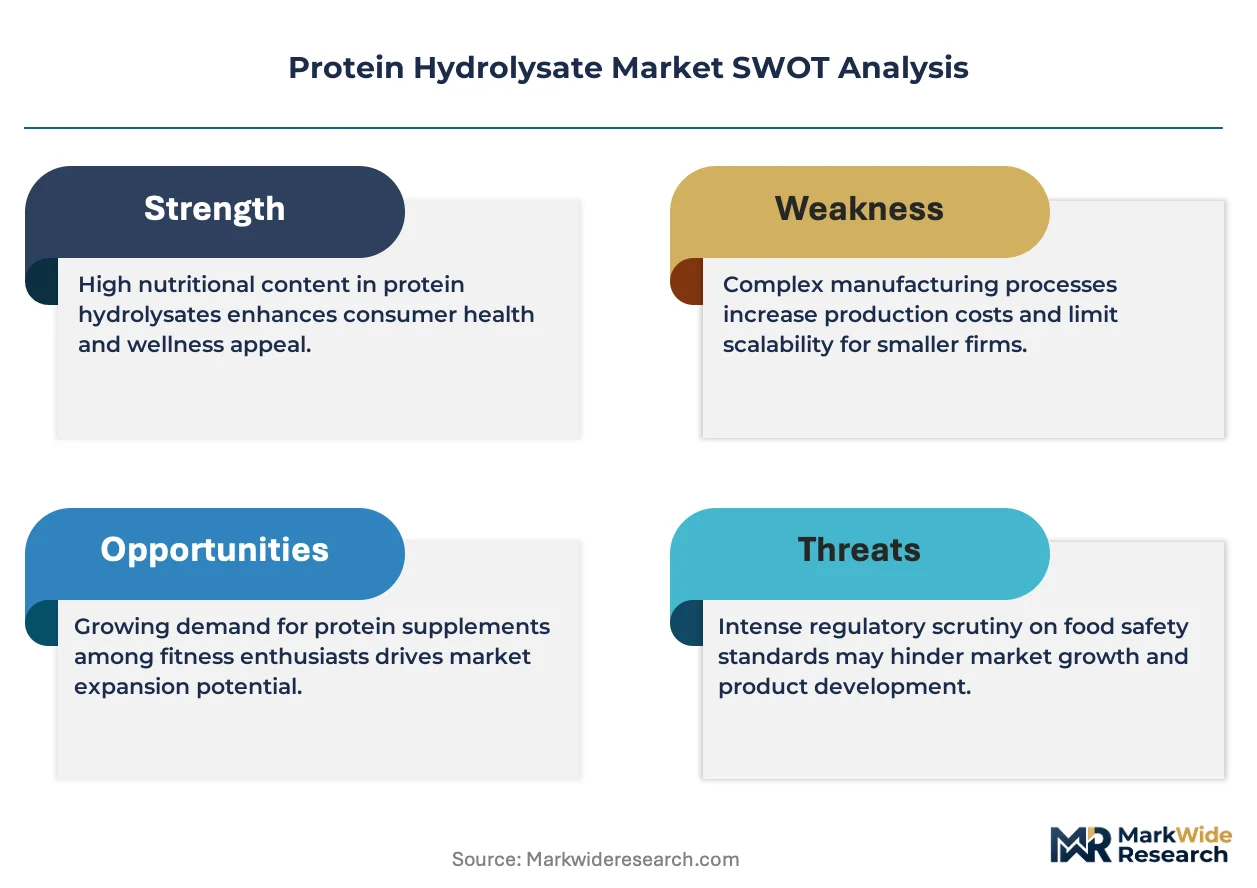
Market Restraints
- Enzyme Input Volatility:Protease concentrate prices fluctuate with fermentation substrate costs, squeezing gross margins for toll manufacturers without backward integration into enzyme production.
- Chinese Import Testing:NMPA extended peptide sequencing protocols add 6-10 weeks to customs clearance, straining working capital for exporters targeting food-grade concentrate segments.
- Intact Protein Substitution:Cold-processed microfiltrated whey isolates achieve comparable leucine bioavailability without hydrolysis capital expenditure, threatening mid-tier hydrolysate positioning in performance nutrition.
Strategic Opportunities
- Cellular Agriculture Feedstock:Precision fermentation platforms require pharmaceutical-grade amino acid cocktails, creating premium hydrolysate demand from cultivated meat bioreactor operators.
- India PLI Scheme:Food processing infrastructure incentives under the Production Linked Incentive framework support domestic hydrolysate manufacturing for export-oriented nutraceutical clusters.
- Direct-to-Consumer Subscription:Personalized nutrition platforms bypass traditional wholesale distribution, capturing margin pools previously allocated to sports nutrition brand intermediaries.
Industry Challenges
- Peptide Characterization Talent:Mass spectrometry analysts with hydrolysate-specific method development experience command 40% salary premiums, constraining quality control scaling for mid-cap producers.
- Pharmacopeial Certification Timelines:USP and EP monograph compliance for clinical nutrition grades requires 18-24 month validation cycles, delaying revenue recognition for new manufacturing lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protein Hydrolysate Market |
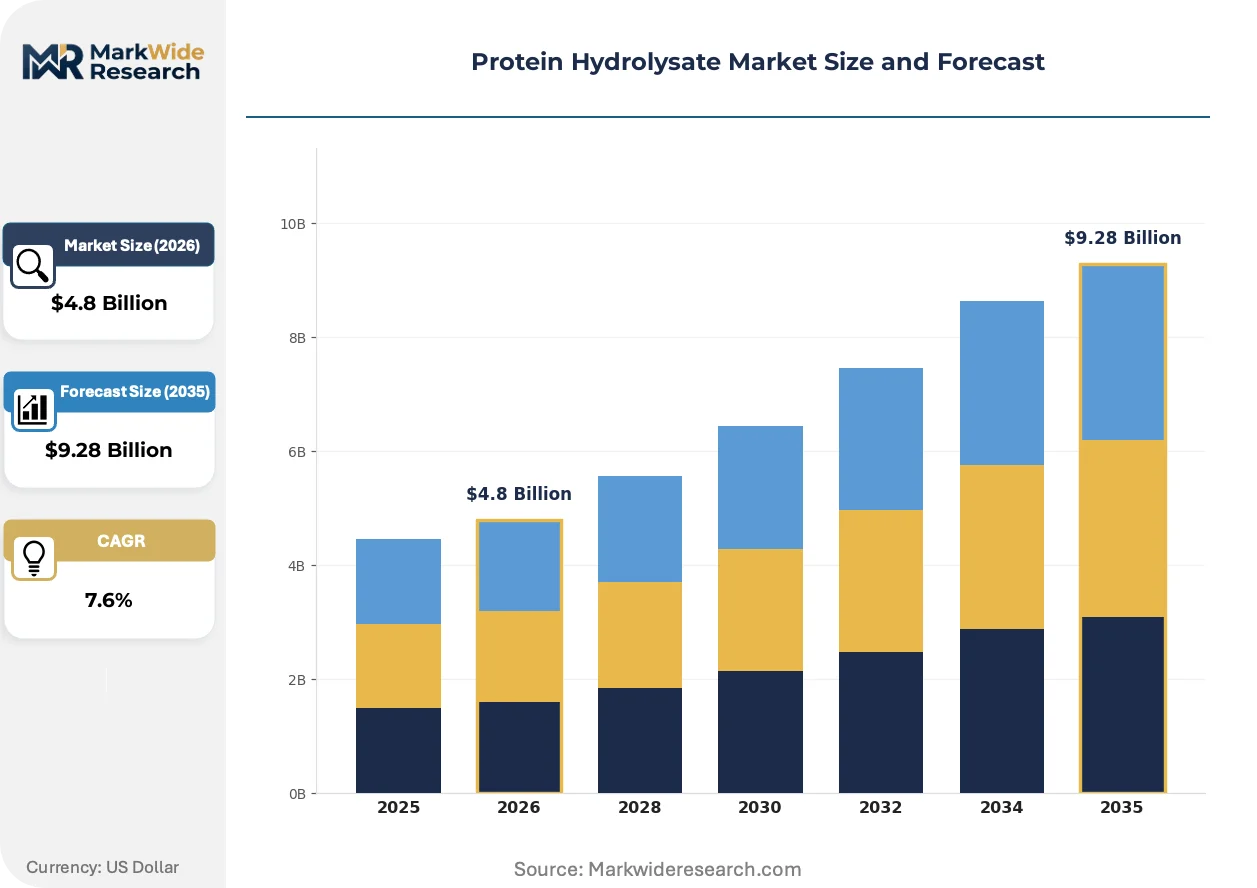
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein Protein, Soy Protein, Pea Protein Application: Nutritional Supplements, Sports Nutrition, Food & Beverages, Clinical Nutrition Source: Animal-Based, Plant-Based, Microbial, Fermented Form: Powder, Liquid, Granule, Tablet |
| Companies Covered | Archer Daniels Midland Company, Mead Johnson Nutrition, Arla Foods Ingredients, Merck KGaA, Hilmar Cheese Company, Fonterra Co-operative Group, Royal FrieslandCampina, Davisco Foods International, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protein Hydrolysate Market Emerging Trajectories
Continuous enzymatic membrane reactors are displacing batch tank operations, enabling real-time degree-of-hydrolysis monitoring that tightens peptide molecular weight distribution for medical food specifications.
Immobilized enzyme cartridge systems is fragmenting equipment vendor hierarchies. Smaller dairy processors in Wisconsin and Victoria now access hydrolysis capability without stainless-steel reactor capex, compressing minimum efficient scale thresholds. Regional toll manufacturers capture share from integrated multinationals in premium whey hydrolysate segments.
The EU F-Gas Regulation mandates refrigerant phase-down in spray-drying operations, forcing European hydrolysate producers to retrofit heat recovery systems or relocate drying capacity to jurisdictions with less stringent fluorinated gas controls. German and Dutch manufacturers face 15-20% energy cost premiums versus competitors with access to geothermal or biomass-powered drying infrastructure.
Hospital procurement consolidation is compressing supplier rosters for clinical nutrition enteral feeding formulations. GPOs in the United States and NHS Supply Chain in the United Kingdom now mandate dual-source hydrolysate supply with documented peptide mapping, disqualifying single-source vendors and favoring manufacturers with redundant production sites and validated cross-facility equivalency protocols.
Protein Hydrolysate Market Segmentation
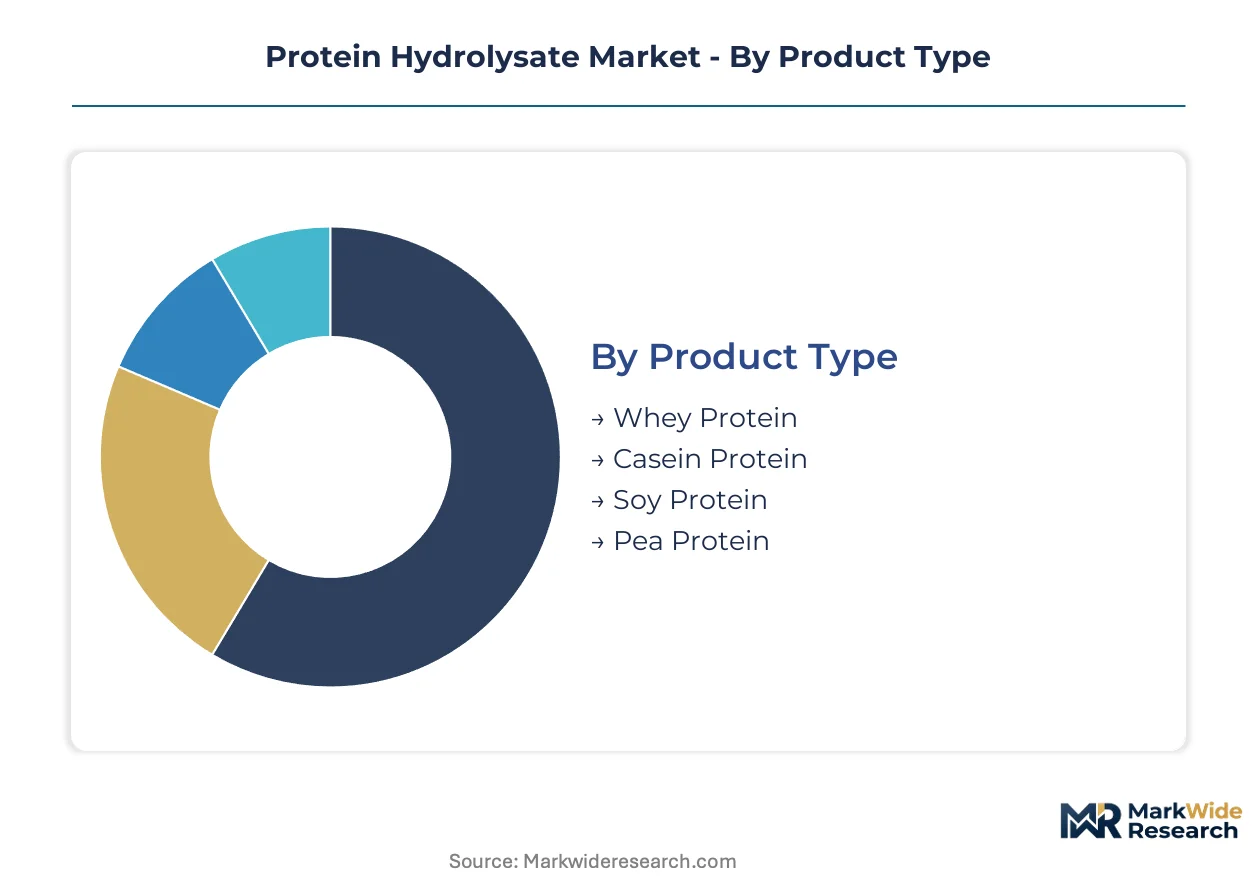
Protein hydrolysate procurement patterns diverge sharply between domestic food-grade consumption and export-oriented pharmaceutical-grade supply. Manufacturers configure production lines around these channel distinctions, with peptide mapping protocols and certification tiers determining facility eligibility.
Product Type:
Whey and casein hydrolysates dominate export flows to clinical nutrition markets, while plant-derived variants serve expanding domestic allergen-free applications.
- Whey Protein:Enzymatic cleavage of beta-lactoglobulin and alpha-lactalbumin yields rapid gastric emptying peptides prized for post-surgical recovery formulations. Hospital GPOs in the United States and NHS Supply Chain in the United Kingdom specify documented peptide mapping for enteral feeding contracts. Whey commands the established base.
- Pea Protein:Wet-milled yellow pea isolate undergoes controlled proteolysis to achieve molecular weights below 5 kDa for infant formula applications. Wet-milling infrastructure expansion in the Canadian Prairies and Northern France generates captive feedstock for allergen-free product lines. The steepest expansion runs through pea protein.
- Casein Protein:Slow-release peptide fractions from micellar casein hydrolysate target overnight muscle protein synthesis in medical foods.
- Soy Protein:Acid-precipitated glycinin and beta-conglycinin hydrolysates face declining demand in pediatric segments due to phytoestrogen concerns.
Whey protein hydrolysate anchors revenue concentration through clinical nutrition premiums. Pea protein hydrolysate gains share fastest as food brands reformulate away from major allergens.
Application:
Cost tier stratification separates pharmaceutical-grade clinical nutrition from commodity sports nutrition, with certification requirements determining margin capture.
- Clinical Nutrition:USP and EP monograph compliance for enteral feeding tubes and medical foods demands 18-24 month validation cycles. Hospital procurement consolidation favors manufacturers with redundant production sites and cross-facility equivalency protocols. Clinical nutrition commands the established base.
- Sports Nutrition:Professional cycling and endurance running teams now specify hydrolysate-based recovery formulations in multi-year supply contracts. Cold-processed microfiltrated whey isolates threaten mid-tier positioning with comparable leucine bioavailability at lower capital intensity. Sports nutrition climbs the fastest.
- Nutritional Supplements:Direct-to-consumer subscription platforms bypass traditional wholesale distribution, capturing margin pools from brand intermediaries.
- Food & Beverages:Clean-label infant formula applications drive pea protein hydrolysate uptake as major allergen avoidance intensifies.
Clinical nutrition retains the deepest margin pools through pharmacopeial compliance. Sports nutrition volume expansion accelerates as professional athletic procurement formalizes.
Source:
Supply concentration varies by origin, with animal-based processing clustering in dairy regions and plant-based capacity expanding near pulse cultivation zones.
- Animal-Based:Dairy-derived hydrolysates leverage existing whey and casein fractionation infrastructure across Wisconsin, Victoria, and the Netherlands. Integrated processors capture economies of scale through captive enzyme supply and spray-drying capacity. Animal-based sources command the established base.
- Plant-Based:Pea, rice, and fava bean protein hydrolysates emerge as the fastest-growing source category. Wet-milling and dry-fractionation investments in Canada, France, and China reduce dependence on imported concentrates. Plant-based sources expand most quickly.
- Microbial:Single-cell protein from fungal fermentation offers amino acid profiles approaching casein completeness for specialized medical foods.
- Fermented:Precision fermentation platforms require pharmaceutical-grade amino acid cocktails, creating premium demand from cultivated meat bioreactor operators.
Animal-based hydrolysates retain volume leadership through clinical nutrition lock-in. Plant-based variants accelerate as allergen-free formulation becomes non-negotiable for pediatric applications.
Form:
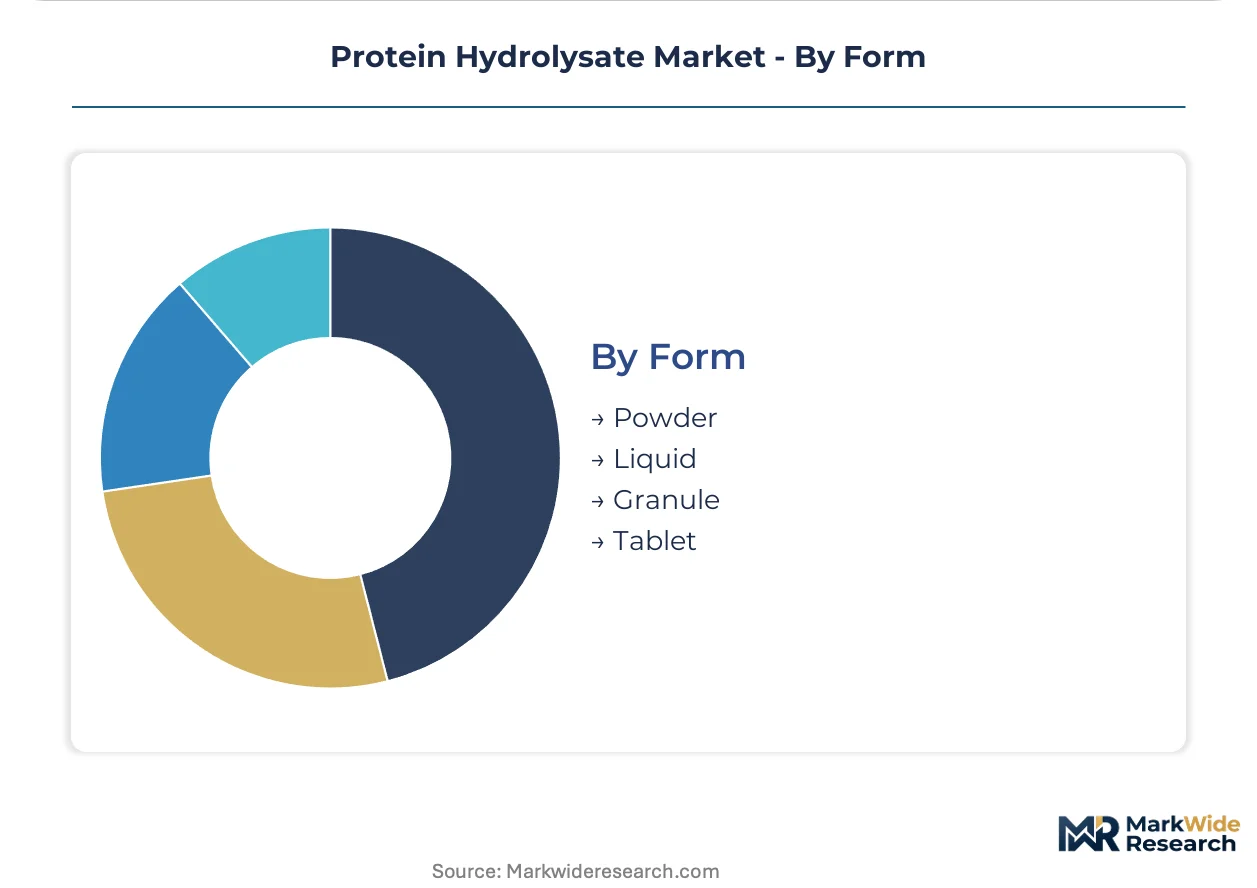
Customer type differentiation separates bulk powder procurement by nutraceutical manufacturers from finished tablet and liquid formats for retail pharmacy.
- Powder:Spray-dried hydrolysate powders dominate business-to-business supply to infant formula and sports nutrition brand owners. EU F-Gas Regulation refrigerant phase-down forces European producers to retrofit heat recovery systems or relocate drying capacity. Powder commands the established base.
- Liquid:Ready-to-drink enteral feeding formulations require aseptic processing and extended shelf-life stability testing. Hospital procurement mandates dual-source supply with validated peptide equivalency. Liquid gains share fastest.
- Granule:Agglomerated hydrolysate granules improve dispersibility in instant beverage applications for elderly nutrition.
- Tablet:Compressed amino acid tablets target direct-to-consumer sports nutrition segments with convenience positioning.
Powder retains manufacturing scale advantages through spray-drying infrastructure. Liquid formats accelerate as hospital procurement consolidates around ready-to-use enteral feeding systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows for protein hydrolysate concentrate trade reveal stark asymmetries between dairy-surplus exporters and allergen-free formulation demand centers. The United States maintains net export dominance in whey hydrolysate grades, while China and India drive import volume expansion for pediatric and sports nutrition applications.
United States
Wisconsin and Idaho dairy processing clusters generate the bulk of whey hydrolysate export volume for clinical nutrition contracts. FDA GRAS notification pathways and EPA effluent guidelines shape compliance costs for domestic toll manufacturers. Greater Chicago serves as the primary consolidation hub for spray-dried hydrolysate powder distribution to infant formula brand owners.
Germany
EFSA novel food opinions and REACH chemical safety registrations govern market access for new hydrolysate entrants targeting pharmaceutical-grade segments. The EU F-Gas Regulation mandates refrigerant phase-down in spray-drying operations, forcing producers in Bavaria and Lower Saxony to retrofit heat recovery systems. North Rhine-Westphalia hosts specialized peptide characterization laboratories serving clinical nutrition validation requirements.
China
NMPA extended peptide sequencing protocols and GB standards for food-grade peptides impose testing burdens on imported concentrates, adding clearance delays at Shanghai and Tianjin ports. Domestic wet-milling infrastructure expansion in Shandong and Heilongjiang provinces reduces dependence on Canadian pea protein feedstock. Yangtze River Delta formulation facilities drive demand for low-allergen hydrolysate variants in infant formula.
India
FSSAI food safety standards and the PLI scheme for food processing infrastructure incentivize domestic hydrolysate manufacturing capacity near nutraceutical export clusters. Maharashtra and Gujarat host emerging toll manufacturing sites targeting Middle East and Southeast Asian markets. Import substitution policies accelerate backward integration into enzyme production for regional manufacturers.
Netherlands
REACH pre-registration dossiers for novel peptide sequences accelerate market access for hydrolysate innovators targeting EFSA novel food pathways. Rotterdam port logistics and integrated dairy processing in Friesland support re-export flows to United Kingdom and German clinical nutrition channels. Geothermal-powered drying infrastructure in the north provides energy cost advantages versus German competitors.
Protein Hydrolysate Market Vendor Landscape
Concentration sits with integrated dairy processors and specialized enzyme technology providers rather than fragmented toll manufacturers. The vendor base stratifies across three tiers: multinational ingredient suppliers with captive fractionation infrastructure, regional dairy cooperatives with spray-drying scale, and emerging plant-protein specialists with wet-milling integration. Dominant competitive moves include capacity expansion in pea protein fractionation and strategic partnerships between enzyme suppliers and toll manufacturers.
Within the integrated dairy tier, Fonterra Co-operative Group and Royal FrieslandCampina exemplify cooperative structures with backward integration into milk supply and captive hydrolysis capability. Merck KGaA occupies a distinct position in pharmaceutical-grade supply through bioprocessing heritage. Cargill represents the plant-based pivot, extending commodity fractionation into specialized hydrolysate grades for allergen-free applications.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Mead Johnson Nutrition |
| Arla Foods Ingredients |
| Merck KGaA |
| Hilmar Cheese Company |
| Fonterra Co-operative Group |
| Royal FrieslandCampina |
| Davisco Foods International |
| Cargill |
| Others |
Supply Flow & Price Mechanics
Multi-year take-or-pay contracts between sports nutrition brands and toll manufacturers lock in both peptide supply security and forward price visibility across volatile enzyme input markets. These arrangements concentrate procurement power with volume-commitment buyers while exposing mid-tier producers to margin compression when protease concentrate costs spike.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the protein hydrolysate market. Premium tiers command pharmacopeial-grade certification premiums from hospital GPOs, while standard grades serve sports nutrition formulators and economy tiers supply commodity infant formula applications. Price differentiation hinges on degree-of-hydrolysis precision and peptide mapping documentation depth. Cost compression in mid-tier whey hydrolysate is intensifying as cold-processed microfiltrated isolates achieve comparable leucine bioavailability without hydrolysis capital expenditure. Sports nutrition brand procurement teams exhibit highest price sensitivity, whereas clinical nutrition buyers prioritize supply security over unit cost.
Supply Chain Analysis
Strategic stockpile preferences dominate clinical nutrition procurement, with hospital GPOs mandating 90-180 day safety inventories to ensure enteral feeding continuity. Geographic supply concentration centers on the United States, Germany, and the Netherlands for dairy-derived hydrolysates, while Canada and France anchor plant-based pea protein fractionation. Raw material dependencies rest on fermentation-derived protease concentrates, spray-drying energy inputs, and wet-milled pulse isolates. Single-source vulnerability threatens tier-two toll manufacturers lacking redundant enzyme supply agreements. Distribution runs through Rotterdam and Greater Chicago consolidation hubs serving pharmaceutical-grade and food-grade channels respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital procurement consolidation and sports nutrition brand vertical integration, fragmenting supplier leverage across tier-two manufacturers. This shift rewards scale-backed incumbents while squeezing mid-cap toll operators.
For Market Incumbents: Secure redundant production site certification under USP and EP monograph protocols to meet dual-source mandates from NHS Supply Chain and United States hospital GPOs. Deepen captive enzyme production through backward integration into fermentation infrastructure, mitigating protease concentrate price volatility that threatens toll manufacturing margins. Cold-processed microfiltrated whey isolates represent a substitution threat requiring differentiation through peptide bioavailability documentation. For New Entrants and Emerging Players: Anchor in wet-milled pea protein fractionation serving allergen-free infant formula applications, where EFSA novel food pathways and REACH pre-registration dossiers create regulatory moats against commodity competitors. Target Indian PLI scheme incentives for food processing infrastructure near Maharashtra and Gujarat export clusters. Direct-to-consumer subscription platforms offer a go-to-market angle bypassing entrenched wholesale distribution channels. For Investors and Strategic Acquirers: Regional toll manufacturers with validated cross-facility equivalency protocols represent the most defensible acquisition archetype in a market consolidating around supply security requirements. Long-term viability favors operators with geothermal or biomass-powered drying infrastructure insulating against EU F-Gas Regulation energy cost premiums. Watch for NMPA clearance timeline compression as an inflection signal opening Chinese import volume expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Pea Protein Fractionation | Captures allergen-free formulation demand from infant formula brands reformulating away from dairy and soy. |
| Backward Integration into Enzyme Production | Insulates toll manufacturers from protease concentrate price volatility squeezing gross margins. |
| Pharmacopeial Certification Investment | Unlocks hospital GPO and NHS Supply Chain contracts requiring USP and EP monograph compliance. |
| Geothermal-Powered Drying Infrastructure | Delivers 15-20% energy cost advantages versus German competitors under EU F-Gas Regulation constraints. |
| Direct-to-Consumer Subscription Launch | Bypasses wholesale distribution margin pools, capturing value from personalized nutrition platform growth. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with hydrolysate manufacturing executives, enzyme technology suppliers, hospital procurement managers, and sports nutrition brand formulators; and secondary validation against FDA GRAS notifications, EFSA novel food opinions, REACH pre-registration dossiers, and customs trade flow records. Bottom-up volume modeling triangulated against top-down market sizing across the value chain.
Across the analysis window, the forecasting framework modeled segmentation dimensions including product type, application tier, source origin, and form factor, with CAGRs derived from elasticity-adjusted demand projections and capacity expansion pipelines. Key inputs incorporated enzyme cost trajectories, regulatory clearance timelines, and hospital procurement consolidation patterns.
Material uncertainties — protease concentrate price shocks, NMPA protocol extensions, and intact protein substitution acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions around degree-of-hydrolysis technology adoption and EFSA novel food approval velocities. Revision becomes warranted when cold-processed isolate bioavailability claims cross clinical validation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Gelatin Market
Ingredients
Global Inactive Dried Yeast Market
Ingredients
Bone and Joint Health Ingredients Market
Ingredients
Europe Fats and Oil Market
Ingredients
Middle East and Africa Lipids Market
Ingredients
Pea Fiber Market
Ingredients
Vegetable Glycerin Market
Ingredients
Global Vitamin Ingredients Market
Ingredients
Seaweed Derivatives Market
Ingredients
Non Meat Ingredients Market
Ingredients
Brewer's Yeast Market
Ingredients
Acacia Gum Market
Ingredients
Proteose Peptone Market
Ingredients
United Arab Emirates Sunflower Oil Market
Ingredients
Beetroot Powder Market
Ingredients
Asia-Pacific Fats and Oil Market