
 Frozen Tart Shells Market | 2026-2036
Frozen Tart Shells Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Tart Shells Market Insights
Restaurant pastry programs is expanding faster than traditional bakery channels, pulling frozen tart shells into high-volume kitchen operations. Dawn Foods leverages its bakery-ingredient heritage to supply co-manufactured shells for food-service distributors. Rich Products Corporation anchors North American institutional accounts with frozen dough systems designed for thaw-and-fill workflows. Europastry competes across European food-service chains with laminated and shortcrust varieties scaled for consistency.
Frozen tart shells are pre-formed, par-baked or unbaked pastry vessels, typically composed of laminated dough or shortcrust formulations with specified fat content and moisture retention parameters, manufactured through sheeting, cutting, pressing, and flash-freezing processes for subsequent filling and finishing. Sweet tart shells dominate retail freezer space, yet savory variants capture expanding food-service menu slots as operators build all-day tart programs. Almond flour and gluten-free dough segments are accelerating fastest, though wheat flour formulations still occupy the bulk of volume and margin pools through commodity-scale milling contracts.
FDA food-contact and labeling standards shape ingredient declarations and allergen management for US-manufactured shells, while EFSA and EU Green Deal sustainability frameworks pressure reformulation of palm oil and shortening sources across European production. The EU F-Gas Regulation indirectly affects cold-chain logistics costs for frozen distribution networks. Stakeholders must monitor how dual carbon goals in China and emerging clean-label mandates in India reshape supplier qualification criteria for export-oriented tart shell manufacturers.
Market Dynamics
Clean-label mandates from the FDA and EFSA are forcing frozen tart shell manufacturers to reformulate shortening and palm oil sources, compressing formulation flexibility while expanding allergen-management costs across production networks.
Growth Catalysts
- EU Green Deal sustainability frameworks:European producers are accelerating reformulation of laminated dough fats to meet deforestation-free supply chain requirements, opening premium positioning for certified sustainable tart shells in food-service procurement.
- Almond flour dough technology:Gluten-free and grain-free formulations are capturing shelf space in US retail freezers as household consumers with dietary restrictions seek convenience without wheat-based ingredients.
- France:Artisanal tart traditions anchor centralized purchasing by bakery chains and restaurant groups, creating stable volume anchors for frozen shell suppliers with heritage shortcrust capabilities.
Market Restraints
- Wheat flour commodity volatility:Milling contract pricing swings directly compress margin pools for standard shortcrust formulations that still occupy bulk volume positions.
- Cold-chain infrastructure concentration:Flash-freezing and distribution networks cluster in Northern European logistics hubs, creating geographic vulnerability for just-in-time food-service deliveries.
- Fresh-baked substitute competition:In-house pastry programs at high-end restaurant groups threaten displacement of frozen shells in premium positioning tiers where labor cost absorption is feasible.
Strategic Opportunities
- India clean-label import mandates:Emerging regulatory requirements for ingredient transparency are reshaping supplier qualification criteria, creating first-mover advantage for exporters with established allergen-management systems.
- Savory tart menu expansion:All-day tart programs at European and North American food-service operators are pulling frozen shells into lunch and dinner dayparts beyond traditional breakfast and pastry applications.
- Direct-to-food-service e-procurement platforms:Digital ordering systems are compressing distributor layers, enabling shell manufacturers to capture margin previously allocated to intermediaries in institutional accounts.
Industry Challenges
- Laminated dough technician scarcity:Specialized skills for sheeting and fat-layer management are concentrating in aging workforce pools, constraining quality consistency at scaled production facilities.
- F-Gas Regulation compliance timelines:EU cold-chain equipment retrofit requirements are forcing capital redeployment into refrigeration infrastructure, diverting investment from line expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Tart Shells Market |
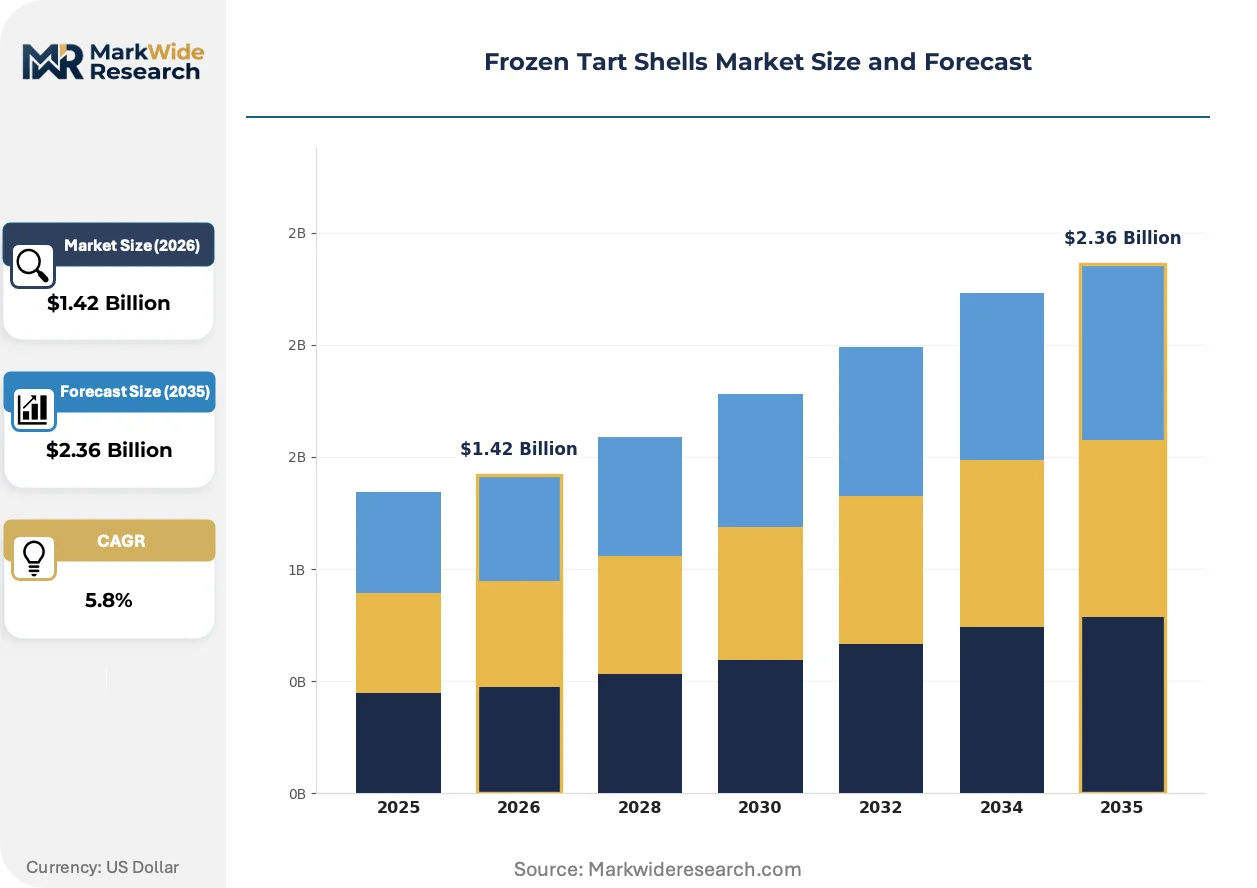
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweet Tart Shells, Savory Tart Shells, Mini Tart Shells, Large Tart Shells Material: Wheat Flour, Almond Flour, Gluten-Free Dough, Whole Wheat Flour Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Food Service End User: Bakery, Restaurant, Catering Service, Household |
| Companies Covered | General Mills, Conagra Brands, Dawn Foods, Pidy Gourmet, La Rose Noire, Pillsbury, Dutch Ann Food, Europastry, Rich Products Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Tart Shells Market Trends and Innovations
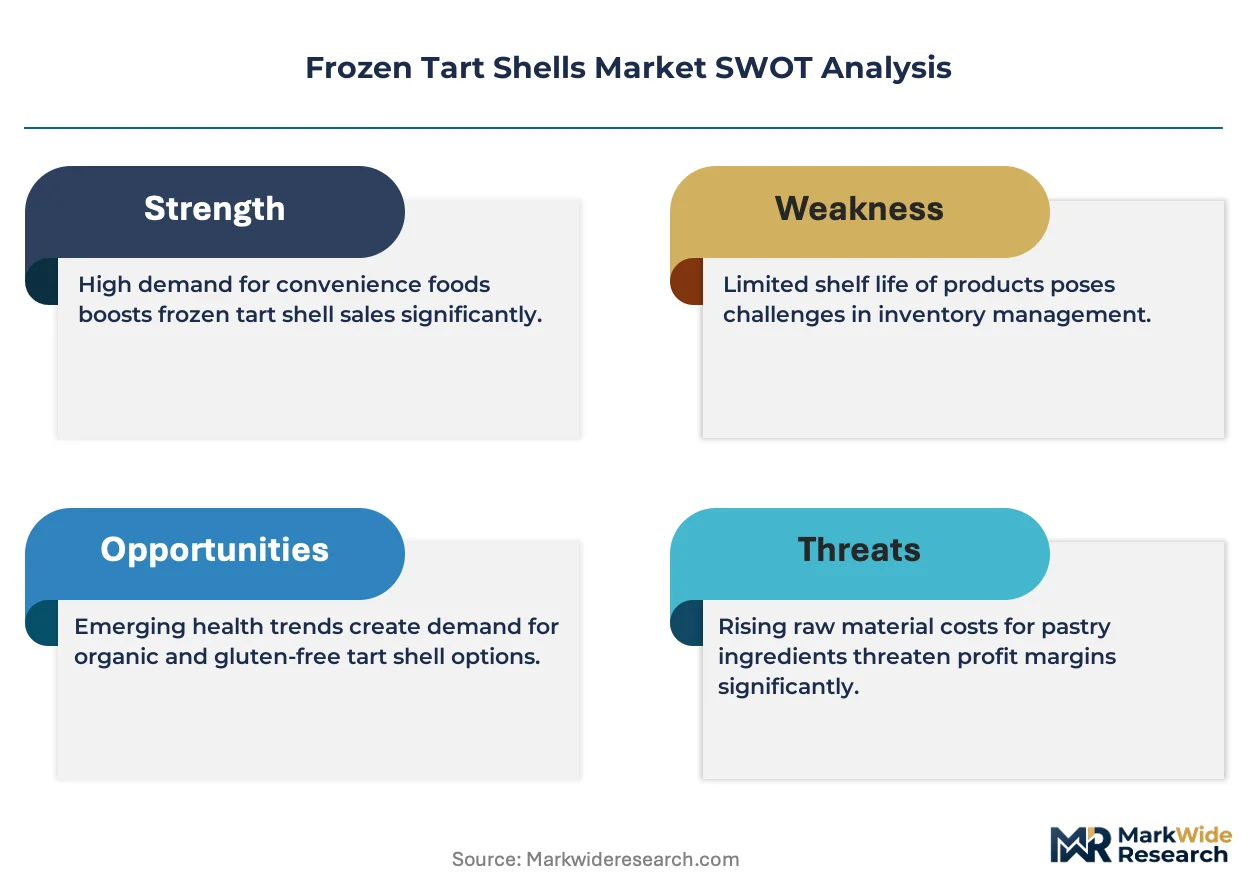
Refrigeration technology advances and reformulation science are redistributing competitive advantage across frozen tart shell manufacturing, compressing legacy differentiation while opening new capability-based positioning.
Individual quick-freezing (IQF) technology with cryogenic carbon dioxide injection is decentralizing production geography for frozen tart shells. Mid-scale regional bakeries in the United States and Germany are adopting compact IQF lines previously restricted to industrial facilities. This capability diffusion is enabling localized supply to food-service operators who previously relied on centralized national distribution.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants across frozen distribution networks. Cold-chain operators are retrofitting transport refrigeration with natural refrigerant alternatives, compressing equipment replacement cycles and reshaping logistics cost structures. European frozen tart shell distributors with captive fleet operations face the most concentrated compliance pressure.
Food-service procurement teams are consolidating supplier panels and demanding single-source accountability for allergen documentation. Large US restaurant groups are reducing approved vendor lists from multiple regional suppliers to two or three national partners with integrated quality systems. This buyer concentration is visible most acutely in institutional accounts where liability exposure drives risk-averse sourcing behavior.
Frozen Tart Shells Market Segmentation
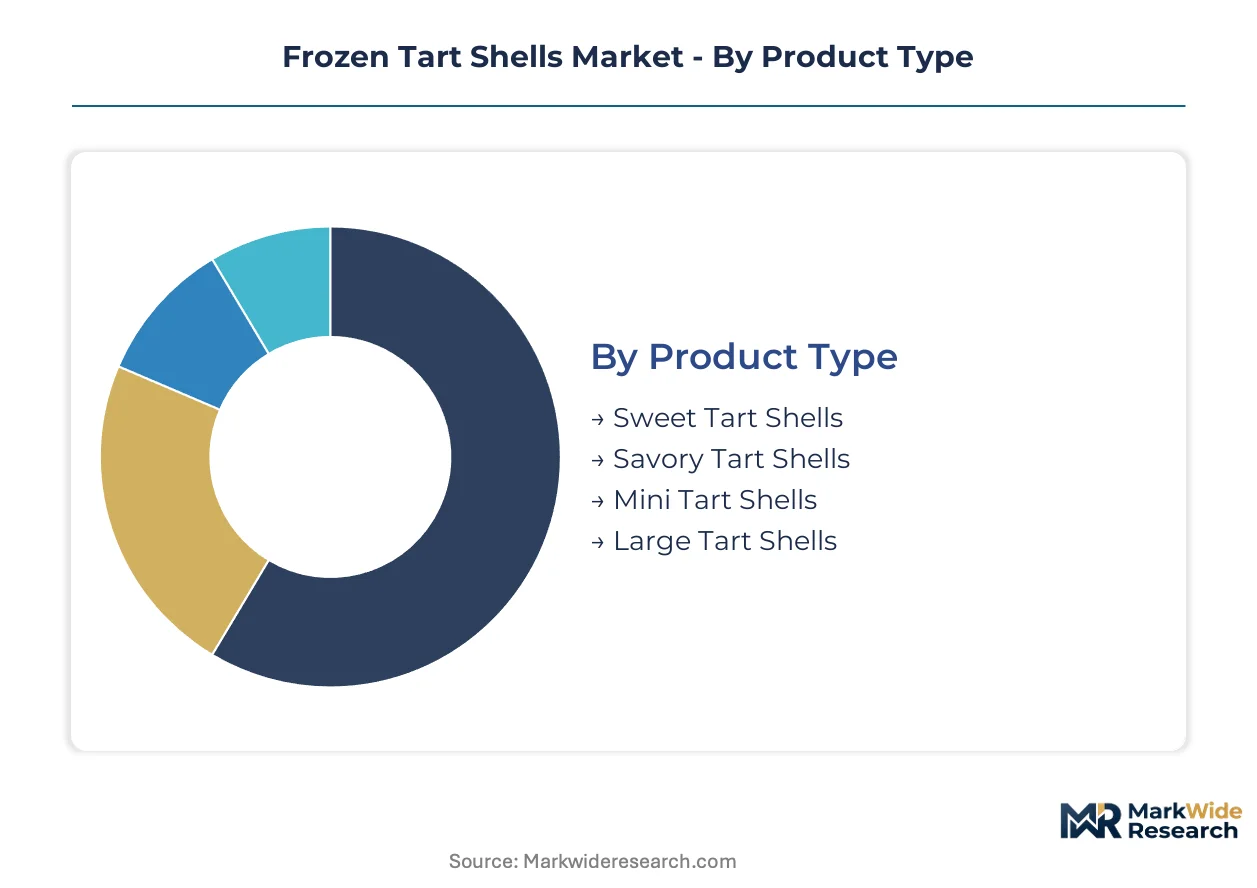
Segmentation in frozen tart shells reveals how formulation choices and channel access determine margin capture. Supply concentration varies sharply across material types and distribution pathways, reshaping where manufacturers invest production capacity.
Product Type:
Supply concentration clusters around formats that align with equipment standardization in commercial kitchens.
- Sweet Tart Shells:Shortcrust and laminated formulations with specified sugar content and moisture retention parameters dominate retail freezer space. Demand concentrates in US household consumption as convenience-seeking home bakers prioritize thaw-and-fill workflows for dessert applications.
- Savory Tart Shells:Reduced-sugar dough compositions with higher fat stability for hot-fill applications capture expanding food-service menu slots. European restaurant groups building all-day tart programs in France and Germany are pulling these shells into lunch and dinner dayparts beyond traditional pastry applications.
- Mini Tart Shells:Bite-sized formats for catering and buffet service with standardized portion control.
- Large Tart Shells:Family-size and commercial-scale vessels for institutional baking operations and high-volume restaurant dessert programs.
Today's leader: Sweet Tart Shells. Tomorrow's challenger: Savory Tart Shells.
Material:
Cost tier stratification separates commodity-scale milling contracts from specialty ingredient premiums.
- Wheat Flour:Standard shortcrust formulations occupy bulk volume positions through long-term milling contracts with major grain suppliers. Margin pools compress directly when commodity pricing swings hit centralized production facilities in Northern European logistics hubs.
- Almond Flour:Grain-free dough technology with higher protein content and distinct textural properties is climbing the fastest in US retail freezers. Household consumers with dietary restrictions in California and Texas metro areas seek convenience without wheat-based ingredients.
- Gluten-Free Dough:Rice flour, tapioca starch, and xanthan gum formulations for celiac and gluten-sensitive segments.
- Whole Wheat Flour:Higher-fiber shortcrust variants targeting health-positioned bakery chains and clean-label procurement criteria.
Volume dominance: Wheat Flour. Steepest expansion trajectory: Almond Flour.
Distribution Channel:
Customer type determines order frequency, batch size, and documentation requirements across channel pathways.
- Food Service:Direct and distributor-mediated supply to restaurant groups, bakery chains, and institutional accounts with integrated allergen-management systems. Large US restaurant groups are consolidating approved vendor lists from multiple regional suppliers to two or three national partners with single-source accountability.
- Supermarkets:Branded and private-label retail freezer placement with seasonal promotional cycles and packaging format requirements.
- Online Retailers:Direct-to-consumer fulfillment with cold-chain packaging specifications and subscription-based reordering.
- Specialty Stores:Gourmet food retailers and bakery supply shops with curated artisanal positioning and smaller batch procurement.
Margin concentration: Food Service. Channel gaining share fastest: Online Retailers.
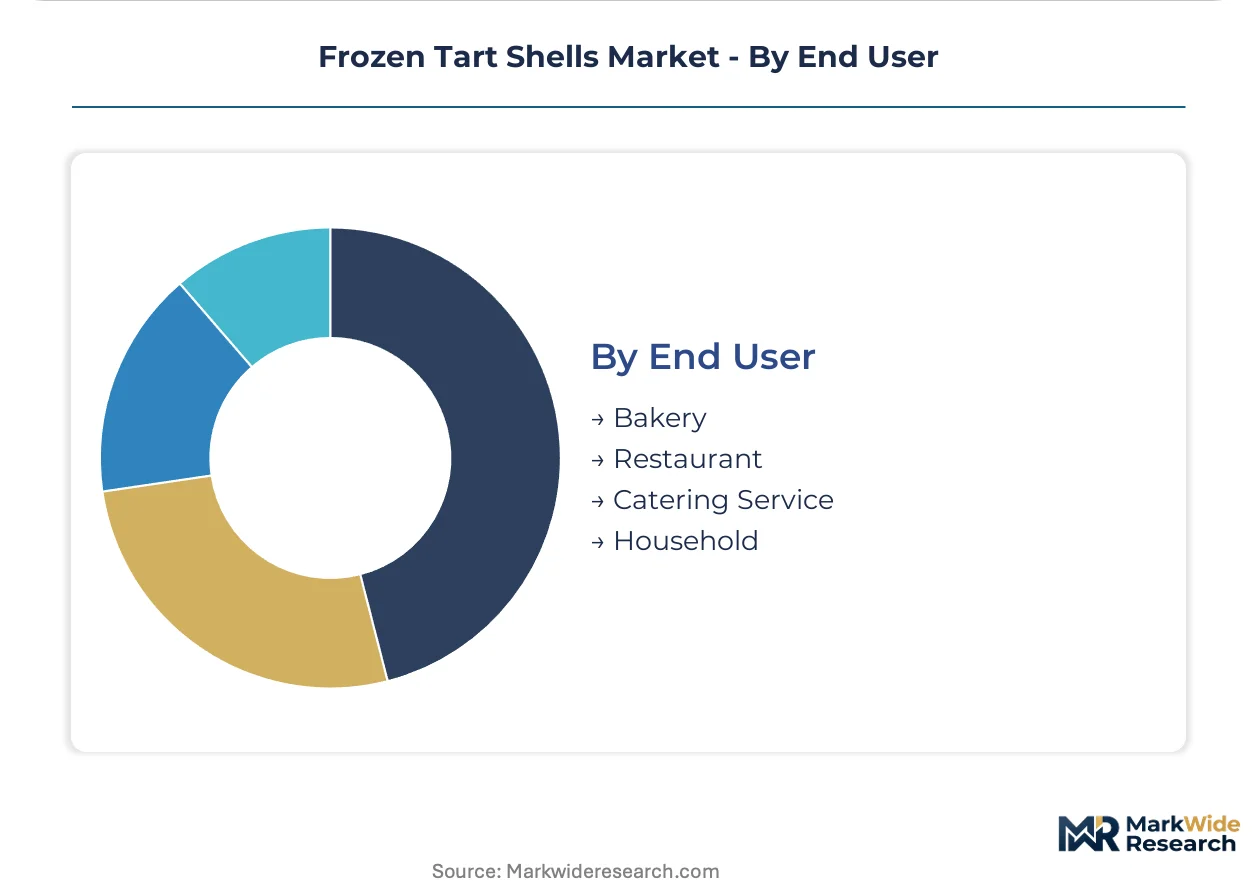
End User:
Application maturity shapes whether frozen shells displace in-house production or complement existing pastry programs.
- Restaurant:High-volume kitchen operations with thaw-and-fill workflows and standardized finishing protocols. Expansion of pastry programs at European and North American food-service operators is accelerating faster than traditional bakery channels.
- Bakery:Artisanal and commercial baking operations with mixed frozen-fresh production models.
- Catering Service:Event-based volume demand with fluctuating seasonal patterns and portable holding equipment requirements.
- Household:Individual consumers in US suburban markets prioritizing convenience without scratch preparation time investment.
Current volume anchor: Bakery. Fastest-growing application: Restaurant.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's artisanal tart heritage anchors food-service procurement networks across Europe. Bakery chains and restaurant groups in Paris and Lyon drive centralized purchasing of heritage shortcrust formulations. Regulatory pressure from EFSA clean-label mandates and EU Green Deal sustainability frameworks is accelerating reformulation of palm oil and shortening sources.
United States
Convenience-driven household consumption in suburban markets is pulling frozen tart shells into retail freezer space. FDA food-contact and labeling standards shape ingredient declarations and allergen management for domestic manufacturers. California and Texas metro areas concentrate demand for almond flour and gluten-free dough variants as dietary restrictions reshape purchasing patterns.
Germany
Industrial bakery operations in Bavaria and North Rhine-Westphalia anchor laminated dough production for European food-service chains. EU F-Gas Regulation compliance timelines are forcing capital redeployment into refrigeration infrastructure across cold-chain distribution networks. Frankfurt logistics hubs cluster flash-freezing capacity for just-in-time deliveries to restaurant groups.
China
Dual carbon goals are reshaping supplier qualification criteria for export-oriented manufacturers in Yangtze River Delta production zones. The country's national food safety regulator is tightening cold-chain standards for frozen dough imports. Shanghai and Jiangsu province concentrate mid-scale regional bakeries adopting compact IQF lines for localized food-service supply.
India
Emerging clean-label import mandates from FSSAI are creating first-mover advantage for exporters with established allergen-management systems. Maharashtra and Gujarat industrial corridors host bakery ingredient distributors building procurement relationships with frozen shell suppliers. Mumbai restaurant groups are expanding pastry programs that pull imported tart shells into high-volume kitchen operations.
Frozen Tart Shells Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers retrofit refrigeration infrastructure and adopt compact IQF technology. The vendor base separates into three tiers: multinational ingredient conglomerates with bakery heritage, European laminated dough specialists with food-service scale, and regional co-manufacturers serving distributor networks. Two strategic archetypes prevail—suppliers integrating backward into flour milling contracts and those building direct e-procurement relationships with restaurant groups. M&A activity and geographic expansion into emerging clean-label markets represent the dominant competitive moves.
Within the multinational tier, General Mills and Conagra Brands exemplify scale-driven positioning through diversified frozen dough portfolios. Dawn Foods occupies a heritage anchor position in North American food-service channels. Europastry represents the European laminated dough specialist archetype with continental food-service chain relationships. Rich Products Corporation sits within the institutional account tier with thaw-and-fill workflow systems.
| Leading Market Players |
|---|
| General Mills |
| Conagra Brands |
| Dawn Foods |
| Pidy Gourmet |
| La Rose Noire |
| Pillsbury |
| Dutch Ann Food |
| Europastry |
| Rich Products Corporation |
| Others |
Pricing and Supply Chain Analysis
Consolidated vendor lists at large US restaurant groups are compressing supplier margins while demanding single-source accountability for allergen documentation, forcing manufacturers to absorb certification costs or cede volume to national competitors with integrated quality systems.
Pricing Analysis
Input-cost pass-through from wheat flour commodity contracts and palm oil reformulation expenses is compressing margin pools for standard shortcrust formulations. Three-tier pricing structure across premium, standard, and economy levels separates certified sustainable shells from conventional formulations and private-label economy tiers. Pricing pressure stems from clean-label mandate compliance costs and cold-chain logistics retrofit requirements. Food-service distributors exhibit highest price sensitivity due to thin distributor margins, while specialty retail channels absorb premium positioning with less elasticity.
Supply Chain Analysis
Regional distribution centers in Northern European logistics hubs anchor hub-and-spoke cold-chain networks for flash-frozen tart shell delivery. Manufacturing concentrates in France, Germany, and the United States, with emerging capacity in China's Yangtze River Delta. Production draws from wheat flour milling contracts, shortening and palm oil supply chains, and cryogenic refrigerant distribution networks. Single-source vulnerability concentrates in specialized laminated dough technician labor pools. Distribution runs through food-service distributors, supermarket retail freezer systems, and direct-to-operator e-procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The frozen tart shells market functions as a regulatory compounder where EU F-Gas Regulation compliance timelines and FDA clean-label mandates are accelerating capital deployment into reformulation and refrigeration infrastructure, creating structural advantage for early movers with integrated quality systems.
For Market Incumbents: Cement market position by securing long-term milling contracts for wheat flour and almond flour to lock in input cost stability against commodity volatility. Invest in captive IQF line capacity in Germany and the United States to serve consolidated food-service accounts with localized supply. Build direct e-procurement relationships with restaurant groups to capture margin previously allocated to distributor intermediaries.
For New Entrants and Emerging Players: The price-point gap between premium certified-sustainable tart shells and economy private-label tiers opens white-space opportunity in mid-market branded positioning. Target India's emerging clean-label import mandate window with established allergen-management documentation. Pursue savory tart shell segments in European all-day menu programs as the fastest-penetrable application. Go-to-market through specialty food distributors serving independent restaurant groups seeking differentiated pastry programs.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional co-manufacturers possessing compact IQF technology and direct food-service relationships in fragmented markets. Long-term viability over the analysis window favors suppliers with backward integration into flour milling and forward integration into digital procurement platforms. Acquisition targets should demonstrate certified sustainable supply chain credentials and laminated dough technical capabilities. Monitor F-Gas Regulation compliance timelines as inflection indicator for logistics cost restructuring and competitive shakeout.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flour Milling | Captures margin from commodity wheat and specialty almond flour supply chains. |
| Compact IQF Line Deployment | Enables localized production in California and Texas metro markets for dietary-restricted segments. |
| Direct E-Procurement Platform Launch | Compresses distributor layers and captures institutional account margin for national restaurant groups. |
| Sustainable Palm Oil Certification Program | Meets EU Green Deal deforestation-free requirements for premium food-service positioning. |
| Savory Tart Shell Product Line Extension | Captures lunch and dinner daypart demand from European all-day tart menu expansion. |
Research Methodology
Multiple input streams — primary interviews with frozen dough plant managers, food-service procurement directors, and bakery chain category buyers; secondary validation through FDA food-contact guidance documents, EFSA clean-label frameworks, EU F-Gas Regulation filings, and customs trade data; and bottom-up production capacity modeling reconciled against top-down food-service spending estimates — were synthesized to construct market sizing and growth projections.
Data-stream reconciliation across supply-side capacity assessments and demand-side channel audits informed analytical framework development across the projection horizon. Segmentation dimensions modeled include product type, material composition, distribution channel, and end-user application with regional regulatory cluster overlays. CAGRs were derived from trend extrapolation of clean-label adoption curves and IQF technology diffusion patterns, incorporating wheat flour commodity pricing volatility and cold-chain logistics cost trajectories as scenario variables.
The model assumes a particular technology adoption path for cryogenic carbon dioxide IQF systems; alternative pathways for ammonia-based natural refrigerant retrofits would alter the outlook for production geography decentralization. Forecasts reflect documented assumptions regarding regulatory compliance timelines and buyer consolidation trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
North America Dehydrated Food Market
Processed and Frozen Foods
Frozen Yogurt Market
Processed and Frozen Foods
North America Frozen Food Market
Processed and Frozen Foods
Global Chilled and Deli Foods Market
Processed and Frozen Foods
Frozen Processed Food Market
Processed and Frozen Foods
Freeze Dried Tropical Fruits Market
Processed and Frozen Foods
Europe Frozen Desserts Market
Processed and Frozen Foods
Cold Cuts Market
Processed and Frozen Foods
North America Frozen Pizza Market
Processed and Frozen Foods
Spiral Freezer Market
Processed and Frozen Foods
Low-Fat Cool Whip Market
Processed and Frozen Foods
Frozen Bread Market
Processed and Frozen Foods
Frozen Sardine Market
Processed and Frozen Foods
IQF Food Products Market
Processed and Frozen Foods
Freeze-Dried Food Market
Processed and Frozen Foods
Taiyaki Ice Cream Market